
 Feed Vitamins Market | 2026-2036
Feed Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Vitamins Market Analysis
Integrated poultry operations is unwinding reliance on traditional livestock producers as the primary demand anchor for bulk vitamin blends. DSM Nutritional Products AG leverages its premix formulation expertise to serve automated feeding systems across European broiler houses. Cargill sustains geographic dominance through backward integration into vitamin E synthesis and captive distribution networks in North American corn-belt feed mills. BASF SE anchors its position via specialized carotenoid production for egg yolk pigmentation, a high-margin niche within fat-soluble vitamins.
Feed vitamins are micronutrient additives formulated to precise IU or milligram-per-kilogram concentrations, typically blended into premixes through sequential dilution processes to ensure homogeneity in finished feed. Their primary commercial purpose is to prevent deficiency disorders, optimize metabolic efficiency, and support immune function in animals raised for protein production. Water-soluble vitamins occupy the largest volume share due to B-complex requirements across all monogastric species, while fat-soluble vitamins command premium positioning where enhanced bioavailability formulations justify higher pricing. The aquaculture application represents the fastest-expanding demand pool as shrimp and salmon producers intensify stocking densities and require precise vitamin C stabilization to prevent skeletal deformities.
The EU Green Deal and FDA's Veterinary Feed Directive jointly constrain antibiotic growth promoter alternatives, redirecting formulation investment toward immunomodulatory vitamin protocols that comply with residue monitoring programs. China's MEE enforces stricter effluent standards on vitamin manufacturing facilities, elevating capital requirements for fermentation-based B-vitamin producers and tightening supply availability during environmental inspection cycles. Stakeholders must monitor regulatory divergence between jurisdictions that accept novel vitamin metabolites and those maintaining conservative positive-list approaches, as this split determines where innovation premiums can be captured versus where commodity competition prevails.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing antibiotic use windows and forcing feed formulators toward immunomodulatory vitamin protocols that satisfy residue monitoring thresholds. This regulatory compression is rewiring procurement priorities across protein supply chains.
Growth Catalysts
- Precision Nutrition Mandates:The EU Green Deal tightens residue limits and pushes producers toward micronutrient optimization. Feed mills invest in automated premix systems to meet Farm to Fork compliance deadlines.
- Brazilian Cattle Professionalization:Large-scale finishing operations in Mato Grosso state are standardizing vitamin protocols. Professional integrators displace traditional ranchers as volume anchors for bulk B-vitamin blends.
- Aquaculture Intensification:Shrimp and salmon producers raise stocking densities and require stabilized vitamin C formulations. Skeletal deformity prevention drives precise ascorbic acid dosing in recirculating systems.
Market Restraints
- Fermentation Input Volatility:Corn syrup and molasses prices swing with biofuel policy shifts. B-vitamin producers face margin compression when feedstock costs spike without formula pass-through mechanisms.
- Chinese Supply Concentration:Environmental inspections by China's MEE shutter fermentation facilities unpredictably. Global buyers face allocation rationing when Mato Grosso orders coincide with Chinese export restrictions.
- Synthetic Carotenoid Substitution:Natural pigment extracts from marigold and paprika displace synthetic astaxanthin in niche egg markets. Premium positioning erodes where clean-label preferences override performance metrics.
Strategic Opportunities
- Sub-Saharan Underpenetration:Smallholder poultry operations across Nigeria and Kenya lack premix access. Mobile blending units and micro-dosing technology could unlock volume at the village cooperative tier.
- Regenerative Agriculture Incentives:The US IRA funds soil health practices that elevate forage quality variability. Supplemental vitamin programs gain traction where pasture nutrition gaps widen seasonally.
- Digital Feed Formulation Convergence:Near-infrared spectroscopy merges with cloud-based ration software. Real-time nutrient adjustment enables dynamic vitamin dosing that manual blending cannot replicate.
Industry Challenges
- Homogeneity Certification Timelines:Premix suppliers face extended validation cycles for CV under 5% across sequential dilution batches. FDA's Veterinary Feed Directive inspection backlogs delay new facility approvals.
- Fermentation Talent Scarcity:Industrial microbiology expertise concentrates at legacy B-vitamin producers. New entrants struggle to recruit strain optimization specialists capable of yield improvements.
- Legacy Mill Integration Friction:Automated dosing systems require retrofitting mechanical blenders with load-cell precision. Family-owned feed mills defer capex and rely on manual premix addition with higher variation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Vitamins Market |
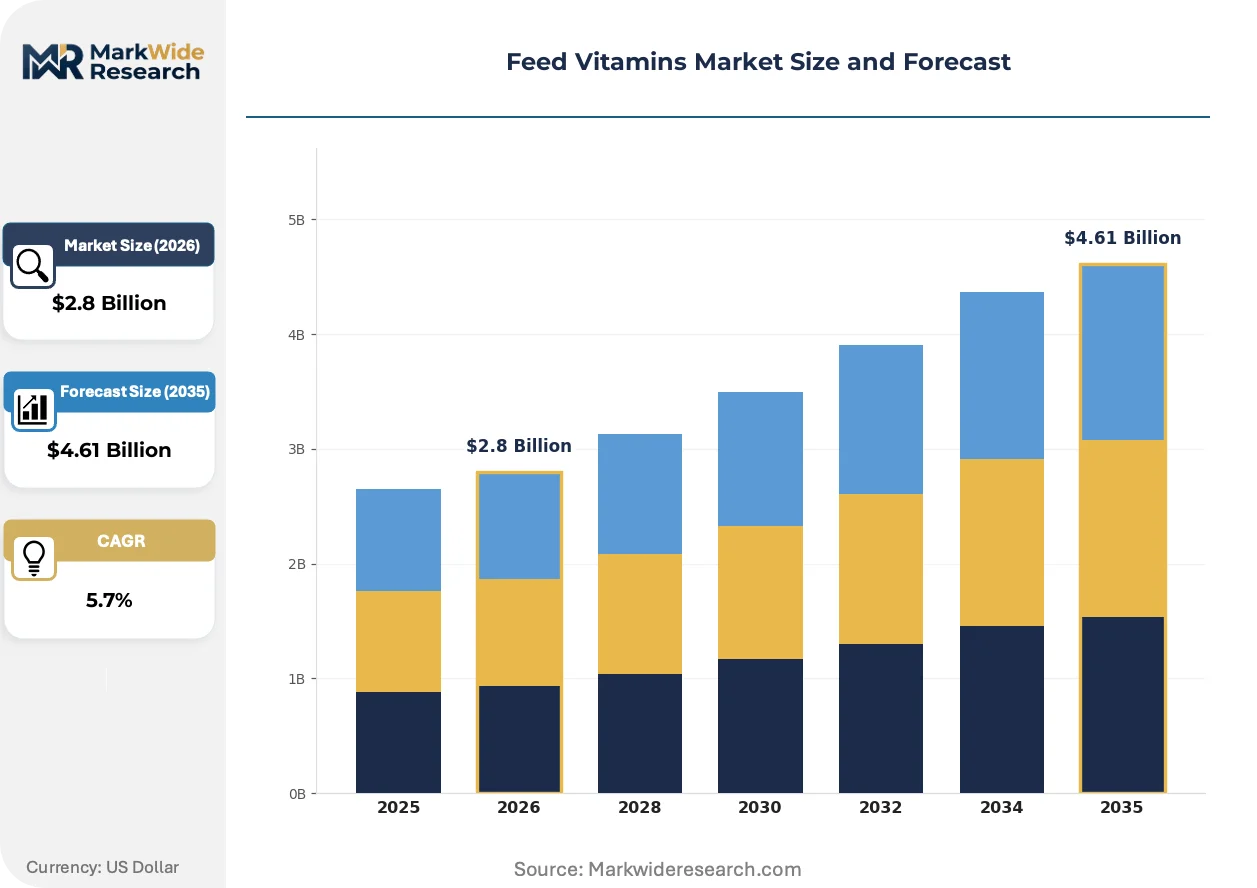
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Soluble Vitamins, Fat-Soluble Vitamins, Amino Acids, Minerals Application: Poultry, Swine, Ruminants, Aquaculture Form: Powders, Granules, Liquids, Tablets End User: Farmers, Feed Manufacturers, Livestock Producers, Veterinary Clinics |
| Companies Covered | Adisseo, Archer Daniels Midland, BASF SE, Brenntag SE, Cargill, DSM Nutritional Products AG, Evonik Industries AG, Lonza Group Ltd, Nutreco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Vitamins Market Emerging Trajectories
Encapsulation chemistry and digital dosing hardware are converging to enable precision micronutrient delivery that manual blending cannot achieve. These advances compress variation coefficients and unlock new regulatory compliance pathways.
Microencapsulation of fat-soluble vitamins is decomposing the traditional trade-off between storage stability and bioavailability. Poultry integrators in the Netherlands and Denmark are retrofitting automated feeding systems with precision dosing hardware at accelerating pace. This technology is decomposing the premium pricing power of legacy premix suppliers who rely on standard emulsion formulations.
REACH authorization timelines for novel vitamin metabolites are lengthening competitive moats for early filers. ECHA's data requirements for reproductive toxicity endpoints force smaller formulators toward commodity vitamin sources. Aquaculture premix specialists face the tightest compliance windows as salmon producers in Norway demand documentation for every metabolite variant in their export-bound feed.
Integrated protein companies are consolidating vitamin procurement under centralized technical teams that bypass traditional distributor relationships. Broiler houses in Brazil's southern states now contract directly with premix formulators for custom B-complex ratios. This concentration is most visible in Mato Grosso, where three integrators control the majority of vitamin E volume and negotiate synthesis-grade pricing previously reserved for pharmaceutical buyers.
Feed Vitamins Market Segmentation
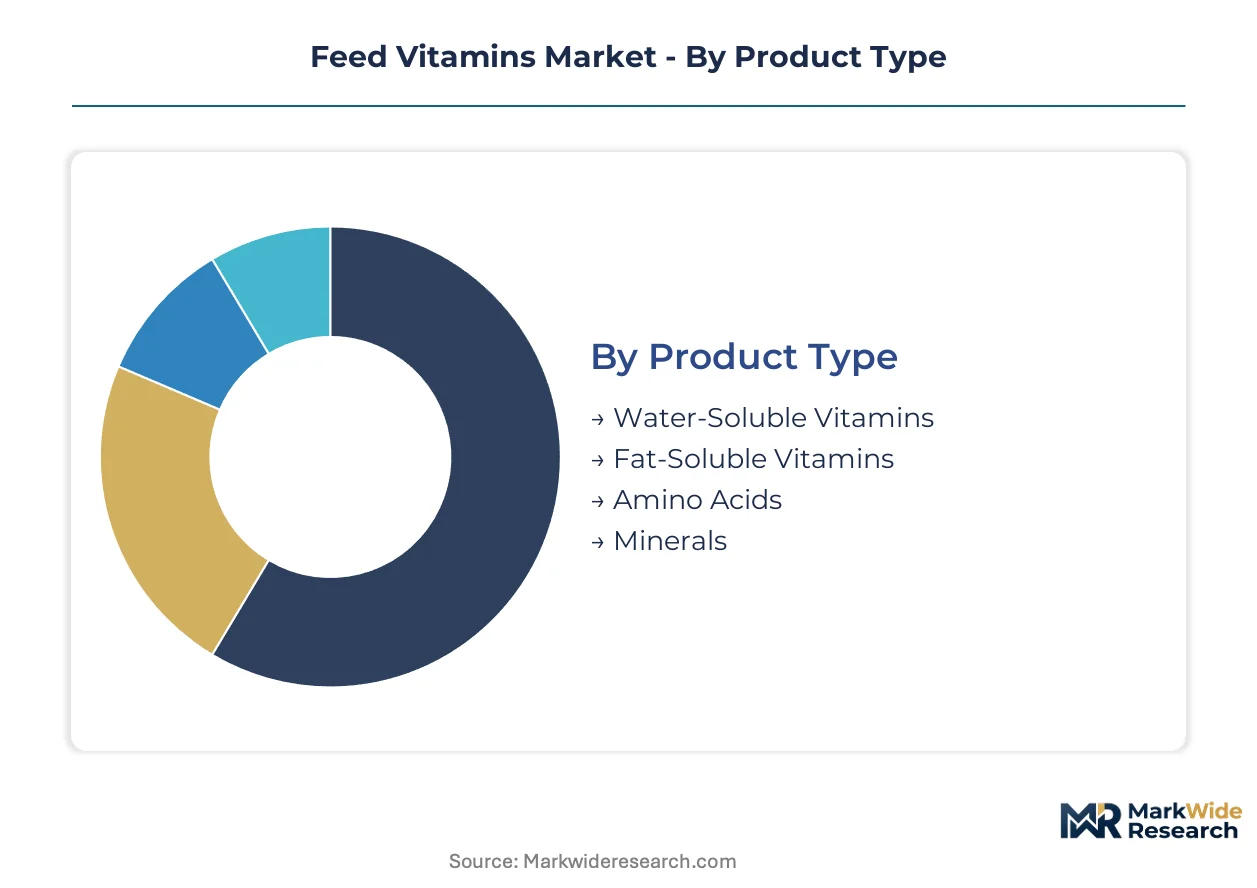
Feed vitamins segment along four intersecting dimensions that determine formulation priorities, distribution economics, and regulatory compliance pathways. Product chemistry dictates stability requirements and dosing precision. Application species define metabolic needs and residue monitoring thresholds. Form factors influence mill integration costs and homogeneity certification.
Product Type:
Water-soluble vitamins dominate domestic consumption across monogastric-heavy markets, while fat-soluble concentrates travel farther to reach ruminant and aquaculture exporters.
- Water-Soluble Vitamins:B-complex formulations including thiamine, riboflavin, and cobalamin synthesized through fermentation processes. Demand concentrates in automated broiler operations across the Netherlands and Denmark, where DSM Nutritional Products AG supplies premixes calibrated to CV under 5% for Farm to Fork compliance.
- Fat-Soluble Vitamins:Vitamins A, D, E, and K requiring emulsion or encapsulation for stability in finished feed. Export-led demand from Norwegian salmon producers drives premium bioavailability formulations, with BASF SE anchoring supply through specialized carotenoid production for egg yolk pigmentation.
- Amino Acids:Lysine, methionine, and threonine produced via fermentation or chemical synthesis. Brazilian integrators in Mato Grosso state standardize these in cattle finishing protocols.
- Minerals:Trace elements including selenium, zinc, and copper bound to organic chelates for improved absorption. Smallholder poultry operations across Nigeria and Kenya lack consistent premix access.
Water-soluble vitamins hold the largest share; momentum sits with fat-soluble formulations as aquaculture intensification accelerates.
Application:
Species-specific metabolic demands create divergent margin structures, with poultry integrating fastest and aquaculture commanding formulation premiums.
- Poultry:Broiler and layer operations requiring precise B-vitamin ratios for feed conversion optimization. European houses retrofit automated dosing systems at accelerating pace, decomposing legacy premix supplier pricing power.
- Swine:Growing-finishing protocols emphasizing biotin and niacin for hoof integrity and lean tissue deposition. Chinese environmental inspections by MEE periodically constrain B-vitamin supply availability.
- Ruminants:Beef cattle finishing in Brazil's Mato Grosso state and dairy operations across the US corn belt. Supplemental vitamin E and beta-carotene address pasture nutrition gaps widened by regenerative agriculture incentives under the US IRA.
- Aquaculture:Shrimp and salmon producers raising stocking densities and requiring stabilized vitamin C formulations. Skeletal deformity prevention drives precise ascorbic acid dosing in Norwegian recirculating systems.
Poultry holds the largest share; aquaculture climbs the fastest as export certification requirements tighten.
Form:
Physical presentation determines blending equipment compatibility and storage stability, with powders suiting high-volume mills and liquids enabling precision integration.
- Powders:Standard premix base requiring sequential dilution to achieve homogeneity. Family-owned feed mills defer capex on automated systems and rely on manual addition with higher variation risk.
- Granules:Agglomerated forms reducing dust and improving flowability for mechanical handling. Preferred by European integrators retrofitting load-cell precision into legacy blenders.
- Liquids:Emulsion or suspension formats enabling post-pelleting application and heat-sensitive nutrient protection. Aquaculture specialists favor these for recirculating system integration.
- Tablets:Compressed single-nutrient or multi-vitamin formats for veterinary-directed supplementation. Veterinary clinics in Kenya and Nigeria dispense these where premix infrastructure is absent.
Powders hold the largest share; liquids gain share fastest where heat treatment of feed is standard practice.
End User:
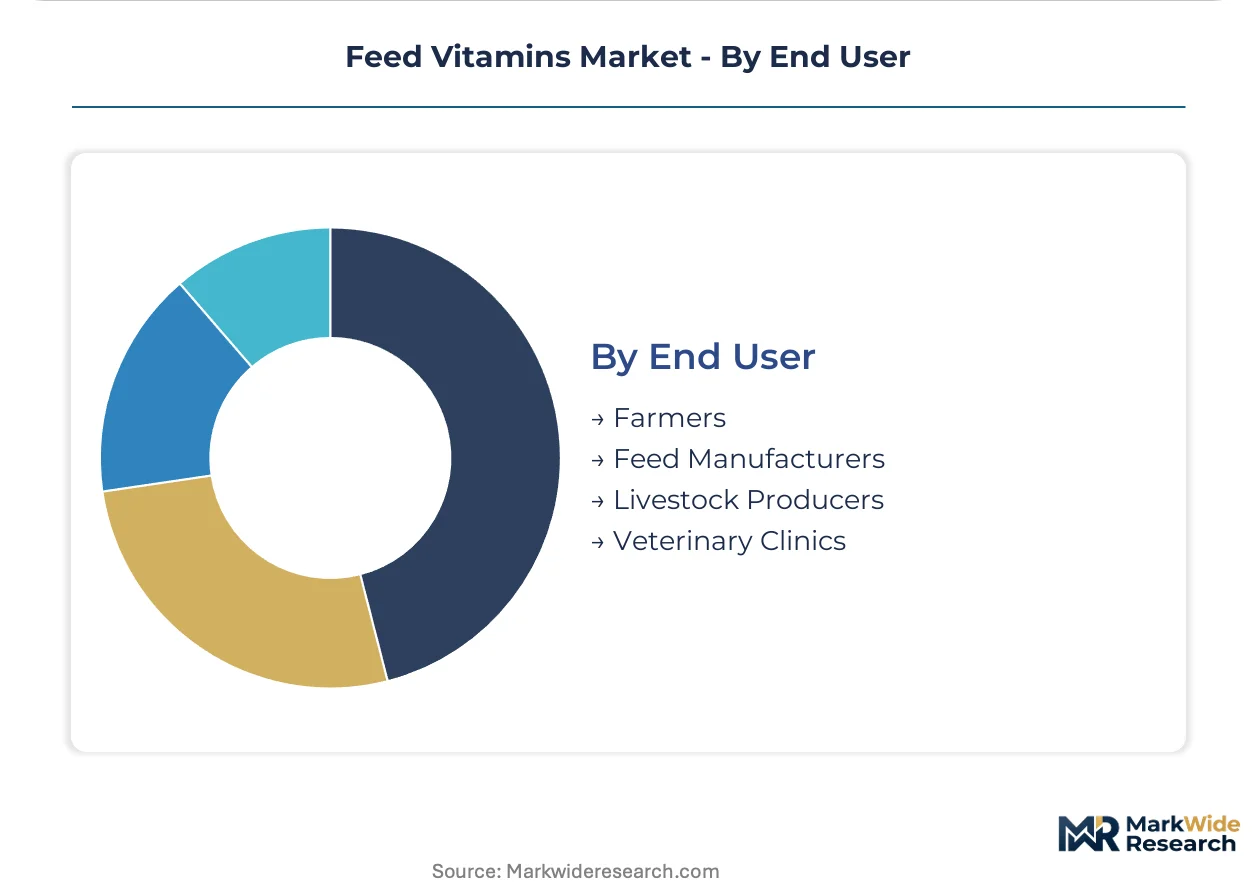
Procurement concentration varies sharply, with feed manufacturers consolidating volume and farmers fragmenting across cooperative tiers.
- Farmers:Smallholder poultry and swine operators purchasing bagged premix or finished feed. Mobile blending units could unlock volume at the village cooperative tier in Sub-Saharan markets.
- Feed Manufacturers:Integrated mills with in-house premix capabilities or toll blending arrangements. Three integrators in Mato Grosso now negotiate synthesis-grade vitamin E pricing previously reserved for pharmaceutical buyers.
- Livestock Producers:Large-scale finishing operations and dairy cooperatives contracting directly with formulators. Brazilian cattle professionalization shifts volume anchors from traditional ranchers to technical integrators.
- Veterinary Clinics:Prescription and therapeutic vitamin supplementation for deficiency correction. REACH authorization timelines for novel metabolites lengthen competitive moats for early filers serving this channel.
Feed manufacturers hold the largest share; livestock producers are concentrating procurement fastest through centralized technical teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports fermentation-derived B-vitamins to Brazilian integrators in Mato Grosso, while European premix formulators supply automated dosing systems to Dutch and Danish poultry houses. This trade-flow corridor concentrates procurement power among three integrators negotiating synthesis-grade vitamin E pricing.
United States
Regenerative agriculture incentives under the US IRA widen seasonal pasture nutrition gaps, elevating demand for supplemental vitamin E and beta-carotene in dairy operations. The FDA's Veterinary Feed Directive constrains antibiotic alternatives and redirects investment toward immunomodulatory vitamin protocols. Feed mills across the Midwest corn belt retrofit legacy blenders with load-cell precision to meet homogeneity certification requirements.
Brazil
Large-scale cattle finishing operations in Mato Grosso state professionalize micronutrient protocols and displace traditional ranchers as volume anchors for bulk vitamin blends. ANVISA residue monitoring thresholds tighten compliance windows for export-bound beef. Three integrators now control the majority of vitamin E procurement and negotiate directly with synthesis-grade suppliers.
China
Environmental inspections by the MEE shutter fermentation facilities unpredictably, tightening global B-vitamin supply during peak demand cycles. The country's dual carbon goals elevate capital requirements for industrial microbiology operations. Zhejiang and Jiangsu provinces concentrate fermentation capacity, where yield optimization specialists command premium recruitment packages.
Netherlands
Broiler houses accelerate retrofitting of automated feeding systems with precision dosing hardware, decomposing legacy premix supplier pricing power. The EU Green Deal's Farm to Fork strategy mandates CV under 5% across sequential dilution batches. DSM Nutritional Products AG supplies premixes calibrated to these thresholds from facilities near Rotterdam.
Norway
Salmon producers intensify stocking densities and require stabilized vitamin C formulations to prevent skeletal deformities in recirculating aquaculture systems. REACH authorization timelines for novel vitamin metabolites lengthen competitive moats for early filers. Bergen and Trondheim clusters concentrate aquaculture premix formulation expertise serving export certification requirements.
Feed Vitamins Market Vendor Landscape
Listed leaders compete with private specialists across formulation technology and geographic coverage. The vendor base fragments between fermentation-based B-vitamin producers, fat-soluble vitamin synthesizers, and premix formulation specialists. Three strategic archetypes dominate: integrated nutrition platforms with captive synthesis, precision premix formulators serving automated systems, and regional distributors with backward integration into blending capacity. Competitive moves center on M&A to secure fermentation talent and strategic partnerships to access novel encapsulation chemistries.
Within the integrated nutrition tier, DSM Nutritional Products AG and BASF SE exemplify divergent specialization strategies. DSM anchors European poultry automation through premix formulation expertise calibrated to Farm to Fork compliance thresholds. BASF occupies a position in fat-soluble vitamin production, particularly specialized carotenoid supply for egg yolk pigmentation. Cargill represents the scale-driven archetype with geographic dominance through captive distribution networks across North American feed mills. These three entities collectively illustrate how synthesis-grade capabilities, automated system integration, and regional channel control constitute distinct competitive vectors.
| Leading Market Players |
|---|
| Adisseo |
| Archer Daniels Midland |
| BASF SE |
| Brenntag SE |
| Cargill |
| DSM Nutritional Products AG |
| Evonik Industries AG |
| Lonza Group Ltd |
| Nutreco |
| Others |
Supply Flow & Price Mechanics
Synthetic astaxanthin displacement by marigold and paprika extracts is redrawing supply geography toward agricultural pigment clusters while compressing premium pricing tiers in European egg markets. This substitution dynamic simultaneously elevates spot-market volatility for fermentation-derived carotenoids and rewards backward-integrated producers with captive natural extraction capacity.
Pricing Analysis
Encapsulation-generation pricing gaps separate microencapsulated fat-soluble formulations from standard emulsion grades and next-gen precision-dosed liquids. Three-tier pricing structure across premium bioavailability, standard stability, and economy bulk blends dominates procurement negotiations. Price differentiation rests on Farm to Fork certification tier and automated system compatibility. Cost compression in standard emulsion tiers is intensifying because Brazilian integrators leverage volume concentration for synthesis-grade terms. Smallholder cooperatives in Sub-Saharan markets exhibit highest price sensitivity; Norwegian salmon producers show least sensitivity due to export certification requirements.
Supply Chain Analysis
Fermentation facility concentration in Zhejiang and Jiangsu provinces creates single-source vulnerability for global B-vitamin availability. China's dual carbon enforcement and Mato Grosso cattle finishing demand draw from overlapping export windows, amplifying allocation rationing risk. Raw material dependencies center on corn syrup feedstocks, molasses substrates, and selenium yeast precursors. Tariff exposure runs through biofuel policy linkages that spike fermentation input costs without formula pass-through mechanisms. Distribution runs through integrated nutrition platforms with captive premix formulation and regional toll-blending networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial microbiology expertise scarcity concentrates yield optimization capability at legacy fermentation producers, creating acquisition premiums for strain-development talent and automated dosing integration skills.
For Market Incumbents: Consolidate fermentation talent pools through targeted recruitment of yield specialists from Zhejiang and Jiangsu facilities threatened by MEE inspection cycles. Deepen backward integration into natural carotenoid extraction to defend margin position against marigold and paprika substitution in European egg markets. Prioritize certification investment for REACH-authorized novel metabolites to extend competitive moats as ECHA data requirements lengthen. For New Entrants and Emerging Players: Differentiate on microencapsulation chemistry for heat-sensitive aquaculture applications where Norwegian producers demand skeletal deformity prevention documentation. Target mobile blending unit deployment across Nigerian and Kenyan village cooperatives lacking premix infrastructure. Pursue go-to-market partnerships with regional distributors possessing existing veterinary clinic relationships for tablet-format therapeutic supplementation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision premix formulators serving automated European poultry houses. Long-term viability favors platforms combining fermentation capacity with cloud-based ration software integration. Watch MEE inspection intensity as inflection indicator for B-vitamin supply availability and corresponding margin expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Extraction | Captures marigold and paprika supply chains displacing synthetic astaxanthin in premium egg markets. |
| Mobile Blending Unit Deployment | Unlocks village cooperative volume across Nigeria and Kenya where premix infrastructure remains absent. |
| REACH Authorization for Novel Metabolites | Lengthens competitive moats as ECHA reproductive toxicity requirements force smaller formulators toward commodity sources. |
| Automated Dosing System Integration | Decomposes legacy premix supplier pricing power in Dutch and Danish broiler house retrofits. |
| Fermentation Talent Acquisition | Secures strain optimization specialists concentrated at legacy B-vitamin producers facing MEE inspection pressures. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation plant managers, premix formulation technical directors, Brazilian integrator procurement leads, and aquaculture nutrition specialists and refined through secondary validation against customs trade data, SEC filings of listed nutrition platforms, ANVISA residue monitoring protocols, and EU Green Deal implementation timelines. Bottom-up volume modeling across water-soluble, fat-soluble, amino acid, and mineral product categories triangulated with top-down expenditure analysis from feed manufacturer procurement disclosures.
Variance decomposition across product chemistry, application species, physical form, and end-user concentration dimensions structured the analytical framework. Modeled segmentation captured formulation precision tiers, residue certification levels, and regional regulatory divergence patterns. CAGRs were derived from slope-consistent trajectory fitting validated against historical input cost pass-through elasticities and capacity expansion announcements. Forecast inputs incorporated biofuel policy linkage effects on fermentation feedstock costs and MEE inspection cycle probability distributions.
Material uncertainties — MEE enforcement intensity, EU Green Deal deadline acceleration, natural pigment substitution velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding strain yield improvement rates and automated system adoption curves. Practitioners should keep alternative scenarios live as regulatory divergence between metabolite-positive and conservative-list jurisdictions evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Fortified Juices Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Natural Vitamins Market