
 Yeast Derivatives Market | 2026-2036
Yeast Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast Derivatives Market Analytics
Subscription-based technical support for fermentation optimization is repositioning how yeast derivative suppliers capture recurring revenue. Lesaffre leverages its global strain library to anchor long-term supply contracts with industrial bakeries. Lallemand competes through specialized probiotic-yeast hybrid formulations that command premium positioning in animal nutrition. Angel Yeast sustains manufacturing scale advantages across Asia-Pacific through integrated molasses-to-extract vertical operations.
Yeast derivatives comprise processed whole-cell or cell-wall fractions including beta-glucans, mannoproteins, nucleotides, and autolyzed peptides, typically manufactured through controlled autolysis or plasmolysis at temperatures between 45°C and 60°C followed by spray-drying or drum-drying to preserve bioactive functionality. These inputs serve primarily as natural flavor potentiators, nutritional fortifiers, and fermentation accelerants across food and life-science applications. Yeast extracts occupy the dominant margin pool given their replacement value for synthetic flavor enhancers in clean-label formulations, while yeast beta glucan generates the fastest trajectory as immunomodulatory claims expand in nutraceutical and companion animal segments. Bulk packaging configurations still control volume economics for industrial buyers, though sachet formats gain share in pharmaceutical and specialty dietary applications where dosing precision and shelf stability matter.
FDA GRAS self-affirmation pathways and USDA organic certification standards govern yeast derivative placement in U.S. food and feed channels, while EU REACH and EFSA novel food assessments constrain beta-glucan health claim substantiation in European markets. China's NMPA and GB standards for food-grade yeast products impose additional strain-documentation requirements that filter market access for imported concentrates. Stakeholders must monitor evolving clean-label enforcement intensity and fermentation-input traceability mandates as these regulatory vectors determine which product forms and geographies offer viable expansion pathways.
Market Dynamics
Clean-label reformulation mandates from major retailers are compressing synthetic additive volumes while redirecting procurement toward autolyzed yeast extracts as drop-in umami replacers across processed food portfolios.
Growth Catalysts
- EU REACH allergen disclosure rules:Food manufacturers face expanded labeling obligations for synthetic flavor enhancers, accelerating yeast autolysate substitution in savory applications.
- Companion animal immunomodulation:Veterinary nutrition formulators integrate beta-glucan fractions into therapeutic pet diets targeting gut-associated lymphoid tissue modulation.
- Molasses supply regionalization:Beet sugar processing concentration in France and Germany anchors captive yeast biomass feedstock for continental extract production.
Market Restraints
- Input cost volatility:Molasses pricing tracks sugar commodity swings, compressing margin predictability for non-integrated extract manufacturers.
- Supply concentration risk:Strain banking and primary culture maintenance capabilities cluster with legacy fermentation houses in Western Europe.
- Regulatory friction:EFSA novel food assessments delay beta-glucan immunomodulatory claim approvals, freezing premium positioning in EU nutraceutical channels.
Strategic Opportunities
- Underpenetrated markets:Southeast Asian processed seafood sectors present white-space demand for nucleotide-rich yeast extracts as natural flavor potentiators.
- Technology convergence:Precision fermentation platforms enable recombinant strain engineering for customized peptide profiles in pharmaceutical applications.
- Channel innovation:Direct-to-compounder digital procurement portals bypass traditional distributor markups for mid-volume feed additive buyers.
Industry Challenges
- Specialized fermentation workforce scarcity:Industrial-scale bioprocess engineering expertise concentrates with aging technical cohorts in established production regions.
- Capex intensity for GMP compliance:Pharmaceutical-grade extract facilities require validated cleanroom suites and continuous monitoring infrastructure.
- Strain documentation complexity:China's NMPA mandates exhaustive genetic stability records for imported yeast concentrates, extending registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast Derivatives Market |
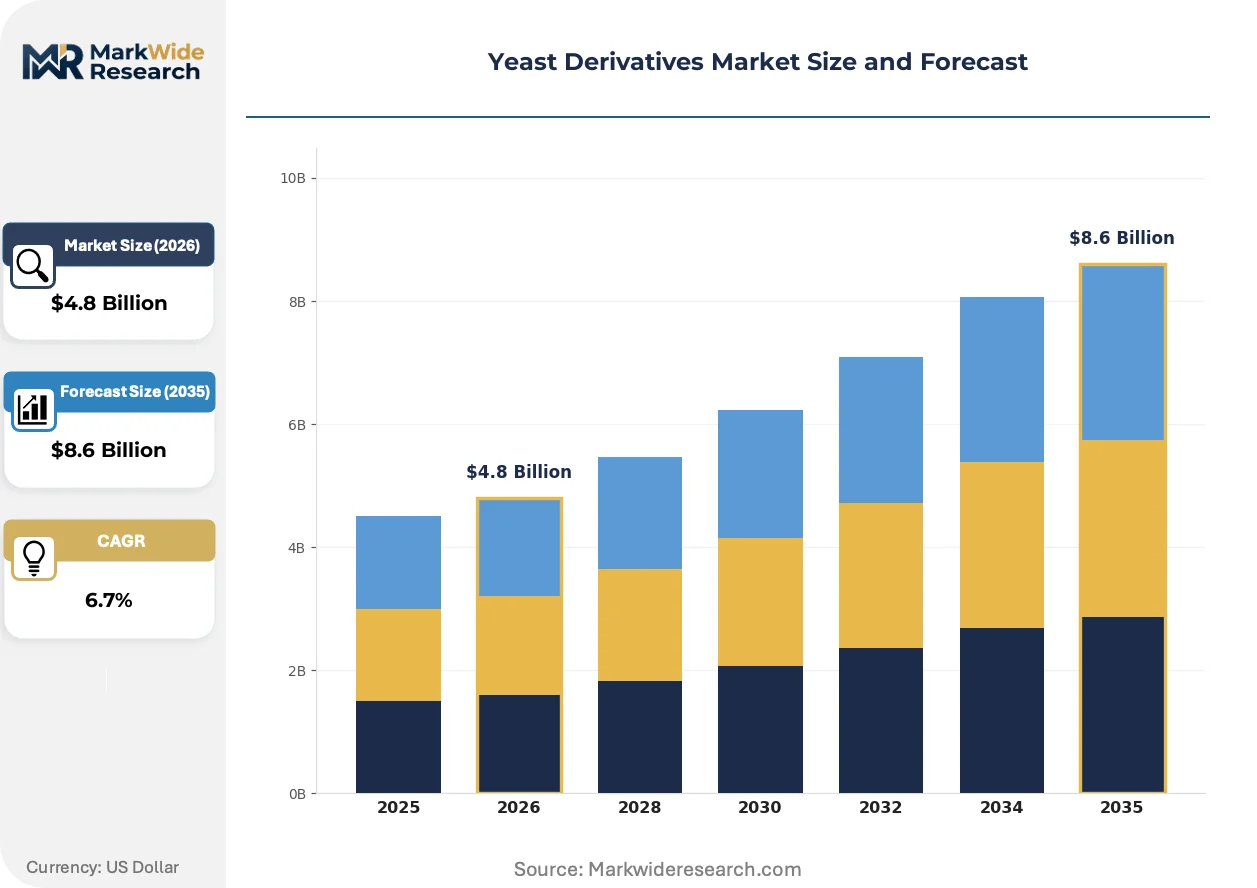
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
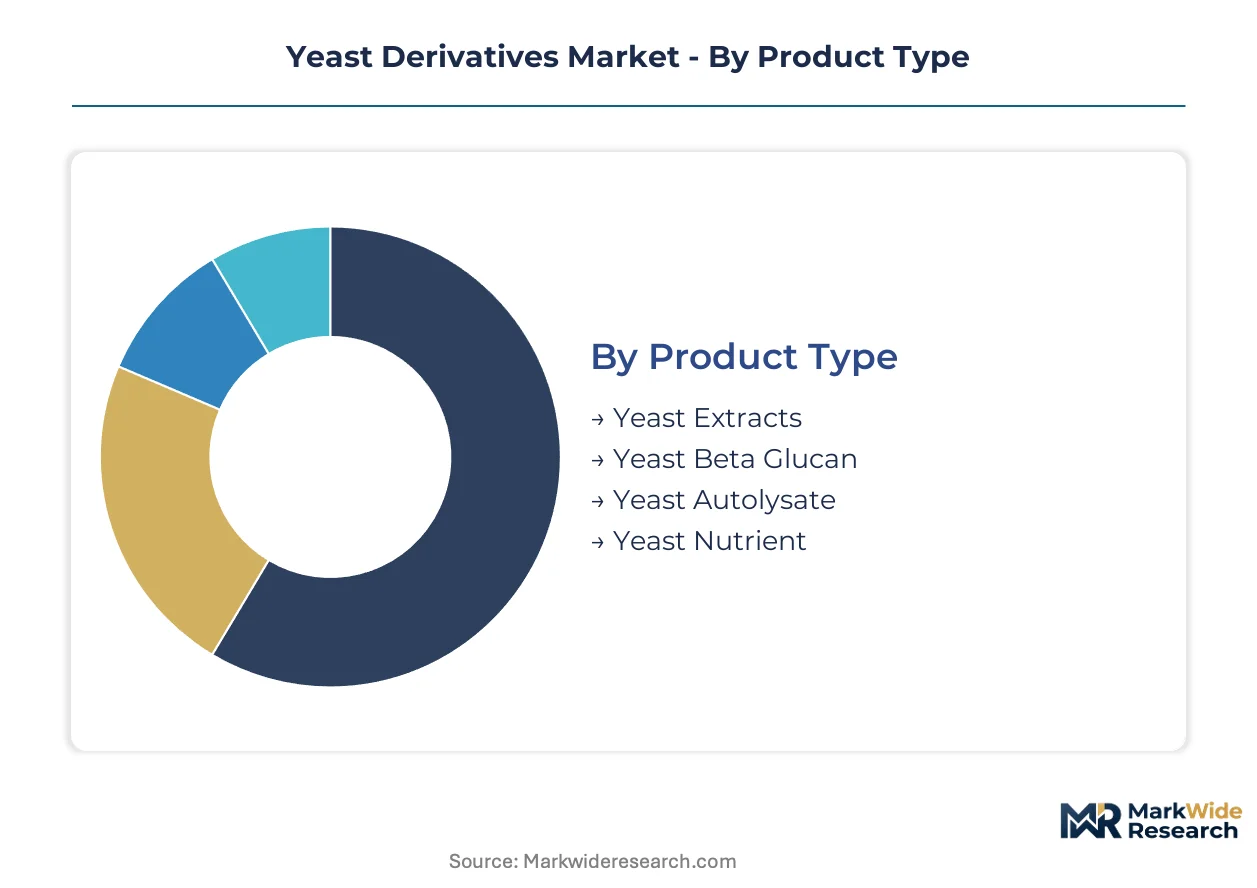
| Segmentation | Product Type: Yeast Extracts, Yeast Beta Glucan, Yeast Autolysate, Yeast Nutrient End User: Food Industry, Nutraceuticals, Animal Feed, Pharmaceuticals Packaging Type: Bulk Bags, Drums, Sachets, Bottles Application: Flavor Enhancer, Nutritional Supplement, Fermentation Agent, Dietary Additive |
| Companies Covered | Lesaffre, Lallemand, Angel Yeast, Archer Daniels Midland, ABF Ingredients, Leiber GmbH, Chr. Hansen, Alltech, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast Derivatives Market Evolving Landscape
Bioprocess intensification and modular fermentation systems are fragmenting production geography while enabling regional supply proximity to end-use clusters.
Continuous fermentation technology is decentralizing yeast derivative manufacturing away from centralized mega-facilities toward distributed 50,000-liter skid-mounted systems. Mid-size food compounders in Poland and Italy adopt these units to secure captive extract supply without long-haul logistics exposure. This shift compresses working capital cycles and enables just-in-time autolysate delivery for seasonal sauce production ramps.
EFSA's evolving position on Article 13.1 health claims is tightening substantiation requirements for beta-glucan immune function messaging in consumer-facing products. Manufacturers now commission human intervention trials rather than relying on in-vitro mechanistic data. German and Dutch nutraceutical brands delay EU launch timelines to accumulate acceptable clinical packages, redirecting near-term volume toward less regulated veterinary channels.
Retail-led clean-label auditing is compressing synthetic additive tolerance thresholds across private-label ready-meal portfolios. Major European supermarket chains now mandate yeast-extract-first formulation hierarchies in savory categories. This procurement preference shift forces contract manufacturers to revalidate entire seasoning matrices, with French and Spanish co-packers reporting 18-month reformulation cycles for legacy soup and sauce lines.
Yeast Derivatives Market Segmentation
Yeast derivative buyers exhibit sharply divergent technical requirements across product categories. Food manufacturers prioritize clean-label umami delivery, while pharmaceutical formulators demand GMP-validated immunomodulatory fractions. Understanding these segmentation fault lines exposes where margin pools concentrate and which specifications command premium positioning.
Product Type:
Cost tier separates commodity buyers from specialty purchasers in this category.
- Yeast Extracts:Concentrated autolyzed preparations rich in free amino acids and nucleotides, typically standardized to 60-80% crude protein content. Food manufacturers in Germany and France dominate procurement as clean-label reformulation mandates displace synthetic flavor enhancers in savory applications. Volume sits with industrial sauce and ready-meal compounders; growth tilts toward low-sodium variants that amplify perceived saltiness through glutamate synergy.
- Yeast Beta Glucan:Cell wall polysaccharide fractions isolated through alkaline extraction, yielding 70-85% purity beta-1,3/1,6-glucan chains. Veterinary nutrition formulators in North America integrate these fractions into therapeutic pet diets targeting gut-associated lymphoid tissue modulation, though EFSA novel food assessments delay comparable health claims in EU consumer channels.
- Yeast Autolysate:Partially hydrolyzed whole-cell preparations retaining cell wall structure and B-vitamin complexes.
- Yeast Nutrient:Standardized growth media components supplying nitrogen, vitamins, and minerals for industrial fermentation processes.
Yeast extracts command the dominant revenue share; beta glucan climbs the fastest as immunomodulatory applications expand.
End User:
Application maturity dictates whether buyers prioritize price stability or technical collaboration.
- Food Industry:Processed food manufacturers, seasoning blenders, and savory flavor houses across France, Spain, and Italy. Retail-led clean-label auditing from major European supermarket chains now mandates yeast-extract-first formulation hierarchies, forcing 18-month reformulation cycles for legacy soup and sauce lines.
- Nutraceuticals:Dietary supplement brands and functional food developers in Germany and the Netherlands. Human intervention trial requirements for EFSA Article 13.1 health claims delay EU launch timelines, redirecting near-term volume toward less regulated veterinary channels.
- Animal Feed:Pet food manufacturers and livestock nutrition compounders.
- Pharmaceuticals:Fermentation-based biologics producers and cell culture media suppliers.
Food industry procurement anchors current volume; nutraceutical applications show steepest expansion trajectory pending regulatory clarity.
Packaging Type:
Volume scale and handling infrastructure separate buyer segments in this dimension.
- Bulk Bags:500-1000 kg flexible intermediate bulk containers for high-throughput industrial compounders. Mid-size food manufacturers in Poland and Italy adopt distributed 50,000-liter skid-mounted fermentation systems to secure captive extract supply without long-haul logistics exposure.
- Drums:200-liter steel or fiber containers for mid-volume buyers with batch processing requirements.
- Sachets:Unit-dose aluminum-laminate pouches for pharmaceutical and specialty dietary applications where dosing precision and shelf stability matter.
- Bottles:Consumer-facing retail formats for home fermentation and culinary use.
Bulk configurations dominate tonnage economics; sachet formats gain share in precision-dosing segments.
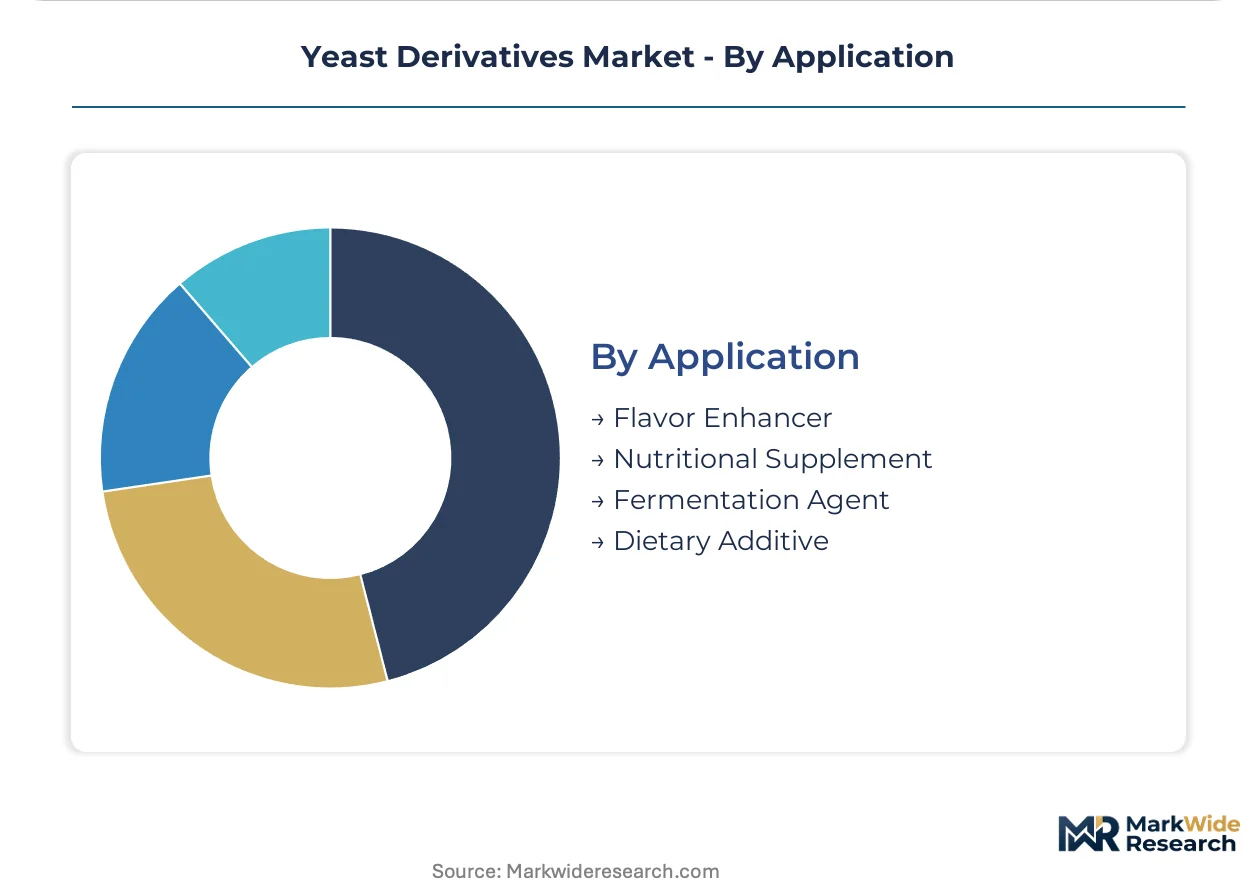
Application:
Functional performance requirements determine specification stringency and supplier qualification depth.
- Flavor Enhancer:Umami delivery through nucleotide-glutamate synergy in processed foods, soups, and sauces. Southeast Asian processed seafood sectors present white-space demand for nucleotide-rich yeast extracts as natural flavor potentiators.
- Nutritional Supplement:B-vitamin fortification and protein enrichment in dietary products.
- Fermentation Agent:Growth factor provision for industrial bioprocesses including bioethanol and biopharmaceutical production.
- Dietary Additive:Prebiotic and immunomodulatory functionality in companion animal and livestock feeds.
Flavor enhancement absorbs the largest volume share; dietary additive applications expand most quickly on pet humanization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Western European fermentation clusters while consumption spreads across reformulating food manufacturers and expanding nutraceutical formulators in multiple continents.
Germany
Beet sugar processing in Bavaria and North Rhine-Westphalia supplies captive molasses feedstock for extract manufacturers serving savory compounders. EFSA novel food assessments delay beta-glucan immunomodulatory claims, redirecting German nutraceutical brands toward veterinary channels. The Rhine-Ruhr industrial corridor hosts primary culture maintenance facilities that anchor continental strain banking capabilities.
United States
Pet food manufacturers in Kansas and Missouri drive beta-glucan procurement for therapeutic companion animal diets targeting gut-associated lymphoid tissue modulation. FDA GRAS self-affirmation pathways govern yeast derivative placement in clean-label reformulations displacing synthetic flavor enhancers. Chicago-area seasoning houses and St. Louis-based feed compounders coordinate just-in-time autolysate delivery for seasonal production ramps.
China
Integrated molasses-to-extract vertical operations in Hubei and Guangdong provinces sustain manufacturing scale advantages for regional food and fermentation media suppliers. NMPA strain-documentation requirements and GB standards for food-grade yeast products filter market access for imported concentrates. Yangtze River Delta processed seafood sectors present white-space demand for nucleotide-rich extracts as natural flavor potentiators.
France
Retail-led clean-label auditing from major supermarket chains mandates yeast-extract-first formulation hierarchies in savory ready-meal portfolios. REACH compliance on allergen labeling redirects formulation choices toward autolysates in sauce and soup production. Lesaffre operates major production facilities in Marcq-en-Baroeul serving European food and feed compounders with standardized autolyzed preparations.
Netherlands
Nutraceutical brands in Utrecht and Rotterdam commission human intervention trials to accumulate EFSA-acceptable clinical packages for beta-glucan immune function messaging. Dutch feed additive buyers adopt direct-to-compounder digital procurement portals bypassing traditional distributor markups. The Eindhoven region hosts modular fermentation system adopters securing captive extract supply without long-haul logistics exposure.
Yeast Derivatives Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across the yeast derivatives landscape. Legacy fermentation houses with integrated molasses supply chains and primary culture maintenance capabilities occupy positions distinct from specialized extract blenders and regional distributors. Three archetypes dominate: integrated biomass processors controlling upstream feedstock, precision fermentation technology licensors, and application-focused compounders blending standardized fractions. Capacity expansion and portfolio diversification toward immunomodulatory fractions constitute the primary competitive vectors as health claim substantiation requirements tighten.
Within the integrated processor tier, Lesaffre and Lallemand exemplify archetypes anchored by strain library depth and global production footprints. Angel Yeast represents the Asia-Pacific scale-driven position through captive vertical operations. These three entities occupy positions that reflect geographic production concentration and end-market specialization rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| Lesaffre |
| Lallemand |
| Angel Yeast |
| Archer Daniels Midland |
| ABF Ingredients |
| Leiber GmbH |
| Chr. Hansen |
| Alltech |
| Cargill |
| Others |
Value Network & Pricing Analysis
Industrial sauce compounders in France and Germany concentrate procurement volumes, anchoring contract-based long-term offtake pricing that favors integrated molasses processors over non-integrated extract blenders. This buyer-architecture compresses margin capture for peripheral suppliers while rewarding strain-banking incumbents with captive feedstock security.
Pricing Analysis
Margin tightening in standard-grade yeast extracts reflects molasses commodity volatility and beet sugar processing regionalization. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates GMP-validated fractions from commodity autolysates. Cost-down pressure on non-integrated manufacturers accelerates as Lesaffre and Lallemand leverage backward integration into captive molasses supply. Mid-volume seasoning houses in Poland and Italy exhibit highest price sensitivity; pharmaceutical formulators in Germany and the Netherlands demonstrate lowest sensitivity given immunomodulatory claim premiums.
Supply Chain Analysis
EFSA novel food qualification gates EU nutraceutical channel access, extending registration timelines for beta-glucan immunomodulatory claims. Manufacturing concentrates in France, Germany, and China, with Hubei and Guangdong provinces hosting integrated molasses-to-extract operations. Raw material flows draw from beet sugar processing in Bavaria and North Rhine-Westphalia, cane molasses in Guangdong, and specialized fermentation nutrients for pharmaceutical-grade production. Single-source vulnerability clusters with legacy strain-banking capabilities in Western European primary culture maintenance facilities. Distribution runs through regional compounder networks and direct-to-feed-procurement portals bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EFSA health claim substantiation requirements and China's NMPA strain-documentation mandates filter subscale competitors from premium positioning tiers. Regulatory compliance capex is forcing weaker players toward acquisition or exit.
For Market Incumbents: Cement strain library depth as a defensive moat through expanded primary culture maintenance capabilities in the Rhine-Ruhr corridor. Add pharmaceutical-grade GMP capacity in Germany or the Netherlands to capture immunomodulatory premium pools before regulatory clarity resolves. Emerging precision fermentation technology licensors threaten legacy autolysis economics; preempt through selective licensing or acquisition of recombinant strain engineering platforms.
For New Entrants and Emerging Players: FDA GRAS self-affirmation pathways in the United States open a window for beta-glucan veterinary nutrition positioning without EFSA trial burdens. Target pet food manufacturers in Kansas and Missouri with nucleotide-rich extract formulations for gut-associated lymphoid tissue modulation claims. Southeast Asian processed seafood sectors in Thailand and Vietnam present the most penetrable white-space for flavor potentiator applications. Pursue direct-to-compounder digital procurement channel entry to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor non-integrated extract blenders in Poland and Italy facing margin compression from molasses volatility. Long-term viability hinges on backward integration potential or modular fermentation technology adoption for regional supply proximity. Watch EFSA Article 13.1 health claim resolution timelines as the inflection signal for EU nutraceutical channel re-entry and premium pricing restoration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Molasses Supply | Secures feedstock cost predictability against sugar commodity swings in Bavaria and North Rhine-Westphalia. |
| GMP Pharmaceutical-Grade Capacity Expansion | Unlocks immunomodulatory premium positioning pending EFSA novel food assessment resolution. |
| Modular Fermentation System Deployment | Enables Polish and Italian compounders to secure just-in-time autolysate delivery without logistics exposure. |
| Direct-to-Compounder Digital Procurement Portal | Bypasses traditional distributor markups for mid-volume feed additive buyers in the Netherlands. |
| Human Intervention Trial Investment for EFSA Substantiation | Accumulates acceptable clinical packages for beta-glucan immune function messaging in German nutraceutical channels. |
Research Methodology
Independent corroboration across fermentation plant managers, procurement leads at savory compounders, regulatory affairs specialists, and veterinary nutrition formulators underwrites the qualitative findings. Secondary validation draws from EFSA novel food assessment databases, FDA GRAS notification filings, NMPA strain-registration records, and customs trade data for molasses and yeast extract flows. Bottom-up volume modeling from individual production facility capacities reconciles with top-down market sizing from end-use consumption patterns.
Comparable-period anchoring to historical autolysate production volumes and beta-glucan immunomodulatory application adoption curves structures the projection horizon. Segmentation dimensions span product type, end-use industry, packaging configuration, and regional regulatory cluster. CAGRs derive from trend extrapolation moderated by input cost elasticity estimates and substitution dynamics between synthetic flavor enhancers and yeast-derived alternatives. Molasses supply regionalization and clean-label reformulation intensity constitute primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation-based recombinant strain engineering would alter the outlook. Forecasts reflect assumptions regarding EFSA regulatory resolution pace, REACH allergen labeling enforcement intensity, and NMPA documentation requirement stability. A model refresh is warranted upon material change in health claim substantiation timelines or molasses supply concentration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
L-Arabinose Market
Ingredients
Commercial Amino Acids Market
Ingredients
Quark Powder Market
Ingredients
Cocoa Butter Market
Ingredients
Soluble Fibers Market
Ingredients
Boysenberry Extract Market
Ingredients
Microencapsulated Oil Market
Ingredients
Modified Flour Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Non-GMO Oil Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Mung Bean Protein Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Green Gram Powder Market