
 Vitamin B12 Drops Market | 2026-2036
Vitamin B12 Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin B12 Drops Market Insights
Precision fermentation and biosynthetic cobalamin production is rewriting cost structures for active pharmaceutical-grade B12. Garden of Life leverages organic certification and whole-food positioning to command premium shelf placement in natural retail. Thorne sustains clinician-channel loyalty through NSF Certified for Sport formulations and practitioner-exclusive distribution. Nordic Naturals anchors its portfolio with third-party purity testing that resonates with quality-sensitive buyers.
Vitamin B12 drops constitute aqueous or glycerin-based solutions delivering cobalamin compounds—typically cyanocobalamin or methylcobalamin—via sublingual or oral administration, with standard concentrations ranging from 500 mcg to 5000 mcg per serving to address deficiency states or support metabolic function. Liquid Drops formulations capture the largest volume share due to dosing flexibility and pediatric accessibility, while Medical Treatments applications carry the highest margin pools as clinicians prescribe therapeutic-grade products for pernicious anemia and post-surgical malabsorption. The Oral delivery mode dominates household consumption, though Buccal formats attract consumers seeking bypass of gastrointestinal degradation.
FDA Current Good Manufacturing Practice regulations for dietary supplements mandate identity testing and contamination controls that elevate compliance costs for new entrants. EFSA health claim evaluations and EU Food Supplements Directive harmonization constrain permissible marketing language around energy and neurological benefits, reshaping label strategy for brands selling into European markets. Stakeholders must monitor evolving pharmacovigilance requirements for high-dose cobalamin products as regulators scrutinize long-term safety thresholds.
Market Dynamics
Precision fermentation is collapsing legacy extraction economics for pharmaceutical-grade cobalamin, forcing incumbent suppliers to reconfigure cost structures or surrender margin to biosynthetic entrants.
Growth Catalysts
- Aging demographics in Germany and Japan:Elderly populations seek sublingual B12 for nutritional enhancement, creating sustained demand for liquid formulations that bypass gastric absorption issues.
- FDA Current Good Manufacturing Practice mandates:Rigorous identity testing and contamination controls elevate quality thresholds, filtering out substandard competitors and rewarding compliant manufacturers with shelf access.
- Direct-to-consumer e-commerce expansion:United States and United Kingdom consumers bypass traditional retail, shifting volume toward subscription models and specialized wellness platforms.
Market Restraints
- Input cost volatility in pharmaceutical-grade glycerin:Refined vegetable-derived carriers face price pressure from biofuel feedstock competition, squeezing formulation margins.
- Supply concentration in Chinese API manufacturing:Bulk cyanocobalamin active pharmaceutical ingredients cluster among a handful of fermentation facilities, creating single-source vulnerability.
- EU Food Supplements Directive harmonization:EFSA health claim evaluations constrain permissible marketing around energy and neurological benefits, limiting differentiation on European labels.
Strategic Opportunities
- Pediatric accessibility gaps:Liquid drops bypass swallowing difficulties in children, opening formulation partnerships with family medicine networks in underpenetrated markets.
- Buccal delivery technology convergence:Mucoadhesive polymers combined with metered-dose spray devices enable bypass of gastrointestinal degradation for malabsorption patients.
- India PLI scheme for nutraceuticals:Production-linked incentives for active ingredient manufacturing attract contract fermentation investment, reducing import dependence for domestic brands.
Industry Challenges
- Analytical chemistry talent scarcity:Cobalamin isomer identification and stability testing require specialized chromatography expertise that outpaces current training pipeline output.
- NSF Certified for Sport timeline compression:Athletic-grade certification demands rigorous banned-substance screening that extends product launch cycles by 8-14 months.
- Legacy ERP integration with track-and-trace mandates:FDA serialization requirements force mid-tier manufacturers to overhaul inventory systems without dedicated IT capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin B12 Drops Market |
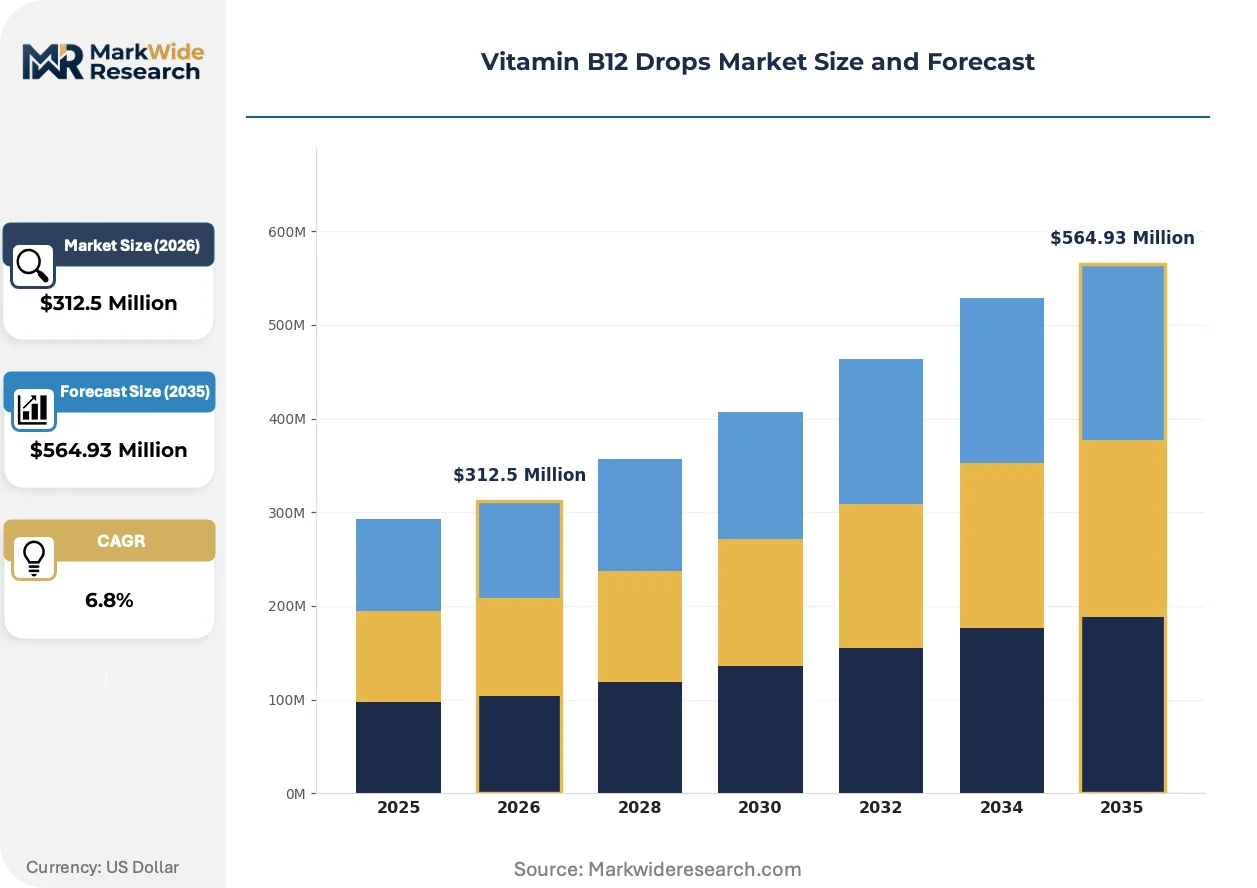
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Drops, Sublingual Tablets, Injectable Solutions, Gummies Application: Dietary Supplements, Nutritional Enhancement, Energy Boosting, Medical Treatments Delivery Mode: Oral, Injectable, Transdermal, Buccal Customer Type: Health-Conscious Consumers, Athletes, Patients, Elderly Population |
| Companies Covered | Garden of Life, Nature's Bounty, Carlyle, Global Healing Center, Pure Encapsulations, Thorne, HUM Nutrition, OLLY, Nordic Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin B12 Drops Market Trends and Innovations
Biosynthetic production methods and regulatory digitization are compressing traditional competitive moats, while channel fragmentation rewards agile fulfillment architectures over legacy wholesale relationships.
Cell-free enzymatic cobalamin synthesis is collapsing the capital intensity barrier that protected incumbent fermentation operators for decades. Biotechnology startups in Switzerland and the Netherlands now achieve pharmaceutical-grade yields without stainless-steel bioreactor farms. Contract manufacturers serving Nordic Naturals and Thorne are piloting these platforms to decouple volume from geographic production clusters.
EFSA novel food assessments are tightening evidentiary standards for methylcobalamin formulations seeking European market entry. Brands must now submit comprehensive toxicological dossiers that extend approval timelines and favor well-capitalized incumbents with dedicated regulatory affairs functions. Smaller direct-to-consumer labels are redirecting launch sequences toward United States FDA notification pathways rather than Brussels pre-authorization.
Sublingual absorption claims now dominate consumer search behavior, displacing generic "high potency" positioning in e-commerce metadata. Amazon and iHerb algorithmic ranking rewards products with verified dissolution studies, pushing brands toward third-party pharmacokinetic validation. Clinician-channel loyalty programs from Thorne and Garden of Life emphasize bioavailability certificates as countermeasures to commoditized liquid formulations.
Vitamin B12 Drops Market Segmentation
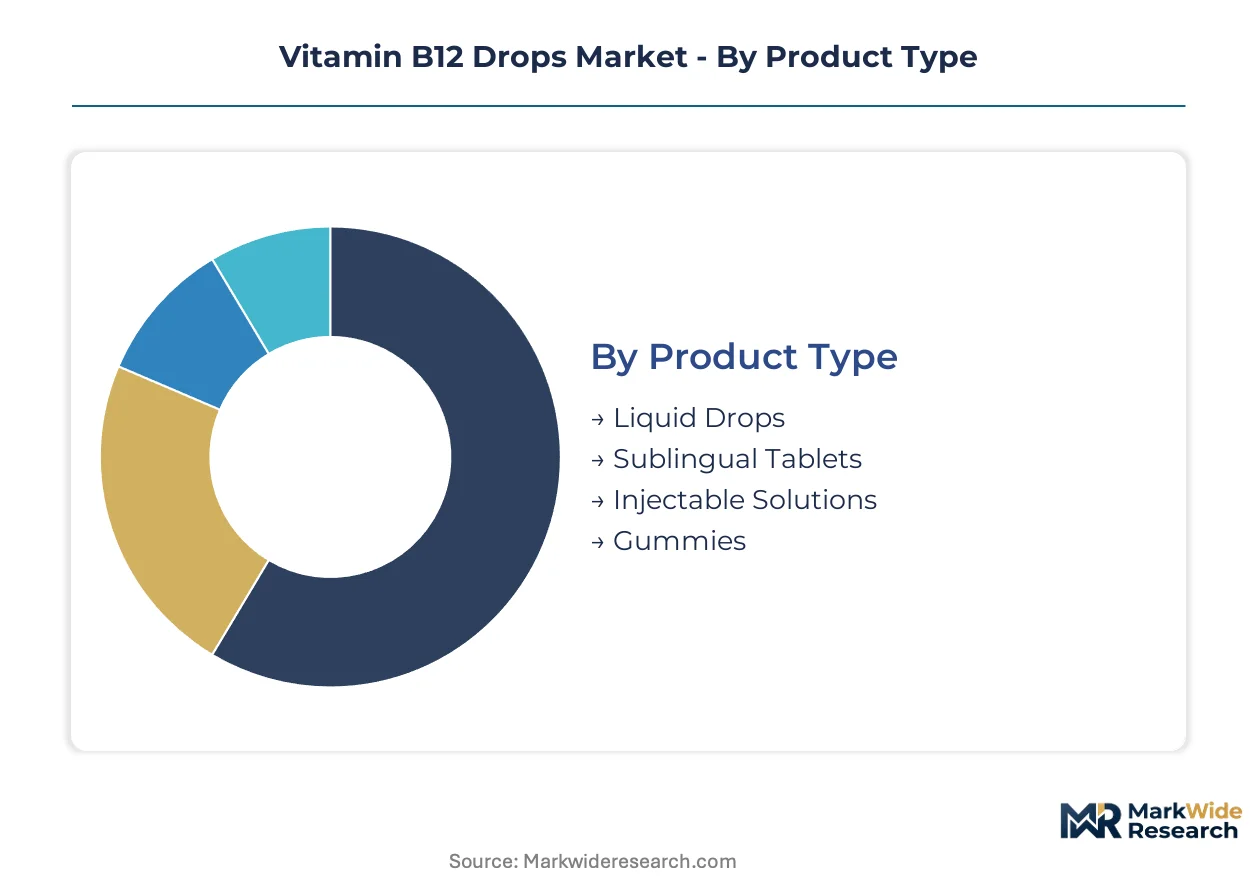
Segmentation in Vitamin B12 drops reveals divergent margin profiles and channel requirements across formulation formats and user populations. Manufacturers configure production lines and compliance investments differently depending on whether they target clinical prescription workflows or direct-to-consumer wellness platforms.
Product Type:
After-sales intensity varies sharply across formats, with clinical-grade injectables demanding cold-chain support and patient education that liquid drops simply do not require.
- Liquid Drops:Aqueous or glycerin-based solutions delivering 500-5000 mcg cobalamin per serving enable flexible micro-dosing for pediatric and geriatric populations. Demand concentrates in United States and United Kingdom e-commerce channels where subscription models bypass retail markup.
- Sublingual Tablets:Compressed methylcobalamin or cyanocobalamin formulations dissolve under the tongue to bypass gastric degradation. Athletes and biohackers in Germany favor these for portability and precise dosing during training cycles.
- Injectable Solutions:Pharmaceutical-grade hydroxocobalamin for intramuscular administration in clinical settings.
- Gummies:Gelatin or pectin matrices masking B12 bitterness with flavor systems for children and flavor-sensitive adults.
Liquid Drops holds the largest share; momentum sits with Sublingual Tablets.
Application:
Margin stratification follows regulatory burden, with Medical Treatments commanding premium pricing that Dietary Supplements cannot approach due to marketing constraint.
- Dietary Supplements:General wellness positioning for consumers seeking metabolic support without diagnosed deficiency. FDA notification pathways and EFSA health claim restrictions limit differentiation to dissolution speed and carrier purity.
- Nutritional Enhancement:Targeted supplementation for vegetarians, vegans, and post-bariatric surgery patients with documented absorption impairment. Clinician-channel brands like Thorne dominate this specification-sensitive segment.
- Energy Boosting:Positioning around fatigue reduction and cognitive clarity, constrained by EFSA evaluations that reject unsubstantiated neurological claims.
- Medical Treatments:Prescription-grade products for pernicious anemia, post-surgical malabsorption, and confirmed B12 deficiency states. PMDA in Japan and FDA in the United States enforce batch-level potency verification that elevates manufacturing costs.
Medical Treatments captures the highest margins; Nutritional Enhancement is climbing the fastest.
Delivery Mode:
Supply concentration in oral formats is fragmenting as buccal and transdermal alternatives capture malabsorption patients unwilling to self-inject.
- Oral:Swallowed liquid drops and capsules relying on intrinsic factor-mediated ileal absorption. Household consumption in the United States and United Kingdom dominates volume, though gastric bypass patients increasingly reject this route.
- Injectable:Intramuscular hydroxocobalamin administered in clinical settings or via home nursing for severe deficiency. Japanese geriatric clinics and German hematology practices sustain demand despite patient aversion to needles.
- Transdermal:Patches delivering cobalamin through dermal absorption, still marginal due to pharmacokinetic variability.
- Buccal:Mucoadhesive films and sprays absorbing through oral mucosa to bypass gastrointestinal degradation entirely. Swiss and Dutch biotechnology firms are piloting metered-dose polymer systems for post-surgical malabsorption patients.
Oral maintains dominant volume; buccal formats are gaining share fastest.
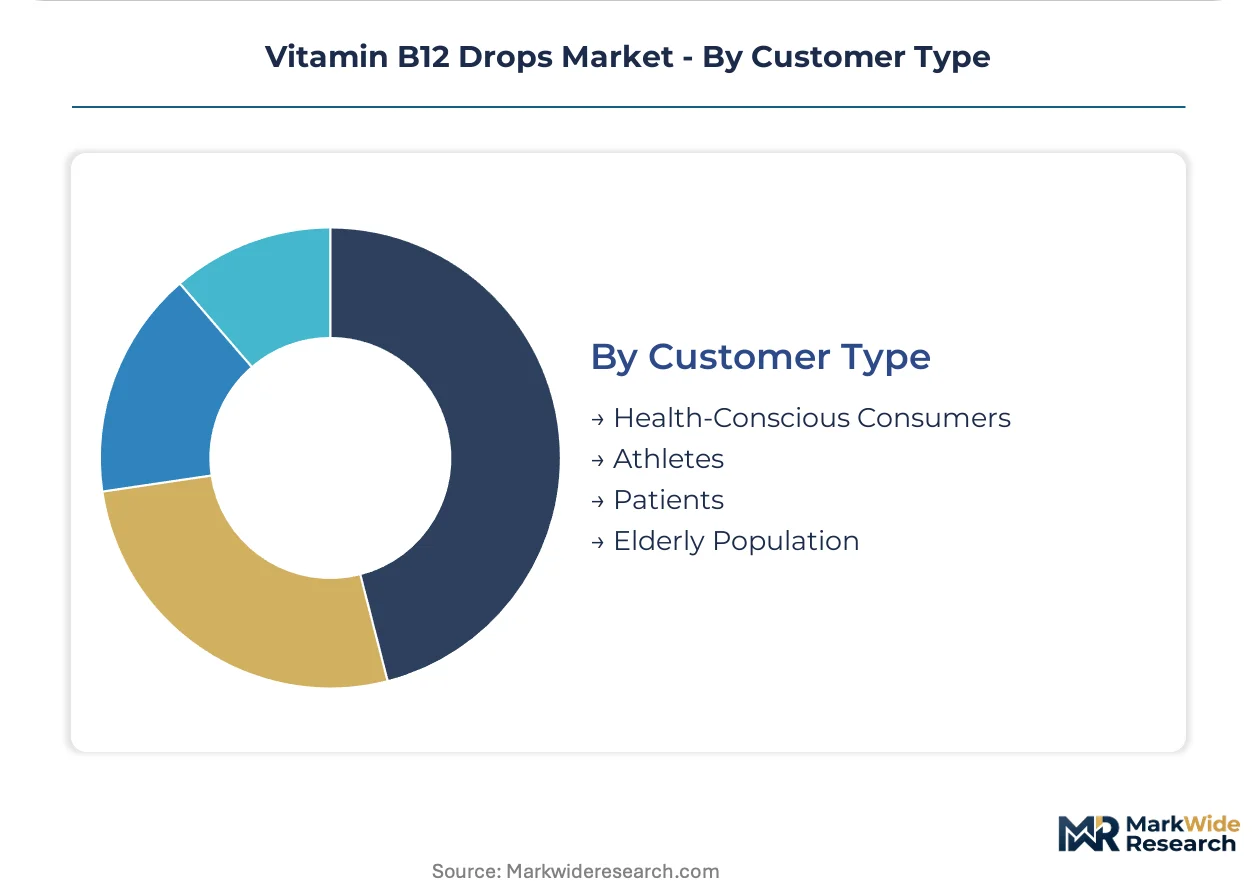
Customer Type:
Purchasing behavior diverges by sophistication level, with Athletes and Patients demanding certificate-backed quality that Health-Conscious Consumers rarely verify.
- Health-Conscious Consumers:Wellness-focused buyers seeking preventive supplementation through Amazon, iHerb, and direct-to-consumer brand sites. Algorithmic ranking rewards verified dissolution studies and third-party purity testing.
- Athletes:NSF Certified for Sport and Informed Sport verification drives loyalty among competitive and recreational athletes subject to anti-doping protocols. Thorne and Nordic Naturals anchor this specification-heavy segment.
- Patients:Diagnosed deficiency or malabsorption conditions requiring clinician oversight and prescription-grade products. Japanese elderly and German pernicious anemia patients sustain demand for therapeutic-grade formulations.
- Elderly Population:Sublingual and liquid formats addressing age-related gastric acid decline and medication-induced absorption interference. Aging demographics in Germany and Japan concentrate demand here.
Health-Conscious Consumers represent the largest addressable base; Athletes show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese active pharmaceutical ingredient manufacturers export bulk cyanocobalamin to formulation facilities in the United States, Germany, and Japan, creating a trade-flow corridor that shapes regional supply security calculations.
United States
Direct-to-consumer e-commerce channels concentrate demand among health-conscious consumers seeking subscription-based liquid formulations. FDA Current Good Manufacturing Practice regulations mandate identity testing and contamination controls that elevate compliance costs for new entrants. The Pacific Northwest hosts several specialized wellness platforms that algorithmically rank products with verified dissolution studies.
Germany
Aging demographics drive sustained uptake of sublingual B12 among elderly consumers with gastric absorption impairment. EFSA health claim evaluations constrain permissible marketing language around energy and neurological benefits, reshaping label strategy for brands selling into European markets. Bavaria houses multiple contract fermentation facilities serving clinician-channel brands.
Japan
Geriatric clinics sustain prescription-grade demand for therapeutic hydroxocobalamin formulations addressing pernicious anemia. PMDA enforces batch-level potency verification that elevates manufacturing costs for domestic and imported products. The Kanto region around Tokyo anchors distribution networks for both clinical and over-the-counter segments.
United Kingdom
Subscription wellness platforms bypass traditional retail markup, shifting volume toward specialized direct-to-consumer channels. EU Food Supplements Directive harmonization constrains marketing differentiation for brands seeking continental European expansion. Greater London serves as the primary logistics hub for cross-border e-commerce fulfillment.
India
Domestic brands seek to reduce import dependence through contract fermentation investment attracted by production-linked incentives. FSSAI regulations govern dietary supplement quality thresholds while the central bank monitors foreign exchange exposure for API procurement. Maharashtra and Gujarat host emerging nutraceutical manufacturing clusters.
Vitamin B12 Drops Market Competitive Landscape
On the supply side, the industry is fragmented across three distinct tiers: multinational wellness conglomerates with broad distribution reach, clinician-channel specialists with certification-heavy positioning, and direct-to-consumer pure-plays with agile fulfillment architectures. Strategic archetypes include organic-certified whole-food formulators, NSF Certified for Sport holders targeting athletic verification, and biosynthetic technology adopters. Competitive moves concentrate on portfolio diversification into adjacent delivery formats and strategic partnerships with contract manufacturers piloting precision fermentation platforms.
Within the organic-certified tier, Garden of Life exemplifies whole-food positioning that commands premium shelf placement in natural retail channels. Thorne occupies a position within the clinician-channel vector, sustaining loyalty through practitioner-exclusive distribution and sport-verified formulations. Nordic Naturals anchors the third-party purity testing segment, resonating with quality-sensitive buyers who prioritize certificate-backed verification. These three entities represent the dominant strategic archetypes that shape competitive dynamics across formulation, certification, and channel positioning.
| Leading Market Players |
|---|
| Garden of Life |
| Nature's Bounty |
| Carlyle |
| Global Healing Center |
| Pure Encapsulations |
| Thorne |
| HUM Nutrition |
| OLLY |
| Nordic Naturals |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-to-Rotterdam maritime corridor carries bulk cyanocobalamin API shipments that face biofuel feedstock competition for refined vegetable glycerin carriers, creating cost cascades that separate pharmaceutical-grade formulations from commodity dietary supplements and concentrate margin pressure on mid-tier contract manufacturers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, clinician-channel, and mass-market economy levels reflects the technology-generation gap between precision fermentation biosynthesis, legacy fermentation extraction, and synthetic cobalamin analogues. Certification grade—specifically NSF Certified for Sport versus standard GMP—drives price differentiation alongside volume scale and vertical integration depth. Cost compression in mass-market liquid drops is intensifying because Chinese API producers face input volatility in pharmaceutical-grade glycerin. Health-conscious consumers on Amazon and iHerb show highest price sensitivity, while Japanese geriatric clinics and German hematology practices demonstrate lowest sensitivity due to prescription-grade reimbursement pathways.
Supply Chain Analysis
Upstream feedstock dependence on corn-derived dextrose and refined vegetable glycerin draws from agricultural commodity markets vulnerable to biofuel policy shifts. Supply concentrates in Chinese fermentation facilities for bulk cyanocobalamin API, with formulation finishing clustered in the United States, Germany, and Switzerland. Single-source vulnerability in Zhejiang and Shandong province API manufacturing creates structural risk from regulatory inspection backlogs or export license suspensions. Distribution runs through direct-to-consumer e-commerce platforms in the United States and United Kingdom, bypassing traditional wholesale pharmaceutical channels for non-prescription segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vitamin B12 Drops Market operates as a regulatory entrenchment story where FDA Current Good Manufacturing Practice mandates and EFSA novel food assessment timelines create switching costs that protect incumbent positions against biosynthetic technology disruptors.
For Market Incumbents: Entrench position through captive supply of pharmaceutical-grade methylcobalamin via precision fermentation partnerships in Switzerland and the Netherlands, while extending NSF Certified for Sport verification across liquid drop formats to defend against emerging biosynthetic entrants threatening legacy extraction economics. Capacity addition in Bavaria contract fermentation facilities reinforces clinician-channel loyalty against direct-to-consumer pure-plays.
For New Entrants and Emerging Players: India PLI scheme contract manufacturing zones offer the most penetrable geography for production-linked incentive capture, enabling domestic brands to reduce API import dependence and serve underpenetrated pediatric accessibility gaps through family medicine network partnerships. A buccal delivery technology convergence go-to-market angle—metered-dose mucoadhesive polymer systems—bypasses gastrointestinal degradation claims that dominate e-commerce search algorithms.
For Investors and Strategic Acquirers: Clinician-channel specialists with dedicated regulatory affairs functions and practitioner-exclusive distribution represent the priority acquisition archetype, given EFSA novel food assessment timeline extensions that favor well-capitalized incumbents. Long-term viability across the projection horizon hinges on precision fermentation platform adoption. The signal to watch is biosynthetic yield parity announcements from Swiss and Dutch biotechnology startups that would collapse incumbent cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Adoption | Cell-free enzymatic synthesis collapses capital intensity for pharmaceutical-grade cobalamin production. |
| NSF Certified for Sport Portfolio Extension | Athletic-grade verification captures specification-sensitive buyers in anti-doping protocol segments. |
| Buccal Delivery Technology Partnership | Mucoadhesive polymer systems enable gastrointestinal bypass claims for malabsorption patients. |
| India PLI Scheme Contract Manufacturing Investment | Production-linked incentives reduce API import dependence for domestic nutraceutical brands. |
| Direct-to-Consumer Subscription Model Launch | Algorithmic ranking on Amazon and iHerb rewards verified dissolution studies and third-party purity testing. |
Research Methodology
A standing panel of regulatory affairs directors at clinician-channel brands, contract fermentation facility managers in Bavaria and Maharashtra, e-commerce platform category managers, and hospital procurement specialists at Japanese geriatric clinics provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA warning letter databases, EFSA novel food assessment registers, FSSAI dietary supplement quality notifications, and customs trade data for cyanocobalamin API shipments. Bottom-up volume modeling across formulation types and top-down macroeconomic triangulation anchored the analytical framework.
Scenario-bracketing around precision fermentation adoption rates, EFSA health claim evaluation timelines, and Indian PLI scheme uptake generated bounded projections across the analysis window. Segmentation dimensions modeled included product type, application, delivery mode, customer type, and regional regulatory cluster. CAGRs derived from volume-price elasticity curves and input cost trajectory assumptions. Forecast inputs incorporated biofuel feedstock competition intensity for pharmaceutical-grade glycerin and PMDA batch-level potency verification enforcement patterns.
Practitioners should monitor biosynthetic yield parity announcements, EFSA novel food assessment backlog durations, and Chinese API export license suspension patterns for early signals of forecast revision. Cross-checking against FDA dietary supplement GMP inspection citation trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Vitamin a in Feed Additives Market