
 North America Vitamin Fortified and Mineral Enriched Food and Beverages Market | 2026-2036
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market Analytics
The manufacturing scale gap between multinational and mid-tier producers is unwinding as automation costs decline. General Mills Inc. leverages its cereal fortification infrastructure to dominate the breakfast segment. Nestlé SA anchors its position through dairy-based delivery systems. Abbott Laboratories specializes in clinical nutrition formulations for medical channels.
Vitamin fortified and mineral enriched food and beverages denote products with added micronutrients—vitamins A, D, B-complex, iron, zinc, calcium—delivered through spray-drying, microencapsulation, or direct blending to address dietary deficiencies and support targeted health outcomes. Ready-to-drink beverages command premium shelf positioning as consumers prioritize convenience in functional consumption. Fortified dairy maintains mature volume leadership while nutritional bars capture margin pools through protein-vitamin hybrid positioning.
The FDA governs nutrient content claims and fortification ceilings under 21 CFR 101, while USDA's National Organic Program constrains permitted additives in certified products. Health Canada and PMRA coordinate cross-border standards through the Canada-U.S. Regulatory Cooperation Council. Stakeholders must monitor evolving bioavailability testing requirements and state-level sugar reduction mandates that could force reformulation across the category.
Market Dynamics
The FDA's updated nutrition labeling rules under 21 CFR 101 are forcing systematic reformulation across the North American fortified food sector. This regulatory compression is reshaping how manufacturers balance micronutrient density against sugar reduction mandates and clean-label positioning.
Growth Catalysts
- Clinical nutrition channels:Hospital discharge protocols and homecare nutrition programs in the US and Canada are expanding prescription-strength fortified product reimbursement.
- 21 CFR 101 modernization:The FDA's revised Daily Value benchmarks and added sugar disclosure requirements are accelerating premium positioning for inherently nutritious fortified formulations.
- Microencapsulation advances:Lipid-shell and polymer-matrix encapsulation technologies are improving heat-stable vitamin retention in baked and extruded applications.
Market Restraints
- Input cost volatility:Vitamin premix concentrates and chelated mineral complexes face price pressure from concentrated supplier bases in China and India.
- Technical bioavailability ceilings:Iron-fortified dairy and calcium-zinc competitive inhibition limit efficacy claims without expensive chelation or separation technologies.
- USDA Organic Program constraints:The National Organic Program's restricted substance lists block synthetic nutrient forms in certified products, constraining fortification options.
Strategic Opportunities
- Pediatric nutrition white space:Mexico's school feeding programs and early childhood nutrition initiatives present underexploited demand for fortified beverages and shelf-stable dairy.
- Precision fermentation convergence:Bioactive vitamin B12 and vitamin D3 from microbial production are converging with plant-based dairy alternatives to create novel delivery systems.
- Direct-to-clinic distribution:Registered dietitian networks and hospital outpatient pharmacies represent emerging channels bypassing traditional retail slotting constraints.
Industry Challenges
- Formulation scientist scarcity:The specialized knowledge required for stability testing, nutrient interaction mapping, and accelerated shelf-life validation is concentrating among a limited pool of experienced technologists.
- Dual certification complexity:Simultaneous pursuit of USDA Organic and FDA medical food designations creates conflicting formulation requirements and extended timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vitamin Fortified and Mineral Enriched Food and Beverages Market |
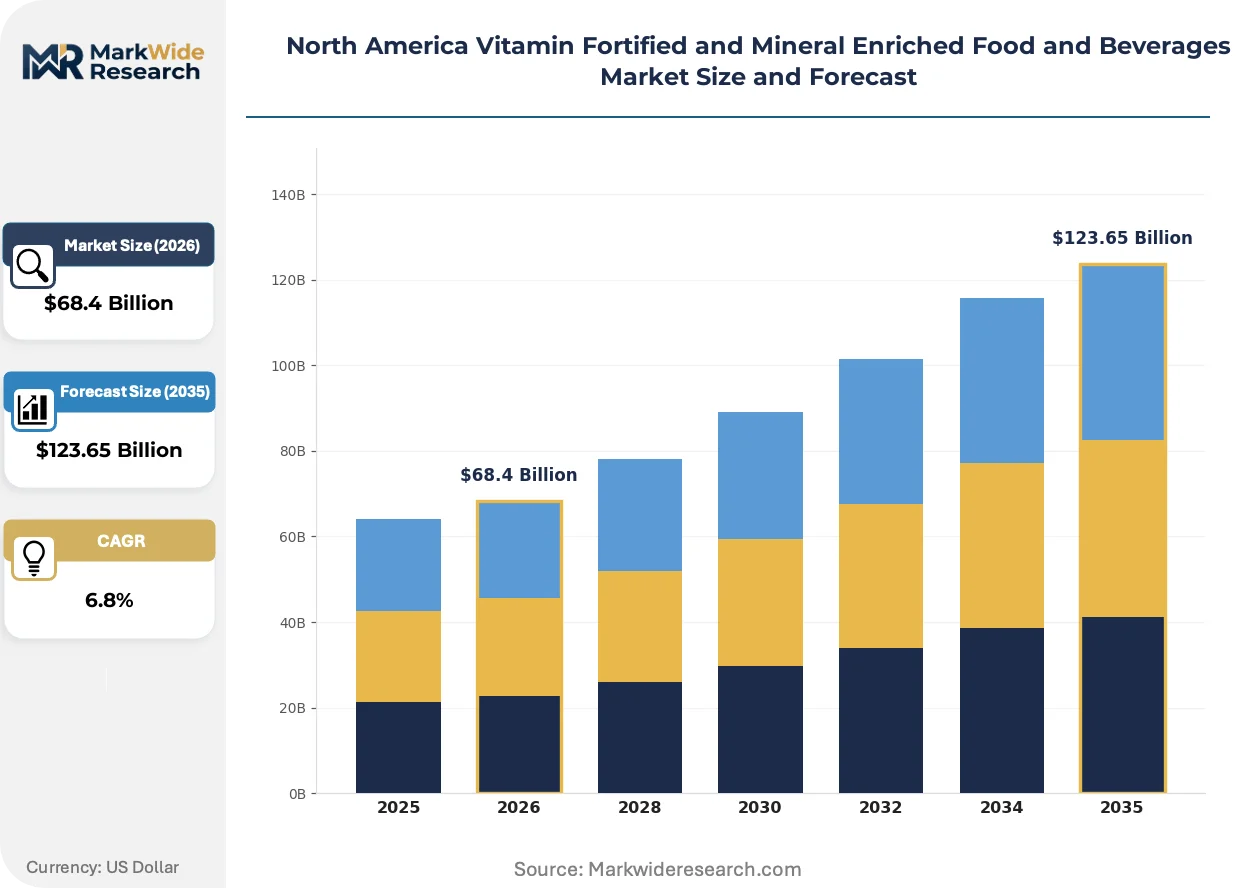
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink Beverages, Nutritional Bars, Fortified Dairy, Enriched Snacks End User: Children, Adults, Seniors, Athletes Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Stores Formulation: Powdered, Liquid, Tablets, Gummy |
| Companies Covered | General Mills Inc., Danone SA, Kellogg Company, Keurig Dr Pepper Inc., The Coca-Cola Company, Nestlé SA, Abbott Laboratories, Monster Beverage Corporation, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market Evolving Landscape
Spray-drying and microencapsulation infrastructure is being retooled for smaller-batch, higher-SKU production runs as personalization pressures mount. This equipment transition is compressing minimum efficient scale thresholds and enabling regional co-manufacturing networks.
Lipid-based nano-delivery systems are decomposing the traditional trade-off between fortification intensity and sensory acceptability. Sports nutrition brands and pediatric formula producers are adopting phospholipid-encapsulated vitamin D and omega-3 complexes at accelerated procurement cycles. The technology is decomposing incumbent spray-dried powder margins by enabling liquid suspension formats with extended stability.
Health Canada and the FDA are harmonizing bioavailability testing protocols through the Canada-U.S. Regulatory Cooperation Council framework. This coordination is forcing manufacturers to standardize dissolution and absorption validation methods across cross-border product lines. The clinical nutrition and medical food segments are responding by consolidating testing vendor relationships to ensure dual-jurisdiction compliance efficiency.
Subscription-based personalized nutrition services are fragmenting traditional retail purchasing patterns. Direct-to-consumer vitamin profiling kits and algorithm-driven fortification recommendations are displacing mass-market multivitamin reliance among health-conscious millennials. California's functional food corridor and Toronto's wellness startup ecosystem represent the geographic concentration of this demand rotation.
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market Segmentation
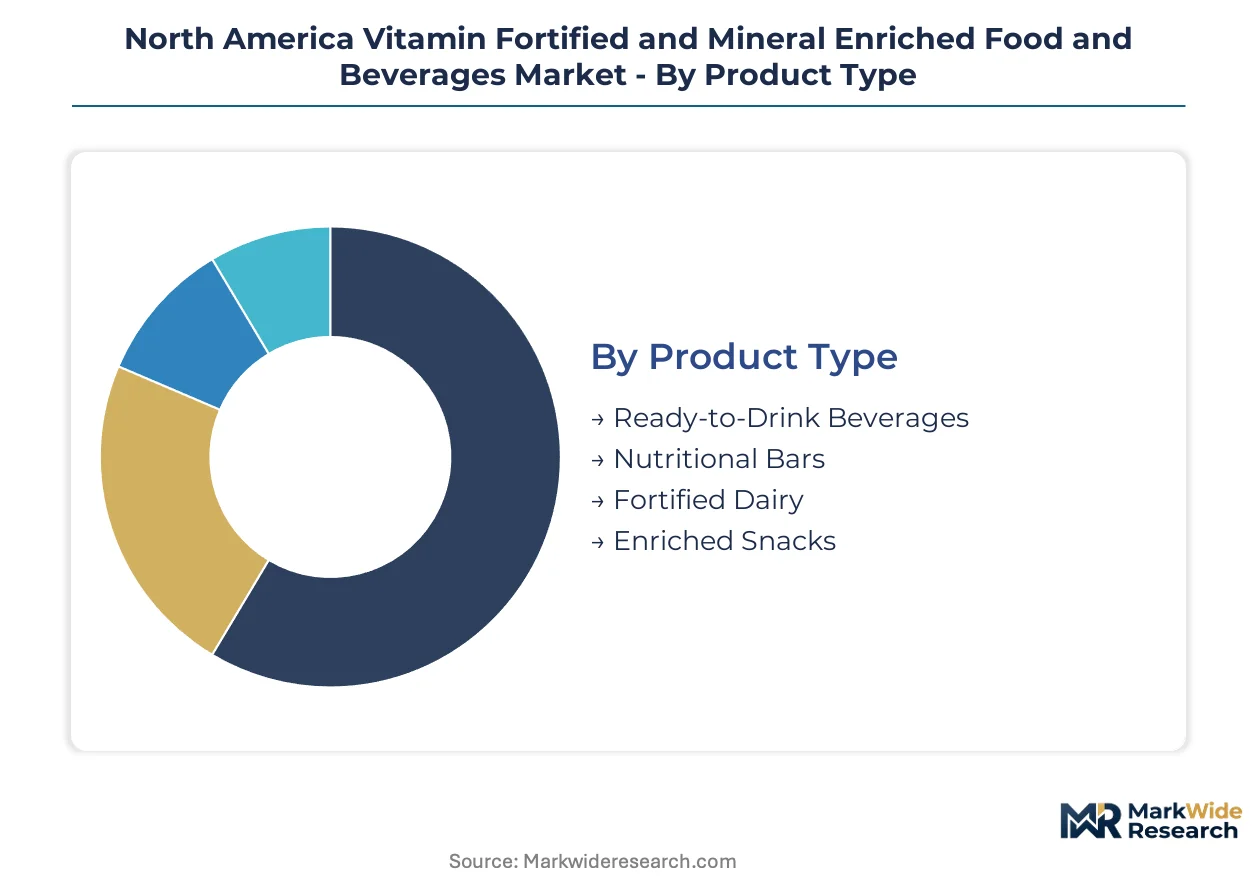
Segmentation in North America's fortified food sector reveals how formulation complexity and channel access determine margin capture. Manufacturers must navigate divergent stability requirements across delivery formats while targeting distinct micronutrient deficiency profiles by life stage.
Product Type:
Ready-to-drink beverages face the most acute substitution pressure from functional waters and nootropic shots that bypass traditional fortification infrastructure entirely.
- Ready-to-Drink Beverages:Shelf-stable liquid formulations carrying water-soluble B-complex and fat-soluble vitamins A, D, E in emulsion systems. Demand clusters in California's functional food corridor where convenience-driven millennials prioritize grab-and-go micronutrient delivery over pill-based supplementation.
- Nutritional Bars:Extruded or cold-pressed matrices combining protein isolates with spray-dried vitamin premixes and chelated minerals. Athletes and time-constrained professionals in Toronto's wellness startup ecosystem drive procurement of protein-vitamin hybrid positioning.
- Fortified Dairy:Fluid milk, yogurts, and cheeses with added vitamins A, D and calcium through direct blending or post-pasteurization injection. Mature infrastructure across US Midwest dairy cooperatives supports volume production.
- Enriched Snacks:Baked crackers, cereals, and savory items with microencapsulated nutrients surviving extrusion temperatures. Mexican school feeding programs expand shelf-stable cracker and cookie fortification procurement.
Fortified dairy retains volume leadership; nutritional bars hold the steepest expansion curve.
End User:
Cost tier stratification separates prescription-reimbursed clinical nutrition from premium direct-to-consumer positioning.
- Children:Pediatric formulas and school-compliant beverages addressing iron, zinc, and vitamin D deficiency screening protocols. USDA school meal standards and Mexico's Liconsa program shape formulation requirements.
- Adults:Mass-market multivitamin replacement through fortified foods targeting workplace wellness programs. Corporate cafeteria contracts in Texas and Illinois drive B-complex and magnesium-enriched beverage procurement.
- Seniors:High-bioavailability calcium, vitamin D, and B12 formulations addressing malabsorption risks. Homecare nutrition programs in Florida and Arizona expand prescription-strength product reimbursement.
- Athletes:Protein-fortified recovery products with electrolyte and antioxidant complexes. Sports nutrition adoption concentrates in Colorado's endurance athlete communities and Canadian Olympic training centers.
Adult segments dominate current revenue; senior-targeted clinical nutrition is climbing the fastest.
Distribution Channel:
Channel margin structures concentrate premium positioning in health-focused retail while supermarkets enforce volume-driven price compression.
- Supermarkets:Mass-market fortified cereals and dairy commanding end-cap placement through trade promotion spending. Walmart and Kroger slotting fees favor General Mills and Nestlé scale advantages.
- Health Stores:Premium-positioned organic-certified and non-GMO fortified products with restricted synthetic nutrient forms. Whole Foods Market's quality standards filter permitted fortification inputs.
- Online Retail:Subscription-based personalized nutrition kits and direct-to-consumer vitamin profiling services. Algorithm-driven recommendations fragment traditional multivitamin purchasing in California and Toronto.
- Specialty Stores:Clinical nutrition and medical food distribution through hospital outpatient pharmacies and registered dietitian networks. Abbott Laboratories anchors this channel with prescription-strength formulations.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
Formulation:
Application-driven stability requirements separate heat-processed formats from cold-chain dependent delivery systems.
- Powdered:Spray-dried vitamin premixes and mineral complexes for reconstitution in beverages or food matrices. Bakery and extruded snack applications in Mexico and US Southeast rely on heat-stable microencapsulation.
- Liquid:Emulsion-based fat-soluble vitamin delivery and water-soluble suspensions requiring homogenization. Ready-to-drink dairy alternatives in California leverage precision-fermented vitamin D3 and B12.
- Tablets:Compressed multinutrient formats for medical food and clinical nutrition channels. Hospital discharge protocols in Ontario and British Columbia standardize tablet-based supplementation regimens.
- Gummy:Gelatin or pectin-based matrices with lipid-shell encapsulated vitamins masking mineral metallic off-notes. Pediatric compliance in US suburban markets drives sugar-reduced formulation innovation.
Powdered formats retain volume leadership; gummy formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American markets. Mexican school feeding programs operate on thin procurement margins, while US clinical nutrition channels absorb premium pricing for bioavailable formulations. Canadian organic certification adds cost layers that compress volumes in mass retail.
United States
Hospital discharge protocols and homecare nutrition programs in Florida and Arizona expand prescription-strength fortified product reimbursement. The FDA's updated 21 CFR 101 nutrition labeling rules force systematic reformulation across breakfast cereals and ready-to-drink beverages. California's functional food corridor concentrates demand for convenience-driven micronutrient delivery among health-conscious millennials.
Canada
Health Canada coordinates bioavailability testing protocols with the FDA through the Canada-U.S. Regulatory Cooperation Council. The country's National Organic Program constrains synthetic nutrient forms in certified products, limiting fortification options for premium-positioned brands. Toronto's wellness startup ecosystem drives procurement of personalized nutrition services and algorithm-driven fortification recommendations.
Mexico
Liconsa school feeding programs and early childhood nutrition initiatives present underexploited demand for fortified beverages and shelf-stable dairy. The Secretariat of Economy oversees procurement standards for social program distribution. Mexico City Metro anchors formulation R&D for heat-stable microencapsulation targeting tropical climate distribution.
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North America's fortified food sector. Multinational conglomerates with cereal fortification infrastructure and dairy-based delivery systems dominate volume leadership, while clinical nutrition specialists capture margin pools through prescription-channel positioning. Three archetypes define competitive structure: diversified consumer packaged goods conglomerates, medical nutrition formulators, and beverage-focused functional brands. Consolidation pressure is accelerating through strategic partnerships and technology licensing rather than outright acquisition.
Among diversified packaged goods leaders, General Mills Inc. and Nestlé SA exemplify scale-driven breakfast and dairy fortification archetypes. Abbott Laboratories anchors the clinical nutrition specialist tier with medical channel positioning. These three represent the dominant competitive vectors: mass-market volume capture, premium functional positioning, and prescription-reimbursed clinical formulations.
| Leading Market Players |
|---|
| General Mills Inc. |
| Danone SA |
| Kellogg Company |
| Keurig Dr Pepper Inc. |
| The Coca-Cola Company |
| Nestlé SA |
| Abbott Laboratories |
| Monster Beverage Corporation |
| PepsiCo |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for vitamin premix concentrates lock in both supply access and price visibility for North American fortified food manufacturers, insulating them from spot-market volatility in Chinese and Indian feedstock markets while constraining formulation flexibility under FDA 21 CFR 101 ceilings.
Pricing Analysis
After-sales service revenue from clinical nutrition counseling and registered dietitian networks drives lifetime value for manufacturers serving hospital discharge protocols. Three-tier pricing structure across premium organic-certified, standard mass-market, and economy social-program tiers separates Abbott Laboratories' prescription-strength positioning from Walmart shelf-stable dairy. Cost compression in economy-tier school feeding procurement is intensifying because Mexico's Liconsa program operates on thin government margins. Corporate wellness buyers show lowest price sensitivity; social program administrators exhibit highest.
Supply Chain Analysis
Inventory lead times for heat-stable microencapsulated vitamin premixes stretch to 16-20 weeks due to concentrated production in China, India, and Germany. Raw material dependencies center on vitamin A acetate, cholecalciferol, and chelated zinc complexes from pharmaceutical-grade suppliers. Single-source vulnerability in lipid-shell encapsulation technology creates bottleneck risk for sports nutrition brands. Distribution runs through regional dairy cooperatives and direct-to-clinic networks bypassing traditional retail slotting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in personalized nutrition services, where algorithm-driven fortification recommendations displace mass-market multivitamin reliance among health-conscious millennials in California and Toronto.
For Market Incumbents: Consolidate control over precision-fermentation vitamin B12 and D3 supply through backward integration into microbial production platforms. Acquire regional co-manufacturing networks to compress minimum efficient scale thresholds for smaller-batch SKU proliferation. Defend against sports nutrition entrants by locking phospholipid-encapsulation capacity under exclusive supply arrangements. For New Entrants and Emerging Players: Differentiate on bioavailability-verified positioning targeting senior malabsorption risks in Florida and Arizona homecare channels. Penetrate Mexico's pediatric nutrition white space through Liconsa program-compliant heat-stable formulations. Launch direct-to-registered-dietitian distribution bypassing supermarket slotting fee barriers. For Investors and Strategic Acquirers: Capital is best deployed toward clinical nutrition specialists with prescription-channel reimbursement relationships and FDA medical food designations. Long-term viability across the analysis window favors platforms converging precision fermentation with plant-based delivery systems. Watch Health Canada-FDA bioavailability testing harmonization as signal for cross-border consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioactive vitamin B12 from microbial production converges with plant-based dairy alternatives in California. |
| Direct-to-Clinic Distribution Launch | Hospital outpatient pharmacies bypass retail slotting constraints for prescription-strength formulations. |
| Microencapsulation Technology Licensing | Lipid-shell systems decompose trade-offs between fortification intensity and sensory acceptability. |
| USDA Organic Certification Investment | Restricted substance lists block synthetic nutrient forms, constraining fortification options for premium tiers. |
| Pediatric Nutrition Formulation Partnership | Mexico's school feeding programs expand procurement for shelf-stable fortified beverages and crackers. |
Research Methodology
Desk research of FDA 21 CFR 101 filings, Health Canada regulatory guidance, and USDA National Organic Program standards preceded structured interviews with formulation scientists, registered dietitians, hospital procurement managers, and dairy cooperative supply planners. Primary fieldwork combined with secondary validation from Nielsen retail audit data, customs import records for vitamin premix concentrates, and SEC 10-K disclosures from diversified packaged goods conglomerates. Bottom-up SKU-level modeling triangulated against top-down category spending estimates.
Variance decomposition across product type, end-user life stage, distribution channel, and formulation technology dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate assumptions weighted by revenue contribution. Forecast inputs incorporated FDA Daily Value benchmark revisions and Mexico's Liconsa procurement expansion trajectories without specifying implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement expansion for clinical nutrition or prolonged vitamin feedstock price stability would require recalibration. Forecasts reflect documented assumptions regarding bioavailability testing protocol harmonization and precision fermentation cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Colecalciferol Market