
 Europe Feed Vitamins Market | 2026-2036
Europe Feed Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Vitamins Market Foresight
Aftermarket technical service revenue is narrowing as a margin pool, shifting value toward integrated premix formulation and on-farm nutritional consulting. DSM Nutritional Products AG leverages its Swiss R&D campus to sustain vitamin stability research under challenging pelleting conditions. BASF SE anchors its position through backward integration into citral-based vitamin A precursors, controlling feedstock quality from Ludwigshafen. Adisseo competes via specialized methionine and vitamin E complexes tailored to Mediterranean poultry stress profiles.
Europe Feed Vitamins comprise organic micronutrient compounds—water-soluble B-complex and fat-soluble A, D, E, K vitamins—synthesized through chemical fermentation or chemical synthesis at purity grades exceeding 96%, then stabilized with ethoxyquin or coated formulations to withstand extrusion temperatures above 85°C. Their primary purpose is to prevent deficiency disorders, optimize metabolic enzyme function, and substitute for declining antibiotic growth promoters in compound feed. The vitamins segment captures the dominant share of value, though amino acids generate higher tonnage throughput across European compounders. Poultry applications lead volume demand, while aquaculture represents the fastest-expanding animal type as Norwegian and Scottish salmon producers intensify recirculation systems requiring precise micronutrient balancing.
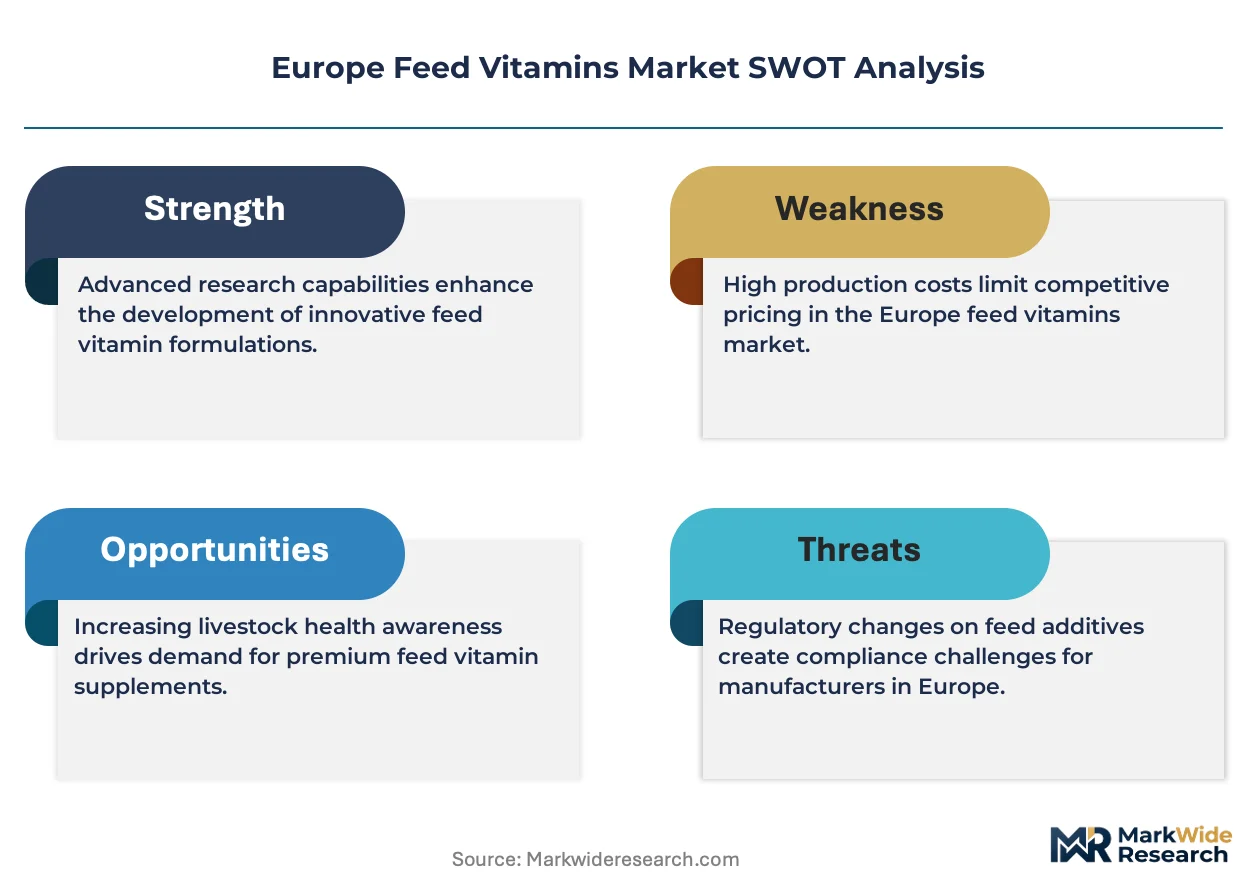
EFSA sets maximum vitamin inclusion thresholds under feed additive regulations, while the EU Green Deal's Farm to Fork strategy mandates 50% antibiotic reduction, directly expanding nutritional alternative demand. REACH compliance governs chemical synthesis inputs, and F-Gas Regulation phases constrain certain solvent-based extraction processes for fat-soluble vitamins. Stakeholders must monitor pending CSRD sustainability disclosure requirements, which will force premix suppliers to document supply chain carbon intensity per vitamin unit and verify deforestation-free sourcing for palm-derived vitamin E carriers.
Market Dynamics
The EU Green Deal's Farm to Fork antibiotic reduction mandates are restructuring feed formulation economics across European livestock sectors, forcing producers to recalibrate micronutrient protocols as nutritional alternatives displace pharmaceutical growth promoters.
Growth Catalysts
- Antibiotic phase-out mandates:The EU Green Deal targets 50% antibiotic reduction in farmed animals by 2030, expanding premix demand from German pig cooperatives and Spanish poultry integrators seeking metabolic optimization alternatives.
- Aquaculture intensification:Norwegian and Scottish salmon producers deploying recirculating aquaculture systems require precision vitamin balancing to compensate for closed-loop nutritional constraints.
- Heat-stable formulation advances:Coated vitamin technologies withstand pelleting temperatures exceeding 85°C, enabling compound feed manufacturers to maintain bioavailability through high-shear extrusion processes.
Market Restraints
- Citral feedstock concentration:Vitamin A precursor synthesis depends on petrochemical-derived citral supplies concentrated at Ludwigshafen and limited Asian manufacturing hubs, creating input vulnerability.
- EFSA inclusion ceilings:Maximum vitamin thresholds under feed additive regulations constrain formulation flexibility for high-performance genetic lines requiring elevated micronutrient densities.
- Palm-derived carrier dependency:Vitamin E formulations rely on tocopherol carriers subject to deforestation-free sourcing verification under pending CSRD disclosure requirements.
Strategic Opportunities
- Polish contract farming expansion:Rapid consolidation in Poland's poultry sector creates standardization opportunities for integrator-level premix programs across vertically coordinated supply chains.
- Precision livestock integration:Real-time feed intake monitoring converges with individualized vitamin dosing, enabling outcome-based nutrition contracts with Danish dairy cooperatives.
- CSRD-compliant carbon accounting:Premix suppliers documenting supply chain carbon intensity per vitamin unit capture preferential positioning with sustainability-mandated retail procurement programs.
Industry Challenges
- Formulation biochemistry expertise scarcity:Compounders struggle to recruit specialists capable of balancing fat-soluble and water-soluble vitamin interactions under variable feed matrix conditions.
- REACH registration timelines:Novel vitamin derivative approvals face 18-24 month ECHA evaluation cycles, delaying product pipeline commercialization.
- Multi-species protocol complexity:Premix suppliers serving diversified livestock operations must maintain separate stability-validated formulations for ruminant, monogastric, and aquaculture applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Vitamins Market |
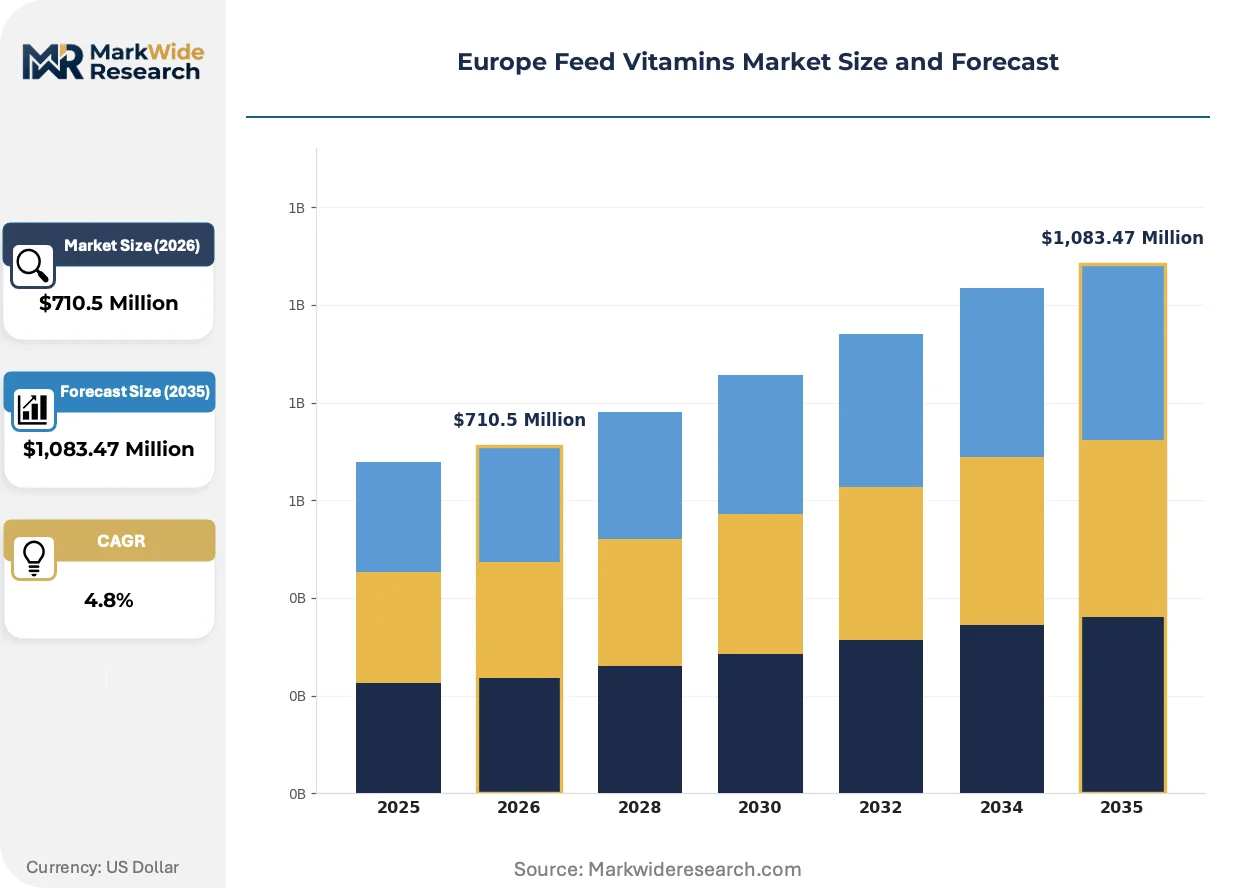
| Market Size in 2026 | $710.5 Million |
| Market Size in 2035 | $1,083.47 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Minerals, Fatty Acids Animal Type: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Blends Distribution Channel: Online, Wholesalers, Retailers, Direct Sales |
| Companies Covered | Archer Daniel Midland Co, Dangschat T O H GmbH & Co KG, DSM Nutritional Products AG, Impextraco NV, Biovet S.A., BASF SE, Brenntag SE, Lonza Group Ltd, Adisseo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Vitamins Market Shifts & Advancements
Formulation science and regulatory disclosure requirements are compressing traditional premix value chains, redirecting competitive advantage toward integrated nutritional consulting and verified sustainability documentation.
Microencapsulation technology using lipid-matrix coating systems is collapsing the historical trade-off between thermal processing stability and intestinal bioavailability. BASF SE and DSM Nutritional Products AG have deployed these formulations across German compound feed networks. The technology is collapsing price premiums previously commanded by specialized aquaculture vitamin grades as heat-stable variants achieve species-agnostic performance.
EFSA's pending revision of maximum vitamin inclusion thresholds under feed additive regulations is forcing reformulation investments across European premix operations. Industrial compounders must revalidate stability data and retest matrix interactions. Pig nutrition protocols in Denmark and the Netherlands face the most immediate compliance pressure given their reliance on elevated vitamin D3 densities for skeletal health optimization.
Integrator-level procurement consolidation is compressing distributor margins and redirecting volume through direct manufacturer relationships. Polish and Spanish poultry cooperatives now negotiate enterprise premix contracts bypassing traditional agricultural merchant channels. This pattern concentrates most visibly in Germany's industrial pig sector where four cooperatives control micronutrient specification for over sixty percent of contract-finishing operations.
Europe Feed Vitamins Market Segmentation
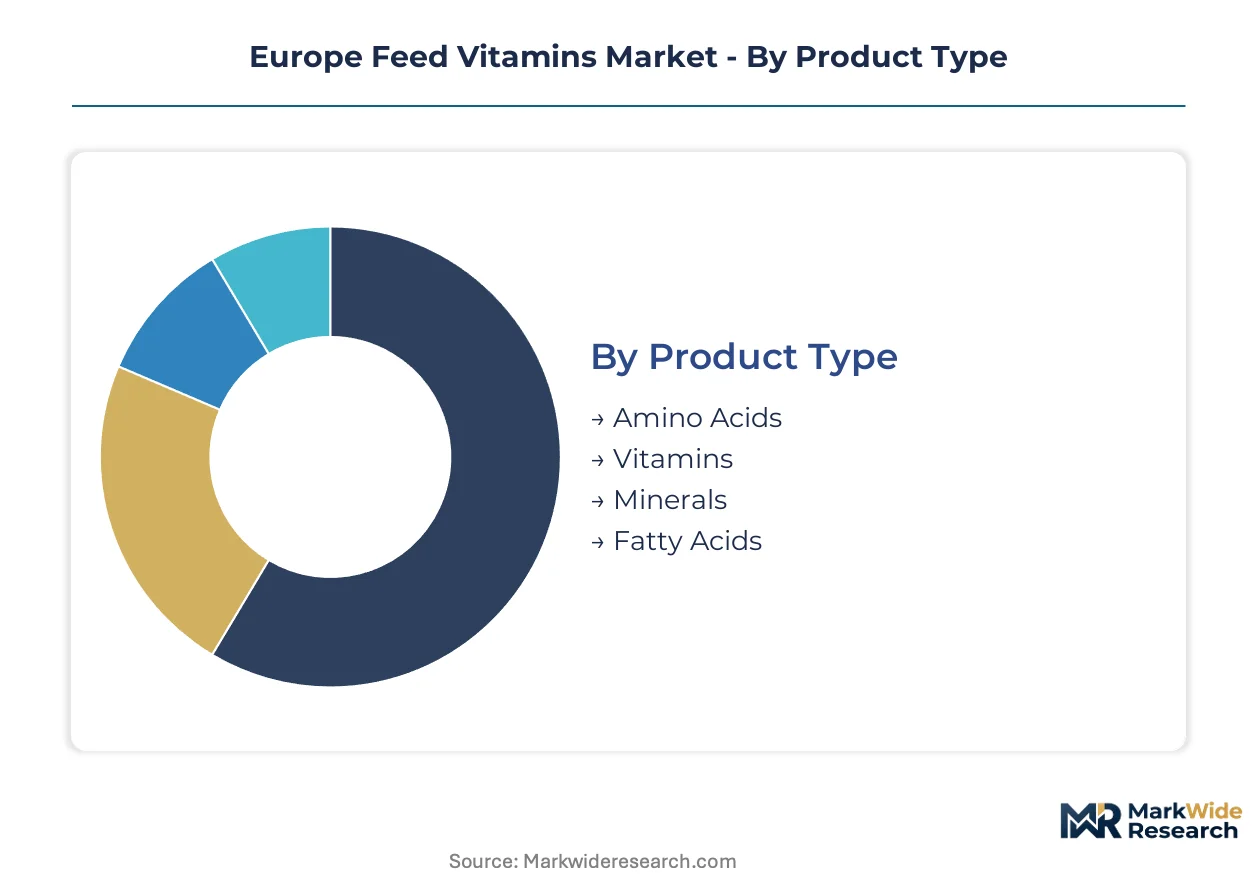
Feed vitamin segmentation in Europe reflects divergent technical service requirements across species and formulation types. Nutritional consulting intensity varies sharply between aquaculture precision protocols and standardized poultry premix programs.
Product Type:
After-sales technical support concentrates heavily in vitamin formulation services, where stability validation and matrix interaction analysis demand specialist biochemistry expertise.
- Vitamins:Organic micronutrient compounds—water-soluble B-complex and fat-soluble A, D, E, K—synthesized at purity grades exceeding 96% and stabilized with ethoxyquin or coated formulations to withstand extrusion temperatures above 85°C. German pig cooperatives and Spanish poultry integrators drive demand as antibiotic reduction mandates expand nutritional alternative adoption. EFSA inclusion ceilings constrain formulation flexibility for high-performance genetic lines.
- Amino Acids:Methionine, lysine, and threonine compounds that generate higher tonnage throughput across European compounders than vitamins despite capturing lower value share. Adisseo competes via specialized methionine complexes tailored to Mediterranean poultry stress profiles. Heat-stable formulation advances enable species-agnostic performance across pelleting processes.
- Minerals:Inorganic and chelated trace elements—zinc, copper, manganese, selenium—supporting enzymatic function and immune response in intensive livestock systems.
- Fatty Acids:Omega-3 and omega-6 lipid supplements enhancing feed energy density and reproductive performance in ruminant and aquaculture applications.
By volume, amino acids lead. By growth pace, vitamins are ahead.
Animal Type:
Cost tier stratification separates intensive monogastric operations requiring precision premix programs from extensive ruminant systems using lower-specification mineral-vitamin blends.
- Poultry:The dominant volume application across Europe, with Polish and Spanish integrators expanding vitamin premix programs to improve feed conversion ratios. DSM Nutritional Products AG deploys Swiss R&D campus innovations for thermal stability under high-shear extrusion. Contract farming consolidation in Poland creates standardization opportunities for enterprise-level premix procurement.
- Aquaculture:Norwegian and Scottish salmon producers deploying recirculating aquaculture systems require precision vitamin balancing to compensate for closed-loop nutritional constraints. Microencapsulation technology using lipid-matrix coating systems collapses historical trade-offs between processing stability and intestinal bioavailability. CSRD-compliant carbon accounting pressures intensify supply chain documentation requirements.
- Swine:Germany's industrial pig sector anchors demand, where four cooperatives control micronutrient specifications for over sixty percent of contract-finishing operations.
- Ruminants:Danish dairy cooperatives pioneer precision livestock integration, converging real-time feed intake monitoring with individualized vitamin dosing protocols.
By volume, poultry leads. By expansion trajectory, aquaculture is climbing fastest.
Form:
Application method dictates formulation chemistry, with pelleting processes above 85°C demanding coated variants that uncoated liquids and standard powders cannot survive.
- Powder:Unstabilized crystalline vitamin forms requiring low-temperature pelleting or post-pellet liquid application, prevalent in smaller compound feed operations lacking extrusion capacity.
- Granular:Agglomerated formulations improving flowability and reducing dust exposure during handling, favored by automated premix blending systems.
- Liquid:Oil-soluble vitamin suspensions and emulsions applied via post-pellet spraying systems, enabling heat-sensitive nutrient preservation.
- Blends:Pre-mixed vitamin-mineral complexes validated for species-specific matrix interactions, reducing formulation complexity for diversified livestock operations.
By volume, powder leads. By technology transition, granular is gaining share fastest.
Distribution Channel:
Customer type fragmentation separates integrator-level direct procurement from merchant-served independent producers, compressing traditional distributor margins.
- Direct Sales:Manufacturer-integrator relationships bypassing agricultural merchant channels, concentrated in Germany's industrial pig sector and Polish poultry cooperatives. BASF SE anchors position through backward integration into citral-based vitamin A precursors from Ludwigshafen.
- Wholesalers:Regional agricultural merchants serving independent livestock producers with standardized premix portfolios and basic technical support.
- Retailers:Farm supply stores and cooperatives distributing bagged vitamin premixes to small-scale producers.
- Online:Emerging procurement channel for specialty vitamin formulations and documentation-heavy CSRD-compliant carbon accounting services.
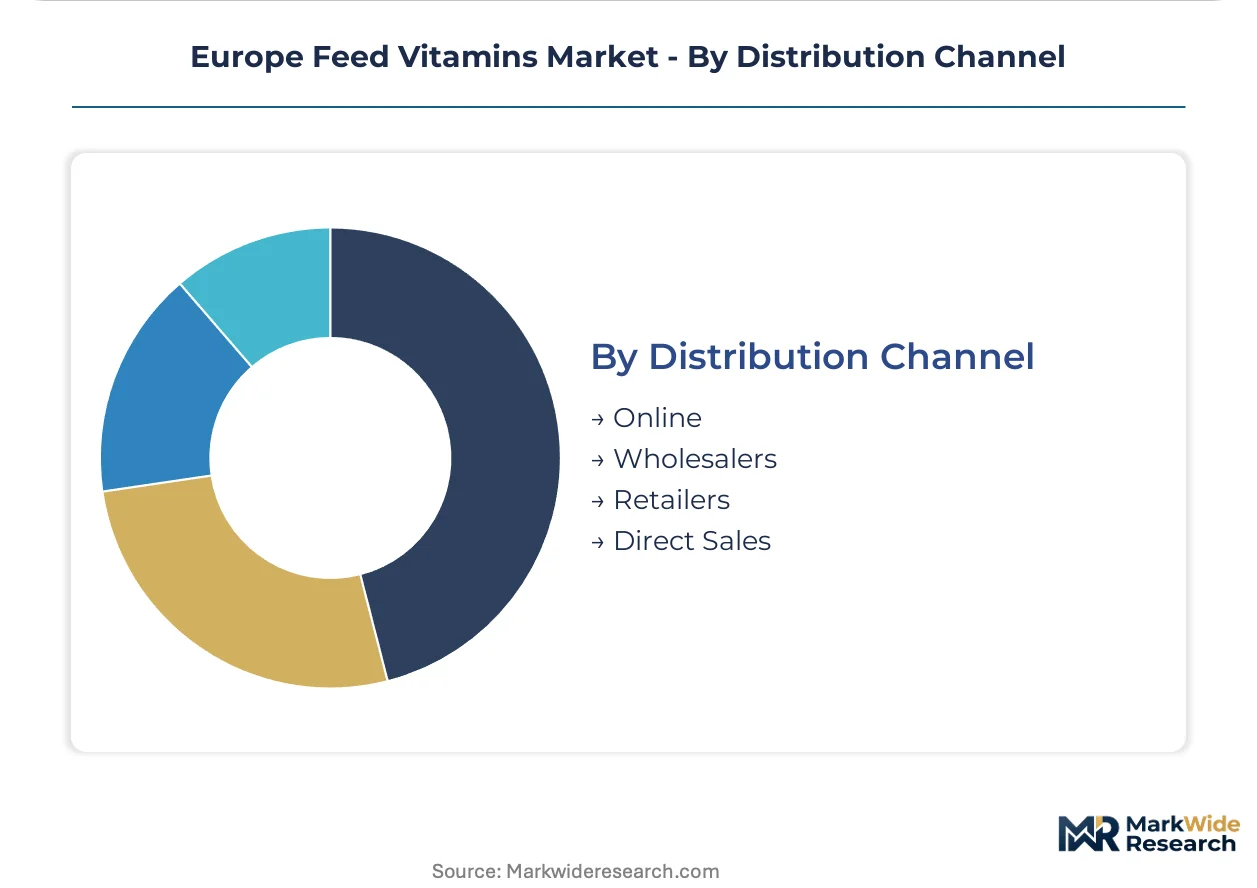
By volume, wholesalers lead. By channel shift velocity, direct sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes feed vitamins through industrial pig cooperatives standardizing micronutrient protocols, while Spain and Poland apply them via poultry integrators targeting feed conversion improvements. Norway and Scotland diverge toward aquaculture precision systems requiring closed-loop nutritional balancing.
Germany
Four cooperatives control micronutrient specifications for over sixty percent of contract-finishing pig operations. EFSA inclusion ceilings under feed additive regulations constrain elevated vitamin D3 densities used for skeletal health optimization. The Ludwigshafen chemical cluster anchors citral-based vitamin A precursor production.
Spain
Poultry integrators expand vitamin premix programs to improve feed conversion ratios across vertically coordinated supply chains. EU Green Deal Farm to Fork antibiotic reduction mandates push producers toward nutritional alternatives. The Catalonia and Valencia production belts concentrate industrial compound feed manufacturing capacity.
Poland
Rapid poultry sector consolidation creates standardization opportunities for integrator-level premix procurement programs. REACH compliance governs chemical synthesis inputs for domestic compounders. The Greater Poland and Lower Silesia regions host expanding contract farming operations negotiating direct manufacturer relationships.
Norway
Salmon producers deploying recirculating aquaculture systems require precision vitamin balancing to compensate for closed-loop nutritional constraints. F-Gas Regulation phases constrain certain solvent-based extraction processes for fat-soluble vitamins. The Bergen and Trondheim coastal clusters intensify recirculation system deployment.
United Kingdom
Scottish salmon operations mirror Norwegian precision requirements while facing pending CSRD sustainability disclosure mandates. The country's national feed regulator enforces maximum vitamin inclusion thresholds aligned with EFSA guidance. The Scottish Highlands concentrate aquaculture vitamin demand alongside East Anglia's poultry integration zones.
Europe Feed Vitamins Market Competitive Landscape
Capability concentration sits with Swiss and German R&D-intensive specialists; scale advantage sits with diversified chemical conglomerates controlling upstream feedstock synthesis. The vendor base organizes around three archetypes: backward-integrated petrochemical players, fermentation-technology nutrition specialists, and regional distribution-anchored formulators. Competitive moves concentrate on direct procurement relationships with poultry cooperatives and carbon-intensity documentation for retail-facing supply chains.
Among diversified chemical conglomerates, BASF SE exemplifies upstream control over citral-based vitamin A precursors. DSM Nutritional Products AG occupies a position within the R&D-intensive tier leveraging Swiss-based stability research. Adisseo represents the specialized nutrition archetype competing through methionine and vitamin E complex formulation. These three anchors illustrate divergent strategic positioning across feedstock control, technical service depth, and species-specific application expertise.
| Leading Market Players |
|---|
| Archer Daniel Midland Co |
| Dangschat T O H GmbH & Co KG |
| DSM Nutritional Products AG |
| Impextraco NV |
| Biovet S.A. |
| BASF SE |
| Brenntag SE |
| Lonza Group Ltd |
| Adisseo |
| Others |
Supply & Pricing Matrix
Citral feedstock concentration at Ludwigshafen and limited Asian manufacturing hubs determines both the spread between contract and spot vitamin A pricing and the geographic shape of European premix supply chains. This single-source dependency for petrochemical-derived precursors compresses margins on standardized formulations while elevating premiums for stability-validated, heat-resistant grades.
Pricing Analysis
Long-term offtake agreements dominate procurement between German pig cooperatives and citral-integrated suppliers, insulating compounders from spot volatility while locking in volume commitments. Pricing stratifies across premium, standard, and economy tiers based on thermal stability certification and after-sales technical service bundling. Cost compression in economy-grade powder formulations is intensifying because Polish poultry integrators are consolidating procurement through direct manufacturer relationships. Spot buyers at smaller compound feed operations exhibit the highest price sensitivity, whereas aquaculture specialists in Norway accept premium positioning for lipid-matrix coated variants.
Supply Chain Analysis
Upstream citral synthesis anchors in Germany's Ludwigshafen chemical cluster, with secondary fermentation capacity concentrated in Switzerland and the Netherlands. Vitamin production draws from petrochemical feedstocks, palm-derived tocopherol carriers, and ethoxyquin stabilization agents. Single-source vulnerability for vitamin A precursors creates structural exposure to REACH compliance delays or feedstock disruptions. Distribution runs through direct manufacturer-integrator channels in Germany and Poland, bypassing traditional agricultural merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across species-specific formulation requirements and divergent CSRD compliance timelines creates niche entry points for specialized premix suppliers. Antibiotic reduction mandates are splintering demand into aquaculture precision protocols, poultry standardization programs, and swine metabolic optimization services.
For Market Incumbents: Insulate position through captive citral supply arrangements and Swiss-based stability R&D infrastructure. DSM Nutritional Products AG and BASF SE should deepen backward integration into vitamin A precursor synthesis to neutralize feedstock vulnerability. Certification investment in CSRD-compliant carbon accounting per vitamin unit captures preferential positioning with sustainability-mandated retail procurement programs. For New Entrants and Emerging Players: Build out precision livestock integration capabilities targeting Danish dairy cooperatives with real-time feed intake monitoring and individualized vitamin dosing protocols. Polish contract farming consolidation represents the most penetrable geography for integrator-level premix standardization. A go-to-market angle anchored in REACH-registered novel vitamin derivatives with shortened ECHA evaluation cycles bypasses incumbent formulation lock-in. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors R&D-intensive specialists with fermentation-technology moats. Long-term viability over the next decade hinges on carbon-intensity documentation capabilities and deforestation-free carrier sourcing verification. Acquisition targets should demonstrate validated stability data under high-shear extrusion conditions. The signal to watch is EFSA's pending revision of maximum vitamin inclusion thresholds, which will force reformulation investments and strain smaller compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citral Synthesis | BASF SE's Ludwigshafen cluster controls vitamin A precursor quality from petrochemical feedstock origin. |
| Microencapsulation Technology Deployment | Lipid-matrix coating systems collapse trade-offs between thermal stability and intestinal bioavailability across species. |
| CSRD-Compliant Carbon Accounting | Premix suppliers documenting supply chain intensity per vitamin unit capture retail-facing sustainability procurement. |
| Precision Livestock Integration | Real-time feed intake monitoring converges with individualized dosing for Danish dairy cooperative contracts. |
| Direct Manufacturer-Integrator Relationships | Polish and Spanish poultry cooperatives bypass agricultural merchants through enterprise premix procurement. |
Research Methodology
Desk research of EFSA feed additive regulations, EU Green Deal policy documents, and REACH registration databases preceded structured interviews with premix formulation chemists, poultry integrator procurement directors, and aquaculture nutrition specialists. Secondary validation drew from compound feed production statistics, customs trade data for citral derivatives, and SEC filings of diversified chemical conglomerates. Bottom-up volume modeling across German pig cooperatives and Spanish poultry operations triangulated against top-down market sizing from industry association reports.
Assumptions held antibiotic reduction targets at 50% phase-out, EFSA inclusion ceilings at current thresholds, and citral feedstock availability at Ludwigshafen capacity across the projection horizon. Segmentation dimensions modeled include product type, animal species, formulation stability grade, and distribution channel structure. CAGRs derived from historical premix volume trends and projected intensification rates in Norwegian recirculating aquaculture systems. Industry-specific inputs incorporated ECHA evaluation cycle timelines and CSRD disclosure requirement implementation pacing.
Sensitivities concentrate around EFSA threshold revisions, REACH registration delays for novel derivatives, and palm-derived carrier supply verification under deforestation-free mandates. Cross-checking against Cefic chemical production data and national feed industry association volume reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Food Fortifying Agents Market