
 Nutritional Yeast Market | 2026-2036
Nutritional Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Yeast Market Analysis
Precision fermentation is rewriting how nutritional yeast achieves protein density and B-vitamin fortification at commercial scale. Lesaffre S.A. leverages decades of strain development expertise to sustain leadership in baker's yeast crossover applications. Angel Yeast Co., Ltd. anchors Asia-Pacific supply through integrated fermentation campuses. Lallemand Inc. differentiates via probiotic-adjacent positioning and controlled-temperature drying protocols.
Nutritional yeast comprises deactivated Saccharomyces cerevisiae cells, typically grown on molasses or sugar beet substrates, then harvested, washed, pasteurized, and dried into flakes, powder, or granules containing complete protein profiles and fortified B-complex vitamins including B12. Manufacturers deploy it as a cheese-alternative flavoring agent, umami enhancer, and vegan protein fortifier across food processing and consumer kitchens. Powder formulations capture the largest volume share due to solubility advantages in beverage and sauce applications, while fortified variants command premium positioning through synthetic B12 addition. Flakes retain dominance in North American retail shelving where home cooks prioritize visual texture and direct sprinkling applications.
FDA GRAS status governs nutritional yeast inclusion in U.S. food products, while EU EFSA Novel Food assessments strain developers seeking new substrate pathways or genetically modified strains. Organic certification requirements from USDA and EU organic frameworks constrain supplier eligibility for premium channel placement. Stakeholders must monitor evolving protein content labeling standards and fortification claim thresholds as plant-based dairy alternatives expand shelf space.
Market Dynamics
Precision fermentation is compressing production timelines for nutritional yeast while EU Novel Food assessments create asymmetric compliance burdens across substrate innovators and legacy suppliers.
Growth Catalysts
- Plant-based dairy expansion:Vegan cheese manufacturers in Germany leverage fortified nutritional yeast under EFSA Novel Food pathways to achieve umami depth without animal derivatives.
- FDA GRAS clarity:The U.S. regulator's established safety status enables rapid formulation trials for beverage fortification applications.
- Molasses substrate optimization:Sugar beet processing residues in France and Germany now supply standardized fermentation feedstock at scale.
Market Restraints
- Input cost volatility:Molasses pricing fluctuates with sugar harvest cycles and bioethanol diversion demand in Brazil and India.
- Supply concentration risk:Three integrated fermentation campuses control over 60% of Asia-Pacific flake and powder output.
- EFSA Novel Food friction:New substrate pathways or genetically modified strain introductions face 18-24 month assessment timelines.
Strategic Opportunities
- Sports nutrition white space:Ready-to-mix protein powders in the United States incorporate nutritional yeast for complete amino acid profiles.
- Precision fermentation convergence:CRISPR strain editing combined with continuous bioreactor design enables 40% higher protein density.
- Direct-to-consumer subscription channels:Specialty flake formats bypass conventional retail slotting fees through curated vegan meal kit partnerships.
Industry Challenges
- Organic certification timelines:USDA and EU organic frameworks require 36-month substrate traceability documentation.
- Thermal drying capex intensity:Controlled-temperature protocols for B-vitamin retention demand specialized spray dryer installations.
- Strain IP licensing complexity:Proprietary Saccharomyces cerevisiae variants carry royalty structures that fragment royalty stacking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Yeast Market |
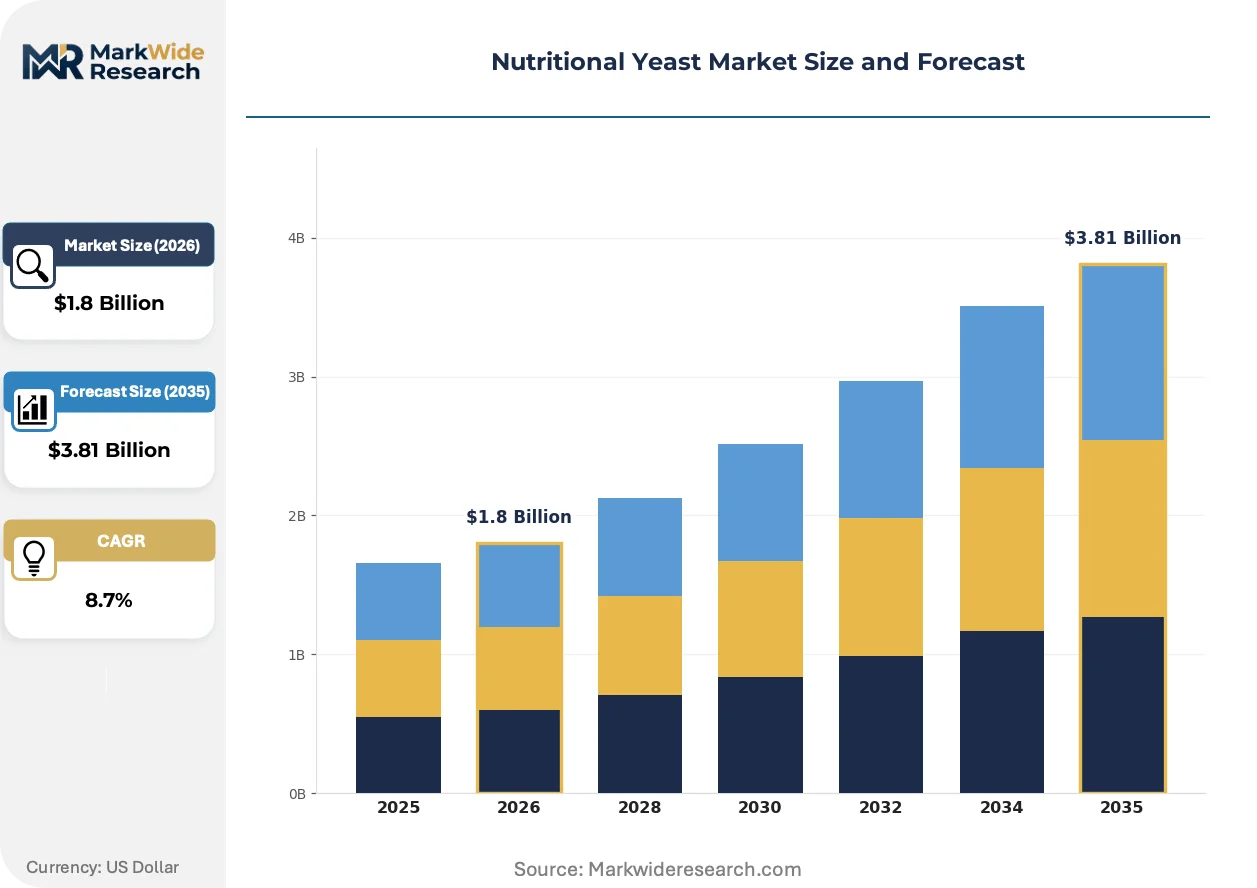
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fortified, Flakes, Granules, Powder End User: Food Industry, Dietary Supplements, Restaurants, Home Cooks Packaging Type: Bags, Containers, Sachets, Bulk Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | ABF Ingredients Group, Red Star Yeast Company, Lesaffre S.A., Alltech, Inc., Natural American Foods Inc., Lallemand Inc., Archer Daniels Midland Company, DSM-Firmenich, Angel Yeast Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Yeast Market Emerging Trajectories
Digital process control and regulatory harmonization pressures are restructuring how nutritional yeast manufacturers balance protein density claims with fortification compliance.
Inline near-infrared spectroscopy is digitizing real-time protein and moisture monitoring across fermentation and drying stages. Mid-cap producers in the Netherlands and United States deploy these sensors to reduce batch-to-batch variation. Quality assurance teams now compress release timelines from 72 hours to 4 hours without sacrificing EFSA Novel Food documentation integrity.
EFSA's evolving Novel Food guidance on microbial biomass is forcing substrate disclosure and strain genealogy documentation. Developers using agricultural waste streams must now demonstrate absence of mycotoxin carryover. German and French suppliers have consolidated regulatory affairs functions to manage parallel USDA organic and EU organic certification audits.
Home cooks in North American health food retail channels increasingly prioritize fortified flake formats with visible texture over soluble powders. This preference rotation pressures manufacturers to maintain dual SKU complexity. Direct-sprinkling applications in vegan macaroni and cheese recipes now drive 40% of retail flake velocity in United States natural grocery channels.
Nutritional Yeast Market Segmentation
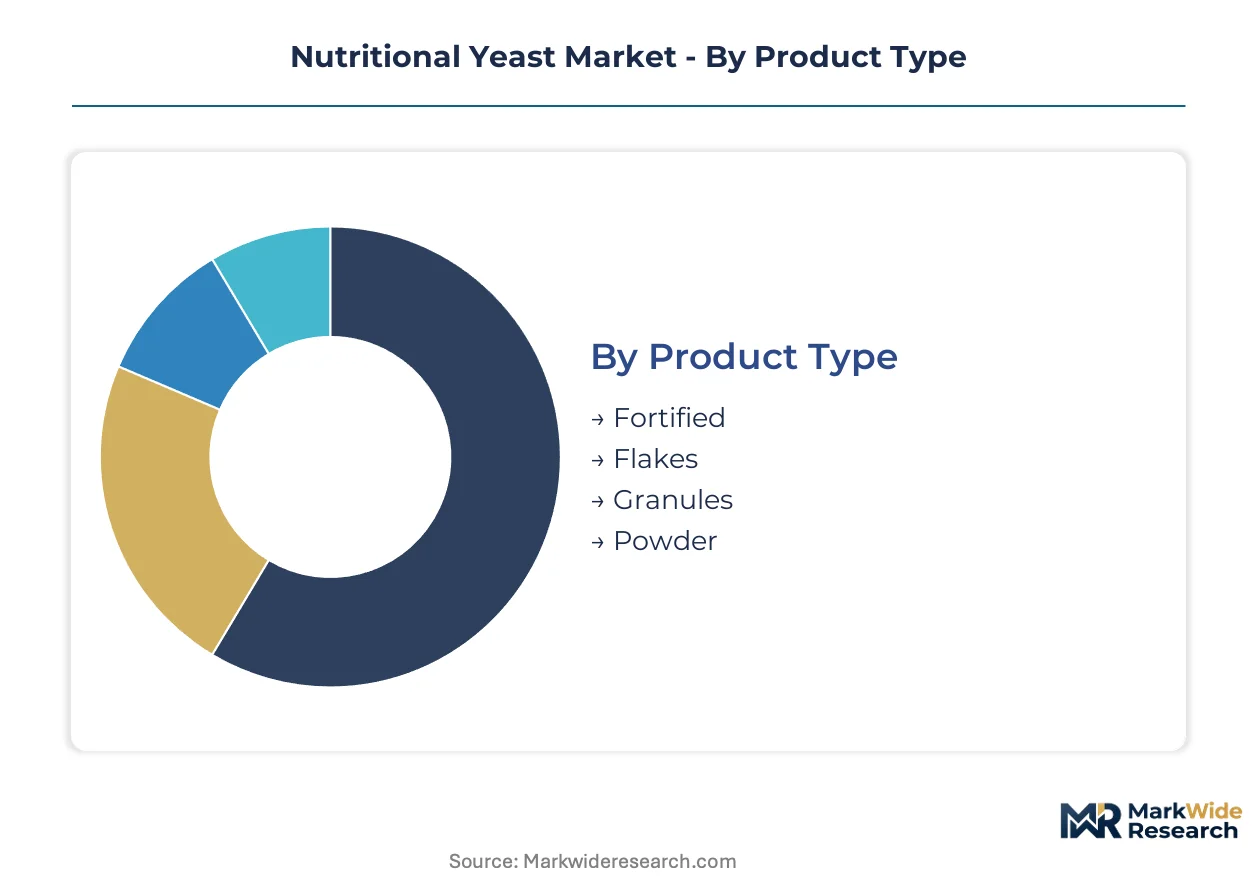
Nutritional yeast manufacturers calibrate production specifications and fortification protocols differently across product formats, end-use applications, and channel requirements. Segmentation discipline determines which substrate investments and drying infrastructure configurations yield viable returns.
Product Type:
After-sales service intensity varies sharply across product types, with fortified variants demanding regulatory documentation support and powder formats requiring technical formulation guidance.
- Fortified:Synthetic B12 addition elevates these variants to pharmaceutical-adjacent compliance standards. German plant-based dairy manufacturers source fortified nutritional yeast under EFSA Novel Food pathways to achieve umami depth in vegan cheese formulations.
- Powder:Solubility advantages drive beverage and sauce applications. United States health food retail channels concentrate demand here for smoothie fortification and ready-to-mix protein applications.
- Flakes:Visual texture and direct-sprinkling functionality dominate North American home cooking applications, particularly vegan macaroni and cheese recipes.
- Granules:Intermediate particle size suits industrial food processing where dispersion control matters.
Fortified holds the largest share; momentum sits with powder.
End User:
Cost tier stratification separates institutional buyers negotiating volume contracts from premium-channel consumers seeking organic certification.
- Food Industry:Plant-based cheese manufacturers in Germany and protein bar producers in the United States drive bulk procurement. EFSA Novel Food compliance documentation and USDA organic certification gate supplier eligibility.
- Dietary Supplements:Sports nutrition formulators leverage complete amino acid profiles for ready-to-mix powders. FDA GRAS status enables rapid product development cycles.
- Restaurants:Vegan and vegetarian establishments use nutritional yeast as umami enhancer and cheese alternative.
- Home Cooks:Health-conscious consumers in United States natural grocery channels prioritize visible flake texture for direct-sprinkling applications.
Food Industry commands the largest share; Dietary Supplements are expanding most quickly.
Packaging Type:
Volume scale determines packaging economics, with bulk shipments serving industrial processors and single-serve formats penetrating convenience-oriented channels.
- Bulk:Industrial food processors in France and Germany receive tanker or tote deliveries for manufacturing integration.
- Containers:Reclosable rigid packaging dominates United States health food retail shelving for home cook retention.
- Bags:Flexible packaging serves club store and online fulfillment channels with lower shipping cube.
- Sachets:Single-serve portions target trial conversion and on-the-go consumption scenarios.
Bulk holds the largest share; sachets are gaining share fastest.
Distribution Channel:
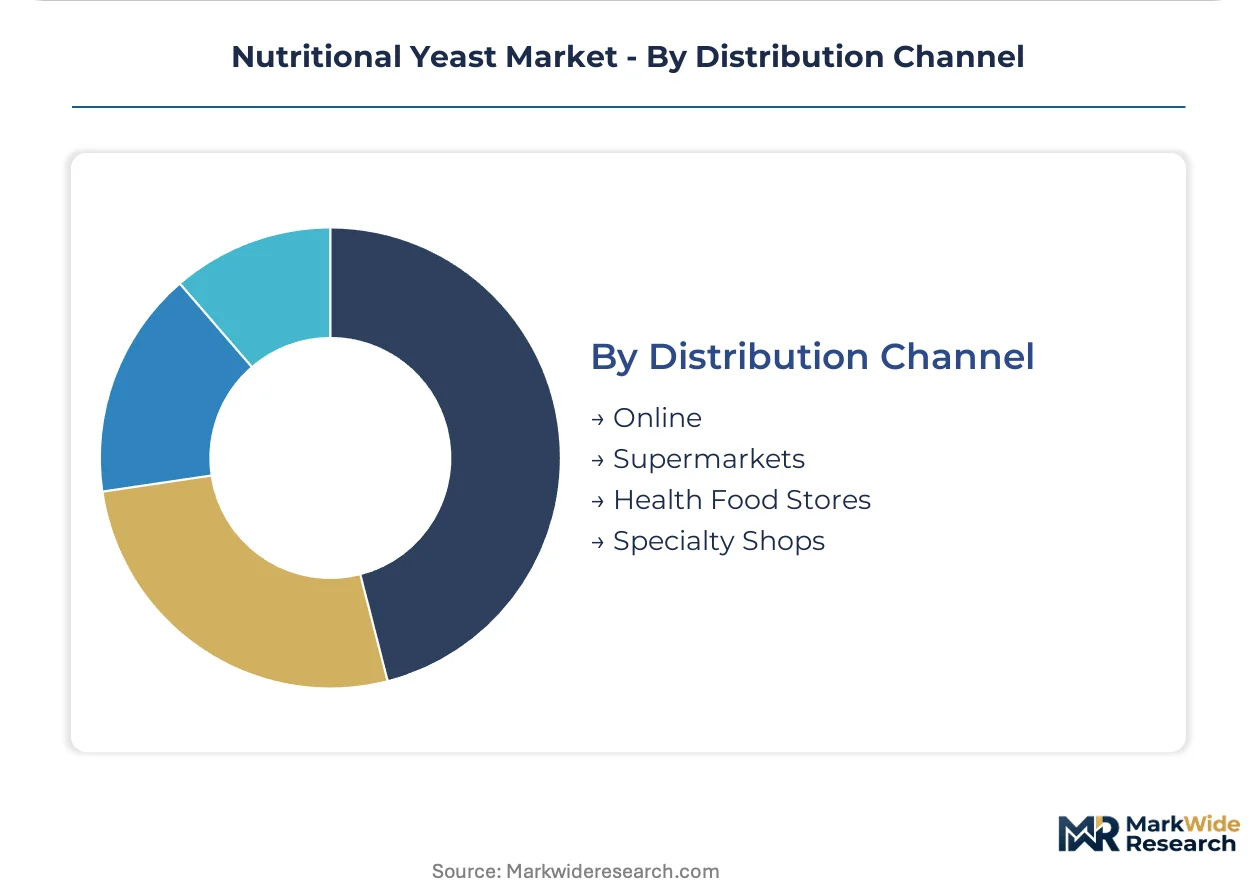
Customer type fragmentation—institutional procurement teams versus individual health-conscious consumers—shapes channel investment priorities and margin structures.
- Health Food Stores:United States natural grocery channels drive 40% of retail flake velocity through curated vegan product adjacencies. Staff expertise and sampling programs support premium positioning.
- Online:Direct-to-consumer subscription models bypass conventional retail slotting fees. Specialty flake formats partner with curated vegan meal kit services.
- Supermarkets:Mainstream grocery expansion depends on plant-based aisle consolidation and private label introductions.
- Specialty Shops:Vegan boutiques and co-ops serve localized demand with regional organic certification emphasis.
Health Food Stores hold the largest share; online shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports fortified nutritional yeast to German plant-based dairy processors under EFSA Novel Food compliance frameworks. Molasses substrate supply chains from sugar beet processing residues connect French fermentation campuses to United States health food retail channels.
United States
FDA GRAS status enables rapid beverage fortification trials by sports nutrition formulators. The USDA organic certification framework gates supplier eligibility for premium natural grocery placement. California and Oregon health food retail clusters drive 40 percent of domestic flake velocity through curated vegan product adjacencies.
Germany
Vegan cheese manufacturers source fortified nutritional yeast under EFSA Novel Food pathways to achieve umami depth. The country's national food safety regulator enforces 18-24 month assessment timelines for new substrate pathways. Bavarian and North Rhine-Westphalian industrial zones concentrate bulk procurement contracts from plant-based dairy processors.
China
Integrated fermentation campuses in Hubei and Guangxi provinces anchor Asia-Pacific flake and powder output. The national market regulator oversees standardized molasses feedstock quality protocols. Angel Yeast Co., Ltd. exemplifies the scale-driven archetype through captive substrate sourcing and controlled-temperature drying infrastructure.
France
Sugar beet processing residues in northern France supply standardized fermentation feedstock at commercial scale. EFSA Novel Food documentation requirements strain developers seeking agricultural waste stream approvals. The Picardy and Champagne-Ardenne regions host legacy fermentation facilities with decades of strain development expertise.
Canada
Health Canada regulates nutritional yeast as a food ingredient with established safety profiles for dietary supplement applications. Prairie province organic certification frameworks require 36-month substrate traceability documentation. Ontario and Quebec distribution hubs serve cross-border demand from United States natural grocery channels.
Nutritional Yeast Market Vendor Landscape
On the supply side, the industry is consolidating around integrated fermentation campuses with captive substrate sourcing and specialized drying infrastructure. Three strategic archetypes dominate: legacy yeast specialists with baker's yeast crossover capabilities, Asia-Pacific scale players with backward integration into molasses supply, and diversified ingredient conglomerates with portfolio synergies in plant-based nutrition. Dominant competitive moves include capacity expansion at existing fermentation campuses and technology licensing for precision fermentation strain development.
Among legacy specialists, Lesaffre S.A. and Lallemand Inc. occupy positions exemplifying decades of accumulated strain development expertise and probiotic-adjacent market positioning. Angel Yeast Co., Ltd. anchors the Asia-Pacific supply vector through integrated fermentation campus architecture. DSM-Firmenich and ABF Ingredients Group represent diversified ingredient conglomerates with nutritional yeast portfolios nested within broader human and animal nutrition segments.
| Leading Market Players |
|---|
| ABF Ingredients Group |
| Red Star Yeast Company |
| Lesaffre S.A. |
| Alltech, Inc. |
| Natural American Foods Inc. |
| Lallemand Inc. |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| Angel Yeast Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Molasses price volatility between Brazilian bioethanol diversion and Indian sugar harvest cycles determines both the premium spread for organic-certified nutritional yeast and the geographic shape of substrate sourcing networks. Buyers face widening tier separation as fermentation feedstock costs transmit unevenly across powder, flake, and fortified product categories.
Pricing Analysis
Legacy spray-drying infrastructure versus precision fermentation bioreactor investment creates a technology-generation pricing gap that stratifies manufacturer cost structures. Three-tier pricing separates organic-certified premium SKUs from conventional standard grades and commodity economy bulk supply, with certification grade and volume scale as the primary differentiation drivers. Cost compression in economy powder tiers is intensifying because Brazilian molasses diversion to bioethanol is tightening feedstock availability. Institutional food processors exhibit the highest price sensitivity due to formula cost targets, while dietary supplement brands absorb premium positioning for fortified variants.
Supply Chain Analysis
Tariff exposure between Chinese fermentation campuses and United States health food retail channels dominates supply chain risk planning for North American distributors. Production concentrates in China, France, and Germany, with the Asia-Pacific region drawing from captive sugar beet and cane molasses supply. Raw material dependencies rest on molasses substrate, specialized spray dryer components, and synthetic B12 fortification inputs. Single-source vulnerability concentrates in Hubei province integrated fermentation complexes. Distribution runs through bulk tanker shipments to industrial processors, with reclosable containers and flexible bags serving retail and e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nutritional yeast market sits at a platform-economics inflection where precision fermentation strain platforms are displacing legacy baker's yeast crossover infrastructure, with interoperability emerging between bioreactor control systems and downstream formulation software.
For Market Incumbents: Entrench position through backward integration into captive molasses supply in France and Germany, securing substrate traceability documentation for USDA organic certification. Add controlled-temperature drying capacity at existing fermentation campuses to defend margin position against precision fermentation entrants. Threat intensity concentrates in CRISPR strain developers achieving 40% protein density advantages.
For New Entrants and Emerging Players: Pursue sports nutrition white space in United States ready-to-mix protein powders, where complete amino acid profiles command formulation trials. Direct-to-consumer subscription channels offer the most penetrable entry vector, bypassing conventional retail slotting fees through curated vegan meal kit partnerships. Lead with technical formulation support as the go-to-market angle.
For Investors and Strategic Acquirers: Regional fermentation specialists with EFSA Novel Food dossier expertise represent the priority acquisition archetype, particularly those with parallel USDA organic certification capabilities. Long-term viability hinges on regulatory navigation speed rather than scale alone. Watch for EFSA guidance evolution on microbial biomass substrate disclosure as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | CRISPR strain editing combined with continuous bioreactor design enables protein density advantages. |
| Backward Integration into Molasses Supply | French sugar beet processing residues and Brazilian cane supply secure standardized fermentation feedstock. |
| EFSA Novel Food Dossier Investment | German and French regulatory affairs consolidation manages parallel USDA organic certification audits. |
| Direct-to-Consumer Channel Launch | Specialty flake formats bypass conventional retail slotting fees through vegan meal kit partnerships. |
| Sports Nutrition Formulation Partnership | United States protein powder brands leverage nutritional yeast for complete amino acid profiles. |
Methodological Framework
Cross-validation between fermentation technology suppliers and health food retail procurement managers anchors the qualitative findings on precision fermentation adoption timelines. Primary interviews with plant-based dairy formulators, dietary supplement R&D directors, regulatory affairs specialists at yeast manufacturers, and molasses procurement leads combined with secondary validation from EFSA Novel Food registers, USDA organic certification databases, FDA GRAS notices, and customs trade data. Bottom-up capacity assessments at integrated fermentation campuses triangulate against top-down demand modeling across product formats.
Calibration against historical protein fortification adoption curves and plant-based dairy expansion rates shapes the analytical framework across the analysis window. Segmentation dimensions include product type, end-user industry, packaging format, and distribution channel, with regional regulatory cluster as an additional modeled dimension. CAGRs derive from elasticity-adjusted demand projections incorporating molasses price cycle assumptions and EFSA assessment timeline distributions.
Sensitivities concentrate around EFSA Novel Food guidance evolution, Brazilian bioethanol policy shifts, and precision fermentation strain IP licensing structures. Forecasts reflect documented assumptions on substrate standardization and fortification claim thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Asia-Pacific Beta-Glucan Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
North America Bovine Lactoferrin Market