
 Calcium-Fortified Food Market | 2026-2036
Calcium-Fortified Food Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium-Fortified Food Market Analytics
The capital-intensity gap between multinational dairy processors and regional beverage specialists is collapsing. Nestlé S.A. leverages captive dairy sourcing networks across Switzerland and Southeast Asia to control input costs on calcium-fortified milk powders. Danone anchors its position through fermented dairy R&D platforms that sustain bioavailable calcium delivery formats. Abbott Laboratories competes in clinical nutrition by dominating hospital and pharmacy channels with prescription-grade fortified formulations.
Calcium-fortified food denotes edible products with added calcium salts—typically calcium carbonate, calcium citrate, or tricalcium phosphate—engineered to deliver measurable daily value percentages per serving, primarily to address dietary deficiencies and prevent osteoporotic conditions in target populations. Milk and yogurt segments lead volume due to inherent dairy-calcium synergy and established consumer acceptance, while cereals represent the fastest-growing category as breakfast manufacturers reformulate for pediatric and senior end users. The tablet form occupies premium margin pools through pharmacy and direct-to-consumer channels, whereas liquid formats sustain mainstream supermarket penetration.
EFSA nutrient reference values and FDA qualified health claims for calcium and osteoporosis jointly shape product positioning and label architecture across the European Union and United States. Japan's Ministry of Health, Labour and Welfare Foods for Specified Health Uses system creates a parallel compliance pathway for functional calcium claims in East Asian markets. Stakeholders must monitor evolving FSSAI fortification mandates in India and emerging GB standards in China to preempt market access constraints.
Market Dynamics
EFSA's tightening nutrient reference values and Japan's FOSHU recertification deadlines are compressing formulation lead times while forcing simultaneous compliance across multiple regulatory jurisdictions. Dairy processors must now validate calcium bioavailability claims through clinical endpoints rather than simple compositional analysis.
Growth Catalysts
- Aging Demographics in Japan and Germany:Government reimbursement programs for osteoporosis prevention are expanding eligible product categories. METI's functional food labeling system accelerates commercialization timelines for clinically validated formats.
- FSSAI Mandatory Fortification:India's 2023 wheat and rice fortification mandates create institutional procurement pipelines. State-level mid-day meal schemes now specify calcium-fortified staples for school nutrition programs.
- Encapsulation Technology Advances:Liposomal and nano-calcium delivery systems mask mineral off-flavors in plant-based beverages. Fermented dairy platforms leverage native pH buffering to sustain ionic calcium stability through shelf life.
Market Restraints
- Phosphate Supply Concentration:Tricalcium phosphate production clusters in Moroccan and Chinese phosphate rock processing corridors. Geopolitical friction disrupts long-term contract negotiations for North American formulators.
- EFSA Health Claim Restrictions:The 2022 bone health claim revision requires prospective fracture-risk reduction data. Retrospective calcium absorption studies no longer satisfy substantiation requirements.
- Plant-Based Calcium Bioavailability Gap:Oxalate and phytate interference reduces fractional absorption from fortified oat and almond bases. Formulators must over-dose mineral content to achieve labeled daily value percentages.
Strategic Opportunities
- Pediatric Cereal Reformulation:Breakfast manufacturers in Mexico and Brazil face mandatory micronutrient enrichment deadlines. Calcium-zinc-iron co-fortification protocols address multiple deficiency patterns in single-serve formats.
- Direct-to-Consumer Subscription Models:Pharmacy-adjacent delivery platforms bypass traditional retail slotting fee structures. Personalized dosing algorithms based on bone density screening data differentiate premium offerings.
- GB Standard Alignment in China:The 2024 national food safety standard revision harmonizes calcium additive maximum levels with Codex Alimentarius. Early compliance positions multinational brands for provincial procurement tenders.
Industry Challenges
- Clinical Validation Talent Scarcity:Bone turnover biomarker expertise concentrates in academic medical centers. Commercial R&D teams struggle to recruit dual-qualified nutrition scientists and regulatory affairs specialists.
- Cross-Contamination Control in Shared Facilities:Allergen management protocols for dairy-soy co-manufacturing extend sanitation downtime. Dedicated calcium-fortification lines require capital deployment that mid-tier processors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium-Fortified Food Market |
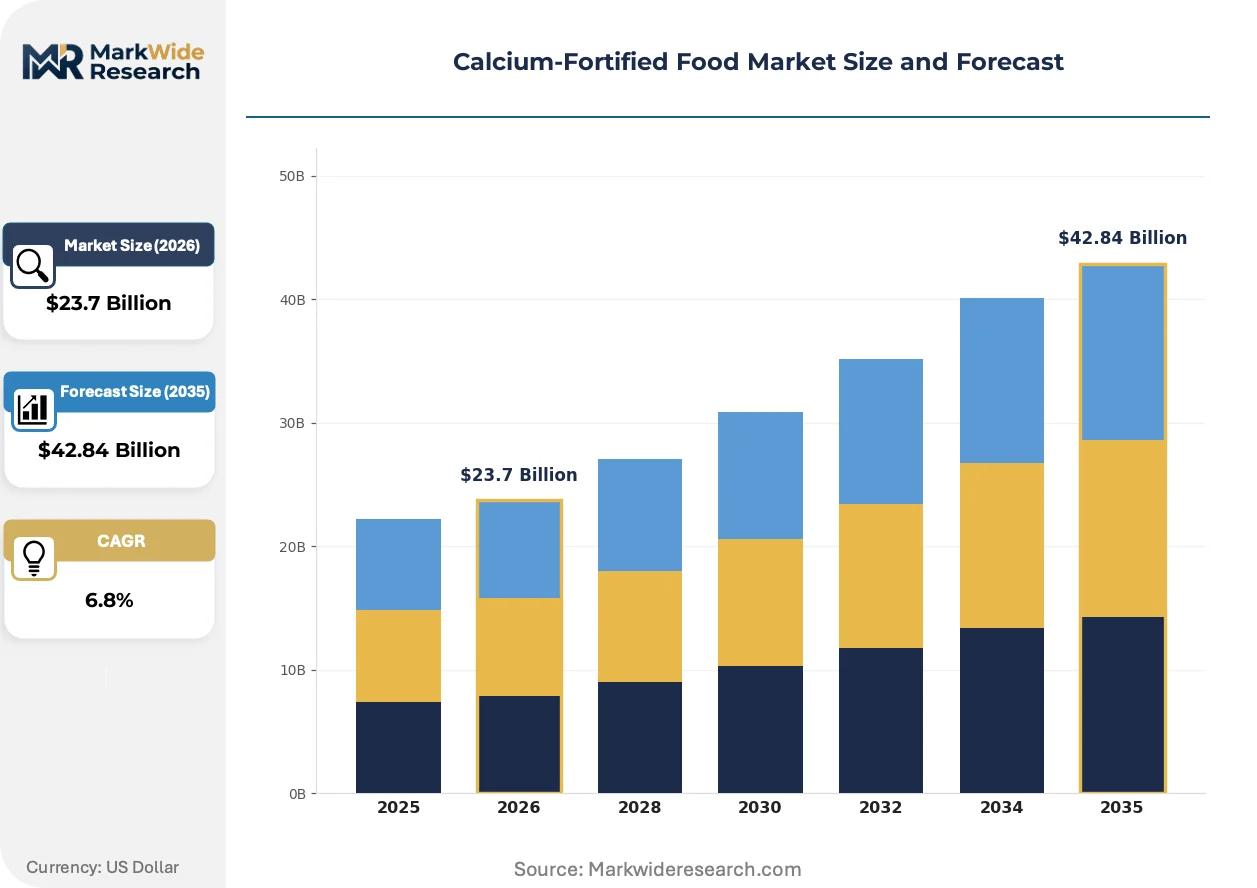
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Orange Juice, Cereals End User: Children, Adults, Seniors, Pregnant Women Form: Liquid, Powder, Granular, Tablet Distribution Channel: Supermarkets, Online, Health Stores, Convenience Stores |
| Companies Covered | General Mills Inc., Kellogg’s, Danone, Abbott Laboratories, Clif Bar & Company, Arla Foods amba, Lucerne Foods, Hain Celestial Group, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium-Fortified Food Market Evolving Landscape
Calcium delivery formats are fragmenting across temperature-stable, ambient, and frozen channels as bioavailability science advances beyond simple solubility metrics. Formulators now engineer matrix-specific mineral release kinetics matched to consumption occasion and co-ingested macronutrients.
Nano-encapsulated calcium carbonate is miniaturizing particle size distribution below 100 nanometers to bypass intestinal saturation kinetics. Pediatric nutrition manufacturers in Germany and South Korea are adopting these formats for fortified juice and puree applications. The technology is miniaturizing serving volume requirements while maintaining fractional absorption rates previously achievable only through larger carbonate doses.
EFSA's 2024 guidance on nutrient profiles restricts calcium fortification claims for products exceeding saturated fat thresholds. Reformulation teams in France and Italy are rebalancing dairy matrices to qualify for remaining permissible health claims. High-fat cheese and cream categories face effective exclusion from functional positioning unless processors deploy fat-replacement technologies.
Hospital procurement consortia are consolidating supplier panels around single-source clinical nutrition contracts. Abbott Laboratories and Nestlé Health Science now compete through outcome-based bone health protocols rather than unit pricing. German Krankenhaus purchasing alliances lead this consolidation, demanding fracture-risk reduction guarantees over 12-month intervention periods.
Calcium-Fortified Food Market Segmentation
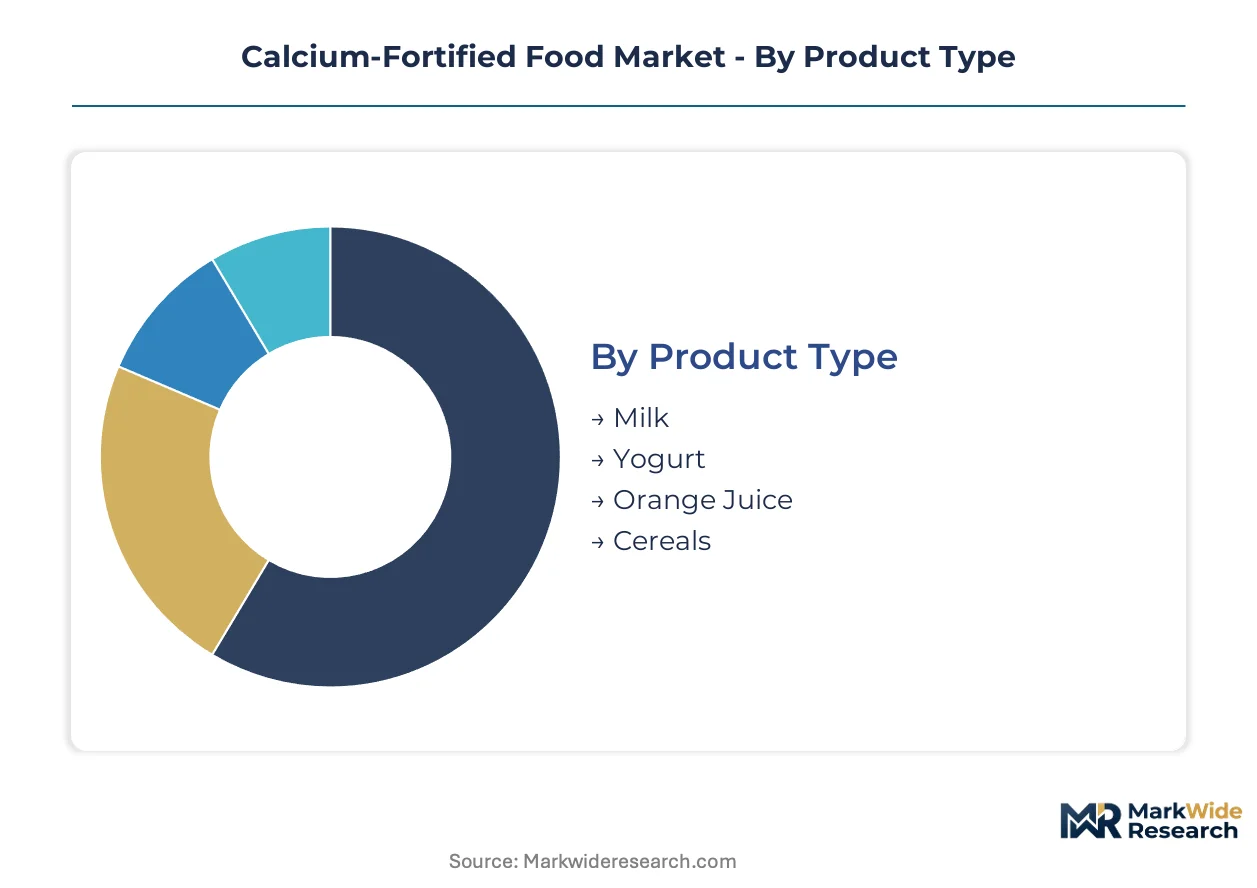
Calcium-fortified food segmentation reveals divergent margin architectures across delivery formats and demographic targeting. Product matrices must align bioavailability science with channel economics and regulatory claim eligibility.
Product Type:
Milk and yogurt concentrate premium margin pools through established dairy-calcium synergy and EFSA-permissible bone health claims. Cereals and functional beverages compete on volume throughput with thinner unit economics.
- Milk:Liquid dairy matrices deliver ionic calcium in highly bioavailable forms without encapsulation overhead. German and Japanese dairy processors leverage this native advantage for pharmacy-channel positioning under osteoporosis prevention reimbursement schemes.
- Yogurt:Fermented platforms exploit pH buffering to sustain mineral stability through shelf life while masking carbonate off-flavors. Abbott Laboratories and Danone anchor clinical nutrition portfolios through prescription-grade fermented formats.
- Orange Juice:Acidic matrices suit citrate salt solubility but require flavor masking for carbonate variants. Brazilian and Mexican processors face FSSAI import alignment for fortified concentrate exports.
- Cereals:Breakfast manufacturers in India and Brazil reformulate for mandatory micronutrient enrichment deadlines. Powder application technology determines coating uniformity and sensory acceptance in pediatric segments.
Milk holds installed capacity. Cereals is rotating up the share rankings.
End User:
Senior targeting commands pricing power through clinical validation requirements and pharmacy channel access. Pediatric positioning depends on institutional procurement scale rather than direct consumer premiumization.
- Children:School nutrition mandates in India and Mexico drive volume through fortified cereal and milk programs. Bioavailability over-dosing compensates for fractional absorption in co-fortified formats.
- Adults:Mainstream supermarket positioning emphasizes convenience and taste masking over clinical substantiation. German and US processors compete on daily value percentage claims per serving.
- Seniors:Bone turnover biomarker studies and fracture-risk endpoints now required for EFSA-permissible claims. Hospital procurement consortia in Germany consolidate around outcome-based supplier contracts.
- Pregnant Women:Pre-natal calcium requirements intersect with iron and folate co-fortification protocols. Japanese FOSHU system creates distinct compliance pathway for gestational health positioning.
Seniors hold installed capacity. Children is rotating up the share rankings.
Form:
Tablets and capsules extract maximum margin through pharmacy and direct-to-consumer channels where clinical credibility justifies price premiums. Liquid and powder formats compete on manufacturing scale and distribution efficiency.
- Liquid:Ambient-stable UHT processing dominates supermarket and institutional channels. Liposomal encapsulation now masks mineral off-flavors in plant-based beverage bases.
- Powder:Spray-dried formats enable dry blending flexibility for cereal and bakery applications. Reconstitution behavior determines consumer acceptance in emerging market contexts.
- Granular:Free-flowing properties suit automated dosing in industrial bakery and confectionery. Particle size distribution affects dispersibility in hot beverage matrices.
- Tablet:Compressed carbonate and citrate salts occupy premium pharmacy positioning. German and Swiss manufacturers lead bioequivalence validation for prescription-grade formats.
Tablet holds installed capacity. Liquid is rotating up the share rankings.
Distribution Channel:
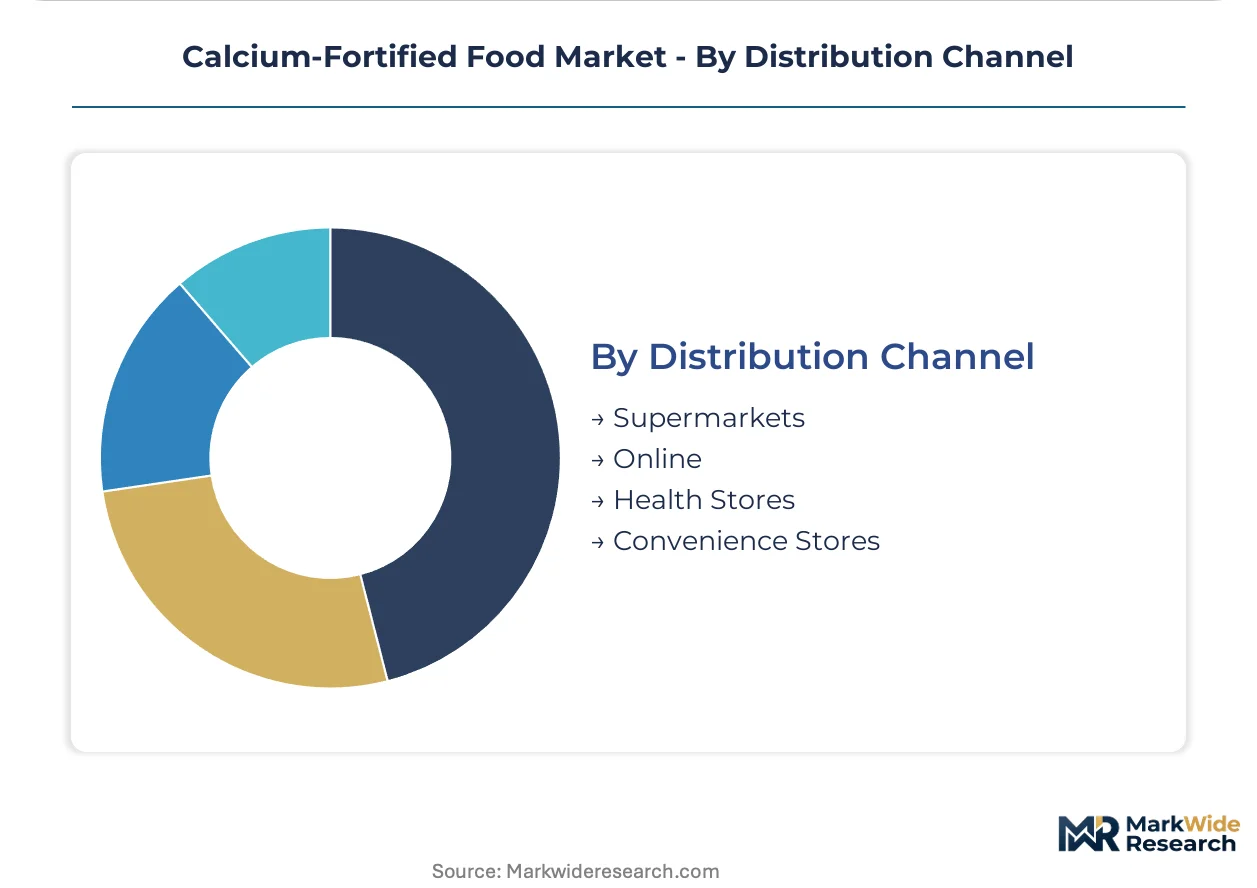
Health stores and pharmacy-adjacent platforms sustain margin through clinical credibility and personalized dosing guidance. Supermarket and convenience channels compete on velocity and slotting fee economics.
- Supermarkets:Mass-market velocity depends on shelf-stable formats and prominent daily value labeling. EFSA nutrient profile restrictions now exclude high-saturated-fat dairy from functional positioning.
- Online:Direct-to-consumer subscription models bypass retail slotting structures. Personalized algorithms using bone density screening data differentiate premium German and US offerings.
- Health Stores:Pharmacy-adjacent positioning demands clinical substantiation and trained staff consultation. Nano-calcium formats command shelf space through bioavailability differentiation.
- Convenience Stores:Single-serve liquid formats target impulse consumption and on-the-go occasions. Ambient stability requirements limit formulation options compared to refrigerated channels.
Supermarkets hold installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for calcium-fortified foods varies sharply across geographies. Japanese and German buyers accept clinical-grade premiums through pharmacy reimbursement pathways. Indian and Brazilian procurement operates on institutional bid economics where fortified staples compete on unit cost.
United States
Pharmacy-channel calcium supplements extract margin through bone density screening integration. FDA qualified health claims for osteoporosis prevention shape label architecture and substantiation requirements. Chicago and Minneapolis dairy processors dominate hospital nutrition contract bidding.
Germany
Krankenhaus purchasing alliances consolidate supplier panels around fracture-risk outcome guarantees. EFSA's 2022 bone health claim revision demands prospective clinical data for permissible positioning. Bavarian fermented dairy specialists anchor prescription-grade format production for Central European distribution.
Japan
Aging demographics drive FOSHU system utilization for functional calcium claims in dairy and beverage formats. METI's functional food labeling accelerates commercialization timelines for clinically validated products. Tokyo-Osaka corridor processors specialize in bioavailable delivery systems for senior nutrition.
India
FSSAI mandatory wheat and rice fortification mandates create state-level institutional procurement pipelines. Mid-day meal schemes specify calcium-fortified staples for school nutrition coverage. Gujarat and Maharashtra milling clusters retrofit powder application technology for uniform mineral coating.
Brazil
Mandatory micronutrient enrichment deadlines for breakfast cereals drive pediatric segment reformulation. ANVISA alignment with Codex Alimentarius maximum levels shapes import and export compliance. São Paulo food manufacturers integrate calcium-zinc-iron co-fortification for single-serve format efficiency.
Calcium-Fortified Food Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in calcium-fortified food manufacturing. The market structure tiers between multinational dairy processors with captive sourcing networks and regional beverage specialists leveraging encapsulation partnerships. Strategic archetypes include clinical nutrition validators, mass-market dairy integrators, and plant-based format innovators. Dominant competitive moves encompass pharmacy-channel outcome-based contracting and nano-encapsulation licensing for bioavailability differentiation.
Within the clinical nutrition tier, Abbott Laboratories and Danone occupy positions anchored by hospital procurement relationships and fermented platform expertise. Nestlé S.A. exemplifies the mass-market dairy integrator archetype through captive sourcing networks spanning Switzerland and Southeast Asia. These three players represent contrasting pathways to calcium-fortified food positioning—prescription-grade validation, dairy-native bioavailability, and global scale procurement integration.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kellogg's |
| Danone |
| Abbott Laboratories |
| Clif Bar & Company |
| Arla Foods amba |
| Lucerne Foods |
| Hain Celestial Group |
| Nestlé S.A. |
| Others |
Value Network & Pricing Analysis
Ninety-day formulation lead times for EFSA-compliant calcium-fortified dairy products compress inventory windows and concentrate pricing power among processors with validated clinical endpoints. German Krankenhaus procurement consortia exploit this tightness through outcome-based contracting that shifts margin risk upstream to suppliers lacking bioavailability certification.
Pricing Analysis
After-sales service contracts for bone density screening integration drive lifetime value in pharmacy-channel positioning. Three-tier pricing structure across premium, standard, and economy levels segments by clinical validation depth: prescription-grade formats with fracture-risk guarantees command maximum tier, supermarket daily-value claims occupy mid-tier, and institutional bid formats for school nutrition programs sit at economy tier. Cost compression in economy-tier cereal fortification is intensifying because Indian and Brazilian millers compete on unit cost for FSSAI-mandated procurement. Pediatric institutional buyers exhibit highest price sensitivity; German hospital procurement committees demonstrate lowest sensitivity when outcome guarantees are attached.
Supply Chain Analysis
Strategic stockpiling of tricalcium phosphate feedstock dominates over just-in-time preferences due to Moroccan and Chinese phosphate rock processing concentration. Raw material dependencies center on calcium carbonate from German and Swiss mineral processors, citrate salts from fermentation corridors in the Netherlands and Belgium, and nano-encapsulation polymers from Japanese chemical specialists. Single-source vulnerability in Moroccan phosphate concentrate creates supply chain risk for North American formulators lacking long-term contract coverage. Distribution runs through pharmacy-adjacent health stores for premium clinical formats and supermarket mass-market channels for mainstream dairy and cereal applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium-fortified food manufacturing builds defensive moats through regulatory entrenchment: EFSA and FOSHU certification timelines create switching costs that lock hospital procurement relationships and pharmacy channel access.
For Market Incumbents: Compound defensive positioning by deepening backward integration into phosphate rock processing or captive mineral sourcing to offset Moroccan supply concentration, while accelerating clinical validation pipelines to meet EFSA's prospective fracture-risk data requirements before 2022 claim revision deadlines tighten further. Channel control through exclusive hospital procurement consortia contracts in Germany anchors pricing power against plant-based entrants lacking bioavailability substantiation. For New Entrants and Emerging Players: Lead with nano-encapsulation technology licensing to bypass intestinal saturation kinetics in pediatric juice and puree segments where German and South Korean manufacturers have established early adoption curves. Direct-to-consumer subscription platforms with personalized dosing algorithms represent the most penetrable white space, bypassing supermarket slotting fee structures that favor Nestlé and Danone scale economics. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EFSA and FOSHU compliance pathways concentrate value capture among validated clinical nutrition platforms while excluding commodity dairy and cereal competitors from premium positioning. Acquisition targets should profile as regional beverage specialists with encapsulation partnerships and existing pharmacy-channel relationships. The signal to watch is FSSAI enforcement intensity for wheat and rice fortification mandates, which would accelerate institutional procurement scale for compliant processors.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Prospective fracture-risk studies satisfy EFSA 2022 claim revision requirements for pharmacy positioning. |
| Backward Integration into Mineral Sourcing | Captive phosphate processing insulates margin from Moroccan supply concentration and geopolitical friction. |
| Nano-Encapsulation Licensing | Sub-100 nanometer particle formats bypass intestinal saturation for pediatric nutrition applications in Germany. |
| Direct-to-Consumer Platform Launch | Subscription models with bone density algorithm integration bypass retail slotting fees and capture premium pricing. |
| FSSAI Compliance Acceleration | Early alignment with India's wheat and rice fortification mandates secures state-level institutional procurement pipelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy processing executives, regulatory affairs specialists at EFSA-notified bodies, hospital procurement managers in German Krankenhaus alliances, and encapsulation technology R&D directors; and secondary validation through EFSA guidance documents, FSSAI fortification mandates, FDA qualified health claim filings, and customs trade data for calcium salt imports. Bottom-up triangulation across product-level volume estimates and top-down macroeconomic anchoring ensured convergence.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type (milk, yogurt, cereals, beverages), end-user demographic (children, adults, seniors, pregnant women), delivery form (liquid, powder, tablet, granular), and distribution channel (supermarkets, online, health stores, convenience). CAGRs were derived from trend extrapolation of historical adoption curves adjusted for regulatory deadline impacts and demographic shift projections. Industry-specific inputs incorporated FOSHU recertification timelines and nano-calcium bioavailability study publication rates.
The analysis sits within stated boundaries; outcomes outside sustained EFSA enforcement of prospective clinical data requirements or disrupted phosphate concentrate supply from Moroccan processing corridors would require recalibration. Forecasts reflect assumptions regarding institutional procurement scale-up in India and Brazil and encapsulation technology cost curves. Revision becomes warranted when FSSAI enforcement intensity for mandatory fortification crosses implementation thresholds or when nano-calcium manufacturing scale achieves cost parity with conventional carbonate formats.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
High Calcium Fortified Food Market