
 Vitamin D Market | 2026-2036
Vitamin D Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin D Market Intelligence
REACH compliance is realigning the cost-of-entry calculus for European vitamin D suppliers by mandating full substance registration and safety dossiers for synthetic cholecalciferol imports. DSM Nutritional Products leverages captive fermentation capacity to control D3 active pharmaceutical ingredient supply from the Netherlands. BASF SE anchors its position through integrated 7-dehydrocholesterol precursor manufacturing at Ludwigshafen. Zhejiang Garden Biochemical High-Tech Co. Ltd navigates export certification complexity by maintaining dual GMP-REACH documentation systems for EU-bound shipments.
Vitamin D comprises a group of fat-soluble secosteroids, primarily ergocalciferol (D2) and cholecalciferol (D3), synthesized industrially via UVB irradiation of 7-dehydrocholesterol or ergosterol precursors with purity specifications typically exceeding 99.5% for pharmaceutical grades. The compound functions physiologically in calcium homeostasis, intestinal absorption, and osteoblast differentiation, driving its incorporation into prescription therapeutics, over-the-counter supplements, and food fortification matrices. Dietary Supplements occupies the dominant revenue position within product type segmentation due to direct-to-consumer subscription models and pharmacy loyalty programs. Immune Support application demand is expanding fastest among structural segments as post-pandemic consumer persistence sustains elevated D3 purchasing for T-cell modulation positioning. Bone Health retains mature volume status but faces margin compression from generic D2 commoditization in emerging markets.
FDA maintains Current Good Manufacturing Practice oversight for vitamin D supplement labeling and adulteration enforcement through routine facility inspections and warning letter authority. EFSA evaluates health claim substantiation under the EU Nutrition and Health Claims Regulation, rejecting unsubstantiated immunity assertions and approving only calcium absorption and bone maintenance claims. India's FSSAI mandates fortification compliance for edible oils and milk under national micronutrient deficiency programs. Stakeholders must monitor evolving pharmacovigilance signal detection for hypercalcemia risk as higher-dose D3 formulations gain over-the-counter traction without prescriber oversight.
Market Dynamics
REACH substance registration deadlines are compressing synthetic vitamin D3 import timelines for European supplement manufacturers, forcing accelerated safety dossier preparation and dual-sourcing validation.
Growth Catalysts
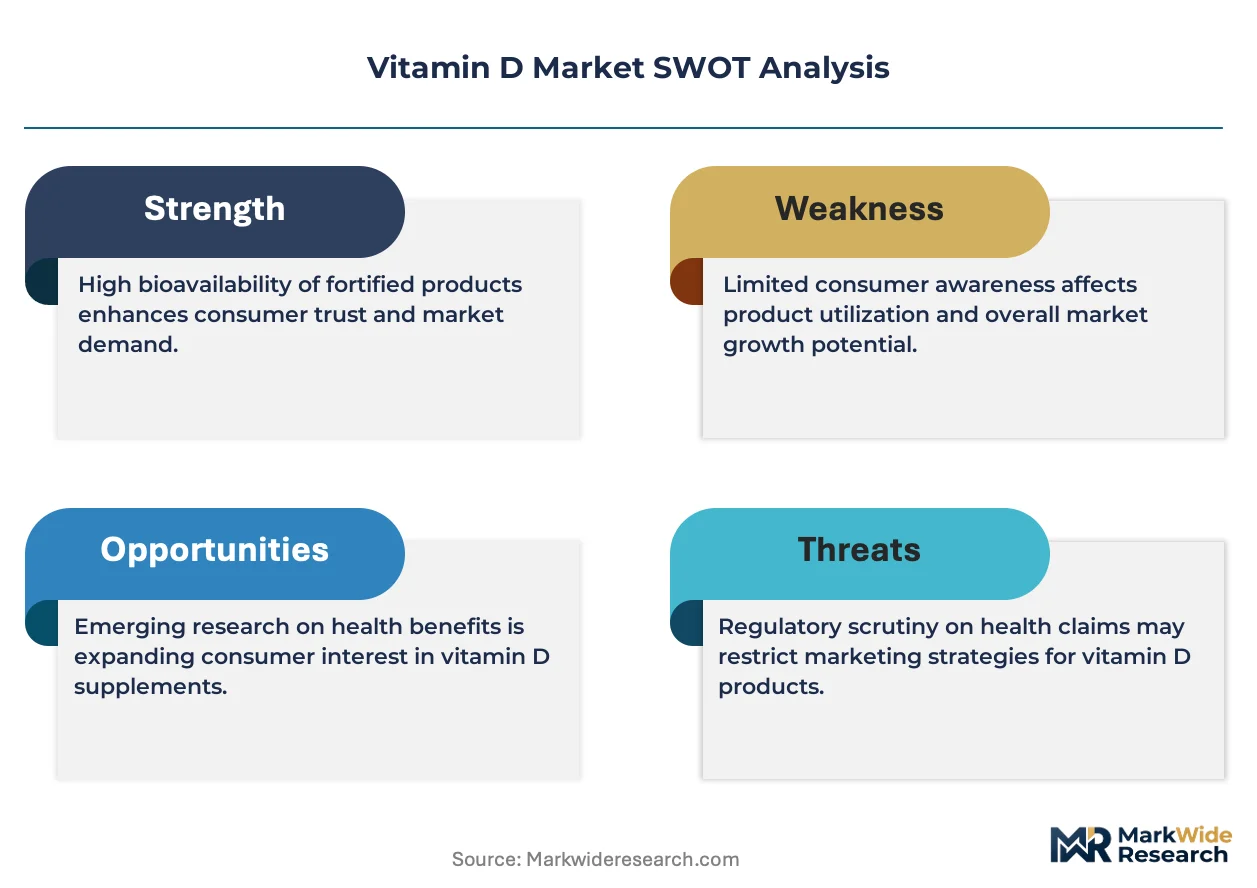
- EFSA-approved bone health claims:The EU Nutrition and Health Claims Regulation provides a permitted marketing foundation for calcium absorption positioning, enabling compliant product differentiation in pharmacy channels.
- FSSAI edible oil fortification mandates:India's national micronutrient deficiency programs create structural volume pull through compulsory D3 incorporation into mass-consumption food matrices.
- Post-pandemic T-cell modulation demand:Consumer persistence in immune support applications sustains elevated D3 purchasing patterns through direct-to-consumer subscription models.
Market Restraints
- 7-dehydrocholesterol precursor concentration:Synthetic D3 production relies on captive supply from integrated chemical manufacturers at Ludwigshafen and Rotterdam, creating single-point vulnerability.
- Hypercalcemia pharmacovigilance signals:Higher-dose over-the-counter formulations without prescriber oversight trigger national regulator safety reviews and dosing restriction proposals.
- Generic D2 commoditization:Ergocalciferol manufacturing in emerging markets erodes pricing power for mature bone health applications.
Strategic Opportunities
- Germany pharmacy-channel dominance:Structural supplement sales concentration through Apotheken creates premium positioning potential for validated immune support formulations.
- UVB irradiation process intensification:Continuous-flow photochemistry convergence with precision fermentation enables yield improvements in D3 active pharmaceutical ingredient production.
- Dual GMP-REACH documentation systems:Export certification complexity for EU-bound shipments rewards suppliers with pre-validated compliance infrastructure.
Industry Challenges
- Photochemical process engineering talent scarcity:Specialized UVB irradiation reactor design and scale-up expertise concentrates among legacy fine chemical manufacturers.
- Substance registration timeline compression:REACH dossier preparation for synthetic cholecalciferol imports demands 18-24 month lead times that outpace product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin D Market |
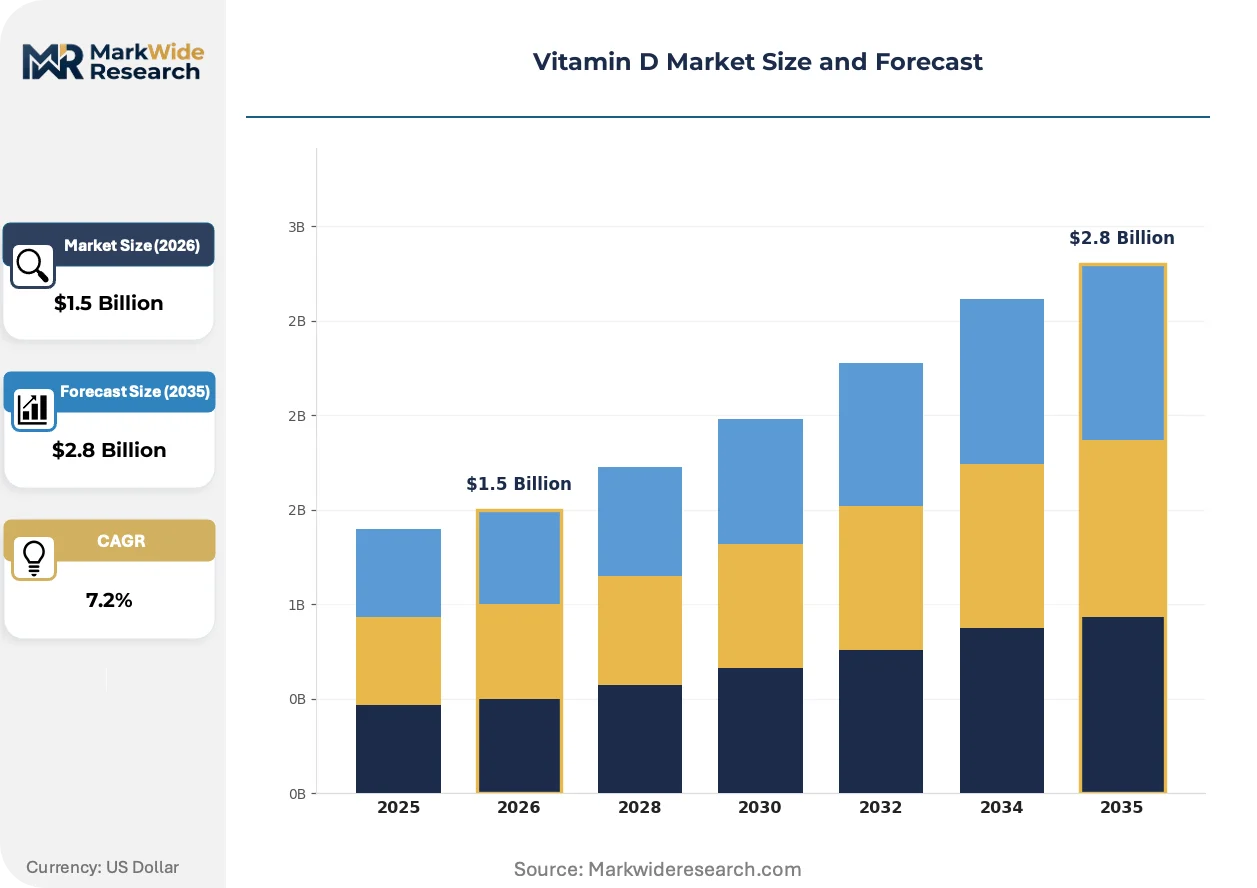
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin D2, Vitamin D3, Fortified Food, Dietary Supplements Application: Bone Health, Immune Support, Cardiovascular Health, Muscle Function Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores End User: Adults, Children, Elderly, Pregnant Women |
| Companies Covered | DSM Nutritional Products, BASF SE, Nestlé S.A., Pfizer Inc., Bayer AG, GlaxoSmithKline Plc, Zhejiang Garden Biochemical High-Tech Co. Ltd, Fermenta Biotech Ltd, Xiamen Kingdomway Vitamin Incorporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin D Market Strategic Shifts & Innovations
Photochemical process intensification and regulatory claim substantiation are restructuring competitive advantage in vitamin D manufacturing, with compliance infrastructure becoming as critical as production scale.
Continuous-flow UVB irradiation systems are absorbing batch reactor market share in D3 synthesis operations. Mid-scale dietary supplement manufacturers in the Netherlands and Germany are retrofitting legacy photochemical lines to reduce solvent waste and improve 7-dehydrocholesterol conversion yields. This technology is absorbing capital allocation that previously funded ergocalciferol capacity expansions, compressing D2 relevance in premium formulations.
REACH authorization requirements for synthetic vitamin D3 intermediates are tightening import documentation standards for non-European suppliers. The European Chemicals Agency's substance evaluation program now demands full exposure scenario assessments for pharmaceutical-grade cholecalciferol, extending registration timelines for Chinese and Indian exporters. German formulation houses are responding by qualifying captive fermentation-derived D3 from Dutch biotechnology suppliers to bypass synthetic intermediate classification.
Direct-to-consumer subscription models are displacing pharmacy counter purchasing for maintenance-dose D3 regimens. Wellness platform integrations with German and US telehealth providers enable automated replenishment tied to seasonal sunlight exposure data, bypassing traditional retail distribution. This channel shift concentrates most visibly in urban consumer segments where convenience positioning outweighs pharmacist consultation preferences.
Vitamin D Market Segmentation
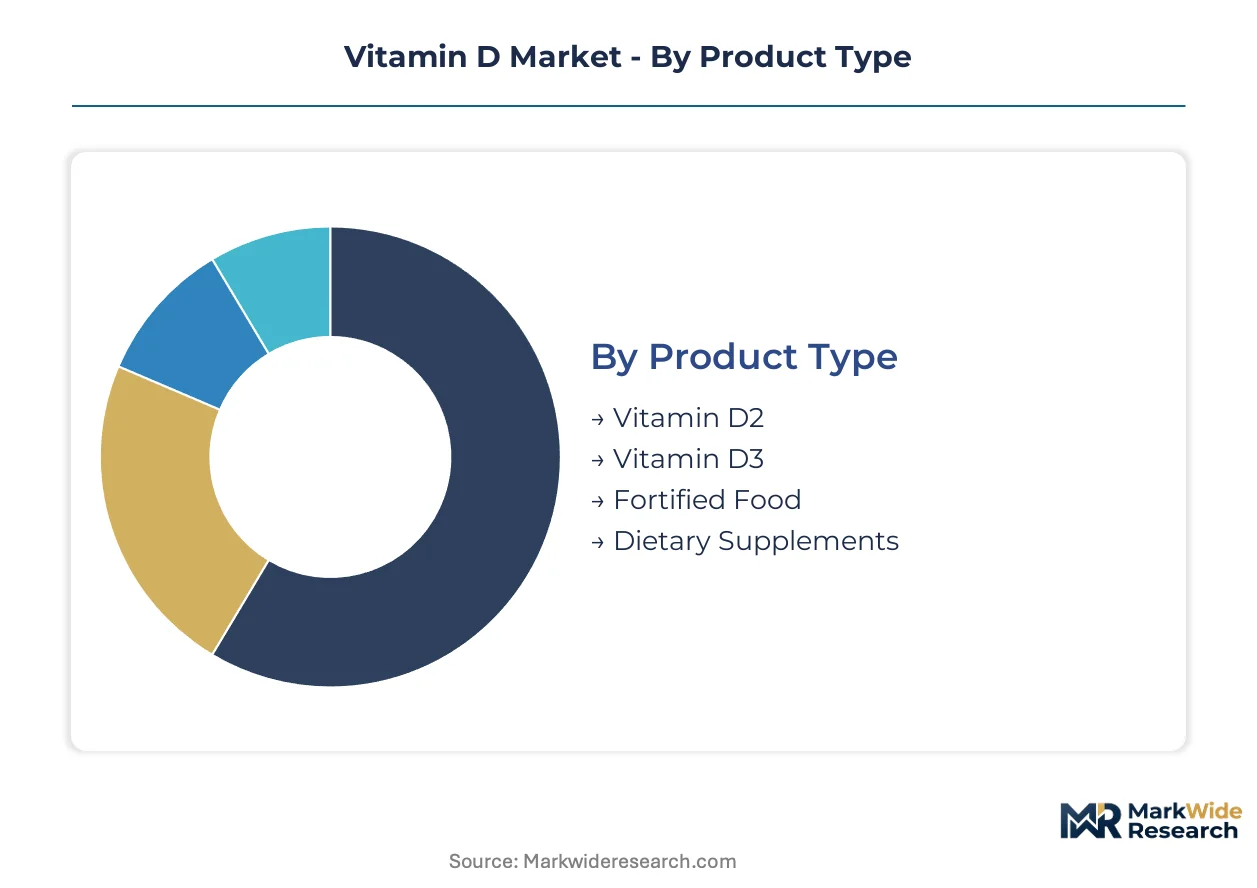
Vitamin D market segmentation reflects divergent regulatory pathways and formulation requirements across pharmaceutical, nutraceutical, and food matrices. Each category demands distinct certification burdens, from EFSA health claim substantiation to FSSAI fortification compliance, shaping supplier qualification and margin structures.
Product Type:
Certification requirements split sharply across synthetic versus natural-origin vitamin D forms, with pharmaceutical-grade D3 demanding REACH registration and GMP validation while food-grade D2 navigates simpler additive approvals.
- Vitamin D2:Ergocalciferol synthesized via UVB irradiation of ergosterol from yeast or fungal sources, typically specified at 98-102% purity for food additive applications. Demand concentrates in India and Southeast Asia where FSSAI and national regulators permit cost-driven fortification of edible oils and cereals, constrained by thermal instability during cooking processes.
- Vitamin D3:Cholecalciferol produced through 7-dehydrocholesterol photochemical conversion or lanolin-derived precursors, commanding pharmaceutical-grade specifications exceeding 99.5% purity. German and Dutch pharmacy channels prioritize D3 for EFSA-compliant bone health positioning, with REACH-registered synthetic supply qualifying for EU therapeutic applications.
- Fortified Food:Microencapsulated D3 or D2 integrated into dairy, beverages, and bakery matrices requiring stability validation through shelf-life testing and sensory impact assessment.
- Dietary Supplements:Softgel, tablet, and liquid delivery formats combining D3 with absorption-enhancing lipids, subject to FDA CGMP labeling enforcement and EFSA health claim restrictions.
Leading the category by volume: Dietary Supplements. Growing fastest: Vitamin D3.
Application:
Application segments diverge by evidentiary burden, with bone health claims resting on decades of clinical validation while immune support positioning navigates stricter substantiation thresholds.
- Bone Health:Calcium homeostasis and osteoblast differentiation applications supported by EFSA-approved health claims for calcium absorption and bone maintenance, anchoring mature volume in German pharmacy sales and prescription therapeutics.
- Immune Support:T-cell modulation and cytokine regulation positioning, expanding through direct-to-consumer subscription channels in urban US and German markets despite EFSA rejection of unsubstantiated immunity assertions.
- Cardiovascular Health:Endothelial function and blood pressure modulation research, currently confined to clinical study populations without approved health claims in major jurisdictions.
- Muscle Function:Sarcopenia prevention and falls reduction in elderly populations, gaining traction in Japanese functional food applications under Foods with Function Claims framework.
Volume leadership resides in Bone Health. Steepest expansion trajectory: Immune Support.
Distribution Channel:
Channel selection determines pricing architecture and regulatory exposure, with pharmacy counters enforcing pharmacist consultation requirements that online platforms bypass.
- Pharmacies:German Apotheken and comparable EU pharmacy-channel dominance enforces prescription-grade dispensing protocols and insurance reimbursement pathways for therapeutic doses.
- Online Retail:Direct-to-consumer subscription models and wellness platform integrations enabling automated replenishment tied to seasonal sunlight data, concentrated in US and UK urban consumer bases.
- Supermarkets:Mass-market fortified food and low-dose supplement placement, scaling through India's FSSAI-mandated edible oil fortification programs.
- Health Stores:Specialty supplement retail with practitioner-grade positioning, emphasizing third-party testing certifications and clean-label formulations.
Pharmacies command the largest revenue share. Online Retail is climbing the fastest.
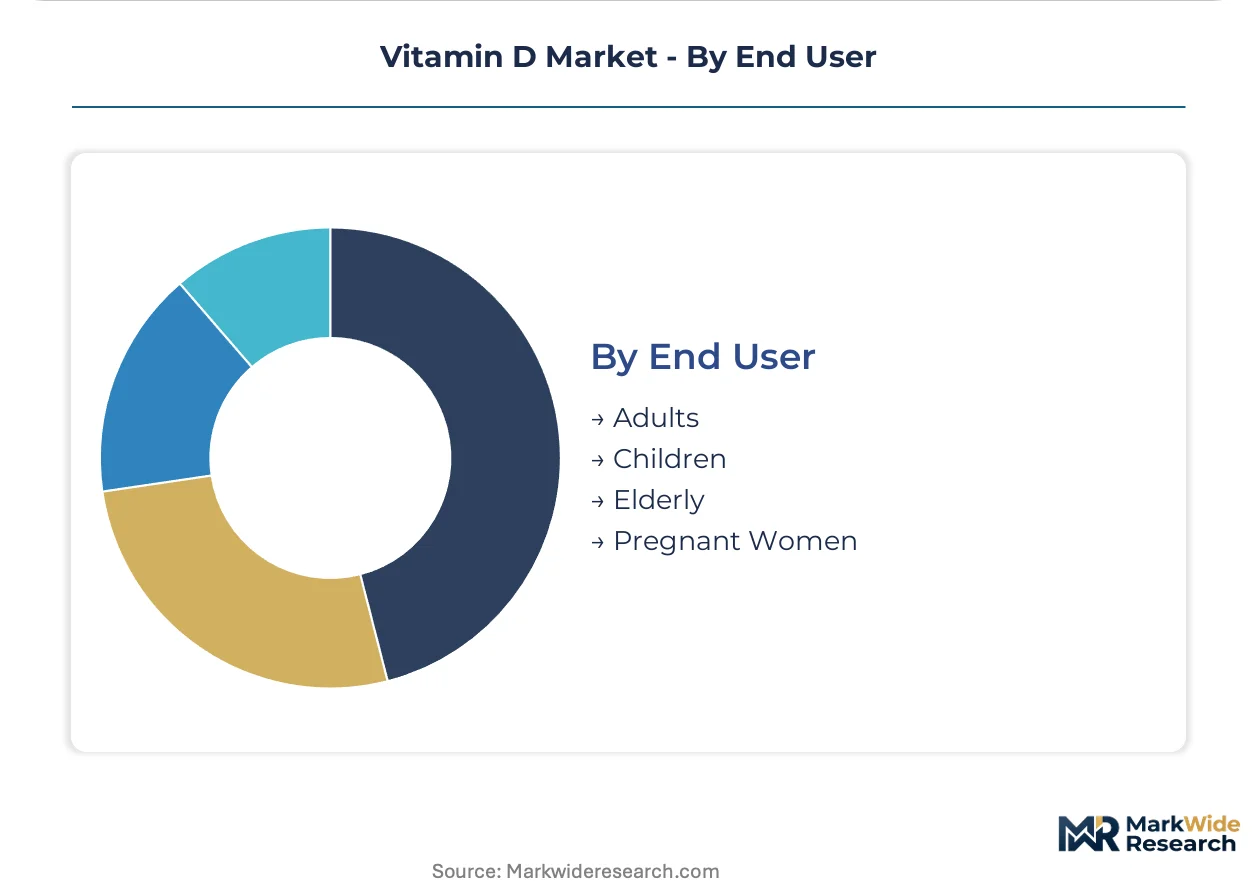
End User:
End-user segmentation reflects physiological dosing requirements and risk-profile differentiation, from pediatric RDA compliance to geriatric falls-prevention protocols.
- Adults:Maintenance-dose supplementation for office-worker populations with limited solar exposure, driving subscription-model adoption in North American and Northern European markets.
- Children:RDA-compliant fortification through dairy and pediatric formulations, subject to strict upper-limit regulations by FDA and EFSA to prevent hypercalcemia risk.
- Elderly:High-dose therapeutic regimens for osteoporosis and sarcopenia management, concentrated in Japanese and German long-term care and outpatient clinic channels.
- Pregnant Women:Prenatal formulations with fetal bone development positioning, requiring teratogenicity safety data and obstetrician endorsement in prescription-adjacent channels.
Adults represent the largest addressable population. Elderly applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Netherlands and Singapore concentrate vitamin D3 active pharmaceutical ingredient distribution, while India's special economic zones drive ergocalciferol export manufacturing. Pharmaceutical-grade production clusters in Germany and China anchor global supply quality tiers.
Germany
Apotheken pharmacy-channel sales dominate consumer vitamin D3 purchasing through prescription-adjacent dispensing protocols. EFSA enforces strict health claim substantiation under the EU Nutrition and Health Claims Regulation, permitting only calcium absorption and bone maintenance assertions. The Ludwigshafen chemical cluster hosts integrated 7-dehydrocholesterol precursor manufacturing for pharmaceutical-grade cholecalciferol synthesis.
United States
Direct-to-consumer subscription models displace pharmacy counter purchasing for maintenance-dose D3 regimens in urban consumer segments. FDA maintains Current Good Manufacturing Practice oversight for supplement labeling and adulteration enforcement through routine facility inspections. Wellness platform integrations with telehealth providers concentrate in California and New York metro areas, enabling automated replenishment tied to seasonal sunlight exposure data.
India
FSSAI-mandated edible oil fortification programs create structural volume pull through compulsory D3 incorporation into mass-consumption food matrices. The national micronutrient deficiency program requires compliance across dairy and oil processing facilities. Gujarat and Maharashtra host ergocalciferol manufacturing clusters serving domestic fortification demand and Southeast Asian export markets.
China
Zhejiang province anchors export-oriented vitamin D3 manufacturing with dual GMP-REACH documentation systems for EU-bound shipments. SAMR and NMPA regulate pharmaceutical-grade production under national drug manufacturing standards. The Yangtze River Delta concentration supports photochemical synthesis operations with integrated precursor supply chains.
Netherlands
Rotterdam port logistics and fermentation biotechnology clusters enable captive D3 active pharmaceutical ingredient supply to European formulation houses. ECHA REACH substance registration requirements compress synthetic import timelines, accelerating qualification of fermentation-derived alternatives. DSM Nutritional Products leverages biotechnology capacity to bypass synthetic intermediate classification for EU therapeutic applications.
Vitamin D Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across vitamin D manufacturing tiers, creating a bifurcated structure where scale advantages clash with agility. The market organizes around three strategic archetypes: integrated chemical manufacturers with captive precursor supply, biotechnology specialists leveraging fermentation-derived production, and formulation houses concentrating on end-product differentiation. Dominant competitive moves include backward integration into 7-dehydrocholesterol precursor manufacturing and qualification of dual-sourcing networks to satisfy REACH registration requirements.
Within the integrated chemical tier, DSM Nutritional Products and BASF SE exemplify European conglomerates with captive supply chain control, while Zhejiang Garden Biochemical High-Tech Co. Ltd represents Chinese specialists navigating export certification complexity. These three anchors illustrate divergent geographic and technological positioning strategies across the value chain.
| Leading Market Players |
|---|
| DSM Nutritional Products |
| BASF SE |
| Nestlé S.A. |
| Pfizer Inc. |
| Bayer AG |
| GlaxoSmithKline Plc |
| Zhejiang Garden Biochemical High-Tech Co. Ltd |
| Fermenta Biotech Ltd |
| Xiamen Kingdomway Vitamin Incorporation |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade certification tiering splits vitamin D markets into parallel pricing tracks, with REACH-registered synthetic D3 commanding sustained premiums over food-grade D2 alternatives while supply chain configurations diverge around captive precursor manufacturing versus spot-import dependencies.
Pricing Analysis
Lead-time compression premiums reward suppliers with pre-validated REACH dossiers and dual GMP documentation, while spot-market ergocalciferol from Indian exporters trades at structural discounts. Three-tier pricing structure across pharmaceutical, nutraceutical, and food additive grades reflects purity specifications and regulatory burden differentiation. Pricing pressure stems from generic D2 commoditization in emerging market fortification programs. Mass-market edible oil processors exhibit highest price sensitivity, whereas German pharmacy-channel buyers prioritize EFSA-compliant sourcing over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired or degraded vitamin D inventory remain underdeveloped, creating working capital inefficiencies for distributors holding temperature-sensitive stock. Supply concentrates in Germany, China, and India, with Ludwigshafen and Zhejiang province anchoring pharmaceutical-grade photochemical synthesis. Production draws from 7-dehydrocholesterol precursors, lanolin-derived intermediates, and ergosterol feedstocks. Single-source vulnerability concentrates around integrated precursor manufacturers at Rotterdam and Ludwigshafen. Distribution runs through Rotterdam port logistics for EU-bound shipments, with direct API supply to Dutch formulation houses bypassing trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitamin D manufacturing is consolidating around compliance infrastructure investments that weaker players cannot replicate, with REACH registration timelines and dual-certification costs forcing exit decisions among non-integrated suppliers.
For Market Incumbents: Deploy captive fermentation capacity to bypass synthetic intermediate classification under ECHA substance evaluation programs. BASF SE and DSM Nutritional Products should extend backward integration into 7-dehydrocholesterol precursor manufacturing to secure supply continuity against Rotterdam logistics disruptions. Qualifying dual-sourcing networks for Indian and Chinese API suppliers mitigates single-point vulnerability from Ludwigshafen production concentration. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for maintenance-dose D3 regimens, bypassing pharmacy-channel dispensing protocols that incumbents dominate. Wellness platform integrations with telehealth providers in California and New York metro areas enable automated replenishment tied to seasonal sunlight data. White-space exists in microencapsulated D3 for beverage fortification, where stability validation capabilities remain scarce among mid-scale suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-derived D3 specialists given ECHA's tightening synthetic intermediate classification and extended registration timelines for photochemical imports. Long-term viability favors biotechnology suppliers with captive API capacity serving EU therapeutic applications. The signal to monitor is EFSA's evolving stance on immune support claim substantiation, which would redirect formulation R&D spending and reshape margin structures across application segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | BASF SE's Ludwigshafen cluster secures 7-dehydrocholesterol supply against Rotterdam bottlenecks. |
| Fermentation-Derived D3 Capacity Expansion | DSM Nutritional Products bypasses REACH synthetic intermediate classification for EU therapeutic markets. |
| Dual GMP-REACH Documentation Systems | Zhejiang Garden Biochemical maintains EU export qualification despite ECHA timeline compression. |
| Direct-to-Consumer Subscription Platform Launch | Wellness platforms displace pharmacy purchasing in California and New York metro areas. |
| Microencapsulation Technology Investment | Beverage fortification applications demand shelf-life stability validation that few mid-scale suppliers possess. |
Research Approach
Document review covered EFSA health claim registers, ECHA REACH substance evaluation records, and FSSAI fortification compliance directives, complemented by interviews with plant managers at photochemical synthesis facilities, procurement leads at German pharmacy-channel distributors, regulatory affairs specialists navigating dual-certification requirements, and technical R&D directors developing microencapsulation stability protocols. Secondary validation incorporated customs and trade data from Rotterdam and Hamburg ports, SEC 10-K filings from diversified chemical conglomerates, and national micronutrient deficiency program reports. Bottom-up volume modeling triangulated against top-down value estimates across product type and application segments.
Cross-referencing historical pricing spreads between pharmaceutical-grade D3 and food-grade D2 against expert panel assessments of REACH registration cost pass-through informed the analytical framework across the analysis window. Segmentation dimensions modeled included product grade tier, end-use application, distribution channel structure, and regional regulatory cluster. CAGRs derived from slope-consistency checks against base-year anchor points and terminal-year demand saturation assumptions. Industry-specific inputs encompassed photochemical process yield improvements and FSSAI edible oil fortification mandate compliance rates.
The model holds under stable REACH substance evaluation timelines and continued EFSA restriction of unsubstantiated immunity claims; deviation in ECHA's synthetic intermediate classification scope or FDA hypercalcemia safety review outcomes would shift volume trajectories between D2 and D3 forms. Forecasts reflect these base-case assumptions without contingency weighting. Practitioners should monitor EFSA's health claim substantiation guidance updates and ECHA's substance evaluation program prioritization for early signals of regulatory inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Gamma-Tocopherol Market