
 Quillaja Saponaria Ingredient Market | 2026-2036
Quillaja Saponaria Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Quillaja Saponaria Ingredient Market Analytics
Chilean quillaja bark harvesters and extract processors is recalibrating export volumes amid rising international offtake. Desert King International leverages captive plantation access in Chile's arid zones to sustain raw material security. Ingredion Incorporated anchors North American distribution through its ingredient formulation networks. Garuda International Inc. specializes in botanical extract purification for pharmaceutical-grade specifications.
Quillaja saponaria ingredient denotes triterpenoid saponin complexes extracted from the inner bark of the soapbark tree, typically comprising quillaic acid glycosides with foaming indices exceeding 200 and critical micelle concentrations near 0.5 g/L, functioning primarily as natural surfactants, emulsifiers, and adjuvants across formulated products. The food and beverage application segment leads volume absorption as carbonated drink manufacturers replace synthetic foaming agents with botanical alternatives, while the liquid extract form captures the dominant share of technical procurement due to superior dispersion characteristics in aqueous systems. The natural source category commands premium positioning as organic certification requirements harden across European and North American procurement specifications.
Chile's CONAF forestry service regulates quillaja bark harvesting quotas under native species protection statutes, while the FDA governs GRAS status determinations for food-grade saponin incorporation in the United States. REACH compliance in Europe mandates full saponin constituent disclosure for cosmetic and pharmaceutical applications. Stakeholders must monitor evolving extraction yield improvements and substitution threats from synthetic saponin analogs as they allocate capacity investments across the value chain.
Market Dynamics
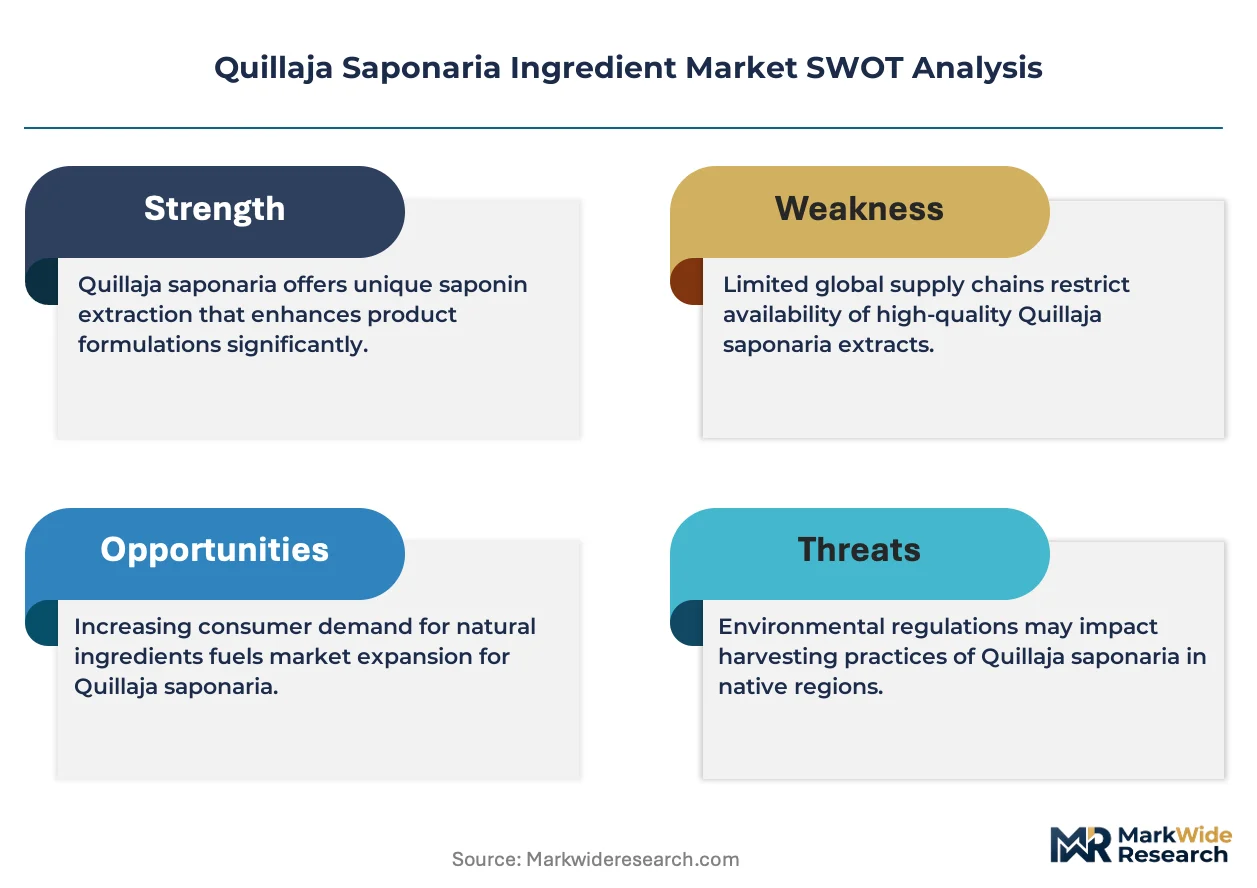
Chile's CONAF forestry service has tightened quillaja bark harvesting quotas under native species protection statutes, compressing raw material availability while North American beverage formulators accelerate clean-label reformulation timelines. This regulatory supply constraint against surging demand for natural emulsifiers is forcing extraction yield investments and geographic sourcing diversification across the value chain.
Growth Catalysts
- Clean-label mandates:F&B manufacturers in the United States are replacing synthetic foaming agents with botanical alternatives under tightening FDA GRAS disclosure expectations.
- REACH constituent disclosure:European cosmetic and pharmaceutical formulators now require full saponin profiling, creating technical differentiation for purified extract suppliers.
- Arid-zone plantation development:Captive cultivation in Chile's northern regions is reducing wild-harvest dependency while securing organic certification pathways.
Market Restraints
- Raw material concentration:Over 80 percent of wild quillaja bark originates from Chile's central valley zones, exposing processors to climate-driven harvest volatility.
- Extraction yield ceilings:Conventional aqueous extraction methods recover only 12-18 percent of available saponin content, limiting unit economics at scale.
- Synthetic saponin analogs:Petroleum-derived surfactants from BASF and Dow maintain cost advantages in mass-market detergent and industrial applications.
Strategic Opportunities
- Pharmaceutical adjuvant specifications:Vaccine formulation standards are incorporating quillaja-derived immunostimulatory complexes, opening high-margin technical segments.
- Carbonated functional beverages:Energy drink and adaptogenic seltzer categories in the United States are specifying quillaja for foam stability without artificial additives.
- Organic certification premiums:USDA Organic and EU Organic label requirements are widening price spreads between certified and conventional extract grades.
Industry Challenges
- Skilled harvester scarcity:Traditional bark strippers in Chile's rural zones are aging without generational replacement, threatening sustainable collection practices.
- Multi-jurisdiction compliance timelines:Simultaneous FDA GRAS petitions, EFSA novel food assessments, and CONAF export permits extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quillaja Saponaria Ingredient Market |
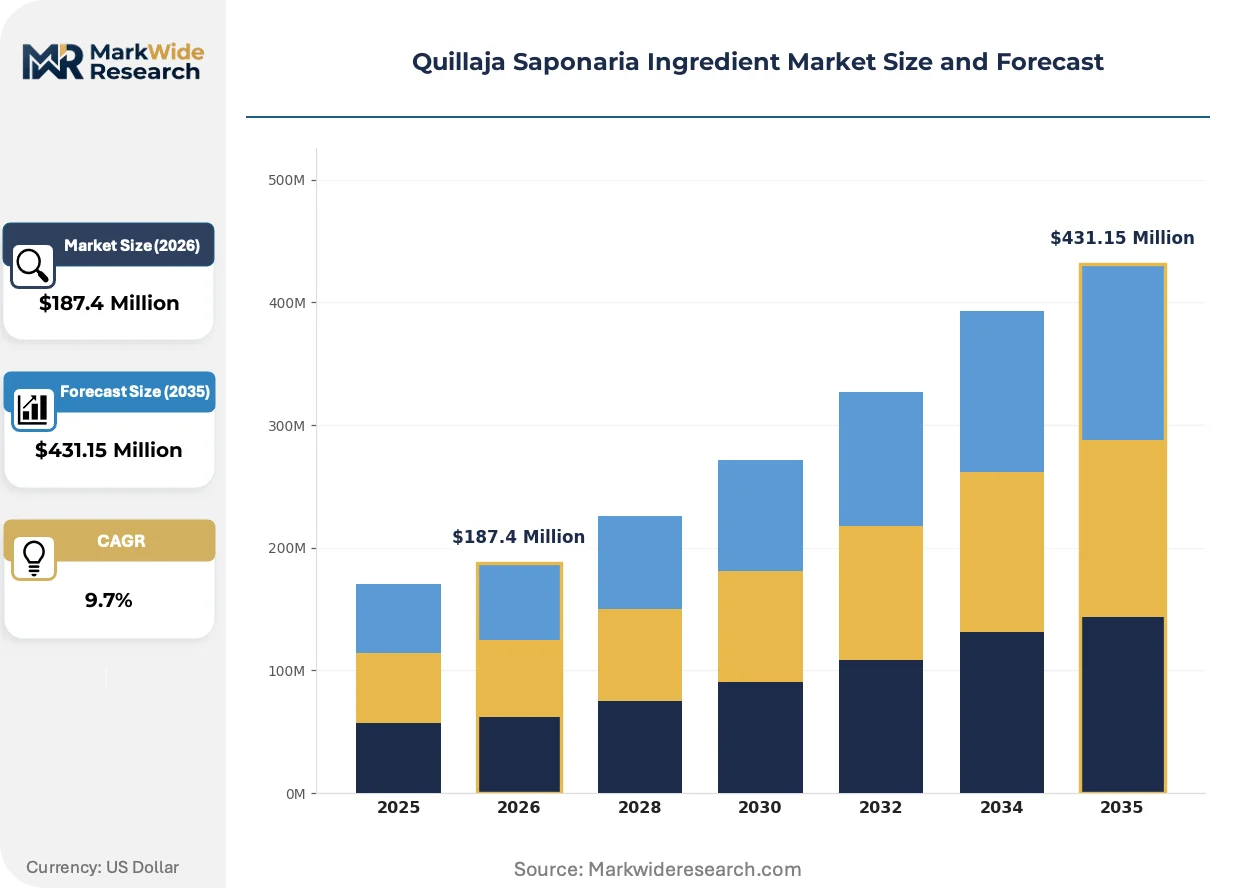
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cosmetics, Food & Beverage, Pharmaceuticals, Animal Feed Form: Liquid Extract, Powder, Granules, Capsules Source: Natural, Organic, Synthetic, Bio-Based End User: Manufacturers, Distributors, Retailers, Research Institutions |
| Companies Covered | Garuda International Inc., Chile Botanics S.A, Ingredion Incorporated, Givaudan SA, Naturex S.A, Desert King International, Baja Yucca Company, Quillaja Green Biosolutions, Plantae Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quillaja Saponaria Ingredient Market Evolving Landscape
Supercritical CO2 extraction and membrane filtration technologies are displacing conventional solvent-based methods, enabling higher-purity saponin fractions with reduced environmental discharge. These process innovations are compressing the gap between food-grade and pharmaceutical-grade specifications while opening new application categories.
Membrane filtration systems with molecular weight cut-offs between 10-50 kDa are integrating into Chilean processing facilities to separate quillaic acid glycosides from polyphenolic co-extractives. North American beverage formulators are adopting these refined extracts for transparent finished products. The technology is integrating previously separate food and pharmaceutical supply chains, forcing mid-tier extractors to upgrade or exit.
REACH Article 33 disclosure requirements for saponin constituents above 0.1 percent concentration are compelling European cosmetic manufacturers to demand certified analytical profiles from Chilean suppliers. ECHA enforcement actions against incomplete SDS documentation have accelerated third-party testing adoption. Small-scale harvester cooperatives are consolidating to afford the required chromatographic certification infrastructure.
Carbonated drink manufacturers are specifying liquid extract forms over powdered alternatives to eliminate reconstitution steps and reduce batch variability. Procurement teams are negotiating direct supply agreements with Chilean processors, bypassing traditional botanical distributors. This disintermediation is most visible in the United States, where functional beverage startups with in-house formulation capabilities are establishing captive sourcing relationships.
Quillaja Saponaria Ingredient Market Segmentation
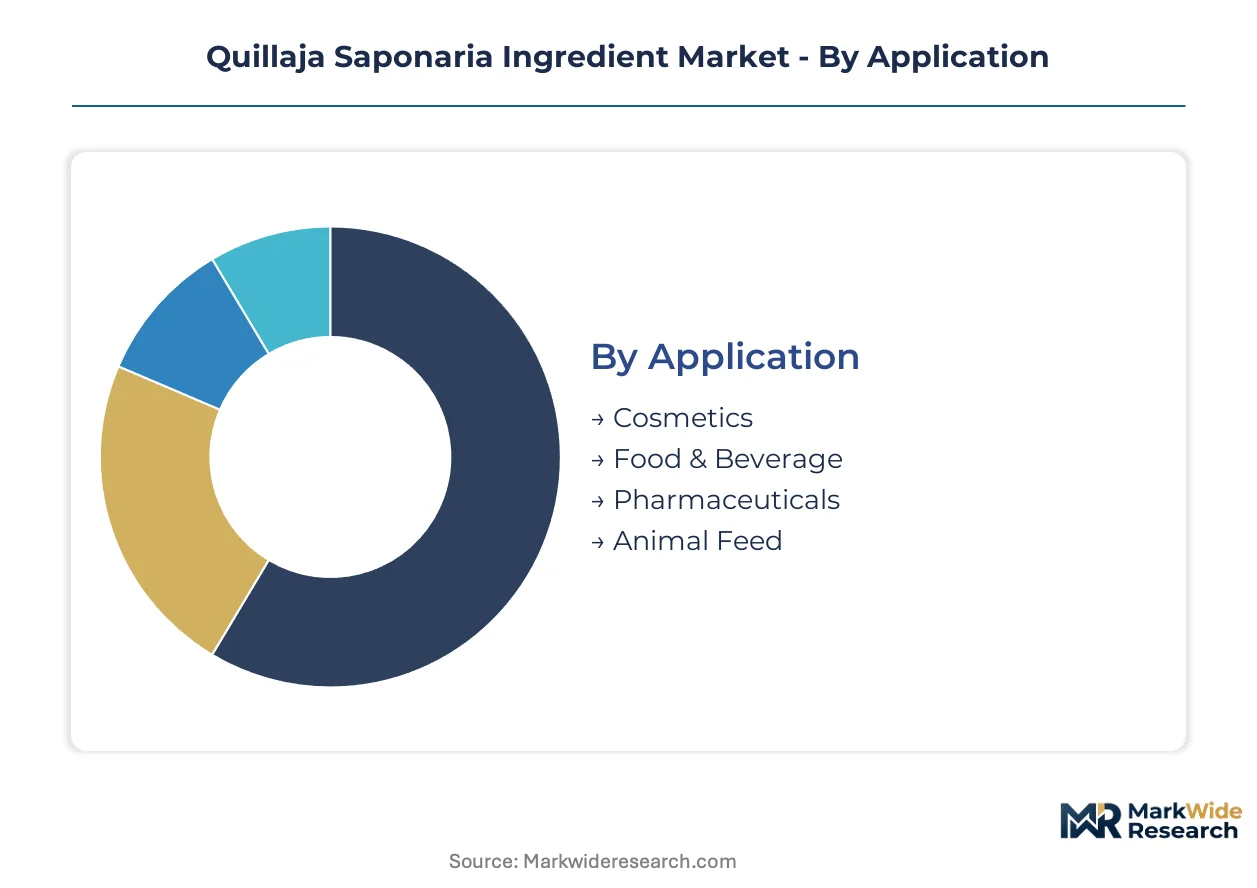
Quillaja saponaria ingredient procurement patterns diverge sharply across application verticals, with pharmaceutical-grade specifications demanding extraction investments that food-grade buyers avoid. Form factor preferences and certification tiers further fragment sourcing strategies, requiring suppliers to maintain parallel production lines.
Application:
Capital intensity peaks in pharmaceutical applications where GMP-compliant extraction suites and validated analytical protocols demand seven-figure facility investments. Food and beverage manufacturing requires lower barrier-to-entry processing equipment but commands volume scale.
- Food & Beverage:Carbonated drink manufacturers specify quillaja saponaria for foam stability in clean-label reformulations, with procurement concentrated among United States functional beverage startups bypassing traditional distributors. FDA GRAS disclosure expectations are tightening formulation documentation requirements.
- Pharmaceuticals:Vaccine adjuvant applications require immunostimulatory complex purification with chromatographic constituent profiling meeting EMA and FDA pharmacopeial standards. Chilean processors are upgrading membrane filtration capacity to serve this specification tier.
- Cosmetics:REACH Article 33 saponin disclosure mandates are driving European formulators toward certified analytical profiles from consolidated Chilean supplier cooperatives.
- Animal Feed:Saponin inclusion for rumen methane suppression operates on price-sensitive procurement with limited premium extraction requirements.
Most installed capacity flows through Food & Beverage. Expansion is steepest in Pharmaceuticals.
Form:
Processing technology investments determine competitive positioning across physical formats, with liquid handling infrastructure requiring distinct capital deployment from spray-drying or encapsulation systems.
- Liquid Extract:Superior dispersion in aqueous systems eliminates reconstitution variability, making this format preferred by carbonated beverage formulators specifying direct-batch incorporation. Procurement teams at United States functional drink manufacturers are negotiating direct Chilean processor agreements.
- Powder:Spray-dried saponin concentrates serve cosmetic and pharmaceutical powder formulation requirements with extended shelf stability, though reconstitution steps add processing complexity for beverage applications.
- Granules:Flowable intermediate format suits animal feed premix manufacturing with reduced dust exposure during handling.
- Capsules:Pre-measured unit dosing addresses research institution and specialty supplement manufacturer requirements with minimal batch scaling infrastructure.
Liquid Extract commands the dominant procurement share. Powder is gaining share fastest in pharmaceutical contract manufacturing.
Source:
Certification tier investments separate supplier capabilities, with organic conversion requiring three-year transition periods and dedicated audit trails that conventional processors cannot replicate.
- Natural:Wild-harvested Chilean bark with standard extraction protocols serves mass-market food and industrial applications where price sensitivity limits premium positioning.
- Organic:Captive plantation development in Chile's arid northern zones enables USDA Organic and EU Organic certification pathways, widening price spreads against conventional grades as procurement specifications harden in North America and Europe.
- Synthetic:Petroleum-derived saponin analogs from commodity chemical producers maintain cost advantages in detergent and industrial surfactant applications where botanical provenance carries no formulation value.
- Bio-Based:Fermentation-derived saponin constructs from engineered yeast platforms are emerging as botanical alternatives with reduced harvest dependency, though commercial scale remains limited.
Natural source material dominates current volume. Organic is climbing the fastest as certification premiums widen.
End User:
Customer-type capital deployment varies from research-scale analytical equipment to multi-ton extraction infrastructure, with distributor networks requiring working capital intensity distinct from manufacturing asset bases.
- Manufacturers:Formulation-integrated buyers in United States carbonated beverage and pharmaceutical sectors are establishing captive Chilean sourcing relationships, disintermediating traditional botanical distributors with direct processor contracts.
- Distributors:Inventory carrying requirements and multi-jurisdiction regulatory documentation capabilities favor consolidated intermediaries with REACH, FDA, and CONAF compliance infrastructure.
- Retailers:Private-label supplement and natural product channels specify finished-form quillaja capsules and liquid extracts with branded positioning requirements.
- Research Institutions:Small-batch, high-purity specifications for adjuvant and immunology studies operate on limited volume with premium unit economics.
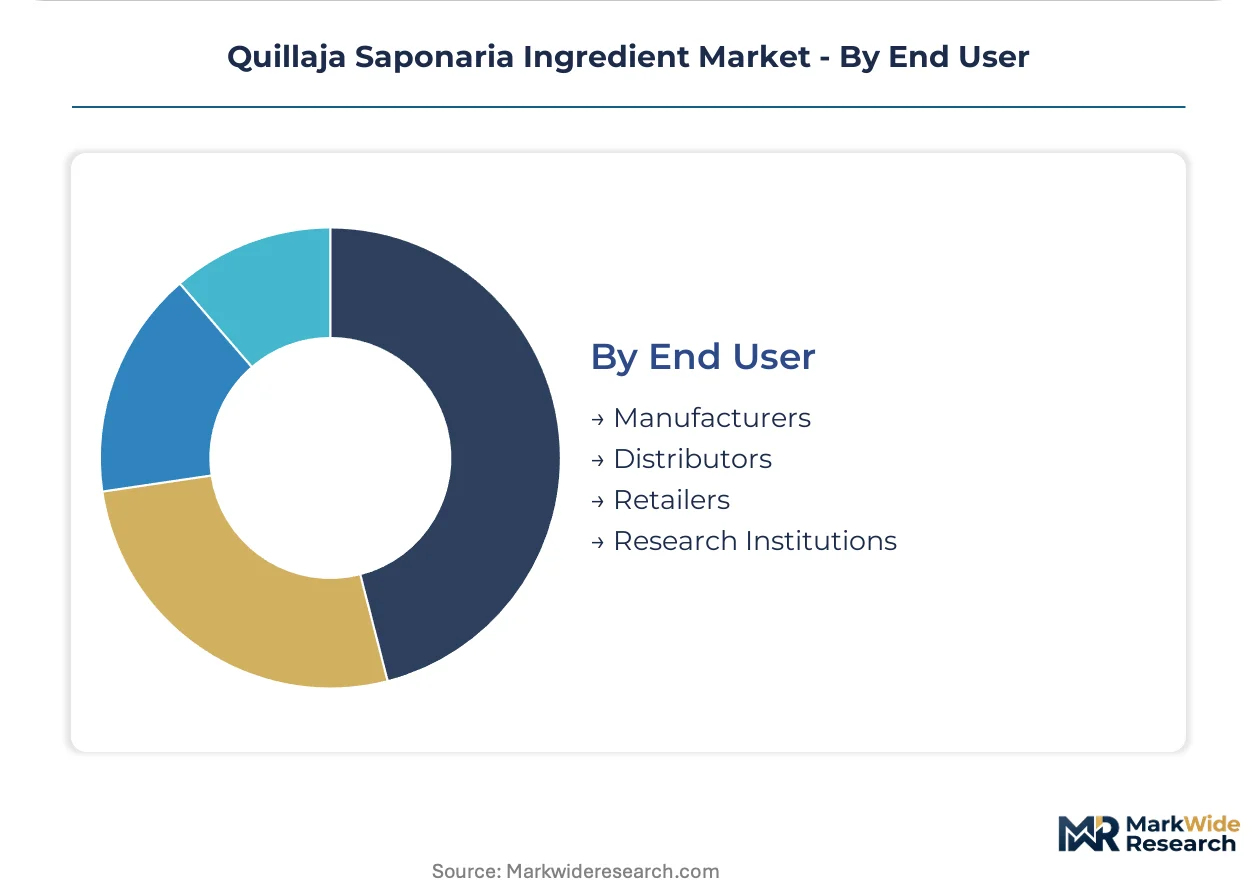
Manufacturers absorb the largest volume share. Direct procurement by Manufacturers is expanding most quickly as in-house formulation capabilities spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile commands raw material access while the United States absorbs the dominant share of processed extract offtake, creating a hemispheric trade flow shaped by regulatory divergence.
Chile
Central valley harvest zones supply over 80 percent of wild quillaja bark, with CONAF forestry service quotas tightening under native species protection statutes. Arid-zone plantations in northern regions are expanding captive cultivation to secure organic certification pathways. Processing clusters near Santiago and Valparaíso are upgrading membrane filtration capacity for pharmaceutical-grade specifications.
United States
Carbonated beverage manufacturers and vaccine formulators drive concentrated demand for liquid extracts and purified saponin fractions. FDA GRAS disclosure expectations are tightening documentation requirements for clean-label reformulations. Functional beverage startups in California and the Pacific Northwest are establishing direct processor agreements with Chilean suppliers.
Germany
Cosmetic and pharmaceutical formulators require full saponin constituent profiling under REACH Article 33 disclosure mandates. ECHA enforcement actions against incomplete SDS documentation have accelerated third-party testing adoption. Industrial clusters in North Rhine-Westphalia and Bavaria are consolidating procurement through REACH-compliant distributors.
Switzerland
Pharmaceutical-grade extract specifications for vaccine adjuvant applications align with Swissmedic pharmacopeial standards. Basel-region formulation houses are specifying chromatographically validated quillaja immunostimulatory complexes. The country's precision chemical sector is deepening analytical certification partnerships with Chilean processors.
Canada
Health Canada and PMRA oversight governs saponin incorporation in natural health products and agricultural applications. Clean-label beverage reformulation in Ontario and Quebec is tracking US regulatory timelines. Prairie-based animal feed manufacturers are evaluating rumen methane suppression applications under price-sensitive procurement terms.
Quillaja Saponaria Ingredient Market Competitive Landscape
Chilean producers anchor the raw material tier; North American distributors and formulation specialists hold the downstream value capture positions. Market structure concentrates around plantation-harvesters with captive land access, mid-tier extract processors with membrane filtration capability, and formulation-integrated buyers establishing direct supply relationships. Competitive moves center on backward integration into arid-zone cultivation and geographic sourcing diversification beyond Chile's central valley.
Within the plantation-harvester archetype, Desert King International exemplifies captive land access strategies, while Chile Botanics S.A. occupies a position within the integrated processor tier. Among North American distributors, Ingredion Incorporated represents formulation network anchoring, and Garuda International Inc. sits within the botanical extract purification specialist segment. These named entities illustrate how competitive positioning stratifies across raw material security, processing technology, and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Garuda International Inc. |
| Chile Botanics S.A |
| Ingredion Incorporated |
| Givaudan SA |
| Naturex S.A |
| Desert King International |
| Baja Yucca Company |
| Quillaja Green Biosolutions |
| Plantae Labs |
| Others |
Value Network & Pricing Analysis
Membrane filtration adoption across Chilean processing clusters is compressing extraction costs while concentrating supply among capitalized operators capable of chromatographic certification investments. This technology transition simultaneously widens price spreads between pharmaceutical-grade and food-grade extracts while reducing the supplier base capable of serving European REACH disclosure mandates.
Pricing Analysis
Capacity additions in Chile's arid-zone plantation regions are reshaping price floors for organic-certified quillaja extracts. Pricing stratifies across premium, standard, and economy tiers based on certification grade and saponin purity profile, with pharmaceutical-grade immunostimulatory complexes commanding substantial premiums over food-grade liquid extracts. Cost compression in conventional wild-harvest grades is intensifying because synthetic saponin analogs from commodity chemical producers maintain cost advantages in mass-market detergent applications. Animal feed manufacturers exhibit the highest price sensitivity due to rumen methane suppression applications operating on thin margin structures, while vaccine formulators demonstrate the least sensitivity given adjuvant inclusion rates.
Supply Chain Analysis
Spent bark and extraction residues flow into composting and soil amendment channels rather than landfill disposal, reflecting circular economy pressures across Chilean processing facilities. Geographic supply concentrates in Chile, the United States, and Germany, with over 80 percent of raw bark feedstock drawing from Chile's central valley harvest zones. Critical inputs include quillaja bark feedstock, membrane filtration equipment, and chromatographic analytical standards. Single-source vulnerability runs through Chile's CONAF-regulated wild-harvest quotas, which face climate-driven volatility and skilled harvester scarcity. Distribution runs through formulation-integrated manufacturers establishing direct processor agreements, bypassing traditional botanical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA GRAS disclosure tightening and REACH Article 33 constituent mandates are accelerating demand for certified analytical profiles. The regulatory trajectory favors suppliers with multi-jurisdiction compliance infrastructure and chromatographic validation capabilities.
For Market Incumbents: Lock in captive plantation access through long-term land leases in Chile's northern arid zones before organic certification premiums widen further. Secure membrane filtration capacity upgrades to serve pharmaceutical-grade specifications, defending against synthetic saponin substitution threats in industrial surfactant segments. Channel control through direct supply agreements with United States functional beverage manufacturers represents the priority lever for margin protection. For New Entrants and Emerging Players: Supercritical CO2 extraction equipment offers a technology-first wedge into pharmaceutical-grade purification segments where incumbent processors still rely on conventional aqueous methods. Target vaccine adjuvant applications as the most penetrable white-space segment, where EMA and FDA pharmacopeial standards have consolidated demand among a limited supplier base. A go-to-market angle anchored in chromatographic constituent profiling services for European cosmetic formulators bypasses capital-intensive extraction infrastructure requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Chilean processors with membrane filtration capability but limited organic certification infrastructure. The long-term viability window favors upstream integration into captive cultivation and downstream integration into formulation partnerships. Acquisition targets should emphasize arid-zone plantation assets with USDA Organic transition timelines already initiated. The signal to watch is CONAF quota tightening velocity, which would accelerate price premiums for certified sustainable supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Arid-Zone Cultivation | Captive plantation access in Chile's northern regions secures organic certification pathways and insulates against CONAF wild-harvest quota compression. |
| Membrane Filtration Capacity Expansion | 10-50 kDa molecular weight cut-off systems enable pharmaceutical-grade saponin fraction separation required for EMA and FDA pharmacopeial standards. |
| Direct Supply Agreement Structuring | Bypassing traditional botanical distributors captures margin compression from disintermediation trends among United States functional beverage startups. |
| Chromatographic Certification Infrastructure | Third-party analytical profiling capabilities unlock European cosmetic procurement governed by REACH Article 33 disclosure mandates. |
| Synthetic Saponin Substitution Defense | Technical differentiation through immunostimulatory complex purification protects pharmaceutical-grade pricing against petroleum-derived surfactant competition. |
Research Methodology
Multiple input streams — structured interviews with extraction plant managers and procurement leads at downstream beverage manufacturers, trade data reconciliation, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged Chilean harvester cooperatives, membrane filtration equipment suppliers, pharmaceutical formulation houses in Switzerland, and regulatory affairs specialists at FDA and ECHA. Secondary validation drew from CONAF export permit databases, SEC 10-K disclosures by listed ingredient distributors, customs records tracking quillaja extract shipments, and pharmacopeial standard updates from USP and EP.
Historical shipment volumes and pricing panels from extraction processors were cross-referenced against capacity expansion announcements and plantation development timelines. Segmentation modeling across application vertical, physical form, certification tier, and end-user type generated volume and value outputs across the analysis window. CAGRs were derived from slope analysis of fitted trend lines adjusted for regulatory milestone impacts. Industry-specific forecast inputs included CONAF quota trajectory assumptions and synthetic saponin substitution elasticity estimates in detergent applications.
The model holds under steady CONAF regulatory enforcement and sustained clean-label reformulation momentum in North American beverage manufacturing; deviation in Chilean harvester labor availability or sudden synthetic saponin cost breakthroughs would shift trajectory materially. Forecasts embed assumptions about membrane filtration adoption rates and organic certification premium persistence. Practitioners should monitor CONAF quota revision announcements and ECHA enforcement action frequency for early signals of supply constraint intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Powdered Fats Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Calcium Inosinate Market