
 Multi Nutritional Supplement Market | 2026-2036
Multi Nutritional Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Nutritional Supplement Market Foresight
Direct-to-consumer subscription revenue is fragmenting across platform models and retail pharmacy networks. Abbott leverages its clinical nutrition heritage to sustain credibility among healthcare practitioners. Herbalife International of America, Inc. anchors its position through independent distributor networks in emerging markets. Glanbia PLC competes aggressively in sports nutrition powders, where protein fortification commands premium positioning.
Multi nutritional supplements combine bioactive compounds including vitamins, minerals, amino acids, and botanical extracts into single-dose formats designed to address multiple micronutrient deficiencies simultaneously. Manufacturing employs direct compression for tablets and spray-drying for instantized powders to ensure uniform active distribution and shelf stability. Pills and capsules occupy the largest volume share due to dosing precision and transport convenience. Gummies attract the fastest growth among pediatric and senior segments where swallowing difficulties limit traditional format uptake. Online retailers capture expanding margin pools as subscription algorithms reduce customer acquisition costs relative to brick-and-pharmacy channels.
The U.S. FDA enforces Current Good Manufacturing Practice regulations that mandate identity testing for raw ingredients and finished batch verification. The EU's EFSA health claims regulation restricts permissible marketing language, forcing reformulation toward clinically substantiated active dosages. China's SAMR implements blue-hat registration requirements that extend approval timelines for imported formulations. Stakeholders must monitor evolving substantiation standards across jurisdictions to determine whether centralized or regional product portfolios minimize regulatory friction.
Market Dynamics
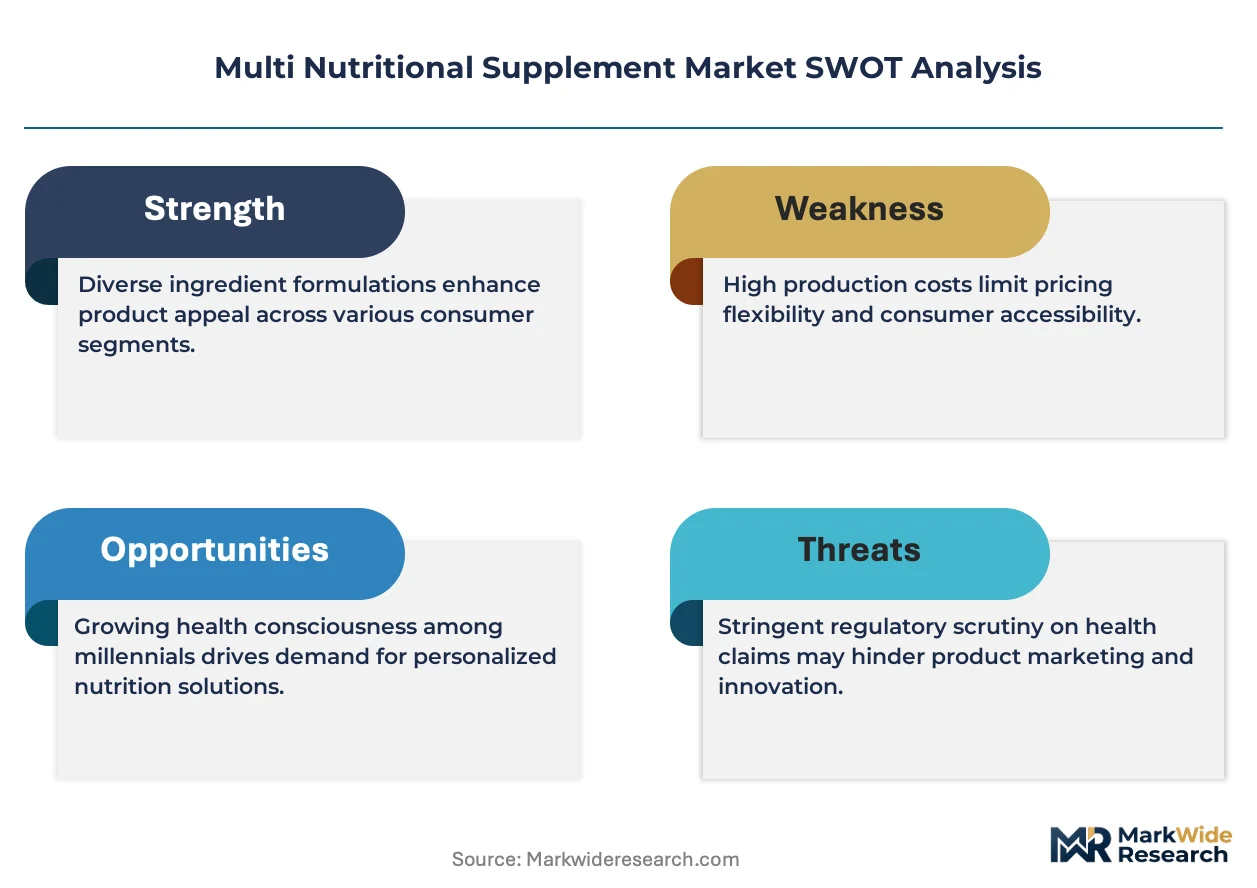
The U.S. FDA's updated dietary supplement labeling rules are forcing manufacturers to rebuild compliance infrastructure around identity testing and finished batch verification, compressing margins for mid-tier producers while advantaging scaled operators with captive laboratories.
Growth Catalysts
- Sports nutrition adoption:Amateur athletes in China's tier-one cities drive volume for protein-fortified powders and instantized formats, with aging populations simultaneously prioritizing preventive health regimens.
- Blue-hat registration pathways:China's SAMR implements streamlined approval timelines for domestically manufactured formulations, reducing regulatory friction for regional production.
- Spray-drying technology:Manufacturing processes ensure uniform active distribution and shelf stability for botanical extracts in single-dose formats, expanding addressable markets for swallowing-limited demographics.
Market Restraints
- Raw material identity testing costs:Current Good Manufacturing Practice regulations mandate ingredient verification that inflates per-batch compliance expenditure.
- EFSA health claims restriction:The EU's substantiation requirements limit permissible marketing language, forcing reformulation toward clinically validated active dosages.
- Supply concentration in botanical extracts:Sourcing dependencies for specialized plant-based actives create input volatility and quality inconsistency risks.
Strategic Opportunities
- Pediatric gummy formats:China's tier-one cities present underpenetrated demand for chewable delivery systems addressing micronutrient deficiencies in children with swallowing difficulties.
- Subscription algorithm deployment:Direct-to-consumer platforms reduce customer acquisition costs relative to brick-and-mortary channels through predictive replenishment models.
- Dual carbon alignment:China's MEE carbon intensity targets create procurement preferences for manufacturers with renewable-powered spray-drying facilities.
Industry Challenges
- Cross-jurisdictional substantiation standards:Stakeholders must maintain parallel documentation for FDA, EFSA, and SAMR requirements, fragmenting product portfolio strategies.
- Active ingredient stability engineering:Bioactive compound degradation during tablet compression demands specialized excipient expertise that concentrates among limited formulation houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Nutritional Supplement Market |
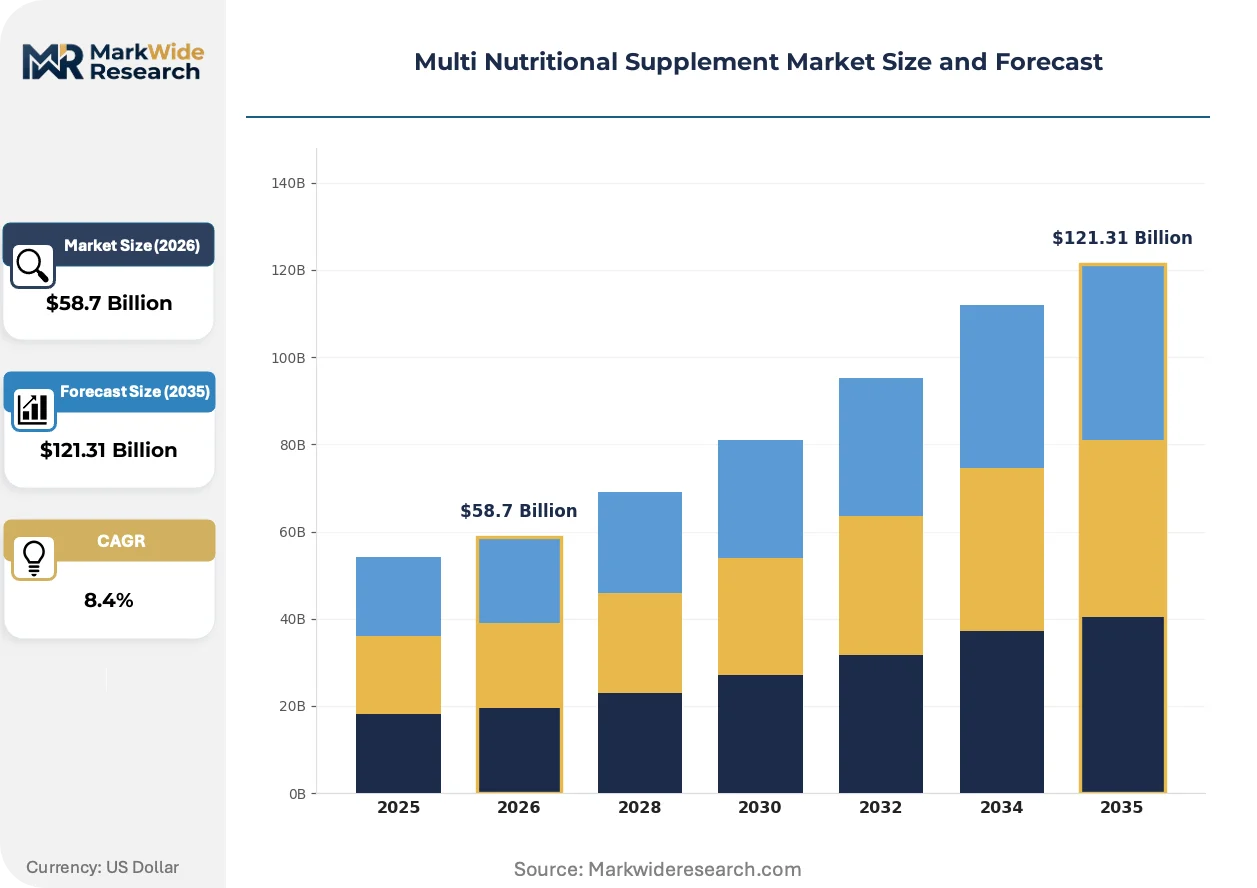
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Pills, Powders, Liquids, Gummies Target Group: Athletes, Seniors, Children, Vegetarians Distribution Channel: Pharmacies, Online Retailers, Supermarkets, Health Food Stores Ingredient Type: Vitamins, Minerals, Herbs, Others |
| Companies Covered | Nestlé, Abbott, Amway Corp, Herbalife International of America, Inc., Glanbia PLC, Bayer AG, Pfizer Inc., Nature’s Bounty Co., Otsuka Holdings Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Nutritional Supplement Market Shifts & Advancements
Formulation science and distribution architecture are undergoing parallel transformation as manufacturers respond to divergent regulatory substantiation requirements and channel-specific margin pressures.
Encapsulation technology is migrating from standard gelatin shells to plant-based and delayed-release polymers. Pediatric and senior segments in China's urban centers adopt these formats fastest due to swallowing limitations and pH-sensitive release requirements. This shift is compressing demand for conventional immediate-release tablets in premium positioning tiers.
EFSA's tightened health claims substantiation protocols now require randomized controlled trial data for immunity and cognitive benefit marketing. Manufacturers serving EU markets reformulate toward clinically validated active thresholds or abandon affected claim categories entirely. Botanical extract suppliers face the steepest compliance burden as traditional use evidence no longer satisfies evidentiary standards.
Healthcare practitioner endorsement is displacing direct-to-consumer advertising as the primary credibility mechanism in clinical nutrition segments. Abbott's heritage positioning demonstrates sustained traction among physicians prescribing preventive regimens for aging populations. This channel rotation is most visible in China's tier-one cities where hospital-affiliated pharmacies capture expanding supplement volumes.
Multi Nutritional Supplement Market Segmentation
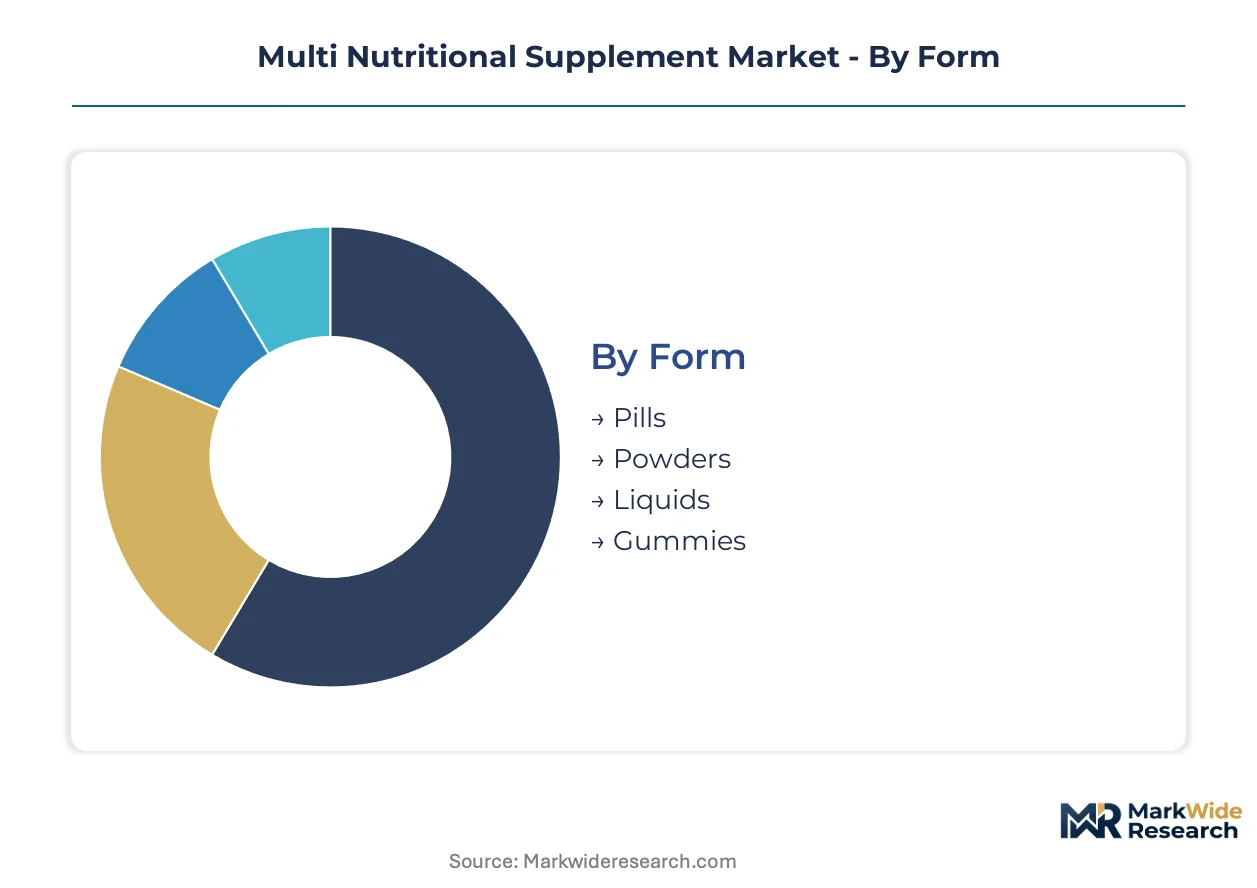
Multi nutritional supplements fragment across four distinct classification axes that determine manufacturing investment cycles, margin profiles, and regulatory compliance burdens. Form and target group classifications drive the shortest product development timelines, while distribution channel and ingredient type selections lock in multi-year commitments to testing protocols and sourcing relationships.
Form:
Pills and powders turn inventory fastest through established supply chains, whereas liquids and gummies demand specialized equipment cycles that extend working capital requirements.
- Pills:Direct compression manufacturing yields dosing precision within tight specification bands. Demand concentrates among China's tier-one city seniors where hospital-affiliated pharmacies validate clinical credibility.
- Powders:Spray-drying technology ensures uniform active distribution across protein-fortified formulations. Amateur athletes in China's urban centers drive volume for instantized formats that dissolve rapidly in shaker bottles.
- Liquids:Emulsion stability requirements demand specialized excipient expertise concentrated among limited formulation houses.
- Gummies:Pediatric and senior adoption climbs fastest where swallowing difficulties constrain traditional format uptake.
Pills dominate installed base across pharmacy networks. Gummies are where expansion concentrates for chewable delivery innovation.
Target Group:
Cost tier stratification separates premium clinical positioning from mass-market accessibility, with athlete and senior segments commanding substantiation investments that children and vegetarian formulations rarely require.
- Athletes:Protein fortification and amino acid profiles demand batch-verified identity testing under FDA Current Good Manufacturing Practice regulations. China's SAMR blue-hat registration creates additional compliance layers for imported formulations targeting competitive sports.
- Seniors:Preventive health regimens prioritize bioavailability-enhanced formats with delayed-release polymers. China's tier-one city aging populations validate products through healthcare practitioner endorsement channels.
- Children:Palatability engineering drives gummy format preference over traditional tablets.
- Vegetarians:Plant-based capsule shells displace gelatin alternatives across ethical positioning tiers.
Seniors anchor revenue concentration through clinical credibility premiums. Athletes represent the steepest expansion trajectory for sports nutrition volume.
Distribution Channel:
Volume concentration varies sharply by customer acquisition economics, with subscription algorithms compressing per-unit marketing spend against brick-and-mortar fixed costs.
- Pharmacies:Healthcare practitioner endorsement sustains margin premiums through prescription-adjacent positioning. China's hospital-affiliated pharmacy networks capture expanding supplement volumes for aging population regimens.
- Online Retailers:Predictive replenishment models reduce customer acquisition costs relative to physical channels. Direct-to-consumer platforms fragment across algorithm-driven subscription services and marketplace aggregators.
- Supermarkets:Mass-market accessibility trades margin compression for volume throughput.
- Health Food Stores:Specialty botanical positioning targets ingredient-conscious consumers with premium tolerance.
Pharmacies retain the highest margin per unit. Online retailers are capturing share fastest through subscription infrastructure deployment.
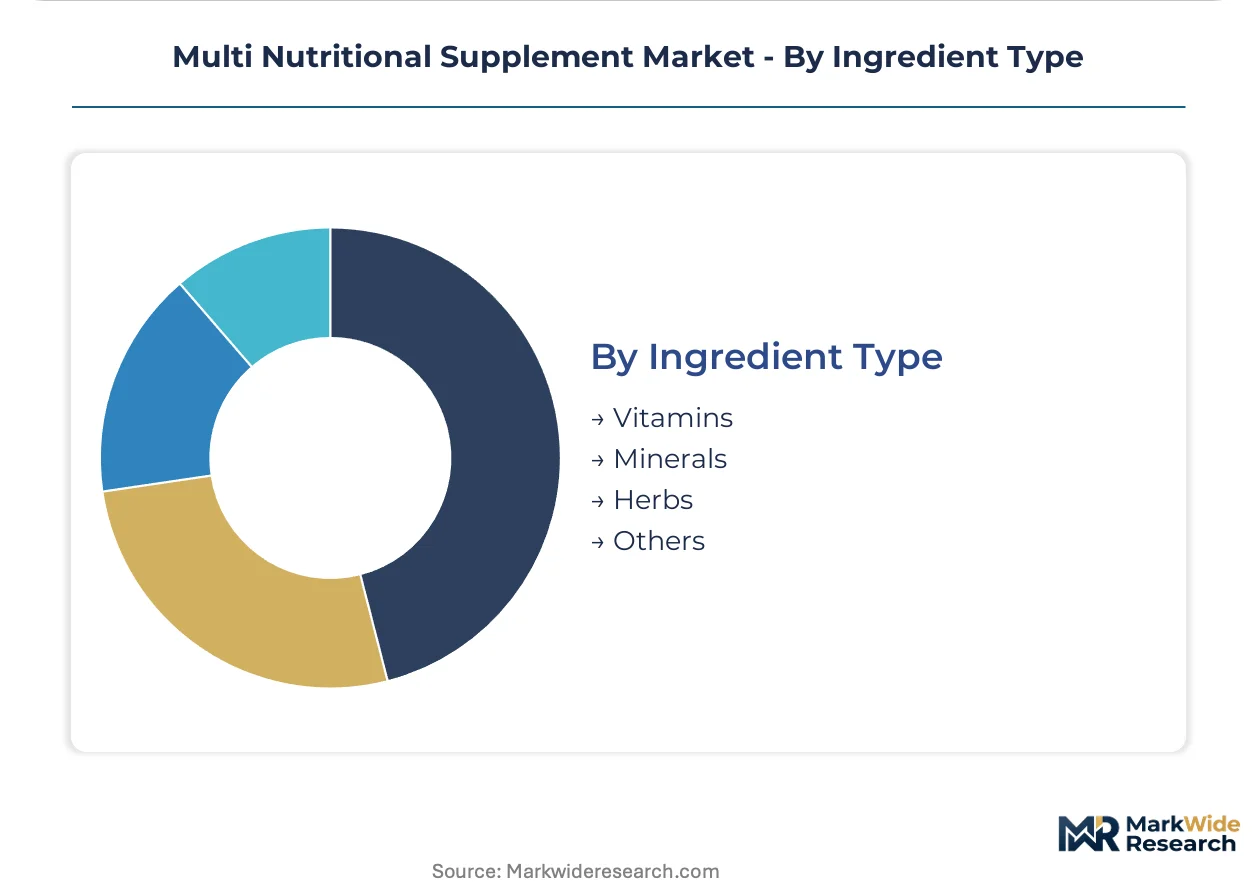
Ingredient Type:
Supply concentration and regulatory substantiation burdens stratify procurement strategies, with vitamins and minerals offering standardized testing pathways that herbs and novel compounds cannot replicate.
- Vitamins:Synthetic and natural-source variants comply with established pharmacopeial standards that accelerate batch release. EFSA health claims substantiation requires randomized controlled trial data for immunity marketing in EU markets.
- Minerals:Chelated forms command bioavailability premiums through enhanced absorption kinetics. China's SAMR implements identity testing mandates that extend approval timelines for imported mineral complexes.
- Herbs:Traditional use evidence no longer satisfies EFSA evidentiary standards, forcing reformulation toward clinically validated thresholds.
- Others:Novel bioactive compounds face the steepest regulatory uncertainty across FDA, EFSA, and SAMR jurisdictions.
Minerals anchor formulation stability across multi-ingredient combinations. Herbs face the most concentrated regulatory pressure for evidentiary upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply by geography. China's tier-one cities absorb premium pricing for practitioner-endorsed clinical formats, while India's mass-market channels prioritize cost-per-dose efficiency over bioavailability claims.
United States
Sports nutrition powders drive volume through amateur athlete adoption in fitness clusters across California and Texas. The FDA's updated dietary supplement labeling rules mandate identity testing infrastructure that compresses margins for mid-tier producers. Chicago and New Jersey manufacturing corridors concentrate spray-drying capacity for instantized protein formulations.
China
Aging populations in Beijing, Shanghai, and Guangzhou prioritize preventive health regimens with hospital-affiliated pharmacy validation. SAMR's blue-hat registration requirements extend approval timelines for imported formulations while streamlining domestic pathways. Yangtze River Delta production hubs deploy renewable-powered facilities to align with MEE carbon intensity targets.
Germany
EFSA health claims substantiation protocols force reformulation toward clinically validated active dosages for immunity and cognitive benefit positioning. Bavaria and Baden-Württemberg house specialized excipient expertise for delayed-release polymer development. Domestic producers abandon traditional use evidence for botanical extracts in favor of randomized controlled trial documentation.
Japan
Senior-targeted bioavailability-enhanced formats command premium positioning through METI quality certification frameworks. Kanto and Kansai regions concentrate healthcare practitioner endorsement channels for clinical nutrition segments. PMDA manufacturing standards enforce batch-verified identity testing that advantages scaled operators with captive laboratory infrastructure.
India
Mass-market gummy adoption climbs among pediatric segments where palatability engineering displaces traditional tablet formats. FSSAI labeling mandates accelerate for imported vitamin and mineral complexes. Maharashtra and Gujarat production clusters scale direct compression capacity for dosing-precision tablets serving pharmacy networks.
Multi Nutritional Supplement Market Competitive Landscape
Capability concentration sits with specialized formulation houses possessing excipient expertise for active ingredient stability; scale advantage sits with diversified nutrition conglomerates deploying captive laboratory infrastructure for batch verification. The vendor base stratifies across three tiers: clinical heritage operators, sports nutrition specialists, and mass-market platform players. Consolidation pressure intensifies as regulatory compliance costs fragment mid-tier producers. Dominant competitive moves include M&A for manufacturing capacity and strategic partnerships for distribution network access.
Within the clinical heritage tier, Abbott and Nestlé occupy positions anchored by healthcare practitioner endorsement channels. Among sports nutrition specialists, Glanbia PLC exemplifies scale-driven protein fortification positioning. Herbalife International of America, Inc. represents the independent distributor network archetype for emerging market penetration. These three entities collectively illustrate the strategic divergence between credibility-driven clinical positioning and volume-driven platform models.
| Leading Market Players |
|---|
| Nestlé |
| Abbott |
| Amway Corp |
| Herbalife International of America, Inc. |
| Glanbia PLC |
| Bayer AG |
| Pfizer Inc. |
| Nature's Bounty Co. |
| Otsuka Holdings Co., Ltd |
| Others |
Supply & Pricing Matrix
China's Yangtze River Delta production hubs concentrate spray-drying capacity for instantized protein powders, capturing margin pools that downstream brand owners in tier-one cities cannot replicate without captive manufacturing assets. This upstream concentration forces pricing power toward integrated operators while fragmenting margin retention among contract-dependent mid-tiers.
Pricing Analysis
Subscription renewals and algorithm-driven replenishment contracts drive lifetime value compression as direct-to-consumer platforms reduce per-unit acquisition costs against brick-and-mortar pharmacy networks. Three-tier pricing structure across premium practitioner-endorsed, standard retail, and economy mass-market levels separates clinical credibility premiums from palatability-engineered gummy formats. Pricing pressure stems from FDA-mandated identity testing infrastructure that inflates per-batch compliance expenditure for non-integrated producers. Pediatric segments in China's urban centers show highest price sensitivity due to caregiver switching between palatability formats, while senior preventive regimens anchored by hospital-affiliated pharmacy endorsement demonstrate lowest elasticity.
Supply Chain Analysis
Extended payment terms from botanical extract suppliers in India and China strain working capital for mid-tier manufacturers lacking supply-chain finance facilities. Raw material sourcing draws from Indian API clusters for mineral chelates, Chinese Yangtze Delta facilities for protein isolates, and European specialized houses for delayed-release polymers. Single-source vulnerability concentrates in certified organic botanical extracts where EFSA substantiation requirements have eliminated traditional-use suppliers. Distribution runs through hospital-affiliated pharmacy networks in China's tier-one cities, online subscription platforms with predictive replenishment algorithms, and mass-market retail chains with fixed slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where SAMR blue-hat registration timelines and FDA Current Good Manufacturing Practice mandates create structural barriers that scale advantages compound over time.
For Market Incumbents: Insulate market position by deepening backward integration into spray-drying capacity in China's Yangtze River Delta production corridors, eliminating single-source vulnerability in botanical extract supply. Prioritize certification investment for EFSA health claims substantiation to capture immunity positioning premiums before mid-tier competitors complete evidentiary upgrades. Channel control through hospital-affiliated pharmacy networks in Beijing and Shanghai sustains margin premiums against direct-to-consumer platform erosion. For New Entrants and Emerging Players: Build out white-space presence in pediatric gummy formats for China's tier-one cities where swallowing-limited demographics remain underpenetrated by incumbent tablet-dominant portfolios. Target amateur athlete segments in urban fitness clusters with instantized protein powders leveraging domestic SAMR registration pathway advantages over imported formulation timelines. Go-to-market execution should anchor in independent distributor networks for emerging market penetration rather than competing directly for pharmacy shelf space. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sports nutrition specialists possessing regional production footprints but lacking clinical credibility channels for senior preventive regimens. Long-term viability over the intermediate investment horizon hinges on regulatory entrenchment depth rather than brand awareness metrics. Watch for SAMR blue-hat registration backlog clearance as inflection signal for domestic manufacturing preference acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spray-Drying Capacity | Yangtze River Delta production hubs with renewable power alignment capture MEE carbon intensity procurement preferences. |
| EFSA Health Claims Substantiation Investment | Randomized controlled trial documentation for immunity positioning unlocks premium tier access in EU markets. |
| Pediatric Gummy Format Development | Palatability engineering for swallowing-limited demographics penetrates fastest-growing segment in China's tier-one cities. |
| Hospital-Affiliated Pharmacy Network Expansion | Practitioner endorsement channels in Beijing and Shanghai validate clinical credibility premiums for senior regimens. |
| Domestic SAMR Blue-Hat Registration Pathway | Streamlined approval timelines for China-manufactured formulations reduce regulatory friction versus imported competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA warning letters, SAMR registration databases, and EFSA health claims opinions to establish regulatory substantiation burden benchmarks. Interviews with formulation scientists at specialized excipient houses, procurement directors at sports nutrition brands, regulatory affairs leads navigating multi-jurisdictional compliance, and pharmacy category managers in China's hospital-affiliated networks provided demand-side validation. Bottom-up volume estimates from production capacity utilization rates triangulate against top-down expenditure flows from national health accounts and consumer panel data.
Forecast inputs span form factor adoption curves, target group penetration rates by age cohort, distribution channel shift dynamics, and ingredient type regulatory substantiation timelines across the analysis window. Segmentation modeling incorporates delivery format, demographic targeting, channel economics, and active compound classification dimensions. CAGRs derive from regression analysis of historical volume elasticities against income growth, aging population demographics, and amateur sports participation rates, with cross-validation against import-export trade flows and production capacity expansion announcements.
Practitioners should monitor SAMR registration backlog fluctuations, EFSA evidentiary standard tightening for botanical extracts, and renewable energy cost trajectories in Chinese manufacturing hubs for early signals of competitive position shifts. Forecasts embed assumptions around regulatory pathway stability, raw material supply continuity, and consumer channel preference evolution; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Testosterone Booster Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Melatonin Supplements Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Bovine Collagen Peptide Market