
 Pantothenic Acid Market | 2026-2036
Pantothenic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Pantothenic Acid Market Analytics
Pharmaceutical applications are consolidating share within the pantothenic acid demand mix as nutraceutical brands reformulate around single-ingredient transparency. BASF SE leverages its German chemical manufacturing base to sustain pharmaceutical-grade output with tight impurity profiles. Koninklijke DSM N.V. anchors European supply through its biotechnology fermentation platforms, while Xinfa Pharmaceutical Co., Ltd dominates bulk powder production from its Zhejiang operations.
Pantothenic acid, or vitamin B5, is a water-soluble B-complex vitamin synthesized commercially via chemical condensation of beta-alanine with pantolactone or through microbial fermentation, typically assayed at minimum 99% purity for pharmaceutical use and functioning as an essential coenzyme A precursor in lipid metabolism and adrenal hormone synthesis. The powder form leads volume shipments into animal feed and bulk supplement manufacturing, where margin pools remain thin but scale-dependent, while capsules and tablets capture higher unit economics in direct-to-consumer channels. Functional foods represent the fastest-growing application as fortified beverages and sports nutrition products incorporate B5 at clinically relevant doses.
The US FDA enforces Current Good Manufacturing Practice standards for dietary supplements under 21 CFR Part 111, compelling ingredient suppliers to maintain batch-level documentation and third-party certification. China's NMPA and SAMR jointly administer nutritional fortification standards under GB 14880, restricting permitted usage levels in domestic food products. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs, as divergent assay methods create compliance friction for multinational suppliers.
Market Dynamics
Fermentation-based manufacturing is displacing chemical synthesis as the dominant production pathway for pharmaceutical-grade pantothenic acid, driven by tightening impurity thresholds from regulators across major import markets. This technological pivot is compressing legacy capacity while concentrating supply among biotech-enabled producers.
Growth Catalysts
- Clean-label supplement reformulation:Nutraceutical brands are stripping excipients and highlighting single-ingredient transparency, pulling pharmaceutical-grade B5 into premium positioning.
- GB 14880 fortification mandates:China's nutritional fortification standards are expanding permitted applications for vitamin B5 in functional beverages and infant formula.
- Jiangsu-Shandong API cluster concentration:Integrated fermentation-to-powder infrastructure in these provinces is lowering unit costs for export-grade material.
Market Restraints
- D-pantolactone feedstock volatility:The chiral precursor for chemical synthesis faces price swings tied to petrochemical feedstock markets, squeezing legacy producers.
- Single-country fermentation dependence:Over-reliance on Chinese biomanufacturing capacity creates geopolitical exposure for global nutraceutical formulators.
- USP-ChP assay divergence:Differing pharmacopeial purity testing methods generate batch rejection risk at customs checkpoints.
Strategic Opportunities
- Indian dietary supplement underpenetration:FSSAI's evolving standards for B-complex fortification open formulation opportunities in a market with low per-capita vitamin consumption.
- Sports nutrition functional foods:Clinically-dosed B5 incorporation into ready-to-drink recovery beverages targets endurance athletes seeking adrenal support claims.
- EU Green Deal bioprocess incentives:Fermentation-derived vitamins qualify for sustainability-linked procurement preferences among European pharmaceutical buyers.
Industry Challenges
- Pharmacopeial harmonization timelines:Reconciling USP, EP, and ChP monograph updates delays new supplier qualification by 18-24 months.
- Contamination control capex:Fermentation facilities require segregated cleanroom suites and closed-system downstream processing to meet pharmaceutical-grade endotoxin limits.
- Coenzyme A pathway expertise scarcity:Biochemists with specialized knowledge of pantothenate kinase regulation command premium compensation in a thin talent pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pantothenic Acid Market |
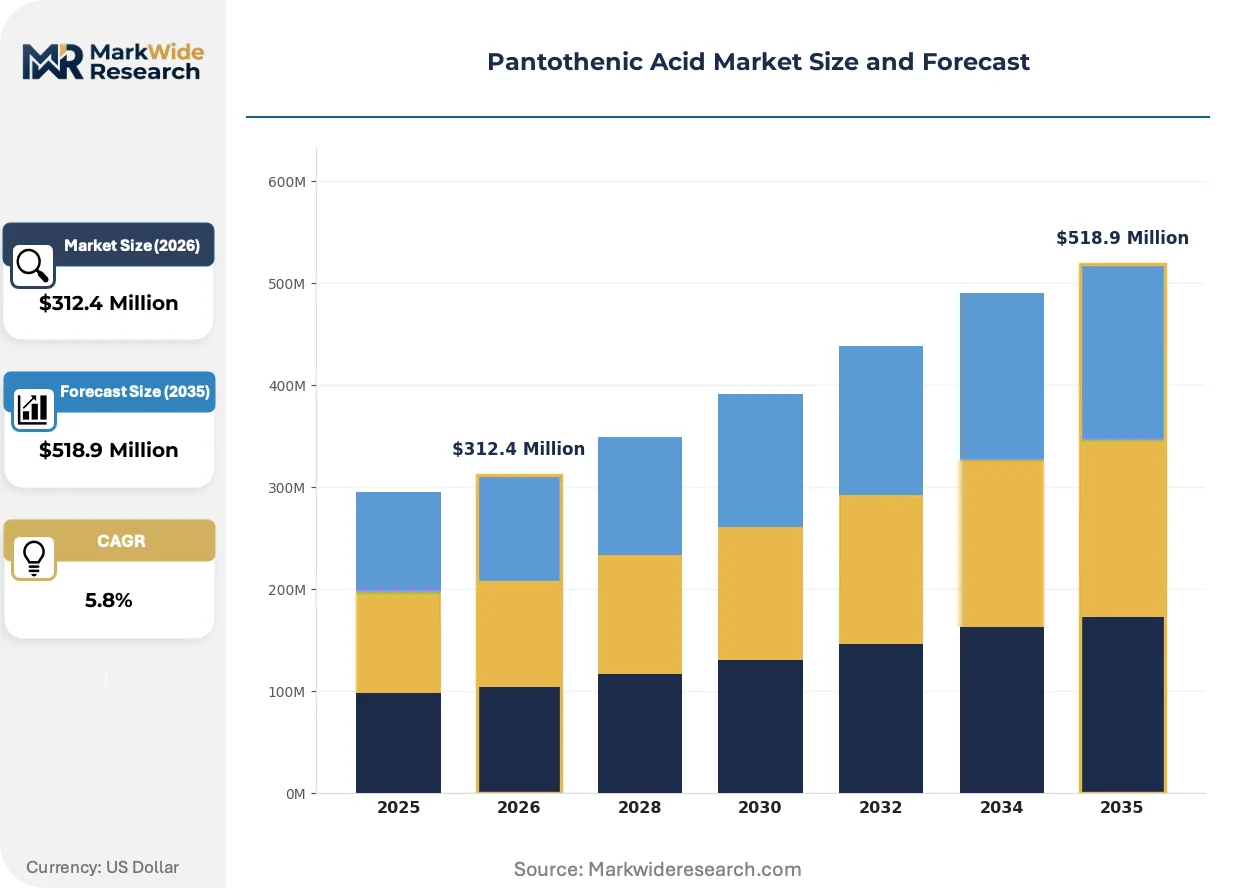
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Capsules, Tablets, Powders, Liquid Application: Dietary Supplements, Pharmaceuticals, Animal Feed, Functional Foods Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets End User: Health-Conscious Consumers, Athletes, Patients, Pet Owners |
| Companies Covered | BASF SE, Koninklijke DSM N.V., Chongqing Yifan Pharmaceutical Co., Ltd, Shandong Hwatson Biochem Co., Ltd, Xinfa Pharmaceutical Co., Ltd, Anhui Tiger Biotech Co., Ltd, Shandong Huachen Pharmaceutical Co., Ltd, Brother Enterprises Holding Co., Ltd, Nutrina Co Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pantothenic Acid Market Evolving Landscape
Bioprocess engineering advances are collapsing the cost gap between fermentation-derived and chemically-synthesized pantothenic acid, while regulatory pressure on residual solvents favors biological routes. These forces are restructuring supplier competitiveness and procurement criteria simultaneously.
Continuous fermentation technology with real-time metabolite monitoring is expanding into pharmaceutical-grade vitamin B5 production, enabling producers to maintain tighter titers and reduce batch-to-batch variability. Animal feed compounders in North America and Europe are adopting this material for premium premix formulations. The technology is compressing quality-adjusted production costs for fermentation-derived material.
REACH registration requirements for imported vitamin intermediates are tightening substance data obligations for non-EU manufacturers supplying European nutraceutical formulators. Downstream users now demand extended safety data sets and supply chain transparency documentation. Pharmaceutical-grade B5 importers are responding by qualifying dedicated EU-based repackaging and testing facilities.
Direct-to-consumer subscription models for personalized vitamin stacks are fragmenting traditional bulk powder procurement patterns among supplement brands. Smaller batch sizes with customized potency specifications are replacing long-term offtake agreements. This behavioral shift is most pronounced in North American markets where digitally-native wellness brands bypass legacy distribution tiers.
Pantothenic Acid Market Segmentation
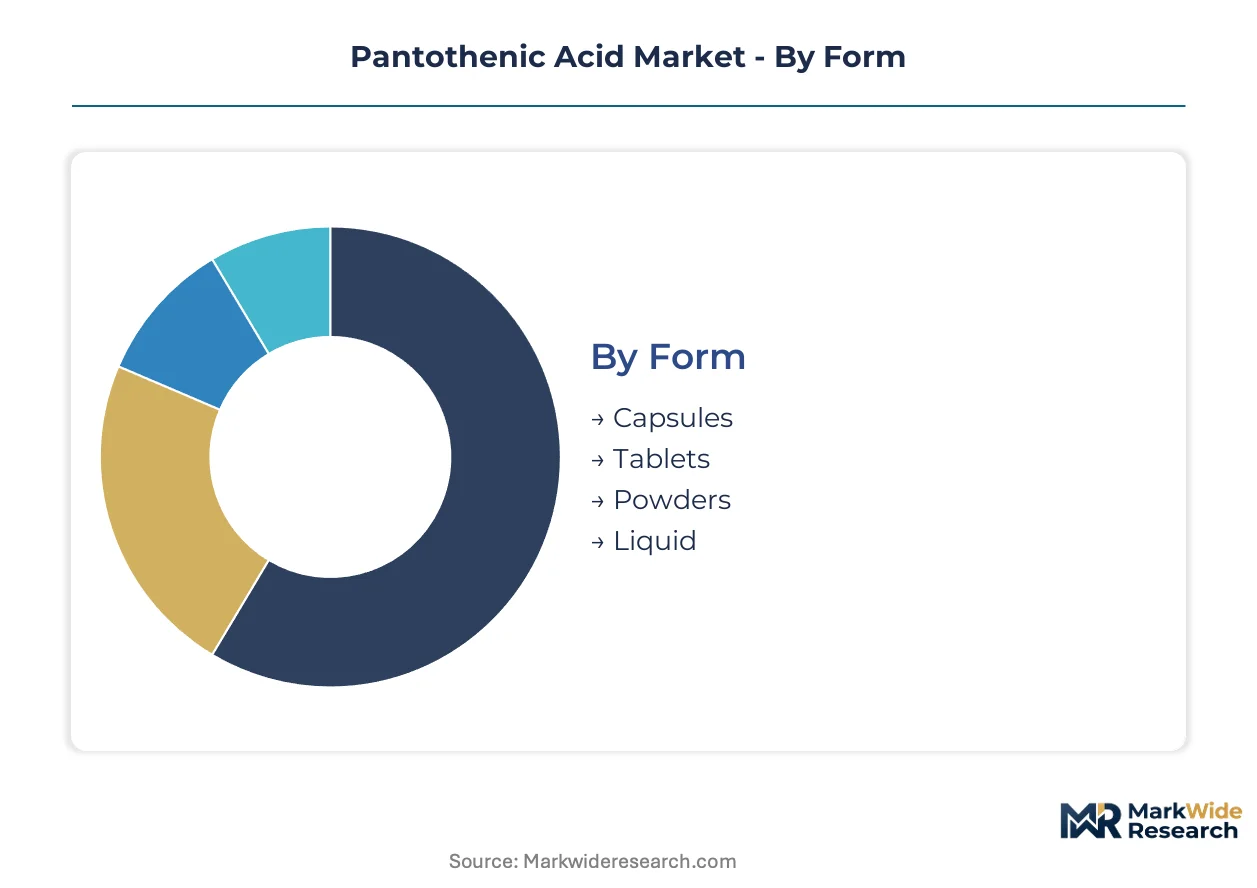
Pantothenic acid's commercial structure fragments across specification grades, delivery formats, and channel economics. Each segmentation axis carries distinct margin profiles and regulatory obligations that reshape supplier competitiveness.
Form:
Specification tiers separate pharmaceutical-grade material from feed-grade bulk, with dissolution kinetics and bioavailability markers defining procurement criteria.
- Powders:Bulk crystalline material with minimum 99% assay purity dominates animal feed compounding and supplement manufacturing. Jiangsu and Shandong API clusters supply export-grade powder to North American and European nutraceutical formulators at scale-dependent margins.
- Capsules:Hard-shell gelatin or vegetable-derived encapsulation captures premium unit economics in direct-to-consumer channels. Clean-label brands specify excipient-free formulations, pulling pharmaceutical-grade B5 into single-ingredient transparency positioning.
- Tablets:Compressed dosage forms with binder systems target mass-market retail placement. US FDA 21 CFR Part 111 cGMP compliance adds batch documentation overhead for contract manufacturers.
- Liquid:Aqueous or oil-based solutions enable fortification of ready-to-drink beverages and pediatric formulations. China's GB 14880 expansion into functional beverages is accelerating liquid specification demand.
Mature deployment sits with powders. Newer deployment is concentrated in capsules.
Application:
End-use concentration shifts with regulatory fortification mandates and consumer wellness positioning strategies.
- Dietary Supplements:Single and multi-vitamin formulations represent the largest volume sink for pharmaceutical-grade material. Subscription-based personalized stacks are fragmenting traditional bulk procurement patterns among North American brands.
- Functional Foods:Clinically-dosed B5 incorporation into sports nutrition and recovery beverages targets endurance athletes. This application is climbing the fastest as fortified product lines expand beyond traditional supplement channels.
- Pharmaceuticals:Prescription-grade coenzyme A precursors for metabolic and adrenal indications require endotoxin-controlled fermentation output. EMA and USP pharmacopeial harmonization delays create supplier qualification friction.
- Animal Feed:Premix formulations for livestock and companion animals consume technical-grade powder at thin margins. North American and European compounders are adopting continuous fermentation-derived material for premium positioning.
Volume concentration remains with dietary supplements. Margin expansion is concentrating in functional foods.
Distribution Channel:
Channel selection determines batch size requirements, certification documentation, and working capital intensity.
- Online Retail:Direct-to-consumer platforms enable digitally-native wellness brands to bypass legacy distribution tiers. Smaller batch sizes with customized potency specifications are replacing long-term offtake agreements.
- Pharmacies:Brick-and-mortar drugstore chains demand serialized supply chain documentation and third-party certification. EU REACH registration requirements are tightening substance data obligations for imported material.
- Health Stores:Specialty retailers emphasize clean-label credentials and single-ingredient transparency. Pharmacopeial-grade certification commands shelf placement premiums.
- Supermarkets:Mass-market grocery placement requires price-competitive positioning and consumer education investment. Functional food fortification is expanding shelf space allocation.
Traditional procurement flows through pharmacies. Channel growth is accelerating in online retail.
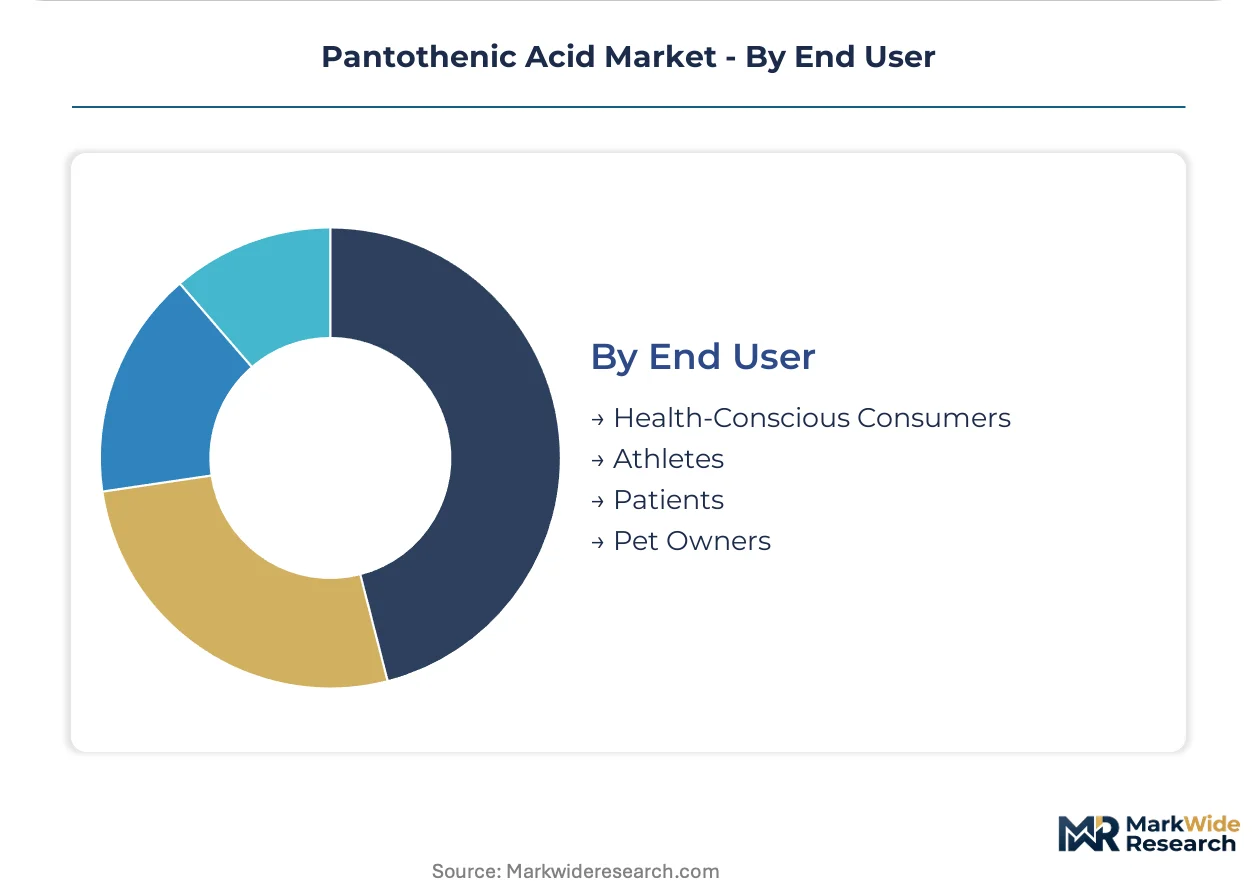
End User:
User segmentation maps to distinct dosage regimens, purchasing behaviors, and clinical validation requirements.
- Health-Conscious Consumers:Preventive wellness seekers drive demand for daily maintenance doses in premium positioning. Clean-label reformulation trends favor single-ingredient transparency.
- Athletes:Endurance and strength-training populations target adrenal support and lipid metabolism optimization. Sports nutrition functional foods with clinically-relevant B5 dosing are gaining traction fastest.
- Patients:Medically-supervised populations require prescription-grade material for metabolic disorders and deficiency correction. Coenzyme A pathway expertise scarcity constrains formulation development.
- Pet Owners:Companion animal wellness trends extend human supplement positioning into veterinary channels. FSSAI and other national regulators are expanding animal nutrition fortification standards.
Established demand centers on health-conscious consumers. User expansion is concentrating among athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang Free Trade Zone's biochemical processing incentives have concentrated fermentation-derived vitamin B5 capacity along China's eastern seaboard. This tax-advantaged positioning shapes global supply availability and export pricing dynamics across pharmaceutical and nutraceutical channels.
China
Jiangsu and Shandong provinces host integrated fermentation-to-powder infrastructure serving global nutraceutical formulators. NMPA and SAMR jointly administer GB 14880 nutritional fortification standards, expanding permitted B5 applications in functional beverages and infant formula. Zhejiang-based Xinfa Pharmaceutical anchors bulk powder production for export-grade material.
Germany
BASF SE leverages Ludwigshafen's chemical manufacturing base to sustain pharmaceutical-grade output with tight impurity profiles. EMA pharmacopeial standards and REACH registration requirements enforce substance data obligations for vitamin intermediates. The country's biotechnology fermentation platforms supply European pharmaceutical buyers prioritizing EU Green Deal sustainability criteria.
United States
Dietary supplement manufacturers drive pharmaceutical-grade B5 demand as clean-label reformulation strips excipients for single-ingredient transparency. FDA enforces 21 CFR Part 111 cGMP standards, compelling batch-level documentation and third-party certification. New Jersey and North Carolina nutraceutical clusters import fermentation-derived material for encapsulation and tableting operations.
India
FSSAI's evolving B-complex fortification standards open formulation opportunities in a market with low per-capita vitamin consumption. CDSCO regulates pharmaceutical-grade imports through drug master file requirements. Maharashtra and Gujarat supplement manufacturers represent emerging demand centers for imported pantothenic acid powder.
Netherlands
Koninklijke DSM N.V. anchors European supply through biotechnology fermentation platforms in the Randstad region. ECHA's REACH enforcement tightens supply chain transparency documentation for non-EU manufacturers. Rotterdam's port infrastructure facilitates repackaging and testing facilities for pharmaceutical-grade B5 distribution across continental Europe.
Pantothenic Acid Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade fermentation capacity, while mid-scale chemical synthesis operations face margin compression from feedstock volatility. The supplier base stratifies across biotechnology-enabled producers with integrated downstream processing and legacy condensation-chemistry operators dependent on petrochemical precursors. Three archetypes dominate: integrated fermentation specialists, API cluster-based bulk powder suppliers, and European chemical conglomerates with vitamin portfolios. Competitive moves concentrate on capacity expansion in tax-advantaged zones and pharmacopeial certification investments to reduce customs friction.
Within the integrated fermentation tier, Koninklijke DSM N.V. and BASF SE exemplify European bioprocess leadership, while Xinfa Pharmaceutical Co., Ltd occupies a position representing Chinese API cluster scale. These three anchors illustrate the geographic bifurcation between EU sustainability-linked procurement preferences and eastern cost-optimized bulk production. DSM's Dutch biotechnology platforms and BASF's German chemical manufacturing base serve pharmaceutical buyers requiring EMA-compliant documentation, whereas Zhejiang-based Xinfa supplies export-grade powder to North American and European nutraceutical formulators. The competitive dynamic between these archetypes shapes pricing stratification across pharmaceutical-grade, feed-grade, and food-fortification specification tiers.
| Leading Market Players |
|---|
| BASF SE |
| Koninklijke DSM N.V. |
| Chongqing Yifan Pharmaceutical Co., Ltd |
| Shandong Hwatson Biochem Co., Ltd |
| Xinfa Pharmaceutical Co., Ltd |
| Anhui Tiger Biotech Co., Ltd |
| Shandong Huachen Pharmaceutical Co., Ltd |
| Brother Enterprises Holding Co., Ltd |
| Nutrina Co Inc. |
| Others |
Value Network & Pricing Analysis
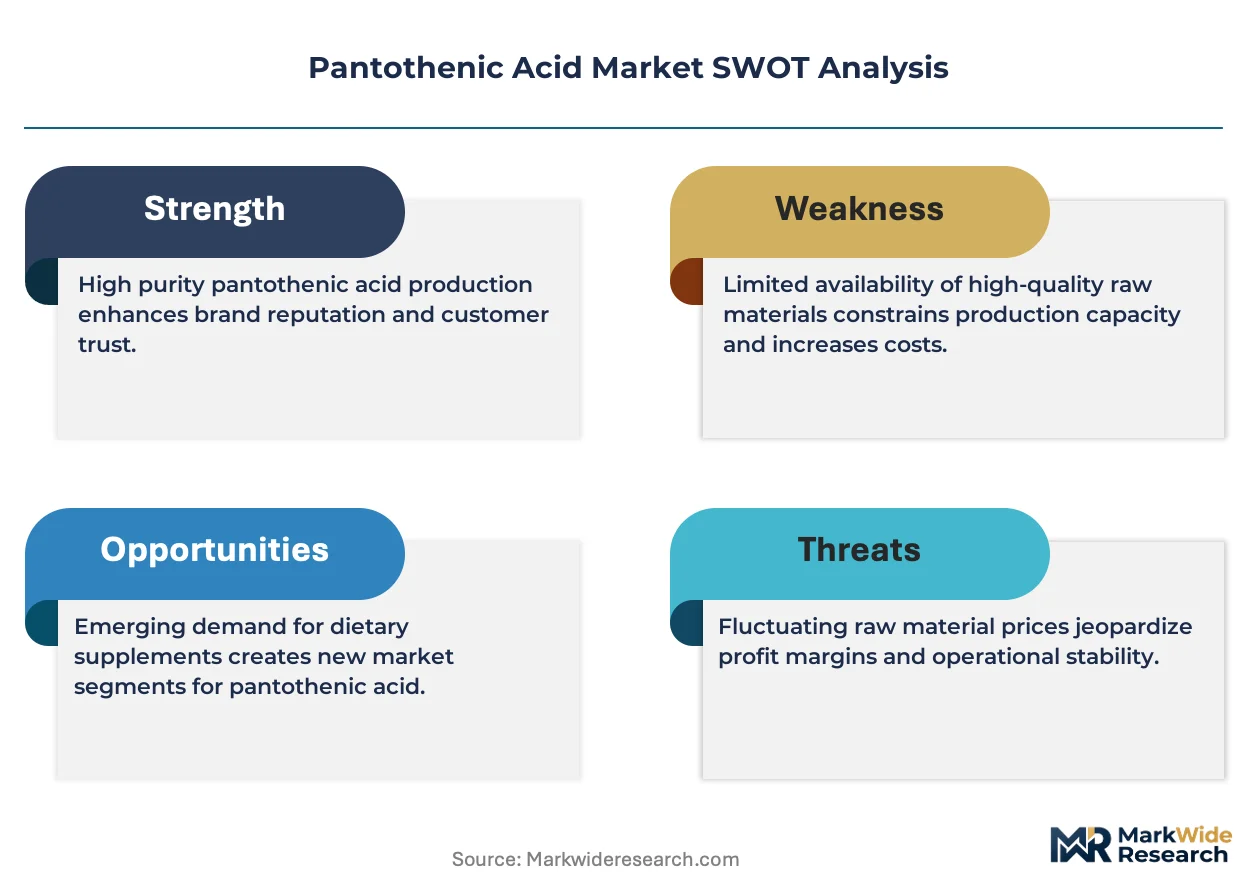
EU Green Deal sustainability criteria gate qualified supply access and premium-tier pricing for pantothenic acid, favoring fermentation-derived material with documented carbon intensity profiles while excluding chemically-synthesized alternatives from European pharmaceutical procurement pools. This environmental mandate stratifies supplier competitiveness across certification tiers and reshapes buyer-seller negotiations in continental markets.
Pricing Analysis
Short lead-time premiums command substantial markups over contract-scheduled deliveries as nutraceutical formulators buffer against pharmacopeial assay divergence delays. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and food-fortification levels separates certified fermentation output from technical-grade powder and unclassified bulk material. Pricing pressure stems from D-pantolactone feedstock volatility squeezing legacy chemical producers. Animal feed compounders exhibit highest price sensitivity; prescription-grade pharmaceutical buyers demonstrate lowest elasticity due to endotoxin-controlled sourcing requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg consolidate European pharmaceutical-grade material before hub-and-spoke dispatch to nutraceutical compounders. Fermentation capacity concentrates in China, Germany, and the Netherlands, with Jiangsu-Shandong API clusters supplying bulk powder exports. Raw material flows draw from glucose feedstock, specialized yeast strains, and downstream crystallization chemicals. Single-country fermentation dependence creates geopolitical exposure for global formulators. Distribution runs through integrated fermentation-to-powder facilities with captive downstream processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-based manufacturing is displacing chemical synthesis as the dominant production pathway, compressing legacy capacity while rewarding biotechnology-enabled producers with integrated downstream infrastructure and pharmacopeial certification depth.
For Market Incumbents: Deploy pharmacopeial harmonization investments to reduce USP-ChP assay divergence friction at customs checkpoints. BASF SE and Koninklijke DSM N.V. should expand endotoxin-controlled cleanroom suites to defend pharmaceutical-grade positioning against Chinese API cluster cost advantages. Capacity addition in Zhejiang Free Trade Zone tax-advantaged zones sustains export competitiveness for Xinfa Pharmaceutical against European sustainability-linked procurement preferences.
For New Entrants and Emerging Players: Capture Indian dietary supplement formulation opportunities as FSSAI evolves B-complex fortification standards in a market with low per-capita vitamin consumption. Sports nutrition functional foods for endurance athletes represent the most penetrable application segment, with clinically-dosed B5 incorporation into ready-to-drink recovery beverages offering direct-to-consumer brand partnerships as the optimal go-to-market angle.
For Investors and Strategic Acquirers: EU Green Deal bioprocess incentive qualification is the leading indicator that fermentation-derived vitamin platforms will command sustainability-linked procurement premiums over the coming decade. Acquisition targets should display integrated fermentation-to-powder infrastructure with existing EMA or USP pharmacopeial dossiers. Watch for NMPA-SAMR GB 14880 expansion announcements signaling Chinese domestic demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captures margin from glucose feedstock through pharmaceutical-grade crystallization under one roof. |
| Pharmacopeial Certification Investment | Reduces batch rejection risk at FDA and EMA checkpoints for multinational suppliers. |
| Long-term Supply Agreement with Sports Nutrition Brands | Locks in offtake for clinically-dosed B5 incorporation into functional beverage lines. |
| Joint Venture in Zhejiang Free Trade Zone | Accesses tax-advantaged biochemical processing incentives concentrated along China's eastern seaboard. |
| Green Manufacturing Transition | Qualifies fermentation-derived material for EU Green Deal sustainability-linked procurement preferences. |
Research Methodology
Document review covered FDA 21 CFR Part 111 guidance documents, EMA pharmacopeial monographs, NMPA GB 14880 fortification standards, and SEC 10-K filings from listed vitamin manufacturers, complemented by interviews with fermentation plant managers, nutraceutical procurement leads, pharmaceutical regulatory affairs directors, and distribution channel partners. Secondary validation drew from customs/trade data, USP and ChP assay method publications, and EU REACH substance data obligations. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segmented outputs across the projection horizon reflect specification grade tiers, delivery format categories, application end-uses, and regional regulatory clusters. CAGRs were derived from weighted average growth contributions across these dimensions. Key forecast inputs included NMPA-SAMR fortification mandate expansion timelines, EU Green Deal procurement preference adoption curves, and FSSAI B-complex standard evolution patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial harmonization delays, single-country fermentation dependence disruptions, and D-pantolactone feedstock volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Vitamin C Market