
 Middle East and Africa Vitamin a Market | 2026-2036
Middle East and Africa Vitamin a Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Vitamin a Market Foresight
South African pharmaceutical ingredient producers is recalibrating output schedules to serve rising orders from Nigerian and Kenyan supplement contract manufacturers. Bayer AG leverages its established distribution infrastructure across Gulf markets to sustain shelf presence in pharmacy channels. BASF SE anchors regional supply of synthetic retinol intermediates through its technical-grade production network. Glanbia PLC competes in the sports nutrition segment with vitamin A-fortified protein formulations targeted at athlete end users.
Vitamin A comprises a group of fat-soluble retinoids including retinol, retinal, and retinyl esters, synthesized commercially through beta-ionone chemistry or extracted from marine and plant carotenoid sources, with specifications typically expressed in international units per gram for pharmaceutical and food-grade applications. The compound serves as an essential micronutrient fortificant in edible oils, dairy, and ready-to-use therapeutic foods, plus as an active pharmaceutical ingredient in dermatological and ophthalmic preparations. Retinol and retinyl palmitate dominate product-type revenue due to their stability in thermal processing and established bioequivalence data, while beta-carotene generates premium positioning as a provitamin A source for clean-label formulations. Application demand tilts toward dietary supplements and pharmaceuticals where margin pools exceed those in commodity animal feed, though food and beverage fortification retains volume leadership through mandatory national programs in Egypt and Morocco.
Saudi Food and Drug Authority (SFDA) and Emirates Authority for Standardization and Metrology (ESMA) enforce Gulf-standard maximum permitted levels for vitamin A in dairy and infant nutrition products, while South Africa's Department of Health regulates fortification compliance through its food control directorate. These frameworks elevate testing costs for importers but simultaneously screen out substandard suppliers, tightening effective vendor lists. Egypt's drug authority applies pharmaceutical-grade GMP requirements to retinol-containing ophthalmic preparations, adding a separate compliance layer for finished dose manufacturers. Stakeholders must monitor divergence between Gulf and North African regulatory timelines as countries advance independent fortification mandates and bioequivalence study requirements.
Market Dynamics
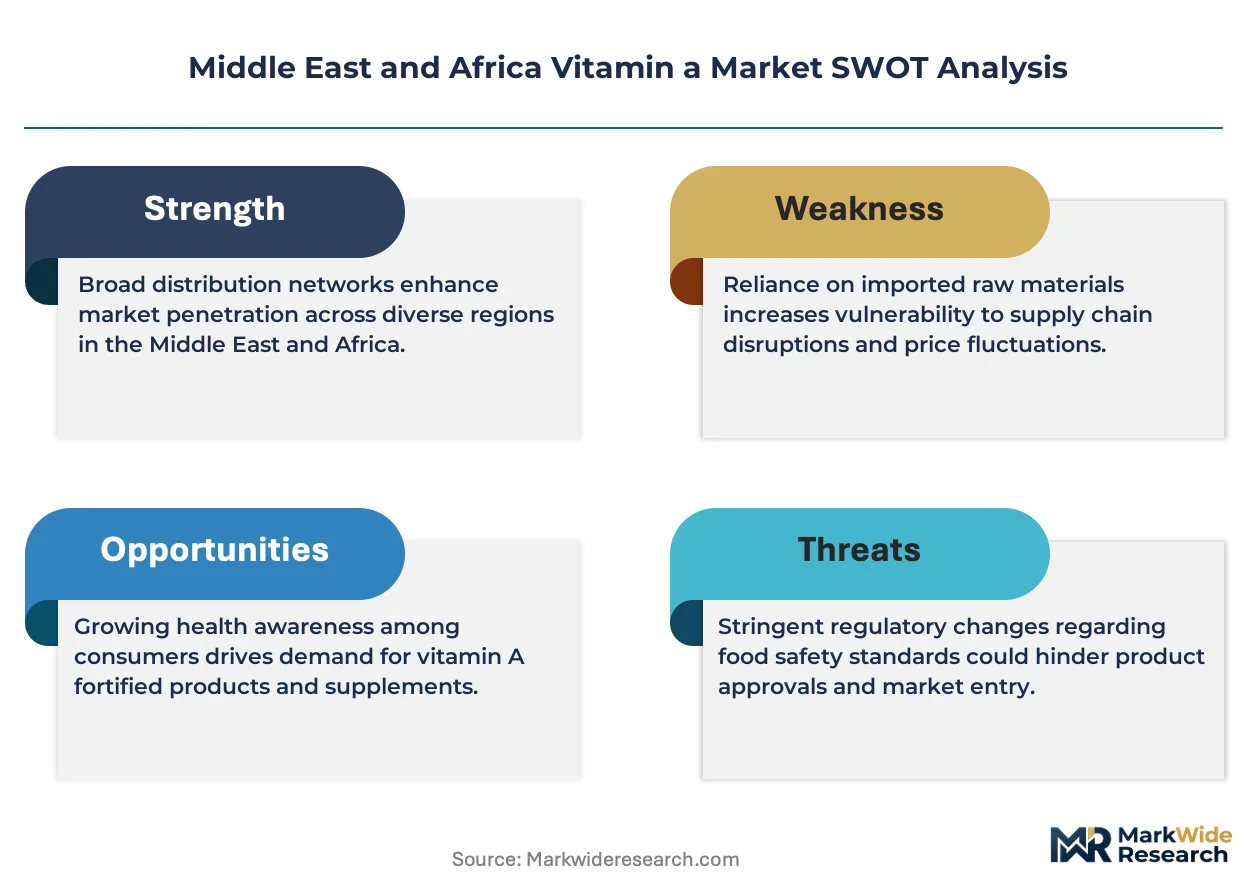
The Gulf Cooperation Council's harmonized fortification standards and South Africa's updated labeling requirements are compressing vendor eligibility while simultaneously elevating compliance costs for cross-border suppliers.
Growth Catalysts
- Mandatory fortification programs:Egypt and Morocco enforce vitamin A inclusion in edible oils and wheat flour through national nutrition strategies, locking in baseline demand for retinol premixes.
- Pharmaceutical formulation expansion:Egypt's ophthalmic and dermatological sectors are scaling local production of retinol-based APIs to reduce import dependency.
- Sports nutrition premiumization:Athlete-focused protein fortification is electrifying demand for stable retinyl ester formulations in South Africa and Nigeria.
Market Restraints
- Beta-ionone feedstock volatility:Synthetic retinol production depends on petrochemical-derived precursors, exposing margins to crude oil price swings.
- Concentrated intermediate supply:Technical-grade retinol synthesis capacity clusters in a limited number of specialized chemical producers outside the region.
- Thermal stability limitations:Natural carotenoid extracts degrade faster than synthetic alternatives, restricting their use in high-heat food processing applications.
Strategic Opportunities
- Kenyan contract manufacturing:Underdeveloped local premix blending capacity creates white space for regional toll-manufacturing partnerships serving East African supplement brands.
- Clean-label provitamin positioning:Beta-carotene from marine algae sources commands premium pricing in Gulf pharmacy channels targeting health-conscious consumers.
- SFDA-ESMA convergence:Harmonized maximum permitted levels across Saudi Arabia and UAE streamline multi-market product registration, reducing redundant testing expenditure.
Industry Challenges
- Analytical chemistry talent scarcity:Quantifying vitamin A content in complex food matrices requires specialized HPLC expertise that remains concentrated in Johannesburg and Cairo laboratories.
- Dual certification timelines:Suppliers must separately validate pharmaceutical-grade GMP for Egypt's drug authority and food-grade compliance for Gulf standards, extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Vitamin a Market |
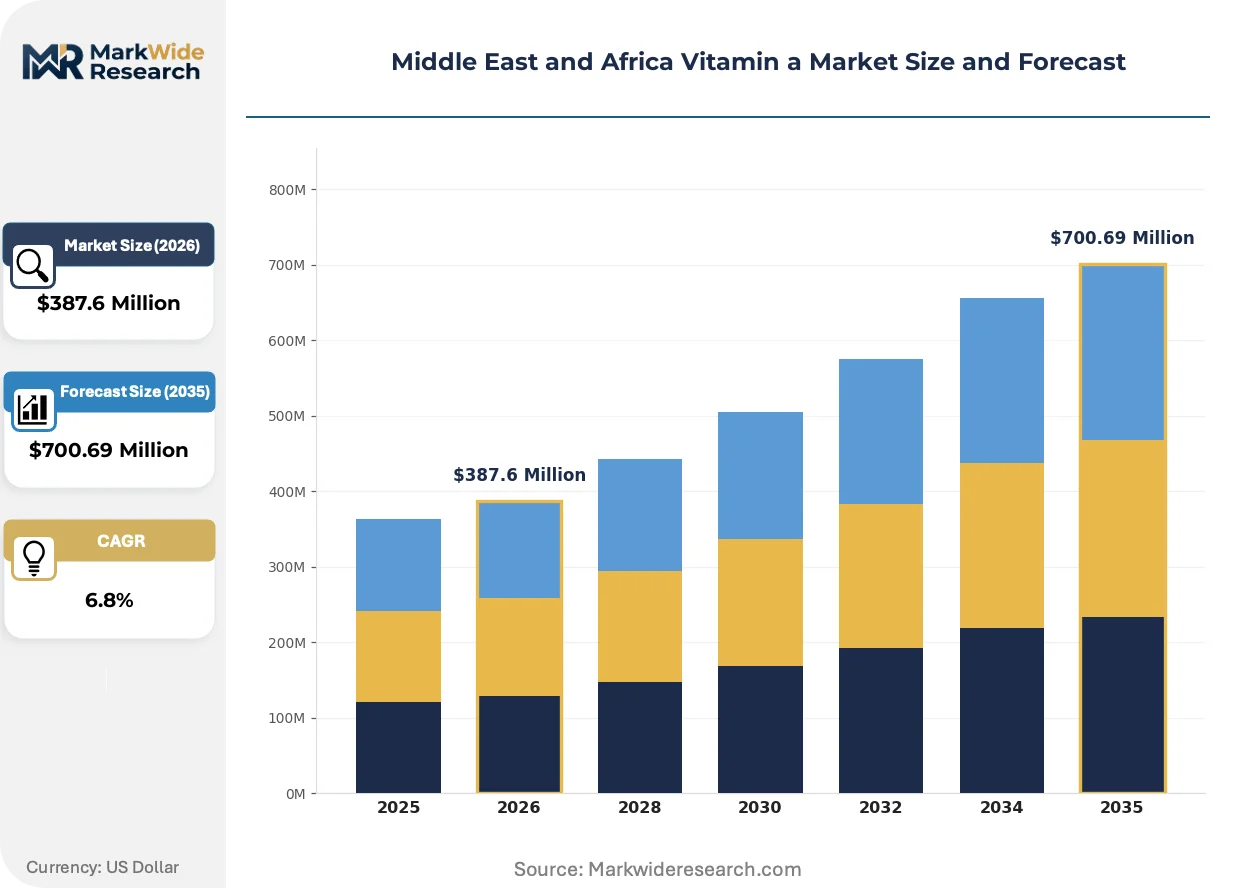
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retinol, Retinyl Palmitate, Beta-Carotene, Carotenoids Application: Food & Beverages, Dietary Supplements, Animal Feed, Pharmaceuticals End User: Health-conscious Consumers, Athletes, Pet Owners, Medical Professionals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Bayer AG, Amway Corp., Abbott, Glanbia PLC, Herbalife Nutrition Ltd., GSK plc, DuPont de Nemours, Inc., Archer Daniels Midland Company, BASF SE, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Vitamin a Market Shifts & Advancements
Formulation chemistry advances and regulatory convergence are compressing product development cycles while fragmenting procurement authority across new buyer segments.
Encapsulation technologies using modified starch and gum arabic matrices are electrifying bioavailability in fortified beverages. Dairy processors in Saudi Arabia and UAE are adopting these systems at pilot scale ahead of mass rollout. The technology is electrifying competition between synthetic retinol and natural carotenoid suppliers by narrowing the stability-performance gap.
SFDA and ESMA's synchronized maximum permitted level enforcement for infant nutrition is eliminating regulatory arbitrage between Gulf markets. Importers now face unified testing protocols rather than country-specific dossiers. Dairy and formula manufacturers are consolidating supplier relationships to vendors with pre-approved multi-market registration packages.
Direct procurement from ingredient specialists is displacing traditional distributor intermediaries among large-scale South African supplement manufacturers. Mid-tier brands in Nigeria and Kenya are replicating this model, establishing technical relationships with BASF and Glanbia technical service teams. The shift is most visible in Johannesburg and Lagos, where procurement teams now specify retinol potency and excipient compatibility directly in supply agreements.
Middle East and Africa Vitamin a Market Segmentation
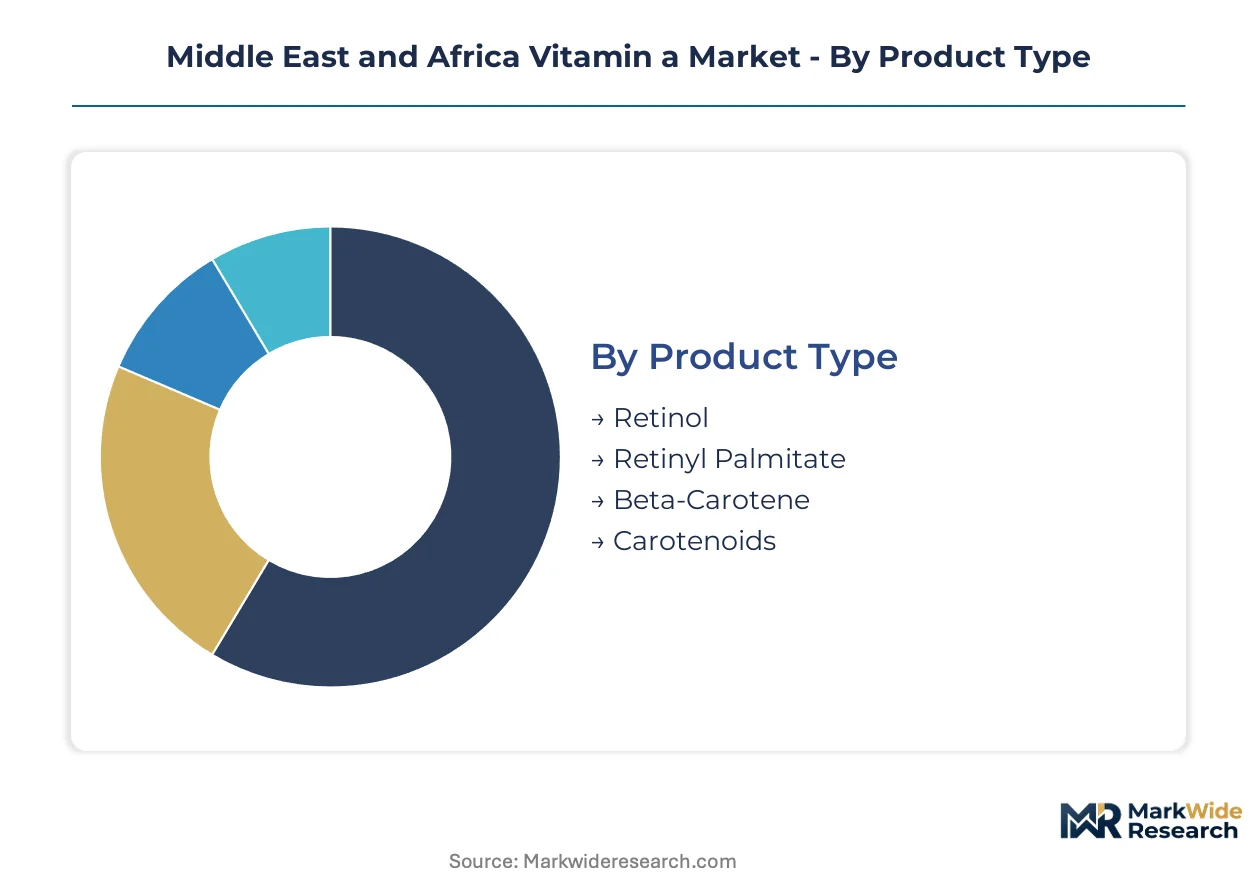
Vitamin A procurement patterns diverge sharply across the Middle East and Africa depending on whether buyers prioritize thermal stability, bioequivalence data, or clean-label positioning. Segmentation reveals where capital deployment concentrates and which customer cohorts command premium formulation services.
Product Type:
Capital intensity peaks with synthetic retinol intermediates requiring beta-ionone chemistry infrastructure, while natural extraction demands specialized solvent recovery systems.
- Retinol:The alcohol form of vitamin A delivers highest bioactivity per international unit and dominates pharmaceutical-grade specifications. Egyptian ophthalmic API manufacturers and Saudi dairy fortifiers both specify retinol for its established stability data under Gulf standard thermal processing.
- Retinyl Palmitate:Esterified retinol offers superior oxidative stability in high-heat food matrices, making it the default choice for edible oil fortification programs in Morocco and wheat flour processors across Egypt. Palmitate esters resist degradation during extrusion and spray-drying operations common in ready-to-use therapeutic food production.
- Beta-Carotene:Marine algae-derived provitamin A commands premium positioning in UAE pharmacy channels targeting health-conscious consumers seeking clean-label alternatives.
- Carotenoids:Mixed carotenoid complexes from plant sources serve niche applications in natural cosmetics and specialty nutraceuticals with limited regional processing infrastructure.
Retinyl Palmitate absorbs the bulk of installed capacity; Beta-Carotene is expanding most quickly.
Application:
Margin structure varies dramatically across applications, with pharmaceutical and supplement formulations capturing value pools that dwarf commodity animal feed volumes.
- Food & Beverages:Mandatory national fortification programs in Egypt and Morocco lock in baseline demand for retinol premixes in edible oils, wheat flour, and dairy. SFDA and ESMA maximum permitted levels enforce compliance testing that elevates barriers for substandard suppliers.
- Dietary Supplements:Sports nutrition premiumization in South Africa and Nigeria is electrifying demand for stable retinyl ester formulations, with athlete-focused protein fortification driving specification upgrades. Direct procurement from BASF and Glanbia technical teams is displacing traditional distributor intermediaries among large-scale Johannesburg manufacturers.
- Animal Feed:Poultry and aquaculture operations in Egypt and Saudi Arabia utilize vitamin A for growth optimization, though pricing pressure from commoditized premixes limits margin expansion.
- Pharmaceuticals:Egypt's drug authority applies GMP requirements to retinol-containing ophthalmic preparations, creating a separate compliance layer for finished dose manufacturers reducing import dependency.
Food & Beverages commands absolute volume leadership; Dietary Supplements is climbing the fastest on a value basis.
End User:
Procurement authority fragments across end users with divergent technical sophistication, from institutional pharmaceutical buyers to direct-to-consumer online segments.
- Health-conscious Consumers:Gulf pharmacy channels and South African wellness retailers drive demand for beta-carotene positioning and algae-sourced provitamin A with premium clean-label attributes.
- Athletes:Protein fortification specifications in Johannesburg and Lagos sports nutrition manufacturing specify retinyl palmitate potency and excipient compatibility directly in supply agreements with ingredient specialists.
- Pet Owners:Premium pet food formulations in UAE and Saudi Arabia incorporate vitamin A for coat and vision health, following humanization trends in companion animal nutrition.
- Medical Professionals:Egyptian dermatological and ophthalmic prescribers specify retinol-based APIs with bioequivalence documentation, influencing hospital procurement committees and private clinic formularies.
Health-conscious Consumers represent the largest addressable base; Athletes are gaining share fastest on a per-capita spending basis.
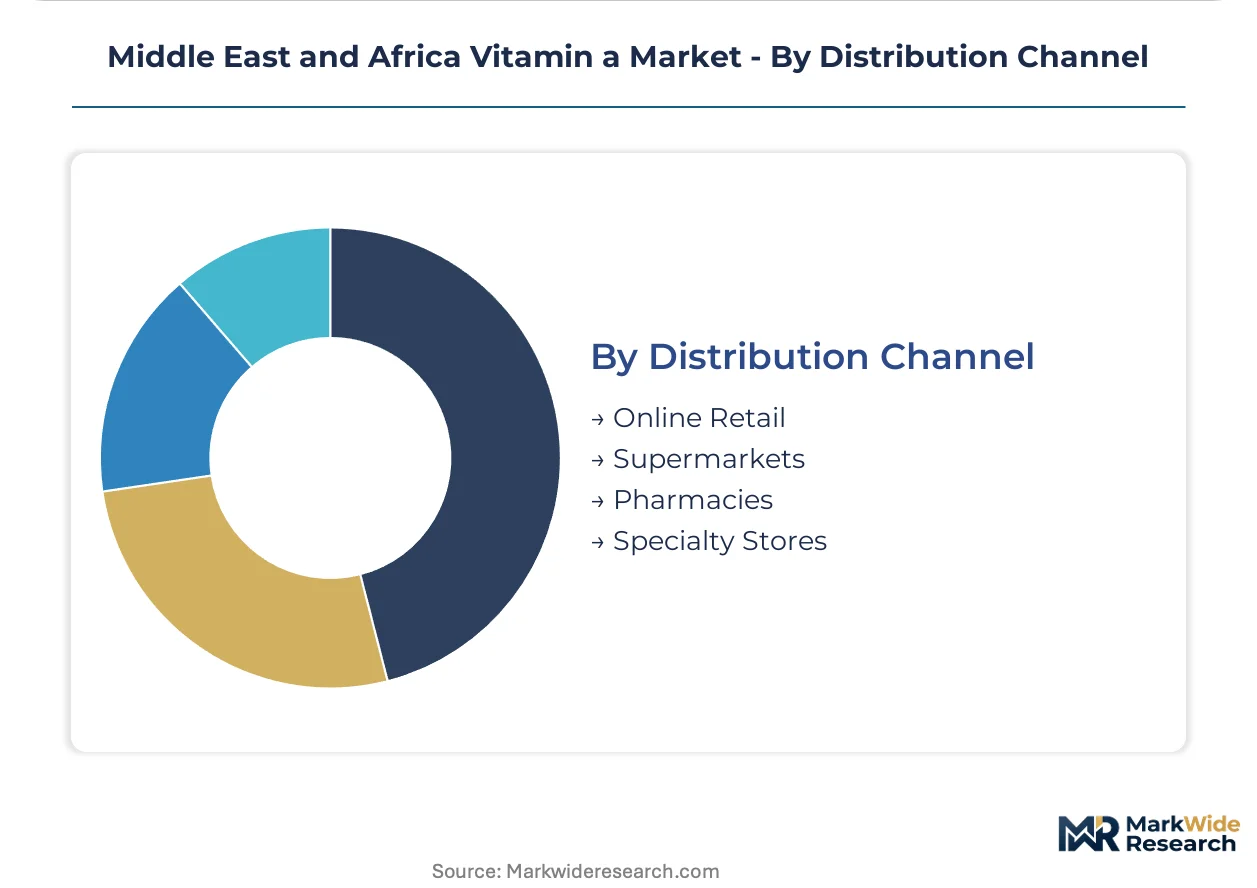
Distribution Channel:
Channel economics reflect the technical complexity of vitamin A products, with pharmacies and specialty stores capturing high-margin segments that resist online commoditization.
- Online Retail:Direct-to-consumer supplement brands in Nigeria and Kenya are establishing technical relationships with ingredient suppliers, bypassing traditional distribution layers for retinol and beta-carotene premixes.
- Supermarkets:Mass-market fortified food distribution in Saudi Arabia and Egypt concentrates procurement through established dairy and edible oil processors with SFDA pre-approved registration packages.
- Pharmacies:Gulf pharmacy chains enforce multi-market registration requirements that favor vendors with harmonized SFDA-ESMA compliance documentation, consolidating supplier relationships around pre-approved dossiers.
- Specialty Stores:Sports nutrition and wellness boutiques in South Africa serve athlete segments with vitamin A-fortified protein formulations, competing on technical service rather than price alone.
Supermarkets move the highest absolute tonnage; Online Retail is expanding most quickly among mid-tier brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beta-ionone chemistry infrastructure and marine carotenoid extraction capacity anchor procurement patterns across the Middle East and Africa, with Gulf petrochemical feedstocks and South African solvent recovery systems serving distinct formulation needs.
Saudi Arabia
Edible oil fortification mandates and dairy processor expansion drive retinyl palmitate procurement volumes. SFDA maximum permitted levels for infant nutrition enforce unified testing protocols across domestic manufacturers. Riyadh-based dairy conglomerates are consolidating supplier relationships around vendors with pre-approved multi-market registration packages.
United Arab Emirates
Pharmacy channel premiumization and clean-label supplement demand elevate beta-carotene positioning in Dubai and Abu Dhabi retail. ESMA harmonized standards with Saudi Arabia eliminate redundant dossier requirements for cross-border suppliers. Dubai's free zone logistics hubs are attracting toll-manufacturing investments serving Gulf supplement brands.
Egypt
Ophthalmic API production scaling and wheat flour fortification programs lock in dual demand streams for retinol and retinyl esters. The country's drug authority applies pharmaceutical-grade GMP requirements to finished dose manufacturers reducing import dependency. Cairo's formulation clusters are recalibrating output schedules to serve rising orders from regional contract manufacturers.
South Africa
Sports nutrition premiumization and updated labeling regulations for health products tighten compliance requirements for Johannesburg supplement manufacturers. The Department of Health regulates fortification compliance through its food control directorate. Cape Town and Durban laboratories concentrate specialized HPLC expertise for quantifying vitamin A content in complex food matrices.
Nigeria
Supplement contract manufacturing expansion and direct procurement from ingredient specialists displace traditional distributor intermediaries. Underdeveloped local premix blending capacity creates white space for regional toll-manufacturing partnerships. Lagos procurement teams now specify retinol potency and excipient compatibility directly in supply agreements with technical service providers.
Middle East and Africa Vitamin a Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution infrastructure, creating a tiered structure where synthetic retinol specialists, premix blenders, and finished goods marketers occupy distinct competitive positions. The market fragments across pharmaceutical-grade API suppliers, food-grade fortification specialists, and sports nutrition formulators with divergent margin profiles. Three archetypes dominate: petrochemical-integrated intermediate producers, regional toll-manufacturing partners, and brand-owners with pharmacy channel control. Capacity expansion in Egyptian ophthalmic API production and strategic partnerships for Kenyan contract manufacturing represent the dominant competitive moves.
Among German chemical conglomerates, BASF SE anchors regional supply of synthetic retinol intermediates through technical-grade production networks. Bayer AG exemplifies the pharmacy-channel archetype, leveraging established distribution infrastructure across Gulf markets to sustain shelf presence. Irish nutrition specialists Glanbia PLC occupy a position in the sports nutrition segment, competing on technical service rather than commodity pricing alone.
| Leading Market Players |
|---|
| Bayer AG |
| Amway Corp. |
| Abbott |
| Glanbia PLC |
| Herbalife Nutrition Ltd. |
| GSK plc |
| DuPont de Nemours, Inc. |
| Archer Daniels Midland Company |
| BASF SE |
| Others |
Supply & Pricing Matrix
Beta-ionone spot prices and petrochemical feedstock indices cascade through synthetic retinol production costs, compressing margins for Egyptian API manufacturers while elevating procurement premiums for Gulf dairy fortifiers seeking multi-market registration packages. Price stratification across pharmaceutical-grade, food-grade, and feed-grade tiers reflects divergent compliance burdens and thermal stability specifications rather than raw material differentials alone.
Pricing Analysis
Technical service bundling separates premium-tier suppliers from commodity vendors, with BASF and Glanbia embedding formulation support and excipient compatibility testing into supply agreements while unbundled retinol intermediates trade on spot markets. Pharmaceutical-grade retinol commands substantial premiums over food-grade retinyl palmitate due to Egypt's GMP certification requirements and bioequivalence documentation burdens. Cost compression in feed-grade beta-carotene intensifies because Nigerian poultry operations prioritize volume scale over stability performance. Animal feed buyers exhibit highest price sensitivity, while Egyptian ophthalmic API manufacturers absorb premium pricing to secure validated supply chains.
Supply Chain Analysis
Dual-sourcing mandates from Saudi dairy conglomerates and Egyptian drug authorities force buyers to qualify alternate suppliers for retinol and retinyl ester streams, extending procurement cycles but reducing single-source vulnerability. Technical-grade synthetic retinol production concentrates in Germany, China, and India, while marine algae beta-carotene extraction clusters in Israel and Australia. Supply chains draw from petrochemical-derived beta-ionone precursors and solvent-recovered carotenoid complexes, exposing margins to crude oil volatility and solvent recovery yield fluctuations. Distribution runs through Dubai free zone logistics hubs serving Gulf markets and Johannesburg blending facilities supplying East African contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa vitamin A market sits at a formulation technology inflection, with encapsulation systems using modified starch and gum arabic matrices displacing conventional spray-dried powders in Saudi beverage applications.
For Market Incumbents: Extend technical service capabilities into excipient compatibility testing and stability validation to defend against direct procurement trends among Johannesburg supplement manufacturers. Deepen backward integration into beta-ionone precursor supply through long-term offtake agreements with petrochemical producers, insulating margins from feedstock volatility that threatens Egyptian API operations. For New Entrants and Emerging Players: Begin with Kenyan toll-manufacturing partnerships targeting underdeveloped local premix blending capacity serving East African supplement brands. Lagos and Nairobi direct-to-consumer channels offer the most penetrable entry points, with clean-label algae-sourced beta-carotene positioning commanding pharmacy channel premiums in UAE health-conscious segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor Egyptian ophthalmic API specialists with validated GMP credentials and existing SFDA registration dossiers, as Cairo's formulation clusters recalibrate to serve regional contract manufacturing demand. Monitor convergence between Gulf and North African regulatory timelines as the primary inflection signal, with harmonized maximum permitted levels accelerating multi-market vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Adoption | Modified starch matrices narrow stability gaps between synthetic retinol and natural carotenoids in Saudi beverage trials. |
| Backward Integration into Beta-Ionone | Petrochemical offtake agreements insulate Egyptian API margins from crude oil price volatility exposure. |
| Kenyan Toll-Manufacturing Partnerships | Regional blending capacity addresses underdeveloped local premix infrastructure serving East African supplement brands. |
| SFDA-ESMA Registration Harmonization | Unified testing protocols eliminate redundant dossier costs for cross-border suppliers serving Gulf dairy processors. |
| Algae-Sourced Beta-Carotene Positioning | Marine-derived provitamin A commands pharmacy channel premiums targeting UAE health-conscious consumers. |
Research Methodology
Trade databases, pharmaceutical regulatory filings, and food fortification program documentation formed the secondary backbone, cross-referenced with primary interviews involving premix procurement managers at Saudi dairy conglomerates, Egyptian ophthalmic API formulators, and South African sports nutrition technical directors. Bottom-up and top-down triangulation validated volume estimates across retinol, retinyl palmitate, and beta-carotene product streams.
Bottom-up modeling aggregated segment-level demand across application categories, while top-down analysis anchored total market size to national fortification program tonnage disclosures and import customs records. Segmentation dimensions included product type, application vertical, end-user archetype, and distribution channel complexity. CAGRs were derived from elasticity-adjusted demand projections incorporating regulatory mandate expansion rates and pharmaceutical localization policies.
Underlying measurement precision varies by segment; mandatory fortification program volumes carry tighter precision than discretionary supplement consumption estimates. Forecasts reflect assumptions regarding SFDA-ESMA regulatory convergence and Egyptian API localization timelines. Deviation in beta-ionone feedstock pricing or Gulf harmonization delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Micronutrients Market