
 Food Fortification Market | 2026-2036
Food Fortification Market Size, Share, and Industry Trends Forecast 2026-2036
Food Fortification Market Analysis
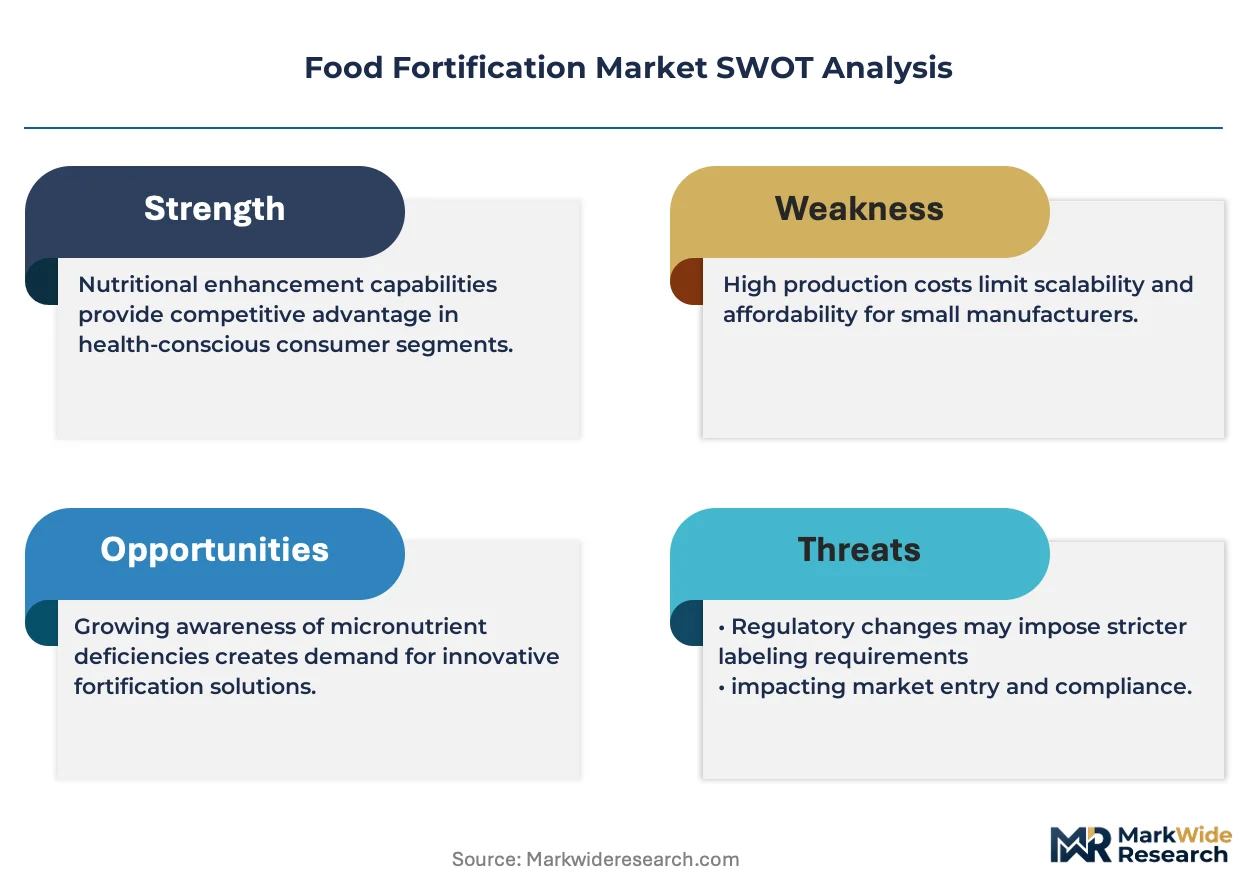
Precision blending technology is tilting food fortification from batch processing toward continuous-flow manufacturing with real-time nutrient monitoring. DSM Nutritional Products leverages its integrated premix and customized solutions portfolio to anchor supply relationships with large-scale millers across Asia and Africa. Cargill competes through backward integration into vitamin sourcing and regional formulation facilities that reduce lead times for food manufacturers. BASF SE differentiates via its Carotenoids and vitamins technology leadership, sustaining R&D intensity in encapsulated nutrient delivery systems.
Food fortification involves the deliberate addition of micronutrients—vitamins, minerals, amino acids, or proteins—to edible products to correct or prevent deficiencies, with iron, folic acid, and vitamin A representing the most widely mandated additions. The process employs thermal-stable premixes, extrusion coating, and spray-drying to ensure bioavailability retention through cooking and storage temperatures up to 180°C. Vitamins and minerals occupy the dominant product type position due to mandatory flour, salt, and oil fortification programs across developing economies. Powder and liquid forms lead the form category, though granules are gaining share in industrial-scale rice and grain fortification where uniform dispersion is critical.
The FDA governs nutrient content claims and fortification limits under 21 CFR 101, while FSSAI in India mandates rice fortification standards and premix quality benchmarks that directly determine supplier qualification. WHO guidelines and Codex Alimentarius frameworks shape national legislation, creating harmonization pressure on exporters serving multiple regulatory jurisdictions. Stakeholders must monitor evolving maximum nutrient levels and labeling requirements as bioequivalence evidence standards tighten for novel delivery formats.
Market Dynamics
Mandatory wheat and maize flour fortification directives from WHO are compressing supplier qualification timelines while millers in emerging economies scramble for thermal-stable premix sourcing. This regulatory tightening is forcing premix manufacturers to reconfigure formulation facilities for real-time nutrient monitoring.
Growth Catalysts
- FSSAI Rice Fortification Mandate:India's government-backed rice fortification programs are reshaping procurement patterns for premix suppliers across South Asia.
- Extrusion Coating Technology:Industrial-scale rice processors are adopting spray-drying and extrusion coating to ensure uniform micronutrient dispersion at cooking temperatures up to 180°C.
- WHO Flour Guidelines:Mandatory fortification standards for wheat and maize flour are tightening compliance requirements across multiple African and Asian jurisdictions.
Market Restraints
- Vitamin Input Volatility:Concentration of vitamin A and folic acid precursor supply among specialty chemical producers creates pricing instability for premix formulators.
- Encapsulation Cost Barrier:Thermal-stable encapsulated nutrient delivery systems require capital-intensive equipment that excludes smaller regional millers.
- Codex Harmonization Friction:Divergent maximum nutrient level standards between WHO guidelines and national FSSAI benchmarks complicate exporter compliance.
Strategic Opportunities
- Sub-Saharan Africa Staple Programs:Underpenetrated maize flour fortification in Nigeria, Kenya, and Tanzania offers white space for premix suppliers with regional formulation capabilities.
- PLI Scheme Alignment:India's production-linked incentive schemes for food processing infrastructure reduce capital barriers for domestic micronutrient integration.
- Continuous-Flow Convergence:Integration of precision blending with real-time nutrient monitoring enables shift from batch processing to continuous manufacturing.
Industry Challenges
- Bioequivalence Evidence Gap:Novel delivery formats face tightening evidence standards for nutrient bioavailability claims under evolving FDA 21 CFR 101 requirements.
- Legacy System Integration:Millers with established batch processing infrastructure encounter technical friction retrofitting continuous-flow monitoring equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Fortification Market |
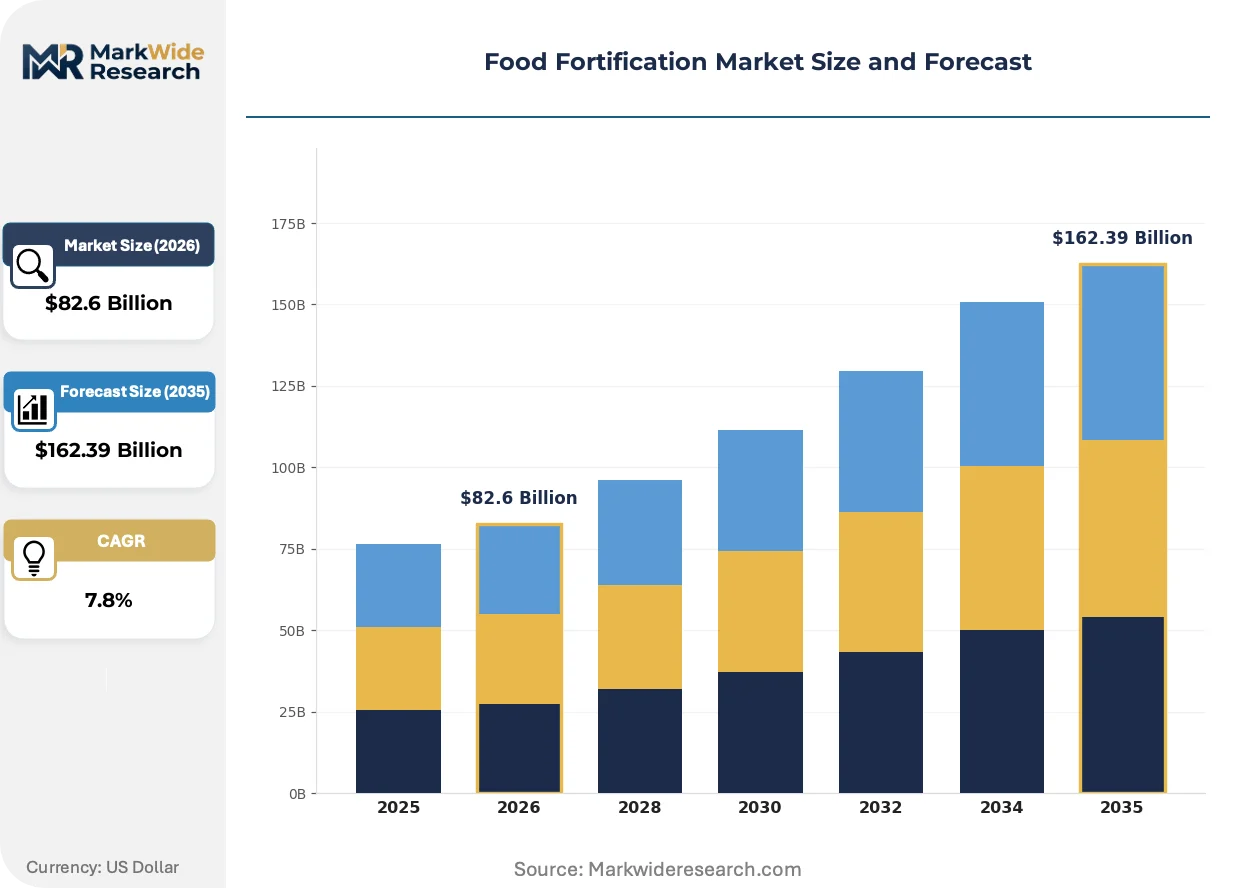
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $162.39 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Proteins Form: Powder, Liquid, Granules, Tablets End User: Households, Food Manufacturers, Healthcare Providers, Nutritional Institutions Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | DSM Nutritional Products, General Mills, Nestlé S.A., Glanbia PLC, Bühler Group, Cargill, BASF SE, Tate & Lyle PLC, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Fortification Market Emerging Trajectories
Food fortification is pivoting from commodity premix supply toward engineered nutrient delivery systems with embedded quality verification. This shift is compressing supplier margins while rewarding technology-integrated formulators.
Encapsulated vitamin and mineral matrices with thermal barrier coatings are rendering obsolete conventional powder premixes that degrade during high-temperature extrusion. Large-scale rice millers in India and Southeast Asia are adopting these systems at accelerating pace. The technology is rendering obsolete spot-check quality assurance in favor of inline spectroscopic monitoring.
REACH chemical safety registrations in Europe and FSSAI premix quality benchmarks in India are converging on stricter heavy metal and contaminant thresholds for micronutrient additives. Industrial consequence includes mandatory third-party certification for suppliers serving multiple regulatory jurisdictions. Encapsulated nutrient delivery formats face the steepest compliance burden due to complex multi-component supply chains.
Millers are consolidating premix procurement under long-term technical partnership agreements rather than spot commodity purchasing. Large packaged food manufacturers are displacing fragmented local supplier relationships with integrated premix-and-formulation service contracts. This pattern concentrates most visibly in India's government rice fortification tenders where technical compliance outweighs unit cost.
Food Fortification Market Segmentation
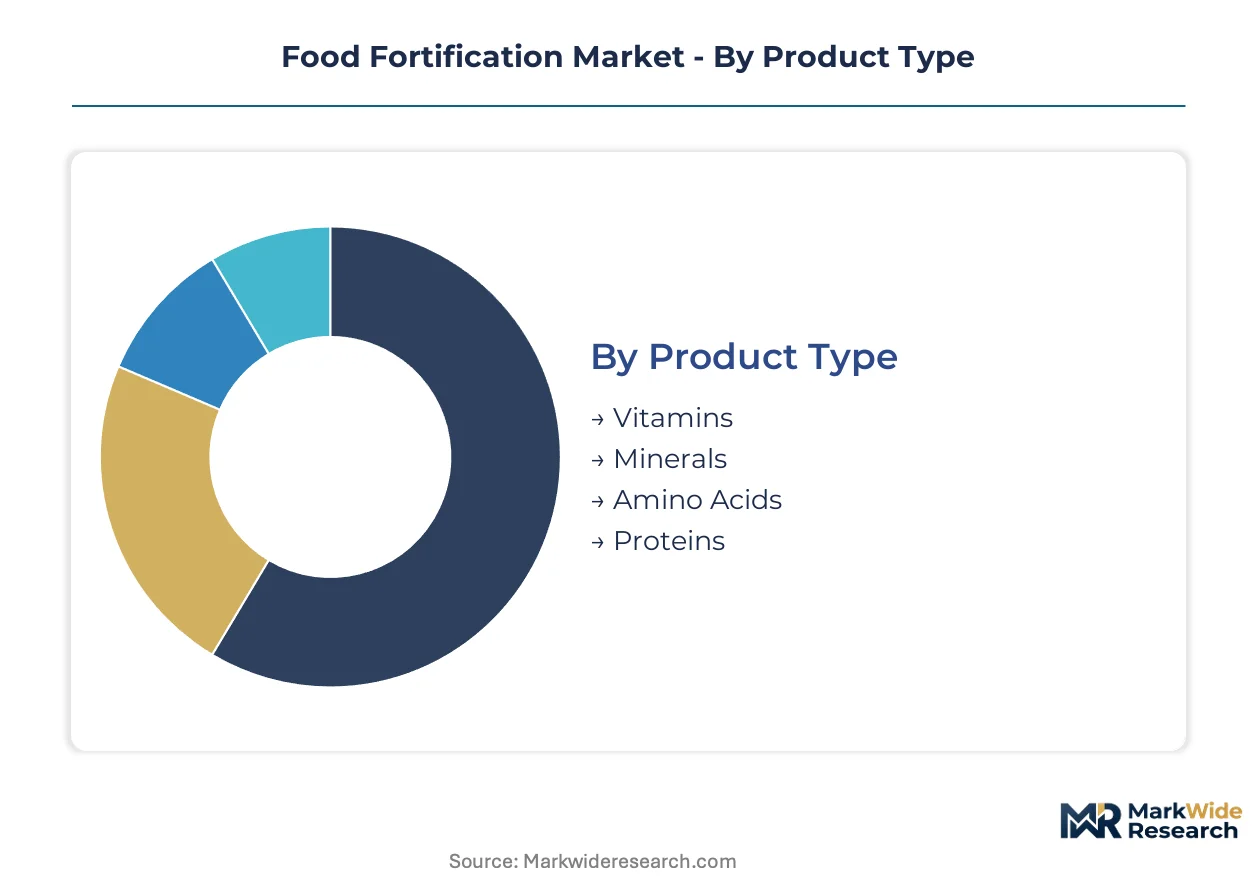
Food fortification segmentation reveals distinct technical requirements across micronutrient categories, with formulation stability and bioavailability retention driving supplier specialization. Each dimension carries unique regulatory compliance burdens and procurement patterns that reshape competitive positioning.
Product Type:
After-sales technical support intensity varies sharply across micronutrient categories, with vitamins and minerals demanding continuous formulation troubleshooting while amino acids require integration engineering.
- Vitamins:Thermal-stable premixes of vitamin A, D, B-complex, and folic acid dominate mandatory flour and rice fortification programs. Demand concentrates in India where FSSAI rice fortification standards require real-time bioavailability verification through cooking cycles.
- Minerals:Iron, zinc, iodine, and selenium compounds formulated for high-temperature stability in extrusion processes. Iron premixes for wheat flour anchor procurement volumes across African milling operations governed by WHO fortification directives.
- Amino Acids:Lysine and methionine supplementation for cereal protein quality enhancement in institutional feeding programs.
- Proteins:Concentrated dairy and plant protein fortification for specialized nutrition products targeting healthcare channels.
Vitamins and minerals hold the largest share; momentum sits with amino acids as protein quality standards tighten in school feeding programs.
Form:
Cost tier stratification separates industrial-scale continuous-flow systems from batch-compatible formats accessible to smaller millers.
- Powder:Standard micronutrient premixes for dry blending into flour, salt, and sugar with established dispersion protocols. Powder formats retain dominance in Indian government rice fortification tenders where unit economics outweigh advanced delivery premiums.
- Liquid:Oil-soluble vitamin concentrates for edible oil fortification with simplified dosing equipment requirements. Liquid premixes for vitamin A in palm oil are gaining traction in Nigerian and Kenyan processing facilities.
- Granules:Extrusion-coated micronutrients engineered for thermal barrier protection during high-temperature rice processing. Granule adoption accelerates in Southeast Asian industrial mills where cooking temperature exposure exceeds 180°C.
- Tablets:Pre-measured fortification units for small-batch artisanal millers and institutional kitchen applications.
Powder maintains volume leadership; granules are climbing the fastest as precision coating technology diffuses through Asian rice processing infrastructure.
End User:
Application-driven specification divergence separates commodity-scale food manufacturing from precision-dose healthcare requirements.
- Food Manufacturers:Large-scale millers and packaged food producers integrating premixes into staple products under mandatory fortification mandates. Indian wheat millers represent the most concentrated procurement segment following FSSAI compliance deadline acceleration.
- Nutritional Institutions:School feeding programs, disaster relief operations, and military ration systems requiring bulk premix procurement with documentation rigor.
- Healthcare Providers:Clinical nutrition formulators demanding bioequivalence certification and patient-specific dosing precision.
- Households:Direct-to-consumer fortified salt and condiment purchases through retail channels with minimal technical support requirements.
Food manufacturers command the largest procurement volumes; nutritional institutions are expanding most quickly as government-backed rice distribution scales across South Asia.
Distribution Channel:
Customer type stratification separates technical partnership models from transactional procurement.
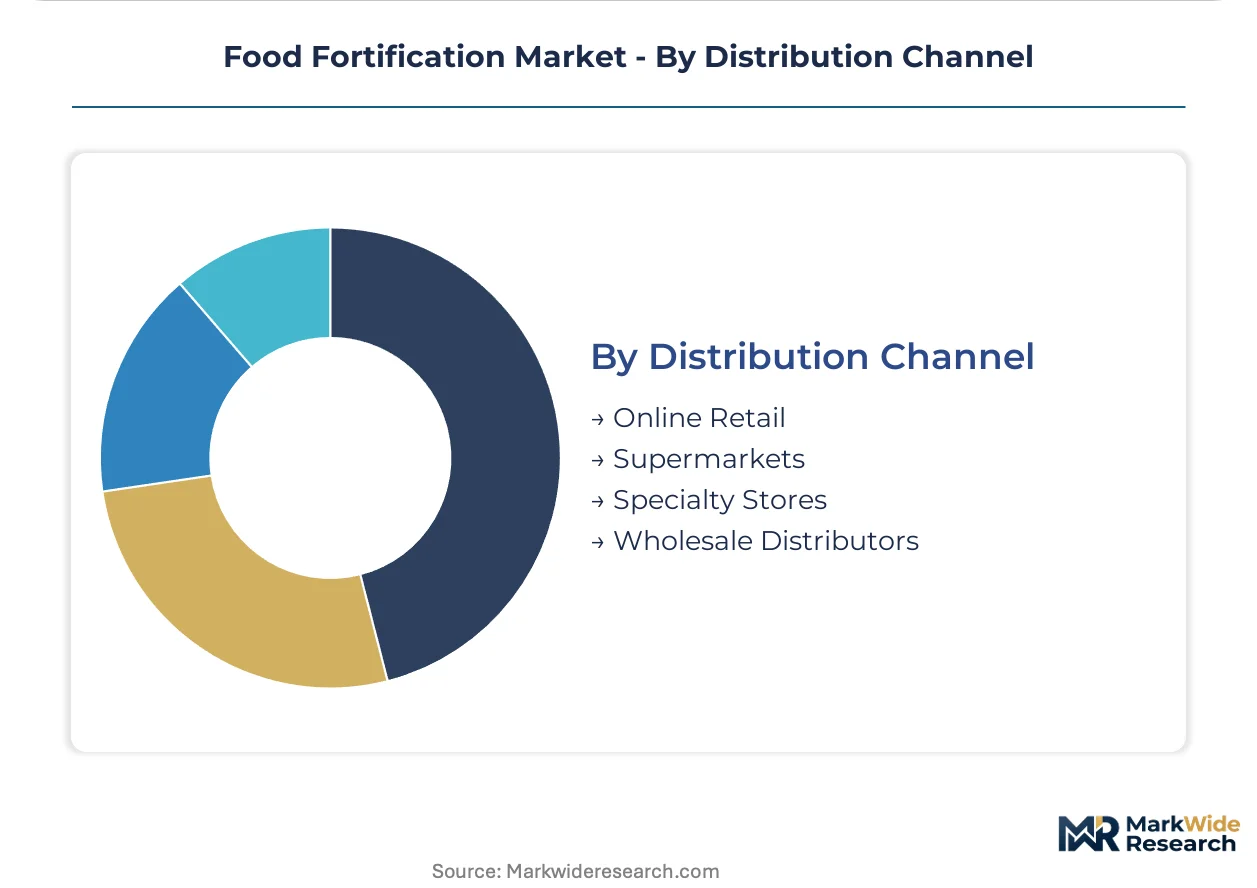
- Wholesale Distributors:Regional premix aggregators serving fragmented milling operations with inventory management and technical advisory services. Distributor networks anchor supply relationships across Sub-Saharan African markets where direct supplier presence remains limited.
- Online Retail:Direct premix procurement platforms enabling smaller millers to bypass traditional distributor markups.
- Supermarkets:Consumer-facing fortified product retail with minimal influence on industrial premix sourcing patterns.
- Specialty Stores:Niche channels for organic and non-GMO certified fortification ingredients targeting premium food manufacturers.
Wholesale distributors retain channel dominance; online retail is gaining share fastest as digital procurement platforms penetrate mid-sized milling operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports fortified rice premixes to Bangladesh and Nepal while importing thermal-stable vitamin matrices from European specialty chemical producers. This trade corridor reflects broader South Asian dependency on external micronutrient sourcing despite expanding domestic formulation capacity.
India
Government rice distribution programs and FSSAI fortification mandates drive premix procurement volumes. The FSSAI rice fortification standards require real-time bioavailability verification, reshaping supplier qualification. Mumbai and Delhi-NCR host concentrated premix formulation facilities serving northern wheat belt millers.
United States
FDA 21 CFR 101 nutrient content claims govern wheat flour and cereal fortification specifications. The FDA maintains strict maximum nutrient level thresholds for voluntary fortification programs. Minneapolis and Chicago anchor Midwest milling clusters where large-scale millers integrate continuous-flow premix systems.
Germany
REACH chemical safety registrations impose heavy metal and contaminant thresholds on imported micronutrient additives. EFSA scientific opinions shape national fortification policy for dairy and beverage applications. Bavaria and North Rhine-Westphalia concentrate encapsulation technology providers serving pan-European food manufacturers.
Brazil
Mandatory wheat flour fortification laws expand premix demand from industrial baking and pasta manufacturing sectors. ANVISA governs maximum fortification levels and labeling requirements for packaged foods. São Paulo state hosts the dominant milling infrastructure where regional premix distributors compete for technical partnership contracts.
Nigeria
Underpenetrated maize flour fortification creates procurement opportunities for suppliers with regional formulation capabilities. The country's national food safety regulator implements WHO-aligned fortification standards with variable enforcement across states. Lagos and Kano represent primary demand centers where distributor networks manage inventory for fragmented milling operations.
Food Fortification Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated nutrition conglomerates with captive vitamin sourcing anchor the premium tier, while regional premix formulators occupy mid-market positions through distributor relationships. Technology-integrated specialists and commodity premix suppliers represent the remaining archetypes. Competitive dynamics center on backward integration into vitamin sourcing and geographic expansion through regional formulation facilities.
Within the integrated nutrition tier, DSM Nutritional Products and BASF SE exemplify archetypes combining premix formulation with captive nutrient production capabilities. Cargill occupies a position bridging agricultural commodity processing and micronutrient integration services. These three entities represent distinct strategic postures: DSM anchors through customized solutions portfolios, BASF sustains technology leadership in encapsulated delivery systems, and Cargill leverages backward integration into vitamin sourcing with regional formulation infrastructure.
| Leading Market Players |
|---|
| DSM Nutritional Products |
| General Mills |
| Nestlé S.A. |
| Glanbia PLC |
| Bühler Group |
| Cargill |
| BASF SE |
| Tate & Lyle PLC |
| Archer Daniels Midland |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Mumbai maritime corridor anchors vitamin A and folic acid precursor movements, with freight cost volatility compressing margins for premix formulators serving Indian government rice tenders while amplifying price differentiation between thermal-stable encapsulated grades and commodity powder formats.
Pricing Analysis
Prior-generation powder premixes trade at commodity spot benchmarks, current-generation encapsulated granules command formulation-service premiums, and next-generation continuous-flow integrated systems are resetting contract structures toward outcome-based pricing. Pricing stratifies across premium encapsulated, standard spray-dried, and economy dry-blend tiers. Price differentiation hinges on FSSAI certification grade and volume scale, with bulk government tenders squeezing unit economics. Cost compression in standard powder grades is intensifying because Indian millers consolidate procurement under technical partnership agreements. Small regional millers exhibit highest price sensitivity; large packaged food manufacturers prioritize bioavailability guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning for vitamin precursor sourcing. China, India, and Switzerland concentrate active ingredient production for thermal-stable micronutrient matrices. Raw material dependencies center on retinol acetate, iron fumarate, and modified starch encapsulation substrates. Single-source vulnerability persists for high-purity vitamin A palmitate where European specialty chemical producers control capacity. Distribution runs through wholesale distributor networks across Sub-Saharan Africa and direct technical partnerships in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food fortification is pivoting toward engineered nutrient delivery systems where formulation-as-a-service layers expand faster than commodity premix volumes, creating attach-rate expansion for technology-integrated suppliers.
For Market Incumbents: Build regulatory certification moats by securing dual FSSAI and REACH registrations ahead of harmonization pressure. DSM Nutritional Products and BASF SE should deepen backward integration into vitamin A precursor sourcing to offset input volatility. Cargill must defend against regional formulators by accelerating continuous-flow equipment deployment in Indian milling clusters. Channel control through long-term technical partnerships remains the critical lever. For New Entrants and Emerging Players: Build out regional formulation capabilities in Nigeria and Kenya where maize flour fortification penetration lags WHO compliance targets. White space concentrates in thermal-stable iron premixes for African milling operations lacking encapsulated delivery access. Target nutritional institutions with documentation-heavy procurement requirements where incumbent service coverage is thin. Partner with established distributors to bypass capital-intensive direct miller relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors continuous-flow integration specialists over commodity premix suppliers. Five-to-ten year viability hinges on bioequivalence certification capabilities and regulatory compliance infrastructure. Acquisition targets should demonstrate embedded quality verification systems and multi-jurisdiction registration portfolios. Watch FSSAI enforcement acceleration in Indian states as the inflection signal for regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Sourcing | Cargill reduces lead times by controlling retinol acetate supply chains for Asian millers. |
| Continuous-Flow Manufacturing Deployment | Precision blending with real-time monitoring displaces batch processing in Indian rice fortification. |
| Dual Jurisdiction Certification Investment | FSSAI and REACH alignment enables single-supplier contracts across South Asian and European markets. |
| Regional Formulation Facility Expansion | Local premix production in Lagos and Kano penetrates underenforced Nigerian maize flour mandates. |
| Technical Partnership Contract Structuring | Long-term service agreements displace spot purchasing in Indian government rice distribution tenders. |
Methodological Framework
The analysis maps premix formulation technologies, micronutrient delivery formats, and end-user procurement patterns, each validated through miller procurement directors, premix technical sales leads, and regulatory compliance officers at FSSAI and FDA. Primary interviews with distribution channel partners and secondary validation through customs trade data, SEC filings of integrated nutrition conglomerates, WHO guideline documentation, and FSSAI premix quality benchmarks informed segmentation sizing. Bottom-up premix volume estimates triangulated against top-down fortified food production forecasts.
Assumptions held fixed include current WHO flour fortification directive coverage and existing FSSAI rice fortification enforcement timelines, while vitamin input cost trajectories and continuous-flow technology diffusion rates were varied across scenarios. The forecast framework models product type, form, end user, and distribution channel dimensions alongside regional regulatory cluster adoption curves. CAGRs derive from segment-level volume projections calibrated against historical fortified staple production growth. Bioequivalence evidence standards and encapsulation technology cost curves served as industry-specific forecast inputs.
Stress conditions across vitamin A precursor supply disruptions, FSSAI enforcement acceleration, and continuous-flow equipment adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and thermal stability technology maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Europe Vitamin a Market