
 Vitamin AD Drops Market | 2026-2036
Vitamin AD Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin AD Drops Market Insights
Pediatric wellness program revenue is fragmenting across direct-to-consumer channels, hospital formulary contracts, and pharmacy benefit managers. Abbott Laboratories leverages its neonatal care franchise to sustain institutional purchasing relationships across North America. ZYDUS Cadila anchors its position through cost-optimized emulsion formulations targeted at India's public health procurement tenders.
Vitamin AD Drops deliver retinol and cholecalciferol in liquid or emulsion form, typically dosed at 400 IU vitamin D and 1,500 IU vitamin A per milliliter for infant populations; manufacturers suspend active compounds in oil-based carriers to enhance bioavailability in fat-malabsorbing neonates. Liquid formulations dominate volume due to ease of titration for low-body-weight infants, while softgel and capsule variants capture margin pools among adult and pregnant-women segments seeking portability. Pharmacy channels retain the largest value share, though online distribution is gaining traction among subscription-based pediatric nutrition programs.
The US FDA oversees dietary supplement cGMP compliance for domestic manufacturers, while India's CDSCO regulates pharmaceutical-grade vitamin AD formulations under its drug licensing framework; WHO prequalification standards additionally shape export-access requirements for suppliers targeting low-income country procurement programs. Stakeholders must monitor evolving purity thresholds for retinol esters and vitamin D3 sourcing as regulatory bodies tighten contaminant specifications.
Market Dynamics
WHO prequalification standards are compressing supplier margins while simultaneously locking qualified manufacturers into multi-year procurement contracts with UNICEF and national immunization programs across low-income countries.
Growth Catalysts
- India's public health procurement:Government-backed maternal and child health initiatives drive institutional volume through state tender systems. State governments aggregate demand for vitamin AD drops under the Reproductive and Child Health program.
- Emulsion technology advancement:Nano-emulsion formulations improve bioavailability in preterm infants with fat malabsorption disorders. Manufacturers adopting this process capture premium positioning in neonatal intensive care segments.
- WHO micronutrient guidelines:Updated supplementation protocols expand recommended dosing populations from infants to postpartum women in malaria-endemic regions. National programs align procurement specifications to these standards.
Market Restraints
- Retinol ester input volatility:Synthetic vitamin A precursor prices fluctuate with petrochemical feedstock costs and Chinese API export quotas. Formulators lack short-term hedging instruments for this concentrated input.
- Single-source API dependence:Seven Chinese manufacturers supply over 80 percent of global vitamin D3 for pharmaceutical-grade formulations. Geopolitical friction or environmental enforcement shutdowns propagate supply shocks.
- FSSAI-DGFT regulatory misalignment:India's food safety and drug import frameworks apply conflicting purity thresholds to identical vitamin AD products. Importers face dual compliance costs and detention risks at ports.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:National vitamin A supplementation programs in Nigeria, Ethiopia, and the Democratic Republic of Congo rely on capsule formats with higher wastage rates. Liquid drop formulations reduce dosing errors and nurse time per child.
- Subscription pediatric nutrition platforms:Direct-to-consumer channels bypass pharmacy markups while capturing longitudinal adherence data. Platforms integrate dosing reminders with growth tracking apps for parent retention.
- EU MDR pharmaceutical-grade pathway:Medical device regulation convergence creates a premium tier for vitamin AD drops positioned as clinical nutrition. Manufacturers achieving CE-MDR certification access hospital formulary budgets distinct from dietary supplement channels.
Industry Challenges
- Pharmaceutical emulsion formulation expertise:Stable oil-in-water systems for neonatal populations require specialized rheology and oxidation protection knowledge. Talent scarcity in lipid chemistry constrains product pipeline expansion.
- WHO prequalification timeline compression:Documented stability data requirements extend submission preparation to 24-36 months. Accelerated WHO-PQ pathways for pandemic supplies do not extend to routine micronutrient products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin AD Drops Market |
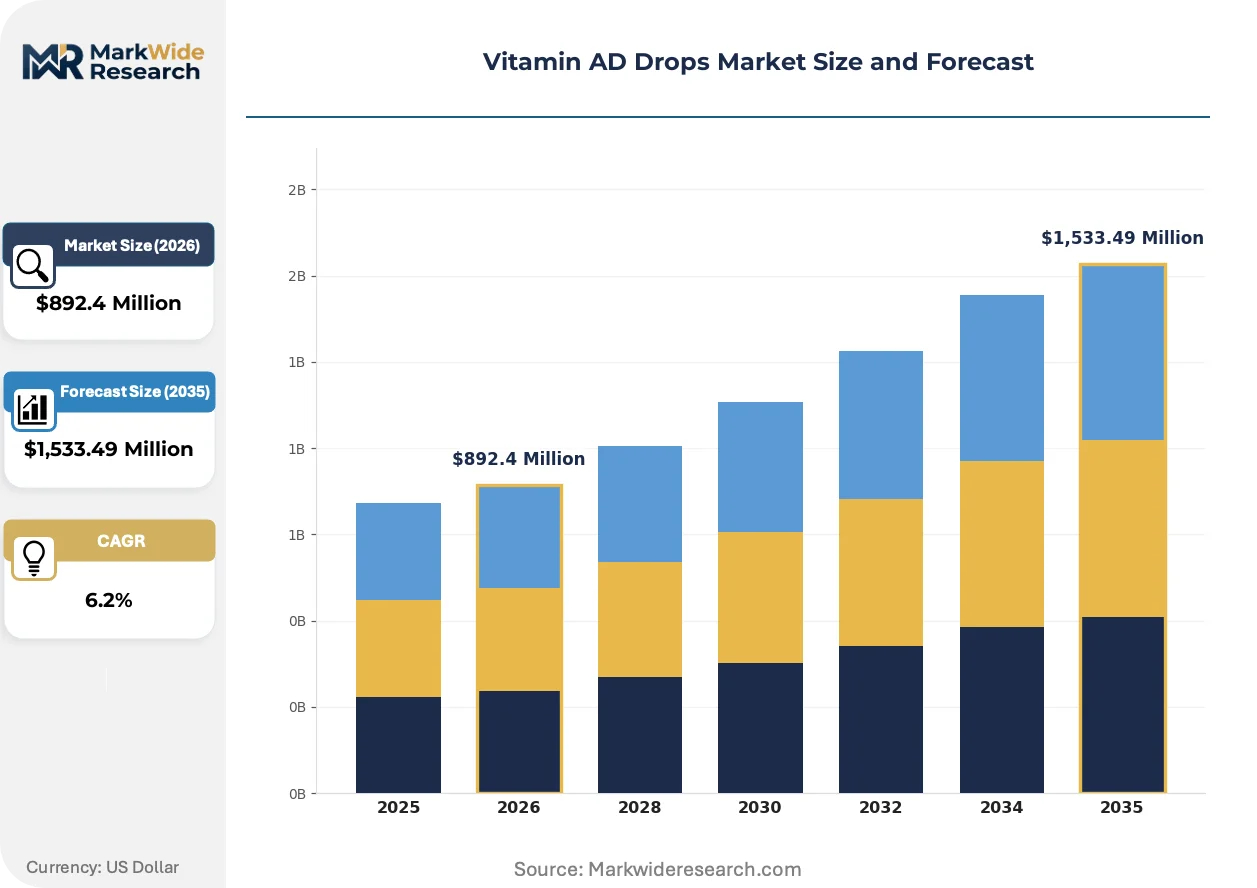
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,533.49 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Softgel, Capsule, Powder End User: Infants, Children, Adults, Pregnant Women Distribution Channel: Online, Retail, Pharmacy, Health Store Formulation: Syrup, Emulsion, Suspension, Suspension with Flavor |
| Companies Covered | Meganutra, Nature's Nutra, Ddrops Company, Carlson Laboratories, GSK, DSM, ZYDUS Cadila, Abbott Laboratories, Nordic Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin AD Drops Market Trends and Innovations
Formulation science and procurement digitization are restructuring competitive advantage away from manufacturing scale toward bioavailability proof and supply chain transparency.
Nano-emulsion delivery systems using ultrasonic homogenization achieve particle sizes below 200 nanometers, enhancing lymphatic absorption of lipophilic vitamins in neonates with cholestatic liver conditions. European neonatal intensive care units in Germany and the Netherlands are transitioning procurement specifications to mandate this particle size threshold. The technology is rendering obsolete conventional macro-emulsion products in premium hospital segments despite their lower unit cost.
REACH Annex XVII restrictions on peroxide contaminants in cosmetic and pharmaceutical-grade oils are forcing reformulation of traditional vitamin A carrier oils. ECHA enforcement actions against Spanish and Italian contract manufacturers elevated testing costs but also consolidated supply relationships toward vertically integrated oil processors. Pediatric pharmaceutical-grade drops face the strictest residual solvent limits, compressing available supplier pools for retinol ester sourcing.
Hospital formulary managers in the United States are unbundling vitamin AD drops from bundled neonatal nutrition contracts, creating direct price competition between Abbott, Mead Johnson, and generic emulsion suppliers. Pharmacy benefit managers are responding with narrow network carve-outs for preferred manufacturers. This disintermediation is most advanced in California and Texas, where Medicaid managed care organizations pilot reference pricing for preventive pediatric supplements.
Vitamin AD Drops Market Segmentation
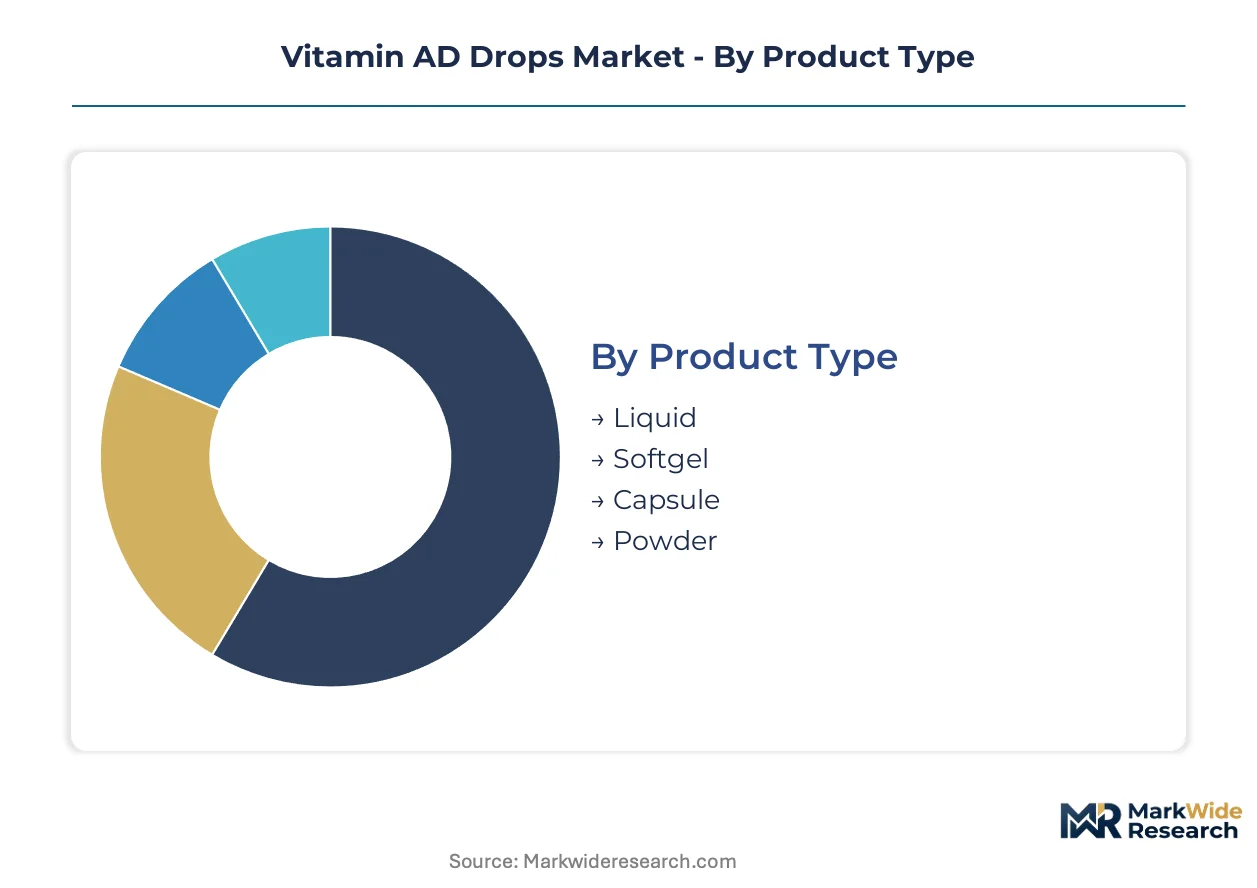
Vitamin AD drops manufacturers configure production lines around bioavailability requirements and dosing precision rather than interchangeable commodity formats. Segment boundaries reflect divergent regulatory pathways—pharmaceutical-grade emulsions face CDSCO drug licensing while dietary supplement liquids navigate FSSAI food safety thresholds.
Product Type:
Cost tier separates mass-market accessibility from premium positioning in neonatal intensive care procurement.
- Liquid:Oil-based carriers suspend retinol palmitate and cholecalciferol at 400 IU vitamin D per milliliter, enabling precise titration for low-birth-weight infants. India's state tender systems under the Reproductive and Child Health program aggregate institutional demand for this format, though oxidation stability constraints limit shelf life to 24 months. Liquid holds installed capacity. Softgel is rotating up the share rankings.
- Softgel:Gelatin-encapsulated oil concentrates deliver portability for adult and pregnant-women segments seeking adherence convenience outside clinical settings. German hospital formulary managers in Bavaria and North Rhine-Westphalia specify softgel for postpartum supplementation programs, displacing liquid in ambulatory care. Softgel commands margin premiums but requires moisture-barrier packaging for tropical distribution.
- Capsule:Hard-shell gelatin or HPMC variants dominate Nigeria and Ethiopia's national vitamin A supplementation programs despite higher nurse administration time per child.
- Powder:Sachet formats for reconstitution serve humanitarian relief logistics where cold chain constraints prohibit liquid transport.
Liquid commands manufacturing scale. Softgel is climbing the fastest in value contribution.
End User:
Application urgency varies from preventive public health campaigns to acute neonatal intervention.
- Infants:Preterm populations with cholestatic liver conditions require nano-emulsion particle sizes below 200 nanometers for lymphatic absorption. Dutch and German neonatal intensive care units mandate this specification in procurement tenders, consolidating supplier relationships toward ultrasonic homogenization specialists. Infants anchor clinical revenue. Children are rotating up the share rankings.
- Children:WHO-expanded supplementation protocols now cover ages 6-59 months in malaria-endemic regions, broadening addressable populations beyond historical infant-only targeting. India's Integrated Child Development Services distributes drops through anganwadi centers, creating last-mile infrastructure dependencies.
- Adults:Malabsorption syndromes and bariatric surgery recovery drive prescription-grade demand in US Medicare Part D formularies.
- Pregnant Women:Postpartum protocols in sub-Saharan Africa emphasize maternal repletion to prevent night blindness in breastfeeding infants.
Infants concentrate R&D investment. Pregnant Women represent the steepest expansion trajectory in program eligibility.
Distribution Channel:
Customer access patterns fragment between institutional procurement and direct household purchase.
- Pharmacy:Community and hospital dispensaries retain the largest value share through prescription anchoring and insurance reimbursement integration. California and Texas Medicaid managed care organizations pilot reference pricing for preventive pediatric supplements, compressing pharmacy markups. Pharmacy holds installed capacity. Online is rotating up the share rankings.
- Online:Subscription-based pediatric nutrition platforms bypass traditional distribution tiers while capturing longitudinal adherence data through dosing reminder apps. Parent retention depends on integration with growth tracking tools rather than price competition alone.
- Retail:Mass merchandisers and supermarkets stock dietary supplement-grade products with limited pharmacist consultation.
- Health Store:Natural products channels emphasize organic carrier oils and absence of synthetic preservatives for parental preference segments.
Pharmacy dominates tender capture. Online is expanding most quickly in customer acquisition efficiency.
Formulation:
Supply concentration in lipid chemistry expertise determines competitive moat durability.
- Emulsion:Oil-in-water systems with specialized rheology and oxidation protection enable stable retinol delivery in fat-malabsorbing neonates. Talent scarcity in pharmaceutical emulsion formulation constrains pipeline expansion despite premium pricing in neonatal intensive care. Emulsion holds installed capacity. Suspension is rotating up the share rankings.
- Suspension:Micronized vitamin particles in aqueous carriers address cost-sensitive procurement in India's state tender systems, accepting lower bioavailability for unit economics.
- Syrup:Viscous sugar-based vehicles mask bitterness but conflict with WHO sugar reduction guidelines for early childhood nutrition.
- Suspension with Flavor:Fruit essences improve infant acceptance in direct-to-consumer channels, though flavor additive regulatory thresholds vary between FSSAI and CDSCO jurisdictions.
Emulsion concentrates technical differentiation. Suspension with Flavor is gaining share fastest in parent-directed purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seven Chinese manufacturers supply over 80 percent of global vitamin D3 API, concentrating upstream supply risk in the Yangtze River Delta and Shandong Peninsula clusters. Procurement patterns diverge sharply between institutional tender systems and direct-to-consumer channels across major markets.
United States
California and Texas Medicaid managed care organizations pilot reference pricing for preventive pediatric supplements, compressing pharmacy markups. FDA cGMP compliance requirements filter domestic manufacturers while allowing dietary supplement-grade imports. Hospital formulary managers in the Boston and San Francisco metro areas unbundle vitamin AD drops from bundled neonatal nutrition contracts.
India
State governments aggregate demand under the Reproductive and Child Health program, creating volume procurement through tender systems. CDSCO drug licensing and FSSAI food safety frameworks apply conflicting purity thresholds, imposing dual compliance costs on importers. Manufacturing clusters in Ahmedabad and Hyderabad specialize in cost-optimized emulsion formulations for public health procurement.
Germany
Bavarian and North Rhine-Westphalia hospital formulary managers specify softgel formats for postpartum supplementation programs, displacing liquid in ambulatory care. ECHA REACH Annex XVII restrictions on peroxide contaminants in carrier oils force reformulation of traditional retinol ester products. Neonatal intensive care units in Munich and Cologne mandate nano-emulsion particle sizes below 200 nanometers.
China
Environmental enforcement shutdowns in Shandong and Jiangsu provinces propagate vitamin D3 supply shocks to global formulators. NMPA pharmaceutical-grade licensing and export quota administration shape API availability. Zhejiang and Jiangsu coastal clusters host the seven manufacturers dominating pharmaceutical-grade vitamin D3 synthesis.
Nigeria
National vitamin A supplementation programs rely on capsule formats with higher wastage rates, creating opportunity for liquid drop conversion. WHO prequalification standards compress supplier margins while locking qualified manufacturers into multi-year UNICEF procurement contracts. Lagos and Abuja serve as distribution hubs for West African regional program logistics.
Vitamin AD Drops Market Competitive Landscape
Multinational pharmaceutical conglomerates and specialized pediatric nutrition firms split the market along institutional tender versus premium direct-to-consumer lines. The structure consolidates around three tiers: API-integrated conglomerates commanding supply security, formulation specialists capturing neonatal intensive care premiums, and regional generics competing on state tender unit economics. Dominant competitive moves include backward integration into vitamin D3 synthesis and technology licensing for nano-emulsion delivery systems.
Among North American specialists, Ddrops Company and Carlson Laboratories occupy positions in the premium direct-to-consumer segment, while Abbott Laboratories anchors the institutional hospital formulary tier. ZYDUS Cadila represents the cost-optimized emulsion archetype targeting India's public health procurement tenders. These three exemplify the strategic divergence between premium bioavailability positioning and volume-driven tender capture.
| Leading Market Players |
|---|
| Meganutra |
| Nature's Nutra |
| Ddrops Company |
| Carlson Laboratories |
| GSK |
| DSM |
| ZYDUS Cadila |
| Abbott Laboratories |
| Nordic Naturals |
| Others |
Pricing and Supply Chain Analysis
Seven Chinese manufacturers controlling over 80 percent of global vitamin D3 API production concentrate upstream margin capture in the Yangtze River Delta and Shandong Peninsula, forcing downstream formulators into long-term offtake negotiations or backward integration investments to secure supply security. This supply asymmetry pushes finished product pricing power toward API-integrated conglomerates while fragmenting margin pools for pure-play emulsion specialists competing on India's state tender unit economics.
Pricing Analysis
After-sales revenue from subscription-based pediatric nutrition platforms drives lifetime value capture as direct-to-consumer channels bypass pharmacy markups and capture longitudinal adherence data. Three-tier pricing structure across pharmaceutical-grade emulsions, dietary supplement liquids, and economy suspensions segments buyers by certification tier and bioavailability proof. Pricing pressure stems from California and Texas Medicaid managed care organizations piloting reference pricing for preventive pediatric supplements, compressing pharmacy margins. Hospital formulary managers exhibit lowest price sensitivity due to unbundled procurement specifications, while India's state tender systems aggregate volume buyers with extreme unit cost sensitivity.
Supply Chain Analysis
Tariff exposure between China and major importing markets dominates supply chain risk planning as environmental enforcement shutdowns in Shandong and Jiangsu provinces propagate vitamin D3 supply shocks. Manufacturing concentrates in China for API synthesis, India for cost-optimized emulsion formulation, and Germany for nano-emulsion specialty production. Raw material dependencies center on retinol palmitate, cholecalciferol, and pharmaceutical-grade carrier oils with REACH Annex XVII peroxide restrictions. Single-source API vulnerability from concentrated Chinese supply creates systemic exposure. Distribution runs through institutional tender systems for volume procurement, pharmacy networks for prescription anchoring, and direct-to-consumer platforms for subscription retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitamin AD Drops Market fragmentation creates entry niches as WHO prequalification standards bifurcate procurement between qualified institutional suppliers and unqualified dietary supplement channels. Direct-to-consumer platform expansion and sub-Saharan Africa program conversion from capsules to liquid drops represent parallel demand-side shifts opening white-space opportunities.
For Market Incumbents: Build formulation moats through nano-emulsion particle size thresholds below 200 nanometers as Dutch and German neonatal intensive care units mandate this specification in procurement tenders, displacing conventional macro-emulsion products. Secure backward integration into vitamin D3 synthesis or captive long-term offtake agreements with the seven dominant Chinese API manufacturers to neutralize single-source supply vulnerability. Invest in CDSCO drug licensing and FSSAI food safety dual compliance infrastructure to capture India's fragmented regulatory pathway arbitrage. For New Entrants and Emerging Players: Establish a beachhead in Nigeria, Ethiopia, and Democratic Republic of Congo national vitamin A supplementation programs by converting capsule-dependent wastage-heavy formats to liquid drop precision dosing, reducing nurse administration time per child. Target subscription-based pediatric nutrition platforms with integrated growth tracking apps and dosing reminder systems to bypass pharmacy distribution tiers entirely. Pursue WHO prequalification pathway despite 24-36 month timeline compression to lock multi-year UNICEF procurement contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nano-emulsion delivery system manufacturing as ultrasonic homogenization equipment and specialized lipid chemistry talent scarcity constrain capacity expansion. Acquisition targets should prioritize emulsion formulation specialists with existing CE-MDR certification or CDSCO drug licensing rather than pure dietary supplement players facing purity threshold escalation. Monitor ECHA REACH Annex XVII enforcement actions against peroxide contaminants in carrier oils as signal for supplier consolidation toward vertically integrated oil processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin D3 Synthesis | Captive API supply neutralizes Shandong environmental shutdown propagation risk for formulators. |
| Nano-Emulsion Technology Licensing | Ultrasonic homogenization patents secure premium positioning in German and Dutch neonatal intensive care procurement. |
| WHO Prequalification Pathway Investment | Documented stability data submission unlocks multi-year UNICEF and national immunization program contracts. |
| Direct-to-Consumer Platform Launch | Subscription pediatric nutrition bypasses pharmacy markups while capturing longitudinal adherence data for parent retention. |
| Dual CDSCO-FSSAI Compliance Infrastructure | Regulatory arbitrage capture in India's conflicting drug and food safety frameworks reduces import detention risk at ports. |
Research Methodology
Cross-validation between primary interviews with neonatal care specialists, hospital formulary managers, and pharmaceutical procurement officers and secondary validation through FDA cGMP filings, CDSCO drug licensing records, and WHO prequalification databases anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down macroeconomic drivers across the analysis window. Stakeholder roles engaged include emulsion formulation chemists, state tender system administrators in India, and ECHA regulatory compliance leads. Secondary sources span FSSAI food safety notifications, REACH Annex XVII enforcement actions, and UNICEF procurement contract disclosures.
Calibration against historical volume data from India's Reproductive and Child Health program tenders and German hospital formulary procurement specifications refines the analytical framework. Segmentation dimensions modeled include product type (liquid, softgel, capsule, powder), end user (infants, children, adults, pregnant women), distribution channel (pharmacy, online, retail, health store), and formulation technology (emulsion, suspension, syrup). CAGRs derive from compound growth trajectory analysis across these dimensions. Industry-specific forecast inputs incorporate nano-emulsion adoption rates in European neonatal intensive care and subscription platform customer acquisition efficiency metrics.
Stress conditions across retinol ester input volatility, Chinese API export quota administration, and FSSAI-DGFT regulatory misalignment enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding WHO guideline expansion timelines and environmental enforcement patterns in Shandong province. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Global Vitamin Tonics Market