
 Asia-Pacific Food Fortifying Agent Market | 2026-2036
Asia-Pacific Food Fortifying Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Fortifying Agent Market Outlook
FSSAI fortification mandates for rice, wheat flour, and edible oil is expanding the cost-of-entry calculus for new participants across India. BASF SE leverages its vitamin premix technology leadership to sustain formulation partnerships with major Indian millers. Kerry Group plc anchors its position through integrated taste and nutrition solutions that dominate Southeast Asian beverage applications. Cargill, Incorporated controls extensive supply chain infrastructure for mineral sourcing across Australian and Indonesian operations.
Food fortifying agents encompass vitamins, minerals, amino acids, and probiotics added to processed foods to restore nutrients lost during manufacturing or enhance nutritional profiles beyond baseline levels; these agents typically achieve incorporation rates of milligrams per kilogram and require thermal stability above pasteurization temperatures. Dairy Products applications lead absolute volume consumption due to fluid milk and yogurt fortification programs across China and India, while Nutritional Supplements represents the fastest-growing application segment as aging populations in Japan and South Korea shift toward targeted micronutrient intake. Powder form dominates manufacturing economics due to extended shelf stability and lower logistics costs, though Liquid form gains traction in ready-to-drink beverage lines where homogeneous dispersion proves critical.
FSSAI in India mandates micronutrient standards for packaged staples, while China's SAMR enforces GB national standards for nutrient fortification limits in prepackaged foods, and Japan's Ministry of Health, Labour and Welfare sets stringent specifications for functional food claims; collectively these frameworks elevate product registration costs and reshape competitive access. Stakeholders must monitor divergence between national fortification schedules and harmonized Codex Alimentarius guidelines to anticipate reformulation obligations and regional production relocation decisions.
Market Dynamics
FSSAI fortification mandates across India's packaged staple foods are forcing manufacturers to absorb micronutrient premix costs while reformulating production lines, compressing margins for mid-tier millers and redrawing supplier relationships toward certified premix specialists.
Growth Catalysts
- China's SAMR enforcement of GB nutrient limits:Prepackaged food manufacturers in Shanghai and Hangzhou must fortify dairy and beverage products to national standards, locking in steady premix demand.
- Japan's aging demographic pivot:Senior consumers in Tokyo and Osaka drive targeted micronutrient supplementation through functional food claims regulated by the Ministry of Health, Labour and Welfare.
- Australian mineral export infrastructure:Cargill's captive supply chains for zinc and iron compounds feed Southeast Asian premix processors, reducing raw material lead times.
Market Restraints
- Vitamin E acetate price volatility:Feedstock fluctuations in palm oil derivatives destabilize premix cost structures for Indian edible oil fortifiers.
- Chinese vitamin B12 concentration:Three state-owned fermentation facilities control bulk cobalamin supply, exposing downstream formulators to single-source risk.
- Thermal degradation ceiling:Probiotic fortifying agents face viability loss above pasteurization thresholds, limiting application in UHT milk processing.
Strategic Opportunities
- Vietnam's underpenetrated beverage sector:Ready-to-drink functional drinks in Ho Chi Minh City lack micronutrient standardization, creating first-mover space for liquid premix suppliers.
- South Korea's MFDS fast-track approval:Streamlined health functional food registration accelerates novel mineral chelate market entry.
- Indonesia's POS channel digitization:Direct-to-miller premix ordering platforms bypass traditional distributor markups in Java's rice fortification programs.
Industry Challenges
- Food technologist scarcity:Premix formulation expertise concentrates in Mumbai and Bangalore, forcing Southeast Asian processors to rely on Indian expatriate talent.
- Dual certification burden:Exporters to Japan must satisfy both Codex Alimentarius guidelines and PMDA functional claim specifications, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Fortifying Agent Market |
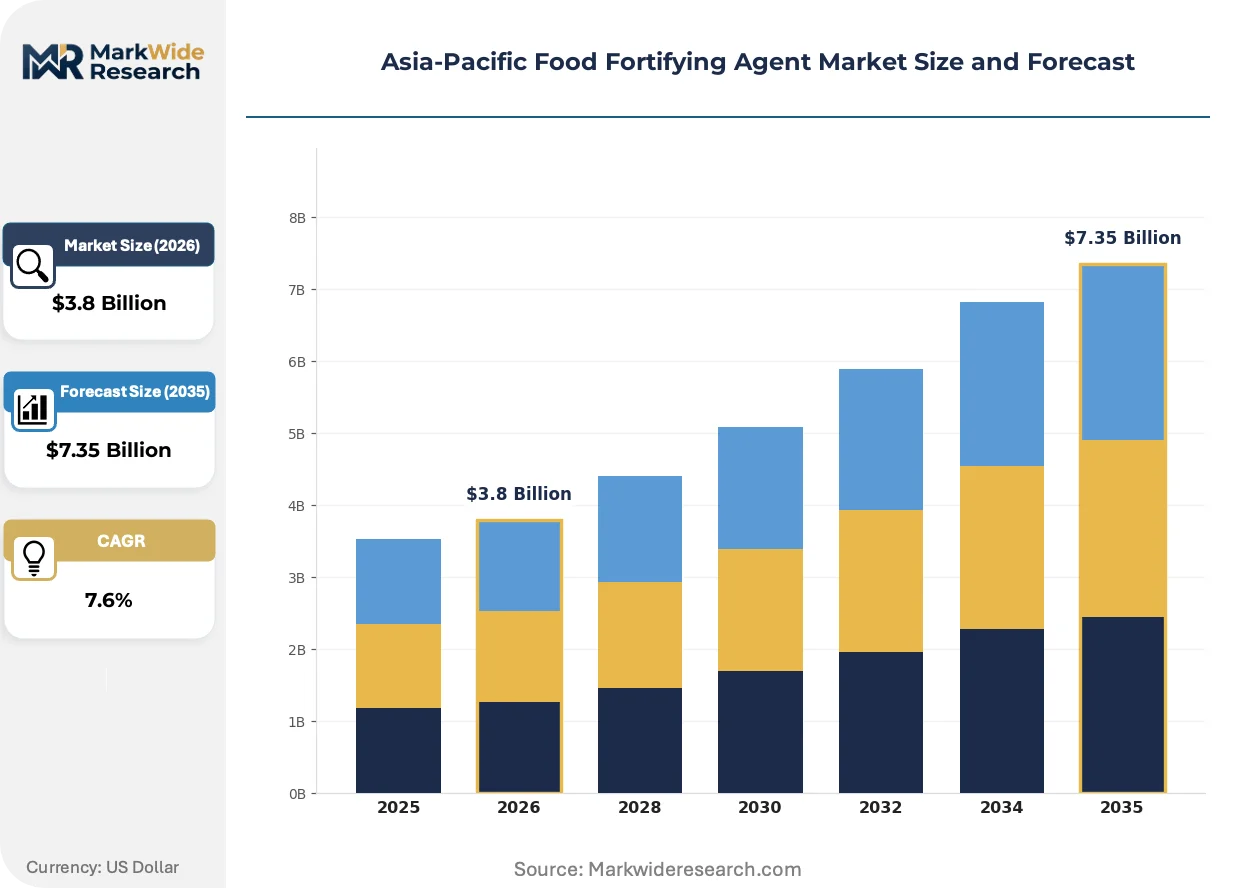
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
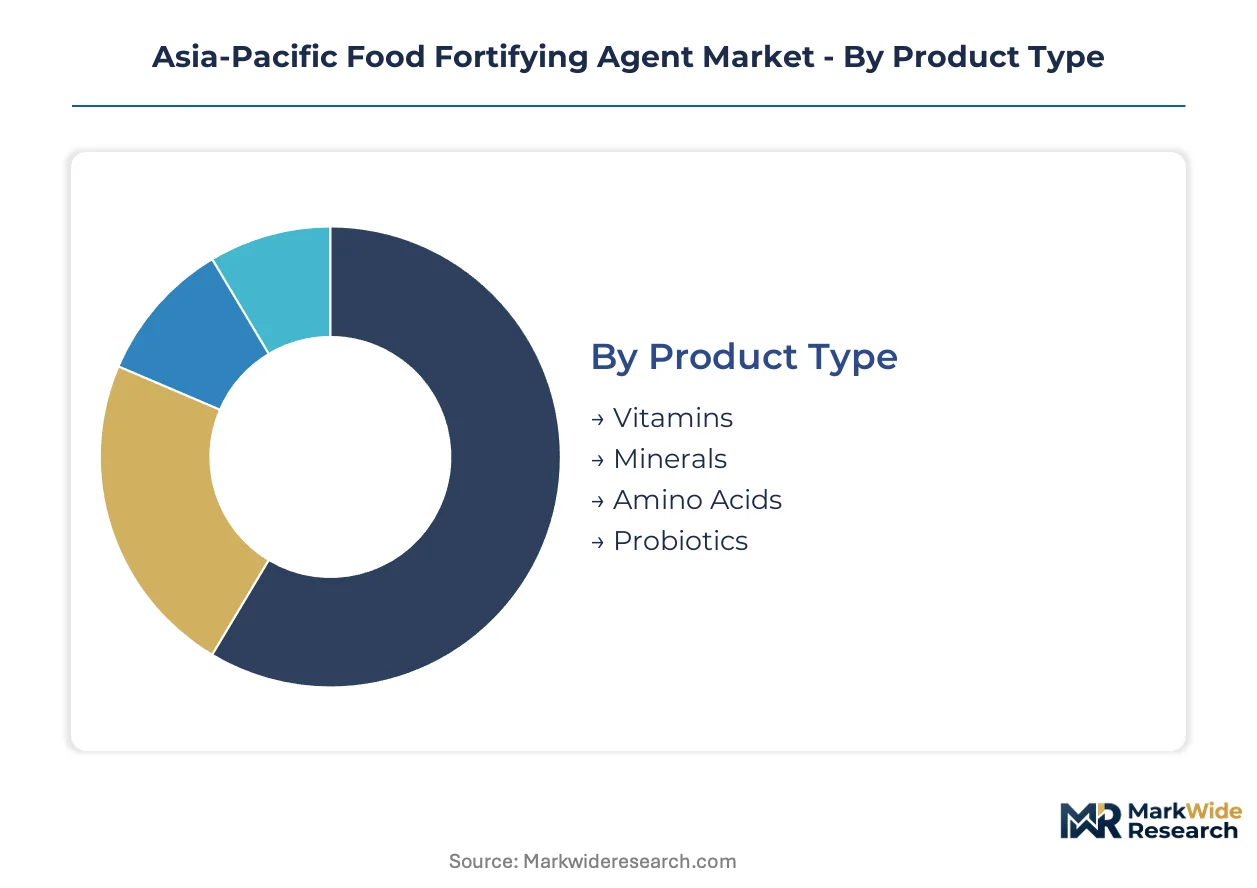
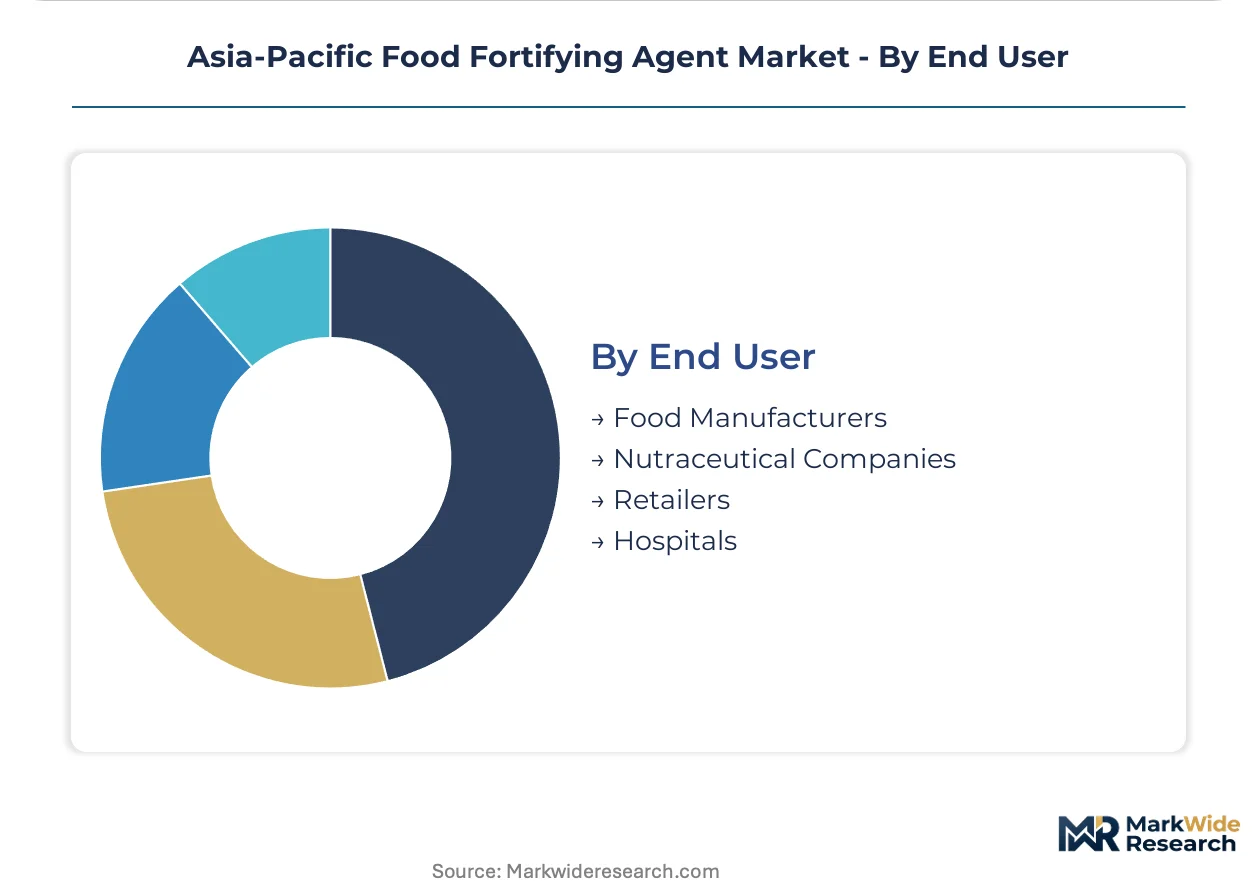
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Application: Dairy Products, Baked Goods, Beverages, Nutritional Supplements Form: Powder, Liquid, Granules, Tablets End User: Food Manufacturers, Nutraceutical Companies, Retailers, Hospitals |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, BASF SE, Tate & Lyle PLC, Glanbia PLC, Kerry Group plc, Ingredion Incorporated, Chr. Hansen Holding AS, DuPont, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Fortifying Agent Market Strategic Shifts
Encapsulation technologies and bioavailability enhancement methods are reshaping competitive differentiation, as thermal stability and controlled-release functionality become non-negotiable specifications in high-temperature processing environments.
Microencapsulation of lipid-soluble vitamins using modified starch matrices is expanding into UHT dairy applications across China's eastern manufacturing corridor. Inner Mongolia Mengniu and Yili Group processors adopt spray-dried vitamin A palmitate systems to withstand sterilization temperatures above 135°C. This thermal protection architecture is expanding into infant formula lines where nutrient retention rates directly determine shelf-life claims and export eligibility.
FSSAI's 2024 technical amendment to micronutrient premix quality standards mandates third-party laboratory certification for iron, folic acid, and vitamin B12 content verification. Indian rice millers in Punjab and Haryana must submit batch test reports to state food safety commissioners before distribution clearance. The compliance burden falls heaviest on small-scale millers lacking in-house analytical laboratories, accelerating consolidation toward integrated premix-slurry service providers.
Japanese convenience store chains now specify premix supplier sustainability credentials in procurement tenders, displacing pure price-based vendor selection. Seven-Eleven Japan and Lawson require vitamin premix partners to document carbon footprint per kilogram and renewable energy share in manufacturing. This buyer-driven environmental screening concentrates contract awards toward European and Australian suppliers with verified lifecycle data, pressuring Chinese and Indian competitors to accelerate emissions disclosure systems.
Asia-Pacific Food Fortifying Agent Market Segmentation
Food fortifying agent procurement patterns diverge sharply between commodity bulk buyers and precision formulators seeking micronutrient stability guarantees. Segment boundaries blur where premix suppliers bundle multiple agent categories into application-specific solutions for dairy and beverage processors.
Product Type:
Standalone vitamin and mineral premixes dominate high-volume staple fortification, while amino acid and probiotic systems require embedded delivery architectures to survive processing stresses.
- Vitamins:Lipid-soluble variants (A, D, E, K) demand microencapsulation against thermal degradation during UHT milk sterilization. Chinese dairy processors in Shanghai specify spray-dried palmitate forms for infant formula lines bound for domestic distribution and export qualification.
- Minerals:Iron, zinc, and selenium compounds anchor government-mandated rice and wheat flour programs across India. FSSAI compliance deadlines in Punjab and Haryana drive concentrated procurement of ferrous sulfate and zinc oxide premixes with certified bioavailability metrics.
- Amino Acids:Lysine and methionine supplementation targets plant-based protein fortification in Southeast Asian noodle manufacturing.
- Probiotics:Viability constraints above pasteurization temperatures restrict deployment to ambient-stable spore-forming strains in Japanese functional beverages.
Volume placements concentrate in Minerals; the faster expansion belongs to Vitamins.
Application:
Cost-tier stratification separates commodity fluid milk fortification from premium-positioned nutritional supplements commanding formulation premiums.
- Dairy Products:Fluid milk and yogurt fortification absorbs the largest absolute tonnage of vitamin A and D premixes. China's eastern manufacturing corridor near Hangzhou clusters the highest concentration of premix procurement offices serving Mengniu and Yili processing networks.
- Nutritional Supplements:Targeted micronutrient powders and capsules for aging populations in Japan and South Korea extract the highest per-kilogram margins. MFDS fast-track approvals for novel mineral chelates accelerate product lifecycle velocity in Seoul's functional food startups.
- Baked Goods:Folic acid and iron enrichment of wheat flour follows mandatory schedules in India and voluntary protocols in Australian bread manufacturing.
- Beverages:Ready-to-drink functional drinks in Vietnam's Ho Chi Minh City distribution networks lack standardized micronutrient specifications, creating specification volatility for premix suppliers.
Revenue concentrates in Nutritional Supplements; Dairy Products sustain the deepest volume penetration.
Form:
Supply chain economics favor powder logistics, though liquid systems penetrate beverage lines where dispersion homogeneity determines shelf-stability performance.
- Powder:Extended shelf stability and containerized shipping efficiency make this the default for cross-border premix trade. Australian mineral processors export zinc and iron compounds to Southeast Asian blenders in powder form to minimize moisture exposure during maritime transit.
- Liquid:Homogeneous dispersion requirements in ready-to-drink beverages drive adoption where UHT processing tolerances permit. Japanese beverage formulators specify liquid vitamin D3 emulsions for transparent sports drink applications requiring optical clarity.
- Granules:Intermediate flow properties suit intermediate-scale millers lacking sophisticated blending equipment.
- Tablets:Direct compression formats serve retail nutraceutical channels and hospital formulary procurement in South Korea.
Procurement weight concentrates in Powder; Liquid formats are climbing the fastest in beverage applications.
End User:
Customer-type segmentation tracks divergence between compliance-driven commodity buyers and innovation-seeking premium formulators.
- Food Manufacturers:Rice millers in India's Punjab and Haryana states constitute the largest addressable base, with FSSAI mandates forcing premix adoption regardless of margin compression. Third-party laboratory certification requirements accelerate consolidation toward integrated premix-slurry service providers.
- Nutraceutical Companies:Japanese and South Korean functional food specialists drive demand for bioavailability-enhanced mineral chelates and sustained-release vitamin architectures. PMDA claim substantiation requirements extend development timelines but protect pricing power for validated formulations.
- Retailers:Private-label supplement programs in Australian pharmacy chains specify premix supplier sustainability credentials, displacing pure price-based vendor selection.
- Hospitals:Enteral and parenteral nutrition specifications in Tokyo and Osaka medical centers demand pharmaceutical-grade micronutrient purity tiers.
Contract value concentrates in Food Manufacturers; Nutraceutical Companies deliver the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor operates as the dominant tax-incentive zone for food fortifying agent demand, clustering dairy and beverage processors near Shanghai and Hangzhou. India's FSSAI compliance mandates have transformed Punjab and Haryana into compulsory premix adoption zones for rice millers. Southeast Asian markets remain specification-volatile, with Vietnam's beverage sector and Indonesia's POS-digitized rice programs presenting contrasting maturity levels.
China
SAMR enforcement of GB nutrient limits locks in steady premix demand from Mengniu and Yili dairy processors. State-owned fermentation facilities control bulk vitamin B12 supply, exposing downstream formulators to concentration risk. Shanghai and Hangzhou anchor the eastern manufacturing corridor where spray-dried vitamin A palmitate systems penetrate UHT milk and infant formula lines.
India
FSSAI mandates for rice, wheat flour, and edible oil fortification force mid-tier millers to absorb micronutrient premix costs while reformulating production lines. Third-party laboratory certification requirements for iron, folic acid, and vitamin B12 content verification accelerate consolidation toward integrated premix-slurry service providers. Punjab and Haryana rice millers constitute the largest addressable base of compliance-driven commodity buyers.
Japan
Aging demographics in Tokyo and Osaka drive targeted micronutrient supplementation through functional food claims regulated by the Ministry of Health, Labour and Welfare. PMDA claim substantiation requirements extend development timelines but protect pricing power for validated formulations. Seven-Eleven Japan and Lawson now specify premix supplier sustainability credentials in procurement tenders, displacing pure price-based vendor selection.
South Korea
MFDS fast-track approval for health functional food registration accelerates novel mineral chelate market entry. Seoul's functional food startups extract premium margins from bioavailability-enhanced formulations. The Seoul Capital Area concentrates demand for pharmaceutical-grade micronutrient purity tiers in hospital enteral and parenteral nutrition specifications.
Vietnam
Ready-to-drink functional drinks in Ho Chi Minh City distribution networks lack standardized micronutrient specifications, creating first-mover space for liquid premix suppliers. Underpenetration relative to regional peers leaves pricing power with specification-setting entrants. Vietnamese beverage manufacturers represent the fastest-growing addressable pocket for homogeneous dispersion technologies.
Asia-Pacific Food Fortifying Agent Market Competitive Environment
European chemical conglomerates anchor one tier; Asia-Pacific nutrition specialists hold formulation partnerships with regional millers. The vendor base separates into three strata: bulk mineral processors with captive supply chains, integrated taste-and-nutrition platforms, and certified premix specialists serving compliance-driven markets. Strategic archetypes include backward-integrated raw material controllers, application-specific solution bundlers, and sustainability-credentialed premium suppliers. Dominant competitive moves center on geographic expansion into underpenetrated Southeast Asian markets and portfolio diversification toward bioavailability-enhanced delivery architectures.
Within the integrated solution tier, Kerry Group plc and Tate & Lyle PLC exemplify platforms that combine taste optimization with micronutrient stability guarantees. Among chemical-origin multinationals, BASF SE occupies a position representing vitamin premix technology leadership sustained through formulation partnerships. Cargill, Incorporated anchors the raw material control archetype through extensive supply chain infrastructure for mineral sourcing. These three entities collectively represent the competitive positioning spectrum: application bundling, technology licensing, and upstream supply security.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Tate & Lyle PLC |
| Glanbia PLC |
| Kerry Group plc |
| Ingredion Incorporated |
| Chr. Hansen Holding AS |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FSSAI-mandated premixes and discretionary nutraceutical formulations manifests in divergent pricing architectures and procurement network geometries across the Asia-Pacific region. Premium-tier suppliers command 40-60% markups for third-party verified micronutrient batches while commodity rice millers in Punjab absorb standardized pricing through consolidated slurry-service contracts.
Pricing Analysis
Lead-time compression premiums reward suppliers maintaining regional blending inventory near Shanghai and Mumbai distribution hubs. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FSSAI third-party verification commanding the top tier and uncertified spot powder trading at discounts. Pricing pressure stems from palm oil derivative volatility destabilizing vitamin E acetate cost structures. Mid-tier Indian edible oil fortifiers exhibit highest price sensitivity; Japanese nutraceutical formulators show least sensitivity due to PMDA claim substantiation protecting margin structures.
Supply Chain Analysis
Vitamin B12 fermentation supply rests on three Chinese state-owned facilities controlling bulk cobalamin output for downstream formulators. Mineral feedstock draws from Australian zinc and iron compound processors, Indian ferrous sulfate refiners, and Indonesian selenium extractors. Single-source vulnerability concentrates in Chinese vitamin B12 supply where downstream exposure to state-owned production quotas creates allocation risk. Distribution runs through integrated premix-slurry service providers consolidating small-scale miller procurement in India's northern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in certified premix laboratory capacity prop pricing premiums, with FSSAI-mandated third-party verification creating a structural bottleneck that protects incumbent margin structures.
For Market Incumbents: Deploy backward integration into mineral sourcing to secure zinc and iron compound supply chains against Australian export volatility. Consolidate formulation partnerships with major Indian millers facing FSSAI compliance deadlines. Threat substitution from encapsulated probiotic alternatives intensifies in Japanese functional beverages; certification investment in bioavailability-enhanced delivery architectures counters displacement risk. For New Entrants and Emerging Players: Capture Vietnam's underpenetrated ready-to-drink beverage sector where micronutrient standardization gaps create specification-setting opportunities. Liquid premix homogeneous dispersion technology represents the most penetrable application layer. Direct-to-miller digital ordering platforms bypass traditional distributor markups in Indonesia's rice fortification programs. For Investors and Strategic Acquirers: Re-rating potential sits with integrated taste-and-nutrition platforms given Southeast Asian beverage application bundling demand. Long-term viability favors suppliers with verified lifecycle carbon data serving Japanese convenience store procurement tenders. Watch FSSAI technical amendment enforcement intensity as inflection indicator for Indian market consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Thermal stability patents protect UHT dairy applications above 135°C sterilization thresholds. |
| Regional Blending Capacity Expansion | Shanghai and Mumbai hub proximity reduces lead times for Chinese and Indian dairy processors. |
| Third-Party Certification Investment | FSSAI laboratory accreditation creates compliance moats against uncertified commodity competitors. |
| Sustainability Credential Verification | Carbon footprint documentation satisfies Seven-Eleven Japan and Lawson procurement tender requirements. |
| Direct-to-Miller Digital Platform | POS channel digitization in Java bypasses traditional distributor markups for rice fortification programs. |
Study Parameters
Document review covered FSSAI technical amendments, SAMR GB standards filings, and MFDS health functional food registrations, complemented by interviews with premix formulation specialists, rice miller procurement officers, and dairy processor quality assurance directors. Secondary validation drew from customs trade data for mineral compound flows, Codex Alimentarius guideline revisions, and SEC filings of listed nutrition ingredient suppliers. Bottom-up volume modeling from application-specific consumption rates triangulated against top-down market sizing from regional production cluster analysis.
Historical consumption patterns across dairy, beverage, and nutritional supplement applications were cross-referenced against expert panel input from technical directors at integrated solution providers. The analytical framework segmented by product type, application, form, and end user across the projection horizon, with CAGRs derived from elasticity-adjusted demand curves incorporating regulatory mandate enforcement schedules. Industry-specific forecast inputs included FSSAI compliance deadline phasing and Japanese convenience store sustainability procurement adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese state-owned vitamin B12 production quota adjustments and palm oil derivative price volatility. Forecasts reflect documented assumptions on regulatory enforcement intensity and mineral feedstock trade flow stability. A small set of triggers—FSSAI laboratory certification backlog duration, SAMR GB standard revision timing, and Japanese retailer sustainability mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Vitamin B Market