
 Dispensing Tap Market | 2026-2036
Dispensing Tap Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Tap Market Outlook
Asset-light leasing models for draft beverage equipment is fragmenting competitive dynamics in the dispensing tap sector. Micro Matic leverages its specialized distribution network across European hospitality venues. Perlick Corporation anchors its position through in-house stainless steel fabrication capabilities. Alfa Laval competes on precision engineering standards for industrial-scale dispensing systems.
A dispensing tap is a flow-control device engineered with specified bore diameters, seal compositions, and actuation mechanisms to regulate liquid discharge from pressurized or gravity-fed containers. Stainless steel variants dominate commercial installations where sanitation cycles and corrosion resistance govern equipment lifespan. Electronic taps represent the fastest-growing product category as sensor-actuated pouring reduces waste and labor overhead in high-volume bars and stadiums. Brass material segments retain margin concentration in premium residential and craft brewery niches where tactile aesthetics and thermal conductivity differentiate positioning.
EPA guidelines on lead-free plumbing components and FDA food-contact surface requirements shape material selection and certification pathways for manufacturers serving North American accounts. EMA-aligned hygiene standards and EU F-Gas Regulation compliance for refrigerated dispensing systems create dual compliance burdens for exporters. REACH substance restrictions on certain brass alloys and plasticizers directly impact supply chain qualification timelines. Stakeholders must monitor evolving PFAS limitations and state-level plumbing codes as these frameworks increasingly dictate product redesign cycles and market access conditions.
Market Dynamics
Electronic actuation systems are compressing replacement cycles across commercial hospitality installations as sensor-based flow control displaces manual valve mechanisms in high-throughput venues.
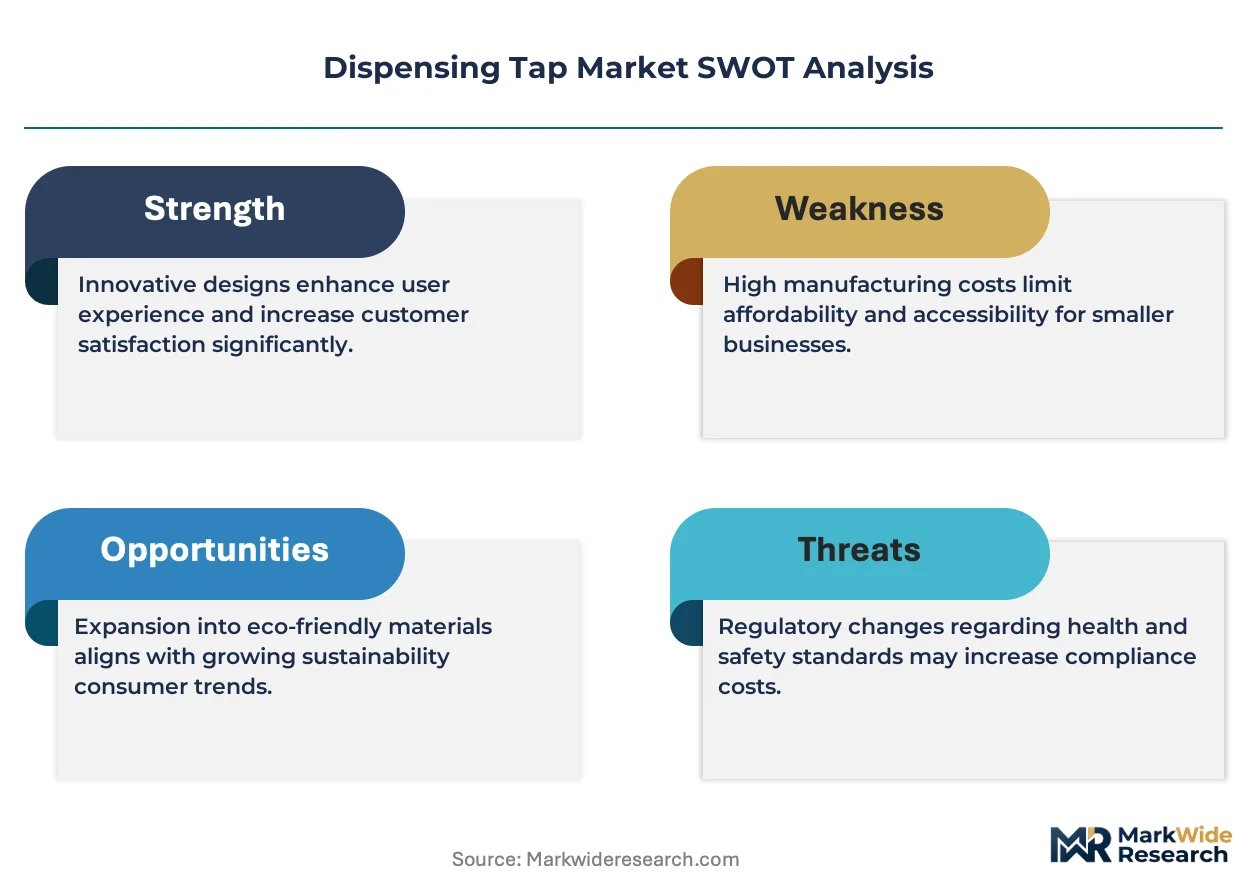
Growth Catalysts
- EMA-aligned hygiene standards:European hospitality operators are retrofitting draft lines with sealed electronic taps to satisfy audit protocols for food-contact surfaces in beverage service environments.
- Stadium and arena renovations:Mass-gathering venues in Germany and the United States are specifying automated dispensing to reduce per-pour labor overhead during peak event windows.
- Copper alloy substitution:Lead-free brass formulations certified under EPA guidelines are unlocking regulatory clearance for residential premium installations previously restricted by plumbing codes.
Market Restraints
- Stainless steel input volatility:Nickel and molybdenum price swings compress fabrication margins for in-house metalworking specialists serving commercial-grade specifications.
- REACH substance restrictions:ECHA evaluations of certain brass alloying elements extend qualification timelines for European component suppliers by twelve to eighteen months.
- Gravity-fed system persistence:Low-cost mechanical taps retain installed base in emerging market microbreweries where pressurized CO2 infrastructure remains capital-prohibitive.
Strategic Opportunities
- India FSSAI compliance pathway:Domestic food safety modernization creates first-mover advantage for exporters certifying stainless steel surface treatments to national contact-material standards.
- Leasing model penetration:Asset-light equipment subscriptions are displacing capital purchase in United Kingdom pub chains seeking to offload maintenance liability.
- Refrigerated dispensing convergence:Integration of tap mechanisms with EU F-Gas Regulation-compliant cooling circuits addresses combined compliance burdens for integrated system vendors.
Industry Challenges
- Multi-jurisdiction certification backlog:Parallel FDA food-contact, EPA lead-free, and state plumbing code approvals fragment product launch sequencing for North American market entry.
- Legacy system integration:Sensor-actuated retrofits require custom mounting adaptations for existing tower configurations in historic European hospitality properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Tap Market |
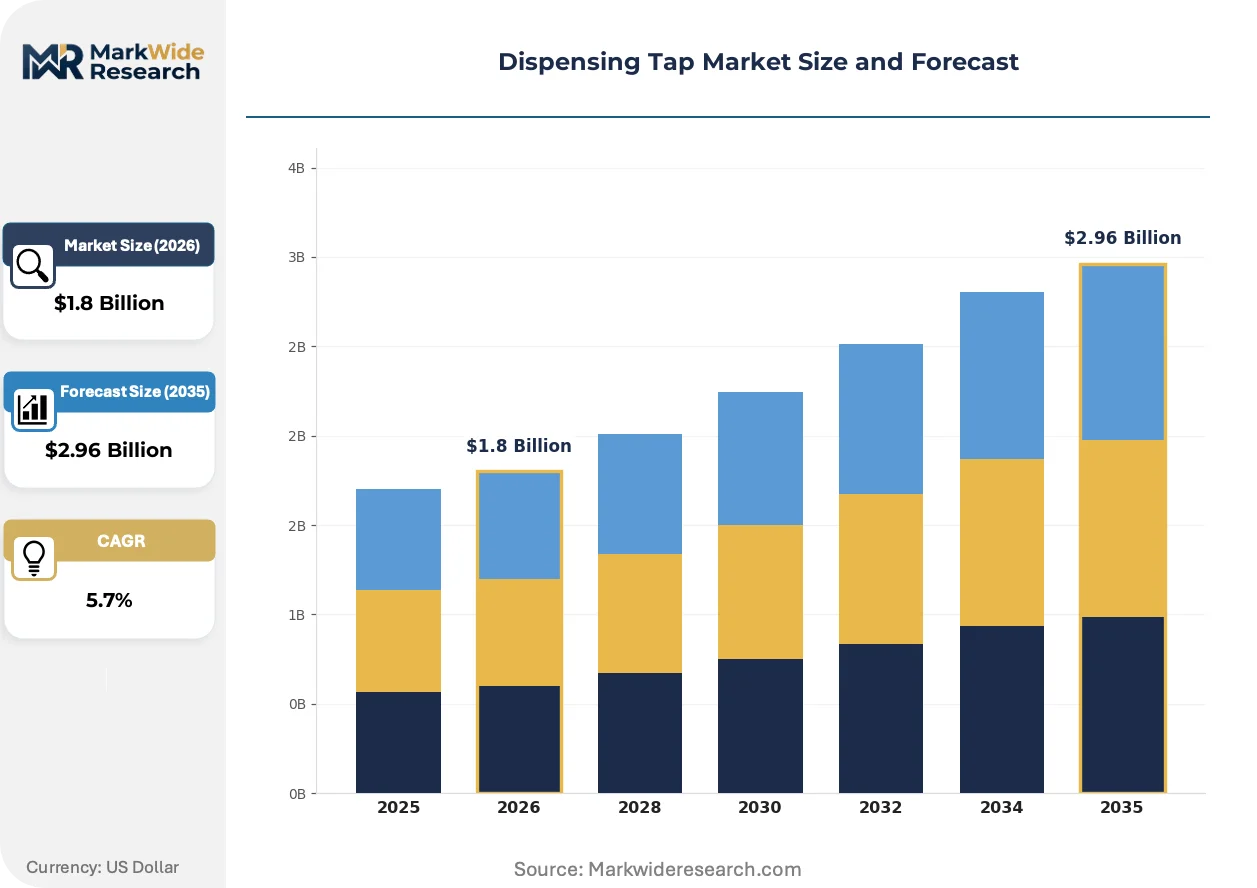
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Taps, Electronic Taps, Pressure Taps, Timer-Driven Taps Material: Stainless Steel, Brass, Plastic, Rubber End User: Residential, Commercial, Industrial, Hospitality Installation Type: Wall-Mounted, Countertop, Free Standing, Integrated |
| Companies Covered | Perlick Corporation, Micro Matic, Alfa Laval, KegWorks, Intertap, McCann's Engineering, Draft Products, Prosstomatic, Taprite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Tap Market Strategic Shifts
Material science advances and regulatory tightening are compressing traditional product lifecycles while opening substitution pathways across price-tier boundaries in commercial and residential applications.
Smart dispensing hardware is hybridizing mechanical reliability with digital telemetry. Stainless steel valve bodies now incorporate flow sensors and wireless connectivity modules that transmit consumption data to inventory management systems. High-volume bars in Germany and the United States are adopting these units to automate reorder triggers and reduce waste from over-pouring. The technology is hybridizing equipment vendor business models from pure hardware sales toward recurring software and data-service revenue streams.
REACH and RoHS compliance deadlines are accelerating material transitions across European supply chains. ECHA substance evaluations have restricted specific brass alloy compositions and plasticizer chemistries used in seal and handle components. Manufacturers serving German draft equipment clusters are reformulating metal specifications and qualifying alternative polymer grades ahead of sunset dates. Premium residential segments absorb cost premiums for compliant materials more readily than price-sensitive commercial replacement markets.
Equipment-as-a-service contracts are restructuring buyer-vendor relationships in United Kingdom and Irish hospitality markets. Pub groups now lease complete dispensing systems inclusive of maintenance, sanitation cycles, and technology upgrades rather than owning depreciating assets. This procurement evolution concentrates purchasing authority at regional chain headquarters and disadvantages smaller fabrication shops lacking capital reserves to underwrite leased fleet deployment.
Dispensing Tap Market Segmentation
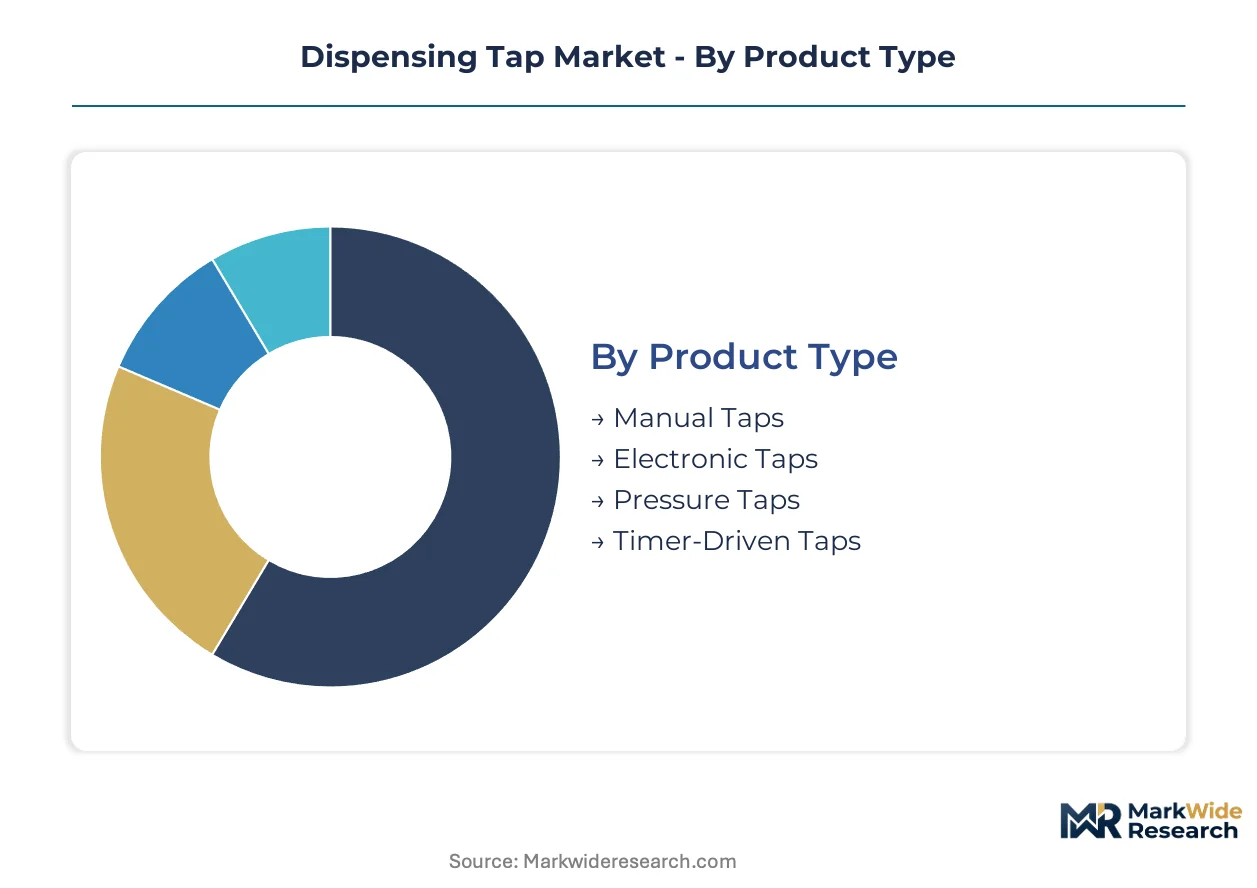
Dispensing tap procurement varies sharply across installation contexts, with hospitality operators prioritizing sanitation audit compliance while residential buyers emphasize tactile aesthetics and thermal conductivity. Material selection and actuation technology choices cascade through after-sales service requirements, spare parts availability, and field technician specialization needs.
Product Type:
After-sales service intensity escalates with electronic complexity, as sensor-actuated mechanisms require specialized calibration protocols and firmware update cycles that manual valve systems avoid.
- Electronic Taps:Sensor-actuated flow control integrates infrared or capacitive triggers with solenoid valves for precise portioning. Stadium concession operators in Germany and the United States deploy these units to reduce per-pour labor during peak event windows, though firmware maintenance and sensor recalibration impose recurring service contracts.
- Manual Taps:Mechanical lever or knob actuation relies on compressed seals and spring-loaded valve seats for flow regulation. Craft breweries in emerging markets retain these units where pressurized CO2 infrastructure remains capital-prohibitive, minimizing service dependency through field-replaceable gaskets.
- Pressure Taps:Direct CO2-driven dispensing for carbonated beverages.
- Timer-Driven Taps:Programmable pour duration for standardized portion control.
Manual taps hold the largest share; momentum sits with electronic variants.
Material:
Cost tier positioning separates specification-grade stainless from premium brass and commodity plastic alternatives, with fabrication margin compression most acute in nickel-alloy supply chains.
- Stainless Steel:Austenitic grades with molybdenum additions deliver corrosion resistance through repeated sanitation cycles in commercial kitchens. EMA-aligned hygiene standards in European hospitality are accelerating specification of electropolished surfaces that reduce bacterial adhesion, though nickel price volatility squeezes in-house metalworking specialists.
- Brass:Lead-free copper-zinc alloys certified under EPA guidelines unlock residential premium installations previously restricted by plumbing codes. REACH substance evaluations on specific alloying elements extend European qualification timelines, concentrating margin in craft brewery niches where thermal conductivity and tactile weight differentiate positioning.
- Plastic:Polymer formulations for cost-sensitive replacement markets.
- Rubber:Elastomer seals and gaskets for compression-fit assemblies.
Stainless steel dominates commercial volume; brass gains fastest in regulatory-cleared residential tiers.
End User:
Application environment dictates pressure ratings, cycle frequency, and aesthetic requirements, with hospitality venues driving specification complexity through integrated cooling and telemetry demands.
- Hospitality:Pubs, bars, and restaurants require high-cycle durability with visual appeal.
- Commercial:Stadium and arena installations specify automated dispensing to reduce labor overhead.
- Residential:Premium kitchen and home bar installations emphasize finish quality.
- Industrial:Bulk liquid handling with chemical compatibility requirements.
Hospitality commands the highest unit value; commercial replacement volume expands most quickly.
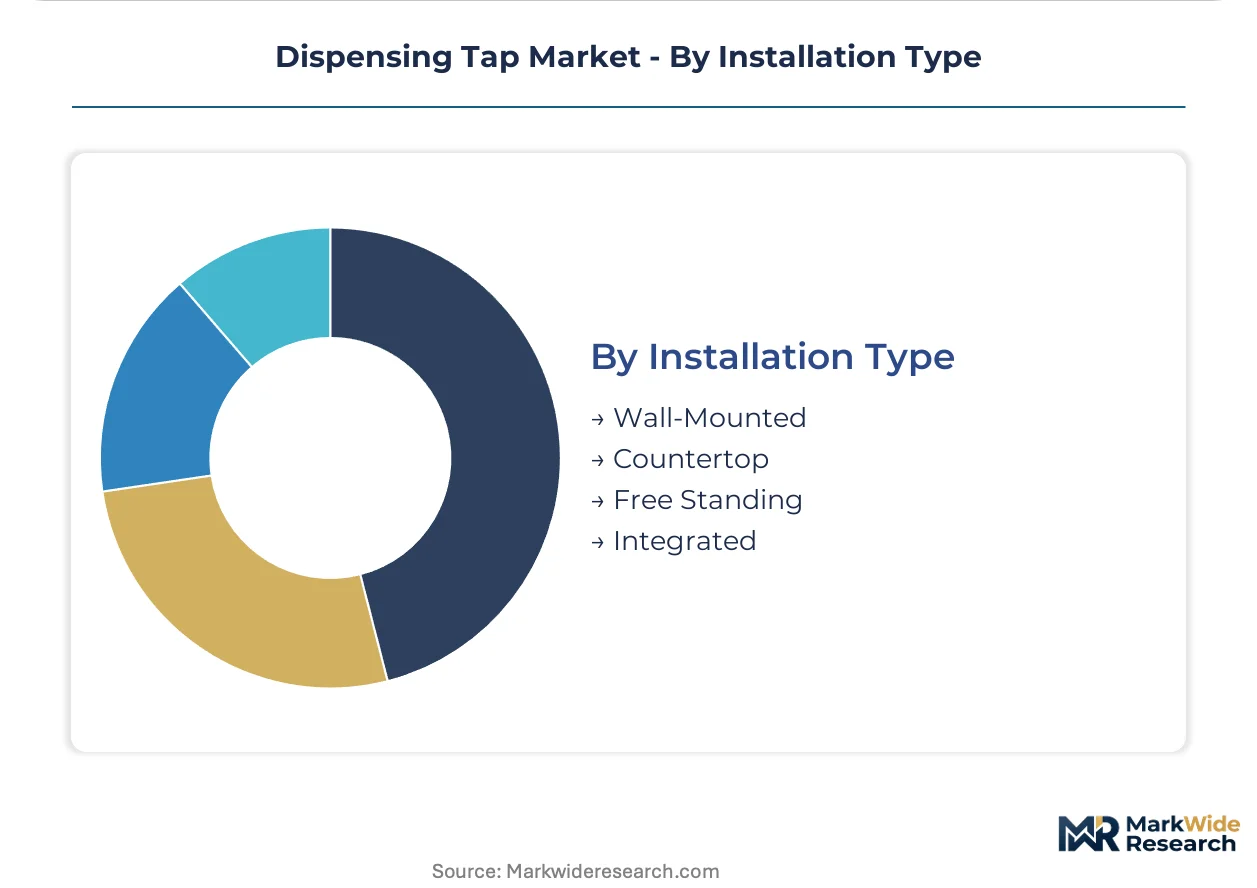
Installation Type:
Customer type fragmentation separates retrofit flexibility from new-build integration, with historic European properties creating legacy tower adaptation challenges for sensor-actuated retrofits.
- Wall-Mounted:Vertical surface attachment for space-constrained service areas.
- Countertop:Freestanding base units for flexible positioning.
- Free Standing:Portable dispensing for event and temporary installations.
- Integrated:Built-in cooling circuit convergence for EU F-Gas Regulation compliance.
Countertop configurations retain broadest applicability; integrated systems are climbing fastest as combined compliance burdens favor bundled system vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers extract pricing premiums through REACH-compliant brass formulations that North American fabricators cannot match under EPA lead-free timelines. This asymmetry concentrates margin capture in Bavarian metalworking clusters while US distributors absorb certification delay costs.
Germany
Draft beverage equipment manufacturing clusters around Munich and Nuremberg drive specification-grade stainless steel demand for automated stadium installations. REACH substance evaluations on brass alloying elements extend ECHA qualification timelines for component suppliers. Bavarian fabricators leverage in-house electropolishing capabilities to satisfy EMA-aligned hygiene standards for sealed electronic tap exports.
United States
Stadium concession operators in Texas and California specify sensor-actuated dispensing to reduce per-pour labor during peak event windows. EPA guidelines on lead-free plumbing components restrict brass alloy selections for residential premium installations. Chicago-area metalworking specialists face margin compression from nickel and molybdenum price volatility in austenitic stainless supply chains.
United Kingdom
Pub chain headquarters in London and Manchester are displacing capital purchase with asset-light equipment subscriptions that offload maintenance liability. EU F-Gas Regulation compliance for refrigerated dispensing systems creates dual certification burdens for integrated system vendors. Midlands-based fabricators struggle to underwrite leased fleet deployment against regional chain procurement consolidation.
India
Microbrewery expansion in Maharashtra and Karnataka sustains gravity-fed mechanical tap demand where pressurized CO2 infrastructure remains capital-prohibitive. FSSAI food safety modernization creates first-mover pathways for exporters certifying stainless steel surface treatments to national contact-material standards. Tamil Nadu component suppliers face qualification delays against evolving domestic hygiene audit protocols.
China
Mass-gathering venue construction in Shanghai and Beijing accelerates automated dispensing specification for labor reduction in high-throughput service environments. GB standards for food-contact metal surfaces diverge from EMA-aligned protocols, fragmenting export qualification pathways. Yangtze River Delta fabricators concentrate on cost-sensitive plastic and rubber seal components for emerging market replacement demand.
Dispensing Tap Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fragmented supply chains serving retrofit and replacement demand. The vendor base separates into three strategic archetypes: stainless steel fabrication houses with in-house metalworking, specialized distribution networks with hospitality venue relationships, and precision engineering firms targeting industrial-scale specifications. Competitive moves concentrate on leasing model penetration and refrigerated dispensing convergence to address combined compliance burdens.
Among European equipment specialists, Micro Matic and Alfa Laval occupy positions at opposite ends of the integration spectrum. Micro Matic exemplifies the distribution-centric archetype through specialized venue relationships across hospitality markets. Alfa Laval represents precision engineering standards for industrial-scale dispensing systems with regulatory compliance capabilities. Perlick Corporation anchors the fabrication-specialist tier through captive stainless steel production capabilities that support sanitation-intensive commercial specifications.
| Leading Market Players |
|---|
| Perlick Corporation |
| Micro Matic |
| Alfa Laval |
| KegWorks |
| Intertap |
| McCann's Engineering |
| Draft Products |
| Prosstomatic |
| Taprite |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Bavarian electropolishing facilities is compressing fabrication margins while elevating configured-to-order premiums for REACH-compliant brass formulations. German metalworking clusters leverage constrained capacity to enforce pricing discipline on North American distributors facing EPA certification delays.
Pricing Analysis
The customization-premium spread between configured-to-order electronic taps and standard manual valves spans three performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with EMA-aligned hygiene standards commanding substantial premiums over basic NSF-rated alternatives. Cost compression in stainless steel commercial tiers is intensifying because nickel and molybdenum volatility erodes in-house metalworking margins. Pub chains in the United Kingdom exhibit highest price sensitivity through asset-light leasing procurement, while German stadium operators absorb premium pricing for automated dispensing with minimal negotiation.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk calculations for brass component flows. Manufacturing gravity centers on Germany, China, and the United States, with Bavarian fabricators controlling premium REACH-compliant alloy formulations. Raw material dependencies draw from nickel-alloy austenitic stainless, lead-free copper-zinc brass, and specialized fluoropolymer seals. Single-source vulnerability concentrates in electropolished surface treatment capacity serving EMA hygiene protocols. Distribution runs through specialized hospitality equipment distributors with venue-level relationships rather than direct OEM-to-operator sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dispensing tap market is cycling through post-renovation demand normalization as stadium construction peaks in Germany and the United States moderate replacement velocity.
For Market Incumbents: Insulate margin position by deepening captive stainless steel fabrication capacity against nickel price volatility. Secure exclusive distribution lockups with United Kingdom pub chains before regional procurement consolidation eliminates smaller fabricators from leasing competition. Vertical integration into electropolishing capabilities satisfies EMA-aligned hygiene standards without third-party qualification delays. For New Entrants and Emerging Players: Build out FSSAI-certified stainless steel surface treatment capabilities for Indian microbrewery expansion where gravity-fed mechanical taps retain installed base. Target Maharashtra and Karnataka state markets with capital-light CO2 infrastructure solutions bundled with basic tap systems. Partner with Tamil Nadu component suppliers navigating domestic hygiene audit protocol evolution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-as-a-service providers with maintenance-inclusive leasing contracts in United Kingdom hospitality markets. Five-to-ten-year viability favors platform integrators with refrigerated dispensing convergence capabilities addressing combined EU F-Gas and REACH compliance burdens. Monitor ECHA substance evaluation timelines as inflection signals for brass alloy formulation disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electropolishing | Bavarian fabricators capture EMA hygiene premium without third-party bottlenecks. |
| Leasing Model Penetration | United Kingdom pub chains offload maintenance liability to concentrate procurement authority. |
| Refrigerated Dispensing Convergence | Integrated system vendors address dual EU F-Gas and REACH compliance burdens. |
| FSSAI Certification Pathway | First-mover exporters secure Indian microbrewery demand ahead of domestic supplier qualification. |
| Sensor-Actuated Retrofit Adaptation | Custom mounting solutions unlock historic European hospitality properties for electronic tap displacement. |
Study Parameters
The analysis maps electronic tap, manual tap, pressure tap, and timer-driven tap sub-sectors, each validated through equipment procurement directors at hospitality chains, aftermarket service technicians, and metalworking specialists. Primary interviews with draft beverage system integrators, regulatory compliance officers, and stainless steel fabrication plant managers combined with secondary validation against SEC filings, ECHA substance restriction databases, customs trade records, and FSSAI notification archives. Bottom-up unit shipment estimates triangulated against top-down value projections from regional equipment clusters.
Assumptions held fixed include REACH substance evaluation timelines, EPA lead-free plumbing code stability, and nickel alloy price volatility patterns, while EMA hygiene standard adoption rates and leasing model penetration varied across sensitivity scenarios. Segmentation dimensions modeled encompass actuation technology, material grade tier, end-use application, and installation type across the projection horizon. CAGRs derived from regression against historic replacement cycles and regulatory compliance-driven upgrade waves, with stadium renovation pipelines and microbrewery expansion trajectories as industry-specific forecast inputs.
Sensitivities concentrate around ECHA brass alloy restriction acceleration, FSSAI protocol evolution in India, and United Kingdom pub chain consolidation velocity. Forecasts reflect assumptions about regulatory timeline stability and commodity price regime continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Ice Maker Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Commercial Griddles and Flat Top Grills Market
Food Service Equipment
Countertop Griddle Market