
 Vitamin B Complex Ingredients Market | 2026-2036
Vitamin B Complex Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin B Complex Ingredients Market Intelligence
Chinese producers' expansion of fermentation capacity is broadening the supply base for several key B vitamins, especially B12. DSM Nutritional Products leverages its extensive R&D portfolio to develop high-purity formulations for pharmaceutical and infant nutrition applications. BASF SE sustains a dominant position in animal nutrition through its large-scale production capabilities and global distribution network. Meanwhile, Zhejiang NHU Co., Ltd. competes aggressively on price and volume, particularly in the Vitamin B5 (Pantothenic Acid) segment.
Vitamin B complex ingredients are a group of eight distinct water-soluble vitamins essential for cellular metabolism, energy production, and overall health. These compounds, including thiamine (B1) and riboflavin (B2), are produced via multi-step chemical synthesis or large-scale microbial fermentation for commercial use. The dietary supplements segment represents the largest end-use application, driven by strong consumer health consciousness. Within product types, Vitamin B3 (Niacin) and Vitamin B5 (Pantothenic Acid) command significant market volume due to their widespread use in both human and animal nutrition.
Regulatory frameworks from the US FDA and the European Food Safety Authority (EFSA) dictate permissible daily intake levels and define the health claim language on product labels. In China, the NMPA enforces strict quality and purity standards for ingredients intended for use in pharmaceutical and fortified food products. Navigating these disparate regional regulations for product formulation, testing, and marketing claims remains a central strategic challenge for ingredient manufacturers.
Market Dynamics
The central dynamic shaping the vitamin B complex ingredients market is the structural tension between high-volume, cost-sensitive production for animal nutrition and the demand for high-purity, specialized grades for pharmaceutical and human dietary supplement applications.
Growth Catalysts
- Mandatory Fortification Programs:Government mandates in developing nations across Asia and Latin America requiring the fortification of staple foods like flour and rice with B vitamins to address public health deficiencies are a significant demand driver.
- Dietary Supplement Expansion:The growing consumer focus on preventative health and wellness in developed economies fuels demand from the dietary supplements sector for targeted formulations addressing energy, cognitive function, and healthy aging.
- Animal Nutrition Demand:Intensifying livestock production, particularly in China, relies on B vitamin supplementation in animal feed to enhance growth rates, improve feed conversion efficiency, and maintain overall herd health.
Market Restraints
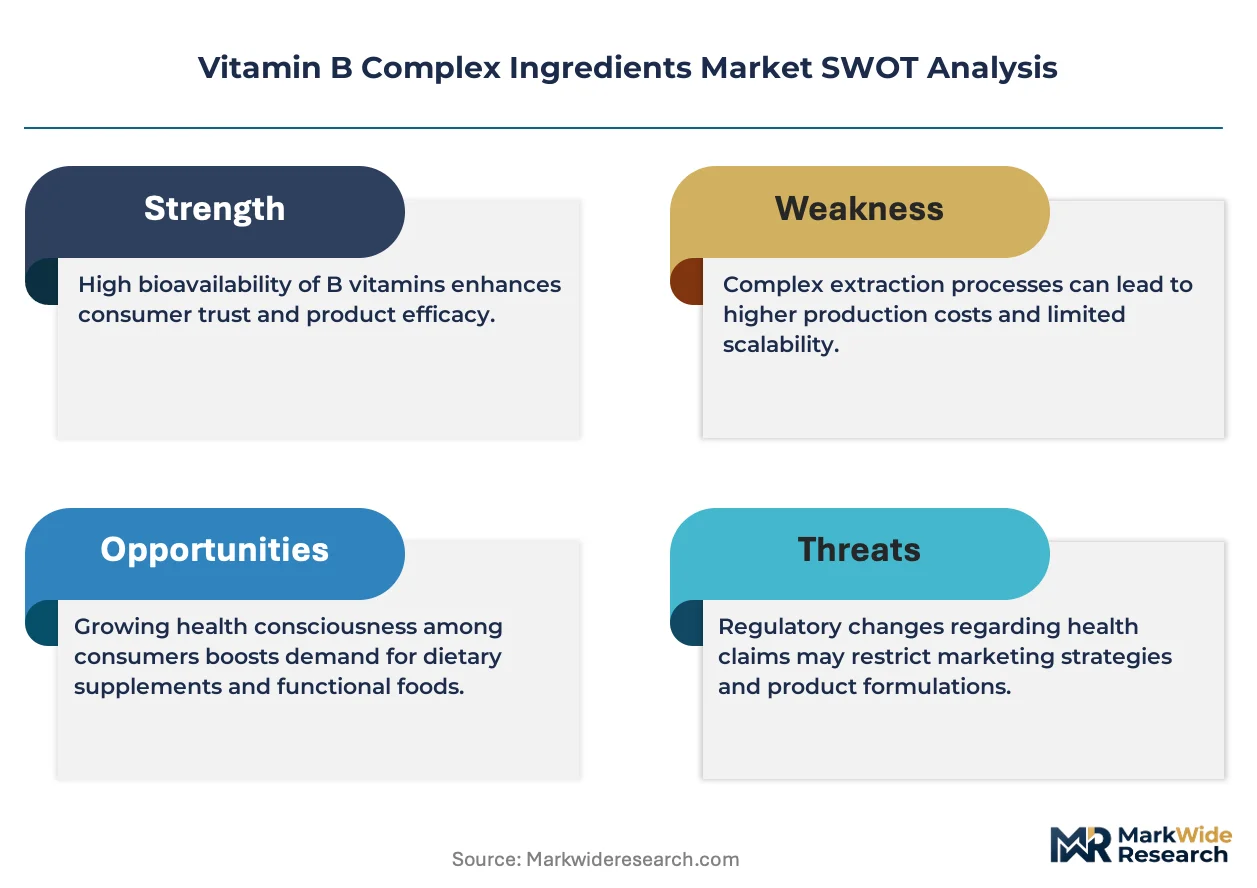
- Input Cost Volatility:Production costs are subject to fluctuations in the price of key raw materials for fermentation and synthesis, including specific chemical precursors, energy, and carbohydrate feedstocks, which can compress manufacturer margins.
- Supply Chain Concentration:A heavy concentration of manufacturing capacity for certain vitamins, such as B12 and B2, in China creates potential for global supply disruptions and price instability due to regional policy changes or logistical bottlenecks.
- Regulatory Divergence:Navigating the disparate and evolving regulatory requirements for purity, labeling, and health claims set by authorities like the US FDA, Europe's EFSA, and China's NMPA increases compliance costs and complexity for global suppliers.
Strategic Opportunities
- Plant-Based Food Fortification:The rapid growth of the plant-based meat and dairy alternatives market presents a major opportunity for fortifying products with B vitamins, particularly B12, to achieve nutritional parity with their animal-derived counterparts.
- Advanced Delivery Systems:Developing and commercializing novel delivery technologies, such as liposomal encapsulation or microencapsulation, can create premium, high-bioavailability ingredients for the discerning nutraceutical and pharmaceutical segments.
- Geographic Expansion:Untapped demand in emerging markets across Southeast Asia and Africa, where rising disposable incomes are correlated with greater spending on health and wellness products, offers significant growth potential for ingredient suppliers.
Industry Challenges
- Quality and Purity Consistency:Ensuring consistent batch-to-batch quality and adherence to the stringent purity standards required for pharmaceutical applications, as enforced by bodies like the NMPA, remains a significant operational hurdle for producers.
- Capital-Intensive Scaling:The substantial capital investment needed to construct and operate large-scale, cGMP-compliant fermentation and chemical synthesis plants creates a high barrier to entry and makes competing on volume challenging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin B Complex Ingredients Market |
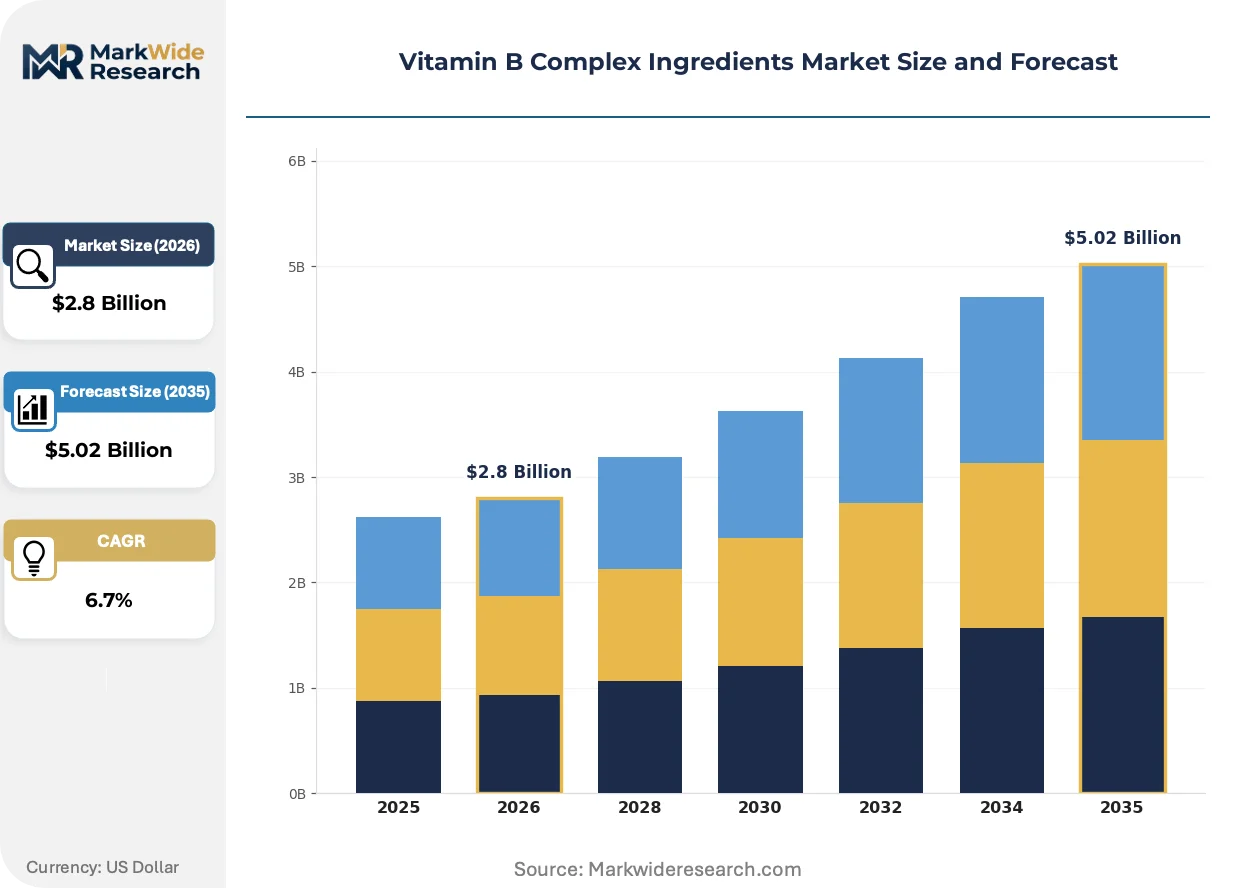
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin B1, Vitamin B2, Vitamin B3, Vitamin B5, Vitamin B6, Vitamin B7 Form: Powder, Capsules, Tablets, Liquid, Gummies, Effervescent End Use Industry: Dietary Supplements, Functional Food, Animal Nutrition, Sports Nutrition, Cosmetics, Pharmaceuticals Distribution Channel: Online Retailers, Pharmacies, Health Stores, Direct Sales, Supermarkets, Specialty Stores |
| Companies Covered | Evonik Industries AG, Zhejiang NHU Co., Ltd., BASF SE, Adisseo, Archer Daniels Midland, DSM Nutritional Products, Kyowa Hakko Bio Co., Ltd., Glanbia plc, Lonza Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin B Complex Ingredients Market Strategic Shifts & Innovations
Innovation in the vitamin B complex ingredients market is driven by a dual focus on bioprocess optimization to control costs in commodity segments and advanced formulation science to create differentiated, high-value products for specialized health applications.
Precision fermentation is a key technological evolution, enabling the production of specific vitamin forms and isomers with exceptional purity. Pharmaceutical and premium nutraceutical formulators are the primary adopters of these high-grade ingredients for applications demanding superior bioavailability and performance. This technology is expanding into the creation of other high-value bio-actives, allowing manufacturers to leverage their core fermentation expertise and capital assets.
European Union policies, particularly the Green Deal and its Farm to Fork Strategy, are introducing new sustainability criteria for food and feed ingredients. This shift compels ingredient producers to provide greater transparency and documentation regarding the environmental footprint of their manufacturing processes, from sourcing to synthesis. The animal nutrition sector is particularly affected, driving procurement towards suppliers who can offer verifiable data on carbon emissions and resource efficiency.
Consumer demand for personalized nutrition is altering purchasing behaviors away from generic, one-size-fits-all multivitamins. This trend favors customized supplement regimens, often informed by health tracking or genetic data, and is disrupting the traditional mass-market retail channel. The shift is most visible in developed markets like the United States, where it fuels the growth of direct-to-consumer (DTC) brands offering tailored vitamin solutions.
Vitamin B Complex Ingredients Market Segmentation
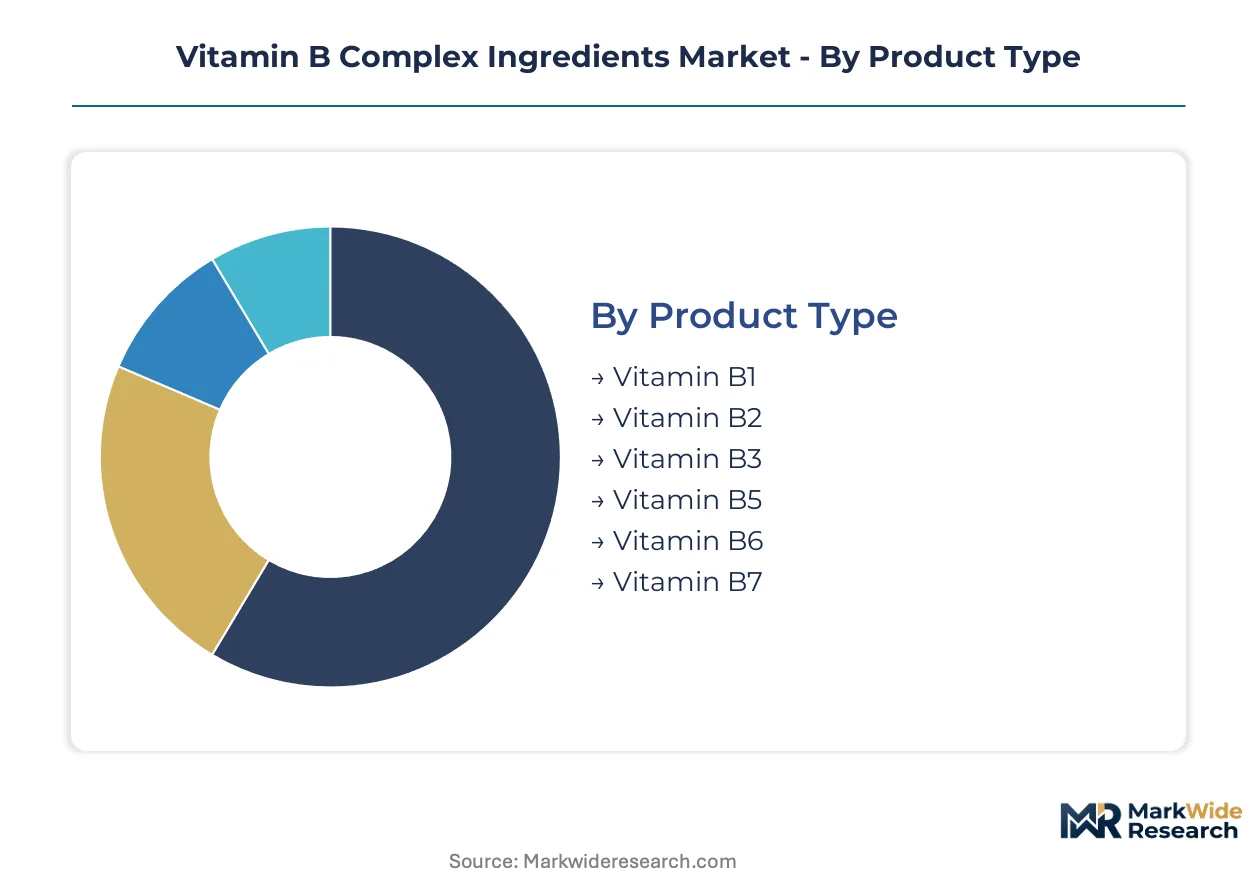
Understanding the distinct segments within the vitamin B complex ingredients market is crucial for ingredient manufacturers and end-product formulators. Each segment presents unique demand characteristics, regulatory considerations, and production requirements, influencing strategic investments and market positioning.
Product Type:
The integration depth of vitamin B complex ingredients varies, with some forms primarily used as standalone supplements and others as components within broader formulations.
- Vitamin B3:Niacin, available as nicotinic acid and nicotinamide, is essential for cellular energy metabolism. Demand for B3 is substantial in both human nutrition for cholesterol management and animal feed to improve growth rates, particularly in poultry and swine operations.
- Vitamin B5:Pantothenic Acid supports fatty acid synthesis and energy production, often supplied as calcium pantothenate. This vitamin commands significant market volume, especially in animal nutrition where it enhances feed conversion efficiency and in dietary supplements for skin health.
- Vitamin B1:Thiamine hydrochloride and mononitrate are crucial for carbohydrate metabolism and nerve function.
- Vitamin B2:Riboflavin, a key coenzyme in energy production, finds widespread use in food fortification and animal feed.
- Vitamin B6:Pyridoxine hydrochloride is vital for amino acid metabolism and neurotransmitter synthesis.
- Vitamin B7:Biotin supports healthy hair, skin, and nails, primarily targeting the cosmetics and dietary supplement sectors.
Volume placements concentrate in Vitamin B3; the faster expansion belongs to Vitamin B7.
Form:
Application flexibility dictates the prevalent forms of vitamin B complex ingredients, ranging from bulk industrial powders to consumer-ready dosage formats.
- Powder:This versatile form offers high purity and ease of incorporation into animal feed, fortified foods, and bulk supplement manufacturing. Its cost-effectiveness and stability make it a preferred choice for large-scale industrial applications.
- Capsules:Providing precise dosing and convenient consumption, capsules are a dominant form in the dietary supplements sector. Encapsulated vitamins protect sensitive ingredients and offer controlled release benefits for human health products.
- Tablets:Compressed solid forms offer durability and extended shelf life for over-the-counter vitamin products.
- Liquid:Liquid formulations facilitate easy absorption and are often preferred for infant nutrition and specialized medical dietary needs.
- Gummies:This palatable form targets pediatric and adult consumers seeking an enjoyable supplement experience.
- Effervescent:Dissolvable tablets provide a quick and refreshing way to consume vitamins, appealing to lifestyle-focused consumers.
The segment for Powder commands substantial revenue due to its widespread utility.
End Use Industry:
Customer type significantly influences ingredient specifications and volumes, with distinct requirements across human and animal applications.
- Dietary Supplements:This sector demands high-purity, often specialized B vitamin forms for targeted health benefits like energy, cognition, and anti-aging. Consumer health consciousness in developed economies fuels this segment's expansion.
- Animal Nutrition:Large-scale livestock production relies heavily on B vitamin supplementation in feed to enhance growth, improve feed conversion efficiency, and maintain herd health. China leads demand in this segment.
- Functional Food:Food manufacturers incorporate B vitamins into products for fortification, addressing public health deficiencies or marketing health benefits.
- Sports Nutrition:Athletes and active individuals seek B vitamins for energy metabolism and recovery, often in higher potency formulations.
- Cosmetics:Certain B vitamins, like biotin and pantothenic acid, are used in skincare and haircare products for their beneficial properties.
- Pharmaceuticals:This segment requires the highest purity and stringent quality standards for B vitamins used in drug formulations and medical treatments.
Demand for Dietary Supplements is robust, while Animal Nutrition demonstrates consistent market penetration.
Distribution Channel:
The maturity of distribution channels varies, from established brick-and-mortar retail to rapidly expanding digital platforms.
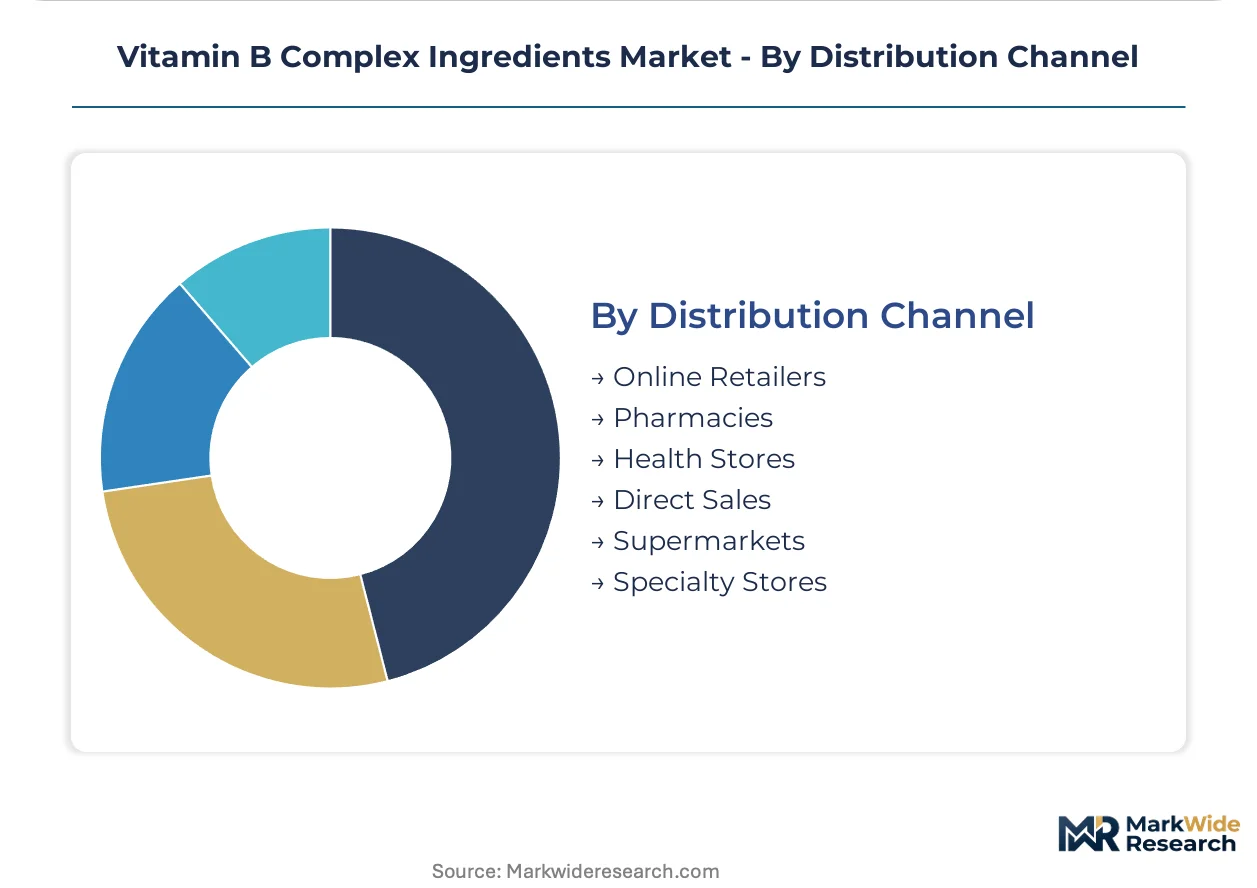
- Online Retailers:E-commerce platforms offer broad product selection and convenience, catering to the growing personalized nutrition trend and direct-to-consumer brands. This channel provides global reach for specialized vitamin products.
- Direct Sales:This channel facilitates bulk procurement by large industrial buyers, including animal feed manufacturers and pharmaceutical companies. It ensures consistent supply and allows for direct negotiation on volume and specifications.
- Pharmacies:Retail pharmacies provide trusted access to dietary supplements and over-the-counter vitamin products.
- Health Stores:Specialty health food stores cater to consumers seeking natural and organic vitamin B complex formulations.
- Supermarkets:Mass-market retail offers accessible and affordable vitamin products to a broad consumer base.
- Specialty Stores:These outlets focus on niche markets like sports nutrition or specific dietary needs, offering curated vitamin selections.
The reach of Online Retailers is expanding quickly, reflecting evolving consumer preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding fermentation capacity for B vitamins, particularly B12, underpins the global supply base. This concentration influences pricing and availability across diverse regional markets. Global demand for these essential nutrients continues to rise, driven by various end-use applications.
China
Intensifying livestock production and mandatory food fortification programs drive substantial demand for B vitamins. The NMPA enforces strict quality and purity standards for ingredients destined for pharmaceutical and fortified food products. Shandong and Zhejiang provinces house major B vitamin production facilities, driving high-volume output for global distribution.
United States
Expanding dietary supplements and functional foods segments represent significant consumption drivers. The US FDA dictates permissible daily intake levels and governs health claim language on product labels. California and the Northeast corridor show high activity in nutraceutical formulation and advanced ingredient R&D.
Germany
Demand centers on high-purity pharmaceutical and premium human nutrition applications. EFSA frameworks influence product formulation, safety assessments, and permissible health claims across the European Union. Chemical parks along the Rhine, including Ludwigshafen, are centers for advanced chemical synthesis and ingredient manufacturing.
India
The expanding dietary supplements sector and government-mandated food fortification programs fuel B vitamin consumption. FSSAI mandates fortification of staple foods to address widespread nutritional deficiencies. States like Gujarat and Maharashtra are developing manufacturing hubs for pharmaceutical ingredients and nutraceuticals.
Brazil
Significant growth occurs in both animal nutrition and human health supplements. ANVISA regulates food and pharmaceutical ingredients, impacting market access and product specifications. São Paulo state leads in feed additive production and nutraceutical manufacturing, reflecting regional agricultural and consumer trends.
Vitamin B Complex Ingredients Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, high-purity applications. This market exhibits a tiered structure, with large-scale chemical manufacturers coexisting with niche ingredient suppliers. Strategic archetypes include diversified chemical giants, dedicated fermentation specialists, and regional volume leaders. Dominant competitive moves involve significant capital investment in capacity expansion and continuous R&D for advanced formulations.
On the scale-driven end, German-based BASF SE exemplifies a global leader in animal nutrition ingredients. Chinese-based Zhejiang NHU Co., Ltd. occupies a position as a high-volume producer, particularly for Vitamin B5. Dutch-based DSM Nutritional Products represents a key player focusing on high-purity formulations for pharmaceutical and infant nutrition applications. These entities collectively anchor production and supply across diverse end-use sectors.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Zhejiang NHU Co., Ltd. |
| BASF SE |
| Adisseo |
| Archer Daniels Midland |
| DSM Nutritional Products |
| Kyowa Hakko Bio Co., Ltd. |
| Glanbia plc |
| Lonza Group AG |
| Others |
Cost & Logistics Intelligence
The bifurcation between high-volume commodity ingredients and specialized, high-purity formulations directly influences both pricing strategies and supply chain configurations within the vitamin B complex ingredients market. This divergence necessitates distinct production methods and distribution channels for different end-use applications.
Pricing Analysis
Service-level bundling often dictates the final price point for vitamin B complex ingredients. The dominant pricing model incorporates contract-based long-term offtake for commodity grades and value-based pricing for specialized applications. Price differentiation drivers include the quality grade and specific regulatory certifications like NMPA or US FDA approval, alongside the volume scale of the order. Pricing pressure stems from input cost volatility for chemical precursors and carbohydrate feedstocks. Animal nutrition manufacturers are highly price-sensitive, while pharmaceutical and infant nutrition segments prioritize purity over cost.
Supply Chain Analysis
Direct sales channels facilitate bulk procurement by large industrial buyers, including animal feed manufacturers and pharmaceutical companies. Geographic supply concentration for many B vitamins, notably B12 and B2, centers heavily in China, with advanced chemical synthesis hubs in Germany. Raw material dependencies include specific chemical precursors, energy, and carbohydrate feedstocks. Single-source vulnerability due to this concentration creates a structural supply chain risk. Online retailers are expanding their reach for specialized, consumer-facing products, reflecting evolving purchasing patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for consolidation, with capital-intensive scaling requirements creating significant barriers for smaller, undercapitalized players.
For Market Incumbents:
Deepen vertical integration into key raw material production to mitigate input cost volatility. Expand fermentation capacity in emerging markets like Southeast Asia to diversify supply and access new demand centers. Invest heavily in R&D for advanced delivery systems to maintain a premium position against price-aggressive competitors. Navigate complex regulatory divergence by establishing regional compliance expertise, particularly for pharmaceutical and infant nutrition applications.
For New Entrants and Emerging Players:
Launch via specialized online retail channels, targeting the personalized nutrition segment in developed economies. Focus on niche white-space opportunities, such as plant-based food fortification with B12, where demand for nutritional parity is high. Develop advanced delivery technologies like microencapsulation to offer differentiated, high-bioavailability ingredients for nutraceuticals. Pursue strategic partnerships with direct-to-consumer brands to accelerate market penetration and build brand recognition.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized fermentation technology providers given the increasing demand for high-purity ingredients. Long-term viability for the market remains strong, driven by global health consciousness and mandatory fortification programs. Target acquisition archetypes include niche manufacturers with proprietary bioprocess optimization or advanced formulation expertise. Adoption rates of precision fermentation technology serve as a key signal to watch for future growth inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Strengthens global supply base for B vitamins, supporting animal nutrition demand. |
| Green Manufacturing Transition | Aligns with EU Green Deal policies, enhancing market access for European customers. |
| Long-term Supply Agreements | Secures stable raw material access and mitigates price volatility for key inputs. |
| Precision Fermentation R&D | Enables production of high-purity B vitamins for premium pharmaceutical applications. |
| Strategic Partnership in India | Expands market penetration into a rapidly growing dietary supplements sector. |
Research Approach
US FDA filings, EFSA reports, and NMPA guidelines formed the secondary backbone for this analysis, supplemented by trade association publications. Primary research involved interviews with R&D directors, procurement leads, regulatory affairs specialists, and product formulators across key geographies. This blend of top-down market sizing and bottom-up validation ensured comprehensive data triangulation.
Historical trendline analysis across the analysis window informed the projection framework, which modeled market evolution by product type, form, end-use industry, and distribution channel. CAGRs were derived through a combination of regression analysis and expert consensus, incorporating industry-specific inputs like consumer health consciousness indices and livestock production volumes. Regional regulatory frameworks also influenced the forecast model.
Raw material price volatility, new regulatory mandates, and shifts in consumer dietary trends are the dominant revision risks for future projections. Forecasts reflect assumptions regarding economic stability and technological advancements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
North America Gelatin Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Cacao Bean Market
Ingredients
Fruit Concentrate Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Europe Phytosterols Market
Ingredients
Sesame Seed Extract Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Grape Seed Extracts Market
Ingredients
Europe Vegetable Oil Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Glucuronolactone Market
Ingredients
Cooking Oil Market
Ingredients
Pea Fiber Market
Ingredients
Murumuru Butter Market