
 Low Fat and Low Cholesterol Diet Foods Market | 2026-2036
Low Fat and Low Cholesterol Diet Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat and Low Cholesterol Diet Foods Market Analytics
Premium clean-label certification is unwinding conventional mass-market positioning across the low fat and low cholesterol diet foods sector. Nestlé leverages its dairy alternative R&D pipeline to sustain European market presence, while Danone anchors its competitive stance through specialized fermentation technologies for reduced-fat yogurt platforms. General Mills competes via in-house whole grain formulation capabilities that control ingredient quality from farm to packaged goods shelf.
Low fat and low cholesterol diet foods constitute formulated consumer products containing less than three grams of fat per serving and under twenty milligrams of cholesterol, manufactured through controlled lipid extraction, enzymatic modification, or plant-base substitution to meet cardiovascular health protocols. Dairy alternatives lead product type margins as oat and almond bases displace traditional skim milk formulations, while online retailers represent the fastest-growing distribution channel as direct-to-subscription models capture weight watcher and medical patient segments with personalized nutrition bundles. Supermarkets remain the volume anchor for health-conscious consumer trial and repeat purchase of snack bars and salad dressings.
FDA nutrition labeling requirements and USDA Dietary Guidelines for Americans shape product formulation thresholds and front-of-pack claim permissibility, compelling reformulation of legacy SKUs to maintain shelf placement. EFSA health claim verifications in Europe and FSSAI fat-content ceilings in India add compliance layers for multinational portfolios. Stakeholders must monitor evolving regulator positions on alternative protein cholesterol equivalency and prepare for tightened sodium-fat interaction rules that could redefine category boundaries.
Market Dynamics
FDA cholesterol labeling thresholds and USDA dietary guideline revisions are compressing formulation timelines, forcing manufacturers to retire legacy fat-based emulsifiers ahead of scheduled reformulation cycles. This regulatory acceleration is redistributing competitive advantage toward firms with captive enzyme modification capabilities.
Growth Catalysts
- USDA Dietary Guidelines for Americans:Updated saturated fat limits are compelling institutional foodservice operators to source certified low-fat dairy alternatives for K-12 and hospital contracts.
- Enzymatic lipid modification:Commercial-scale lipase catalysis now enables fat reduction without texture degradation, opening reformulation pathways for legacy baked goods portfolios.
- Urban medical corridor clustering:Cardiac rehabilitation centers in Houston, Munich, and Singapore are concentrating procurement volume for physician-prescribed low-cholesterol meal plans.
Market Restraints
- Oat protein concentrate supply:Nordic milling capacity constraints are creating input bottlenecks for dairy-alternative formulators dependent on Scandinavian oat fiber streams.
- EFSA health claim substantiation:The European regulator's tightened cholesterol-reduction evidentiary standards are extending product launch timelines by 18-24 months for EU-bound portfolios.
- Full-fat natural positioning:Clean-label competitors leveraging whole-food credentials are capturing perimeter-of-store placement from reduced-fat processed alternatives.
Strategic Opportunities
- FSSAI fat-content ceilings:India's packaged food regulator is mandating progressive fat reduction in edible oils, creating first-mover advantage for enzymatically modified lipid suppliers.
- Direct-to-patient subscription:Cardiology clinic partnerships are enabling recurring revenue models for personalized low-cholesterol meal bundles with biometric monitoring integration.
- Fermentation-derived proteins:Precision biomass cultivation is converging with flavor masking technologies to unlock palatable low-fat meat analog formats for institutional channels.
Industry Challenges
- Cross-functional formulation expertise:The intersection of food chemistry, cardiovascular nutrition science, and sensory engineering is creating acute talent scarcity in product development functions.
- Dual certification timelines:Simultaneous FDA qualified health claim petitions and USDA organic compliance audits are straining regulatory affairs bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat and Low Cholesterol Diet Foods Market |
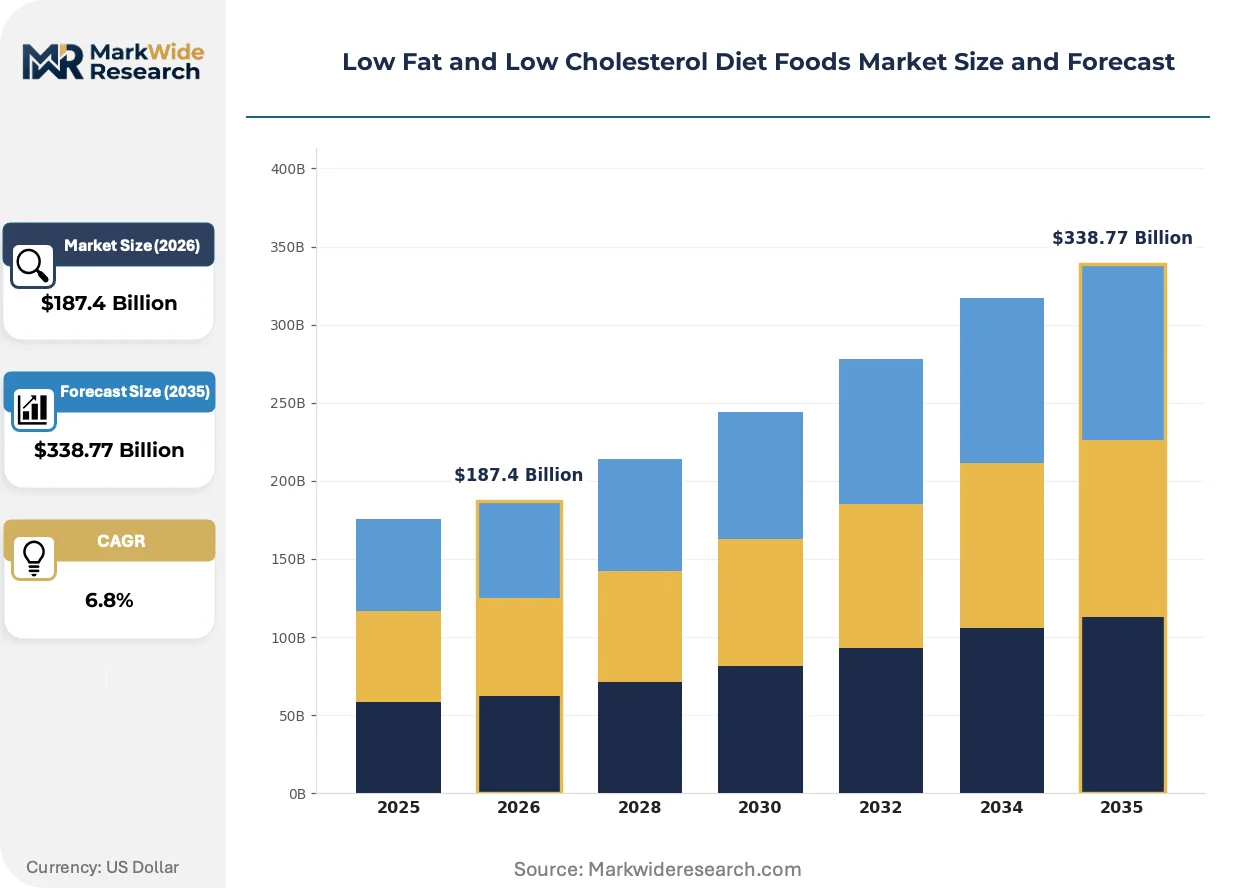
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Bars, Salad Dressings, Dairy Alternatives, Meat Substitutes End User: Health-conscious Consumers, Athletes, Weight Watchers, Medical Patients Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Ingredient Type: Whole Grains, Lean Proteins, Fruits, Vegetables |
| Companies Covered | Nestlé, Danone, The Kraft Heinz Company, General Mills, Kellogg, Cargill, PepsiCo, Unilever, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat and Low Cholesterol Diet Foods Market Evolving Landscape
Clean-label enzyme technologies are displacing chemical extraction methods across fat-reduction processes, while cardiovascular health protocols are migrating from hospital discharge instructions into mainstream retail positioning. These shifts are compressing the gap between clinical nutrition and consumer packaged goods.
Microbial lipase systems derived from Aspergillus oryzae are supplanting traditional solvent-based fat extraction in commercial dairy-alternative production. Weight management subscription services and cardiac rehabilitation programs are adopting these enzyme-treated bases at accelerated procurement cycles. The technology is enabling fat-content claims below 1.5 grams per serving without the chalking defects that previously limited low-fat yogurt acceptance.
EFSA's 2023 revision to cholesterol-related health claim substantiation requirements is mandating human intervention trials for all new product authorizations. European manufacturers are consolidating reformulation pipelines to amortize clinical study costs across multi-country portfolios. Reduced-fat cheese alternatives and spreadable formats face the steepest compliance burden, with several SKUs withdrawn from German and French retail pending dossier resubmission.
Medical patient segments are consolidating purchase authority through registered dietitian gatekeepers rather than direct retail selection. Hospital discharge protocols and insurance-covered nutrition counseling are redirecting volume toward clinically validated low-cholesterol brands, displacing self-directed supermarket trial. This channel migration is most pronounced in US metropolitan areas with integrated health system dominance and in Netherlands pharmacy-retail hybrid formats.
Low Fat and Low Cholesterol Diet Foods Market Segmentation
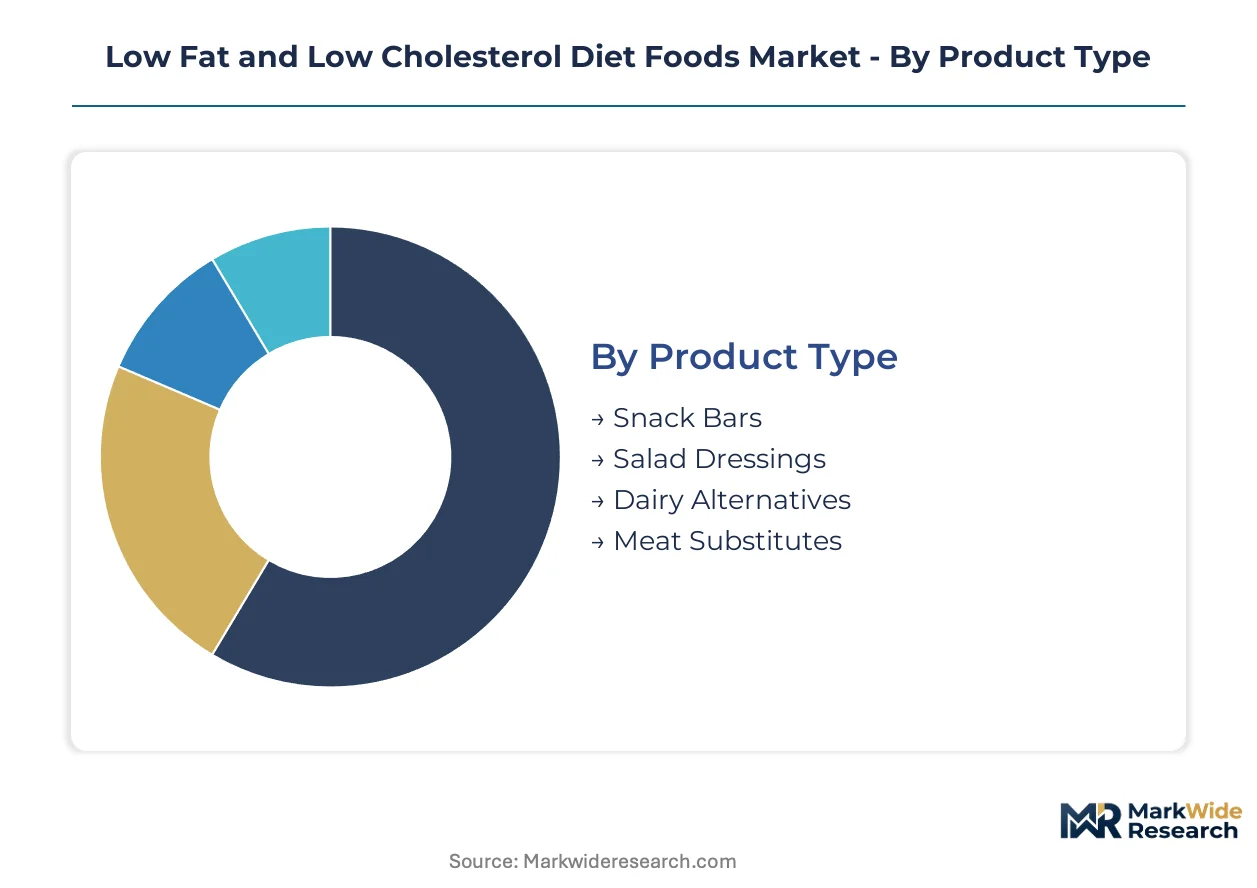
Segmentation in the low fat and low cholesterol diet foods market reveals distinct procurement patterns across clinical, athletic, and lifestyle consumer bases. Channel strategy and ingredient sourcing decisions diverge sharply between supermarket trial purchases and subscription-based medical nutrition programs.
Product Type:
Channel-mix dynamics concentrate dairy alternatives in online subscription bundles while supermarkets anchor snack bar and salad dressing volumes for health-conscious trial buyers.
- Dairy Alternatives:Oat and almond bases manufactured through enzymatic lipid modification now displace traditional skim milk formulations. Hospital discharge protocols in Houston and Munich are concentrating procurement for physician-prescribed meal plans around certified low-fat yogurt platforms.
- Snack Bars:Controlled-fat emulsion systems deliver under three grams per serving through whole grain binding matrices. Weight management programs in Singapore and cardiac rehabilitation centers across Texas medical corridors are adopting these formats at accelerated procurement cycles.
- Salad Dressings:Enzyme-modified oil-in-water emulsions maintain mouthfeel without cholesterol-bearing egg yolk bases.
- Meat Substitutes:Fermentation-derived protein concentrates are converging with flavor masking technologies for institutional channel penetration.
Dairy alternatives dominate installed base. Snack bars are where expansion concentrates.
End User:
Cost tier stratification separates premium clinical validation from mass-market self-directed purchasing, with medical patients commanding subscription price premiums.
- Medical Patients:Cardiology clinic partnerships enable recurring revenue models with biometric monitoring integration. Insurance-covered nutrition counseling in US metropolitan areas redirects volume toward clinically validated brands, displacing supermarket self-selection.
- Health-conscious Consumers:Clean-label competitors leveraging whole-food credentials capture perimeter-of-store placement from reduced-fat processed alternatives in urban retail formats.
- Weight Watchers:Direct-to-subscription models capture this segment with personalized nutrition bundles through online retailer channels.
- Athletes:Lean protein formats cluster around certified low-fat dairy alternatives for performance nutrition protocols.
Medical patients command premium pricing tiers. Health-conscious consumers anchor volume scale.
Distribution Channel:
Volume concentration in supermarkets contrasts with margin expansion in direct-to-patient subscriptions, reshaping fulfillment infrastructure requirements.
- Online Retailers:Direct-to-subscription models with personalized nutrition bundles are climbing the fastest as weight watcher and medical patient segments consolidate purchase authority. Cardiology clinic partnerships enable recurring revenue with biometric monitoring integration.
- Supermarkets:Health-conscious consumer trial and repeat purchase of snack bars and salad dressings maintains volume anchor status. FDA labeling rules and USDA dietary guidelines tighten shelf placement requirements for legacy SKU reformulation.
- Health Food Stores:Specialty positioning for clean-label enzyme technologies and certified organic low-fat formats.
- Specialty Shops:Pharmacy-retail hybrid formats in Netherlands concentrate clinically validated low-cholesterol brand placement.
Supermarkets dominate installed base. Online retailers are where expansion concentrates.
Ingredient Type:
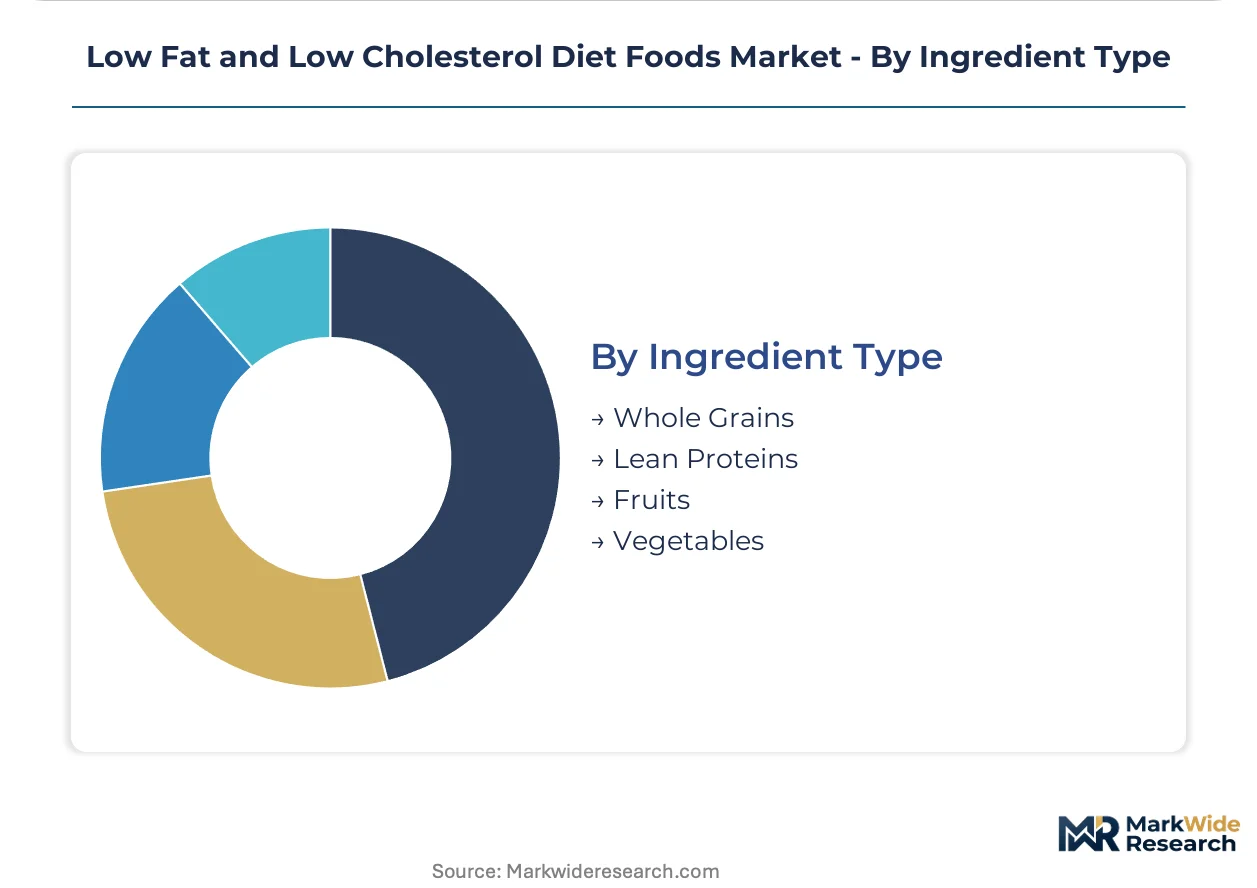
Supply concentration in Nordic oat fiber streams creates input bottlenecks for dairy-alternative formulators, while whole grain capabilities anchor competitive differentiation.
- Whole Grains:In-house formulation capabilities control ingredient quality from farm to packaged goods shelf. General Mills leverages captive supply chains for reduced-fat baked goods portfolios.
- Lean Proteins:Specialized fermentation technologies enable reduced-fat yogurt platforms with fat-content claims below 1.5 grams per serving.
- Fruits:Natural sweetness profiles reduce added sugar requirements in low-fat dessert alternatives.
- Vegetables:Plant-base substitution protocols meet cardiovascular health certification thresholds.
Whole grains dominate installed base. Lean proteins are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for low-fat and low-cholesterol diet foods varies sharply across geographies. Medical patient segments in Germany and Singapore absorb premium pricing for clinically validated formats, while mass-market adoption in India and Mexico remains highly sensitive to unit economics and subsidy availability.
United States
FDA cholesterol labeling thresholds and USDA dietary guideline revisions compress formulation timelines for domestic manufacturers. Hospital discharge protocols in Houston and cardiac rehabilitation centers across Texas medical corridors concentrate procurement volume for physician-prescribed meal plans. Insurance-covered nutrition counseling in US metropolitan areas redirects volume toward clinically validated brands.
Germany
EFSA health claim substantiation requirements extend product launch timelines for EU-bound portfolios. Reduced-fat cheese alternatives face steep compliance burdens, with several SKUs withdrawn from German retail pending dossier resubmission. Munich anchors European demand for certified low-fat yogurt platforms through specialized fermentation technology clusters.
India
FSSAI fat-content ceilings mandate progressive fat reduction in edible oils, creating first-mover advantage for enzymatically modified lipid suppliers. Price-sensitive mass-market consumers drive demand for affordable dairy alternatives in urban centers. Maharashtra and Gujarat host concentrated formulation capacity for plant-base substitution protocols.
Singapore
Urban medical corridor clustering concentrates procurement for physician-prescribed low-cholesterol meal plans. Weight management programs adopt controlled-fat snack bar formats at accelerated procurement cycles. The city-state's integrated health system dominance enables direct-to-patient subscription models with biometric monitoring integration.
Netherlands
Pharmacy-retail hybrid formats concentrate clinically validated low-cholesterol brand placement. EFSA regulatory compliance creates competitive moats for established European portfolios. Amsterdam and Rotterdam anchor distribution infrastructure for enzymatically modified dairy alternatives serving northwest European markets.
Low Fat and Low Cholesterol Diet Foods Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the low-fat and low-cholesterol diet foods sector. The market structure consolidates around multinational packaged goods conglomerates with captive R&D pipelines, while mid-scale specialists compete on clean-label certification and regional formulation expertise. Three archetypes dominate: enzyme modification technology leaders, whole grain supply chain integrators, and dairy alternative fermentation specialists. Competitive moves concentrate on strategic partnerships with cardiology clinics and capacity expansion in enzymatic lipid modification infrastructure.
Within the multinational conglomerate tier, Nestlé and Danone occupy positions anchored to European dairy alternative and reduced-fat yogurt expertise. General Mills exemplifies the supply chain integrator archetype through in-house whole grain formulation capabilities. These three companies represent distinct competitive vectors: Nestlé and Danone through specialized fermentation and R&D scale, General Mills through backward integration into ingredient quality control from farm to shelf.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| The Kraft Heinz Company |
| General Mills |
| Kellogg |
| Cargill |
| PepsiCo |
| Unilever |
| Campbell Soup Company |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for enzymatically modified oat protein concentrates are compressing margin buffers for dairy-alternative formulators while amplifying pricing power among Nordic milling operators with captive supply. This lead-time tension concentrates procurement leverage upstream and forces downstream brands toward long-term offtake commitments or backward integration into Scandinavian fiber streams.
Pricing Analysis
Subscription renewal revenue from direct-to-patient meal bundles drives lifetime value capture beyond initial product sales. Three-tier pricing structure across premium clinical-validation, standard clean-label, and economy mass-market levels separates medical-prescribed formats from self-directed retail alternatives. Pricing pressure stems from EFSA cholesterol-claim substantiation costs extending EU launch timelines. Medical patients absorb premium tiers through insurance-covered nutrition counseling; health-conscious supermarket trial buyers exhibit acute unit-price sensitivity.
Supply Chain Analysis
Inventory concentration in Nordic oat milling, North American whole grain belts, and Indian edible oil processing creates geographic supply anchoring for enzymatically modified lipid inputs. Raw material dependencies center on Scandinavian oat fiber streams, Aspergillus oryzae microbial lipase cultures, and fermentation-derived protein concentrates. Single-source vulnerability in Nordic oat protein concentrate supply exposes formulators to milling capacity bottlenecks. Distribution runs through supermarket volume anchors for trial purchases and online subscription platforms for recurring medical-patient revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiology clinic partnership ecosystems are converging with biometric monitoring interoperability, creating platform-economics inflection where meal-plan personalization and health-data integration lock in patient switching costs.
For Market Incumbents: Fortify enzymatic lipid modification capabilities through captive R&D infrastructure or exclusive supplier agreements to defend against precision-fermentation entrants. Secure shelf placement through accelerated FDA-qualified health claim petitions before USDA dietary guideline revisions tighten thresholds. Channel control through registered dietitian gatekeeper relationships protects against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Cardiac rehabilitation center procurement gaps in Texas medical corridors and Singapore urban clusters offer white-space entry where incumbent coverage remains thin. Target institutional foodservice operators in K-12 and hospital contracting channels where USDA saturated-fat limits are compelling certified low-fat dairy alternative sourcing. Go-to-market through cardiology clinic partnerships with biometric-integrated meal bundles bypasses retail slotting fee barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EFSA health claim substantiation and FDA qualified health claim petition requirements create 18-24 month launch barriers that protect validated incumbent portfolios. Acquisition target archetype: mid-scale enzymatic modification specialists with existing clinical-study dossiers and Nordic oat fiber supply relationships. Signal to watch: FSSAI fat-content ceiling enforcement velocity in Maharashtra and Gujarat formulation clusters as India demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Lipid Modification Capacity Expansion | Captive lipase catalysis infrastructure locks in reformulation pathways for legacy baked goods portfolios under FDA timeline compression. |
| Cardiology Clinic Partnership Development | Direct-to-patient subscription models with biometric monitoring integration capture recurring revenue from insurance-covered nutrition counseling. |
| EFSA Health Claim Dossier Investment | Human intervention trial amortization across multi-country EU portfolios defends shelf placement against withdrawn SKUs in German and French retail. |
| Nordic Oat Fiber Supply Integration | Backward integration into Scandinavian milling capacity mitigates oat protein concentrate input bottlenecks for dairy-alternative formulators. |
| FSSAI Compliance-First Entry | Enzymatically modified lipid supplier positioning under India's progressive fat-reduction mandates captures first-mover advantage in Maharashtra and Gujarat clusters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with product development directors at enzymatic modification technology leaders, regulatory affairs leads navigating FDA and EFSA cholesterol claim pathways, supermarket category buyers for health-conscious trial segments, and cardiac rehabilitation center procurement officers; alongside secondary validation through FDA qualified health claim petition filings, EFSA health claim authorization databases, USDA Dietary Guidelines for Americans revision documentation, and FSSAI packaged food regulation circulars. Bottom-up SKU-level volume triangulation against top-down category spend estimates anchored forecast confidence.
Across the projection horizon, the analytical framework modeled demand by product type, end-user segment, distribution channel, and ingredient sourcing geography. CAGRs were derived from segment-level growth rate reconciliation against macro dietary guideline adoption curves and regulatory compliance timeline assumptions. Industry-specific forecast inputs incorporated enzymatic lipid modification technology diffusion rates and cardiology clinic partnership ecosystem maturation patterns.
Forecasts assume regulatory continuity in FDA cholesterol labeling thresholds, EFSA health claim substantiation requirements, and FSSAI fat-content ceiling enforcement; material policy shifts in any regime would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Tobacco Alternative Gum Market