
 Europe Vegetable Oil Market | 2026-2036
Europe Vegetable Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vegetable Oil Market Foresight
Precision fermentation and enzymatic interesterification is narrowing the performance gap between conventional vegetable oils and tailored lipid formulations. Avril Group leverages its integrated crush-to-refine network across France to secure supply continuity for food and fuel customers. Cargill, Inc. sustains its position through backward integration into Ukrainian and Romanian sunflower seed origination. AAK AB specializes in high-value confectionery fats, competing on technical service rather than commodity tonnage.
Europe vegetable oil comprises triglycerides extracted from oilseeds and fruits through mechanical pressing or solvent extraction, typically refined to free fatty acid levels below 0.05% for food-grade applications. These oils serve as cooking media, food ingredients, and feedstocks for oleochemical and biodiesel production. Rapeseed oil dominates the product type landscape due to EU cultivation subsidies and local crush capacity, while sunflower oil commands premium positioning in Eastern European retail channels. Biodiesel end use draws the fastest structural growth, anchored by renewable fuel mandates that guarantee offtake irrespective of price volatility in food applications.
EMA, EFSA, and REACH collectively govern contaminant limits, novel food approvals, and chemical safety registrations for vegetable oil derivatives entering European commerce. The EU Green Deal's deforestation-free supply chain rules are forcing importers to geolocate every hectare of palm and soy origin, reshaping procurement patterns toward Black Sea and intra-EU sources. Stakeholders must monitor how the CSRD's scope-three disclosure requirements will redistribute margin pools between traders with traceable systems and those reliant on opaque bulk sourcing.
Market Dynamics
EU Green Deal deforestation-free supply chain rules are forcing importers to geolocate every hectare of palm and soy origin, redrawing procurement patterns toward Black Sea and intra-EU crush capacity.
Growth Catalysts
- Renewable Energy Directive blending mandates:Germany's biodiesel quotas guarantee offtake volumes irrespective of food-price volatility, anchoring structural demand for rapeseed methyl ester.
- Precision fermentation:Enzymatic interesterification is narrowing the performance gap between commodity oils and tailored lipid formulations for confectionery applications.
- Black Sea origination:Ukrainian and Romanian sunflower seed crush capacity is expanding as traders pivot from Southeast Asian deforestation-risk supply chains.
Market Restraints
- Input cost volatility:Natural gas prices directly determine solvent extraction economics, compressing refiner margins during energy price spikes.
- Supply concentration risk:Four crushers control over half of EU rapeseed processing capacity, creating bottleneck vulnerability at Rotterdam and Hamburg ports.
- REACH registration friction:Novel lipid derivatives face extended ECHA safety evaluation timelines, delaying commercialization of bio-based oleochemical intermediates.
Strategic Opportunities
- Polish retail channel expansion:Eastern European private-label sunflower oil demand outpaces Western saturation, rewarding crush-to-shelf integrated operators.
- CSRD scope-three disclosure:Mandatory carbon-accounting rules create first-mover advantage for traders with traceable geolocation systems versus opaque bulk sourcing.
- AI-driven oilseed grading:Machine vision and near-infrared spectroscopy convergence enables real-time quality sorting, reducing post-harvest downgrades.
Industry Challenges
- EFSA contaminant compliance:3-MCPD and glycidyl ester limits in refined oils require capital-intensive dual-column deodorization retrofits at legacy facilities.
- Geolocation system integration:Deforestation-free due diligence rules demand ERP overhauls to track farm-level coordinates through multi-tier supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vegetable Oil Market |
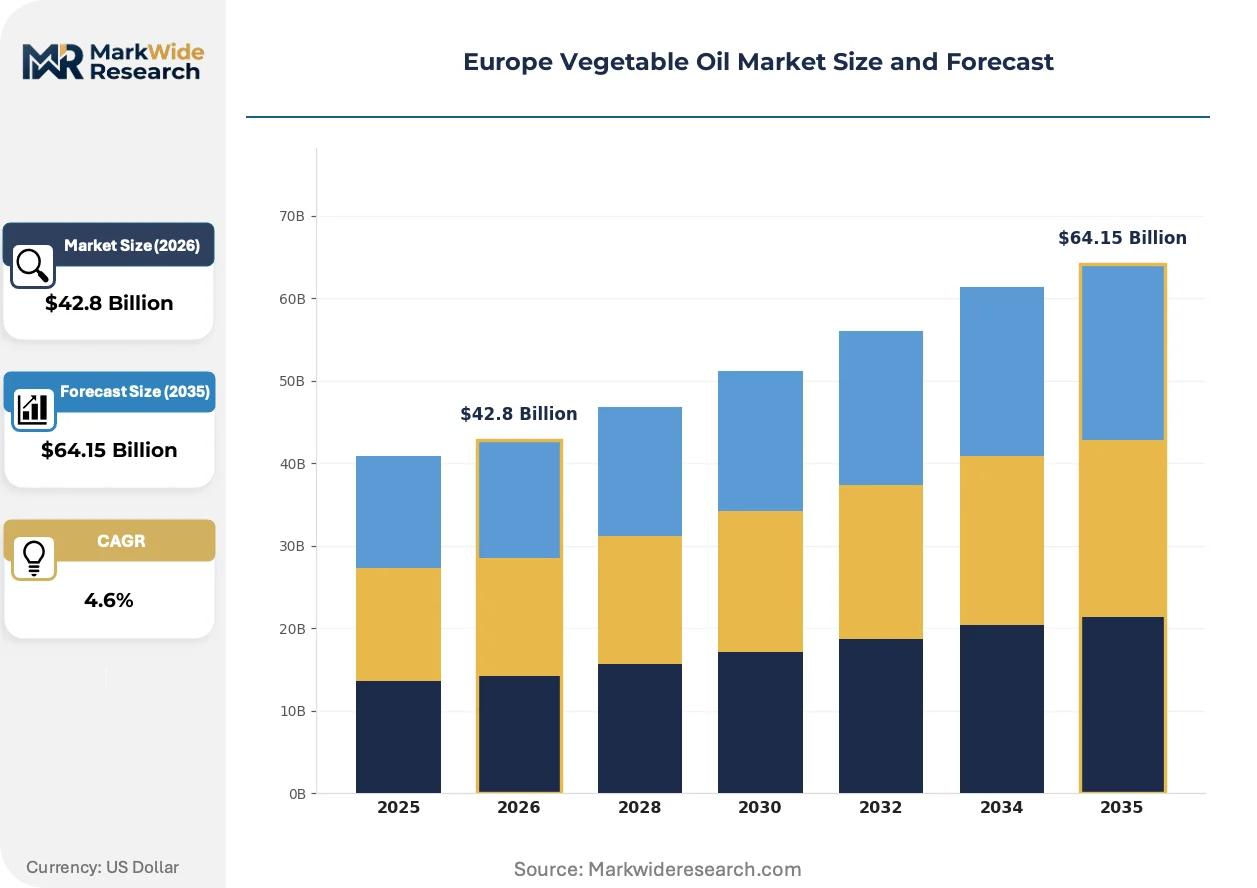
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Sunflower Oil, Palm Oil, Rapeseed Oil End Use Industry: Food Processing, Biodiesel, Cosmetics, Pharmaceuticals Packaging Type: Bulk Containers, Bottles, Pouches, Cans Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale |
| Companies Covered | Wilmar International, Avril Group, Archer Daniels Midland, Fuji Oil Holdings, EFKO Group, Cargill, Inc., Louis Dreyfus Company, AAK AB, Bunge Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vegetable Oil Market Shifts & Advancements
Digital traceability infrastructure and enzymatic processing advances are compressing the gap between commodity bulk oils and performance-specified lipid ingredients.
Enzymatic interesterification is virtualizing the traditional chemical randomization process for structured fats. Margarine and shortening manufacturers across the Netherlands and Belgium are retrofitting batch plants with immobilized lipase reactors. This technology is virtualizing capital allocation away from high-pressure hydrogenation assets toward modular bioreactor skids with lower carbon footprints.
REACH and the EU Green Deal deforestation regulation collectively mandate farm-level geolocation for imported palm and soy derivatives. Compliance departments must now validate coordinates against satellite imagery before customs clearance. German biodiesel blenders are responding by accelerating offtake contracts from certified Black Sea sunflower and domestic rapeseed crush operations.
Clean-label procurement criteria now exclude chemically refined oils from premium retail positioning. French and German food processors are specifying cold-pressed or physically refined alternatives for private-label portfolios. This specification shift concentrates margin capture among crushers with segregated refining lines rather than commodity bulk handlers.
Europe Vegetable Oil Market Segmentation
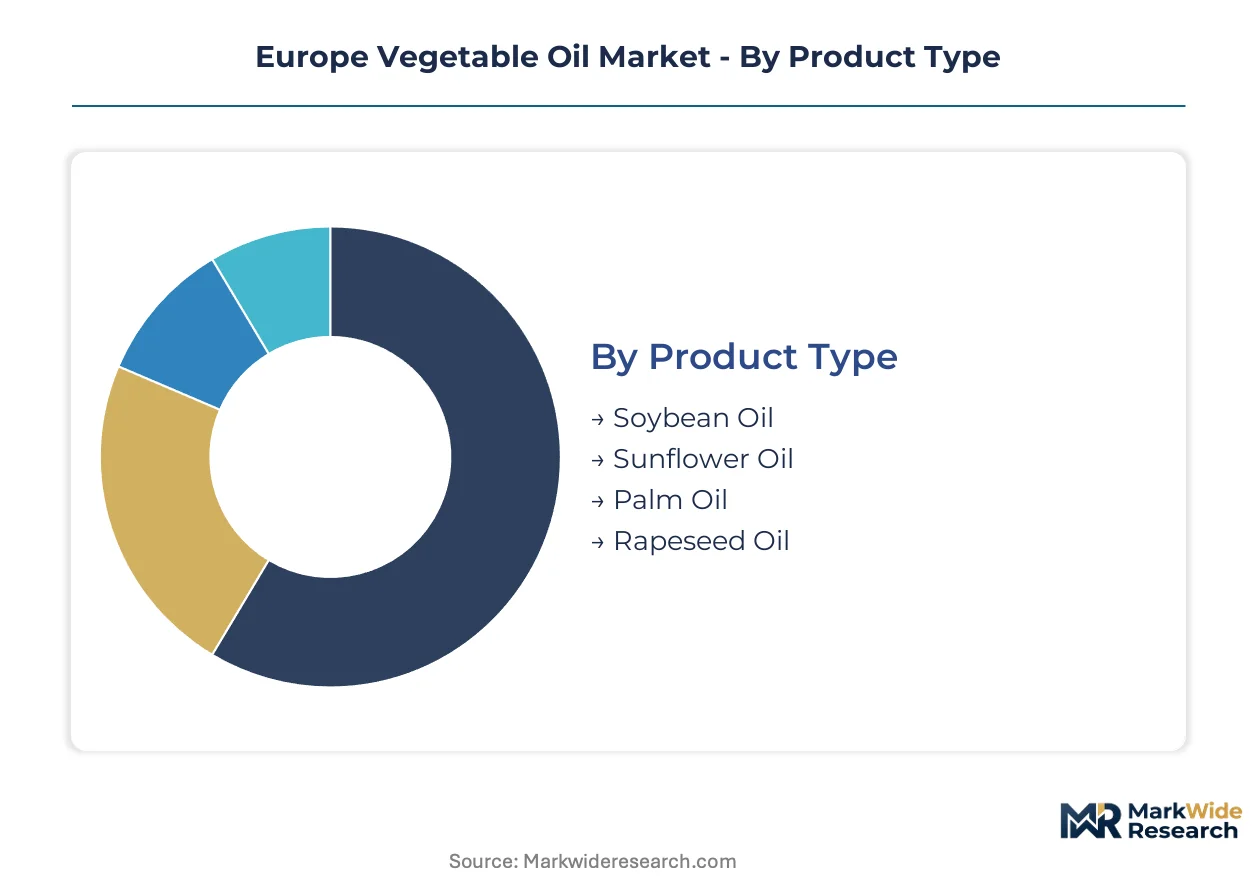
European vegetable oil procurement patterns diverge sharply between food-grade specifications demanding contaminant compliance and fuel-grade offtake governed by blending mandates. Segmentation clarity enables suppliers to align crush capacity with diverging margin structures across these channels.
Product Type:
Refiners configure extraction and refining lines around oilseed fatty acid profiles and end-use viscosity requirements.
- Rapeseed Oil:High erucic acid variants serve industrial lubricant formulations while low erucic grades dominate German and Polish food processing. EU cultivation subsidies sustain crush margins near Rotterdam and Hamburg despite import competition.
- Sunflower Oil:Oleic acid content above 80 percent commands premium positioning in Romanian and Bulgarian retail channels. Black Sea origination is displacing Southeast Asian supply chains under EU Green Deal deforestation compliance rules.
- Soybean Oil:Standard commodity grade for bulk biodiesel feedstock with limited food-grade penetration due to allergen labeling requirements.
- Palm Oil:Fractionated derivatives supply oleochemical intermediates; food applications face reputational headwinds driving substitution.
Established volume favors rapeseed crush infrastructure; emerging adoption favors high-oleic sunflower formulations.
End Use Industry:
Margin capture varies with regulatory intensity and specification stringency across downstream applications.
- Biodiesel:Rapeseed methyl ester dominates German blending pools under Renewable Energy Directive quotas. Refiners secure offtake contracts independent of food-price volatility, anchoring structural demand.
- Food Processing:Cold-pressed and physically refined specifications command clean-label premiums in French and German private-label portfolios. EFSA 3-MCPD limits force capital-intensive deodorization retrofits.
- Cosmetics:High-linoleic sunflower fractions serve emollient formulations; REACH registration delays novel lipid commercialization.
- Pharmaceuticals:Super-refined grades meeting European Pharmacopoeia standards for parenteral emulsions; batch traceability requirements concentrate supply among certified crushers.
Regulatory-guaranteed offtake stabilizes biodiesel margins; premium positioning expands fastest in food processing.
Packaging Type:
Packaging selection tracks channel economics and shelf-life requirements from crush facility to final consumer.
- Bulk Containers:Tanker and flexitank configurations serve biodiesel blenders and industrial food processors with dedicated intake infrastructure at Rotterdam and Constanța.
- Bottles:PET and glass formats dominate Polish and Romanian retail sunflower oil segments; label real estate conveys origin and pressing method claims.
- Pouches:Stand-up bag-in-box gaining share in Eastern European discount channels; reduced material cost offsets shorter shelf stability.
- Cans:Metal packaging preserves quality in ambient distribution; residual presence in traditional Southern European retail.
Operational scale favors bulk logistics; consumer convenience favors pouch and bottle formats.
Distribution Channel:
Channel selection determines working capital intensity and traceability system requirements.
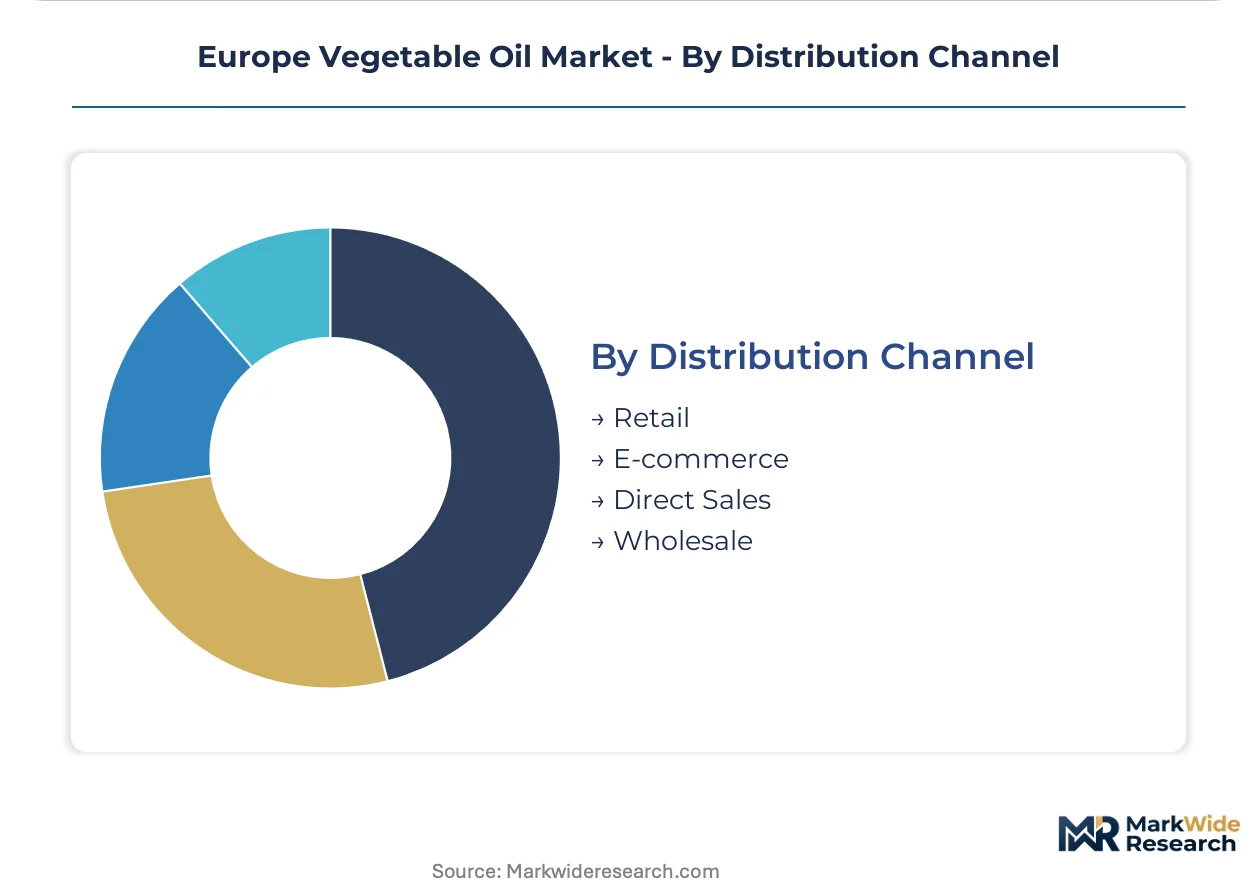
- Wholesale:Volume aggregation through Rotterdam and Hamburg trading houses supplies biodiesel refiners and industrial food manufacturers with standardized specifications.
- Direct Sales:Crush-to-refine operators like Avril Group bypass intermediaries for large food and fuel accounts; CSRD scope-three disclosure requirements reinforce traceability advantages.
- Retail:Supermarket private-label specifications in Germany and France now mandate geolocation documentation for palm and soy derivatives.
- E-commerce:Niche organic and specialty oil platforms serving clean-label consumers; limited volume but high margin per liter.
Procurement efficiency favors wholesale consolidation; compliance differentiation favors direct sales relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's vegetable oil trade flows reflect a structural deficit in oilseed crush capacity relative to biodiesel and food processing demand. Import dependence concentrates on Black Sea sunflower and intra-EU rapeseed origination as deforestation compliance rules redirect procurement away from Southeast Asian palm sources.
Germany
Biodiesel blenders under the Renewable Energy Directive sustain rapeseed methyl ester offtake irrespective of food-price volatility. The Federal Office for Agriculture and Food enforces sustainability certification for biofuel feedstocks. Crush-to-refine clusters along the Rhine corridor at Hamburg and Mannheim process domestic and imported seed for fuel and food channels.
France
Food processors specify cold-pressed and high-oleic formulations for clean-label private-label portfolios. ANSM and EFSA jointly govern contaminant limits for refined oils entering French commerce. Avril Group's integrated network spans crushing plants in Grand Est and Pays de la Loire, securing supply continuity for downstream customers.
Netherlands
Rotterdam serves as Europe's largest vegetable oil transshipment hub, with tank storage and refining infrastructure processing Black Sea and intra-EU flows. REACH registration requirements at ECHA delay novel lipid derivative commercialization. The port's biodiesel blending facilities anchor northwest European renewable fuel supply chains.
Poland
Eastern European retail sunflower oil demand outpaces Western saturation, rewarding crush-to-shelf integrated operators. The country's national agricultural regulator enforces EU Green Deal geolocation requirements for imported feedstocks. Processing clusters in Mazovia and Silesia expand cold-pressing capacity for private-label supermarket chains.
Romania
Black Sea sunflower seed crush capacity is expanding as traders pivot from deforestation-risk supply chains. EFSA contaminant compliance rules govern refined oil exports into Western European food channels. Constanța port infrastructure supports bulk exports to German and Italian biodiesel refiners.
Europe Vegetable Oil Market Competitive Landscape
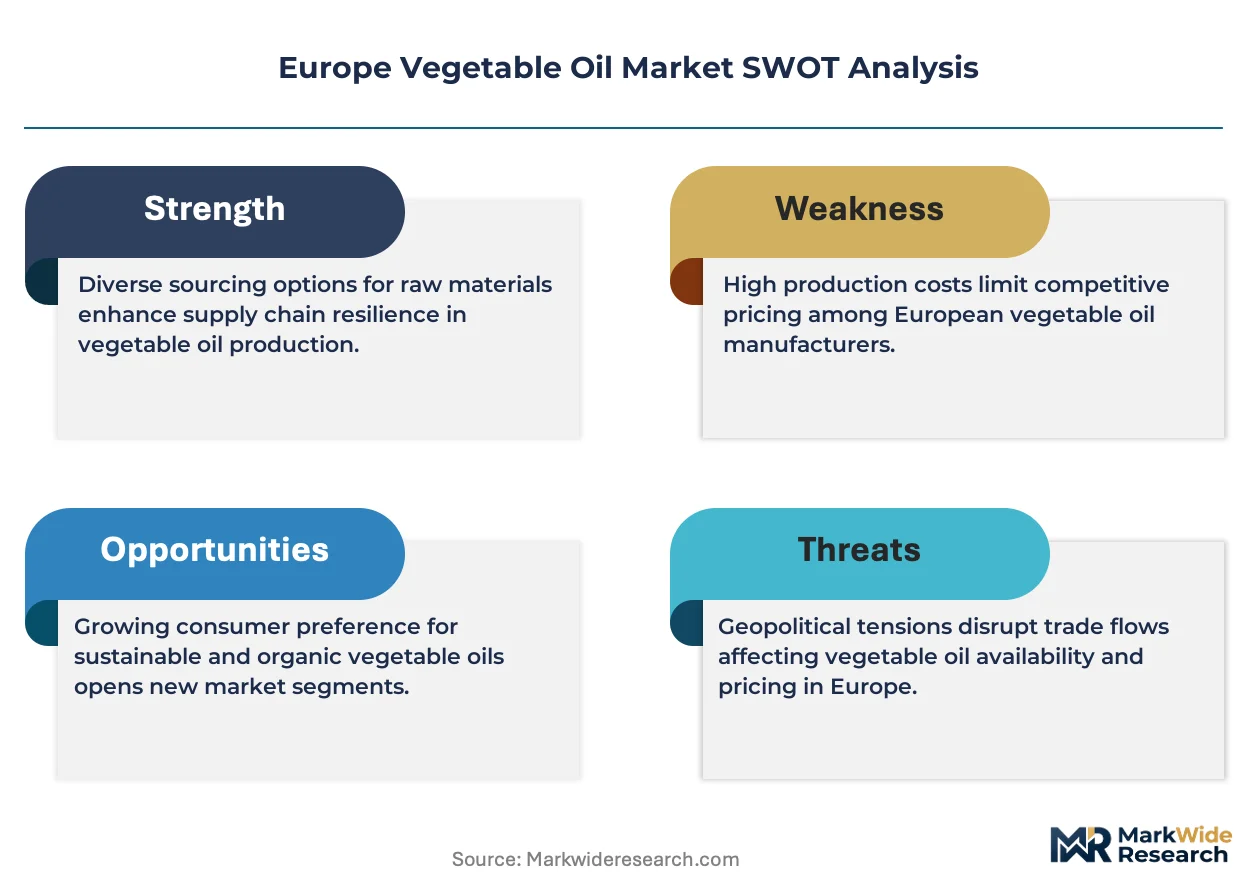
On the supply side, the industry is moderately consolidated around integrated crush-to-refine operators and specialized lipid formulators. Four crushers control over half of EU rapeseed processing capacity, creating bottleneck vulnerability at Rotterdam and Hamburg ports. Strategic archetypes include backward-integrated agricultural conglomerates, technical-service-focused specialty fat suppliers, and commodity trading houses with origination networks. Dominant competitive moves encompass ERP overhauls for geolocation traceability and enzymatic processing retrofits for clean-label product lines.
Among integrated European operators, Avril Group exemplifies the crush-to-refine archetype with captive supply networks across France. Cargill, Inc. represents the global trading house model with upstream control over Black Sea sunflower origination. AAK AB occupies the specialty formulation tier, competing on technical service rather than commodity tonnage. These three anchors illustrate how margin capture concentrates among players with either scale-driven procurement advantages or performance-specified product differentiation.
| Leading Market Players |
|---|
| Wilmar International |
| Avril Group |
| Archer Daniels Midland |
| Fuji Oil Holdings |
| EFKO Group |
| Cargill, Inc. |
| Louis Dreyfus Company |
| AAK AB |
| Bunge Ltd. |
| Others |
Supply & Pricing Matrix
Rotterdam-Hamburg barge freight corridors transmit energy cost volatility directly into crush margin calculations, concentrating pricing power among integrated operators with captive seed supply while forcing merchant refiners into defensive contract structures. This logistics-cost compression amplifies the spread between certified sustainable grades and uncertified bulk oils.
Pricing Analysis
Conventional solvent-extraction grades, enzymatically interesterified formulations, and precision-fermentation lipids occupy distinct pricing tiers based on performance specifications. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and traceability depth. Cold-pressed and high-oleic variants command 15-25% premia over commodity refined grades due to clean-label procurement criteria. Price erosion runs through standard biodiesel feedstock tiers as Black Sea sunflower origination expands crush capacity. Biodiesel blenders show lowest price sensitivity due to Renewable Energy Directive quota guarantees, while private-label food processors negotiate aggressively on volume contracts.
Supply Chain Analysis
Extended payment terms from German biodiesel blenders and supply-chain finance facilities at Rotterdam trading houses are restructuring working capital requirements for Black Sea crushers. Geographic supply concentrates in Ukraine, Romania, and France for sunflower and rapeseed origination. Raw material dependencies center on natural gas for solvent extraction, imported palm kernel for oleochemical feedstocks, and specialized enzymes for interesterification. Single-source vulnerability concentrates at Rotterdam and Hamburg port clusters where four crushers control majority rapeseed processing. Distribution runs through bulk tanker configurations for fuel and industrial channels, with bottle and pouch formats penetrating Eastern European retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's vegetable oil market sits in early-cycle expansion as EU Green Deal deforestation compliance rules force procurement system overhauls, creating first-mover advantage for traceable supply chain operators before mandatory disclosure deadlines tighten.
For Market Incumbents: Build traceability infrastructure moats through ERP geolocation integration that satisfies CSRD scope-three disclosure requirements ahead of competitor compliance timelines. Secure backward integration into Ukrainian and Romanian sunflower origination to displace Southeast Asian deforestation-risk supply chains. Defensive consolidation should target Polish crush-to-shelf operators capturing Eastern European retail growth. Certification investment in segregated cold-pressing lines captures clean-label margin expansion in French and German food processing. For New Entrants and Emerging Players: Build out AI-driven oilseed grading capabilities using machine vision and near-infrared spectroscopy convergence to reduce post-harvest downgrades for mid-size crushers lacking legacy infrastructure. Polish retail sunflower oil channels offer the most penetrable white space as Western European markets saturate. Direct sales relationships with supermarket private-label buyers bypass wholesale margin compression. Go-to-market positioning should emphasize real-time quality verification against EFSA contaminant limits. For Investors and Strategic Acquirers: Crush-to-refine operators with Black Sea origination networks and certified sustainable supply chains represent the highest-conviction acquisition archetype for long-term viability. These assets capture structural demand from biodiesel mandates while positioning for clean-label food processing expansion. Watch for inflection in enzymatic interesterification adoption rates among Dutch and Belgian margarine manufacturers as signal of technology transition timing. Integration of geolocation systems into legacy ERP platforms indicates management quality differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Black Sea Origination | Ukrainian and Romanian sunflower seed crush capacity secures deforestation-compliant supply for EU biodiesel blenders. |
| ERP Geolocation System Deployment | Farm-level coordinate tracking satisfies EU Green Deal due diligence rules before customs clearance. |
| Enzymatic Interesterification Retrofit | Immobilized lipase reactors at Dutch and Belgian plants reduce carbon footprint versus hydrogenation assets. |
| Polish Retail Channel Expansion | Eastern European private-label sunflower oil demand outpaces Western saturation for crush-to-shelf operators. |
| Cold-Pressing Line Segregation | Physically refined capacity captures clean-label premiums in French and German food processing portfolios. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade flow databases, EFSA contaminant limit documentation, EU regulatory filings, and crush capacity registries to establish baseline market structure. Primary interviews engaged crushing plant managers, biodiesel blender procurement leads, food processor R&D directors, and Rotterdam trading house operators across Germany, France, Netherlands, Poland, and Romania. Secondary validation drew from customs data, ECHA REACH registration records, and sustainability certification databases. Bottom-up crush capacity modeling triangulated against top-down demand segmentation across food, fuel, and oleochemical channels.
Forecast inputs include oilseed yield projections, Renewable Energy Directive blending mandate trajectories, natural gas price scenarios affecting extraction economics, and adoption curves for enzymatic processing technologies. Segmentation dimensions encompass product type, end-use industry, packaging format, and distribution channel with regional production hub differentiation. CAGRs derive from regression analysis of historical crush margins against regulatory intensity indicators. Industry-specific inputs center on EU Green Deal implementation timelines and precision fermentation cost reduction curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated agricultural conglomerates or trading houses with origination networks would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Olive Oil Market
Ingredients
Cooking Oil Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Oyster Peptide Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Bouillon Cubes Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Potato Protein Market
Ingredients
Cacao Extracts Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
US Choline Bitartrate Market
Ingredients
Almond Ingredients Market
Ingredients
Textured Milk Protein Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Licorice Root Market