
 Glucuronolactone Market | 2026-2036
Glucuronolactone Market Size, Share, and Industry Trends Forecast 2026-2036
Glucuronolactone Market Analysis
Chinese pharmaceutical-grade production is hardening as domestic fermentation capacity expands. Shandong Fuyuan Bio-Tech leverages vertical integration across glucose feedstock to finished glucuronolactone, securing cost advantages. Jungbunzlauer Suisse AG anchors European supply through its Swiss fermentation facilities and food-grade certification depth. Merck KGaA differentiates via pharmaceutical-grade purity standards and analytical service bundling.
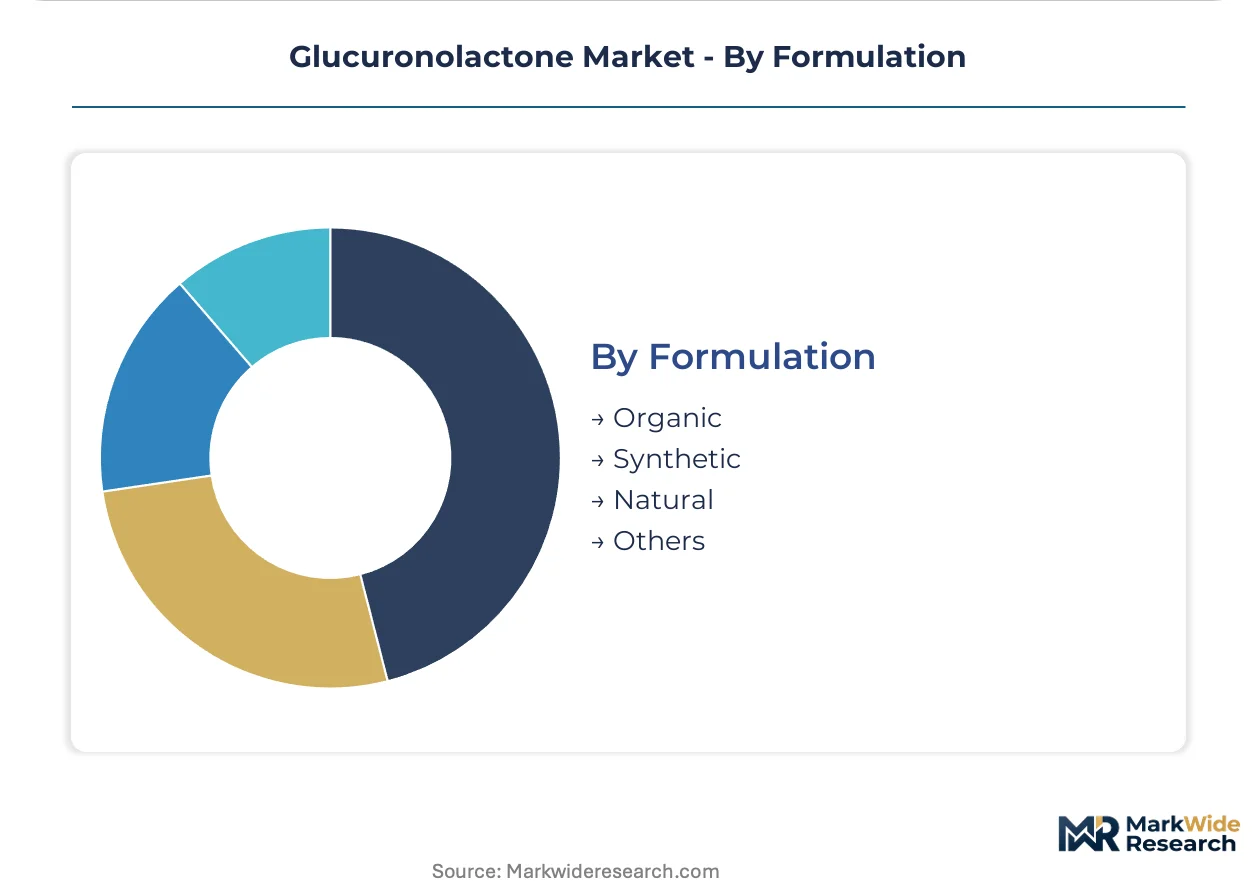
Glucuronolactone is a carbohydrate metabolite formed from glucose oxidation, occurring naturally in connective tissues and commercially produced via microbial fermentation or chemical synthesis with purity grades spanning food to injectable pharmaceutical specifications. Powder formulations dominate current volume due to blending flexibility in beverage and tablet manufacturing, while liquid formats represent the fastest-growing configuration as ready-to-drink functional beverages gain shelf space. Synthetic production occupies the largest share of manufacturing output, though natural and organic formulation segments are expanding as clean-label positioning penetrates nutraceutical channels.
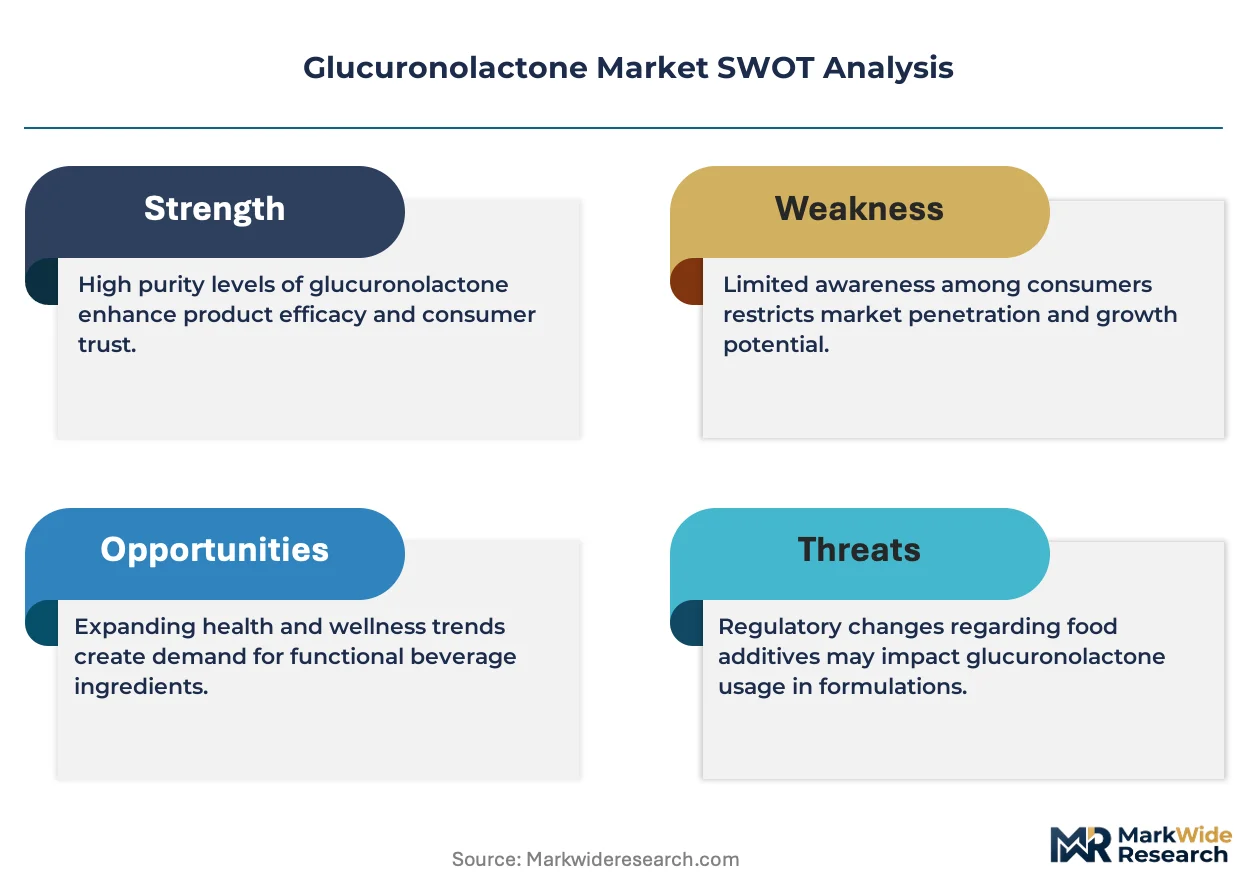
FDA oversight of dietary supplement Good Manufacturing Practices shapes ingredient traceability requirements for US-bound glucuronolactone, while China's NMPA and SAMR enforce dual registration standards for health food additives. The EU's EFSA novel food assessment pathway creates entry barriers for non-traditional glucuronolactone sourcing routes. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP, EP, and ChP standards to anticipate specification-driven procurement shifts.
Market Dynamics
Energy drink manufacturers are consolidating procurement around certified pharmaceutical-grade suppliers as China's NMPA tightens purity standards, compressing margins for uncertified producers while redirecting volume toward vertically integrated fermentation operators.
Growth Catalysts
- Functional beverage diversification:Energy drink portfolios are layering glucuronolactone into pre-workout and hydration subcategories, pulling volume from traditional caffeine-dominant formulations.
- USP pharmacopeial alignment:FDA dietary supplement GMP enforcement is mandating batch-level traceability, advantaging suppliers with in-house analytical capabilities.
- Fermentation yield advances:Microbial production pathways are achieving titer improvements that narrow cost gaps with synthetic chemistry for food-grade material.
Market Restraints
- Glucose feedstock volatility:Corn and wheat-derived glucose prices fluctuate with agricultural commodity cycles, squeezing fermentation-based producers without captive starch processing.
- Shandong supply concentration:China's Shandong province hosts disproportionate fermentation capacity, creating geographic risk for buyers dependent on single-origin pharmaceutical-grade material.
- EFSA novel food barriers:Non-traditional sourcing routes face protracted safety assessments, freezing market entry for alternative production technologies.
Strategic Opportunities
- Clean-label nutraceutical channels:Organic and natural-positioned glucuronolactone variants command price premiums in European health food retail.
- Liquid format ready-to-drink:Beverage brands are specifying pre-dissolved glucuronolactone solutions to eliminate powder-handling complexity at contract manufacturing facilities.
- India PLI scheme leverage:Domestic fermentation infrastructure incentives under India's production-linked incentive framework could anchor South Asian supply.
Industry Challenges
- Pharmacopeial harmonization complexity:Divergent USP, EP, and ChP monograph specifications force dual-validation investments for multi-territory suppliers.
- Specialized fermentation talent scarcity:Industrial microbiology expertise for high-titer glucuronolactone strains concentrates in limited geographic clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucuronolactone Market |
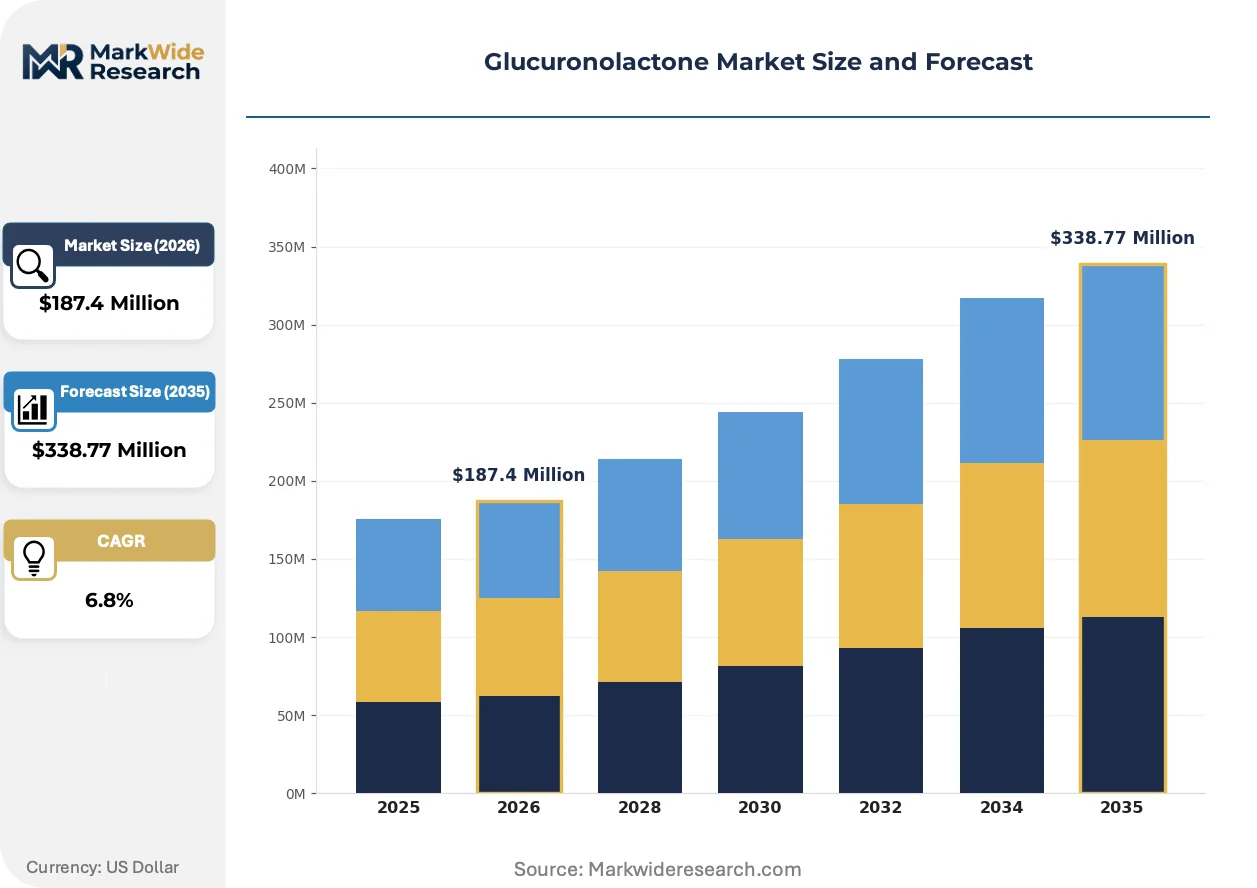
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Tablet, Liquid Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Retail Consumers, Healthcare Providers, Manufacturers, Distributors Formulation: Organic, Synthetic, Natural, Others |
| Companies Covered | Anhui Fubore Pharmaceutical & Chemical Co., Ltd., Hubei Yitai Pharmaceutical Co., Ltd., Shandong Fuyuan Bio-Tech Co., Ltd., Jungbunzlauer Suisse AG, Roquette Frères, Foodchem International Corporation, Shandong Baisheng Biotechnology Co., Ltd., Merck KGaA, Shaoxing Marina Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucuronolactone Market Emerging Trajectories
Production technology and regulatory architecture are simultaneously evolving, with fermentation yield improvements colliding against tightening purity mandates across major import jurisdictions.
Continuous fermentation systems with real-time metabolite monitoring are expanding into commercial-scale glucuronolactone manufacturing. Mid-cap suppliers in Switzerland and Germany are retrofitting batch plants with perfusion bioreactor configurations. This capital-intensive transition is expanding into cost-competitive positioning against traditional chemical synthesis for food-grade specifications.
China's SAMR dual-registration requirement for health food additives is compressing approval timelines for imported glucuronolactone. Domestic producers with existing NMPA certifications are capturing share from exporters awaiting novel food safety dossier reviews. European suppliers are responding by establishing joint-venture fermentation assets within Chinese free-trade zones.
Direct-procurement contracts between energy drink formulators and fermentation operators are displacing traditional distributor intermediaries. Bulk buyers are negotiating multi-year offtake agreements with specified pharmacopeial grade and analytical service bundling. This channel restructuring is most visible in the United States, where pre-workout brand consolidation has concentrated purchasing power among three dominant formulators.
Glucuronolactone Market Segmentation
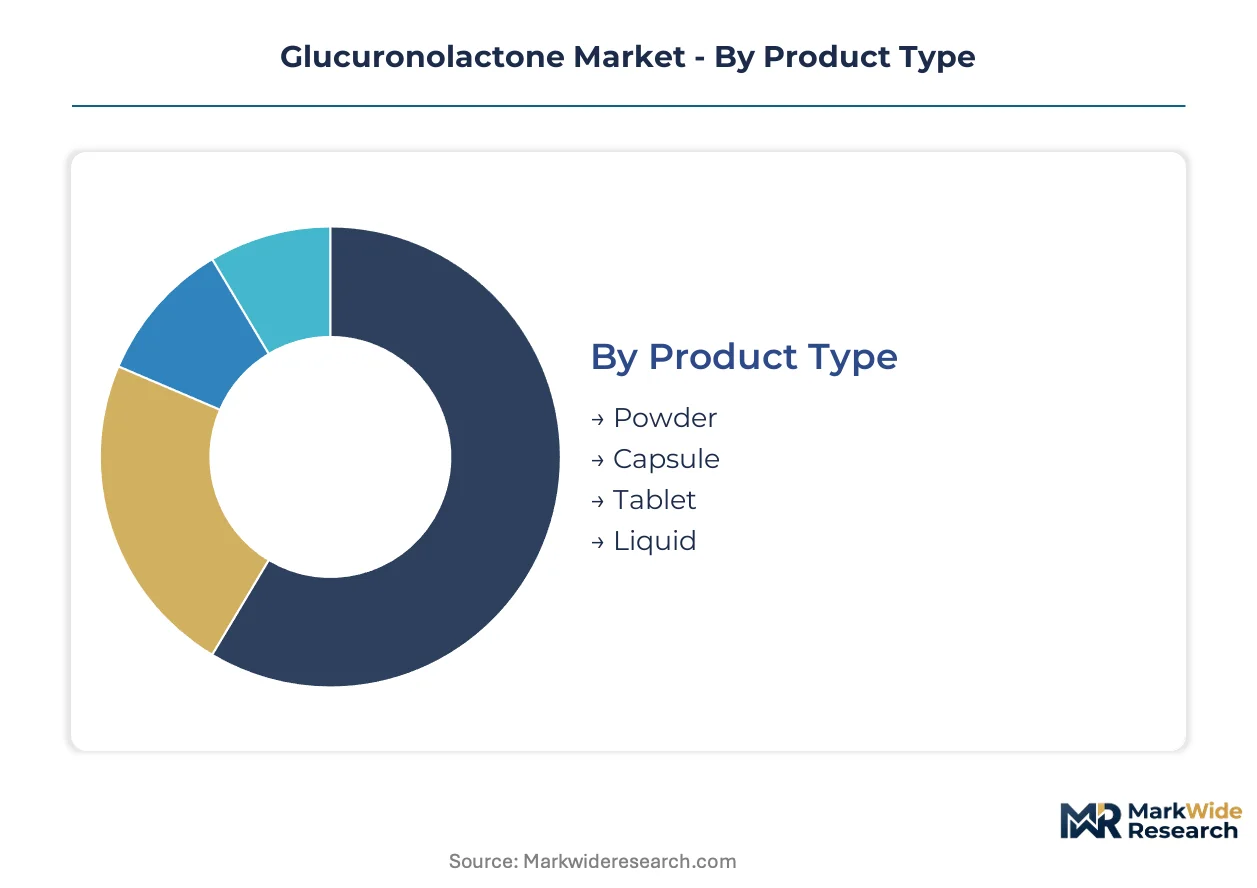
Glucuronolactone procurement patterns diverge sharply across format and purity specifications, with beverage manufacturers driving powder volumes while pharmaceutical buyers enforce stricter monograph compliance. Understanding these segment boundaries reveals where margin pools concentrate and which specifications command premium positioning.
Product Type:
Supply concentration tilts toward powder production due to fermentation infrastructure clustering in Shandong province, where captive glucose processing enables cost-competitive bulk output.
- Powder:Free-flowing crystalline material with standardized mesh sizes for direct compression or dry blending. Demand concentrates among US-based pre-workout and energy drink formulators seeking bulk handling efficiency and extended shelf stability.
- Liquid:Pre-dissolved aqueous solutions or syrups with defined concentration specifications. Ready-to-drink beverage brands in the United States are specifying liquid formats to eliminate powder-handling complexity at contract manufacturing facilities.
- Capsule:Encapsulated single-ingredient or combination products targeting direct-to-consumer nutraceutical channels. Health food retailers in Europe favor capsule formats for clean-label positioning.
- Tablet:Compressed dosage forms with binders and disintegrants for controlled-release applications. Pharmaceutical compounding pharmacies specify tablets for precise unit-dose dispensing.
Today's leader: Powder. Tomorrow's challenger: Liquid.
Application:
Cost tier stratification separates commodity food-grade material from pharmaceutical-grade lots requiring batch-specific analytical certificates.
- Food & Beverage:Energy drinks, functional waters, and sports nutrition products incorporating glucuronolactone as a metabolic cofactor. FDA dietary supplement GMP enforcement is mandating batch-level traceability for US-bound material.
- Pharmaceuticals:Injectable and oral drug formulations requiring USP, EP, or ChP pharmacopeial compliance. China's NMPA tightening of purity standards is redirecting procurement toward certified suppliers with in-house analytical capabilities.
- Cosmetics:Topical formulations leveraging glucuronolactone's humectant and skin-conditioning properties. European personal care brands specify cosmetic-grade material with residual solvent documentation.
- Nutraceuticals:Dietary supplements positioning glucuronolactone for liver support or detoxification claims. EFSA novel food assessment pathways create entry barriers for non-traditional sourcing routes in European health food retail.
Food & Beverage commands current volume. Pharmaceuticals capture expanding margin.
End User:
Volume concentration among manufacturers with captive formulation capabilities is displacing traditional distributor intermediaries.
- Manufacturers:Direct procurement by energy drink, pharmaceutical, and nutraceutical formulators with in-house blending or tableting operations. Bulk buyers are negotiating multi-year offtake agreements with specified pharmacopeial grade and analytical service bundling.
- Distributors:Wholesalers and ingredient traders serving mid-sized formulators without direct fermentation operator relationships. Geographic concentration in China's Shandong province creates single-origin risk for distributor-dependent buyers.
- Retail Consumers:Individual purchasers of finished dietary supplement products through pharmacies, health food stores, and e-commerce channels. Clean-label positioning penetrates this segment fastest in European markets.
- Healthcare Providers:Hospitals, clinics, and compounding pharmacies specifying pharmaceutical-grade material for patient-specific formulations. USP pharmacopeial alignment drives specification rigor in this channel.
Manufacturers dominate procurement scale. Healthcare providers drive purity premiums.
Formulation:
Customer type segmentation separates synthetic chemistry buyers from natural-positioned purchasers commanding clean-label price premiums.
- Synthetic:Chemically synthesized glucuronolactone from glucose oxidation pathways, occupying the largest share of manufacturing output. Synthetic production achieves cost parity with fermentation for food-grade specifications.
- Natural:Material derived from microbial fermentation with non-GMO or fermentation-origin labeling claims. Natural and organic formulation segments are expanding as clean-label positioning penetrates nutraceutical channels.
- Organic:Certified organic production with documented organic glucose feedstock and processing aids. Organic variants command price premiums in European health food retail.
- Others:Emerging production technologies including enzymatic conversion and cell-free synthesis routes. EFSA novel food barriers freeze market entry for alternative production technologies in European jurisdictions.
Synthetic holds volume dominance. Natural gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting glucuronolactone production toward jurisdictions with streamlined fermentation permitting and lower cost-of-compliance structures. China's dual-registration requirements under SAMR and NMPA are pushing pharmaceutical-grade capacity expansion domestically while tightening import pathways. European EFSA novel food assessments create entry friction that advantages established suppliers with dossier precedent.
United States
Pre-workout and energy drink formulators drive volume concentration, with FDA dietary supplement GMP enforcement mandating batch-level traceability for all imported material. Three dominant brand consolidators now negotiate direct multi-year offtake agreements with fermentation operators. Texas and Florida host the largest contract manufacturing clusters for ready-to-drink functional beverages.
China
Shandong province anchors pharmaceutical-grade fermentation capacity through captive glucose processing and vertical integration from feedstock to finished glucuronolactone. NMPA tightening of purity standards is compressing margins for uncertified producers while redirecting procurement toward certified domestic suppliers. Qingdao and Jinan industrial zones concentrate microbial production infrastructure.
Germany
Specialty chemical and pharmaceutical compounders enforce USP and EP pharmacopeial alignment for injectable-grade material. EFSA novel food assessment pathways create procedural delays for non-traditional sourcing routes, freezing market entry for alternative production technologies. Frankfurt-Rhine-Main corridor hosts analytical service bundling capabilities for batch certification.
Switzerland
Jungbunzlauer Suisse AG anchors European food-grade supply through Swiss fermentation facilities with depth of certification for beverage applications. Swissmedic oversight of pharmaceutical intermediates ensures specification rigor for healthcare-bound material. Basel-Zurich corridor concentrates industrial biotechnology expertise for high-titer strain development.
India
Domestic fermentation infrastructure incentives under the PLI scheme could anchor South Asian supply for export-oriented pharmaceutical-grade production. CDSCO registration requirements for active pharmaceutical ingredients shape import substitution strategies. Maharashtra and Gujarat industrial corridors are targeting microbial manufacturing capacity expansion.
Glucuronolactone Market Vendor Landscape
Shandong-based producers anchor the cost-competitive tier; Swiss and German specialists hold the premium certification tier. Market structure tilts toward geographic concentration with limited global dispersion of pharmaceutical-grade capacity. Three archetypes dominate: vertically integrated fermentation operators with captive feedstock, specialty chemical houses with pharmacopeial depth, and regional trading intermediaries without manufacturing assets. Competitive moves center on backward integration into glucose processing and multi-year offtake contracting with beverage formulators.
Within the vertically integrated tier, Shandong Fuyuan Bio-Tech Co., Ltd. and Shandong Baisheng Biotechnology Co., Ltd. exemplify the Chinese fermentation model with provincial clustering advantages. Jungbunzlauer Suisse AG occupies a position representing European food-grade certification depth. Merck KGaA sits within the pharmaceutical-grade archetype with analytical service bundling capabilities. Anhui Fubore Pharmaceutical & Chemical Co., Ltd. and Hubei Yitai Pharmaceutical Co., Ltd. represent mid-scale Chinese producers navigating NMPA compliance transitions.
| Leading Market Players |
|---|
| Anhui Fubore Pharmaceutical & Chemical Co., Ltd. |
| Hubei Yitai Pharmaceutical Co., Ltd. |
| Shandong Fuyuan Bio-Tech Co., Ltd. |
| Jungbunzlauer Suisse AG |
| Roquette Frères |
| Foodchem International Corporation |
| Shandong Baisheng Biotechnology Co., Ltd. |
| Merck KGaA |
| Shaoxing Marina Biotechnology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade certification premiums diverge sharply from commodity food-grade material, compressing margins for uncertified producers in China's Shandong province while rewarding Jungbunzlauer Suisse AG and Merck KGaA with pricing power tied to analytical service bundling and pharmacopeial compliance depth. This bifurcation channels procurement toward vertically integrated fermentation operators with captive glucose processing, leaving distributor-dependent buyers exposed to single-origin supply risk.
Pricing Analysis
Distributor margins of 12-18 percent on pharmaceutical-grade lots are collapsing as direct-to-OEM contracts displace traditional intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified injectable material from food-grade powder and uncertified commodity grades. Cost compression in the standard tier is intensifying because NMPA purity mandates force dual-validation investments. Energy drink formulators show highest price sensitivity, while compounding pharmacies accept premiums for batch-specific analytical certificates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated pre-workout brands in Texas and Florida, bypassing distributor intermediaries entirely. Production gravity centers on China, Switzerland, and Germany, with glucose feedstock sourcing from corn and wheat starch processors in Shandong and the US Midwest. Supply chain risk concentrates in geographic clustering: Shandong province hosts disproportionate fermentation capacity, creating single-origin vulnerability for pharmaceutical-grade procurement. Distribution runs through multi-year offtake agreements with specified pharmacopeial grade rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as China's NMPA and SAMR dual-registration requirements redirect procurement toward certified suppliers with in-house analytical capabilities, elevating premium-grade material from cost center to competitive differentiator.
For Market Incumbents: Deploy backward integration into captive glucose processing to defend margin position against feedstock volatility. Shandong Fuyuan Bio-Tech's vertical model from starch to finished glucuronolactone exemplifies this lever. Incumbents must also deepen pharmacopeial certification depth across USP, EP, and ChP standards to preempt procurement shifts as harmonization pressure builds. For New Entrants and Emerging Players: Launch via liquid-format ready-to-drink specifications to bypass powder-handling infrastructure requirements at established contract manufacturers. The most penetrable white space sits in organic-certified production for European health food retail, where clean-label positioning commands price premiums unavailable in commodity synthetic supply. A fermentation-origin labeling claim with non-GMO documentation unlocks this channel. For Investors and Strategic Acquirers: Consolidation pressure builds where NMPA compliance transitions strand mid-scale Chinese producers without certification depth. Long-term viability favors vertically integrated fermentation operators with captive feedstock and multi-territory pharmacopeial dossiers. The signal to watch is CDSCO registration progress under India's PLI scheme, which could anchor South Asian supply and redirect regional procurement gravity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Processing | Shandong Fuyuan's captive starch processing secures cost advantages against agricultural commodity cycles. |
| Pharmacopeial Certification Expansion | USP, EP, and ChP alignment preempts specification-driven procurement shifts as NMPA tightens purity standards. |
| Liquid Format Production Capacity | Pre-dissolved solutions eliminate powder-handling complexity for ready-to-drink beverage contract manufacturers. |
| Organic Certification Investment | European health food retail channels command price premiums for fermentation-origin clean-label positioning. |
| Multi-Year Offtake Contracting | Direct procurement agreements with energy drink formulators displace distributor intermediaries and stabilize volume. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, procurement leads at energy drink OEMs, pharmaceutical compounding pharmacists, and regulatory affairs specialists with secondary validation against NMPA registration databases, USP pharmacopeial monographs, customs trade flows, and SEC filings from listed chemical producers. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Historical reference periods anchored the projection horizon to observed fermentation yield improvements and regulatory compliance cost trajectories. Segmentation dimensions modeled include product format, purity grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from slope analysis of segment-specific growth trajectories, incorporating titer improvement curves in microbial production and NMPA approval timeline compression as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under glucose feedstock price volatility and pharmacopeial harmonization delays. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Corn Starch Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Bay Leaf Oil Market
Ingredients
Murumuru Butter Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Non Meat Ingredients Market
Ingredients
Food Minerals Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Fermentation Ingredient Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Jasmine Extract Market
Ingredients
Elecampane Root Market
Ingredients
Functional Flours Market
Ingredients
South America Vegetable Oil Market
Ingredients
Omega 6 Market