
 Cacao Bean Market | 2026-2036
Cacao Bean Market Size, Share, and Industry Trends Forecast 2026-2036
Cacao Bean Market Insights
Bean-to-bar processing revenue is fragmenting as artisan makers bypass commodity intermediaries. Barry Callebaut leverages industrial-scale grinding capacity across four continents to sustain volume leadership. Cargill anchors its position through direct farmer financing programs in West Africa. Olam International differentiates via digital traceability platforms that map farm-level provenance for premium buyers.
Cacao beans are the fermented and dried seeds of Theobroma cacao, typically containing 50-57% cocoa butter by weight and processed through roasting, winnowing, and grinding into liquor, powder, or butter for chocolate manufacturing and food applications. Cacao butter commands the highest margin pool among product types due to its irreplaceable melting profile in confectionery, while cacao nibs represent the fastest-growing format as clean-label ingredient demand expands across nutraceuticals and baked goods. Confectionery remains the dominant end-use channel, though nutraceuticals is gaining traction as polyphenol-rich cacao extracts enter functional food formulations.
The EU Deforestation Regulation and EUDR due-diligence framework compel exporters to geolocate every farm plot, reshaping supply chain documentation costs and market access conditions for origin countries. FDA food safety standards and FSMA preventive controls govern import thresholds for heavy metals and Salmonella in the United States, forcing processors to upgrade sorting and sterilization infrastructure. Stakeholders must decide whether to absorb compliance costs or reconfigure origin sourcing toward jurisdictions with established traceability systems.
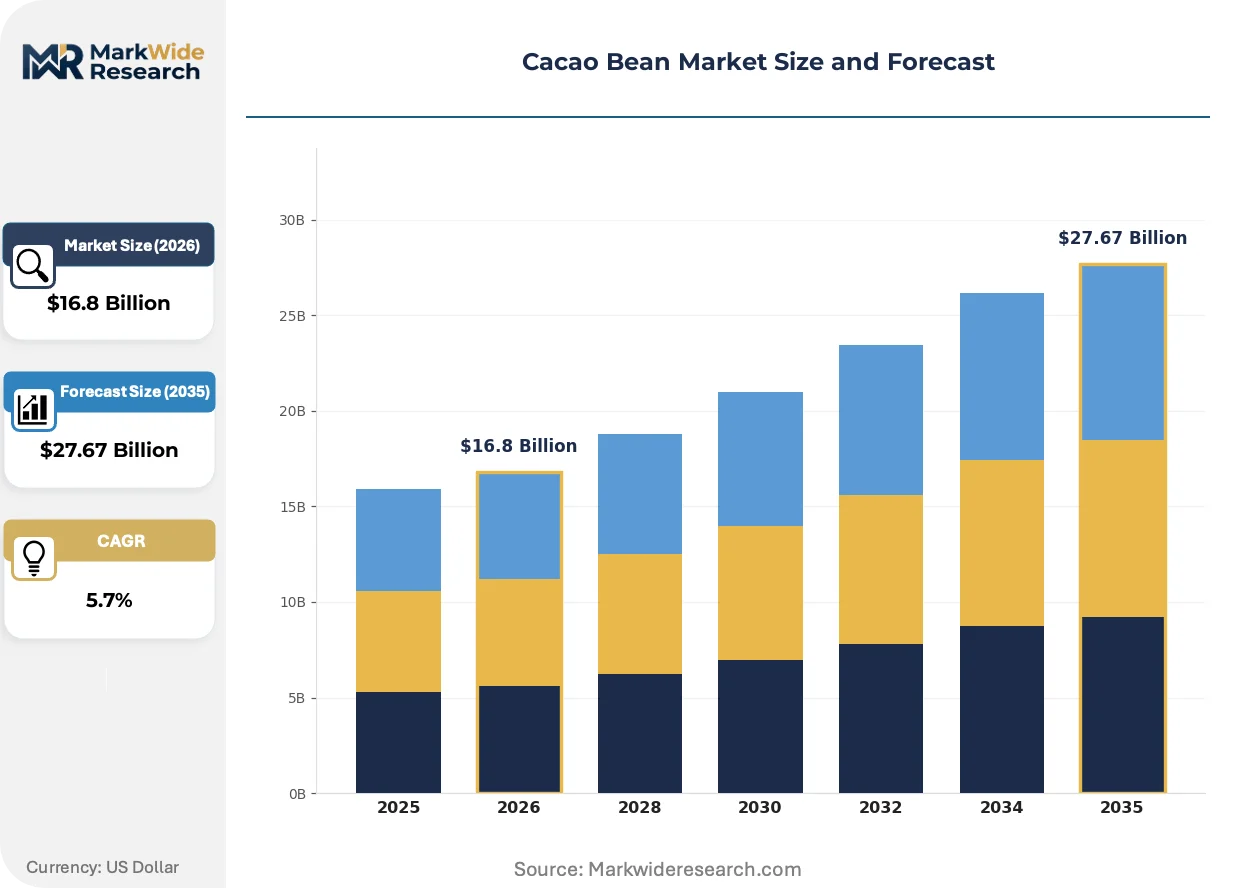
Market Dynamics
The EU Deforestation Regulation (EUDR) is forcing a fundamental reconfiguration of traceability infrastructure, compelling exporters to geolocate every farm plot and document supply chain provenance or face market exclusion from the world's largest chocolate-consuming bloc.
Growth Catalysts
- Regulatory Compliance Mandates:EUDR due-diligence requirements are accelerating investment in farm-level mapping systems and digital traceability platforms across West African and Latin American origins.
- Bean-to-Bar Proliferation:Artisan chocolate makers in Western Europe are bypassing commodity intermediaries to source single-origin beans directly, fragmenting traditional procurement hierarchies and creating premium price tiers.
- Clean-Label Ingredient Demand:Cacao nibs are displacing synthetic flavor additives in nutraceuticals and baked goods as manufacturers seek polyphenol-rich, minimally processed inputs.
Market Restraints
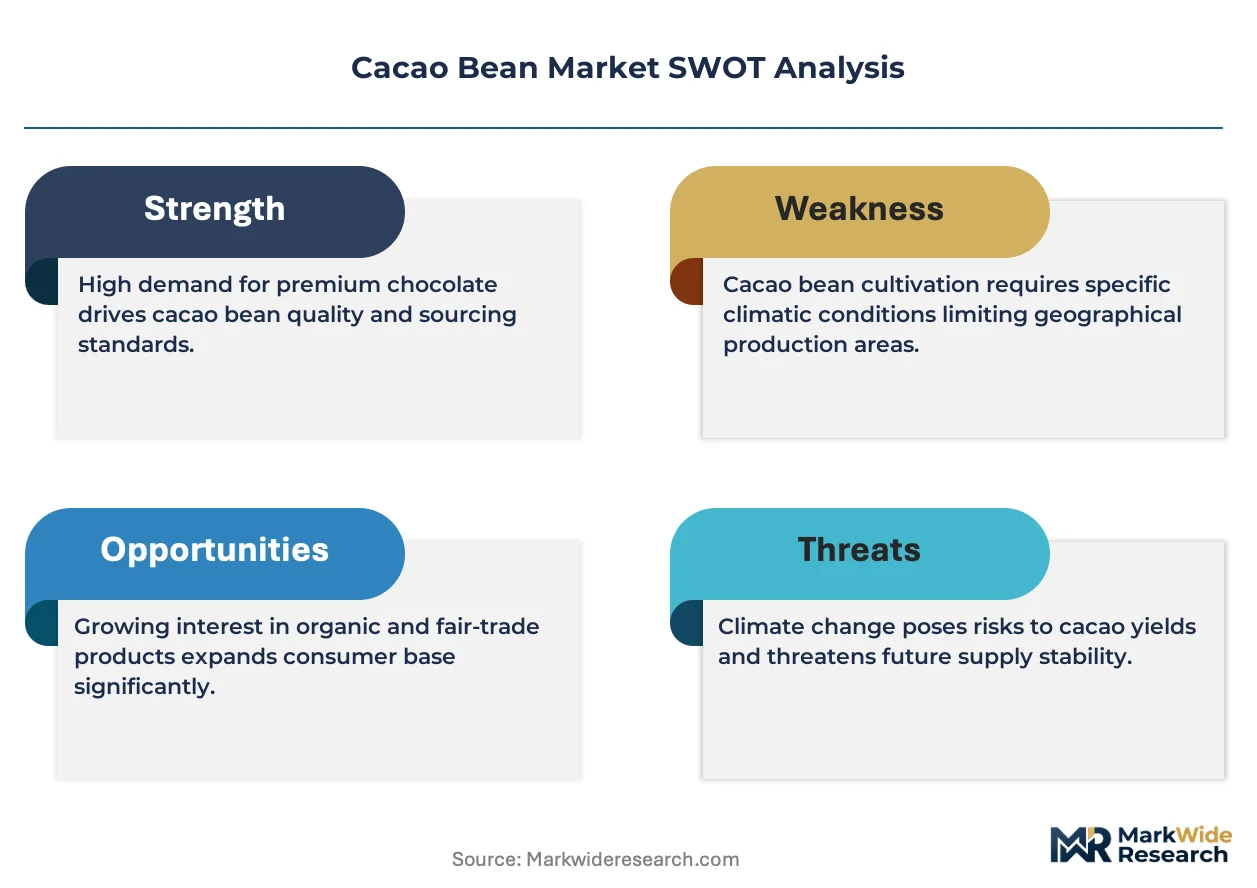
- Supply Concentration Risk:West African origins—Côte d'Ivoire and Ghana—account for roughly two-thirds of global bean volume, creating systemic vulnerability to climate shocks and political instability.
- Input Cost Volatility:Fertilizer prices and agricultural labor costs in origin countries fluctuate with currency movements and energy markets, compressing farmer margins and export volumes.
- Technical Limitation:Cocoa butter's irreplaceable melting profile in confectionery applications prevents substitution by shea or palm oil derivatives, locking processors into high-cost raw material dependence.
Strategic Opportunities
- Underpenetrated Geographies:Ecuadorian fine-flavor cacao remains underutilized relative to its genetic diversity, offering bean-to-bar producers distinct terroir narratives that command pricing premiums.
- Regulatory Tailwind:EU Green Deal carbon-border adjustments will favor origins with established agroforestry systems and low-deforestation supply chains, advantaging certified producers in Colombia and Peru.
- Technology Convergence:Blockchain-enabled provenance tracking combined with satellite-based forest monitoring is enabling real-time compliance verification that reduces documentation lag and audit costs.
Industry Challenges
- Certification Timeline Compression:EUDR compliance deadlines require exporters to retrofit legacy supply chains with geolocation data and risk-assessment protocols within compressed implementation windows.
- Sorting Infrastructure Capex:FDA FSMA preventive controls for heavy metals and Salmonella are forcing processors to upgrade optical sorting, steam sterilization, and laboratory testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cacao Bean Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cacao Powder, Cacao Butter, Whole Cacao Beans, Cacao Nibs End Use Industry: Confectionery, Baked Goods, Dairy Products, Nutraceuticals Quality Grade: Organic, Fair Trade, Conventional, Premium Packaging Type: Bags, Bulk Containers, Boxes, Sachets |
| Companies Covered | Barry Callebaut, Cargill, Olam International, ECOM Agroindustrial, Nestlé, Mondelez International, Mars, Hershey, Ferrero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cacao Bean Market Trends and Innovations
Digital traceability infrastructure is displacing paper-based chain-of-custody systems, while regulatory pressure on deforestation and food safety is compressing supplier qualification timelines and reshaping origin competitiveness.
Near-infrared spectroscopy combined with AI-driven defect detection is rendering obsolete manual bean grading and random-sample laboratory analysis at processing facilities. Mid-scale processors in Belgium and Switzerland are deploying these systems to accelerate intake velocity and reduce quality-control headcount. The technology is rendering obsolete the traditional role of commodity brokers as quality gatekeepers, enabling direct farm-to-manufacturer contracting.
EU Deforestation Regulation geolocation mandates are requiring exporters to submit polygon coordinates for every production plot before customs clearance. Compliance costs are diverting investment from yield improvement to documentation systems in Ghana and Côte d'Ivoire. Fine-flavor origins with pre-existing traceability infrastructure—Ecuador and Madagascar—are capturing volume diverted from compliance-lagged competitors.
Specialty buyers are consolidating procurement around single-origin, direct-trade relationships that bypass commodity exchanges and regional aggregators. Bean-to-bar manufacturers in France, Italy, and the United States are establishing multi-year purchase agreements with named cooperatives, replacing spot-market purchasing. This behavioral shift is most visible in the premium chocolate segment, where provenance storytelling commands shelf price differentiation of 40-60% above mass-market equivalents.
Cacao Bean Market Segmentation
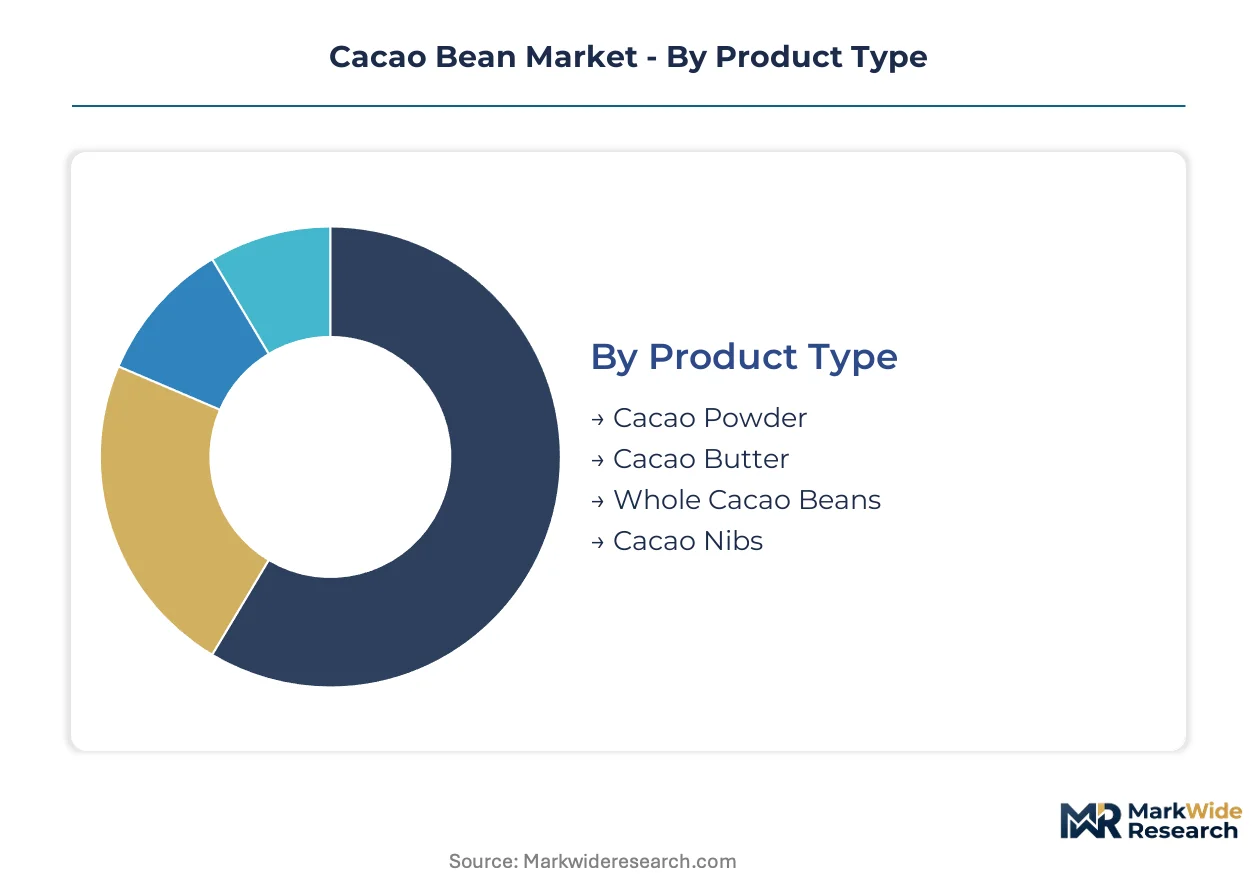
Cacao bean segmentation reveals how processing depth, end-use requirements, and certification premiums fragment procurement strategies across chocolate manufacturers, functional food formulators, and artisan producers. Understanding these divides exposes where margin pools concentrate and which specifications command pricing power.
Product Type:
Use-case spectrum spans industrial ingredient inputs to finished consumer formats, with each tier carrying distinct technical specifications and margin profiles.
- Cacao Butter:Extracted fat fraction comprising 50-57% of bean weight by standard, delivering the polymorphic crystallization behavior essential for chocolate tempering and mouthfeel. Confectionery manufacturers in Belgium and Switzerland anchor demand, though cocoa butter's irreplaceable melting profile locks processors into high-cost raw material dependence without viable vegetable fat substitutes.
- Cacao Nibs:Roasted, cracked, and winnowed kernel fragments retaining full polyphenol content and clean-label appeal. Nutraceuticals and premium baked goods sectors in the United States and Germany are absorbing volumes fastest as formulators replace synthetic flavor additives with minimally processed, antioxidant-rich inclusions.
- Cacao Powder:Press cake residue after butter extraction, standardized to 10-12% fat content for beverage and baking applications.
- Whole Cacao Beans:Unprocessed fermented and dried seeds serving bean-to-bar roasters and specialty chocolate makers seeking origin-specific terroir control.
The dominant share belongs to Cacao Butter, while Cacao Nibs are expanding most quickly as clean-label ingredient demand accelerates.
End Use Industry:
Customer type stratification separates commodity volume buyers from premium specification purchasers with divergent supply chain requirements.
- Confectionery:Chocolate bar manufacturers, praline producers, and coating specialists consuming bulk butter, liquor, and powder in continuous-process operations. EU Deforestation Regulation traceability mandates are forcing Tier-1 confectioners to requalify suppliers and absorb geolocation documentation costs.
- Nutraceuticals:Functional food and dietary supplement formulators leveraging cacao's flavanol content for cardiovascular and cognitive health positioning. Polyphenol-standardized extracts and low-alkalized powders are climbing fastest as supplement brands in California and Bavaria build origin-specific supply agreements.
- Baked Goods:Industrial bakeries and artisan patisseries utilizing cocoa powder for color, flavor, and moisture binding in cakes, cookies, and pastries.
- Dairy Products:Ice cream, yogurt, and flavored milk processors incorporating cocoa for chocolate-variant line extensions.
Confectionery retains volume leadership, though Nutraceuticals is gaining share fastest as functional ingredient specifications proliferate.
Quality Grade:
Margin tier differentiation creates four distinct pricing bands tied to certification burden and provenance verification depth.
- Premium:Single-origin, fine-flavor designations from named estates or cooperatives with genetic traceability and post-harvest processing control. Bean-to-bar makers in France and Italy are consolidating procurement around Ecuadorian and Madagascar origins with established terroir narratives commanding 40-60% shelf price premiums.
- Organic:Certified absence of synthetic pesticides and fertilizers with full farm-level audit trails. German and Dutch retail channels are expanding shelf space allocation, though conversion timelines and yield penalties constrain farmer participation in West Africa.
- Fair Trade:Price floor guarantees and community development premiums administered through cooperative structures.
- Conventional:Unspecified origin bulk beans traded through commodity exchanges with minimal traceability beyond country of export.
Premium grade holds the highest per-kilogram pricing, while Organic is climbing fastest as EU Green Deal carbon-border adjustments favor certified agroforestry systems.
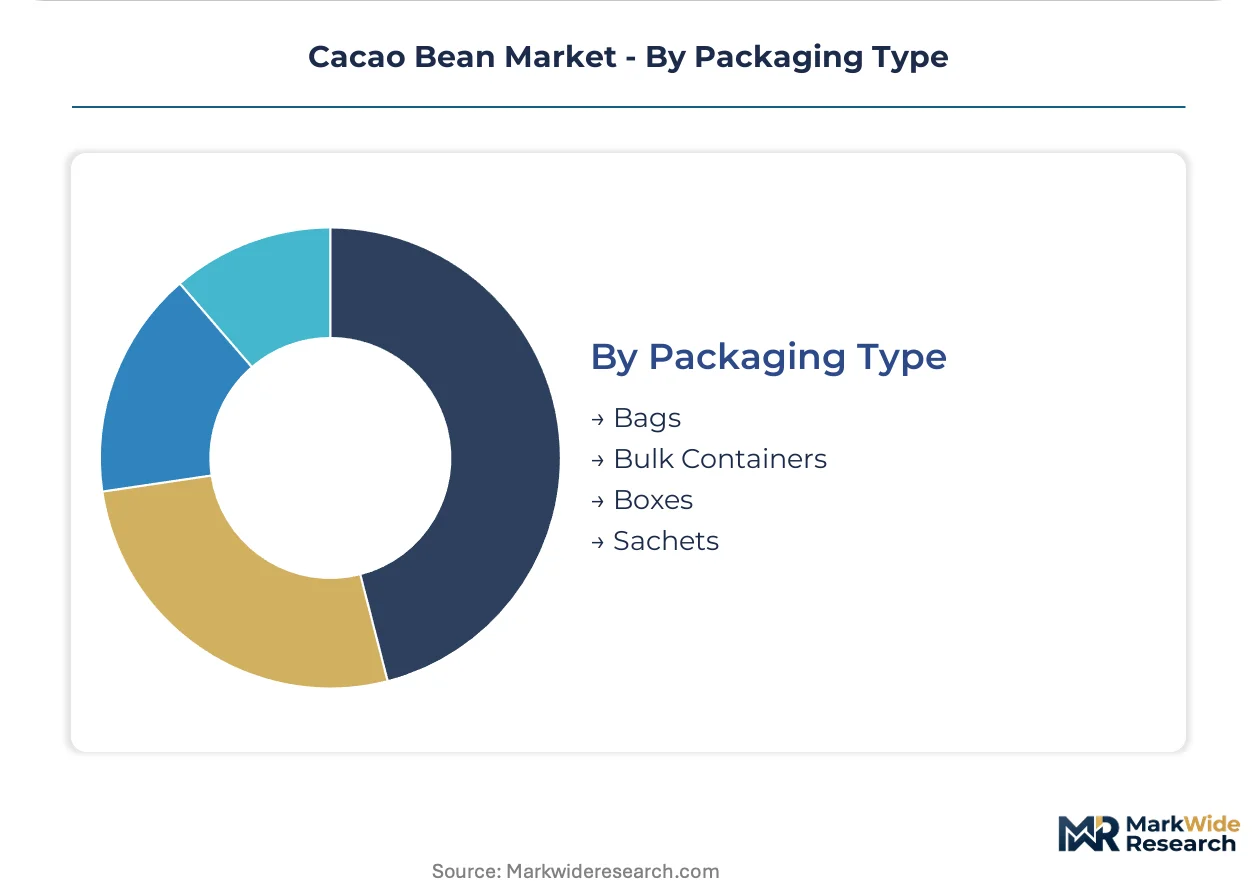
Packaging Type:
Supply concentration and logistics cost structures determine format selection across origin-export and destination-distribution legs.
- Bulk Containers:Standardized 25-tonne flexitanks and containerized bag-in-box systems for ocean freight from Abidjan and San Pedro to Amsterdam and Hamburg. Industrial grinders in Barry Callebaut's network depend on this format for scale efficiency.
- Bags:50-70kg jute or multi-wall paper sacks for break-bulk handling and regional redistribution.
- Boxes:Corrugated cases for specialty bean lots requiring ventilation and moisture protection during air freight.
- Sachets:Retail-ready small formats for direct-to-consumer whole bean and nib sales through specialty channels.
Bulk Containers dominate export volume, though Bags retain flexibility for multi-origin blending operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Belgium process cacao beans into industrial chocolate ingredients at volumes that dwarf per-capita consumption in origin countries, while Japan and the United States diverge toward premium bean-to-bar formats that emphasize provenance storytelling over commodity scale.
Germany
Industrial grinders in Hamburg and Cologne supply compound chocolate to Central European confectioners, with EUDR geolocation mandates forcing processors to requalify West African suppliers ahead of enforcement deadlines. The EU Green Deal carbon-border adjustments favor certified agroforestry systems, advantaging Colombian and Peruvian origins with established traceability infrastructure.
United States
FDA FSMA preventive controls govern heavy metal and Salmonella thresholds, compelling importers to upgrade optical sorting and steam sterilization capacity at port-of-entry facilities. Brooklyn and San Francisco host dense clusters of bean-to-bar makers sourcing directly from Ecuadorian cooperatives, bypassing commodity exchanges entirely.
Belgium
Praline manufacturers in Brussels and Antwerp anchor demand for high-cocoa-butter liquor, with EUDR due-diligence requirements accelerating investment in farm-level mapping systems. The port of Antwerp handles break-bulk specialty beans for artisan roasters seeking single-origin terroir control unavailable through bulk flexitank shipments.
Japan
Functional food formulators in Tokyo and Osaka integrate polyphenol-rich cacao extracts into cardiovascular health supplements, with METI quality standards driving preference for low-alkalized powders. Specialty chocolate boutiques in Ginza and Shibuya command shelf price premiums of 40-60% above mass-market equivalents through origin-specific storytelling.
Switzerland
Swissmedic food safety protocols exceed baseline EU requirements, filtering supplier pools toward origins with laboratory-tested heavy metal documentation. Zurich and Geneva processors deploy near-infrared spectroscopy with AI-driven defect detection to accelerate intake velocity and reduce quality-control headcount at grinding facilities.
Cacao Bean Market Competitive Landscape
Capability concentration sits with artisan bean-to-bar makers who control post-harvest processing narratives; scale advantage sits with industrial grinders operating four-continent grinding networks. The market structures around three tiers: commodity processors serving mass-market confectioners, integrated chocolate manufacturers with captive supply chains, and specialty traders financing farm-level traceability systems. Dominant competitive moves include backward integration into origin-country sourcing and technology licensing for digital provenance tracking.
Among integrated chocolate manufacturers, Barry Callebaut, Cargill, and Olam International exemplify contrasting strategic archetypes. Barry Callebaut occupies a position as the scale-driven industrial grinder with continent-spanning capacity. Cargill represents the agricultural-commodity conglomerate with farmer financing programs embedded in West African origins. Olam International sits within the specialty-trader tier, differentiating through digital traceability platforms that map farm-level provenance for premium buyers.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill |
| Olam International |
| ECOM Agroindustrial |
| Nestlé |
| Mondelez International |
| Mars |
| Hershey |
| Ferrero |
| Others |
Pricing and Supply Chain Analysis
Regulatory chokepoint exposure through the EU Deforestation Regulation determines both tiered pricing spreads across premium-to-commodity grades and supply chain reconfiguration toward traceability-verified origins. Compliance cost absorption in Ghana and Côte d'Ivoire compresses farmer margins while redirecting premium volumes toward Ecuadorian and Peruvian suppliers with pre-existing geolocation infrastructure.
Pricing Analysis
Long-term offtake contracts dominate procurement between industrial grinders and West African cooperatives, locking in volume commitments that insulate against spot-market volatility. Premium-mid-economy pricing differentiation separates single-origin fine-flavor beans from bulk commodity grades, with certification premiums widening spreads. Cost compression in conventional tiers intensifies as EUDR documentation burdens erode exporter margins. Industrial confectioners in Belgium and Germany exhibit highest price sensitivity, while bean-to-bar makers absorb premiums for provenance-verified supply.
Supply Chain Analysis
Export-control regimes limiting agricultural commodity flows have minimal direct application, though EU Deforestation Regulation due-diligence requirements function as de facto trade barriers for non-compliant origins. Supply concentrates in Côte d'Ivoire, Ghana, and Ecuador, with West African origins feeding industrial processing and Ecuadorian fine-flavor beans serving specialty channels. Input dependencies center on fermentation capacity, drying infrastructure, and agricultural labor pools. Single-source vulnerability in West African bulk supply creates systemic exposure to climate shocks and political disruption. Distribution runs through Antwerp and Hamburg port hubs for European processing, with direct air freight serving U.S. artisan roasters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cacao bean market functions as a regulatory-entrenchment moat, where EUDR compliance infrastructure creates switching costs that lock buyers into qualified supplier relationships and exclude laggard origins from premium channels.
For Market Incumbents: Insulate margin pools by deepening backward integration into Ecuadorian and Colombian fine-flavor origins with established traceability systems, while accelerating optical sorting and sterilization capex to meet FDA FSMA preventive controls. Certification investment in agroforestry verification captures EU Green Deal carbon-border preference, defending against margin erosion from compliance-lagged West African competitors. For New Entrants and Emerging Players: Build out direct-trade relationships with Madagascar and Papua New Guinea cooperatives bypassing commodity exchanges, targeting the nutraceuticals segment where polyphenol-standardized extracts command formulation premiums. White-space opportunity sits in blockchain-enabled provenance platforms that reduce audit costs for mid-scale processors seeking EUDR compliance without legacy system retrofit. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated processors with captive origin infrastructure over pure-trading intermediaries. Long-term viability hinges on deforestation-free supply chain control and carbon-accounting capabilities. Acquisition targets should display farm-level mapping systems and cooperative financing relationships. The signal to watch is diversion of premium volumes from compliance-lagged West African origins toward certified Latin American suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin Sourcing | Captures EUDR-compliant supply chains in Ecuador and Peru before competitor lock-in. |
| Digital Traceability Platform Deployment | Reduces documentation lag for Barry Callebaut and Olam International premium buyers. |
| Near-Infrared Spectroscopy Installation | Accelerates intake velocity at Swiss and Belgian grinding facilities while cutting QC headcount. |
| Direct-Trade Contracting with Cooperatives | Enables French and Italian bean-to-bar makers to bypass commodity broker markups entirely. |
| Agroforestry Certification Program | Positions Colombian origins for EU Green Deal carbon-border adjustment advantages. |
Research Methodology
A standing panel of fermentation facility managers, cooperative export directors, industrial procurement leads at European grinders, and specialty chocolate makers provided ongoing calibration across primary fieldwork. Secondary validation drew from EU Deforestation Regulation implementation guidance, FDA FSMA preventive controls documentation, ICCO supply statistics, customs trade records, and sustainability certification databases. Bottom-up volume modeling across origin countries triangulated against top-down demand estimates from confectionery and nutraceuticals end-use channels.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, quality grade, end-use industry, and packaging format. CAGRs derived from historical volume trajectories adjusted for regulatory implementation timelines and substitution elasticity between origins. Forecast inputs incorporated EUDR compliance cost curves, fine-flavor genetic diversity utilization rates, and clean-label ingredient adoption patterns in functional foods.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-enabled traceability providers or carbon-credit aggregators would shift outcomes. Material shifts in EU deforestation enforcement timelines, West African political stability, or breakthroughs in cocoa butter alternatives would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Italy Soy Protein Market
Ingredients
Pet Food Premix Market
Ingredients
Textured Soy Flour Market
Ingredients
South America Protein Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Phytogenic Market
Ingredients
Plant Extracts Market
Ingredients
Commercial Flour Market
Ingredients
Europe Protein Market
Ingredients
Cholesterol API Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Rose Hips Extract Market
Ingredients
Egg Yolk Lecithin Market