
 Cooking Oil Market | 2026-2036
Cooking Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Cooking Oil Market Intelligence
The unbundling of bulk formats into smaller, application-specific packaging like pouches and sachets is restructuring buyer choice in household segments. This trend contrasts with the large-scale commodity trading that anchors the business model of Cargill Incorporated. Archer Daniels Midland leverages its vast processing capabilities to supply both bulk and refined oils. Wilmar International Ltd dominates certain regional markets with its extensive portfolio of branded consumer products.
Cooking oil is a plant, animal, or synthetic fat used in frying, baking, and other types of cooking. These lipids are distinguished by their smoke point, which dictates their suitability for different heat applications. The vegetable oil category, encompassing sunflower and canola oil, holds the largest volume share. Within applications, demand for specialized oils for high-heat frying in the foodservice sector shows significant momentum.
Market access is governed by stringent food safety regulations, including standards set by the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). In markets like India, the FSSAI mandates specific labeling for fortified oils, shaping product development. Stakeholders must now navigate consumer demand for sustainably sourced oils against the backdrop of volatile agricultural commodity prices.
Market Dynamics
The cooking oil market's structure is defined by the dual pressures of government-led food fortification mandates and demand from the food processing industry for bulk supply, creating a complex interplay between public health objectives and industrial-scale economics.
Growth Catalysts
- Food Fortification Mandates:Regulations such as those from India's FSSAI, which require the addition of specific vitamins to edible oils, are creating a mandatory baseline for product formulation and stimulating demand for compliant products.
- Foodservice Sector Expansion:The growth of quick-service restaurants and institutional catering is driving volume demand for specialized, high-performance frying oils, particularly those with high smoke points suitable for continuous use.
- Health-Oriented Consumerism:A shift in household preference towards oils perceived as healthier, such as canola and sunflower oil, is fueling product development and marketing focused on nutritional benefits and specific fatty acid profiles.
Market Restraints
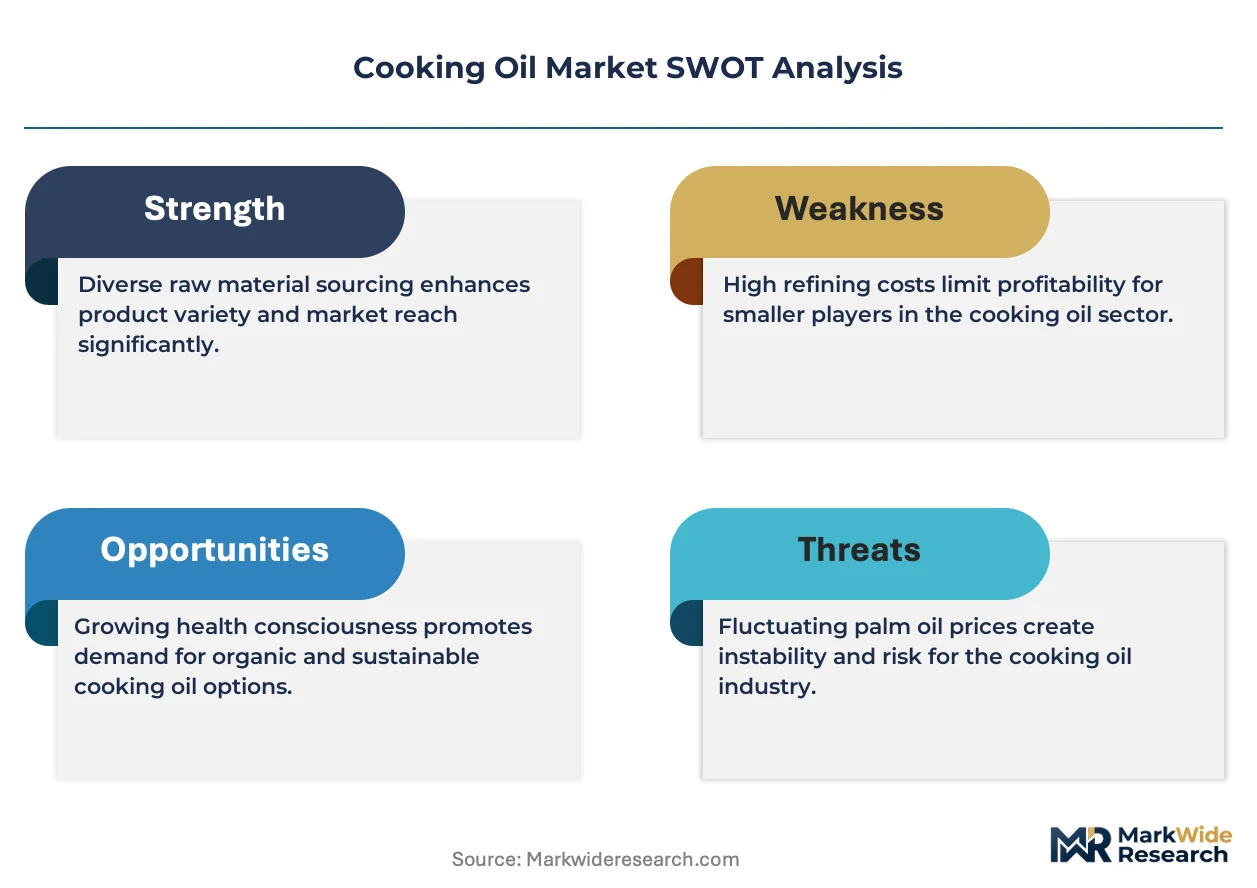
- Agricultural Commodity Volatility:Price and supply instability for key oilseeds like sunflower, soy, and palm, driven by weather events and geopolitical factors, creates significant cost pressure and margin uncertainty for processors.
- Regulatory Divergence:Navigating the patchwork of international food safety standards, including distinct requirements from the US FDA and Europe's EFSA, complicates global trade and increases compliance costs for exporters.
- Substitution from Animal Fats:In certain professional and home cooking applications, particularly for flavor, traditional animal fats like lard and tallow present a persistent substitution threat to vegetable-based cooking oils.
Strategic Opportunities
- Packaging Innovation:The unbundling of oil into small-format pouches and sachets offers a significant opportunity to penetrate price-sensitive household segments in emerging markets by improving accessibility and affordability.
- Specialized Oil Formulations:There is a clear opening for developing and marketing oils tailored for specific applications, such as high-stability oils for industrial frying or cold-pressed oils for premium consumer segments.
- Sustainability Certification:Offering products certified by sustainability bodies provides a distinct advantage, allowing producers to access premium markets and appeal to environmentally conscious consumers and corporate buyers.
Industry Challenges
- Traceability Implementation:Establishing and maintaining fully traceable supply chains to meet consumer and regulatory demands for sustainably sourced oil is a significant operational and technological challenge for the industry.
- Labeling Compliance Complexity:Stakeholders face difficulties in adhering to evolving and often country-specific labeling laws concerning health claims, nutritional information, and fortification, which can delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooking Oil Market |
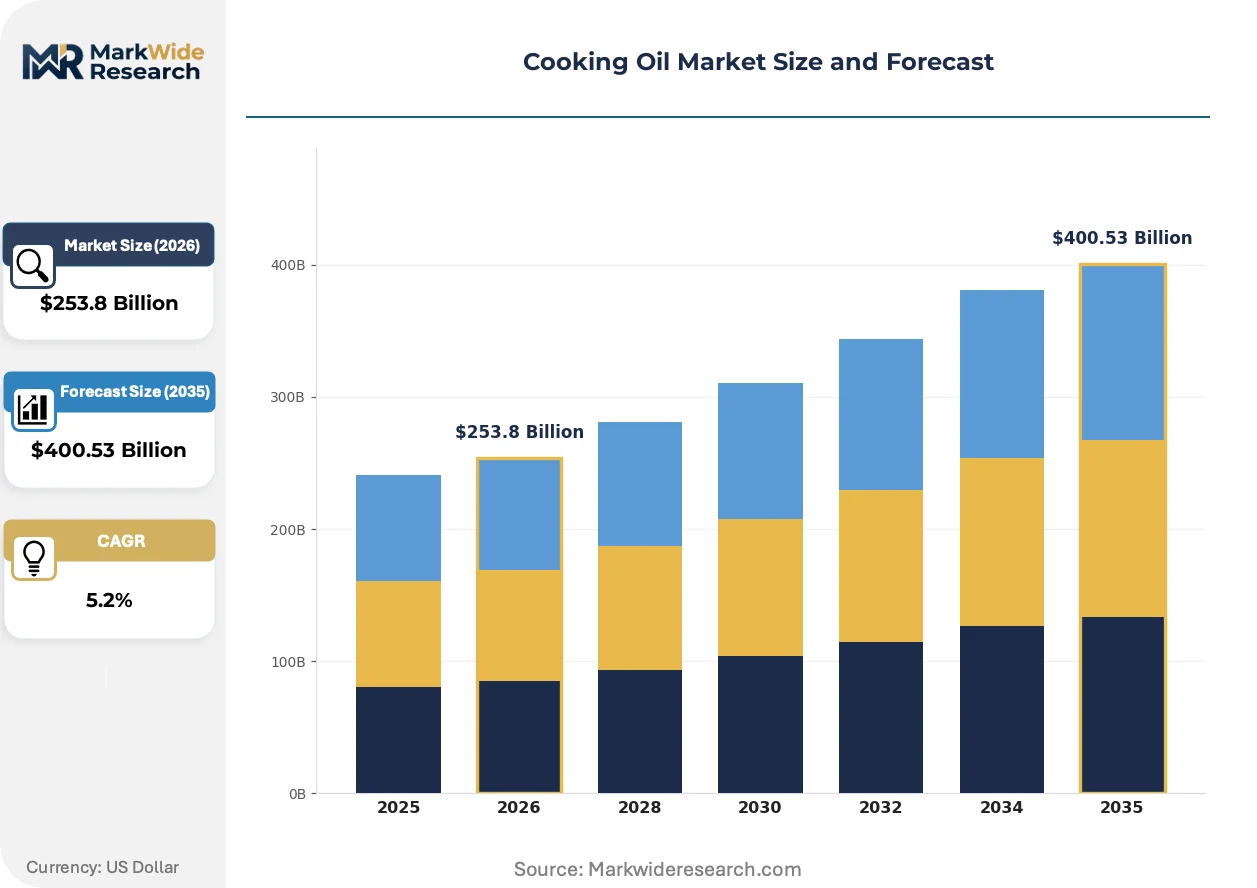
| Market Size in 2026 | $253.8 Billion |
| Market Size in 2035 | $400.53 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oil, Olive Oil, Coconut Oil, Palm Oil, Canola Oil, Sunflower Oil Packaging Format: Bottle, Tin, Pouch, Bulk Container, Jar, Sachet Application: Food Processing, Home Cooking, Restaurants, Frying, Baking, Salad Dressings Customer Type: Households, Foodservice Operators, Catering Services, Small Retailers, Wholesalers, Institutional Buyers |
| Companies Covered | Archer Daniels Midland, Cargill Incorporated, Bunge Global SA, Wilmar International Ltd, Conagra Brands, Louis Dreyfus Company, Fuji Oil Holdings Inc., Associated British Foods plc, Olam Agri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooking Oil Market Strategic Shifts & Innovations
Product formulation is being fundamentally altered by the intersection of consumer health awareness and the technical demands of industrial food production. This dynamic is pushing innovation beyond simple refinement toward creating oils with specific functional and nutritional properties.
Advanced lipid modification techniques like enzymatic interesterification allow for the creation of structured fats with customized melting points. Food manufacturers are adopting this technology to replace partially hydrogenated oils in products like margarine and confectionery. This processing technology is converging with clean-label formulation strategies, enabling the development of products with improved nutritional profiles without compromising texture or shelf life.
The European Union's sustainability agenda, particularly policies under the EU Green Deal, is intensifying scrutiny of agricultural commodity supply chains. This regulation imposes stricter due-diligence and reporting requirements on importers to prevent products linked to deforestation from entering the market. The edible oils segment, especially palm and soy oil, is most affected, which is forcing investment in sophisticated traceability systems to prove compliance.
A notable shift in consumer behavior involves the move from large, all-purpose containers to smaller, application-specific packaging formats. This change disrupts the traditional retail model, creating demand for single-use pouches and right-sized bottles designed for specific cooking methods like deep frying or salad dressings. This purchasing pattern is most pronounced in the urban centers of populous countries like India, where convenience and portion control are valued.
Cooking Oil Market Segmentation
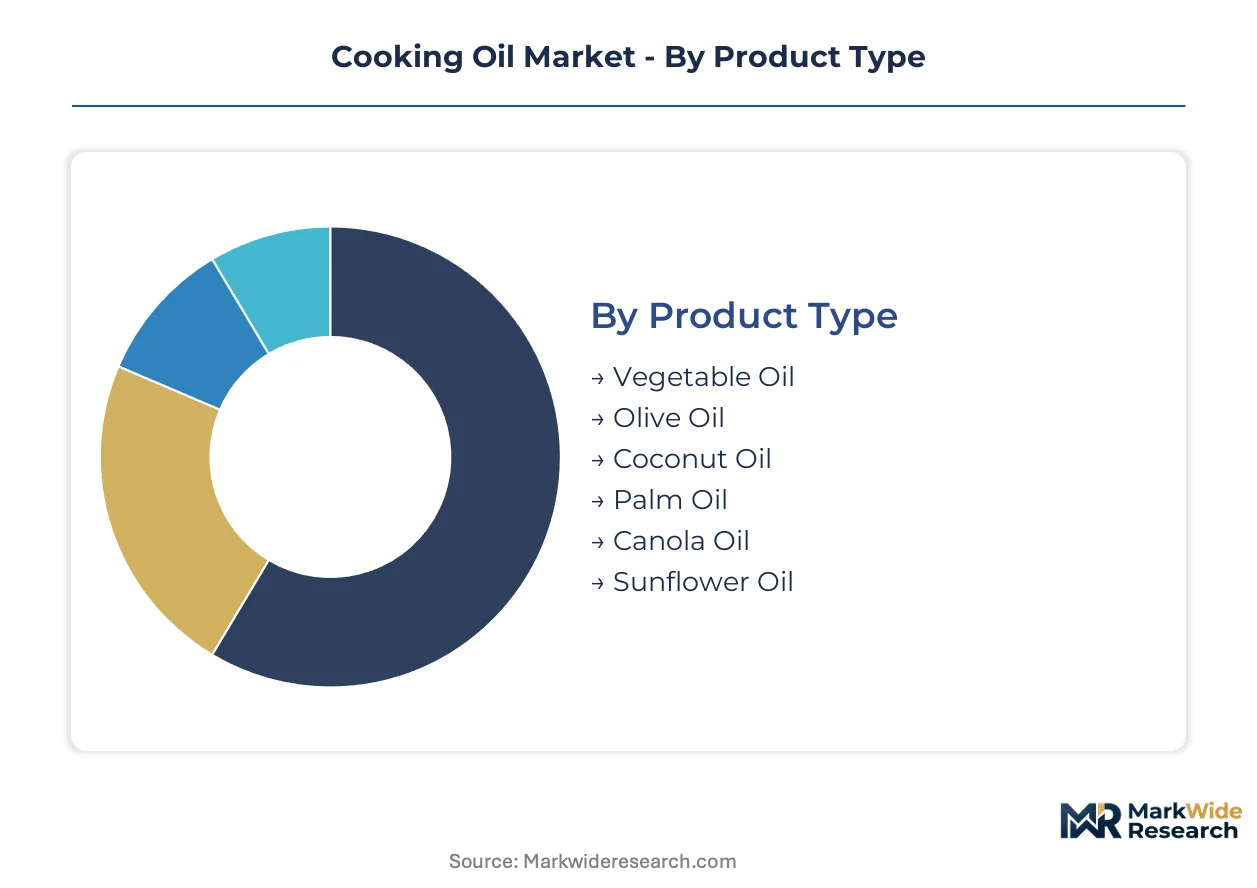
Understanding the cooking oil market through segmentation reveals distinct demand patterns and supply chain dynamics across various product types, packaging, applications, and customer groups. This granular view helps stakeholders identify specific growth opportunities and tailor product development to meet diverse consumer and industrial requirements.
Product Type:
The product type segment highlights how different oils are positioned for either standalone consumption or as integral components within food formulations.
- Vegetable Oil:This broad category encompasses various plant-derived oils, often blended for specific functional properties or cost efficiency. Demand for vegetable oils remains consistently high in both household cooking and large-scale food manufacturing across India.
- Palm Oil:Derived from the fruit of oil palms, palm oil is widely used due to its versatility, stability, and cost-effectiveness in food processing, particularly in Asian markets. Its high smoke point makes it suitable for frying applications in the foodservice sector.
- Olive Oil:Prized for its distinctive flavor and health benefits, olive oil finds primary use in salad dressings and gourmet cooking in premium consumer segments.
- Coconut Oil:Known for its unique flavor profile and medium-chain triglycerides, coconut oil is popular in specific culinary traditions and health-conscious consumer niches.
- Canola Oil:Recognized for its low saturated fat content and neutral flavor, canola oil is a preferred choice for general cooking and baking across many Western markets.
- Sunflower Oil:A light-flavored oil with a high smoke point, sunflower oil is widely consumed in Eastern European and South Asian countries for frying and everyday cooking.
Palm Oil leads volumes today; Canola Oil is gaining share fastest.
Packaging Format:
Packaging format differentiates products based on the customer type and their purchasing habits, from bulk industrial procurement to individual consumer units.
- Bulk Container:Large-volume containers, such as drums and tankers, are primarily used for industrial procurement by food manufacturers and large foodservice chains. This format supports cost efficiencies and continuous supply for high-volume operations.
- Pouch:Small, flexible pouches offer an affordable and convenient option for price-sensitive household segments, particularly prevalent in emerging markets like India for single-use or small-volume purchases. This format improves accessibility for a broad consumer base.
- Bottle:Bottles, typically made of plastic or glass, remain a standard packaging choice for household consumers due to ease of storage and pouring in retail environments.
- Tin:Metal tins provide extended shelf life and protection from light, often favored for certain premium oils or in regions where traditional packaging preferences persist.
- Jar:Jars are less common for liquid cooking oils but are used for specialty oils or solid fats, appealing to consumers seeking premium presentation or reusability.
- Sachet:Ultra-small, single-serving sachets cater to the lowest income segments, offering extreme affordability and portion control for individual cooking needs.
Bulk Container accounts for the largest share; Pouch shows the most rapid expansion.
Application:
The application segment illustrates where cooking oils are primarily utilized, reflecting diverse functional requirements and consumption patterns.
- Food Processing:This segment involves the large-scale use of cooking oils as ingredients in manufactured food products like snacks, baked goods, and ready meals. Food fortification mandates from bodies like India's FSSAI significantly influence the oil types used here.
- Frying:Oils used for frying require high smoke points and oxidative stability to withstand sustained high temperatures, catering to both industrial deep-frying and household pan-frying. The foodservice sector drives substantial volume in this application.
- Home Cooking:This category encompasses the daily use of cooking oils by households for various culinary tasks, including sautéing, roasting, and general meal preparation.
- Restaurants:Commercial kitchens in restaurants and eateries demand oils that can perform consistently under high-volume cooking conditions, often requiring specific flavor profiles or cost efficiencies.
- Baking:Oils in baking contribute to texture and moisture in products like cakes, pastries, and breads, where specific fat profiles can impact the final product quality.
- Salad Dressings:This application often favors oils with distinct flavors and emulsifying properties, such as olive oil or specialty blends, used cold for dressings and marinades.
Food Processing represents the primary demand driver; Frying is expanding most quickly.
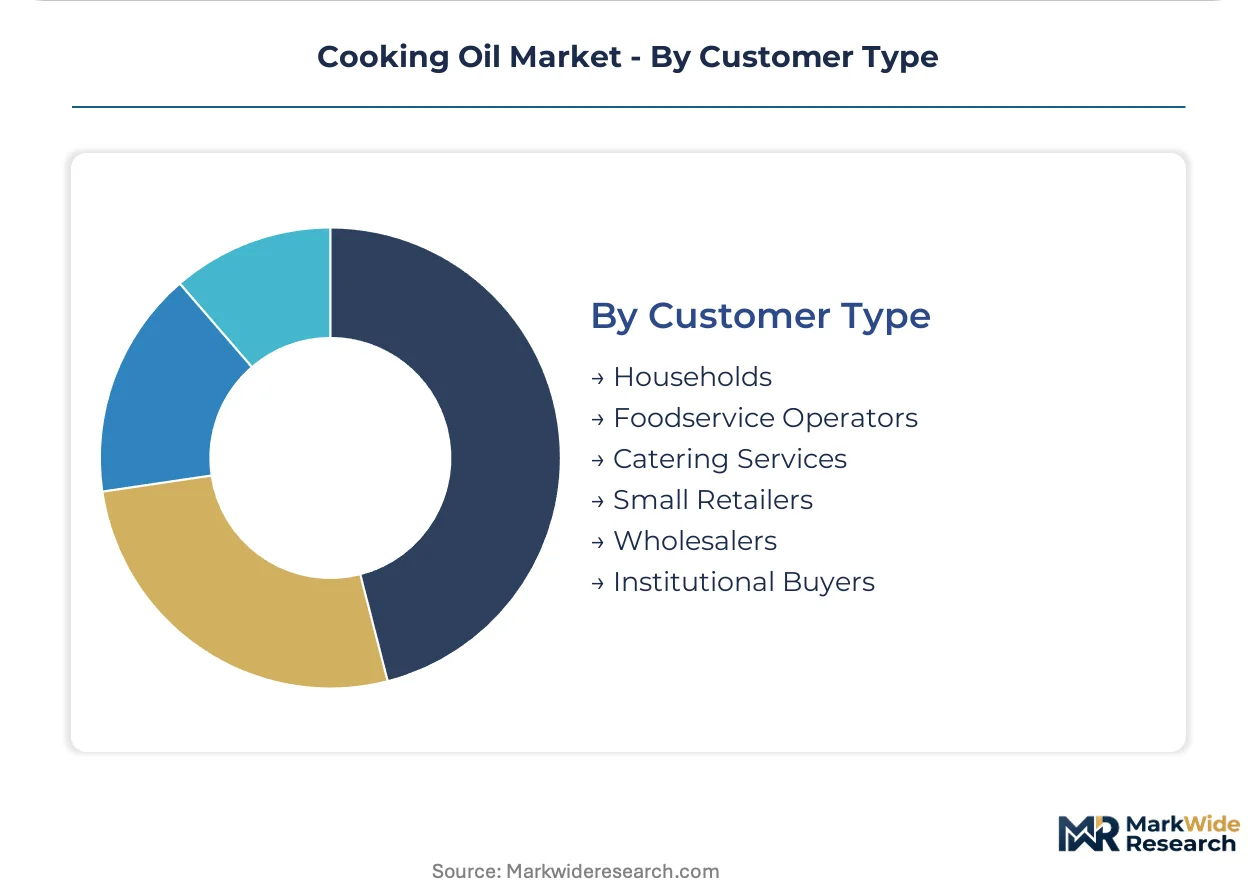
Customer Type:
Customer type segmentation reveals how different buyer groups influence supply chain structures and product offerings in the market.
- Households:Individual consumers purchasing cooking oils for personal home use, driven by factors such as health perception, brand loyalty, and price. Packaging innovation like smaller formats directly targets this segment.
- Foodservice Operators:Businesses such as restaurants, cafes, and institutional caterers that purchase oils in larger quantities for commercial food preparation. Their demand often focuses on performance, consistency, and bulk pricing.
- Catering Services:Companies providing food for events and large gatherings, requiring reliable supply of cooking oils in quantities suitable for their operational scale.
- Small Retailers:Local grocery stores and independent shops that serve neighborhood communities, stocking a range of cooking oil formats and brands to meet local consumer preferences.
- Wholesalers:Intermediaries that buy cooking oils in bulk from manufacturers and distribute them to smaller retailers, foodservice operators, and other businesses.
- Institutional Buyers:Organizations like schools, hospitals, and government facilities that procure cooking oils in large volumes for their internal food service operations.
Households represent the foundational demand; Foodservice Operators exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cooking oil market finds significant historical roots in agricultural powerhouses globally, where oilseed cultivation and processing first scaled to meet widespread culinary needs. Early industrialization of oil extraction transformed local practices into regional supply networks. Today, major economies continue to drive demand and influence production paradigms across the industry.
India
Demand for cooking oil in India is driven by vast household consumption and an expanding food processing sector. The Food Safety and Standards Authority of India (FSSAI) mandates fortification for edible oils, influencing product formulation. Major processing hubs in Maharashtra and Gujarat are adapting to these regulations, increasing output of compliant products for domestic use.
China
Population growth and a rising middle class fuel substantial demand for diverse cooking oils in China. The country's national food safety regulator implements stringent standards for oil imports and domestic production. Processing facilities in the Yangtze River Delta region focus on optimizing efficiency and meeting evolving consumer preferences for specialized oil types.
United States
The United States experiences consistent demand for cooking oils across both retail and the expansive foodservice sector. The US Food and Drug Administration (FDA) sets comprehensive safety and labeling requirements for all edible oils. Large-scale crushing and refining operations in the Midwest, particularly around Illinois, supply major food manufacturers and distributors.
Brazil
Agricultural output positions Brazil as a significant producer and consumer of cooking oils, particularly soy and corn oil. The country's agricultural policies often support domestic oilseed production and processing. Industrial complexes in São Paulo and Paraná drive innovation in biofuel co-products alongside edible oil refining for both local and export markets.
Cooking Oil Market Key Industry Players
The competitive structure tilts toward a tiered system, with global commodity traders dominating bulk supply alongside regional specialists and consumer-focused brands across diverse geographies. This market exhibits consolidation at the primary processing and distribution levels, while downstream consumer segments remain more fragmented. Strategic archetypes include integrated agribusiness giants, specialized refiners, and branded consumer product manufacturers. Companies pursue capacity expansion and portfolio diversification to secure raw material access and broaden market reach, adapting to evolving regulatory landscapes.
Within the integrated agribusiness tier, Archer Daniels Midland and Cargill Incorporated exemplify global commodity trading and large-scale processing capabilities, supplying both bulk and refined oils. These entities anchor the upstream supply chain, leveraging vast logistical networks. Wilmar International Ltd occupies a significant position among branded consumer product manufacturers, particularly in regional markets. This Singapore-based company represents a diversified approach, blending commodity trading with extensive consumer product portfolios across Asia.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Cargill Incorporated |
| Bunge Global SA |
| Wilmar International Ltd |
| Conagra Brands |
| Louis Dreyfus Company |
| Fuji Oil Holdings Inc. |
| Associated British Foods plc |
| Olam Agri |
Cost & Logistics Intelligence
Foodservice operators' bulk procurement of cooking oils directly influences pricing models, primarily driving long-term contract-based offtake agreements with large processors.
Pricing Analysis
Contract-based long-term offtake agreements dominate the industrial segment, providing stability for both buyers and suppliers. Price differentiation stems from volume scale and the specific fortification level mandated by regulators like India's FSSAI. Pricing softness reflects agricultural commodity volatility, particularly for palm and sunflower oil, creating margin pressure for refiners. Households in emerging markets represent the most price-sensitive segment, while premium consumer segments show lower sensitivity to price fluctuations for specialty oils.
Supply Chain Analysis
Single-source vulnerability sits with major oilseed-producing regions in Southeast Asia for palm oil and Eastern Europe for sunflower oil. The supply chain draws from key agricultural hubs in Brazil, India, and the United States for soy and canola. Commodity price volatility, driven by weather events and geopolitical factors, remains a significant structural risk. Downstream distribution runs through a blend of large wholesalers for industrial buyers and a fragmented retail network for household consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cooking oil market functions as a stable compounder, driven by consistent population growth and expanding food consumption globally.
For Market Incumbents: Extend backward integration into oilseed crushing to mitigate raw material price volatility, securing stable input costs. This defends against margin erosion from fluctuating agricultural commodity prices. Invest in advanced lipid modification technologies to meet evolving health-oriented consumer demands, addressing the threat of substitute technologies. Pursue strategic acquisitions of regional players to consolidate market share and optimize distribution networks.
For New Entrants and Emerging Players: Launch via specialized oil formulations targeting high-growth applications like high-heat frying in the foodservice sector. The underpenetrated segment for cold-pressed, sustainably certified oils offers a clear white-space opportunity in premium consumer markets. Focus on innovative packaging solutions, such as small-format pouches, to penetrate price-sensitive household segments in populous countries like India, leveraging affordability as a go-to-market angle.
For Investors and Strategic Acquirers: Integrated agribusiness giants are the most active acquirers in this space, seeking to enhance raw material control and processing capabilities. This market offers long-term viability due to its essential nature in global food systems. Acquisition targets should include specialized refiners with proprietary processing technologies or strong regional consumer brands. The signal to watch is the adoption rate of sustainability certifications across major corporate buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Processing Hubs | Increases efficiency and output for meeting rising global demand for edible oils. |
| Sustainability Certification Programs | Addresses consumer and regulatory pressure for ethically sourced and environmentally friendly products. |
| Advanced Lipid Modification R&D | Enables creation of healthier oil formulations with improved functional properties for food manufacturers. |
| Small-Format Packaging Innovation | Expands market access and affordability for household consumers in emerging economies. |
| Supply Chain Traceability Systems | Ensures compliance with evolving international food safety and deforestation-related regulations. |
Research Approach
Coverage spans major global markets including India, China, the United States, and Brazil, with primary inputs from each region. The analysis combines extensive primary interviews with industry stakeholders, including procurement managers at food processing companies, refinery operations directors, and retail channel heads, with robust secondary validation. This approach leverages bottom-up data collection and top-down market sizing for comprehensive insights.
The rate-of-change decomposition framing underpins the analytical framework across the modeling period. The market is segmented and modeled by product type, packaging format, application, and customer type, with an additional focus on regional consumption patterns. CAGRs were derived through a proprietary algorithm considering historical growth trends and future demand drivers, with input from agricultural commodity price forecasts.
Several conditions sit outside the modeled scope, including sudden geopolitical conflicts impacting oilseed harvests or unforeseen global pandemics affecting consumer behavior. Forecasts reflect assumptions documented through extensive research. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Ahiflower Oil Market
Ingredients
Coconut Oil Based Products Market
Ingredients
South America Fats and Oil Market
Ingredients
Tomato Concentrate Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Jojoba Oil Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Europe Corn Glucose Market
Ingredients
Apple Extract Market
Ingredients
Acetylated Starch Market
Ingredients
Gluten-Free Flour Market
Ingredients
Seaweed Derivatives Market
Ingredients
Insect-Based Ingredients Market