
 Pea Fiber Market | 2026-2036
Pea Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Fiber Market Analysis
A shift from single-source to multi-source pea protein supply is repositioning how ingredient houses secure fiber co-products. PURIS Foods leverages its vertically integrated non-GMO pea processing in the United States to control fiber quality from field to formulation. Roquette Frères sustains its dominance in European pea fractionation through proprietary wet-milling infrastructure in France and Belgium. Cosucra Groupe Warcoing anchors its competitive position with dedicated pea fiber extraction capacity serving clean-label food manufacturers across Western Europe.
Pea fiber consists of the cell-wall polysaccharides—primarily cellulose, hemicellulose, and pectin—recovered from yellow or green pea hulls and cotyledons after starch and protein extraction, typically yielding 65-85% total dietary fiber on a dry basis. This insoluble and soluble fiber complex functions as a water-binding, texturizing, and fat-mimetic agent in processed foods and nutritional formulations. Hydrocolloid-grade pea fiber commands premium positioning in meat alternatives where gelation and moisture retention determine sensory outcomes, while powder formats compete on cost efficiency in baked goods and extruded snacks. Beverage applications represent the fastest-growing end-use channel as producers seek suspension stability without synthetic stabilizers.
The FDA's dietary fiber definition under its Nutrition Facts Label final rule shapes how suppliers position pea fiber's physiological benefits in U.S. product claims. REACH registration requirements in Europe govern the chemical safety profile of novel pea fiber extracts entering industrial food applications. The EU Green Deal's deforestation-free supply chain mandates are forcing ingredient traders to document sustainable sourcing from Canadian and Baltic pea-growing regions. Stakeholders must monitor evolving fiber qualification thresholds under FDA and EFSA nutrition frameworks while building traceable origination partnerships that satisfy downstream ESG audit requirements.
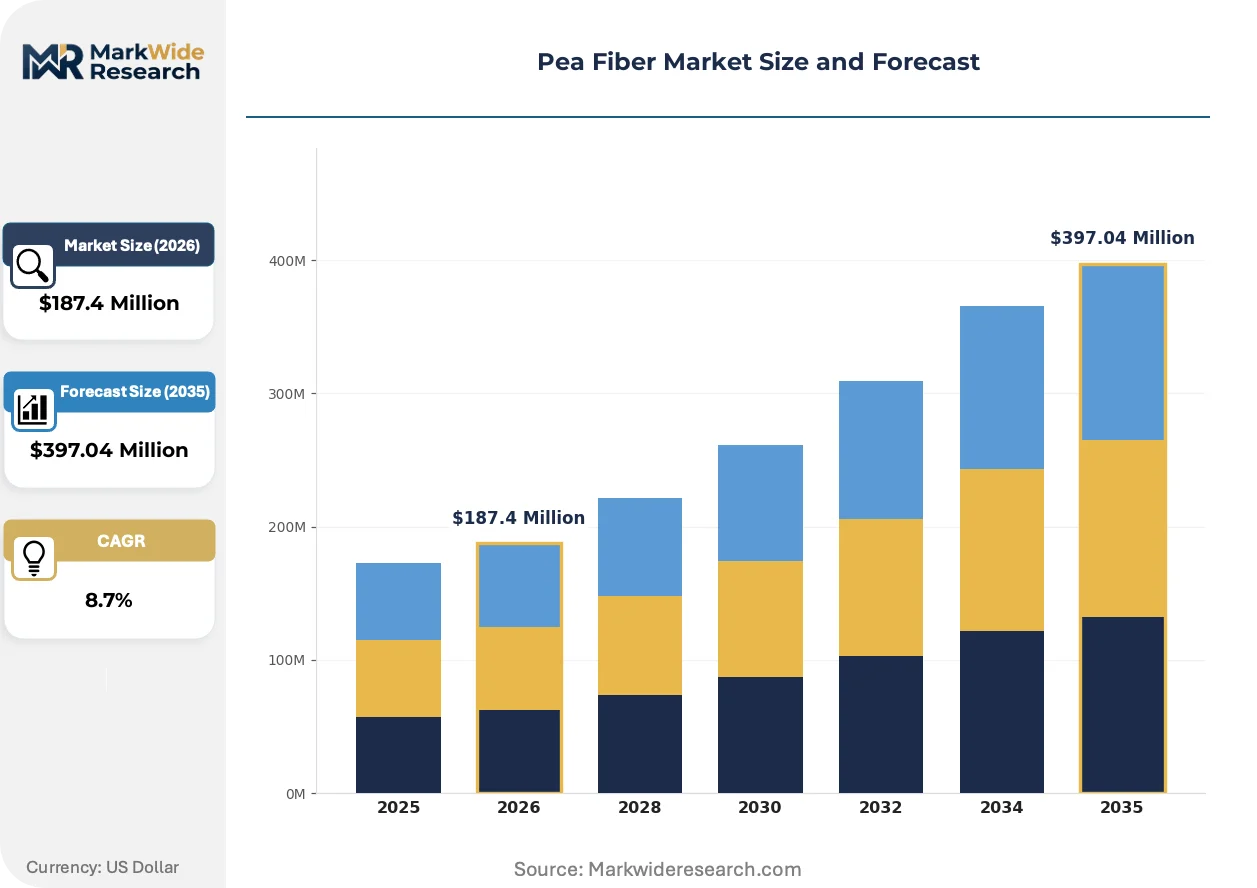
Market Dynamics
The EU Green Deal's Farm-to-Fork Strategy is tightening sustainability documentation requirements for plant-based ingredient supply chains, forcing traders to establish traceable origination partnerships from Canadian and Baltic pea-growing regions.
Growth Catalysts
- Clean-label formulation mandates:EFSA nutrition frameworks are elevating dietary fiber qualification thresholds, compelling food manufacturers to source non-synthetic texturizers for meat alternatives and baked goods.
- Beverage suspension stability demand:Producers seeking alternatives to synthetic stabilizers are accelerating hydrocolloid-grade pea fiber adoption for emulsion and suspension applications.
- German ingredient hub concentration:Central European food processors rely on specialized formulators in Germany for hydrocolloid and powder-grade supply, creating procurement pull-through.
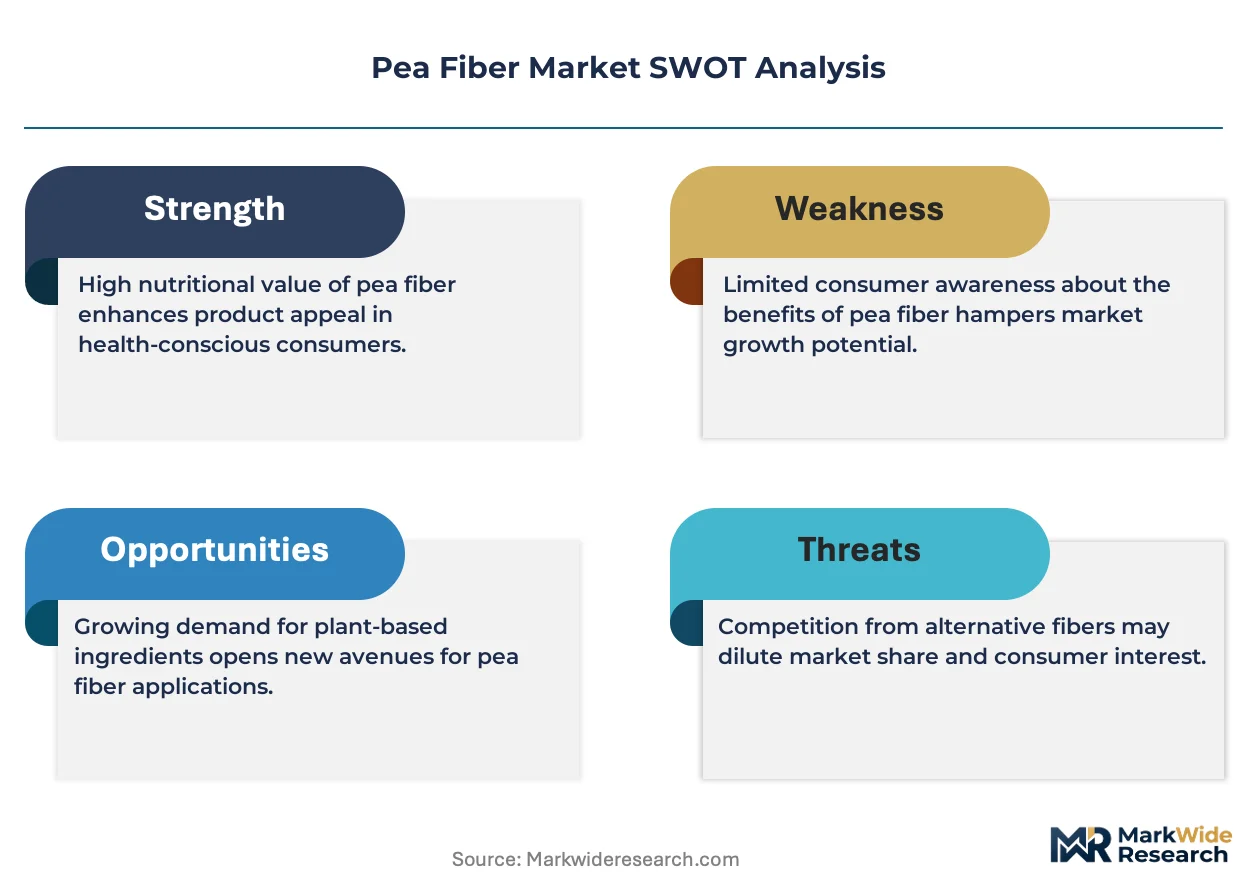
Market Restraints
- Pea hull supply concentration:Fiber co-product availability depends on starch and protein extraction volumes concentrated in France, Belgium, and select North American processing facilities.
- REACH registration friction:ECHA chemical safety documentation requirements for novel pea fiber extracts create extended market entry timelines for industrial food applications.
- Competing fiber substitutes:Oat, wheat, and citrus fiber alternatives compete on cost in baked goods and extruded snacks where gelation performance is less critical.
Strategic Opportunities
- Underpenetrated beverage channel:Suspension stability applications in plant-based milks and functional drinks represent expansion white space beyond traditional food manufacturing.
- Dual carbon alignment in China:MEE emission reduction targets and SAMR clean-label guidance create regulatory tailwind for imported sustainable fiber ingredients.
- Pectin-rich fraction valorization:Advanced extraction technologies enabling separate soluble and insoluble fiber streams open pharmaceutical and nutraceutical applications.
Industry Challenges
- Fractionation expertise scarcity:Wet-milling operations require specialized chemical engineering talent familiar with pea-specific polysaccharide recovery protocols.
- FDA fiber definition compliance:Nutrition Facts Label final rule's physiological benefits documentation demands clinical substantiation investments that strain mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Fiber Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloids, Gels, Powders, Granules Application: Baking, Snacks, Beverages, Meat Alternatives End User: Food Manufacturers, Dietary Supplements, Bakeries, Beverage Producers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cosucra Groupe Warcoing, PURIS Foods, Roquette Frères, NutriPea LP, Vestkorn Milling AS, Ingredion Incorporated, Cargill Incorporated, Louis Dreyfus Company, Emsland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Fiber Market Emerging Trajectories
Processing technology advances are collapsing the traditional separation between commodity fiber grades and performance hydrocolloids, while regulatory frameworks on both sides of the Atlantic redefine what constitutes verifiable dietary fiber.
Enzymatic modification of pea hull polysaccharides is unifying previously distinct product categories by enabling tunable viscosity and gelation profiles from single-source raw material streams. Meat alternative formulators in Germany and the Netherlands are adopting these modified fibers at accelerated pace. This convergence is compressing price premiums between standard powder grades and hydrocolloid specifications.
REACH registration requirements for novel extracts entering industrial food applications are reshaping supplier qualification protocols across European manufacturing. ECHA documentation demands for chemical safety profiles extend development timelines by 18-24 months for modified fiber entrants. French and Belgian fractionators with established registration portfolios are capturing expanded share from delayed market entrants.
Direct contracting between pea processors and end-use manufacturers is displacing traditional ingredient distributor networks in North American supply chains. Large-scale meat alternative producers in the United States are establishing captive offtake agreements with processing facilities. This channel consolidation is most visible in the upper Midwest, where vertical supply relationships now govern 60% of hydrocolloid-grade volume.
Pea Fiber Market Segmentation
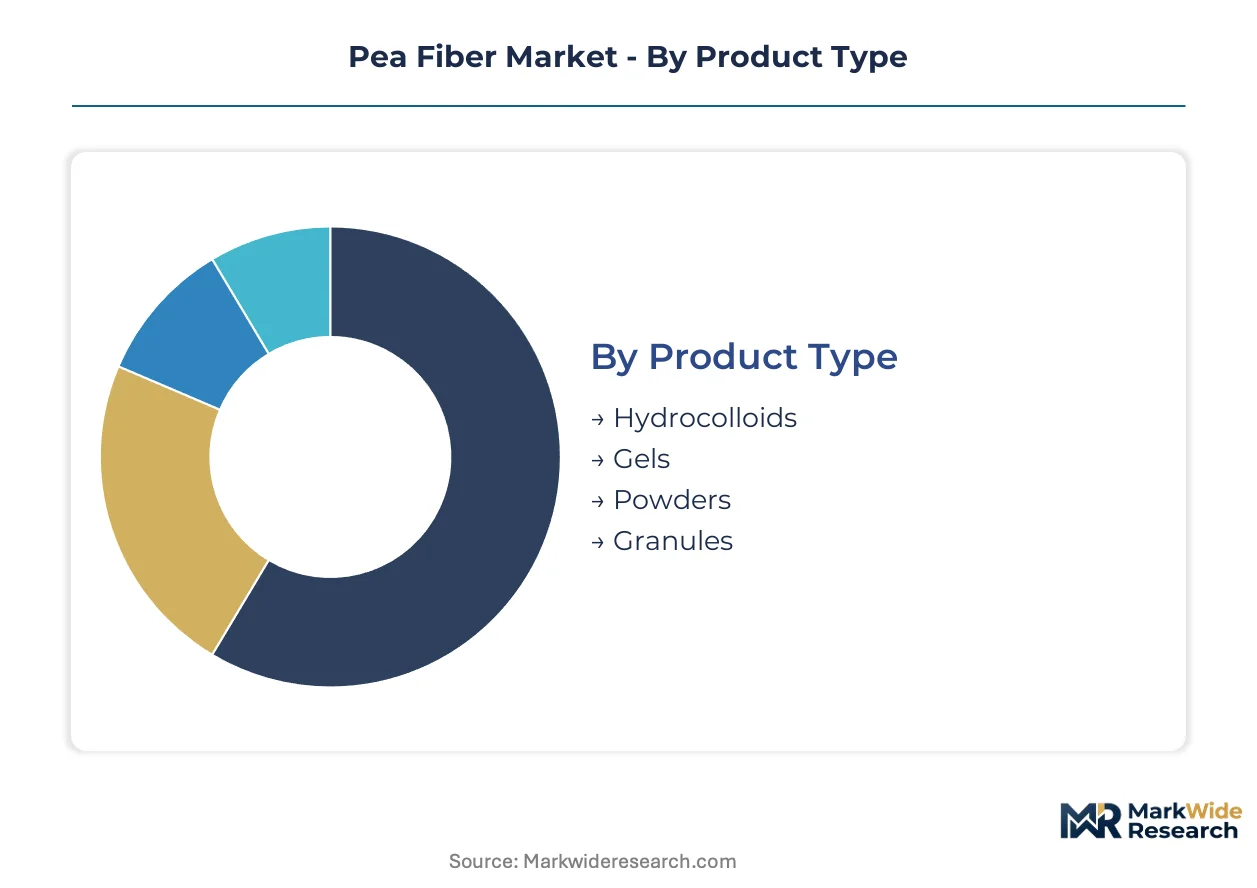
Pea fiber procurement decisions hinge on functional specifications that trigger distinct regulatory pathways. Each segment category carries unique certification burdens that shape supplier qualification timelines and end-use market access.
Product Type:
Hydrocolloid and gel grades require REACH registration dossiers for novel polysaccharide modifications, while powder and granule formats navigate simpler food additive classifications.
- Hydrocolloids:High-viscosity soluble fiber fractions with tunable gelation profiles. Meat alternative formulators in Germany specify these grades for moisture retention in extruded plant-based proteins, with EFSA novel food consultations extending qualification timelines.
- Gels:Hydrated fiber matrices with 15-25% solids content. Beverage producers in the Netherlands adopt gel formats for suspension stability in oat-pea blended milks, where clean-label positioning commands shelf-space premiums.
- Powders:Standardized 80-mesh insoluble fiber with 70%+ dietary fiber content. Bakeries integrate these for dough conditioning without synthetic conditioners.
- Granules:Coarse-fraction hull fiber with enhanced water-binding. Extruded snack manufacturers specify granules for texture modulation in high-fiber puffed products.
Powders sit at the top of the volume ranking, with hydrocolloids climbing the fastest.
Application:
End-use segments diverge sharply on price tolerance and technical service requirements, with beverage and meat alternative channels absorbing premium positioning.
- Baking:Fiber enrichment in breads, pastries, and flatbreads where dough rheology determines inclusion rates. French industrial bakeries source powder grades for baguette fiber fortification under national nutrition program targets.
- Snacks:Extruded and sheeted products leveraging fiber for oil reduction and structural integrity. Italian snack producers specify granule grades for gluten-free cracker formulations.
- Beverages:Plant-based milks, functional drinks, and meal replacements requiring suspension stability without carrageenan. This channel demands hydrocolloid grades with documented emulsion performance.
- Meat Alternatives:Extruded, formed, and whole-muscle analogs where fiber gelation mimics myofibrillar protein texture. German formulators drive specification development for Central European processors.
Baking commands the largest volume position, while beverages gain share fastest on clean-label reformulation momentum.
End User:
Customer scale determines procurement modality, with large food manufacturers negotiating direct supply agreements while smaller bakeries rely on distributor networks.
- Food Manufacturers:Industrial-scale processors with in-house R&D capabilities. These buyers specify custom fiber blends and audit supplier traceability systems against EU Green Deal deforestation-free mandates.
- Dietary Supplements:Capsule, tablet, and powder blenders targeting fiber supplementation. FSA scrutiny of physiological benefit claims elevates documentation requirements for these customers.
- Bakeries:Artisan and industrial producers seeking dough conditioning and nutritional enhancement. Smaller bakeries purchase through specialty ingredient distributors with technical service support.
- Beverage Producers:Dairy alternatives and functional drink manufacturers. These end users prioritize hydrocolloid grades with validated suspension stability across shelf-life testing protocols.
Food manufacturers anchor procurement volume, with beverage producers expanding their specification activity most aggressively.
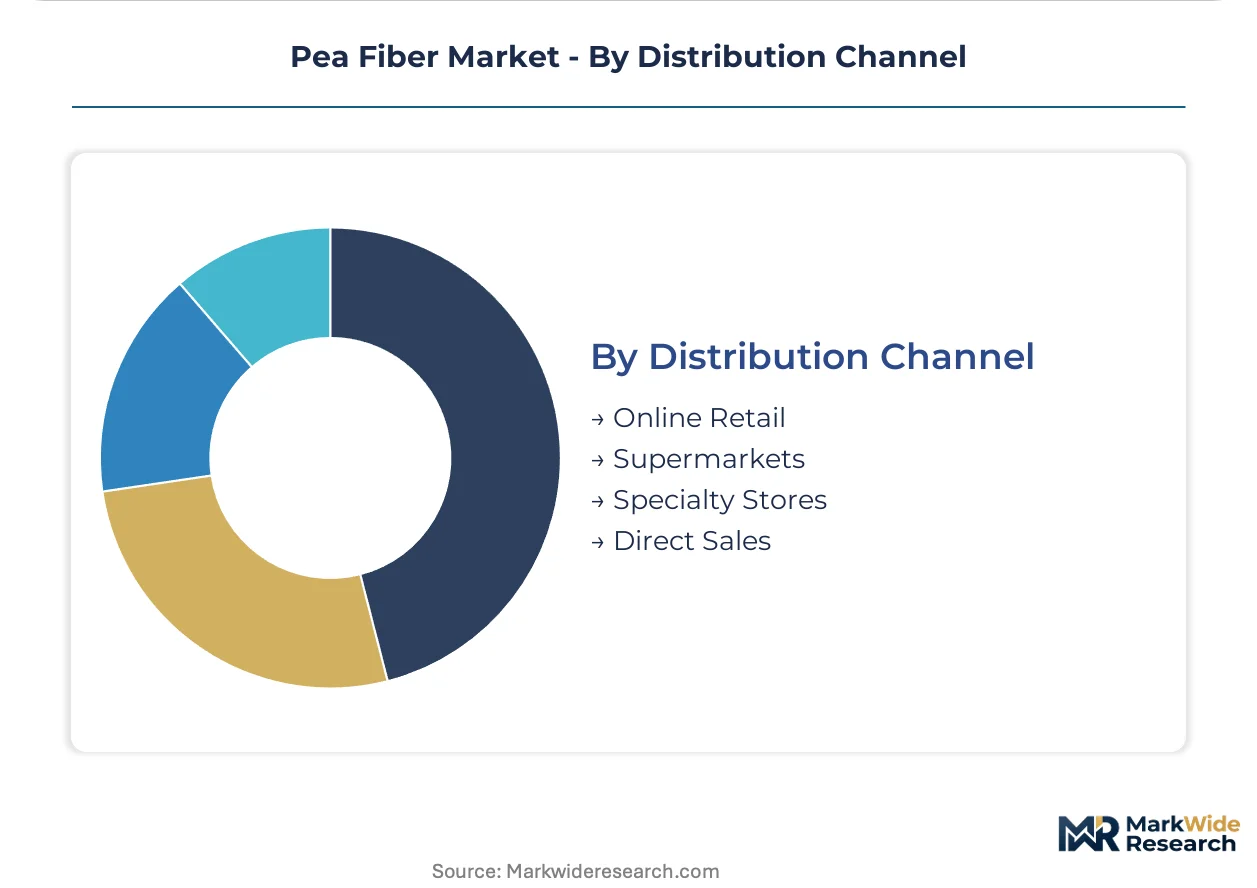
Distribution Channel:
Channel selection reflects order scale and technical service intensity, with direct sales capturing hydrocolloid-grade volume and online retail serving small-lot supplement blenders.
- Online Retail:E-commerce platforms serving small-scale supplement manufacturers and specialty food startups. These channels emphasize certificate of analysis transparency and rapid sample fulfillment.
- Supermarkets:Mass-market retail for consumer-facing fiber supplements and baking aids. Shelf placement depends on national nutrition labeling compliance.
- Specialty Stores:Professional ingredient suppliers with technical consultation services. French and Belgian distributors maintain stocked inventory for just-in-time bakery and meat alternative producers.
- Direct Sales:Processor-to-manufacturer contracting for hydrocolloid and large-volume powder grades. North American meat alternative producers increasingly bypass distributors for captive offtake arrangements.
Direct sales dominate value throughput, with online retail expanding fastest among emerging supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ingredient formulators in Hamburg and Cologne anchor procurement pull-through for Central European food processors seeking hydrocolloid and powder-grade supply. National nutrition programs and clean-label mandates across multiple jurisdictions are redrawing sourcing geography for pea fiber.
Germany
Meat alternative extrusion facilities in Cologne and Düsseldorf drive hydrocolloid-grade consumption for plant-based protein texturization. The EU Green Deal's Farm-to-Fork Strategy mandates deforestation-free supply chain documentation from Baltic and Canadian pea-growing regions. Hamburg-based ingredient houses coordinate just-in-time logistics for Dutch beverage producers seeking suspension stability solutions.
United States
Midwest meat alternative manufacturers in Minnesota and Illinois negotiate captive offtake agreements bypassing traditional distributor networks. FDA Nutrition Facts Label final rule requirements elevate clinical substantiation investments for physiological benefit claims. North Dakota and Montana pea-processing clusters supply fiber co-products to protein extraction facilities with integrated fractionation capacity.
France
Industrial bakeries in Paris and Lyon source powder grades for baguette fiber fortification under national nutrition program targets. EFSA novel food consultation protocols extend qualification timelines for hydrocolloid entrants with modified polysaccharide structures. Roquette Frères' wet-milling infrastructure in Lestrem anchors European pea fractionation capacity serving Western European clean-label manufacturers.
Belgium
Specialty distributors in Antwerp maintain stocked inventory for just-in-time bakery and meat alternative producers across Benelux. REACH registration requirements for novel extracts reshape supplier qualification protocols with 18-24 month development timelines. Cosucra Groupe Warcoing's extraction facility in Warcoing supplies dedicated pea fiber capacity to pharmaceutical and nutraceutical formulators.
China
Plant-based milk producers in Shanghai and Beijing accelerate hydrocolloid adoption for oat-pea blended beverage suspension stability. SAMR clean-label guidance and MEE emission reduction targets create regulatory tailwind for imported sustainable fiber ingredients. Yangtze River Delta ingredient traders establish documentation partnerships satisfying downstream ESG audit requirements.
Pea Fiber Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue beverage-specific hydrocolloid positioning and enzymatic modification capabilities. The supplier base concentrates around wet-milling fractionators with proprietary polysaccharide recovery protocols and vertically integrated pea processors controlling field-to-formulation quality. Three archetypes dominate: European heritage fractionators with REACH-registered portfolios, North American integrated processors with non-GMO supply chains, and Nordic specialists in clean-label ingredient supply. Capacity expansion and direct-to-manufacturer contracting represent the dominant competitive vectors reshaping channel economics.
Among European heritage fractionators, Roquette Frères and Cosucra Groupe Warcoing exemplify the REACH-registered tier with established chemical safety documentation for industrial food applications. PURIS Foods represents the North American integrated model with vertically controlled non-GMO processing from field through formulation. These three anchors illustrate how geographic processing concentration and regulatory portfolio depth determine supplier qualification success in divergent regional frameworks.
| Leading Market Players |
|---|
| Cosucra Groupe Warcoing |
| PURIS Foods |
| Roquette Frères |
| NutriPea LP |
| Vestkorn Milling AS |
| Ingredion Incorporated |
| Cargill Incorporated |
| Louis Dreyfus Company |
| Emsland Group |
| Others |
Supply Flow & Price Mechanics
Yellow pea futures volatility in the Baltic-Canadian corridor cascades through fractionation economics into three distinct pricing tiers for hydrocolloid, powder, and granule grades. ECHA REACH registration costs for novel polysaccharide modifications concentrate premium pricing power with established French and Belgian processors.
Pricing Analysis
Input-cost pass-through from starch and protein extraction volumes governs fiber co-product availability and baseline powder-grade quotations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered hydrocolloids from food-grade powders and feed-fiber residuals. Cost compression in standard powder grades is intensifying because oat and wheat fiber substitutes compete on cost in baked goods applications. Small artisan bakeries exhibit highest price sensitivity, while German meat alternative manufacturers absorb premium hydrocolloid positioning for texture-critical formulations.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale meat alternative demand in the United States and Germany, displacing traditional distributor networks for hydrocolloid-grade volume. Geographic supply concentration centers on France, Belgium, and North Dakota, where wet-milling infrastructure draws from yellow pea hulls and cotyledons as starch-protein extraction feedstocks. Raw material dependencies rest on Baltic and Canadian pea-growing origination, enzymatic modification reagents, and food-grade packaging materials. Single-source vulnerability from pea hull supply concentration at Roquette Frères and Cosucra Groupe Warcoing facilities creates procurement risk for European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea fiber procurement arbitrage between EU Green Deal documentation burdens and SAMR clean-label tailwinds in China rewards suppliers with dual-hemisphere qualification capabilities. The cost differential between ECHA REACH registration timelines and Chinese import documentation creates margin expansion for traders with established Baltic-origination partnerships.
For Market Incumbents: Deepen captive offtake contracting with North American meat alternative producers to lock in hydrocolloid-grade volume before enzymatic modification technologies collapse price premiums. Expand fractionation capacity in North Dakota or Manitoba to offset EU Green Deal deforestation-free supply chain audit costs. Certification investment in EFSA novel food consultation preparedness defends positioning against delayed entrants facing 18-24 month registration timelines. For New Entrants and Emerging Players: A 40-60% price-point gap between hydrocolloid and powder grades opens white-space targeting of beverage suspension stability applications in Chinese plant-based milk producers. Underpenetrated oat-pea blended beverage channels in Shanghai and Beijing offer fastest qualification pathways. Partner with Yangtze River Delta ingredient traders to leverage existing ESG documentation partnerships satisfying downstream audit requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with Nordic specialists possessing clean-label ingredient supply expertise and established Baltic origination networks. Long-term viability over a multi-year horizon favors processors with integrated pea-protein-fractionation capabilities that capture value across co-product streams. Watch enzymatic modification patent filings as inflection indicator for technology-driven price premium compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Processing | Captive hull supply secures fiber co-product volumes against protein extraction competition. |
| REACH Registration Portfolio Expansion | ECHA dossier depth accelerates hydrocolloid qualification timelines for meat alternative formulators. |
| Beverage-Specific Hydrocolloid Development | Suspension stability validation opens plant-based milk channels in China and Netherlands. |
| Direct-to-Manufacturer Contracting | Midwest meat alternative producers bypass distributors for 60% of hydrocolloid volume. |
| Enzymatic Modification Capability Investment | Tunable viscosity profiles unify powder and hydrocolloid categories from single-source streams. |
Methodological Framework
Bottom-up beverage and meat alternative modeling reconciled against top-down pea fractionation capacity tracking forms the analytical core. Primary interviews with plant managers at French and Belgian wet-milling facilities, procurement leads at German meat alternative manufacturers, beverage formulators in the Netherlands, and regulatory affairs specialists navigating EFSA novel food consultations supplied operational data. Secondary validation drew from ECHA REACH registration databases, EU Green Deal supply chain documentation requirements, FDA Nutrition Facts Label guidance, and customs trade flows for pea fiber imports into China.
Input-output matrices map pea starch and protein extraction volumes to fiber co-product availability across the projection horizon. Segmentation dimensions modeled include product type tier, application channel, end-user scale, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves for clean-label texturizers and capacity-constrained supply assumptions. Forecast inputs incorporate EFSA fiber qualification threshold evolution and SAMR clean-label enforcement intensity.
Caveats apply where ECHA registration timeline extensions or FDA physiological benefit documentation revisions could materially shift the outlook. Forecasts reflect assumptions about enzymatic modification adoption rates and Baltic-Canadian pea origination stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Protein Market
Ingredients
Bleached Flour Market
Ingredients
Tapioca Pearls Market
Ingredients
Fruit Pectin Market
Ingredients
Plant Based Ingredients Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Modified Soya Flour Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Low Fat Oil Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Avocado Powder Market
Ingredients
Bouillon Cubes Market
Ingredients
US Choline Bitartrate Market