
 Middle East & Africa Prebiotic Ingredients Market | 2026-2036
Middle East & Africa Prebiotic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Prebiotic Ingredients Market Insights
The capability gap between integrated multinationals and regional distributors is collapsing as raw material sourcing networks consolidate around Gulf ports. Cargill Incorporated leverages its Red Sea logistics infrastructure to anchor supply security for Egyptian dairy processors. Fonterra Co-operative Group Limited competes through its Oceania-to-Middle East cold chain, while Kerry Group plc differentiates via customized prebiotic blends for halal-certified formulations.
Middle East & Africa prebiotic ingredients comprise non-digestible food components—primarily oligosaccharides with degree of polymerization ranging from two to sixty units—that selectively stimulate beneficial gut microbiota colonization in the host colon. Manufacturers extract inulin from chicory root through hot water diffusion followed by spray drying, yielding powders with minimum eighty-five percent dietary fiber content for industrial food fortification. Galactooligosaccharides command premium positioning in infant formula applications across the region, while inulin dominates volume throughput in dairy and bakery segments where cost-sensitive formulation prevails. The functional foods application channel generates the deepest margin pools due to clinical substantiation requirements and brand loyalty effects.
Saudi Food and Drug Authority standards on health claim substantiation reshape product registration timelines, while South African Health Products Regulatory Authority oversight of complementary medicines extends to prebiotic dietary supplements. Gulf Standards Organization harmonization of food additive maximum levels creates cross-border compliance efficiencies for multinational suppliers. Stakeholders must monitor evolving national nutrition strategies and halal certification body rulings on fermentation-derived substrates to preempt formulation reformulation cycles.
Market Dynamics
Gulf Cooperation Council food safety frameworks are tightening labeling requirements for functional food claims, forcing infant formula manufacturers across South Africa and Nigeria to expand galactooligosaccharide procurement while Saudi dairy processors accelerate bulk inulin consumption for beverage fortification programs.
Growth Catalysts
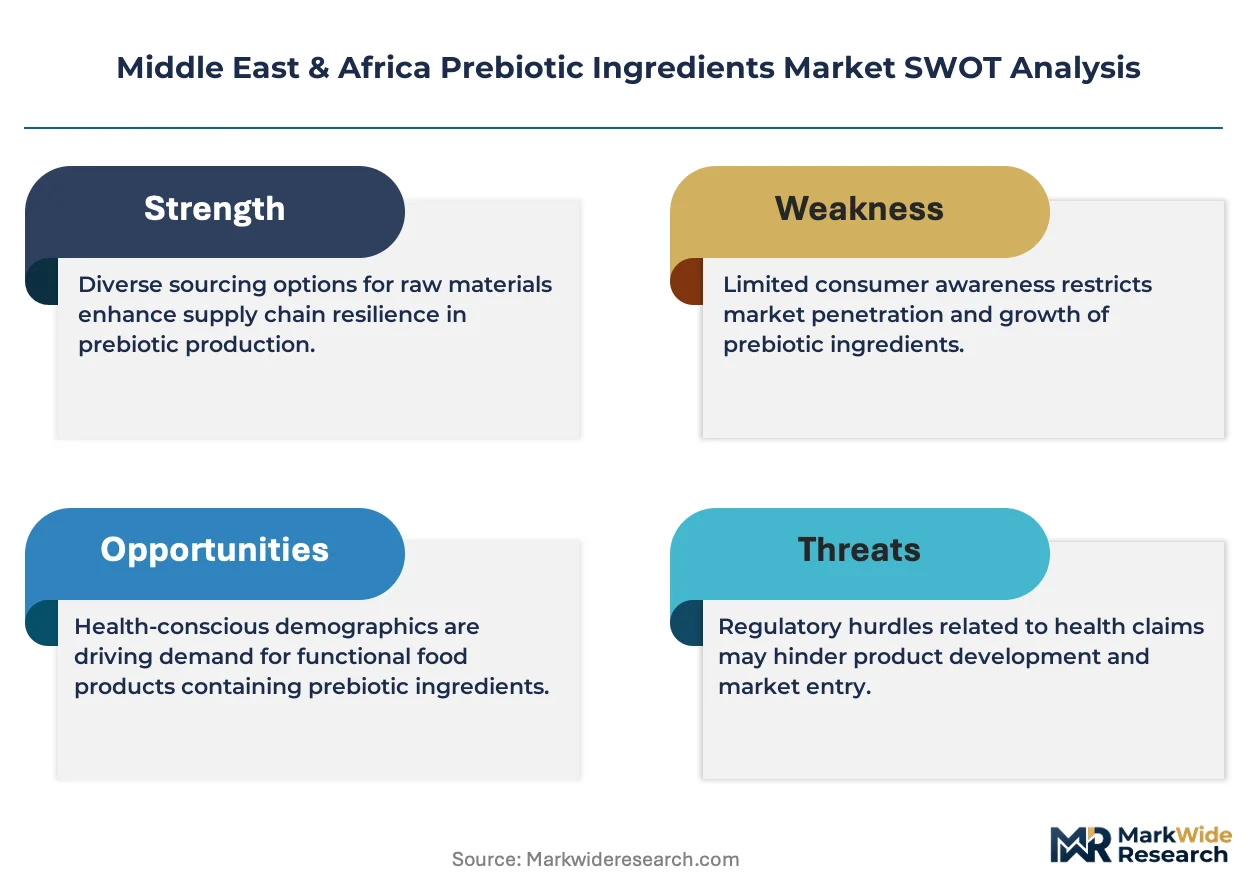
- SFDA Health Claim Substantiation:Saudi Food and Drug Authority standards on health claim verification reshape product registration timelines, compelling manufacturers to invest in clinical substantiation infrastructure that deepens competitive moats.
- Galactooligosaccharide Procurement Surge:Infant formula manufacturers across South Africa and Nigeria are expanding raw material sourcing as regional birth rates sustain formulation demand.
- Halal Certification Harmonization:Gulf Standards Organization alignment of food additive maximum levels creates cross-border compliance efficiencies for multinational suppliers serving dairy and bakery segments.
Market Restraints
- Chicory Root Input Volatility:Inulin extraction depends on hot water diffusion from chicory root, exposing processors to agricultural yield fluctuations and irrigation cost pressures across North African cultivation zones.
- Fermentation-Derived Substrate Uncertainty:Halal certification body rulings on fermentation-derived substrates remain inconsistent, forcing preemptive formulation reformulation cycles that compress margin predictability.
- South African Health Products Regulatory Authority Oversight:SAHPRA extension of complementary medicines regulation to prebiotic dietary supplements lengthens approval timelines and increases compliance expenditure for entrants.
Strategic Opportunities
- Nigerian Infant Nutrition Penetration:Underdeveloped distribution infrastructure in Nigeria's northern states creates first-mover advantage for suppliers establishing cold-chain partnerships with local dairy cooperatives.
- Functional Foods Channel Expansion:Clinical substantiation requirements and brand loyalty effects in functional foods generate the deepest margin pools, rewarding investment in halal-certified customized prebiotic blends.
- National Nutrition Strategy Alignment:Evolving government nutrition strategies across Gulf states mandate fiber fortification in processed foods, creating regulatory tailwinds for inulin suppliers.
Industry Challenges
- Microbiome Research Talent Scarcity:Gut microbiota colonization studies require specialized clinical researchers, and regional universities produce insufficient graduates trained in prebiotic-host interaction methodologies.
- Spray Drying Capex Intensity:Achieving minimum eighty-five percent dietary fiber content specifications demands capital-intensive spray drying infrastructure that mid-scale processors struggle to finance.
- Cross-Border Certification Complexity:Divergent halal certification standards between UAE's Emirates Authority for Standardization and Metrology and Saudi SFDA create documentation friction for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Prebiotic Ingredients Market |
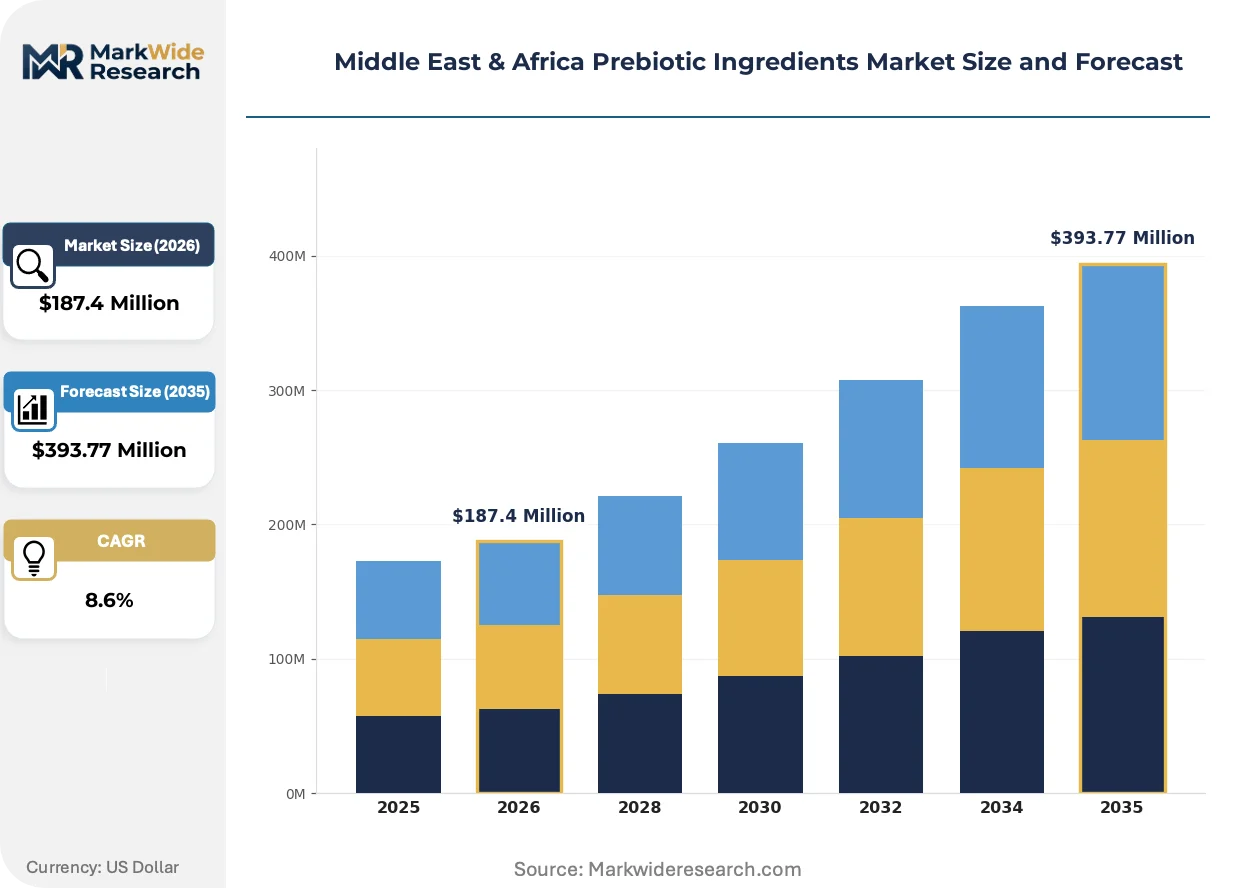
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Galactooligosaccharides, Lactic Acid Bacteria End User: Beverages, Dairy Products, Bakery Items, Nutraceuticals Application: Functional Foods, Dietary Supplements, Infant Formulas, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Fonterra Co-operative Group Limited, Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company, DSM-Firmenich, Kerry Group plc, Sensus, Baolingbao Biology Co., Ltd., Abbott Laboratories, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Prebiotic Ingredients Market Trends and Innovations
Enzymatic synthesis pathways for novel oligosaccharides are compressing production timelines while Gulf port consolidation around raw material sourcing networks reshapes competitive access to Egyptian and Saudi dairy corridors.
Second-generation galactooligosaccharide production via transgalactosylation is displacing first-generation lactose-derived processes in regional infant formula supply chains. Saudi and Nigerian manufacturers are adopting enzymatic synthesis at accelerated procurement cycles. This displacement is compressing cost structures for premium positioning while forcing legacy suppliers to retrofit extraction infrastructure.
Gulf Standards Organization harmonization of food additive maximum levels is streamlining cross-border compliance for multinational suppliers. Industrial consequence includes reduced registration duplication across UAE, Saudi Arabia, and Kuwait. Dairy and bakery segments are responding by consolidating procurement contracts around GSO-certified suppliers with Red Sea logistics capabilities.
Long-term supply agreements with chicory root cooperatives are replacing spot-market purchasing among major dairy processors. Direct farm partnerships are displacing traditional distributor intermediaries in Egypt's Nile Delta cultivation belt. This restructuring is most visible in Saudi Arabia's dairy processing corridor where beverage fortification programs demand volume predictability.
Middle East & Africa Prebiotic Ingredients Market Segmentation
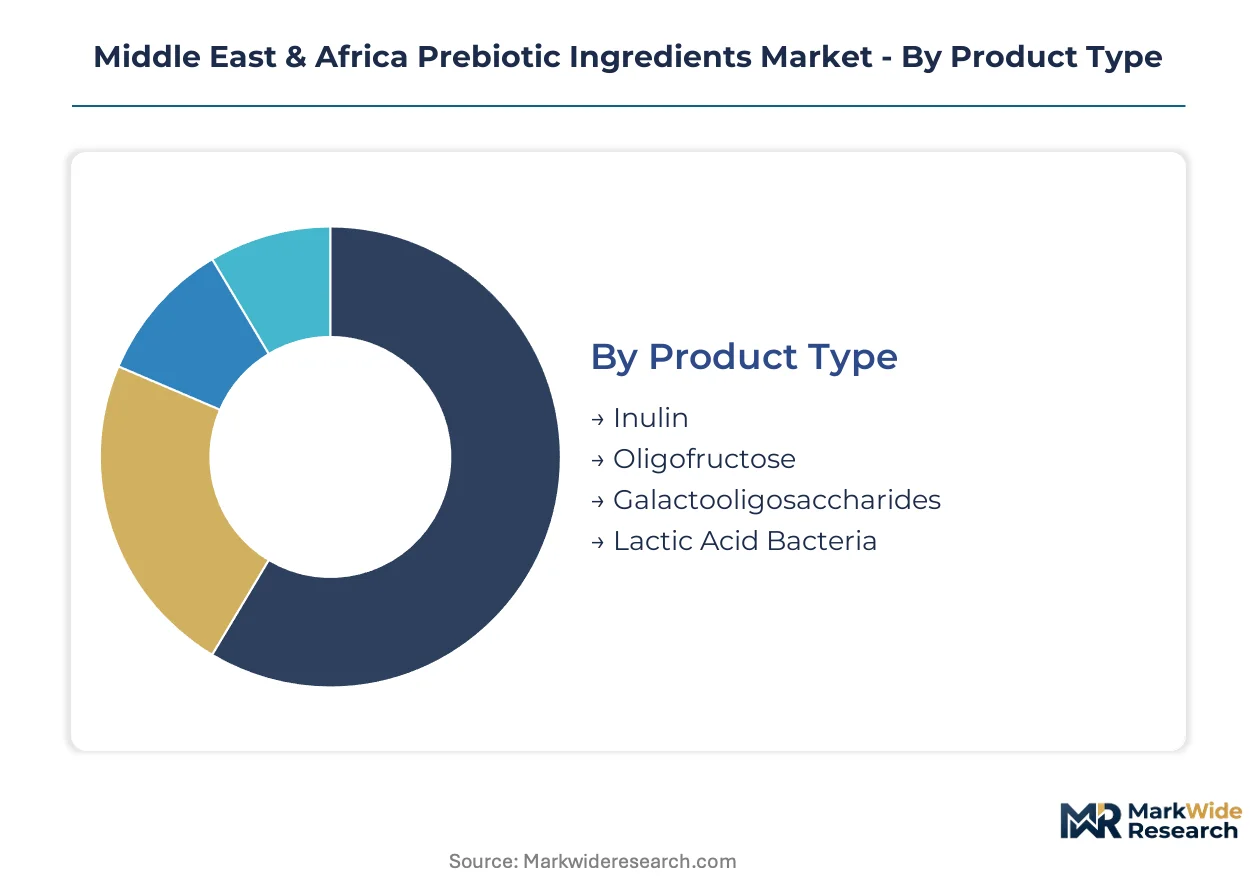
Prebiotic ingredient procurement patterns diverge sharply across product categories and end-use channels in the Middle East and Africa. Manufacturers must align formulation specifications with halal certification requirements and Gulf Standards Organization additive limits while navigating divergent customer price sensitivities.
Product Type:
Galactooligosaccharides face the most acute substitution pressure from emerging enzymatic synthesis pathways, while inulin maintains cost advantages through established chicory root supply chains.
- Inulin:Extracted from chicory root via hot water diffusion and spray drying to achieve minimum eighty-five percent dietary fiber content. Saudi Arabia's dairy processing corridor drives bulk procurement for beverage fortification programs, though North African agricultural yield fluctuations create input volatility.
- Galactooligosaccharides:Second-generation transgalactosylation production is displacing first-generation lactose-derived processes across regional infant formula supply chains. South African and Nigerian manufacturers are expanding procurement as Gulf Cooperation Council labeling requirements tighten for functional food claims.
- Oligofructose:Shorter-chain fructan with enhanced solubility targets bakery applications where moisture retention is critical.
- Lactic Acid Bacteria:Fermentation-derived substrates require careful halal certification body navigation to preempt formulation reformulation cycles.
Inulin anchors the volume base while galactooligosaccharides gain share at the steepest rate.
End User:
Cost tier stratification separates premium nutraceutical positioning from mass-market dairy and bakery penetration.
- Dairy Products:Saudi processors dominate regional inulin consumption through beverage fortification programs aligned with national nutrition strategies. Direct farm partnerships with Egyptian Nile Delta cooperatives are replacing traditional distributor intermediaries to secure volume predictability.
- Nutraceuticals:South African Health Products Regulatory Authority oversight of complementary medicines extends to prebiotic dietary supplements, lengthening approval timelines but deepening margin pools through clinical substantiation requirements.
- Beverages:Functional drink formulations concentrate procurement around Red Sea logistics capabilities for Gulf port efficiency.
- Bakery Items:Cost-sensitive formulation prevails in this segment, with oligofructose preferred for moisture retention and texture optimization.
Dairy products command the largest procurement volumes while nutraceuticals deliver the deepest margin expansion.
Application:
Application maturity varies from established infant formula standards to emerging animal feed experimentation.
- Functional Foods:Brand loyalty effects and clinical substantiation requirements generate the deepest margin pools, rewarding investment in halal-certified customized prebiotic blends. Saudi Food and Drug Authority health claim verification standards reshape product registration timelines.
- Infant Formulas:Galactooligosaccharide procurement concentrates in South Africa and Nigeria as regional birth rates sustain formulation demand and Gulf Cooperation Council safety frameworks tighten.
- Dietary Supplements:SAHPRA regulatory extension increases compliance expenditure for new entrants seeking South African market access.
- Animal Feed:Emerging application with nascent regulatory frameworks across Gulf states and North Africa.
Functional foods lead value capture while infant formulas maintain the most consistent volume trajectory.
Distribution Channel:
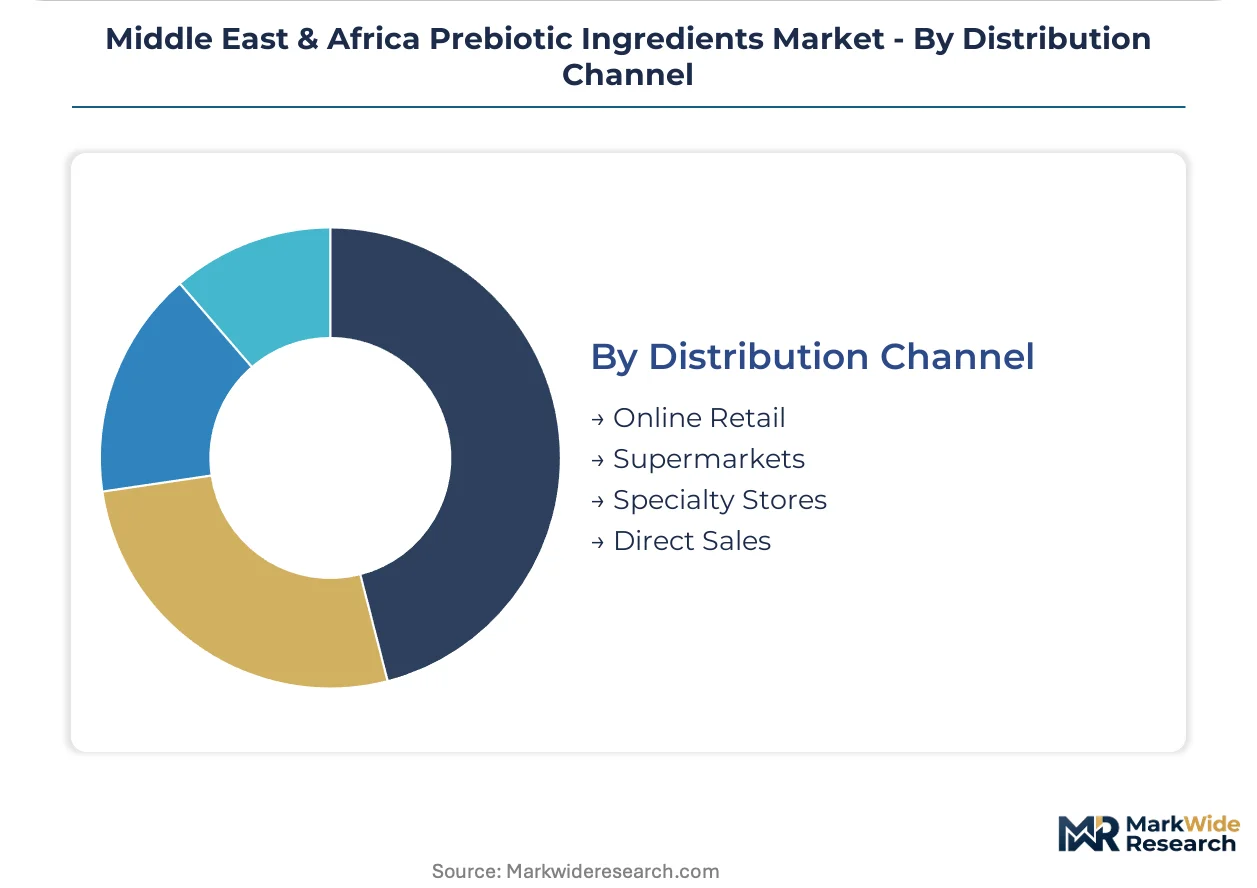
Supply concentration around Gulf ports favors direct sales and specialty store partnerships over fragmented online retail.
- Direct Sales:Long-term supply agreements with chicory root cooperatives are restructuring procurement relationships, displacing spot-market purchasing among major dairy processors. Cargill leverages Red Sea logistics infrastructure to anchor supply security for Egyptian processors.
- Specialty Stores:Halal certification documentation requirements favor certified supplier consolidation, with Kerry Group differentiating via customized prebiotic blend technical support.
- Supermarkets:Mass-market penetration channel for standard-grade inulin in consumer-packaged formats.
- Online Retail:Underdeveloped cold-chain infrastructure limits expansion in temperature-sensitive probiotic combination products.
Direct sales dominate industrial procurement volumes while specialty stores capture the premium branded segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity across the Middle East and Africa varies sharply: Gulf buyers absorb premium pricing for clinically substantiated ingredients while North African and sub-Saharan processors remain acutely sensitive to agricultural input costs.
Saudi Arabia
Saudi dairy processors drive bulk inulin consumption through beverage fortification programs aligned with national nutrition strategies. SFDA health claim substantiation standards reshape product registration timelines and deepen compliance moats. The Eastern Province dairy corridor concentrates procurement activity where direct farm partnerships with Egyptian cooperatives secure volume predictability.
United Arab Emirates
UAE functional food manufacturers command premium positioning for halal-certified customized prebiotic blends. Emirates Authority for Standardization and Metrology maintains additive maximum levels that diverge from Saudi SFDA standards, creating documentation friction. Dubai's logistics infrastructure anchors Red Sea supply security for multinational distributors serving Gulf markets.
South Africa
South African infant formula manufacturers expand galactooligosaccharide procurement as regional birth rates sustain formulation demand. SAHPRA oversight of complementary medicines extends to prebiotic dietary supplements, lengthening approval timelines. Gauteng's pharmaceutical manufacturing cluster concentrates nutraceutical production where clinical substantiation requirements generate the deepest margin pools.
Nigeria
Nigerian infant nutrition penetration remains underdeveloped in northern states where distribution infrastructure gaps persist. National Agency for Food and Drug Administration and Control regulates prebiotic health claims with evolving enforcement intensity. Lagos-based dairy cooperatives present first-mover partnership opportunities for suppliers establishing cold-chain capabilities.
Egypt
Egyptian processors face acute chicory root input volatility from Nile Delta agricultural yield fluctuations and irrigation cost pressures. The country's national food safety regulator aligns gradually with Gulf Standards Organization harmonization efforts. Alexandria and Damietta port zones concentrate extraction infrastructure where spray drying capex requirements filter mid-scale entrants.
Middle East & Africa Prebiotic Ingredients Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East and Africa prebiotic ingredients market. Multinationals with captive Red Sea logistics capabilities and Gulf port consolidation advantages command supply security contracts with major dairy processors. Specialist archetypes include fermentation-derived substrate innovators and halal certification technical advisors. Competitive moves concentrate on long-term supply agreements with chicory root cooperatives and enzymatic synthesis pathway investments that compress production timelines.
Within the integrated multinational tier, Cargill Incorporated and Kerry Group plc occupy anchor positions shaped by logistics infrastructure and formulation customization capabilities respectively. Fonterra Co-operative Group Limited exemplifies the Oceania-to-Middle East cold chain specialist archetype. These three entities represent distinct competitive vectors: Cargill leverages Red Sea supply security, Kerry differentiates through halal-certified blend technical support, and Fonterra competes via temperature-controlled distribution networks.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Ingredion Incorporated |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| Kerry Group plc |
| Sensus |
| Baolingbao Biology Co., Ltd. |
| Abbott Laboratories |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day inventory cycles at Egyptian chicory root processors concentrate pricing power among Red Sea-anchored multinationals while compressing margin buffers for mid-scale dairy formulators dependent on spot purchasing.
Pricing Analysis
After-sales technical support and halal certification documentation services drive lifetime value capture for ingredient suppliers. Three-tier pricing structure across premium, standard, and economy levels separates GSO-certified clinical-grade galactooligosaccharides from bulk inulin and commodity oligofructose. Price differentiation rests on halal certification tier and volume scale commitments. Cost compression in standard-grade inulin intensifies as Egyptian direct-farm partnerships displace distributor markups. Nigerian infant formula manufacturers exhibit acute price sensitivity while Saudi beverage fortification programs absorb premium positioning for clinically substantiated blends.
Supply Chain Analysis
Inventory cycles stretching beyond sixty days at Nile Delta chicory cooperatives expose processors to agricultural yield volatility and irrigation cost pressures. Geographic supply concentration centers on Egypt for chicory root extraction, Saudi Arabia for dairy corridor demand absorption, and South Africa for infant formulation manufacturing. Raw material dependencies include chicory root biomass, lactose feedstock for enzymatic synthesis, and fermentation-derived substrate cultures. Single-source vulnerability runs through Egyptian irrigation-dependent cultivation zones. Distribution runs through Gulf port consolidation with Red Sea logistics capabilities anchoring supply security contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic synthesis pathway maturation and Gulf Standards Organization harmonization are compressing production timelines and cross-border compliance costs, creating a high-growth disruption window for positioned suppliers.
For Market Incumbents: Shield formulation partnerships through captive chicory root cooperative agreements and preemptive halal certification body engagement. Second-generation transgalactosylation investment displaces legacy lactose-derived process exposure. Backward integration into Egyptian Nile Delta cultivation secures volume predictability against agricultural yield volatility. For New Entrants and Emerging Players: Differentiate on customized prebiotic blend technical support for halal-certified functional food manufacturers. Northern Nigerian states present underdeveloped distribution infrastructure with first-mover cold-chain partnership potential. Target SAHPRA-registered nutraceutical positioning where clinical substantiation requirements deepen margin pools and extend approval timeline barriers. For Investors and Strategic Acquirers: Long-term, this sits as a nutrition-security infrastructure play because Gulf national strategies mandate fiber fortification with regulatory tailwind durability. Acquisition target archetype: fermentation-derived substrate innovators with established halal certification body relationships. Watch for SFDA health claim substantiation standard tightening as margin compression signal for undifferentiated bulk suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct farm partnerships with Egyptian cooperatives displace spot-market purchasing volatility for Saudi dairy processors. |
| Enzymatic Synthesis Investment | Second-generation transgalactosylation compresses galactooligosaccharide production timelines and cost structures. |
| Halal Certification Harmonization | GSO-aligned documentation reduces registration duplication across UAE, Saudi Arabia, and Kuwait markets. |
| Clinical Substantiation Infrastructure | SFDA health claim verification requirements deepen competitive moats for substantiated functional food positioning. |
| Cold-chain Partnership Development | Lagos-based dairy cooperative alliances unlock Nigerian northern state infant nutrition penetration. |
Research Methodology
A standing panel of dairy procurement directors, infant formula regulatory affairs leads, halal certification technical advisors, and chicory root cooperative managers provided ongoing calibration across the analysis window. Primary interview insights combined with secondary validation from SFDA registration databases, GSO additive maximum level harmonization documents, SAHPRA complementary medicines guidance, and Egyptian agricultural ministry cultivation statistics. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value outputs.
Consistency checks against external benchmarks validated projections across the modeling period. Analytical framework segmented by product type, end-use application, and halal certification tier while modeling regional demand elasticity differentials. CAGRs derived from historical trajectory analysis and regulatory inflection impact assessment. Forecast inputs included enzymatic synthesis adoption curves and Gulf nutrition strategy implementation timelines.
Material uncertainties — chicory root yield fluctuations, halal certification body ruling inconsistencies, and SAHPRA enforcement intensity evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Low Fat Oil Market
Ingredients
Ice Cream Bases Market
Ingredients
Gymnema Extract Market
Ingredients
Meat Starter Culture Market
Ingredients
Global Pulse Flours Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
North America Carrageenan Market
Ingredients
Food Colors Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Wheat Malt Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Global Dry Yeast Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Soluble Fibers Market