
 USA Prenatal Vitamin Supplements Market | 2026-2036
USA Prenatal Vitamin Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
USA Prenatal Vitamin Supplements Market Analytics
Direct-to-consumer channels is pivoting as millennial and Gen-Z expecting parents shift from traditional pharmacy purchases toward personalized subscription models. Abbott Laboratories leverages its clinical heritage and healthcare provider relationships to anchor institutional prescribing patterns. Garden of Life competes through organic certification and whole-food positioning that resonates with clean-label consumers. Nordic Naturals differentiates via marine-derived DHA specialization and third-party purity testing protocols.
USA prenatal vitamin supplements encompass formulated nutritional products containing folic acid, iron, DHA, calcium, and complementary micronutrients manufactured through tablet compression, gummy confection, powder blending, or liquid emulsification processes. These supplements function to reduce neural tube defects, support fetal neurodevelopment, and correct gestational anemia in pregnant women. Gummies now capture disproportionate growth velocity as palatability concerns drive switching from conventional tablets among nausea-prone first-trimester users. DHA ingredient positioning commands premium shelf space as omega-3 fatty acid awareness penetrates obstetric practice guidelines. Online retail channels extract margin expansion through subscription bundling and algorithmic replenishment that reduces customer acquisition costs relative to brick-and-mortar pharmacy placements.
FDA Center for Food Safety and Applied Nutrition oversees dietary supplement manufacturing under 21 CFR Part 111 current Good Manufacturing Practices, while USP verification programs create de facto market access thresholds for hospital and clinic formularies. State-level Medicaid prenatal nutrition benefit expansions in California and New York amplify formulary inclusion pressure on manufacturers. Stakeholders must monitor evolving ACOG micronutrient guideline revisions and state Medicaid reimbursement policy shifts that could restructure channel economics and ingredient specification requirements.
Market Dynamics
Direct-to-consumer subscription models are compressing traditional pharmacy channels as millennial and Gen-Z expecting parents demand personalized prenatal nutrition regimens with algorithm-driven replenishment cycles.
Growth Catalysts
- Medicaid prenatal nutrition benefit expansions:California and New York state-level program broadening creates formulary inclusion pressure that pulls manufacturers into institutional procurement channels.
- ACOG micronutrient guideline revisions:Updated obstetric practice recommendations elevate DHA and choline specifications, driving ingredient portfolio upgrades across tablet and gummy formats.
- Metropolitan corridor demand concentration:Fertility clinic density and wellness retail penetration in Texas urban centers generate localized volume spikes that reward distribution infrastructure investments.
Market Restraints
- USP verification compliance costs:Third-party purity testing protocols and certification timelines create capital intensity barriers for mid-tier manufacturers seeking hospital formulary access.
- Marine-derived DHA supply concentration:Omega-3 fatty acid sourcing dependence on Peruvian and Norwegian fisheries exposes formulations to catch volatility and price fluctuation risk.
- 21 CFR Part 111 manufacturing standards:FDA current Good Manufacturing Practices enforcement creates documentation and facility upgrade burdens that compress operating margins for smaller producers.
Strategic Opportunities
- First-trimester nausea-responsive gummy formats:Palatability-driven switching from conventional tablets creates white space for chewable and emulsified delivery innovations targeting morning-sickness-prone users.
- Subscription bundling with fertility tracking apps:Digital health platform partnerships enable algorithmic replenishment integration that locks in customer lifetime value ahead of conception planning cycles.
- State Medicaid reimbursement policy alignment:Texas and Florida benefit structure evolution creates tailwinds for manufacturers achieving therapeutic nutrition classification in public program formularies.
Industry Challenges
- Clean-label certification complexity:Organic and non-GMO verification timelines delay product launches as supply chain documentation requirements intensify for whole-food positioning claims.
- Multi-channel inventory synchronization:DTC subscription fulfillment, pharmacy wholesale, and clinic direct-ship operations demand warehouse management system upgrades that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Prenatal Vitamin Supplements Market |
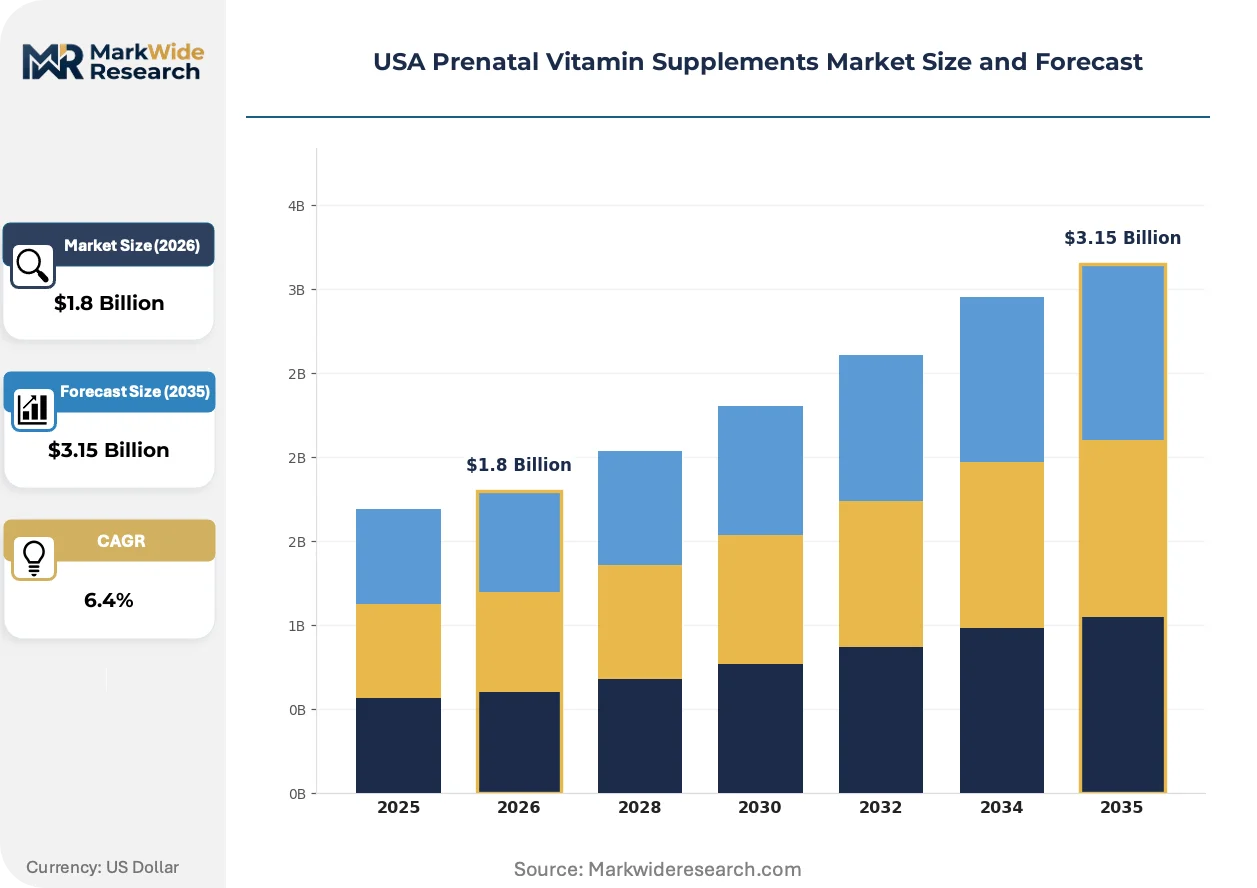
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Gummies, Powders, Liquid Ingredient Type: Folic Acid, DHA, Iron, Calcium Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores End User: Pregnant Women, Healthcare Providers, Nutritionists, Expecting Couples |
| Companies Covered | Church & Dwight Co., Inc., Abbott Laboratories, Garden of Life, Rainbow Light Nutritional Systems, Biotics Research Corporation, Country Life, MegaFood, New Chapter, Nordic Naturals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Prenatal Vitamin Supplements Market Evolving Landscape
Personalized nutrition platforms and ingredient traceability systems are converging to reshape how expecting parents discover, purchase, and adhere to prenatal supplementation protocols across digital and physical touchpoints.
Precision dosing algorithms are converging with at-home micronutrient testing kits to enable individualized folate and iron recommendations based on genetic polymorphism profiles and serum level data. Functional medicine practitioners and fertility clinics are piloting these integrated assessment-to-supplement workflows. This convergence is compressing the gap between diagnostic insight and nutritional intervention, shifting competitive advantage toward platforms owning both data collection and fulfillment infrastructure.
FDA dietary supplement labeling requirements under 21 CFR Part 101 are tightening structure-function claim substantiation standards and mandating clearer pregnancy-specific warning language. Manufacturers face reformulation costs and packaging redesign cycles to maintain shelf placement in institutional channels. Hospital and clinic formularies are responding by elevating USP-verified products in procurement scoring matrices, privileging documentation depth over price positioning.
Millennial and Gen-Z buyers are abandoning episodic pharmacy purchases in favor of subscription-based replenishment models bundled with educational content and trimester-specific formulation rotations. DTC platforms are capturing this behavioral shift through mobile-first onboarding flows and predictive shipping algorithms. California and New York metropolitan markets exhibit the highest subscription penetration rates, correlating with fertility clinic density and wellness retail ecosystem maturity.
USA Prenatal Vitamin Supplements Market Segmentation
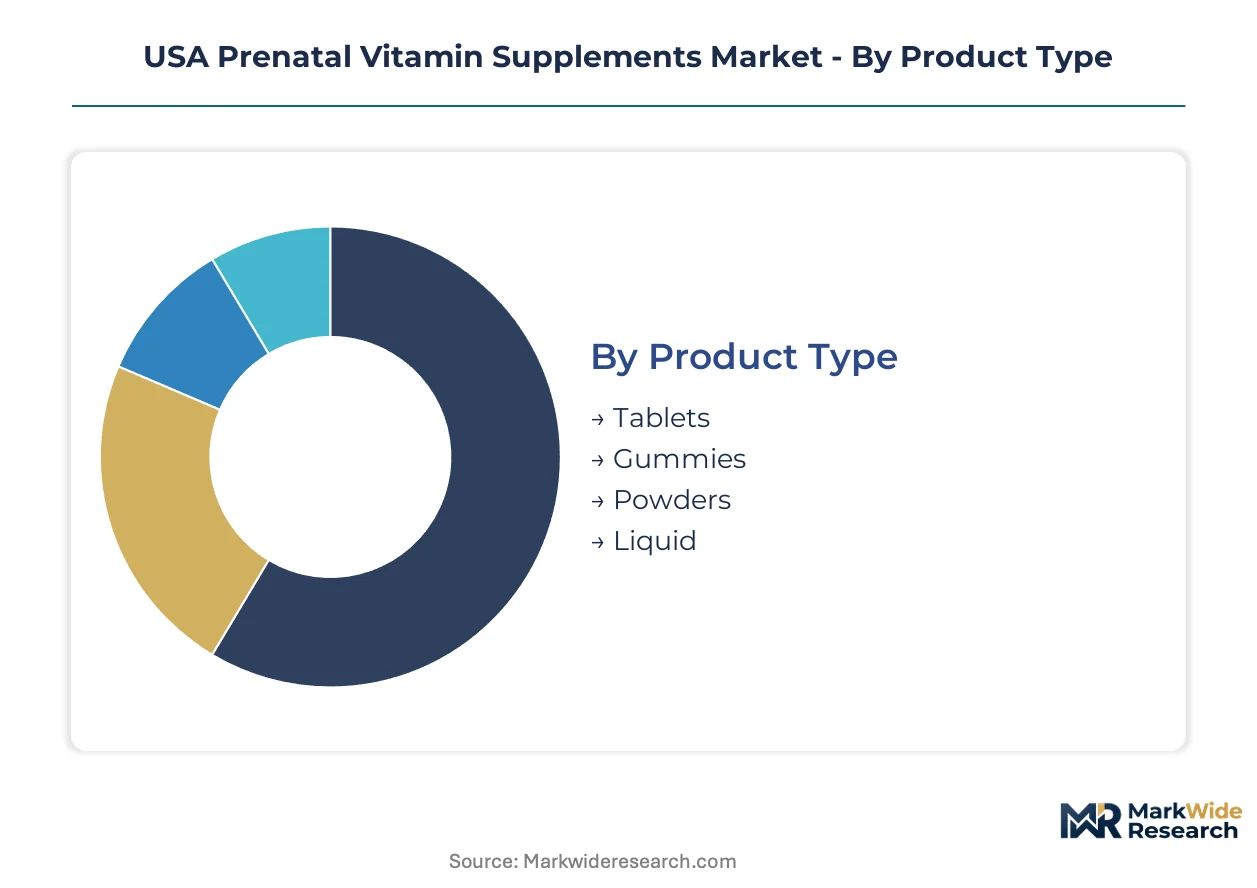
Prenatal vitamin segmentation reveals divergent purchasing behaviors across format preferences, ingredient priorities, and channel access patterns. Manufacturers calibrate formulation, packaging, and distribution investments against these fracture lines to capture lifetime value from conception through lactation cycles.
Product Type:
Format selection reflects trimester-specific physiological tolerance and adherence psychology rather than uniform efficacy profiles.
- Tablets:Compressed formulations deliver precise micronutrient dosing with extended shelf stability. Volume concentrates among managed care formularies in Texas and California where institutional procurement favors unit-dose compliance packaging.
- Gummies:Gelatin or pectin-based matrices mask metallic mineral tastes that trigger first-trimester aversion. Palatability-driven switching accelerates fastest in metropolitan New York wellness retail corridors where nausea-prone users abandon conventional tablets.
- Powders:Blended concentrates enable beverage integration for consumers rejecting solid dosage forms. Demand clusters among functional medicine practitioners in California recommending customized mixing protocols.
- Lipid emulsion liquids:Liposomal delivery systems enhance fat-soluble vitamin bioavailability for malabsorption cases. Prescription-channel positioning limits mass-market penetration.
Volume sits with tablets; growth tilts toward gummies.
Ingredient Type:
Raw material sourcing geography and clinical evidence depth determine premium positioning and formulary inclusion hierarchy.
- DHA:Marine-derived omega-3 concentrates from Peruvian anchovy fisheries anchor neurodevelopment claims. Supply volatility from catch quota fluctuations compresses margin stability for formulations dependent on Norwegian or South American sourcing.
- Folic Acid:Synthetic pteroylmonoglutamic acid remains the neural tube defect prevention standard in USP-verified hospital formularies. Medicaid reimbursement protocols in California mandate minimum 400mcg specification thresholds.
- Iron:Ferrous bisglycinate and fumarate salts address gestational anemia with reduced gastrointestinal side effect profiles. Ferrous sulfate economics dominate mass-market tablet formulations.
- Calcium:Carbonate and citrate salts support fetal skeletal mineralization alongside maternal bone density preservation. Dairy-free positioning gains traction among lactose-intolerant demographic segments.
Formulary access clusters around folic acid; DHA commands the steepest expansion trajectory.
Distribution Channel:
Channel economics diverge sharply between subscription lifetime value extraction and transactional pharmacy margin structures.
- Online Retail:Algorithmic replenishment platforms capture California and New York millennial cohorts through trimester-specific bundle rotations. Customer acquisition cost efficiency improves with fertility app data integration.
- Pharmacies:Chain and independent drugstores retain institutional prescription fulfillment and emergency replenishment traffic. 21 CFR Part 111 compliance documentation supports USP verification display priorities.
- Supermarkets:Mass-market gummy placements leverage impulse purchase behavior in grocery trip consolidation patterns. Shelf space allocation competes against general wellness supplement categories.
- Health Stores:Whole-food and organic-certified positioning resonates with clean-label seekers in Texas metropolitan wellness retail clusters. Staff consultation dependency limits scalability.
Transaction volume flows through pharmacies; subscriber lifetime value accumulates fastest in online retail.
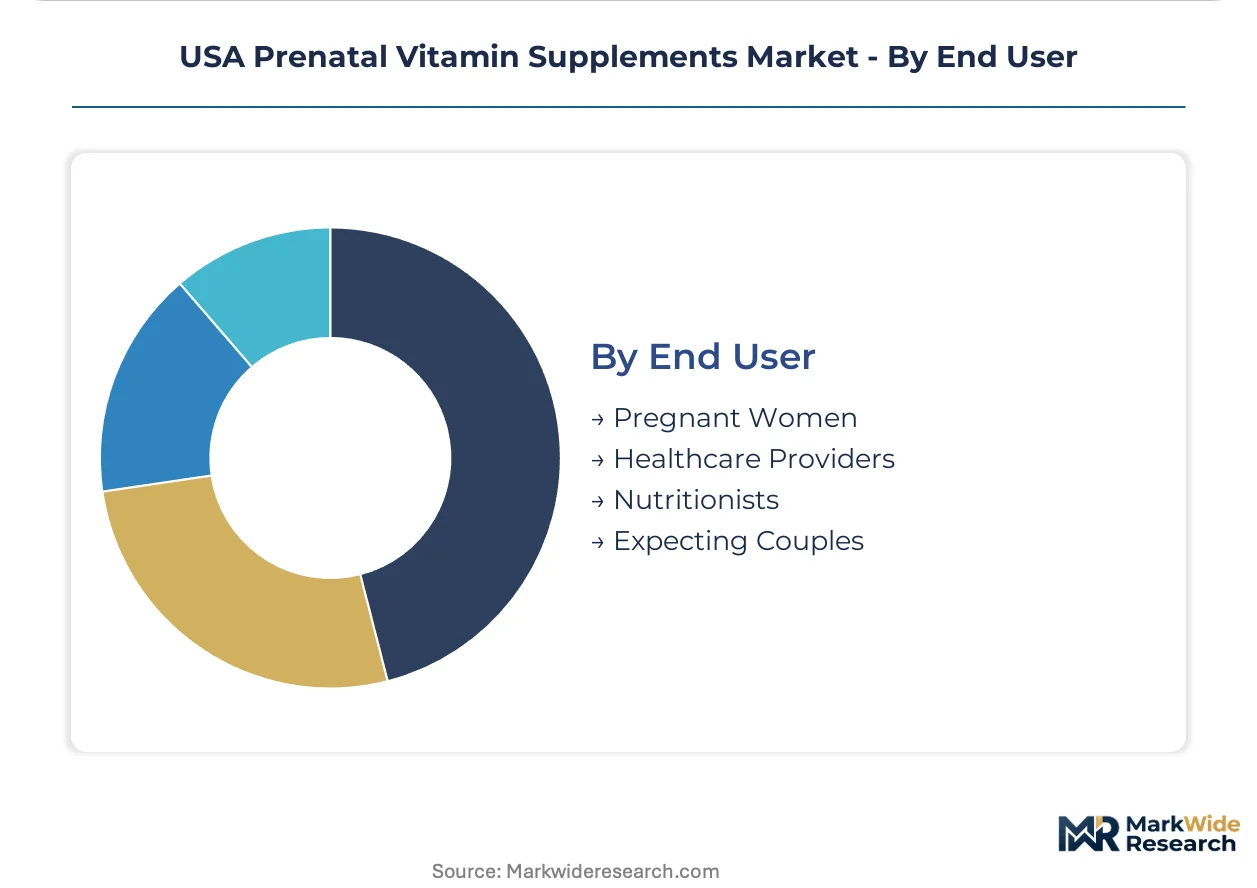
End User:
Purchasing authority and information-seeking behavior fragment across clinical recommendation dependency versus autonomous research patterns.
- Pregnant Women:First-time mothers exhibit highest price elasticity and brand experimentation before settling into trimester-specific adherence routines. Nausea severity in weeks 6-12 drives format switching decisions.
- Healthcare Providers:Obstetricians and midwives function as gatekeepers through prenatal visit sample distribution and formulary specification. Institutional procurement in fertility clinics concentrates volume among USP-verified manufacturers.
- Nutritionists:Registered dietitians recommend condition-specific formulations for high-risk pregnancies including multiple gestations or pre-existing deficiencies. Functional medicine practitioners in California favor methylated folate alternatives.
- Expecting Couples:Male partners increasingly participate in preconception supplementation purchasing, expanding addressable market beyond gestational users alone. Shared decision-making elevates subscription model appeal.
Direct consumption concentrates among pregnant women; prescription influence flows through healthcare providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in California and Texas metropolitan corridors concentrate prenatal supplement demand through fertility clinic density and wellness retail penetration. State-level Medicaid benefit expansions in New York and Florida amplify formulary inclusion pressure. Distribution infrastructure investments track urban population clusters where millennial and Gen-Z expecting parents cluster.
California
Los Angeles and San Francisco fertility clinic networks drive institutional procurement volume for USP-verified formulations. Medi-Cal prenatal nutrition benefit expansions mandate minimum 400mcg folic acid specifications in covered products. Silicon Valley wellness retail corridors exhibit highest direct-to-consumer subscription penetration rates nationally.
Texas
Houston and Dallas obstetric practice networks generate concentrated prescription-channel demand for tablet formats. State Medicaid formulary evolution creates procurement opportunities for manufacturers achieving therapeutic nutrition classification. Austin functional medicine practitioners favor methylated folate and whole-food positioning claims.
New York
Manhattan and Brooklyn millennial cohorts drive gummy format growth through nausea-responsive palatability preferences. State-level Medicaid reimbursement protocols exceed federal minimums for prenatal nutrition coverage. Upstate fertility clinic expansion extends formulary inclusion pressure beyond metropolitan cores.
Florida
Miami and Tampa wellness retail ecosystems support clean-label and organic-certified product positioning. State Medicaid managed care contracts increasingly specify prenatal vitamin coverage in maternal health bundles. Jacksonville distribution hubs serve southeastern pharmacy wholesale channels.
Illinois
Chicago metropolitan fertility clinic density anchors institutional procurement for hospital formularies. State Medicaid prenatal benefit structures align with ACOG micronutrient guideline revisions. Midwest pharmacy chain headquarters concentrate wholesale purchasing decisions affecting national distribution economics.
USA Prenatal Vitamin Supplements Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical heritage players anchoring institutional channels and organic-certified specialists capturing wellness retail. The vendor base organizes into three tiers: multinational healthcare conglomerates with clinical validation infrastructure, mid-scale whole-food positioning specialists, and private-label contract manufacturers serving pharmacy chains. Consolidation pressure concentrates among mid-tier players facing USP verification compliance cost barriers. Dominant competitive moves include fertility clinic formulary exclusivity agreements and direct-to-consumer subscription platform acquisitions.
Among pharmaceutical heritage players, Abbott Laboratories occupies a position exemplifying clinical validation and healthcare provider relationship depth. Garden of Life and Nordic Naturals represent the clean-label and marine-derived specialization archetypes respectively, with the former exemplifying organic certification positioning and the latter anchoring third-party purity testing protocols. These three companies illustrate how divergent strategic vectors—clinical institutional access, whole-food transparency, and omega-3 sourcing specialization—can coexist within the same market structure without direct feature-for-feature competition.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Abbott Laboratories |
| Garden of Life |
| Rainbow Light Nutritional Systems |
| Biotics Research Corporation |
| Country Life |
| MegaFood |
| New Chapter |
| Nordic Naturals |
| Others |
Value Network & Pricing Analysis
Backward integration into marine-derived DHA sourcing anchors both supply security and premium pricing power for manufacturers seeking formulary access. Captive control over Peruvian anchovy and Norwegian cod liver oil procurement buffers against catch quota volatility while supporting USP verification compliance costs passed through to hospital channels.
Pricing Analysis
Short lead-time premiums attach to subscription-based algorithmic replenishment models that lock in millennial and Gen-Z cohorts ahead of conception planning cycles. Three-tier pricing structure across premium, standard, and economy levels separates USP-verified clinical formulations from organic-certified wellness retail positioning and mass-market pharmacy generics. Cost compression in economy tablet tiers is intensifying because ferrous sulfate commodity sourcing faces ferrous bisglycinate substitution pressure. First-time pregnant women exhibit highest price elasticity before trimester-specific adherence routines solidify, while fertility clinic procurement committees show lowest sensitivity due to formulary specification mandates.
Supply Chain Analysis
Single-source vulnerability sits with Peruvian anchovy fisheries that feed marine-derived DHA concentrate production for neurodevelopment claims. Raw material procurement draws from Norwegian cod liver operations, Chinese gelatin substrates for gummy matrices, and Indian synthetic folic acid manufacturers. Tariff exposure on imported omega-3 concentrates compounds margin pressure when catch quotas tighten. Distribution runs through pharmacy wholesale hubs in Illinois and Texas, direct-to-consumer fulfillment centers in California, and clinic direct-ship operations anchored to metropolitan fertility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where USP verification compliance costs and FDA 21 CFR Part 111 facility upgrade burdens force mid-tier manufacturers toward strategic exit or acquisition.
For Market Incumbents: Anticipate margin compression from DHA supply volatility and Medicaid formulary inclusion pressure by deepening captive sourcing agreements with Peruvian fisheries and accelerating methylated folate portfolio diversification. Reinforce hospital channel control through exclusive fertility clinic formulary contracts that elevate switching costs for institutional procurement committees. For New Entrants and Emerging Players: Precision dosing algorithms paired with at-home micronutrient testing kits offer a technology-first wedge into California functional medicine practitioner networks and New York metropolitan wellness retail corridors. Target first-trimester nausea-responsive gummy innovations as the most penetrable white space, deploying fertility app partnership integrations for algorithmic replenishment customer acquisition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pharmaceutical heritage players seeking organic-certified whole-food positioning to complement clinical portfolios. Long-term viability favors manufacturers with dual USP verification and Medicaid formulary inclusion across multiple state benefit structures. Watch ACOG micronutrient guideline revision timing as the critical inflection signal for DHA and choline specification upgrades that trigger portfolio obsolescence cycles.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Achievement | FDA 21 CFR Part 111 compliance opens hospital formulary access in California and Texas networks. |
| Fertility App Platform Integration | Algorithmic replenishment partnerships with Silicon Valley digital health platforms lock subscriber lifetime value. |
| Methylated Folate Portfolio Expansion | Functional medicine practitioner preference in Austin and Los Angeles drives premium positioning. |
| Peruvian Fishery Sourcing Agreement | Captive DHA supply buffers against Norwegian catch quota volatility and price spikes. |
| Medicaid Formulary Inclusion | Therapeutic nutrition classification in New York and Florida benefit structures secures institutional volume. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with obstetric practice administrators, fertility clinic procurement managers, pharmacy chain category buyers, and registered dietitian nutritionists validated demand-side assumptions. FDA 21 CFR Part 111 inspection databases, USP verification program listings, and state Medicaid formulary documents supplemented bottom-up manufacturer capacity estimates against top-down demand triangulation.
Reconciliation of shipment data, channel inventory turns, and subscription platform disclosed metrics informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, ingredient composition, distribution channel, and metropolitan corridor density. CAGRs were derived from curve-fitting historical trajectory patterns against Medicaid benefit expansion schedules and ACOG guideline revision probability assessments.
Several conditions sit outside the modeled scope, including unforeseen FDA enforcement actions, abrupt fishery catch quota suspensions, and state-level Medicaid reimbursement policy reversals. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Lactates Market