
 Vitamin B Market | 2026-2036
Vitamin B Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin B Market Analysis
A shift from single-source to multi-source raw material procurement is expanding across the Vitamin B supply base. DSM Nutritional Products leverages its integrated fermentation capabilities to secure consistent precursor supply for B12 synthesis. Lonza Group anchors its position through specialized biotechnology platforms that sustain high-purity B-vitamin output. BASF SE competes on manufacturing scale, operating large-volume riboflavin production facilities that dominate feed-grade supply.
Vitamin B encompasses a family of eight water-soluble coenzymes—thiamine, riboflavin, niacin, pantothenic acid, pyridoxine, biotin, folate, and cobalamin—each serving as essential metabolic cofactors in cellular energy production, synthesized industrially through chemical synthesis or microbial fermentation with purity grades ranging from feed-quality to pharmaceutical-grade. The primary commercial purpose spans human nutritional supplementation, food fortification, and livestock feed additives to prevent deficiency disorders. B12 and B3 variants command premium positioning within the product type matrix due to complex manufacturing requirements and concentrated therapeutic demand. Powders and capsules lead the form segmentation, with powders capturing bulk feed applications and tablets dominating retail supplement channels. The application landscape tilts toward dietary supplements as direct-to-consumer wellness spending accelerates, while fortified foods retain stable institutional demand from milling and dairy processing industries.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements under 21 CFR Part 111, mandating identity, purity, and composition verification that elevates quality compliance costs for market participants. EFSA establishes population reference intakes and novel food safety assessments within Europe, directly influencing B-vitamin fortification thresholds and label claim permissibility. China's NMPA and SAMR administer blue-hat health food registration requirements that gate market access for imported supplement formulations. Stakeholders must monitor evolving bioequivalence standards for synthetic versus fermentation-derived B-vitamins as regulatory science advances and consumer preference for natural-origin labeling intensifies.
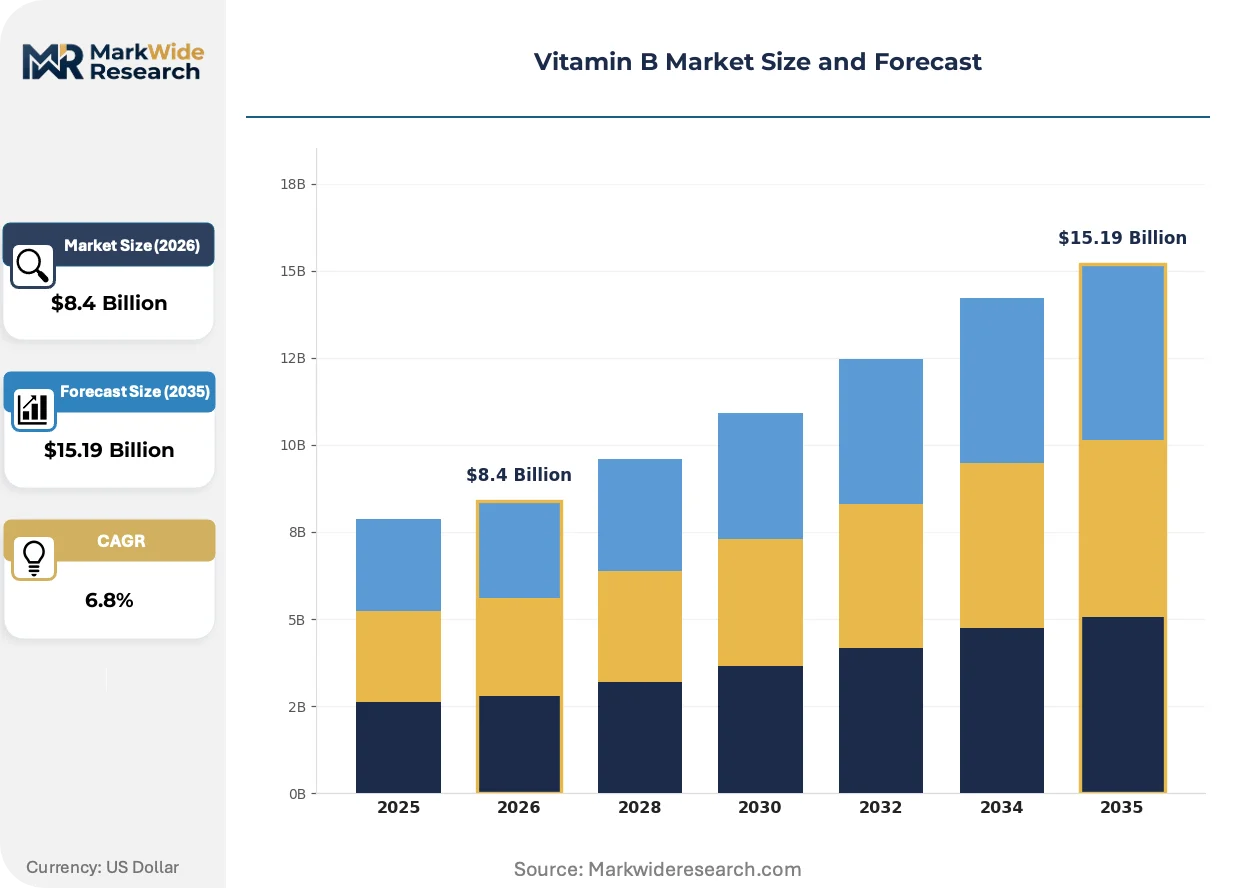
Market Dynamics
Fermentation-derived B-vitamin production is displacing chemical synthesis as the dominant manufacturing paradigm, reshaping capital allocation and supplier qualification requirements across the supply base.
Growth Catalysts
- EFSA Novel Food Safety Assessments:Clearance pathways for fermentation-derived B-vitamins in Europe are accelerating biotech platform investments by ingredient suppliers seeking premium positioning.
- Dietary Supplement Channel Expansion:Direct-to-consumer wellness platforms are capturing margin previously held by pharmaceutical retail, pulling volume through capsule and tablet formats.
- China SAMR Blue-Hat Registration:Streamlined health food approvals for domestic B-complex formulations are concentrating manufacturing investment in Shandong and Zhejiang provinces.
Market Restraints
- Corn-Derived Precursor Volatility:Feedstock costs for microbial fermentation fluctuate with agricultural commodity cycles, compressing margin predictability for B12 and B2 producers.
- Single-Site Fermentation Concentration:Pharmaceutical-grade cobalamin synthesis clusters in three integrated facilities globally, creating supply interruption exposure.
- Synthetic-Fermentation Bioequivalence Standards:Pending FDA guidance on equivalence testing is delaying label claim expansions for natural-origin positioned products.
Strategic Opportunities
- India FSSAI Fortification Mandates:Mandatory wheat and rice enrichment programs are institutionalizing B-vitamin demand outside discretionary supplement channels.
- Precision Fermentation Convergence:Integration of CRISPR-edited strains with continuous bioprocessing is opening therapeutic-grade B12 production at nutraceutical cost structures.
- Veterinary Nutraceutical Channel:Companion animal supplement platforms are absorbing human-grade B-vitamin overcapacity through cross-species formulation licensing.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Industrial-scale fermentation expertise concentrates in legacy antibiotic and enzyme producers, constraining new entrant scale-up velocity.
- Multi-Jurisdiction Label Harmonization:Divergent FDA, EFSA, and NMPA daily value reference ranges force SKU proliferation and inventory fragmentation.
- Legacy Chemical Synthesis Asset Stranding:Depreciated riboflavin and niacin plants face accelerated obsolescence as fermentation yields improve, complicating capital recovery planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin B Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: B1, B2, B3, B12 Form: Capsules, Tablets, Powders, Liquids Application: Dietary Supplements, Fortified Foods, Pharmaceuticals, Animal Feed Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | BASF SE, DSM Nutritional Products, Bayer AG, Pharmavite, Nature's Bounty, NOW Health Group, Lonza Group, Nutraceutical International Corporation, Herbalife Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin B Market Emerging Trajectories
Biotechnology platforms and regulatory science are converging to redefine manufacturing economics and product positioning in B-vitamin markets.
Precision fermentation using engineered Propionibacterium and Pseudomonas strains is decentralizing cobalamin production from centralized chemical plants to distributed bioreactor networks. Contract development and manufacturing organizations are capturing mid-scale B12 orders previously reserved for captive BASF and DSM facilities. This geographic redistribution is compressing logistics costs for Asian and Latin American supplement formulators while fragmenting supplier concentration.
China's NMPA and SAMR are tightening blue-hat health food registration requirements for imported B-vitamin complexes, mandating domestic clinical trial data and manufacturing site inspections. Foreign brands are responding by establishing joint-venture production within China or ceding market share to domestic competitors with established regulatory pathways. The policy shift is accelerating localization of formulation and packaging operations for premium supplement lines.
Direct-to-consumer subscription platforms are displacing retail pharmacy as the primary discovery channel for B-complex products, particularly among urban professionals seeking personalized dosing protocols. These platforms capture consumer preference data that informs SKU development, shortening product cycle times relative to institutional buyers. The channel shift is most pronounced in the United States and United Kingdom, where telehealth-integrated supplement prescribing is normalizing.
Vitamin B Market Segmentation
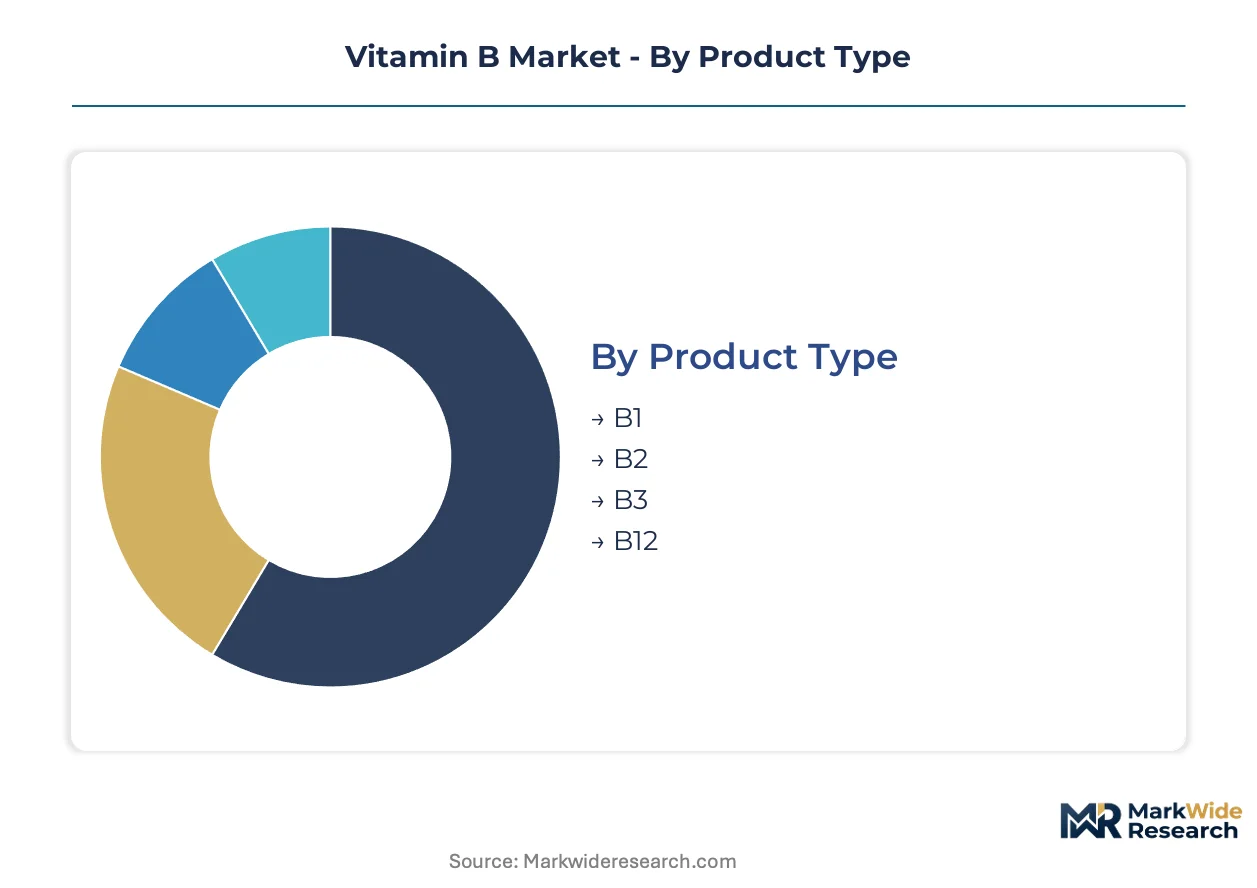
Vitamin B market segmentation reveals divergent margin profiles across chemical synthesis and fermentation-derived supply chains. Form and application splits determine whether producers compete on pharmaceutical-grade purity or feed-grade volume economics.
Product Type:
Volume concentration sits with commodity riboflavin and niacin, while premium positioning accrues to cobalamin and pyridoxine variants with complex bioprocessing requirements.
- B1 (Thiamine):Synthesized through chemical condensation of pyrimidine and thiazole intermediates, this segment supplies flour fortification programs and neurological therapeutic formulations. Demand concentrates in India where FSSAI mandates wheat enrichment, though margin compression from Chinese overcapacity limits producer profitability.
- B12 (Cobalamin):Fermentation-derived via Propionibacterium or Pseudomonas cultures with 99%+ purity specifications for injectable and sublingual applications. Pharmaceutical-grade output clusters in three integrated facilities globally, creating supply interruption exposure that sustains premium pricing.
- B2 (Riboflavin):Microbial fermentation dominates industrial-scale production for animal feed premixes and food colorants.
- B3 (Niacin):Chemical synthesis from pyridine feedstocks serves high-volume fortification and lipid management pharmaceuticals.
Today's leader: B12. Tomorrow's challenger: B3.
Form:
Pharmaceutical-grade tablets and capsules extract maximum margin from direct-to-consumer channels, while bulk powders serve commoditized feed applications with minimal value-add.
- Powders:Free-flowing crystalline or spray-dried formats dominate livestock premix manufacturing and industrial food fortification. Demand concentrates in Shandong province where Chinese producers have scaled fermentation capacity for export-grade riboflavin and niacin.
- Tablets:Compressed dosages with excipient matrices enable precise unit-dispensing for retail supplement and prescription channels. US pharmacy and telehealth platforms are absorbing volume as direct-to-consumer subscription models displace traditional retail distribution.
- Capsules:Gelatin and vegetable-derived shells accommodate acid-sensitive B-vitamin variants for targeted release.
- Liquids:Aqueous suspensions and liposomal emulsions serve pediatric and geriatric populations with swallowing difficulties.
Tablets dominate pharmacy counters. Liquids gain fastest in pediatric formulations.
Application:
Institutional buyers in milling and dairy processing anchor baseline demand, while discretionary supplement spending drives growth volatility.
- Dietary Supplements:Direct-to-consumer wellness platforms capture capsule and tablet volumes with personalized dosing protocols. Urban professionals in the United States and United Kingdom are normalizing telehealth-integrated prescribing that accelerates subscription-based replenishment cycles.
- Fortified Foods:Mandatory wheat and rice enrichment programs in India institutionalize B-vitamin demand outside discretionary channels. FSSAI mandates create stable offtake that buffers producers against supplement market fluctuations.
- Pharmaceuticals:Prescription B-complex and single-entity formulations target deficiency disorders and metabolic adjuvant therapy.
- Animal Feed:Premix additives prevent deficiency in intensive livestock operations across poultry and swine sectors.
Supplements command attention. Fortification commands tonnage.
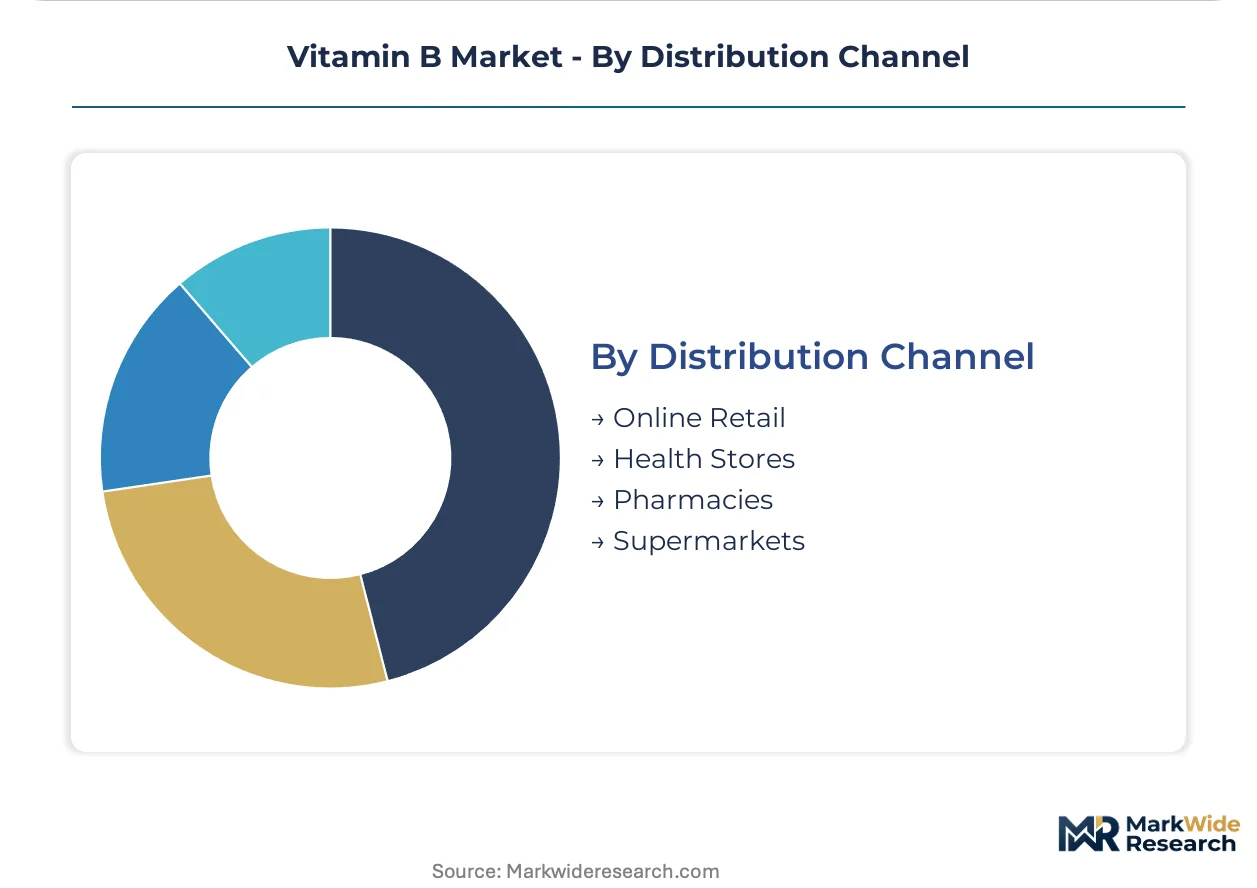
Distribution Channel:
Digital platforms are compressing traditional pharmacy margins by capturing consumer preference data that accelerates SKU development cycles.
- Online Retail:Subscription platforms and marketplace aggregators disintermediate brick-and-mortar discovery with algorithmic personalization. Amazon and specialized wellness sites are absorbing market share from health stores through convenience positioning and auto-replenishment mechanics.
- Health Stores:Specialty retailers with trained staff consultation sustain premium positioning for complex B-complex formulations. GNC and Holland & Barrett anchor shelf space for differentiated products with bioavailability claims.
- Pharmacies:CVS and Walgreens maintain OTC and prescription B-vitamin access with insurance-adjacent purchasing.
- Supermarkets:Mass merchandisers like Walmart and Tesco capture impulse purchases through prominent end-cap placement.
Online retail leads growth. Pharmacies retain trust for therapeutic dosing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors global fermentation capacity for riboflavin and niacin, with Chinese producers exporting bulk powders to feed and fortification markets worldwide. Domestic blue-hat registrations under SAMR are accelerating manufacturing localization for premium supplement lines.
China
Dietary supplement demand concentrates in tier-one cities where urban professionals subscribe to personalized B-complex protocols. NMPA and SAMR mandate domestic clinical trial data for imported health food registrations, forcing foreign brands into joint-venture production partnerships. Shandong and Zhejiang provinces have scaled pharmaceutical-grade fermentation infrastructure to capture this localized formulation opportunity.
United States
Direct-to-consumer wellness platforms displace retail pharmacy as the primary discovery channel for B-vitamin products. FDA enforces Current Good Manufacturing Practice regulations under 21 CFR Part 111, elevating compliance costs for identity and purity verification. Telehealth-integrated prescribing in metropolitan markets normalizes subscription-based replenishment cycles for therapeutic dosing.
India
FSSAI fortification mandates for wheat and rice institutionalize B-vitamin demand outside discretionary supplement channels. Mandatory enrichment programs create stable offtake that buffers producers against consumer market volatility. Domestic flour milling clusters in Punjab and Haryana absorb standardized premix volumes under centralized procurement schemes.
Germany
EFSA novel food safety assessments for fermentation-derived B-vitamins accelerate biotech platform investments by ingredient suppliers. REACH compliance requirements govern chemical synthesis residuals in imported niacin and riboflavin. Bavarian biotechnology hubs specialize in high-purity cobalamin production for pharmaceutical and nutraceutical applications.
Brazil
Anvisa regulates dietary supplement registrations with evolving bioequivalence standards for synthetic versus natural-origin B-vitamins. Poultry and swine feed premixes drive bulk demand for riboflavin through integrated livestock operations in São Paulo state. São Paulo-based distributors consolidate import logistics for South American supplement formulators.
Vitamin B Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation platforms and contract manufacturing partnerships. The supplier base stratifies across integrated chemical conglomerates, specialized biotechnology platforms, and branded formulation houses. Three archetypes dominate: fermentation specialists with captive strain libraries, chemical synthesis operators with depreciated legacy assets, and direct-to-consumer brands with subscription logistics capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure precursor supply chains and regional regulatory approvals.
Within the integrated biotechnology tier, DSM Nutritional Products and Lonza Group exemplify platform-based positioning through fermentation-derived output. BASF SE anchors the scale-driven chemical synthesis segment with large-volume riboflavin infrastructure. Among branded formulation specialists, Nature's Bounty and NOW Health Group occupy retail and digital channels respectively.
| Leading Market Players |
|---|
| BASF SE |
| DSM Nutritional Products |
| Bayer AG |
| Pharmavite |
| Nature's Bounty |
| NOW Health Group |
| Lonza Group |
| Nutraceutical International Corporation |
| Herbalife Nutrition |
| Others |
Supply Flow & Price Mechanics
Family-owned fermentation specialists in Shandong province anchor bulk riboflavin and niacin supply, their disciplined capacity expansion sustaining margin stability against volatile corn-derived precursor costs. Their pricing power draws from captive strain libraries and integrated bioprocessing infrastructure that chemical synthesis competitors cannot replicate.
Pricing Analysis
Corn and agricultural commodity pass-through dominates B-vitamin cost structures, with feedstock volatility compressing margin predictability for fermentation-derived B12 and B2 producers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade purity levels segments buyers by certification stringency. Cost compression in feed-grade riboflavin is intensifying because Chinese overcapacity has saturated bulk export markets. Animal feed premix manufacturers exhibit highest price sensitivity, while injectable cobalamin purchasers accept premium positioning due to supply interruption exposure.
Supply Chain Analysis
Single-source vulnerability sits with pharmaceutical-grade cobalamin synthesis, which clusters in three integrated facilities across China, Germany, and Switzerland. Corn-derived precursors, pyridine feedstocks, and specialized fermentation media constitute critical input dependencies. Tariff exposure runs through US-China trade friction on nutritional ingredient imports. Distribution runs through Shandong-based bulk powder exporters for feed applications, with direct-to-consumer subscription platforms capturing retail supplement volumes in the United States and United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where fermentation capacity costs in Shandong undercut European biotech infrastructure by a factor that absorbs logistics differentials.
For Market Incumbents: Anchor fermentation platform investments in SAMR-registered Chinese joint ventures to defend against localization mandates that threaten imported supplement market share. Consolidate backward integration into corn-derived precursor supply to buffer margin compression from agricultural commodity cycles. Prioritize strain library IP protection as contract manufacturing organizations erode captive production advantages. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable channel entry point, given their algorithmic personalization capabilities and auto-replenishment mechanics. Target precision fermentation B12 production using CRISPR-edited strains to undercut incumbent pharmaceutical-grade cost structures. Pursue cross-species formulation licensing into veterinary nutraceutical channels to absorb human-grade overcapacity. For Investors and Strategic Acquirers: Valuations sit cheapest among depreciated chemical synthesis operators with stranded riboflavin and niacin assets facing fermentation yield obsolescence. Five-to-ten year viability hinges on bioprocess engineering talent acquisition and regulatory pathway navigation for natural-origin positioning. Monitor FDA guidance on synthetic-fermentation bioequivalence standards as the decisive inflection signal for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | CRISPR-edited Propionibacterium strains unlock therapeutic-grade B12 at nutraceutical cost structures. |
| Joint Venture Localization | Shandong manufacturing partnerships satisfy SAMR blue-hat registration requirements for premium supplement access. |
| Backward Integration | Corn-derived precursor supply control buffers margin compression from agricultural commodity price swings. |
| Direct-to-Consumer Platform Launch | Telehealth-integrated subscription models capture urban professional demand in the United States and United Kingdom. |
| Veterinary Channel Licensing | Cross-species formulation agreements absorb human-grade B-vitamin overcapacity through companion animal applications. |
Methodological Framework
Bottom-up dietary supplement and fortified food modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with fermentation plant managers, supplement brand procurement leads, FSSAI fortification program administrators, and veterinary nutraceutical formulators combined with secondary validation from FDA 21 CFR Part 111 filings, EFSA novel food safety assessments, NMPA blue-hat registration databases, and customs trade data. Triangulation between demand-side consumption patterns and supply-side production capacity ensures statistical coherence.
Historical trendline analysis across vitamin B consumption intensity per capita, fortification mandate penetration rates, and fermentation yield improvements established baseline growth trajectories. Segmentation modeling spans product type, purity grade, application channel, and regional regulatory cluster dimensions. CAGRs derive from fitted trend extrapolation adjusted for policy inflection points and technology substitution curves. Forecast inputs incorporate SAMR registration velocity, precision fermentation cost reduction curves, and direct-to-consumer channel share trajectories.
Revisions become necessary when bioequivalence guidance finalizes, major facility interruptions occur, or fortification mandates expand to new geographies. Forecasts reflect documented assumptions about regulatory pathway timelines and yield improvement rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Encapsulated Vitamin C Market