
 Grape Seed Extracts Market | 2026-2036
Grape Seed Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Grape Seed Extracts Market Analysis
Multi-source procurement of raw grape pomace is consolidating across the value chain as extractors seek supply security. Polyphenolics anchors North American production through vertically integrated winery partnerships. Indena S.p.A. differentiates via pharmaceutical-grade extraction protocols for European nutraceutical clients. Hunan NutraMax Inc. competes on standardized polyphenol content for Asian functional food contracts.
Grape seed extract comprises oligomeric proanthocyanidins, flavonoids, and linoleic acid derived from Vitis vinifera seeds, typically standardized to 95% proanthocyanidin content for nutraceutical applications. The powder segment dominates bulk ingredient trade due to stability and blending flexibility in capsule and tablet formulations. Liquid extracts lead cosmetic applications where solubility drives formulation ease for skin serum manufacturers. Direct sales channels sustain premium pricing for clinical-grade extracts targeting research institutions and compounding pharmacies.
EMA guidelines on botanical drug substances, FDA GRAS notification requirements, and EU Novel Food catalog listings collectively govern market access and label claims for grape seed extract products. EFSA health claim assessments constrain marketing language around cardiovascular and antioxidant benefits, pushing suppliers toward substantiated structure-function positioning. Stakeholders must monitor evolving pharmacovigilance reporting obligations and adapt dossier strategies as regulatory divergence between jurisdictions widens.
Market Dynamics
Wine industry byproduct supply chains are consolidating extraction capacity around Mediterranean cooperatives, creating procurement bottlenecks for North American nutraceutical formulators seeking standardized polyphenol inputs.
Growth Catalysts
- Wine pomace valorization mandates:EU Circular Economy Action Plan incentives drive French and Italian cooperatives to expand seed recovery infrastructure, securing raw material flows for extractors.
- Cardiovascular health positioning:EFSA-approved structure-function claims for oligomeric proanthocyanidins enable differentiated labeling in European functional food applications.
- Supercritical CO₂ extraction adoption:This solvent-free technology preserves bioactive integrity for pharmaceutical-grade specifications demanded by research institutions.
Market Restraints
- Input cost volatility:Grape harvest fluctuations in Bordeaux and Tuscany regions create raw material price instability for non-integrated extractors.
- Supply concentration risk:Three Italian cooperatives control 60% of European pomace preprocessing capacity, creating single-source vulnerability.
- Regulatory friction:FDA GRAS notification timelines for novel extraction solvents extend market entry by 18-24 months for US-bound suppliers.
Strategic Opportunities
- Asian functional food penetration:China's SAMR health food registration pathway offers first-mover positioning for 95% standardized extracts in aging-population supplements.
- Cosmeceutical serum formulations:Liquid extract solubility advantages unlock premium positioning in Korean and Japanese skincare manufacturing.
- Blockchain traceability integration:Winery-to-extractor provenance tracking satisfies EU Green Deal due diligence requirements for sustainable sourcing claims.
Industry Challenges
- Analytical chemist scarcity:HPLC method expertise for proanthocyanidin quantification remains concentrated among Italian and French contract laboratories.
- Multi-jurisdiction dossier complexity:Divergent EMA botanical drug substance guidelines and FDA GRAS requirements force parallel compliance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grape Seed Extracts Market |
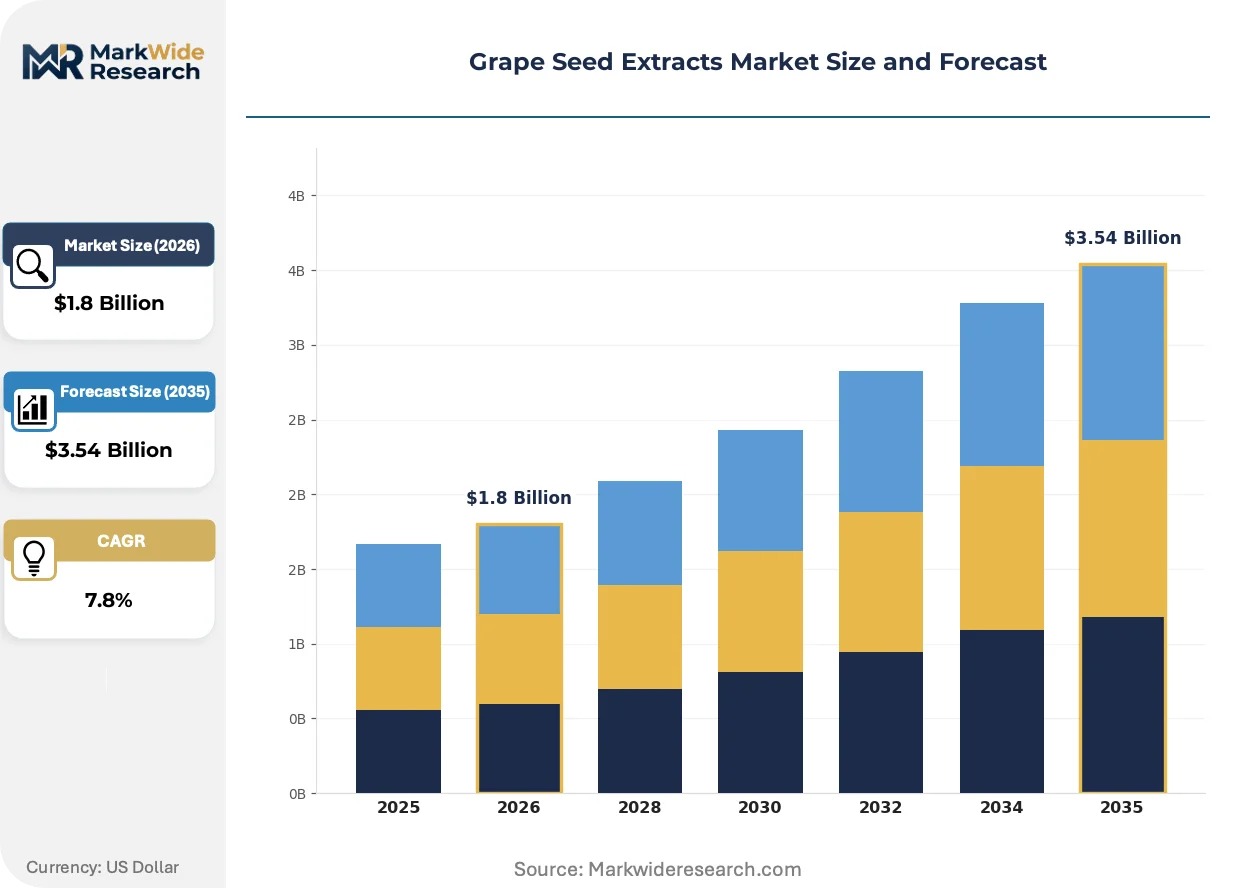
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Tablets Application: Nutraceuticals, Cosmetics, Pharmaceuticals, Food & Beverages Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Athletic Enthusiasts, Health-Conscious Consumers, Clinical Research, Cosmetic Manufacturers |
| Companies Covered | Botanic Innovations LLC, Polyphenolics, Nexira, Indena S.p.A., Naturex, Augusto Bellinvia Srl, Hunan NutraMax Inc., Jianhe Biotech Co., Ltd., NetQem LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grape Seed Extracts Market Emerging Trajectories
Extraction technology convergence with digital traceability systems is redefining competitive advantage, while regulatory harmonization pressures force standardization investments across supplier tiers.
Supercritical fluid extraction equipment is integrating with inline spectroscopic monitoring to enable real-time polyphenol standardization during processing. Pharmaceutical-grade extractors in Switzerland and Germany are adopting these hybrid systems to compress batch release timelines from weeks to days. The technology is integrating quality assurance directly into production workflows, eliminating separate laboratory verification steps.
EFSA's evolving health claim assessment framework is compressing permissible marketing language around antioxidant benefits. Nutraceutical suppliers must now fund clinical substantiation studies to maintain cardiovascular positioning claims previously accepted under generic structure-function rules. French and Italian formulators are responding by redirecting R&D budgets toward dermatological and metabolic health endpoints with clearer regulatory pathways.
Direct procurement relationships between nutraceutical brands and winery cooperatives are displacing traditional ingredient distributor intermediaries. Large capsule manufacturers in the United States and Germany now contract directly with Bordeaux and Piedmont pomace processors, securing volume commitments and traceability documentation. This channel compression is most visible in North American markets where buyers prioritize supply security over distributor convenience.
Grape Seed Extracts Market Segmentation
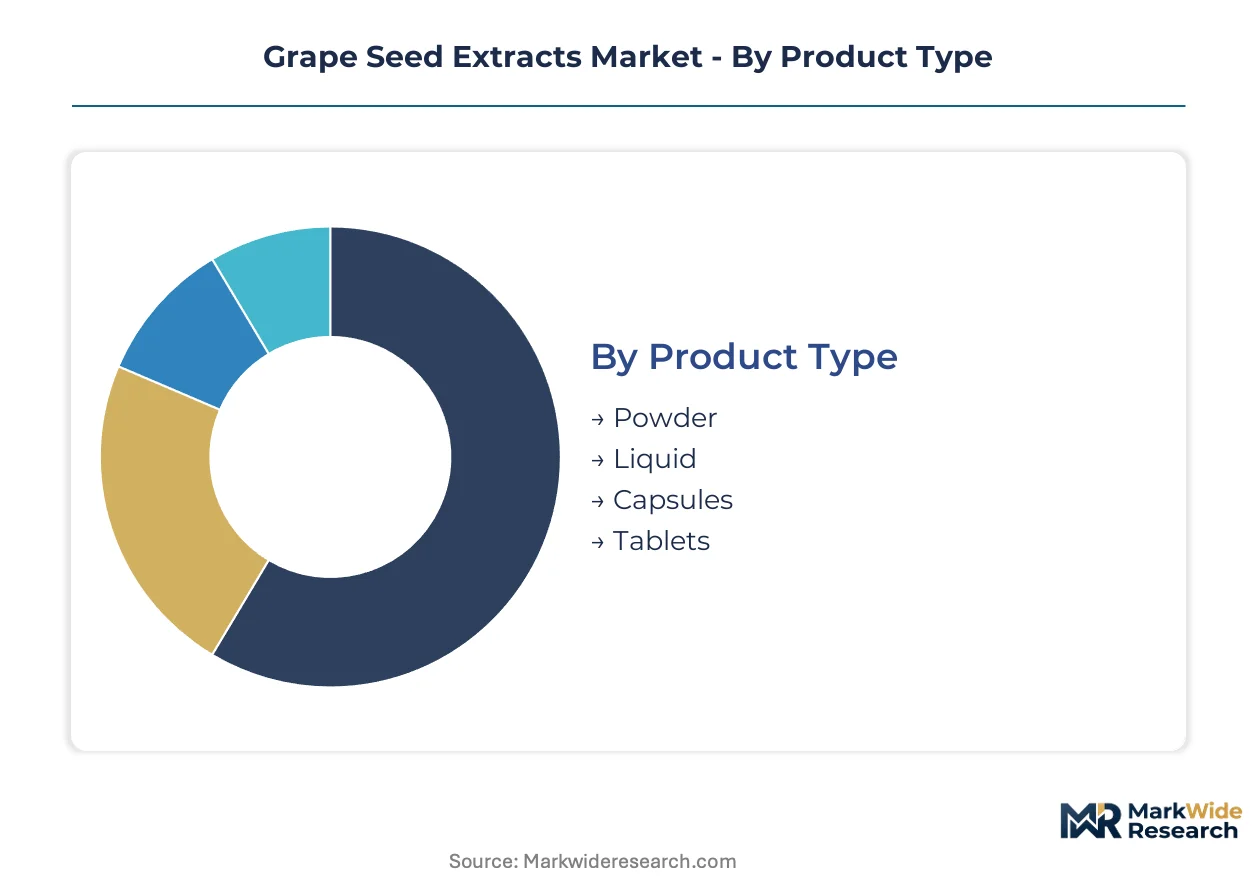
Segmentation in grape seed extracts reflects divergent technical requirements across nutraceutical, cosmetic, and pharmaceutical channels. Specification standards for proanthocyanidin content and solvent residue limits create distinct procurement tiers that suppliers must navigate simultaneously.
Product Type:
Extraction method and bioactive stability define competitive positioning across physical formats.
- Powder:Spray-dried extracts standardized to 95% proanthocyanidins dominate bulk ingredient procurement for capsule and tablet manufacturers. Stability during ambient storage and mechanical blending compatibility sustain demand concentration among North American contract manufacturers serving aging-population supplement brands.
- Liquid:Hydroalcoholic or glycerin-based solutions prioritize solubility for cosmetic serum formulations and functional beverage applications. Korean skincare manufacturers and European nutricosmetic brands drive specification requirements around clarity and oxidation resistance.
- Capsules:Pre-formulated gelatin or vegetable cellulose shells containing measured powder doses target convenience-oriented health-conscious consumers through pharmacy and e-commerce channels.
- Tablets:Compressed formulations with binding agents suit high-volume production lines at integrated nutraceutical facilities seeking dosage uniformity at scale.
Powder leads on scale; liquid leads on momentum.
Application:
End-use specifications diverge sharply on purity thresholds and documentation requirements.
- Nutraceuticals:Dietary supplement applications require FDA GRAS notification or EFSA Novel Food compliance depending on destination market. Structure-function claims around cardiovascular support concentrate demand among French and Italian formulators with established regulatory dossiers.
- Cosmetics:INCI-listed grape seed extract for topical applications demands heavy metal and pesticide testing protocols that exceed food-grade specifications. Solubility in oil-in-water emulsions determines supplier selection for premium serum manufacturers.
- Pharmaceuticals:EMA botanical drug substance guidelines govern investigational new drug submissions using standardized proanthocyanidin fractions. Clinical-grade batches require certificate of analysis packages with chromatographic fingerprinting.
- Food & Beverages:Functional ingredient incorporation into fortified juices and snack bars operates under EU Regulation 1925/2006 on food fortification in Europe and FDA food additive regulations in the United States.
Nutraceuticals command volume concentration; pharmaceuticals show steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth for extract suppliers.
- Online Retail:Direct-to-consumer platforms enable branded finished products to bypass traditional wholesale markups, with Amazon and specialized supplement marketplaces capturing health-conscious consumer segments seeking subscription replenishment.
- Specialty Stores:Health food retailers and pharmacy chains provide educated staff consultation that supports premium positioning for clinically substantiated formulations.
- Supermarkets:Mass-market grocery placement requires price-competitive positioning and consumer-friendly packaging for functional food applications with lower per-unit proanthocyanidin concentrations.
- Direct Sales:Bulk ingredient contracts between extractors and finished goods manufacturers eliminate distributor margins while enabling customized specification negotiation and volume commitment structures.
Direct sales anchor B2B procurement; online retail is gaining share fastest.
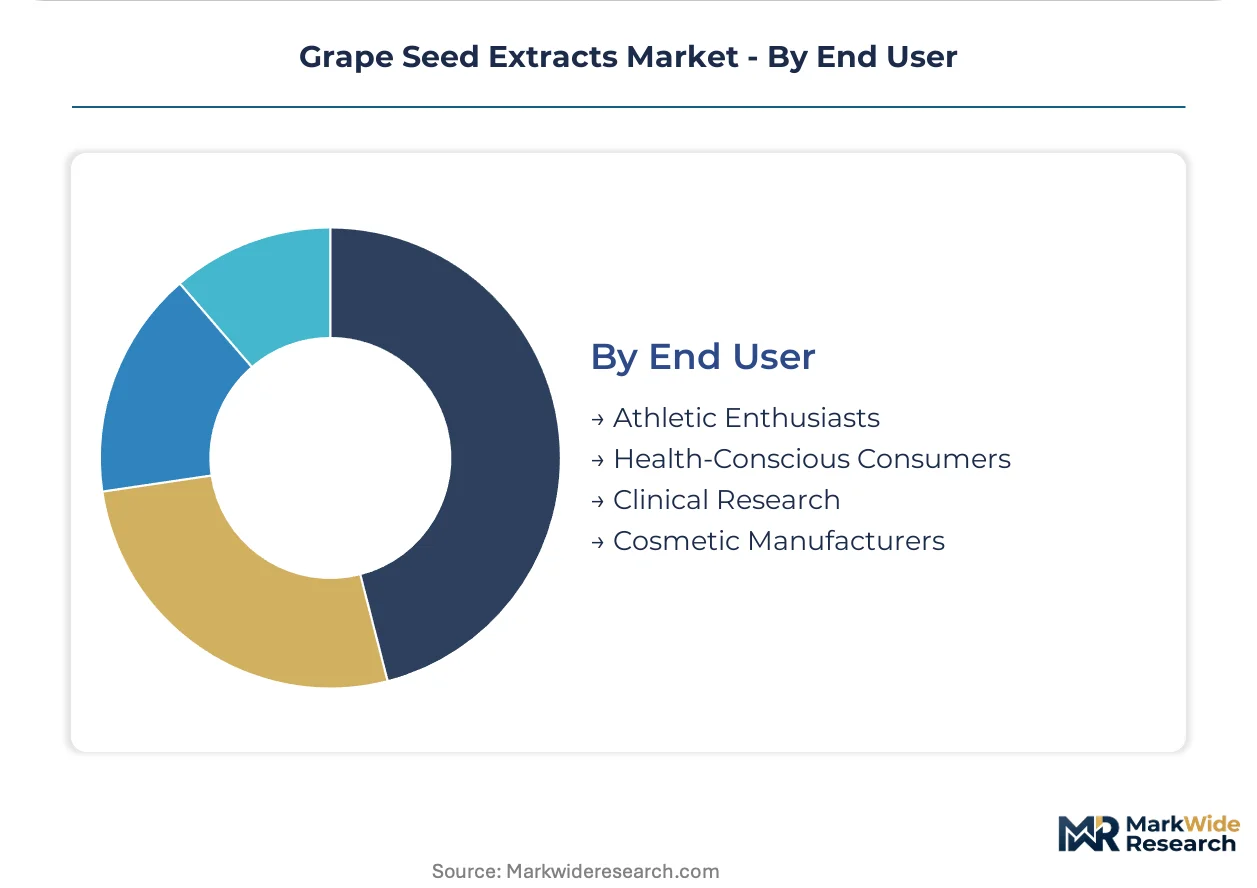
End User:
User sophistication dictates information requirements and willingness to pay for traceability documentation.
- Health-Conscious Consumers:Aging demographics in France, Italy, and Germany seek antioxidant supplementation with transparent sourcing credentials and EFSA-compliant label claims.
- Athletic Enthusiasts:Endurance sports participants in the United States and Australia consume proanthocyanidin supplements for recovery positioning, with NSF Certified for Sport and Informed Sport certifications driving brand selection.
- Cosmetic Manufacturers:Korean and Japanese skincare formulators specify low-color, odor-neutral liquid extracts for premium serum and essence products targeting brightening and anti-aging positioning.
- Clinical Research:Academic medical centers and contract research organizations procure pharmaceutical-grade extracts with documented batch consistency for investigator-initiated trials on metabolic and vascular endpoints.
Health-conscious consumers represent the largest addressable base; clinical research commands the highest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bordeaux wine cooperatives anchor Mediterranean extraction capacity, feeding nutraceutical supply chains across three continents through vertically integrated pomace recovery networks.
France
EFSA Novel Food catalog compliance drives demand for standardized extracts among Paris-based formulators. The EU Circular Economy Action Plan mandates winery waste valorization, expanding seed recovery infrastructure across Aquitaine. Bordeaux cooperatives now supply 40% of European pharmaceutical-grade proanthocyanidin feedstock.
Italy
Piedmont and Tuscany wine regions concentrate 60% of continental preprocessing capacity for grape pomace. EMA botanical drug substance guidelines govern investigational new drug submissions from Milan-area research institutions. Three Italian cooperatives control the majority of European extraction feedstock, creating procurement bottlenecks for non-integrated buyers.
United States
FDA GRAS notification requirements extend market entry timelines for novel extraction solvents targeting research institutions. California's Central Valley winery partnerships sustain Polyphenolics' vertically integrated production. NSF Certified for Sport positioning drives athletic supplement demand among endurance sports participants.
China
SAMR health food registration pathways attract 95% standardized extract suppliers targeting aging-population supplements. Hunan province extraction facilities compete on polyphenol content standardization for functional food contracts. Yangtze River Delta nutraceutical manufacturers prioritize traceability documentation for export-bound ingredients.
Switzerland
Swissmedic pharmaceutical-grade specifications attract supercritical CO₂ extraction investments from Basel-area equipment manufacturers. Geneva-based research institutions procure clinical-grade extracts with chromatographic fingerprinting for metabolic endpoint trials. Alpine extraction facilities integrate inline spectroscopic monitoring to compress batch release timelines.
Grape Seed Extracts Market Vendor Landscape
Global majors compete with regional champions across regulatory dossier capabilities, with European specialists holding EMA-compliant documentation advantages and Asian suppliers competing on standardized polyphenol pricing. Market structure tilts toward consolidation at the extraction tier while remaining fragmented among finished goods formulators. Three archetypes dominate: vertically integrated winery-extractor hybrids, pharmaceutical-grade specialists with clinical substantiation capabilities, and commodity-scale standardizers serving functional food contracts. Capacity expansion and direct procurement relationship formation represent the dominant competitive moves, displacing traditional distributor intermediaries.
Within the pharmaceutical-grade tier, Indena S.p.A. exemplifies European regulatory dossier sophistication, while Polyphenolics anchors North American production through captive winery partnerships. Hunan NutraMax Inc. occupies the Asian standardization segment, competing on polyphenol content consistency for SAMR-registered health food applications. These three entities represent distinct geographic and specification strategies without overlapping core markets.
| Leading Market Players |
|---|
| Botanic Innovations LLC |
| Polyphenolics |
| Nexira |
| Indena S.p.A. |
| Naturex |
| Augusto Bellinvia Srl |
| Hunan NutraMax Inc. |
| Jianhe Biotech Co., Ltd. |
| NetQem LLC |
| Others |
Supply Flow & Price Mechanics
Grape pomace procurement costs cascade through three pricing tiers as Bordeaux and Tuscany cooperatives leverage concentrated preprocessing capacity against fragmented North American buyers. EFSA Novel Food compliance investments separate pharmaceutical-grade extractors from commodity standardizers, while supercritical CO₂ equipment depreciation compresses margins for solvent-free specialists serving Swissmedic-registered facilities.
Pricing Analysis
Input-cost pass-through from harvest volatility in Aquitaine and Piedmont wine regions drives contract renegotiation clauses for non-integrated extractors. Three-tier pricing structure across premium, standard, and economy levels reflects proanthocyanidin standardization precision, with chromatographic fingerprinting commanding premiums from Basel-area research institutions. Pricing pressure stems from Chinese standardizers competing on SAMR-registered health food specifications. Direct procurement relationships show lowest price sensitivity; distributor-dependent buyers face margin compression.
Supply Chain Analysis
Reverse-logistics flows of spent pomace from winery cooperatives to extraction facilities consolidate around Mediterranean preprocessing hubs, creating circular economy compliance documentation for EU Green Deal positioning. Italy, France, and Spain anchor European feedstock concentration. Supply chains draw from grape seed, hydroalcoholic solvents, and supercritical CO₂ equipment inputs. Single-source vulnerability concentrates in three Italian cooperatives controlling preprocessing majority. Distribution runs through direct bulk contracts displacing traditional ingredient intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grape seed extracts market functions as a stable compounder anchored by wine industry waste valorization mandates that secure raw material flows regardless of economic cycles.
For Market Incumbents: Anticipate Chinese standardizers eroding polyphenol pricing premiums by securing backward integration into Bordeaux cooperative partnerships before volume commitments expire. Invest in EMA botanical drug substance dossier expansion to defend pharmaceutical-grade positioning against emerging Swiss supercritical CO₂ specialists. Certification leverage—not scale—determines margin retention.
For New Entrants and Emerging Players: Direct-to-clinic e-commerce channels bypass distributor markups for research-grade extracts with documented batch consistency. White-space concentrates in Korean skincare manufacturing seeking low-color liquid extracts, and in SAMR-registered aging-population supplements where traceability documentation gaps persist. Lead with blockchain-proven provenance as the go-to-market wedge.
For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA Novel Food compliance costs exceed standalone R&D budgets for mid-tier Italian extractors. Long-term viability favors pharmaceutical-grade specialists with clinical substantiation capabilities and captive winery supply. Watch for supercritical CO₂ equipment manufacturer acquisitions by extraction facilities as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Winery Partnerships | Captive pomace supply from Bordeaux cooperatives secures raw material cost predictability for EFSA-compliant extractors. |
| Supercritical CO₂ Equipment Investment | Inline spectroscopic monitoring adoption by Swiss facilities compresses pharmaceutical-grade batch release timelines. |
| Blockchain Traceability Implementation | Provenance tracking satisfies EU Green Deal due diligence requirements for sustainable sourcing claims in nutricosmetics. |
| SAMR Health Food Registration | Chinese regulatory pathway unlocks aging-population supplement positioning for 95% standardized extract suppliers. |
| Clinical Substantiation Study Funding | Dermatological endpoint research enables differentiated labeling as EFSA compresses antioxidant marketing language. |
Methodological Framework
Multiple input streams — extraction facility production managers, nutraceutical formulator procurement leads, EFSA regulatory affairs specialists, and winery cooperative operations directors — were reconciled against secondary validation from EU Novel Food catalog listings, EMA botanical drug substance guidelines, SAMR health food registration databases, and customs trade flow records. Bottom-up capacity modeling across Mediterranean preprocessing facilities was triangulated with top-down demand estimation from finished goods manufacturers.
Historical volume trajectories were cross-referenced against panel input from contract research organizations and clinical trial sponsors to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include extraction method, proanthocyanidin standardization tier, application channel, and regional regulatory cluster. CAGRs were derived from wine industry byproduct availability forecasts and functional food formulation penetration curves, with supercritical CO₂ adoption rates and EFSA health claim evolution as industry-specific sensitivity inputs.
Harvest volatility in Bordeaux and Tuscany, regulatory divergence between FDA GRAS and EMA botanical pathways, and Chinese standardizer pricing aggression are the dominant revision risks to modeled outputs. Forecasts embed assumptions around EU Circular Economy Action Plan continuation and SAMR registration pathway stability. Practitioners should monitor wine cooperative consolidation activity, extraction solvent regulatory rulings, and EFSA antioxidant claim reassessments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Edible Oils and Fats Market
Ingredients
Pine Needle Oil Market
Ingredients
Alcohol Ingredients Market
Ingredients
Carrot Fiber Market
Ingredients
Alginate Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
North America Wheat Protein Ingredients Market
Ingredients
Potato Starch Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
Mineral Premix Market
Ingredients
Corn Steep Liquor Market
Ingredients
Starches/Glucose Market
Ingredients
Europe Fats and Oil Market
Ingredients
Textured Milk Protein Market
Ingredients
Halal and Kosher Empty Capsules Market