
 Mannan-Oligosaccharide (MOS) Market | 2026-2036
Mannan-Oligosaccharide (MOS) Market Size, Share, and Industry Trends Forecast 2026-2036
Mannan-Oligosaccharide (MOS) Market Insights
EU Feed Hygiene Regulation 183/2005 certification compliance is collapsing the supplier base for non-European MOS exporters seeking European animal nutrition market access. Angel Yeast Co. Ltd. leverages captive yeast cell wall extraction infrastructure across multiple Chinese provinces to sustain cost-competitive powder output. Lallemand Inc. anchors its position through vertically integrated fermentation capacity spanning yeast-derived prebiotic production. DSM Nutritional Products differentiates via human-grade MOS qualification pathways that extend into nutraceutical channels.
Mannan-oligosaccharide denotes a class of non-digestible prebiotic carbohydrates derived from yeast cell walls, typically comprising β-1,4 and β-1,6 linked mannose polymers with molecular weights ranging from 1 to 2 kDa, functioning primarily to competitively exclude pathogenic bacteria by binding Type-1 fimbriae in animal and human gastrointestinal tracts. Powder formulations occupy the dominant share in bulk feed manufacturing due to blending compatibility and shelf stability, while liquid MOS concentrates represent the fastest-growing product type for aquaculture immersion and drinking water applications. The gut health application segment leads volume consumption as livestock producers substitute prebiotic interventions for prophylactic antibiotics, whereas immune support positioning in companion animal nutrition commands premium pricing pools.
The European Food Safety Authority evaluates novel prebiotic health claims under Regulation 1924/2006, constraining human nutraceutical marketing unless substantiated by targeted efficacy trials. China's Ministry of Agriculture and Rural Affairs classifies yeast-derived MOS as feed additive under the Feed Additive Catalogue, governing import registration and domestic manufacturing licensing. Brazil's MAPA regulates prebiotic feed ingredients through IN 15/2014, which mandates product registration and quality certification for commercial distribution. Stakeholders must monitor evolving national feed additive positive lists and determine whether to pursue parallel regulatory pathways across multiple jurisdictions or concentrate investment in markets with harmonized approval frameworks.
Market Dynamics
Antibiotic growth promoter bans across major livestock-producing nations are structurally redirecting feed additive procurement toward prebiotic alternatives, with regulatory compliance timelines compressing supplier qualification windows and reshaping competitive access.
Growth Catalysts
- EU Feed Hygiene Regulation 183/2005:Certification mandates are collapsing the supplier base for non-European exporters, creating protected market access for compliant producers.
- Aquaculture immersion protocols:China's expanding aquaculture sector is driving liquid MOS concentrate adoption for water-based delivery systems in shrimp and finfish operations.
- Poultry gut health substitution:Brazilian livestock producers under MAPA IN 15/2014 directives are accelerating MOS inclusion in broiler rations as antibiotic alternatives.
Market Restraints
- Yeast cell wall raw material concentration:Dependence on Saccharomyces cerevisiae biomass from fermentation clusters in China and Brazil creates input supply vulnerability.
- EFSA novel food claim substantiation:Human nutraceutical pathways require targeted efficacy trials under Regulation 1924/2006, extending commercialization timelines.
- Enzymatic hydrolysis cost structure:Mannanase enzyme requirements for MOS extraction from yeast cell walls elevate production costs relative to crude fiber alternatives.
Strategic Opportunities
- Companion animal immune support positioning:Premium pricing pools in pet nutrition segments remain underpenetrated by yeast-derived prebiotic suppliers.
- Drinking water application protocols:Swine operations in North American confinement systems represent untapped demand for liquid MOS delivery formats.
- Dual carbon policy alignment:China's national carbon neutrality targets create preferential licensing pathways for fermentation-based feed additives with verified carbon footprints.
Industry Challenges
- Multi-jurisdictional registration complexity:Feed additive positive lists diverge across Brazil's MAPA, China's MARA, and EU EFSA frameworks, forcing parallel compliance investments.
- Analytical method standardization gaps:Inconsistent mannan-oligosaccharide purity quantification protocols between ISO methods and national standards complicate cross-border quality arbitration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mannan-Oligosaccharide (MOS) Market |
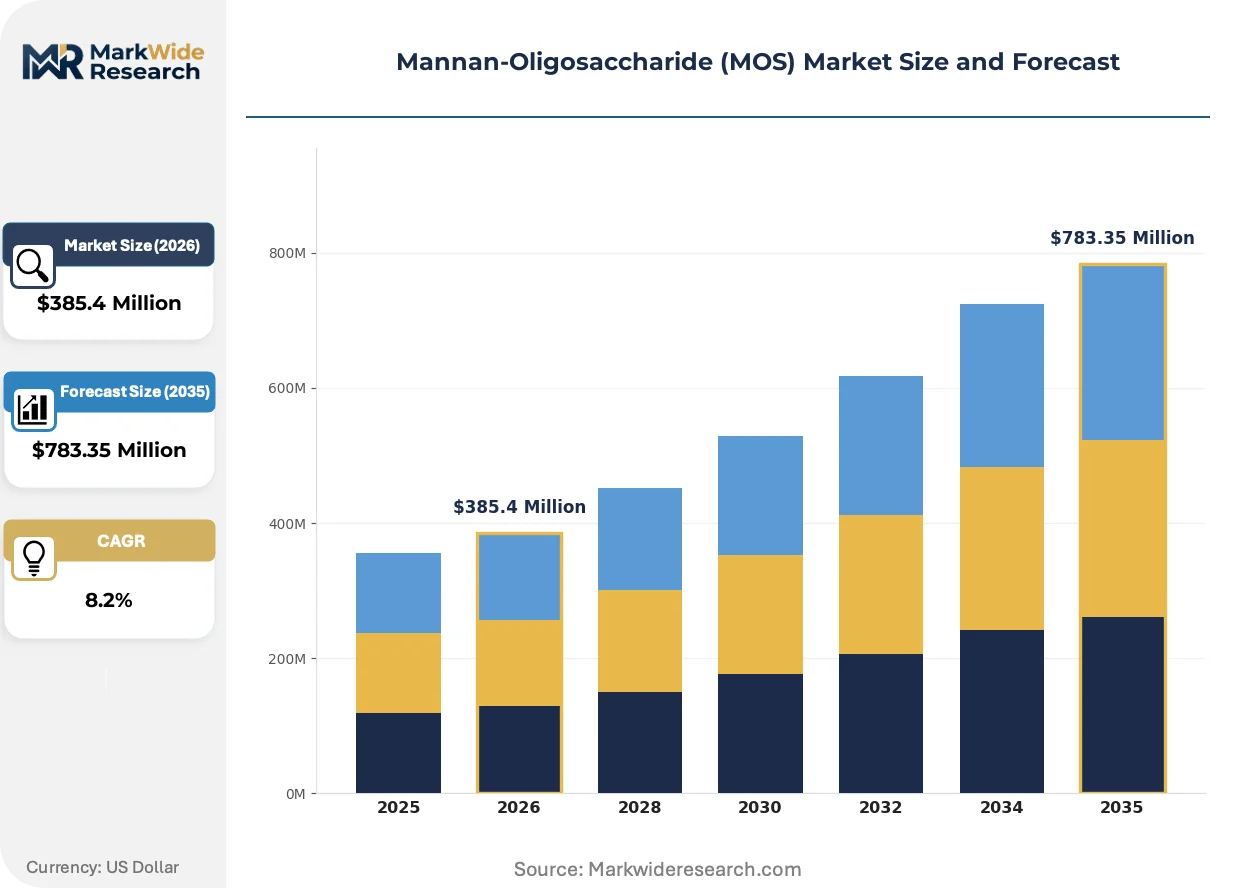
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $783.35 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Capsules End Use: Animal Feed, Nutraceuticals, Food & Beverage, Pharmaceuticals Application: Gut Health, Immune Support, Digestive Aid, Prebiotic Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Angel Yeast Co. Ltd., Royal Canin SAS, Lallemand Inc., DSM Nutritional Products, Cargill Inc., ORFFA International Holding B.V., Alltech Inc., Kemin Industries Inc., Lesaffre International SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mannan-Oligosaccharide (MOS) Market Trends and Innovations
Fermentation process intensification and downstream purification advances are compressing unit economics for yeast cell wall derivatives while regulatory harmonization efforts reshape competitive qualification requirements.
Cell wall autolysis control technology is displacing conventional acid hydrolysis methods in MOS extraction workflows. European feed additive manufacturers are adopting enzymatic precision protocols at commercial scale. This shift is displacing legacy chemical processing infrastructure and enabling higher mannan polymer consistency for pharmaceutical-grade applications.
EFSA's evolving stance on prebiotic health claim substantiation under Regulation 1924/2006 is tightening evidentiary standards for human nutraceutical positioning. Animal nutrition suppliers now face parallel investment requirements to maintain dual-market eligibility. Powder formulation producers targeting European distribution are responding by segregating human-grade and feed-grade production lines.
Integrated feed mill procurement consolidation is compressing supplier qualification cycles and favoring multi-additive portfolio vendors. Large poultry and swine operations in Brazil and China are consolidating prebiotic purchasing under single-source contracts with technical service attachments. This pattern is most visible in Brazil's integrated protein production corridor where MAPA-registered suppliers with in-house nutritionist teams capture disproportionate contract flow.
Mannan-Oligosaccharide (MOS) Market Segmentation
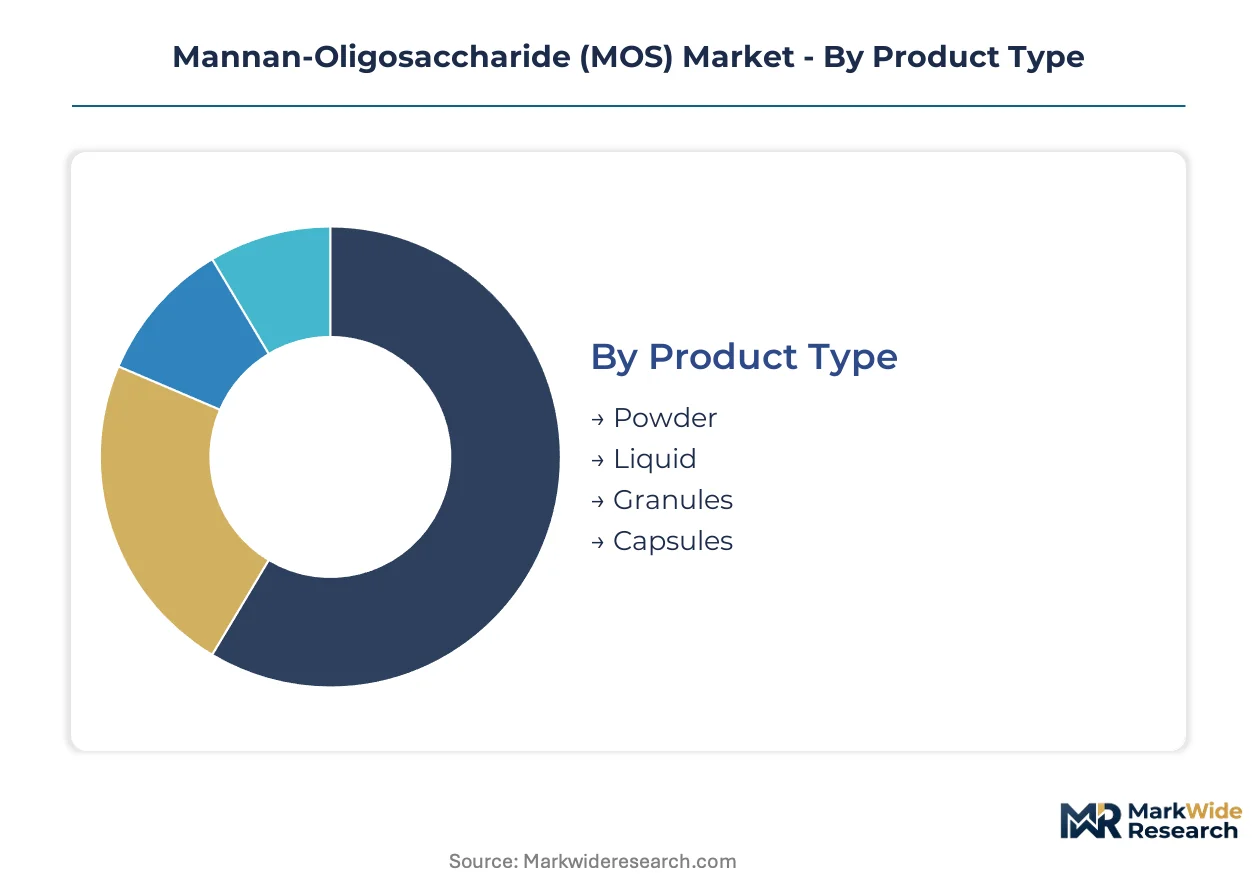
MOS procurement patterns diverge sharply across product formats and end-use channels, with feed-grade powder dominating bulk contracts while nutraceutical capsules command premium positioning. Understanding these segment boundaries clarifies where pricing power concentrates versus where volume scale operates.
Product Type:
Powder formulations anchor domestic feed mill supply chains across Brazil and China, while liquid concentrates serve export-oriented aquaculture operations requiring water-immersion delivery.
- Powder:Comprises β-1,4 and β-1,6 linked mannose polymers with 1-2 kDa molecular weight, optimized for dry feed blending compatibility and extended shelf stability. Brazilian integrated poultry operations under MAPA IN 15/2014 directives source powder MOS for antibiotic-free broiler rations, though enzymatic hydrolysis costs elevate unit economics relative to crude fiber alternatives.
- Liquid:Concentrated aqueous suspensions designed for drinking water systems and aquaculture immersion protocols. China's expanding shrimp and finfish sector in Guangdong and Hainan provinces drives adoption, with MARA-registered suppliers capturing contract flow through technical service attachments for water quality management.
- Granules:Agglomerated particles offering controlled release properties for ruminant feed applications, with demand concentrating in European compound feed manufacturers seeking EFSA-compliant delivery formats.
- Capsules:Encapsulated human-grade formulations targeting nutraceutical channels, requiring parallel production line segregation to maintain dual-market eligibility under Regulation 1924/2006 health claim substantiation pathways.
Powder commands the established base. The steepest expansion runs through liquid concentrates.
End Use:
Cost tier stratification separates commodity feed applications from premium human health positioning, with regulatory compliance investments determining market access barriers.
- Animal Feed:Dominates volume consumption as livestock producers in Brazil and China substitute prebiotic interventions for prophylactic antibiotics under tightening national agricultural ministry directives. Powder formulations integrate into bulk manufacturing channels with blending compatibility requirements.
- Nutraceuticals:Human-grade MOS qualification pathways extend into dietary supplements, with EFSA novel food claim substantiation under Regulation 1924/2006 constraining marketing unless supported by targeted efficacy trials. Premium pricing pools reward suppliers with pharmaceutical-grade extraction infrastructure.
- Food & Beverage:Functional ingredient applications in fermented products and beverages, constrained by limited regulatory approval frameworks for prebiotic health claims in major jurisdictions.
- Pharmaceuticals:Investigational therapeutic applications targeting gastrointestinal pathogen competitive exclusion, with clinical trial requirements extending commercialization timelines beyond standard feed additive pathways.
Animal feed absorbs the volume base. Nutraceuticals deliver the margin expansion.
Application:
Customer type differentiation separates livestock operation procurement from companion animal premium positioning, with immune support commanding pricing premiums in pet nutrition segments.
- Gut Health:Primary functional positioning for pathogenic bacteria competitive exclusion through Type-1 fimbriae binding, driving substitution demand in poultry and swine operations facing antibiotic growth promoter bans.
- Immune Support:Secondary mechanism targeting macrophage activation and cytokine modulation, with premium positioning in companion animal nutrition segments remaining underpenetrated by yeast-derived prebiotic suppliers.
- Digestive Aid:General gastrointestinal comfort applications in food and beverage formulations, with softer regulatory substantiation requirements than disease-related claims.
- Prebiotic:Broad microbiome modulation positioning spanning human and animal applications, with definition standardization gaps complicating cross-border marketing consistency.
Gut health anchors procurement volume. Immune support captures the pricing premium.
Distribution Channel:
Supply concentration in fermentation clusters shapes channel access, with integrated feed mill procurement consolidation favoring direct wholesaler relationships over fragmented retail.
- Wholesalers:Bulk feed additive distributors serving integrated poultry and swine operations in Brazil's protein production corridor, with MAPA-registered suppliers capturing disproportionate contract flow through in-house nutritionist teams.
- Specialty Stores:Premium nutraceutical and companion animal product channels in European and North American markets, requiring dual carbon policy alignment for preferential licensing in China.
- Online Retail:Direct-to-consumer nutraceutical capsules and pet supplements, with regulatory compliance complexity varying across jurisdiction-specific prebiotic claim frameworks.
- Supermarkets:Limited food and beverage ingredient presence, constrained by mass-market price sensitivity and incomplete health claim authorization.
Wholesalers dominate the volume pathway. Specialty stores deliver the margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibiotic growth promoter bans are restructuring procurement patterns across major livestock-producing nations. Feed additive registration frameworks now determine supplier market access. Production clusters concentrate where yeast fermentation infrastructure and regulatory compliance capabilities overlap.
China
Guangdong and Hainan provinces drive liquid MOS concentrate demand for shrimp and finfish aquaculture immersion protocols. The Ministry of Agriculture and Rural Affairs governs yeast-derived MOS under the Feed Additive Catalogue, requiring import registration and domestic manufacturing licensing. Yangtze River Delta fermentation clusters supply cost-competitive powder output through captive yeast cell wall extraction infrastructure.
Brazil
Integrated poultry and swine operations in São Paulo and Paraná accelerate MOS inclusion as antibiotic alternatives tighten under MAPA directives. IN 15/2014 mandates product registration and quality certification for commercial distribution. The country's protein production corridor concentrates contract flow toward MAPA-registered suppliers with in-house nutritionist technical service teams.
United States
North American swine confinement systems represent emerging demand for liquid MOS drinking water delivery formats. The FDA oversees feed additive safety through the Center for Veterinary Medicine, with GRAS self-affirmation pathways available for yeast-derived ingredients. Midwest feed manufacturing clusters source powder formulations for antibiotic-free livestock rations.
Germany
Compound feed manufacturers in Bavaria and Lower Saxony seek EFSA-compliant granule formats for ruminant applications. EU Feed Hygiene Regulation 183/2005 certification requirements collapse the supplier base for non-European exporters. The country's fermentation technology base supports enzymatic precision protocols displacing legacy chemical processing infrastructure.
Netherlands
Randstad-based distributors serve European wholesale channels with EFSA-registered prebiotic portfolios. REACH compliance and CE marking requirements structure import qualification for yeast cell wall derivatives. The country's logistics hub position enables redistribution to neighboring feed manufacturing markets.
Mannan-Oligosaccharide (MOS) Market Competitive Landscape
Player mix skews toward fermentation-based specialists with captive yeast processing infrastructure and diversified nutrition multinationals with multi-additive portfolios. Market structure concentrates around vertically integrated yeast producers and feed additive formulators with regulatory compliance capabilities across multiple jurisdictions. Strategic archetypes include fermentation-based specialists, diversified nutrition conglomerates, and regional feed additive distributors. Dominant competitive moves encompass capacity expansion in yeast cell wall extraction and geographic registration portfolio diversification.
Among fermentation-based specialists, Angel Yeast Co. Ltd. and Lallemand Inc. exemplify the vertically integrated archetype with in-house yeast biomass processing capabilities. DSM Nutritional Products occupies a position bridging human-grade and feed-grade qualification pathways. These three anchors represent divergent strategic vectors: Chinese cost-competitive powder production, North American fermentation scale, and European pharmaceutical-grade extraction infrastructure.
| Leading Market Players |
|---|
| Angel Yeast Co. Ltd. |
| Royal Canin SAS |
| Lallemand Inc. |
| DSM Nutritional Products |
| Cargill Inc. |
| ORFFA International Holding B.V. |
| Alltech Inc. |
| Kemin Industries Inc. |
| Lesaffre International SAS |
| Others |
Pricing and Supply Chain Analysis
Antibiotic growth promoter substitution by yeast-derived prebiotics simultaneously concentrates supply geography in Chinese and Brazilian fermentation clusters and compresses pricing economics through enzymatic hydrolysis cost premiums. Powder MOS contracts for Brazilian poultry operations under MAPA IN 15/2014 now trade at spreads reflecting certification grade rather than commodity feed additive benchmarks.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and feed-grade MOS, with EFSA-compliant granules commanding substantial premiums over standard powder formulations. Three-tier pricing structure across premium, standard, and economy levels reflects dual-use production line segregation costs and regulatory compliance investments. Price compression runs through standard powder tiers as Angel Yeast Co. Ltd. and Lallemand Inc. expand captive yeast cell wall extraction capacity. Brazilian integrated protein producers exhibit highest price sensitivity, while European nutraceutical channels show lowest elasticity due to health claim substantiation barriers.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Chinese powder exports seeking EU Feed Hygiene Regulation 183/2005 certification compliance. Supply concentrates in Yangtze River Delta fermentation clusters, São Paulo state yeast processing facilities, and North American Great Lakes distribution hubs. Raw material flows draw from Saccharomyces cerevisiae biomass, mannanase enzyme inputs, and acid hydrolysis chemical reagents. Single-source vulnerability in Chinese yeast cell wall supply creates structural risk. Distribution runs through MAPA-registered wholesalers with in-house nutritionist technical service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic growth promoter bans across major livestock-producing nations constitute a regulatory inflection generating sustained high-growth disruption in prebiotic feed additive procurement. Yeast-derived MOS suppliers face compressed qualification windows and consolidated contract flows.
For Market Incumbents: Shield market position through backward integration into captive yeast fermentation capacity and accelerated EFSA novel food claim substantiation under Regulation 1924/2006. The threat of enzymatic hydrolysis cost escalation from mannanase supply constraints demands in-house enzyme production or long-term offtake agreements with specialty chemical suppliers. For New Entrants and Emerging Players: Anchor in North American swine confinement systems for liquid MOS drinking water applications, the most penetrable segment given limited incumbent technical service infrastructure. White-space targets include companion animal immune support positioning and dual carbon policy alignment for preferential Chinese licensing. A go-to-market angle emphasizing water quality management protocols for aquaculture operations bypasses established powder distribution channels. For Investors and Strategic Acquirers: EU Feed Hygiene Regulation 183/2005 compliance deadlines reshape the acquisition landscape toward EFSA-registered suppliers with segregated human-grade production lines. Long-term viability over the projection horizon favors vertically integrated fermentation specialists with multi-jurisdictional registration portfolios. Target acquisition archetypes include Chinese powder producers seeking European market access and regional distributors with MAPA-registered technical service capabilities. Monitor EFSA prebiotic health claim substantiation rulings as the critical inflection signal for nutraceutical margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Yeast Cell Wall Extraction | Captive supply of Saccharomyces cerevisiae biomass reduces mannanase cost exposure for Brazilian poultry contracts. |
| EFSA Novel Food Claim Substantiation | Regulation 1924/2006 compliance unlocks premium nutraceutical channels with pharmaceutical-grade pricing power. |
| Geographic Registration Portfolio Diversification | Parallel MAPA, MARA, and EU approval frameworks protect against single-jurisdiction regulatory reversal. |
| Long-term Supply Agreement with Integrated Protein Producers | São Paulo corridor consolidation favors single-source contracts with technical service attachments. |
| Joint Venture for Enzymatic Precision Protocols | Partnership with German fermentation technology base displaces legacy acid hydrolysis infrastructure. |
Research Methodology
Desk research of customs/trade data, SEC filings, and EU regulatory submissions preceded structured interviews with feed mill procurement directors, regulatory affairs leads at yeast processing facilities, MAPA registration consultants, and aquaculture technical service managers. Secondary validation drew from EFSA guidance documents, MARA Feed Additive Catalogue amendments, and Brazilian agricultural ministry directives. Bottom-up segment sizing triangulated against top-down market construction from fermentation capacity disclosures.
Variance decomposition across product type, end-use channel, application mechanism, and geographic regulatory cluster anchored the analytical framework. CAGRs derived from segment-level volume trajectories and value-per-unit spreads across the projection horizon. Industry-specific forecast inputs incorporated antibiotic ban implementation timelines and enzymatic hydrolysis cost curves.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory enforcement and stable yeast biomass supply; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Yeast Derivatives Market
Ingredients
Textured Milk Protein Market
Ingredients
South America Lipid Market
Ingredients
Wheat Germ Oil Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Campesterol Market
Ingredients
Banana Flour Market
Ingredients
Barley Malt Extract Market
Ingredients
Almond Ingredients Market
Ingredients
Farnesene Market
Ingredients
Global Dietary Fibers Market
Ingredients
US Choline Bitartrate Market
Ingredients
South America Feed Yeast Market
Ingredients
Industrial Starch Market
Ingredients
GCC Egg Powder Market