
 Vietnam Online Food Delivery Market | 2026-2036
Vietnam Online Food Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Online Food Delivery Market Intelligence
Asset-light franchise and cloud-kitchen leasing models is rewriting capital requirements for new entrants across Vietnamese cities. ShopeeFood leverages its parent ecosystem's logistics density to sustain last-mile cost advantages. GrabFood anchors nationwide rider networks that dominate urban corridor coverage. beFood competes through hyperlocal specialization in secondary cities where larger platforms operate with thinner density.
Vietnam online food delivery encompasses digitally intermediated fulfillment of prepared meals, groceries, and meal-kit components through mobile-optimized routing algorithms and real-time inventory synchronization. The primary commercial purpose centers on reducing friction between food merchants and dispersed urban consumers while capturing transaction data for demand forecasting. Restaurant delivery leads service type revenue as chained F&B brands migrate cloud-kitchen operations onto third-party platforms. Mobile applications capture the dominant platform share, though social media ordering through integrated mini-programs represents the fastest-growing acquisition channel. Digital wallet penetration reshapes payment method mix as cash-on-delivery share recedes in major metros.
Vietnam's Ministry of Industry and Trade enforces Decree 52 on e-commerce transparency, requiring platform disclosure of merchant contracts and commission structures that alters competitive signaling. The country's food safety authority mandates traceability standards for prepared food logistics, conditioning rider hygiene protocols and thermal packaging specifications. Stakeholders must monitor how forthcoming personal data protection regulations intersect with consumer profiling algorithms that currently drive recommendation engines and dynamic pricing architectures.
Market Dynamics
Vietnam's Decree 52 on e-commerce transparency is forcing platforms to disclose merchant commission structures, fundamentally altering how delivery apps compete on pricing and supplier terms.
Growth Catalysts
- Mobile wallet infrastructure:MoMo and ZaloPay penetration in Ho Chi Minh City and Hanoi eliminates cash-handling friction, accelerating order frequency among urban millennials.
- Cloud kitchen real estate models:Asset-light leasing arrangements in Da Nang and Can Tho reduce capital barriers for chained F&B brands expanding delivery-only operations.
- Decree 52 compliance frameworks:Mandatory contract transparency creates standardized playing fields that attract institutional investment into platform logistics networks.
Market Restraints
- Rider wage inflation:Last-mile labor costs in Hanoi surge as competing platforms exhaust the same pool of motorcycle delivery workers during peak hours.
- Single-point platform dependency:Restaurant merchants in secondary cities face margin compression from thin competition among aggregators, limiting negotiation leverage.
- Thermal packaging standards:Vietnam's food safety authority mandates traceable cold-chain compliance that raises per-order fulfillment costs for prepared meals.
Strategic Opportunities
- Tier-two urban corridors:Hai Phong and Bien Hoa exhibit underpenetrated household delivery penetration relative to their disposable income trajectories.
- Grocery-fast convergence:Dark store networks for fresh produce integration with meal platforms create cross-selling density unavailable to pure-play restaurant apps.
- Mini-program commerce:Zalo and Facebook native ordering interfaces bypass app store acquisition costs while capturing social discovery behavior.
Industry Challenges
- Data localization compliance:Forthcoming personal data protection regulations force re-architecture of consumer profiling algorithms that currently power recommendation engines.
- Rider retention systems:High churn among gig workers demands continuous incentive recalibration without eroding per-unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Online Food Delivery Market |
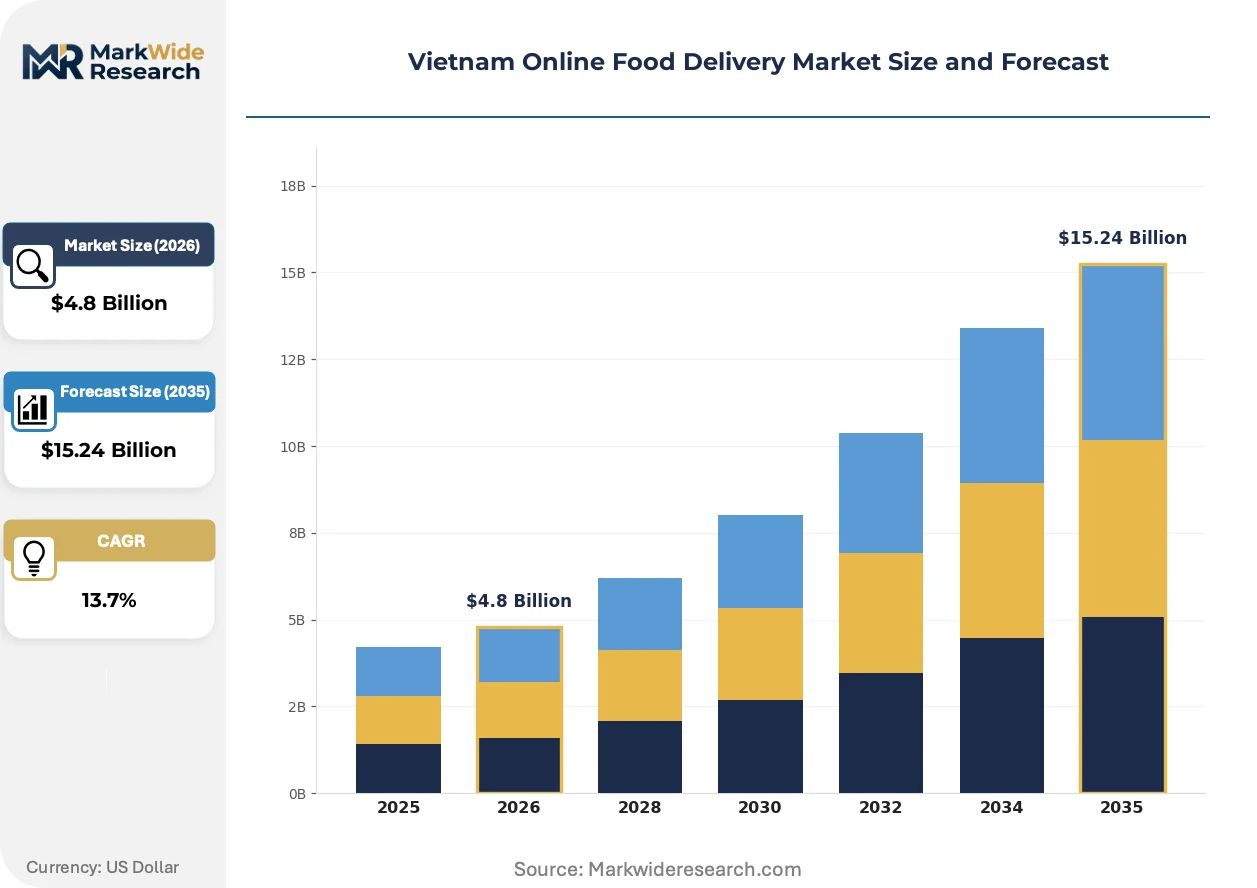
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Restaurant Delivery, Grocery Delivery, Meal Kits, Catering Services Platform: Mobile Applications, Websites, Third-Party Platforms, Social Media Payment Method: Credit Card, Digital Wallet, Cash on Delivery, Bank Transfer Customer Type: Individuals, Corporates, Families, Tourists |
| Companies Covered | Xanh SM Ngon, Eat.vn, ShopeeFood, Vietnammm.com, Foody.vn, GrabFood, Now.vn, Grab Holdings, beFood, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Online Food Delivery Market Strategic Shifts & Innovations
Algorithmic dispatch systems and embedded finance products are compressing the operational stack that separates food merchants from end consumers across Vietnamese cities.
Artificial intelligence-driven demand forecasting is collapsing inventory waste for cloud kitchen operators. Chained F&B brands in Ho Chi Minh City deploy predictive models to pre-position ingredients before lunch and dinner rushes. This capability compresses working capital cycles and reduces spoilage penalties that previously eroded thin delivery margins.
Vietnam's Ministry of Industry and Trade enforces Decree 52 disclosure mandates that strip opacity from platform-merchant contracts. Restaurant operators now benchmark commission rates across competing apps before signing exclusivity arrangements. The regulation most affects small independent eateries in Hanoi that lacked prior visibility into standard terms.
Social commerce integration through Zalo mini-programs displaces standalone app downloads as the dominant customer acquisition channel. Younger demographics in Da Nang discover restaurants through influencer content and complete purchases without leaving messaging interfaces. This behavioral shift concentrates marketing spend on content creators rather than performance advertising on aggregator homepages.
Vietnam Online Food Delivery Market Segmentation
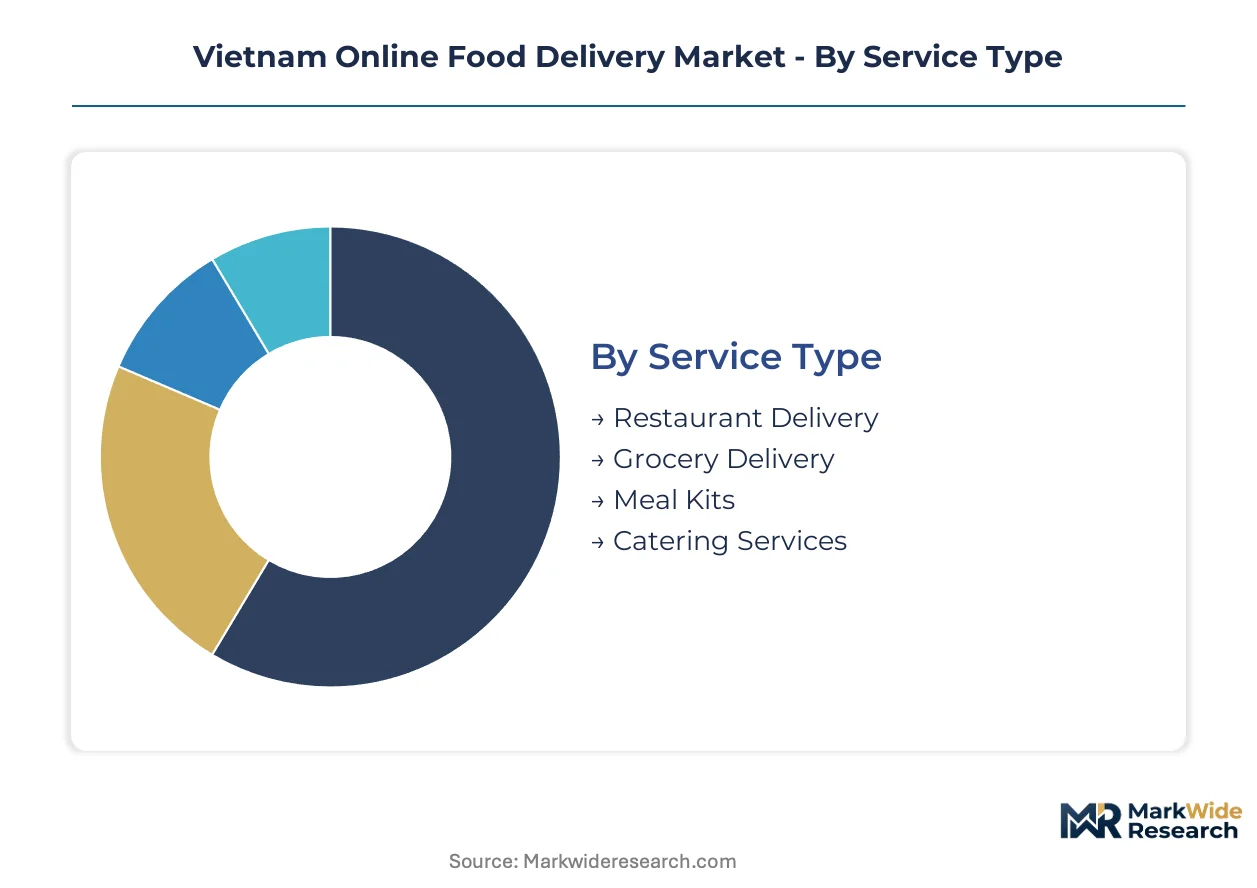
Segmentation reveals how platform economics diverge across service models and customer acquisition channels in Vietnam's food delivery ecosystem. Each dimension exposes distinct margin structures, technology requirements, and regulatory exposure that shape competitive strategy.
Service Type:
Application determines the complexity of logistics orchestration and the depth of merchant relationships required.
- Restaurant Delivery:Prepared meal fulfillment through chained F&B brands and independent kitchens dominates transaction volume. Ho Chi Minh City and Hanoi generate concentrated demand as cloud kitchen operators expand delivery-only footprints to reduce real estate overhead.
- Grocery Delivery:Fresh produce and packaged goods fulfillment demands cold-chain infrastructure and real-time inventory synchronization with supermarket partners. Da Nang and Can Tho exhibit accelerating adoption as dark store networks penetrate secondary urban corridors.
- Meal Kits:Pre-portioned ingredient bundles with recipe instructions target time-constrained households in tier-one cities.
- Catering Services:Bulk-order logistics for corporate events and celebrations require dedicated fleet capacity and advance scheduling systems.
Restaurant delivery holds installed capacity. Grocery delivery is rotating up the share rankings.
Platform:
Channel selection dictates customer acquisition economics and data capture depth for demand forecasting algorithms.
- Mobile Applications:Native iOS and Android apps deliver the richest functionality for order tracking, loyalty programs, and personalized recommendations. Urban millennials in Hanoi and Ho Chi Minh City demonstrate the highest session frequency and average order values through this channel.
- Third-Party Platforms:Aggregator marketplaces like ShopeeFood and GrabFood concentrate merchant supply and consumer demand onto unified logistics networks. Commission structures here face direct scrutiny under Decree 52 disclosure mandates.
- Websites:Desktop and mobile web interfaces serve corporate accounts and older demographics less inclined toward app installation.
- Social Media:Zalo and Facebook mini-programs enable discovery-to-purchase without platform switching, capturing impulse demand from influencer-driven content in Da Nang and Bien Hoa.
Mobile applications capture the dominant transaction share. Social media interfaces are climbing the fastest as acquisition channels.
Payment Method:
Settlement infrastructure shapes working capital cycles and fraud exposure across the transaction stack.
- Digital Wallet:MoMo and ZaloPay integration eliminates cash-handling friction and enables instant refund processing. Ho Chi Minh City's dense merchant acceptance network accelerates wallet preference among urban professionals.
- Cash on Delivery:Motorcycle riders collect physical payment at the doorstep, retaining relevance in secondary cities where digital banking penetration lags. Rider safety protocols and reconciliation overhead constrain platform margin here.
- Credit Card:Visa and Mastercard rails support higher-value corporate catering orders with chargeback protection.
- Bank Transfer:Direct debit arrangements appeal to small merchants seeking lower processing fees than card networks impose.
Digital wallet penetration is accelerating most quickly in major metros. Cash on delivery retains defensive share in tier-two corridors.
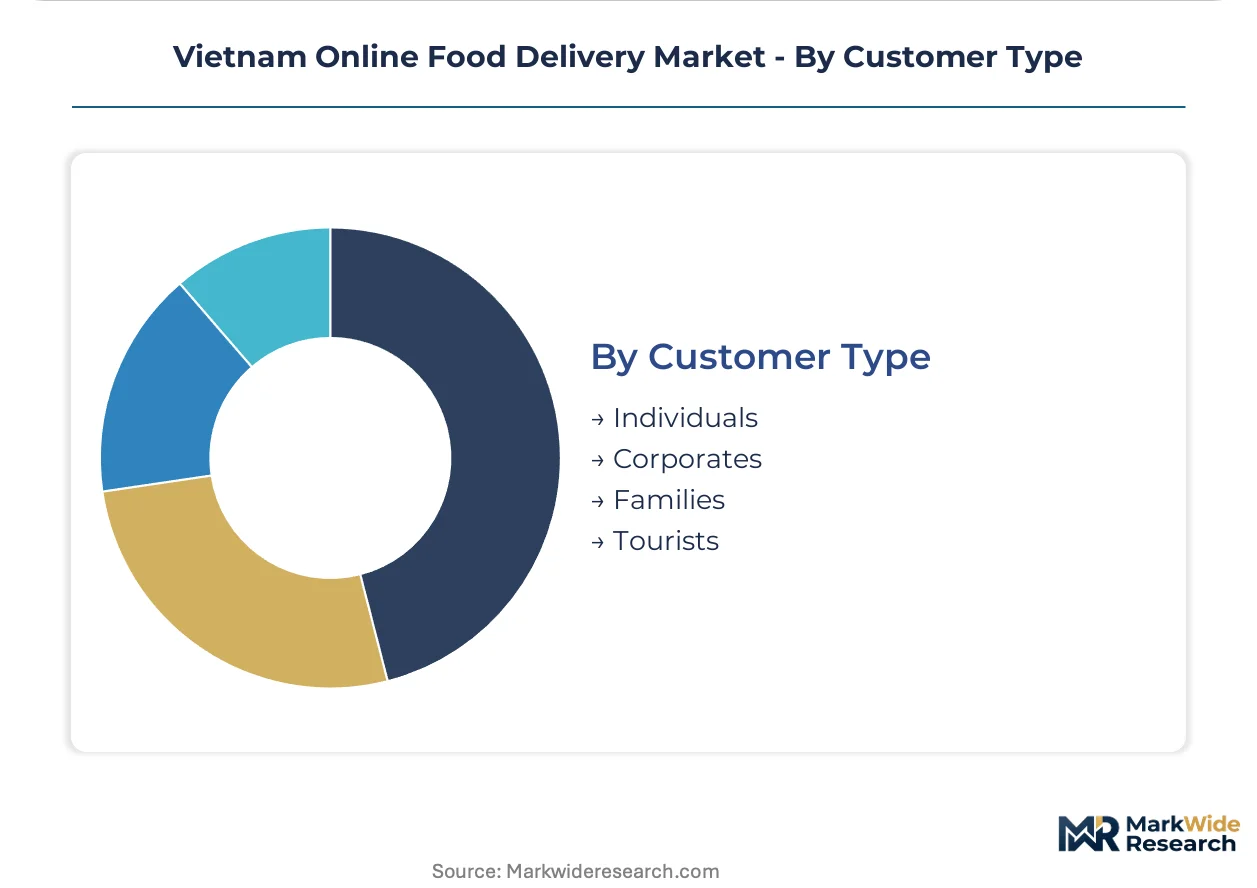
Customer Type:
End-user profile determines order frequency patterns, price sensitivity, and platform loyalty program design.
- Individuals:Single-person households and young professionals generate the highest order frequency through mobile apps, with demand concentrated in Ho Chi Minh City's central districts during lunch and dinner rushes.
- Families:Multi-person households exhibit larger basket sizes and stronger preference for grocery-fast convergence offerings that combine meal and pantry replenishment.
- Corporates:B2B accounts demand invoicing integration, volume discounts, and scheduled delivery windows for employee meal programs and client entertainment.
- Tourists:Short-stay visitors rely heavily on English-language interfaces and international payment methods, with demand clustering around Hanoi and Ho Chi Minh City hospitality districts.
Individuals command the dominant order frequency. Family segment penetration is expanding most steeply as grocery integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's online food delivery sector exhibits concentrated demand in coastal export corridors while inland provinces develop through domestic consumption corridors. Trade balance dynamics in processed foods shape merchant platform participation across sub-regional markets.
Ho Chi Minh City Metropolitan Area
Mobile wallet penetration through MoMo and ZaloPay drives order frequency among young professionals in District 1 and District 7. Vietnam's Ministry of Industry and Trade enforces Decree 52 disclosure mandates that standardize platform-merchant contract transparency. Cloud kitchen clusters in Thu Duc City expand delivery-only footprints as chained F&B brands reduce real estate overhead.
Hanoi Capital Region
Corporate catering demand from government and diplomatic quarters generates high-value B2B order streams during weekday lunch windows. The country's food safety authority mandates traceable cold-chain compliance for prepared meal logistics. Rider wage inflation concentrates in Cau Giay and Dong Da districts where competing platforms exhaust motorcycle delivery labor pools.
Da Nang Central Corridor
Tourism-driven demand from short-stay visitors sustains English-language interface requirements and international payment method acceptance. Provincial authorities align with national e-commerce transparency frameworks while adapting enforcement to smaller merchant bases. Dark store networks for fresh produce penetrate the urban core ahead of pure-play grocery competitors.
Hai Phong Northern Port
Industrial zone worker populations create dense lunch-time demand clusters around manufacturing parks in Dương Kinh and Hồng Bàng districts. Local implementation of national data protection regulations conditions consumer profiling algorithm architectures for platforms entering the market. Underpenetrated household delivery penetration relative to disposable income trajectories attracts platform expansion investment.
Can Tho Mekong Delta
Agricultural commodity processing centers generate merchant supply for farm-to-table delivery concepts targeting urban households. Provincial commerce departments enforce Decree 52 contract disclosure requirements with lighter administrative capacity than major metros. Asset-light cloud kitchen leasing models reduce capital barriers for regional F&B brands testing delivery-only operations.
Vietnam Online Food Delivery Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in logistics infrastructure and payment settlement layers. The vendor structure concentrates around three dominant aggregators with nationwide rider networks, while niche operators exploit hyperlocal density gaps in secondary cities. Two strategic archetypes emerge: ecosystem-leveraged platforms with parent-company logistics density, and specialized regional apps with concentrated urban coverage. Competitive moves center on cloud kitchen real estate partnerships and social commerce integration through messaging mini-programs.
Among Vietnam-based delivery platforms, ShopeeFood and beFood exemplify contrasting scale strategies. ShopeeFood occupies a position leveraging parent-ecosystem logistics density for last-mile cost advantages across tier-one corridors. beFood sits within the hyperlocal specialization archetype, anchoring competitive position in secondary cities where larger platforms operate with thinner density. Grab Holdings represents the integrated super-app model, embedding food delivery within broader mobility and financial services architectures.
| Leading Market Players |
|---|
| Xanh SM Ngon |
| Eat.vn |
| ShopeeFood |
| Vietnammm.com |
| Foody.vn |
| GrabFood |
| Now.vn |
| Grab Holdings |
| beFood |
| Others |
Cost & Logistics Intelligence
Single-source dependency on ShopeeFood and GrabFood rider networks determines both commission tier spreads and supply chain shape across Vietnamese cities. Platform concentration in Ho Chi Minh City and Hanoi compresses merchant margin pools while Decree 52 disclosure mandates strip opacity from contract negotiations.
Pricing Analysis
Industrial OEM buyers anchor commission-based pricing structures where chained F&B brands command volume discounts against independent kitchens. Price differentiation rests on order frequency thresholds and cloud kitchen certification tiers under Vietnam's food safety authority protocols. Commission pressure intensifies in secondary cities where thin platform competition erodes merchant negotiation leverage. Small independent eateries exhibit highest price sensitivity while corporate catering accounts absorb premium pricing for scheduled delivery windows.
Supply Chain Analysis
Cloud kitchen operators and third-party logistics providers hold concentrated fulfillment capacity across Vietnam's tier-one urban corridors. Geographic supply concentration centers on Ho Chi Minh City, Hanoi, and Da Nang where dark store networks penetrate fastest. Raw material dependencies include thermal packaging materials, motorcycle fleet assets, and real-time dispatch software licenses. Supply chain risk hinges on single-point platform dependency in secondary cities where rider pool exhaustion triggers wage inflation. Distribution runs through mobile-optimized routing algorithms with real-time inventory synchronization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home cooking substitution and quick-commerce grocery expansion threaten prepared meal incumbents across Vietnamese urban households. Platform operators must defend share against convenience retail convergence.
For Market Incumbents: Build data moats through AI-driven demand forecasting that pre-positions cloud kitchen inventory before peak rushes. Consolidate position by deepening vertical control over last-mile rider networks in Cau Giay and Dong Da districts where wage inflation concentrates. Invest in Zalo mini-program integration to capture social discovery behavior displacing standalone app downloads. For New Entrants and Emerging Players: Pursue hyperlocal specialization in Hai Phong and Bien Hoa where larger platforms operate with thinner density and household delivery penetration lags disposable income trajectories. Target grocery-fast convergence offerings that combine meal and pantry replenishment for multi-person households. Execute go-to-market through influencer content partnerships rather than performance advertising on aggregator homepages. For Investors and Strategic Acquirers: Forthcoming personal data protection regulations reshape the acquisition landscape by forcing re-architecture of consumer profiling algorithms. Long-term viability favors platforms with embedded finance products and parent-ecosystem logistics density. Monitor Decree 52 enforcement patterns across provincial commerce departments as inflection indicator for competitive transparency costs.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Real Estate Partnership | Asset-light leasing in Thu Duc City reduces capital barriers for chained F&B brands expanding delivery-only operations. |
| Social Commerce Integration | Zalo mini-program deployment captures impulse demand from influencer-driven content without app store acquisition costs. |
| Dark Store Network Expansion | Fresh produce fulfillment infrastructure in Da Nang creates cross-selling density unavailable to pure-play restaurant apps. |
| Rider Retention System Investment | Incentive recalibration platforms reduce churn among gig workers in Hanoi without eroding per-unit economics. |
| Decree 52 Compliance Framework | Contract transparency standardization attracts institutional investment into platform logistics networks across Vietnamese cities. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud kitchen operators, platform logistics directors, chained F&B brand expansion leads, and provincial commerce department officials. Secondary validation drew from Vietnam Ministry of Industry and Trade enforcement bulletins, food safety authority traceability guidelines, digital wallet penetration statistics, and customs records on thermal packaging imports. Bottom-up merchant surveys triangulated against top-down platform transaction estimates.
Calibration anchored historical penetration rates against mobile wallet adoption curves and cloud kitchen lease commencement data across the analysis window. Segmentation dimensions modeled include service type, platform channel, payment method, and customer archetype with regional urban tier as cross-cutting variable. CAGRs derived from logistic diffusion curves fitted to observed adoption patterns in comparable Southeast Asian markets. Forecast inputs incorporated Decree 52 compliance cost assumptions and rider wage inflation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ecosystem-leveraged platforms or quick-commerce entrants would shift outcomes beyond projected ranges. Quarterly review of provincial Decree 52 enforcement intensity and dark store network expansion cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Gas Floor Fryers Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Global Online Food Delivery Services Market
Food Service
Europe Food Away from Home Market
Food Service
Cambodia Foodservice Market
Food Service
Commercial Burger Grill Market
Food Service
Stirrers Market
Food Service
India Foodservice Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Electric Tiffin Market
Food Service
Steam Tables and Food Well Market
Food Service
Europe Cloud Kitchen Market
Food Service
Spain Food Service Market
Food Service
India Inflight Catering Market
Food Service
Mobile Food Services Market
Food Service
United Kingdom Full Service Restaurants Market