
 Mobile Food Services Market | 2026-2036
Mobile Food Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Food Services Market Outlook
Subscription-based catering contracts is rebalancing how mobile food services monetize recurring revenue beyond single-event transactions. Kogi BBQ leverages its Korean-Mexican fusion specialization to anchor brand loyalty across Los Angeles and beyond. The Halal Guys sustains geographic dominance through disciplined franchise expansion into multiple metropolitan clusters. Cousins Maine Lobster competes by controlling premium seafood sourcing that differentiates its trailer and truck operations from commodity competitors.
Mobile food services comprise commercial food preparation and retail operations executed from motorized or towable vehicles equipped with commercial-grade cooking, refrigeration, and ventilation systems designed for on-site service at variable locations. These units typically operate under local health department permits with commissary kitchen requirements and serve construction sites, festivals, business districts, and residential neighborhoods where fixed-location restaurants prove impractical. Food trucks dominate capital investment and media visibility within the service type dimension, while the gourmet menu category captures premium pricing power through chef-driven concepts and Instagram-native branding. The festivals customer type generates concentrated revenue spikes during summer months, whereas corporate events deliver more predictable year-round demand with higher average order values and advance booking cycles.
FDA food safety standards and local health department inspection regimes govern ingredient handling, temperature control, and worker hygiene across US-based operations, while municipal zoning boards and street vending ordinances determine permissible operating locations, hours, and proximity restrictions near brick-and-mortar restaurants. The National Fire Protection Association codes additionally regulate propane and electrical systems installed within converted vehicles and custom-built trailers. Stakeholders must monitor how municipal permit scarcity, commissary kitchen mandates, and evolving food delivery platform commission structures reshape unit economics and expansion feasibility across target markets.
Market Dynamics
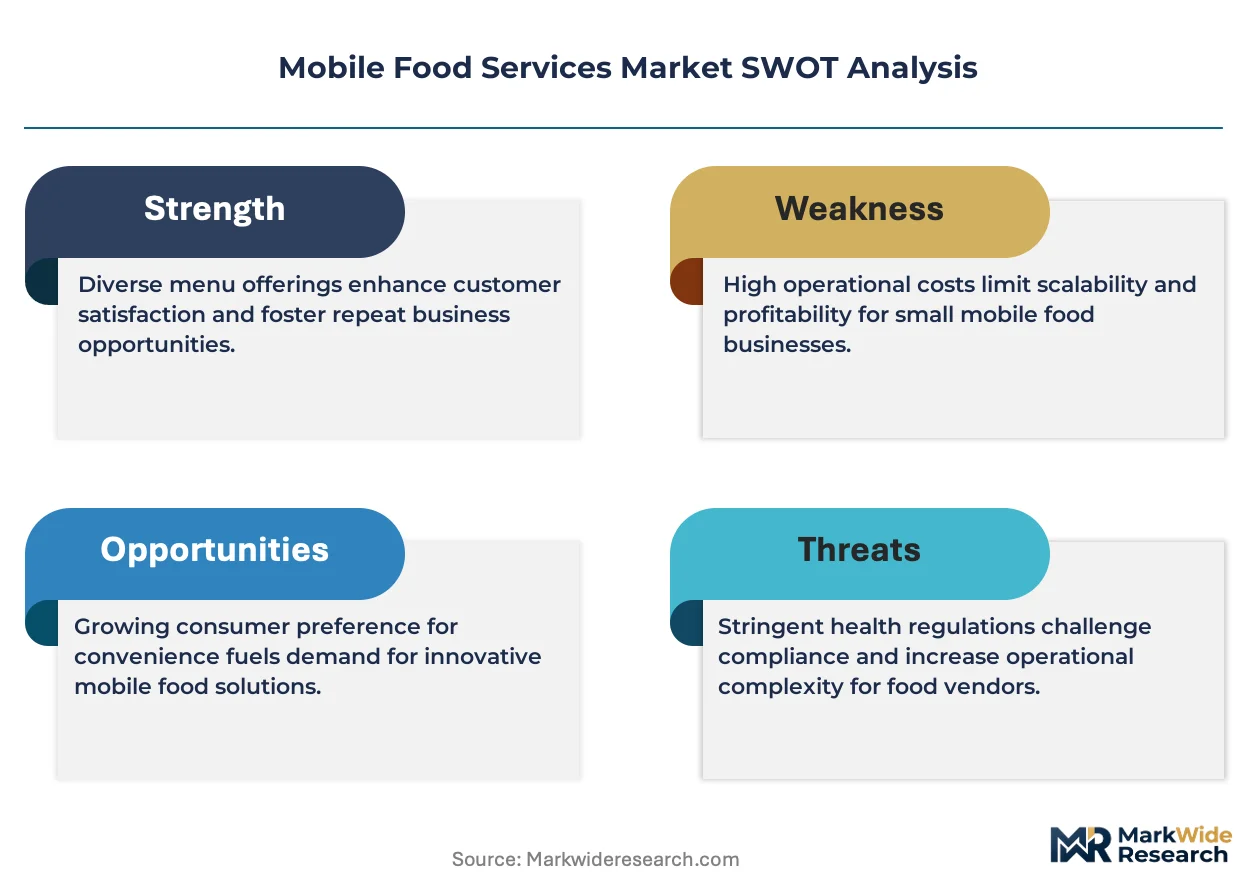
Municipal permit scarcity and commissary kitchen mandates are compressing operational margins while simultaneously creating barriers to entry that favor established operators with capital reserves.
Growth Catalysts
- Corporate Outsourcing:Enterprise catering contracts for employee dining and hospitality functions are generating predictable recurring revenue streams with higher advance booking cycles than festival-dependent operations.
- US FDA Food Safety Standards:Standardized ingredient handling and temperature control protocols are elevating consumer trust and enabling premium pricing for compliant operators across metropolitan clusters.
- Cloud Kitchen Convergence:Shared commissary infrastructure is reducing fixed overhead burdens for mobile operators while satisfying health department mandates in permit-restricted jurisdictions.
Market Restraints
- Propane System Compliance:National Fire Protection Association codes governing vehicle-installed fuel systems impose specialized retrofit costs that strain capital reserves of independent operators.
- Permit Scarcity in Tier-1 Cities:New York, London, and Mumbai operate capped vending license regimes that artificially constrain fleet expansion regardless of underlying demand.
- Brick-and-Mortar Proximity Restrictions:Municipal zoning boards enforce buffer zones protecting fixed-location restaurants from mobile competition in high-traffic commercial districts.
Strategic Opportunities
- Subscription Catering Models:Recurring revenue contracts for corporate campuses and construction sites are displacing single-event transactions with superior cash flow predictability.
- Indian Metropolitan Expansion:Mumbai's evolving street vending frameworks and FSSAI standardization are opening compliant operational pathways in previously informal markets.
- Instagram-Native Branding:Chef-driven concepts with visual menu differentiation are capturing premium pricing power through social media-driven customer acquisition.
Industry Challenges
- Commissary Kitchen Access:Local health department mandates requiring off-site food preparation and storage facilities create geographic constraints on route flexibility.
- Platform Commission Compression:Third-party delivery aggregator fee structures are eroding unit economics for operators dependent on digital order channels.
- Cross-Jurisdictional Permitting:Operators seeking multi-city presence face fragmented regulatory regimes with non-transferable licenses and inspection protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Food Services Market |
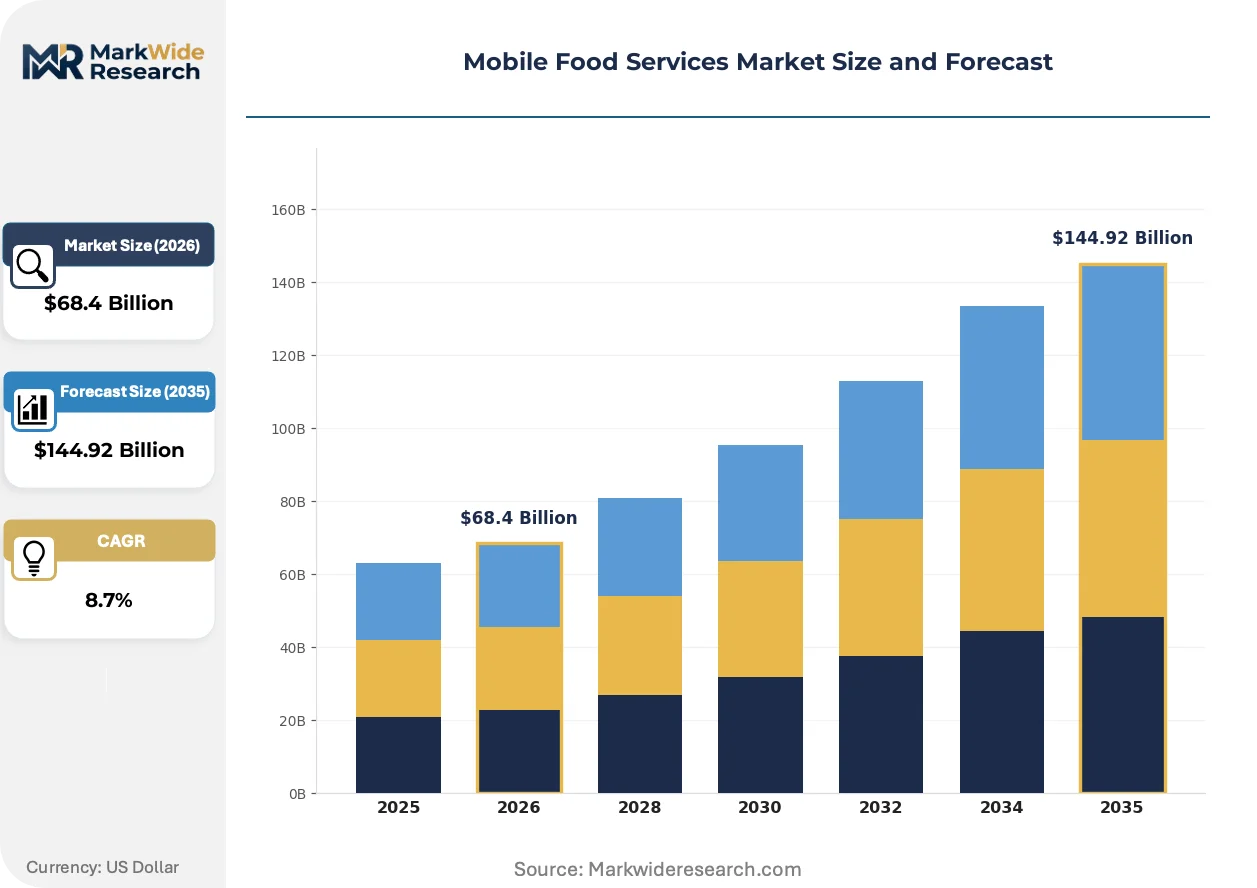
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Trucks, Carts, Trailers, Vans Menu Type: Vegan, Gourmet, Fast Food, Beverages Customer Type: Corporate Events, Festivals, Private Parties, Public Gatherings Sales Channel: Online Orders, Walk-Up Customers, Catering, Delivery Services |
| Companies Covered | Kogi BBQ LLC, Nemo’s Wood-Fired Pizza LLC, Kona Ice LLC, Cruising Kitchens, Prestige Food Trucks, The Halal Guys LLC, The Mighty Quinn’s BBQ LLC, M&R Specialty Trailers and Trucks, Cousins Maine Lobster Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Food Services Market Strategic Shifts
Digital ordering infrastructure and social media discovery mechanisms are restructuring how mobile food services acquire customers and manage demand spikes across variable locations.
Electric vehicle drivetrains and battery-powered kitchen systems are converging with municipal zero-emission mandates in urban cores. Fleet operators in Los Angeles and London are piloting all-electric trucks to satisfy clean air zone requirements. This technology convergence is compressing total cost of ownership calculations while expanding permissible operating hours in noise-restricted districts.
The EU Green Deal's circular economy requirements are mandating sustainable packaging transitions across foodservice operations. Brussels and Amsterdam have enacted single-use plastic bans affecting disposable serviceware procurement. Gourmet menu operators targeting corporate event segments are responding fastest, integrating compostable materials into premium brand positioning.
Advance booking platforms are displacing spontaneous foot traffic as the dominant demand capture mechanism. Corporate event coordinators and festival organizers now expect integrated reservation and payment systems. This behavioral shift concentrates most visibly in the United States, where enterprise procurement departments route employee dining spend through contracted vendor networks with pre-negotiated rate structures.
Mobile Food Services Market Segmentation
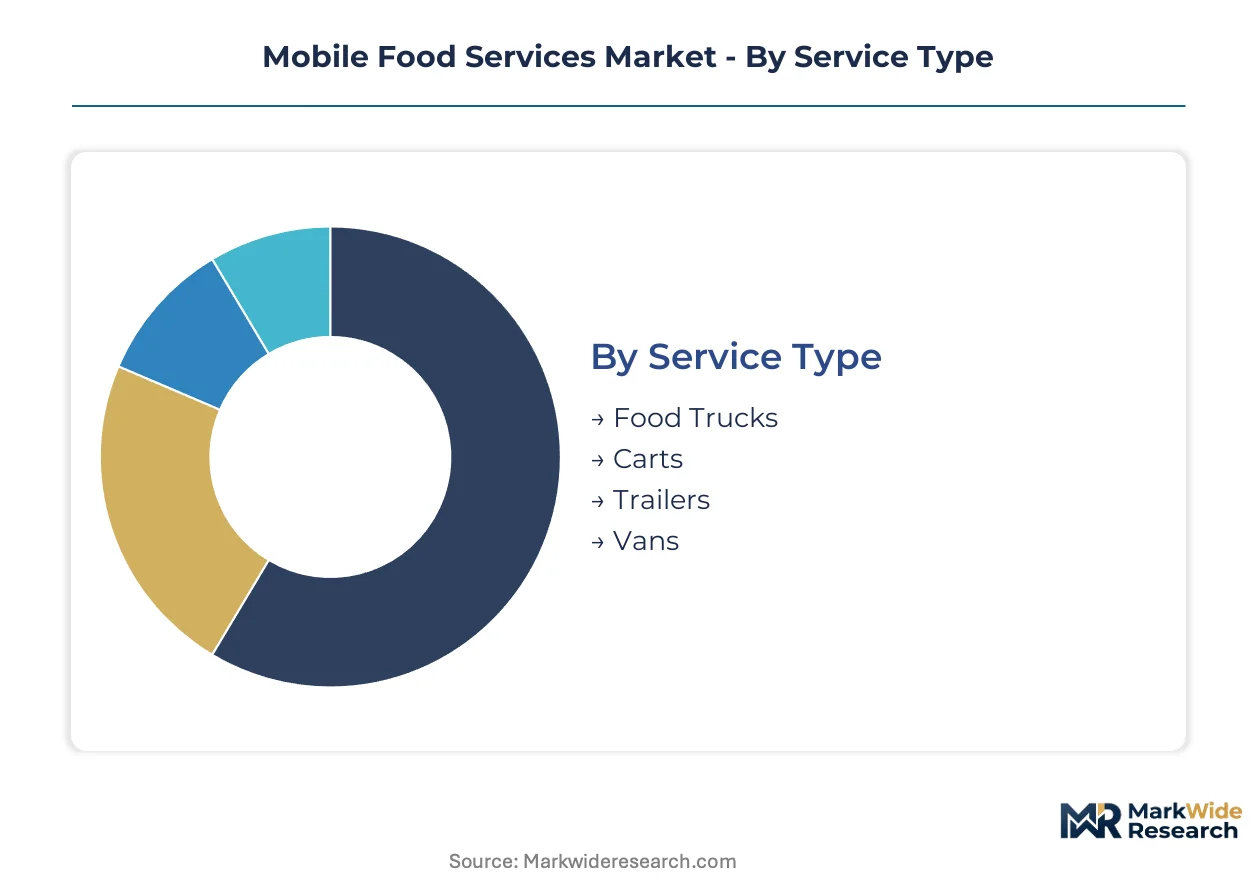
Segmentation in mobile food services determines capital allocation, route planning, and permit acquisition strategies. Operators must match vehicle specifications to customer density patterns while navigating divergent regulatory requirements across service formats.
Service Type:
Capital intensity varies sharply across motorized and towable formats, with drivetrain and kitchen system configurations driving upfront investment tiers.
- Food Trucks:Self-propelled commercial vehicles integrate commercial-grade cooking, refrigeration, and ventilation systems with on-board power generation. These units command premium positioning in Los Angeles and Austin business districts where municipal codes restrict stationary vending. Fleet operators leverage food trucks for maximum route flexibility and brand visibility.
- Trailers:Towable units detach from passenger vehicles to reduce engine maintenance costs while preserving kitchen equipment investments. Demand concentrates at construction sites and festival grounds in Texas and Florida where operators park for multi-day engagements. The format sacrifices mobility for lower insurance premiums and simplified mechanical servicing.
- Carts:Non-motorized push units carry limited prep equipment and rely on commissary kitchens for food safety compliance. Street vending corridors in New York City and Mumbai deploy carts for high-volume, low-overhead breakfast and snack service.
- Vans:Modified passenger vehicles balance cargo capacity with fuel efficiency for beverage-focused and pre-packaged food operations. Corporate catering contracts in London and Chicago favor vans for discrete client site access.
Food trucks absorb the bulk of installed capacity; trailers are expanding most quickly in festival-dependent revenue models.
Menu Type:
Ingredient sourcing complexity and equipment specialization separate premium culinary concepts from commodity foodservice formats.
- Gourmet:Chef-driven concepts featuring specialized proteins, artisanal preparations, and Instagram-native plating command pricing premiums at corporate events. Los Angeles operators like Kogi BBQ anchor brand loyalty through Korean-Mexican fusion specialization. The segment demands higher equipment investment but generates superior unit economics through advance booking cycles.
- Fast Food:Standardized burger, sandwich, and fried item menus optimize throughput velocity at construction sites and public gatherings. Commodity sourcing and simplified prep protocols reduce labor costs across high-volume routes.
- Vegan:Plant-based protein alternatives and allergen-conscious preparations target health-focused consumer clusters in Portland and Brooklyn. Menu development requires specialized supplier relationships and cross-contamination protocols.
- Beverages:Coffee, smoothie, and craft cocktail concepts minimize food safety complexity while capturing impulse purchases. Seasonal demand spikes concentrate at summer festivals and morning commuter corridors.
Gourmet captures the steepest expansion trajectory; fast food retains the largest addressable customer base.
Customer Type:
Booking predictability and average order value separate enterprise procurement relationships from transactional consumer sales.
- Corporate Events:Enterprise catering contracts for employee dining and hospitality functions generate recurring revenue with advance payment terms. Technology campuses in Seattle and Austin route dining spend through contracted vendor networks with pre-negotiated rate structures.
- Festivals:Concentrated summer revenue spikes at music and food events demand seasonal staffing surges and equipment redundancy. Permit scarcity at tier-one events creates auction dynamics for vendor selection.
- Private Parties:Wedding receptions and milestone celebrations command premium pricing for customized menu development and dedicated service windows. Geographic dispersion requires flexible routing capabilities.
- Public Gatherings:Parks, street fairs, and community events provide entry-level market access for new operators with limited capital reserves. Municipal vending license caps constrain participation in high-traffic locations.
Corporate events deliver the most predictable cash flow; festivals show the highest revenue volatility.
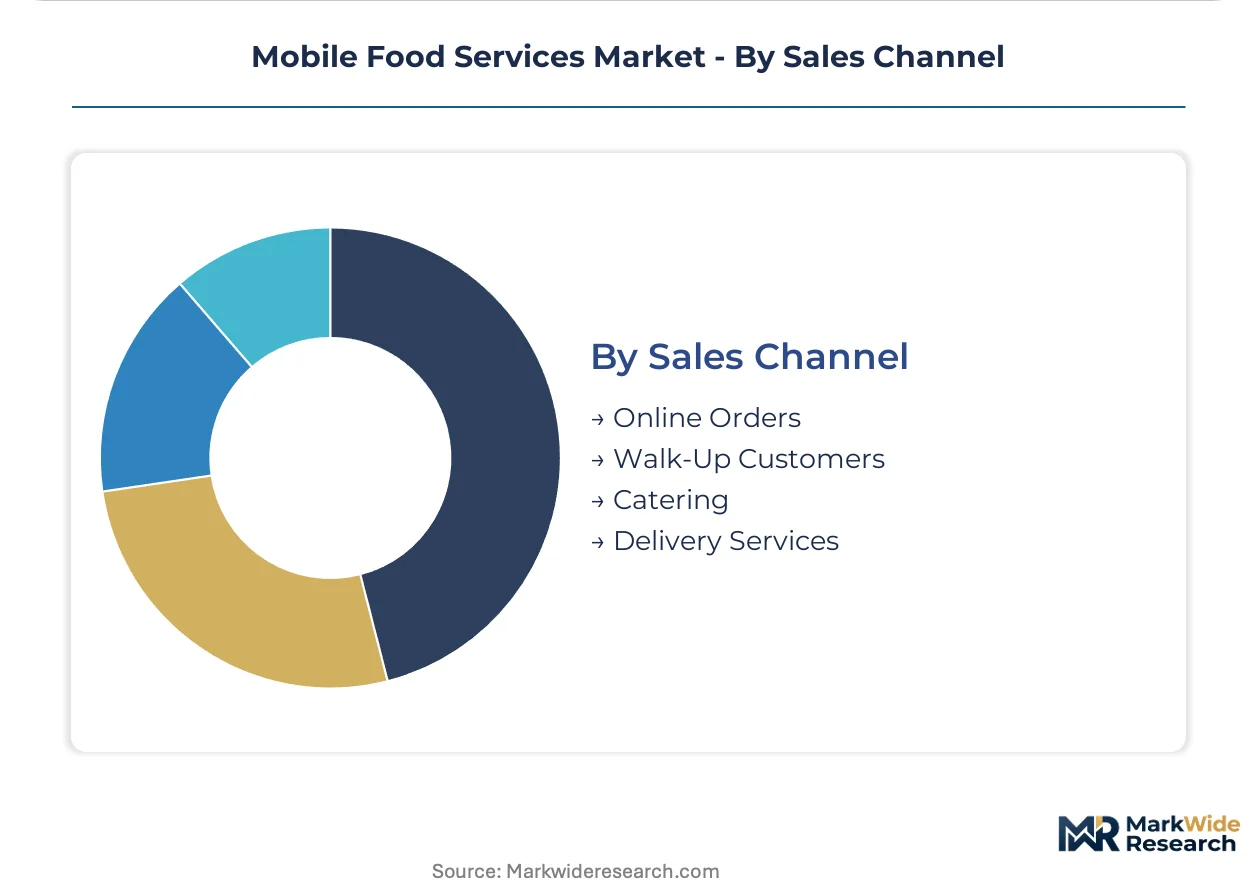
Sales Channel:
Digital infrastructure investment requirements and commission structures reshape how operators capture demand across spontaneous and planned transactions.
- Catering:Direct B2B relationships bypass platform commissions and enable customized menu negotiation. Advance booking platforms now dominate corporate procurement workflows in the United States.
- Walk-Up Customers:Spontaneous foot traffic at high-visibility locations depends on municipal zoning permissions and proximity to office districts. Buffer zone restrictions near brick-and-mortar restaurants constrain viable operating positions.
- Online Orders:Proprietary ordering systems and aggregator platforms capture demand ahead of physical arrival. Commission compression from third-party delivery services erodes margins for operators dependent on digital channels.
- Delivery Services:Third-party logistics integration extends service radius beyond pedestrian catchment areas. Vehicle-mounted warming equipment and packaging investments address food quality degradation during transport.
Catering claims the highest margin structure; online orders are gaining share fastest among urban operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of food trucks and mobile kitchen equipment concentrates in manufacturing hubs across the United States and Germany, while consumption spreads through metropolitan service corridors in North America, Europe, and Asia-Pacific where municipal permit systems enable fleet operations.
United States
Corporate catering contracts and festival circuits drive fleet expansion in Austin, Los Angeles, and New York. FDA food safety standards and municipal health department inspection regimes govern operational compliance. Los Angeles anchors the nation's most mature food truck culture with established supply chains and consumer acceptance.
Germany
Street food festivals and corporate campus dining sustain demand in Berlin, Munich, and Hamburg. EU Green Deal circular economy requirements mandate sustainable packaging transitions affecting disposable serviceware procurement. Berlin's Kreuzberg district hosts Europe's densest concentration of gourmet mobile operators.
United Kingdom
Corporate event catering and wedding receptions generate premium pricing opportunities in London, Manchester, and Birmingham. Municipal zoning boards enforce buffer zones protecting fixed-location restaurants from mobile competition. London's South Bank and Shoreditch districts concentrate permitted vending corridors.
India
Construction site catering and informal street vending create hybrid demand in Mumbai, Delhi, and Bangalore. FSSAI standardization and evolving municipal street vending frameworks are opening compliant operational pathways. Mumbai's Marine Drive and Bandra corridors concentrate permitted mobile food clusters.
Australia
Festival circuits and beachside tourism sustain seasonal revenue spikes in Sydney, Melbourne, and Brisbane. Local council health regulations and noise-restricted operating hours constrain permissible service windows. Sydney's Bondi Beach and Melbourne's laneway precincts anchor premium mobile food positioning.
Mobile Food Services Market Competitive Environment
Top-tier vendors anchor premium gourmet positioning, while mid-tier fabricators compete on equipment customization and regional permit navigation. The vendor base stratifies across chef-driven concept operators, specialized trailer manufacturers, and fleet-scale franchise systems. Three archetypes dominate: fusion cuisine specialists, seafood sourcing controllers, and equipment fabricators with commissary kitchen integration. Competitive moves concentrate on geographic franchise expansion and proprietary booking platform development.
Within the fusion-cuisine tier, Kogi BBQ LLC exemplifies Korean-Mexican specialization that anchors brand loyalty across Los Angeles and beyond. The Halal Guys LLC occupies a position within disciplined franchise expansion models, sustaining geographic dominance through metropolitan cluster penetration. Cousins Maine Lobster Inc. represents premium seafood sourcing control that differentiates trailer and truck operations from commodity competitors.
| Leading Market Players |
|---|
| Kogi BBQ LLC |
| Nemo's Wood-Fired Pizza LLC |
| Kona Ice LLC |
| Cruising Kitchens |
| Prestige Food Trucks |
| The Halal Guys LLC |
| The Mighty Quinn's BBQ LLC |
| M&R Specialty Trailers and Trucks |
| Cousins Maine Lobster Inc. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into commissary kitchen infrastructure anchors both supply security and pricing power for fleet-scale operators, while independent vendors face margin compression from third-party facility rentals and municipal permit scarcity.
Pricing Analysis
Margin tightening in the gourmet tier reflects cloud kitchen convergence and equipment specialization costs. Three-tier pricing structure across premium chef-driven concepts, standard fast-casual formats, and economy construction-site vendors separates average order values. Cost-down pressure on commodity fast-food operators accelerates because construction site procurement departments negotiate volume contracts. Corporate event buyers show lowest price sensitivity; festival-dependent operators face highest bargaining pressure.
Supply Chain Analysis
Refurbishment flows for commercial kitchen equipment and vehicle drivetrains create secondary supply channels for cost-conscious entrants. Manufacturing concentrates in the United States, Germany, and China for custom truck bodies and refrigeration systems. Stainless steel fabrication, propane systems, and NSF-certified components draw from metals processing and specialized fabrication networks. Single-source vulnerability sits with EPA-certified refrigeration compressor suppliers. Distribution runs through regional equipment dealers and direct fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal permit caps in tier-one cities constrain fleet expansion regardless of underlying demand, propping pricing power for incumbents with grandfathered licenses.
For Market Incumbents: Anchor subscription catering contracts with enterprise procurement departments to displace transactional festival revenue. Deepen backward integration into commissary kitchen ownership to defend against rising facility rental costs. Pursue multi-city permit portfolios before municipal caps tighten further.
For New Entrants and Emerging Players: The mid-tier price gap between Kogi BBQ-style gourmet concepts and commodity fast-food operators offers white-space targeting. Construction site catering in secondary US metros and Mumbai's emerging compliant corridors present lowest barrier-to-entry expansion paths. Lead with Instagram-native branding to bypass traditional location-dependent discovery.
For Investors and Strategic Acquirers: Exit pathways concentrate in franchise system acquisitions and fleet-scale regional rollups. Five-to-ten year viability favors operators with captive commissary infrastructure and multi-jurisdiction permit holdings. Monitor FSSAI enforcement intensity in Indian metros as inflection indicator for emerging market compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Kitchen Acquisition | Captive facility ownership eliminates third-party rental compression and satisfies FDA commissary mandates. |
| Corporate Catering Platform Integration | Advance booking systems align with enterprise procurement workflows in Seattle and Austin technology corridors. |
| Electric Fleet Transition | Zero-emission drivetrains satisfy Los Angeles clean air zone requirements and expand noise-restricted operating hours. |
| Franchise Territory Expansion | Disciplined metropolitan cluster penetration replicates The Halal Guys' geographic dominance model. |
| Sustainable Packaging Certification | EU Green Deal compliance enables premium positioning in Berlin and Amsterdam corporate event segments. |
Study Parameters
Document review covered FDA food code filings, municipal health department inspection records, and FSSAI standardization guidelines, complemented by interviews with food truck fleet operators, commissary kitchen managers, corporate catering procurement officers, and municipal licensing administrators. Secondary validation drew from National Fire Protection Association codes, EPA commercial vehicle emissions data, and EU Green Deal circular economy directives. Bottom-up unit economics modeling triangulated against top-down metropolitan demand aggregation.
Revenue and fleet size outputs across the projection horizon reflect segment-level modeling across service type, menu category, customer archetype, and sales channel dimensions. CAGRs derived from historical permit issuance rates, corporate catering contract growth patterns, and festival circuit expansion trajectories. Industry-specific inputs included propane system retrofit cost curves and third-party delivery platform commission trajectories.
Inputs from municipal licensing databases and corporate procurement survey panels were available through the study window; gaps in informal street vendor revenue reporting introduce uncertainty bands around India market sizing. Forecasts reflect documented assumptions regarding permit cap trajectories and cloud kitchen penetration rates. Practitioners should monitor EPA zero-emission mandate acceleration and FSSAI enforcement staffing levels for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Meal Kit Delivery Services Market
Food Service
Latin America Online Grocery Market
Food Service
Healthy Takeout Market
Food Service
Rotisseries Market
Food Service
Netherlands Food Service Market
Food Service
Ice Cream Carts Market
Food Service
Commercial Rice Cooker Market
Food Service
Singapore Food Service Market
Food Service
Virtual Kitchen Market
Food Service
Beverage Coaster Market
Food Service
Commercial Griddle Market
Food Service
Europe Airline Catering Services Market
Food Service
Restaurant Takeout Market
Food Service
One-Off Chopsticks Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market