
 US Packaged Salads Market | 2026-2036
US Packaged Salads Market Size, Share, and Industry Trends Forecast 2026-2036
US Packaged Salads Market Insights
Single-serve salad kits bundled with dressings, toppings, and protein pouches is repositioning household purchasing away from bulk bagged greens toward complete meal solutions. Taylor Farms leverages vertical integration from field processing to retail distribution to sustain cost advantages across the Southeast and Midwest. Dole Food Company Inc. anchors its position through scale manufacturing in California and Florida, while Gotham Greens differentiates via controlled-environment agriculture in urban proximity to major metropolitan demand centers.
US packaged salads comprise fresh-cut leafy greens, vegetables, grains, proteins, and dressings processed under refrigerated cold chain conditions with target shelf lives of five to fourteen days, serving retail and food service channels seeking labor-free meal preparation. Ready-to-eat salads and salad kits command the largest volume positions due to their alignment with time-constrained consumer routines, while single-serve formats in bowl packaging are capturing faster velocity in convenience-oriented channels. Clamshell and bowl packaging types dominate refrigerated retail sets, with pouch formats emerging in protein-addition components that extend product versatility without compromising seal integrity.
FDA Food Safety Modernization Act traceability requirements and USDA organic standards shape product formulation, supplier qualification, and labeling obligations across the category. State-level California Leafy Greens Marketing Agreement protocols and OSHA agricultural worker safety inspections further condition harvest and processing operations. Stakeholders must monitor pending FDA agricultural water quality rules and evolving state plastic packaging bans to anticipate compliance investments and packaging material transitions.
Market Dynamics
The FDA Food Safety Modernization Act traceability mandates are compressing supplier qualification timelines while California's Central Valley growing concentration creates geographic vulnerability in fresh supply chains.
Growth Catalysts
- Quick-service restaurant expansion:Food service operators from corporate cafeterias to convenience stores are widening grab-and-go salad sets as labor costs drive pre-prepared meal adoption.
- USDA organic certification premiums:Certified suppliers capture shelf-space advantages as retailers respond to consumer willingness-to-pay for verified organic leafy greens.
- Controlled-environment agriculture:Urban greenhouse operations near Chicago, New York, and Denver are shortening farm-to-retail cycles for premium bowl formats.
Market Restraints
- Input cost volatility:Fertilizer and agricultural labor expenses swing with commodity cycles, squeezing margin structures for field-grown operations.
- Geographic supply concentration:California's Central Valley and Imperial County generate the majority of domestic leafy greens, exposing the category to drought and water allocation disputes.
- Refrigerated logistics limitations:Cold chain infrastructure gaps in secondary markets restrict five-to-fourteen-day shelf-life distribution beyond major metropolitan zones.
Strategic Opportunities
- Sun Belt urban expansion:Phoenix, Atlanta, and Dallas-Fort Worth metro areas show underpenetrated convenience channel penetration for single-serve bowl formats.
- Protein-addition convergence:Pouch-packaged chicken, tofu, and legume components are merging with base greens to create complete meal solutions without seal integrity trade-offs.
- State plastic packaging bans:California and New York regulations are accelerating fiber-based clamshell adoption, rewarding early packaging material transitions with retail placement priority.
Industry Challenges
- Agricultural water quality compliance:Pending FDA agricultural water rules require extensive testing protocols that extend harvest-to-processing timelines for field operators.
- OSHA agricultural worker safety inspections:Processing facilities face heightened scrutiny on harvest crew housing and equipment standards, elevating operational compliance costs.
- Cold chain integration complexity:Legacy distribution networks designed for frozen goods require reconfiguration to maintain precise temperature bands for fresh-cut products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Packaged Salads Market |
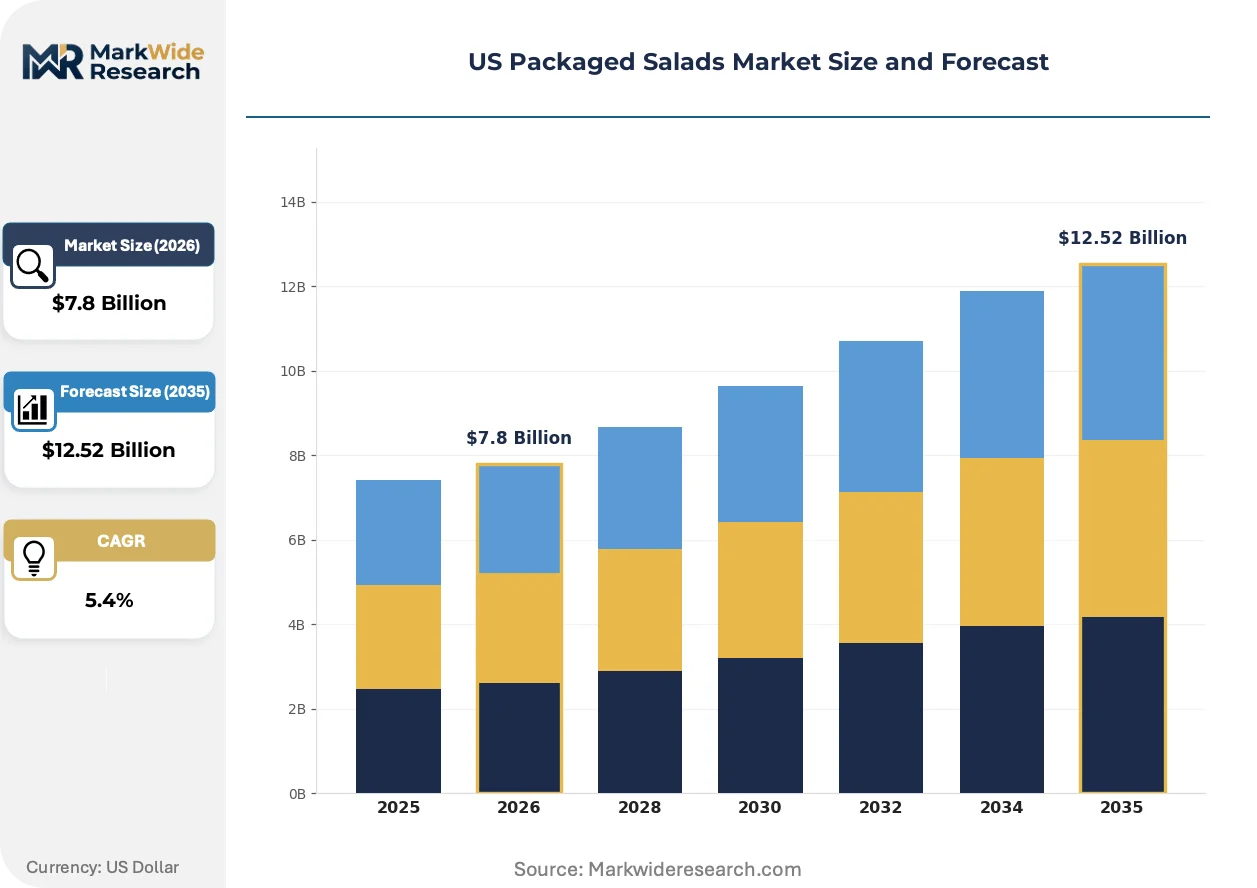
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Eat Salads, Salad Kits, Single-Serve Salads, Bulk Salads Ingredient Type: Green Leafy Vegetables, Grains, Fruits, Proteins Packaging Type: Clamshell, Tray, Bowl, Pouch Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service |
| Companies Covered | Dole Food Company Inc., Taylor Farms, Fresh Express, Earthbound Farm, BrightFarms, Gotham Greens, Mann Packing Co. Inc., Bonduelle Fresh Americas, Ready Pac Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Packaged Salads Market Trends and Innovations
Three forces are compressing traditional supply chain architectures: controlled-environment production, traceability technology mandates, and channel-specific format proliferation.
Controlled-environment agriculture using hydroponic and aeroponic systems is decentralizing production away from California field concentration toward urban perimeter locations. Gotham Greens and similar operators are deploying greenhouse facilities within fifty miles of Chicago, New York, and Denver metropolitan demand centers. This geographic compression is reducing transportation miles and enabling same-day harvest-to-retail cycles that field-grown operations cannot match.
The FDA Food Safety Modernization Act Section 204 traceability requirements are mandating electronic record-keeping from seed-to-shelf for leafy greens. Processors must implement lot-level tracking systems that capture growing location, harvest crew, and temperature history across the cold chain. Small and mid-sized suppliers face disproportionate compliance burdens as they retrofit legacy paper-based systems before enforcement deadlines.
Retail buyers are consolidating procurement around suppliers offering complete meal-kit solutions rather than commodity bagged greens. Chains are reducing SKU counts of plain spinach and romaine in favor of bundled kits containing dressings, toppings, and protein pouches. This preference shift is most visible in the Southeast and Midwest, where time-constrained households prioritize one-purchase meal completion over ingredient assembly.
US Packaged Salads Market Segmentation
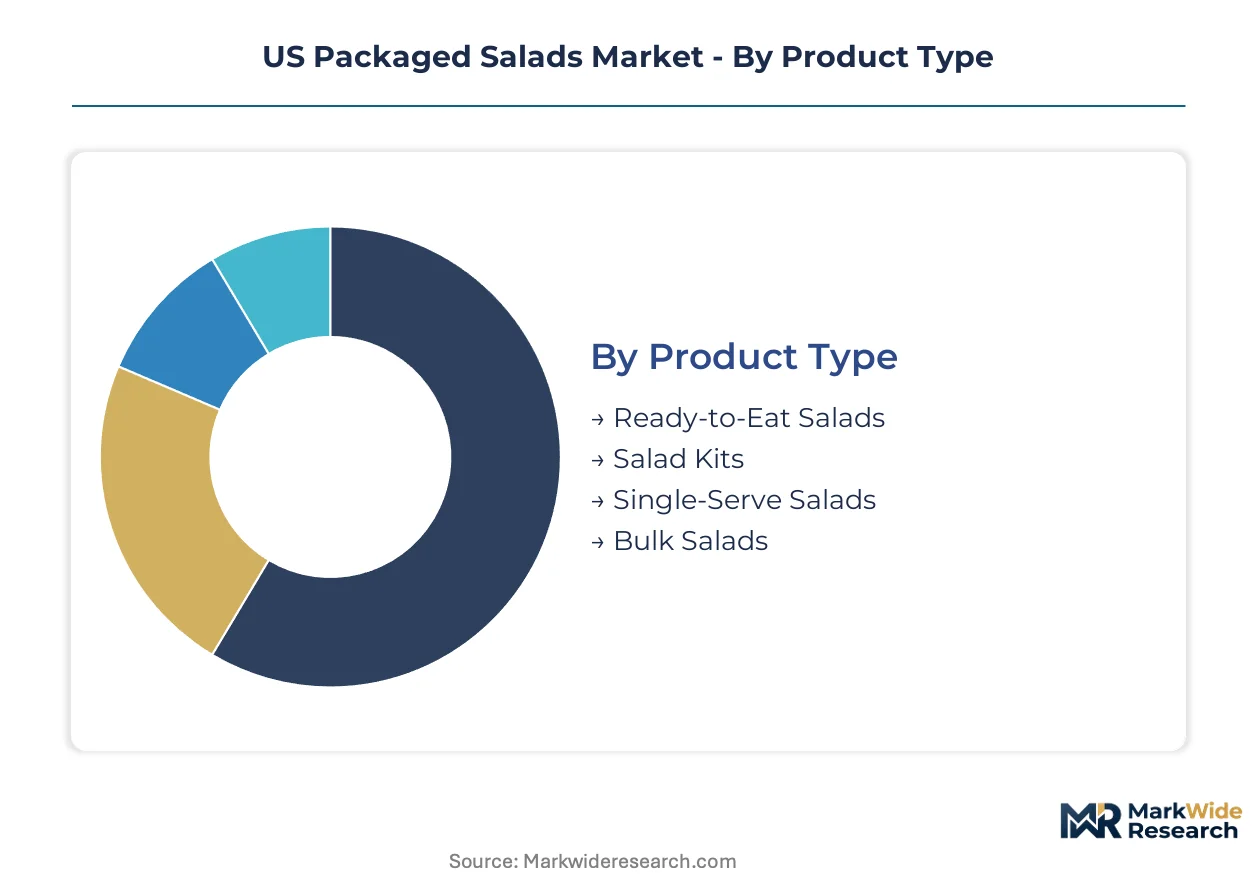
Segmentation in the US packaged salads market reveals how convenience expectations, meal-occasion targeting, and channel logistics reshape product development priorities. Manufacturers configure formulations, portion sizes, and packaging formats to match distinct consumption contexts from quick-service restaurant prep lines to household refrigerator stocking.
Product Type:
Customization intensity varies sharply across this category, from fully composed meals requiring zero preparation to ingredient sets demanding consumer assembly.
- Ready-to-Eat Salads:Pre-dressed, pre-topped compositions in sealed bowls or clamshells with five-to-fourteen-day refrigerated shelf lives. Corporate cafeterias and hospital food service operators in Texas and Florida concentrate procurement here as labor cost pressures eliminate on-site prep stations.
- Salad Kits:Segmented components—base greens, dressing sachets, crunch toppings, protein pouches—packaged together but requiring consumer combination. Southeast and Midwest households drive velocity as time-constrained parents prioritize one-purchase meal completion over ingredient sourcing.
- Single-Serve Salads:Individual portion bowls targeting convenience channel grab-and-go occasions.
- Bulk Salads:Multi-serving bags or tubs for household replenishment and food service back-of-house use.
Leading the category by volume: Ready-to-Eat Salads. Growing fastest: Salad Kits.
Ingredient Type:
Cost tier stratification dominates here, with commodity inputs at the base and certified specialty ingredients commanding shelf-space premiums.
- Green Leafy Vegetables:Romaine, spinach, spring mix, and kale forming the volume foundation of most formulations. California's Central Valley and Imperial County field operations supply the majority, with USDA organic certification creating price tier separation at retail.
- Proteins:Grilled chicken strips, hard-cooked eggs, tofu cubes, and legume blends transforming base greens into complete meals. Pouch packaging innovations from Southeast processing facilities enable protein addition without compromising seal integrity or shelf life.
- Grains:Quinoa, farro, and ancient grain blends adding caloric density and texture variation.
- Fruits:Dried cranberries, apple slices, and citrus segments contributing sweetness and flavor contrast.
Highest volume concentration: Green Leafy Vegetables. Steepest expansion trajectory: Proteins.
Packaging Type:
Channel-specific format requirements and emerging state-level plastic bans are accelerating material transition investments across this category.
- Clamshell:Rigid PET or recycled-content plastic containers dominating refrigerated retail sets for multi-serve and family-size formats. California and New York state regulations are forcing rapid fiber-based material transitions, rewarding early adopters with retail placement priority.
- Bowl:Round or oval single-serve containers capturing faster velocity in convenience-oriented channels. Phoenix, Atlanta, and Dallas-Fort Worth metro areas show underpenetrated penetration for this format relative to coastal markets.
- Tray:Shallow rectangular formats common in food service and club store bulk offerings.
- Pouch:Flexible packaging for dressing, toppings, and protein components enabling modular kit assembly.
Dominant by shelf presence: Clamshell. Gaining share fastest: Bowl.
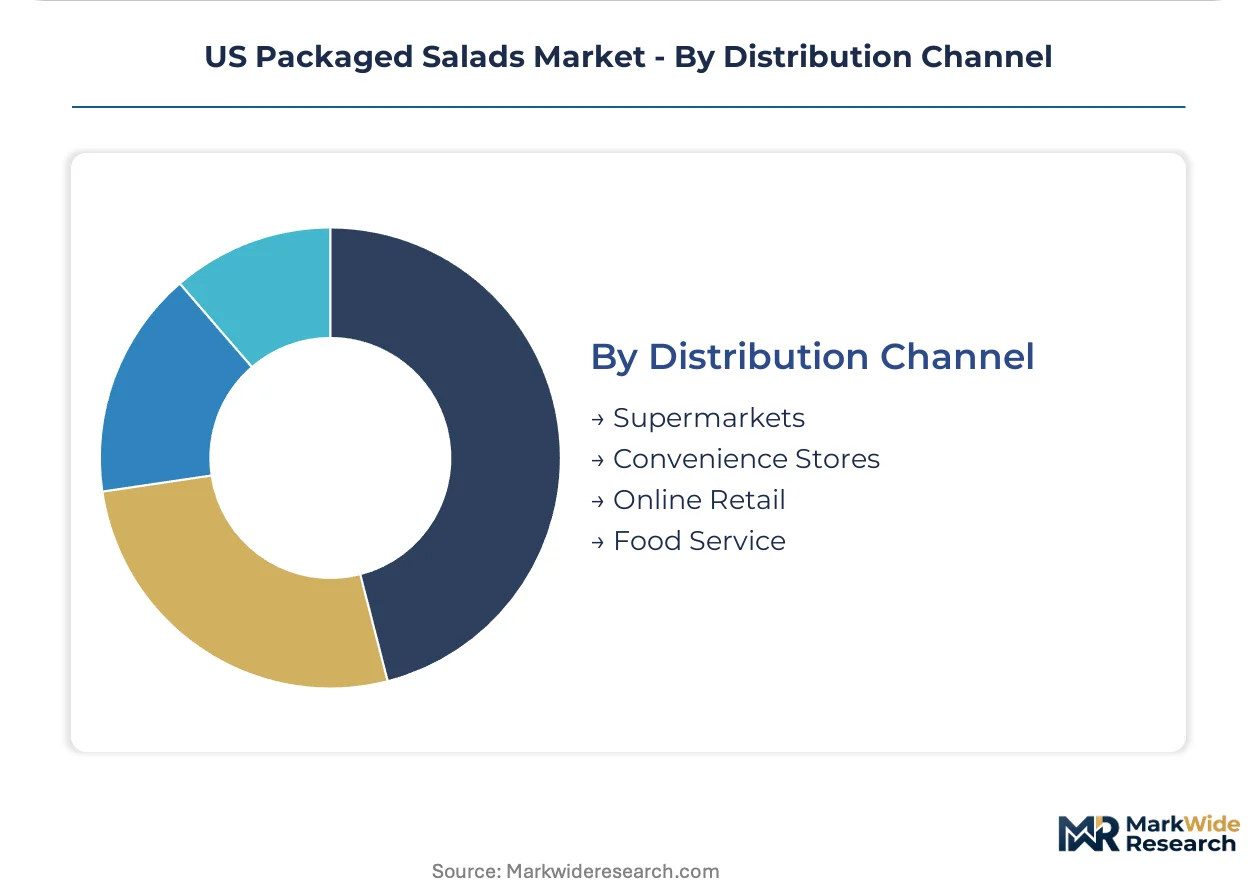
Distribution Channel:
Customer type and purchase-occasion timing create distinct service requirements from temperature-controlled logistics to promotional cadence.
- Supermarkets:Full-line retailers with dedicated refrigerated produce sections and weekly promotional cycles. Taylor Farms and Dole Food Company anchor supply relationships here through direct store delivery networks sustaining cold chain integrity.
- Food Service:Quick-service restaurants, corporate cafeterias, and institutional kitchens requiring case-lot delivery and specification-grade consistency. Labor cost pressures across the Southeast are expanding pre-portioned salad procurement as operators eliminate prep stations.
- Convenience Stores:Limited-assortment channels prioritizing single-serve formats with extended shelf lives.
- Online Retail:E-commerce platforms and meal-kit subscription services with last-mile cold chain requirements.
Largest volume flow: Supermarkets. Expanding most quickly: Food Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley generates the majority of domestic leafy greens supply, yet consumption clusters in Sun Belt metros and Northeast urban corridors where time-constrained households drive kit format velocity.
California
FDA agricultural water quality rules and California Leafy Greens Marketing Agreement protocols shape harvest-to-processing timelines across the Central Valley and Imperial County. The state's OSHA agricultural worker safety inspections elevate operational compliance costs for field operators. Salinas Valley and Fresno County anchor conventional production, while Central Coast organic certification premiums command retail shelf-space advantages.
Texas
Corporate cafeteria operators and quick-service restaurants in Dallas-Fort Worth and Houston expand grab-and-go procurement as labor costs eliminate on-site prep stations. The Texas Department of State Health Services enforces food safety standards parallel to federal FDA mandates. Controlled-environment greenhouse operations near Austin are shortening farm-to-retail cycles for premium bowl formats.
Florida
Year-round growing seasons in the Winter Garden and Immokalee regions support consistent fresh supply chains for Southeast distribution networks. The Florida Department of Agriculture and Consumer Services administers produce safety rules aligned with FSMA traceability requirements. Tampa and Orlando metro areas show underpenetrated convenience channel penetration for single-serve formats relative to coastal markets.
New York
Urban greenhouse facilities within fifty miles of New York City enable same-day harvest-to-retail cycles that field-grown operations cannot match. The state's plastic packaging ban regulations are accelerating fiber-based clamshell adoption, rewarding early material transitions with retail placement priority. Gotham Greens operates controlled-environment production in Brooklyn and Queens to serve metropolitan demand centers.
Illinois
Midwest households in Chicago and surrounding counties drive salad kit velocity as time-constrained parents prioritize one-purchase meal completion. The Illinois Department of Agriculture oversees produce safety compliance for regional distribution. Taylor Farms leverages vertical integration from field processing to retail distribution to sustain cost advantages across the Midwest.
US Packaged Salads Market Competitive Landscape
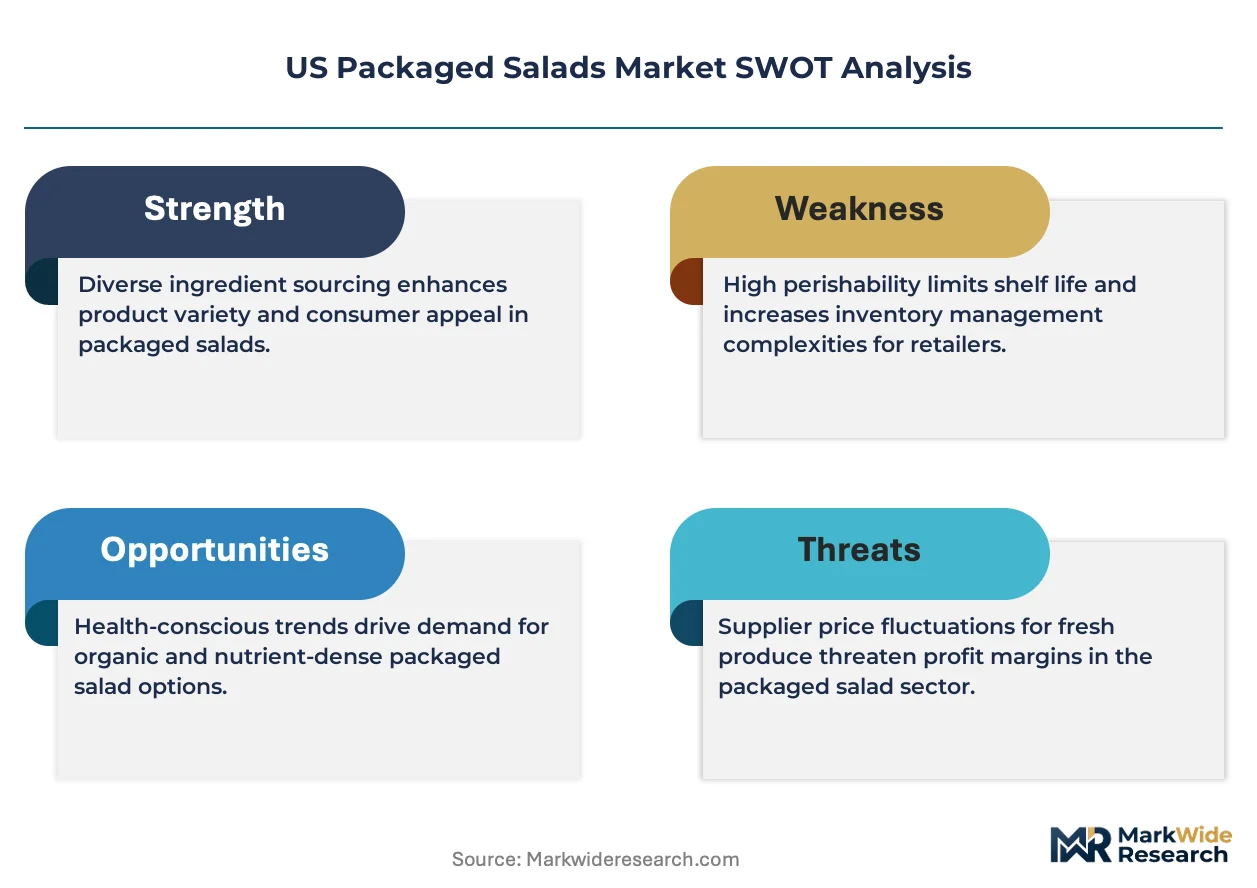
The competitive structure tilts toward scale-driven field operators and urban-controlled-environment specialists. National brands with direct store delivery networks dominate supermarket refrigerated sets, while regional greenhouse operators capture premium positioning through proximity production. Two strategic archetypes define the landscape: vertically integrated agricultural conglomerates with multi-state processing footprints, and technology-enabled urban growers with localized distribution. Dominant competitive moves include backward integration into captive growing operations and packaging material transitions ahead of state-level plastic bans.
Among scale-driven agricultural conglomerates, Dole Food Company Inc. and Taylor Farms occupy positions defined by multi-state manufacturing footprints and direct store delivery relationships. Dole anchors conventional supply through California and Florida field operations. Taylor Farms exemplifies vertical control from growing through retail distribution. Gotham Greens represents the controlled-environment archetype, with urban greenhouse facilities positioned within fifty miles of major metropolitan demand centers to compress transportation cycles.
| Leading Market Players |
|---|
| Dole Food Company Inc. |
| Taylor Farms |
| Fresh Express |
| Earthbound Farm |
| BrightFarms |
| Gotham Greens |
| Mann Packing Co. Inc. |
| Bonduelle Fresh Americas |
| Ready Pac Foods |
| Others |
Pricing and Supply Chain Analysis
California's plastic packaging ban and FDA Food Safety Modernization Act traceability mandates gate qualified supply access while stratifying pricing tiers around certification premiums and fiber-based material compliance investments. Retail placement priority flows to suppliers who absorb these upstream costs, compressing margin structures for non-compliant field operators while rewarding early packaging transitions with shelf-space advantages.
Pricing Analysis
Cost-down pressure on conventional field-grown supply accelerates because fertilizer and agricultural labor expenses swing with commodity cycles. Three-tier pricing structure across USDA organic certified, conventional premium, and economy bulk formats dominates retail sets. Price differentiation hinges on organic certification status and controlled-environment proximity to urban demand centers. Food service buyers exhibit highest price sensitivity due to volume procurement and specification-grade consistency requirements, while metropolitan convenience channels accept premium positioning for single-serve bowl formats.
Supply Chain Analysis
USDA organic certification and FDA traceability lot-level tracking requirements filter supplier qualification timelines and elevate compliance investments for legacy paper-based systems. California's Central Valley, Florida's Winter Garden region, and Texas greenhouse corridors anchor domestic leafy greens supply. Raw material dependencies center on fertilizer inputs, agricultural labor pools, and refrigerated transport capacity. Single-source geographic concentration creates drought and water allocation vulnerability. Distribution runs through direct store delivery networks maintaining cold chain integrity from processing facilities to retail refrigerated sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-environment agriculture using hydroponic and aeroponic systems is displacing legacy field-grown operations as the dominant production architecture. This technology transition compresses farm-to-retail cycles and reconfigures competitive positioning around urban proximity rather than agricultural land scale.
For Market Incumbents: Anchor multi-state processing footprints with backward integration into captive growing operations to defend against urban greenhouse entrants. Invest in fiber-based clamshell packaging transitions ahead of state-level enforcement deadlines to secure retail placement priority. Deepen direct store delivery relationships with supermarket chains to maintain temperature-controlled logistics advantages that controlled-environment specialists cannot easily replicate. For New Entrants and Emerging Players: Convenience store channel partnerships in Phoenix, Atlanta, and Dallas-Fort Worth metro areas offer underpenetrated white-space for single-serve bowl format introduction. Target corporate cafeteria food service operators eliminating on-site prep stations due to labor cost pressures. Pursue protein-addition convergence through pouch-packaged component sourcing to create complete meal solutions without seal integrity trade-offs. For Investors and Strategic Acquirers: FDA agricultural water quality rule implementation timelines are the leading indicator that compliance burden differentiation will reshape acquisition target attractiveness. Long-term viability favors controlled-environment operators with urban perimeter locations and technology-enabled traceability systems. Monitor pending state plastic packaging ban enforcement dates as signals for packaging material transition readiness premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Capacity Expansion | Gotham Greens and BrightFarms shorten farm-to-retail cycles through urban greenhouse proximity to Chicago and New York demand centers. |
| Fiber-Based Packaging Transition | Early clamshell material adopters secure California and New York retail placement priority ahead of state ban enforcement. |
| Protein-Addition Component Integration | Pouch-packaged chicken and tofu components merge with base greens to create complete meal solutions for Southeast households. |
| Direct Store Delivery Network Deepening | Taylor Farms sustains cold chain integrity from field processing through retail distribution across Midwest supermarket sets. |
| USDA Organic Certification Investment | Certified suppliers capture shelf-space advantages as retailers respond to consumer willingness-to-pay for verified organic leafy greens. |
Research Methodology
Document review covered FDA FSMA traceability guidance documents, USDA organic certification standards, and state-level packaging regulations, complemented by interviews with processing facility operations directors, supermarket category buyers, food service procurement managers, and controlled-environment agriculture technology specialists. Secondary validation drew from SEC filings of publicly traded agricultural conglomerates, refrigerated logistics trade association reports, and produce safety compliance databases. Bottom-up volume modeling triangulated against top-down market sizing from retail audit data and food service distribution records.
Market value and volume outputs across the projection horizon reflect segmentation by product type, ingredient composition, packaging format, and distribution channel, with additional granularity on organic certification status and controlled-environment production share. CAGRs were derived from trend extrapolation of historical volume flows adjusted for technology adoption curves and regulatory implementation schedules. Forecast inputs incorporated agricultural labor cost indices, fertilizer price volatility patterns, and cold chain infrastructure expansion timelines.
Caveats apply where FDA agricultural water quality rule enforcement delays, California drought severity, or state plastic packaging ban implementation timelines could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Jams and Spreads Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Global Food Spread Market