
 United Kingdom Full Service Restaurants Market | 2026-2036
United Kingdom Full Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Full Service Restaurants Market Insights
Plant-based protein formulations are restructuring menu economics across the United Kingdom full service restaurants sector. Whitbread PLC leverages its Premier Inn co-location model to sustain captive dinner traffic. Nando's Chickenland Ltd anchors its peri-peri supply chain through in-house marinade production. Mitchells & Butlers PLC competes across pub-restaurant hybrids with distinct brand architectures.
United Kingdom full service restaurants are commercial dining establishments where patrons receive table service from waitstaff, with meals typically prepared to order in on-premises kitchens operating at temperatures between 65°C and 75°C for hot holding compliance. These venues serve as social infrastructure for business entertainment, family occasions, and tourism expenditure. Casual dining dominates volume throughput while fine dining captures disproportionate margin pools. Italian menu types lead penetration in suburban locations, whereas Asian formats show the fastest expansion in metropolitan zones. Family customer segments drive weekend revenue concentration, with professionals sustaining weekday lunch trade.
The Food Standards Agency enforces hygiene rating schemes that determine premises display obligations and directly influence consumer selection behavior. Environmental Health Officers conduct unannounced inspections under the Food Hygiene Rating (Wales) Act 2013 and equivalent frameworks across England, Scotland, and Northern Ireland. HMRC's Making Tax Digital initiative and National Living Wage adjustments from the Low Pay Commission reshape labor cost structures. Stakeholders must monitor regulatory divergence post-UK-EU alignment reviews while calibrating pricing architecture against input cost volatility.
Market Dynamics
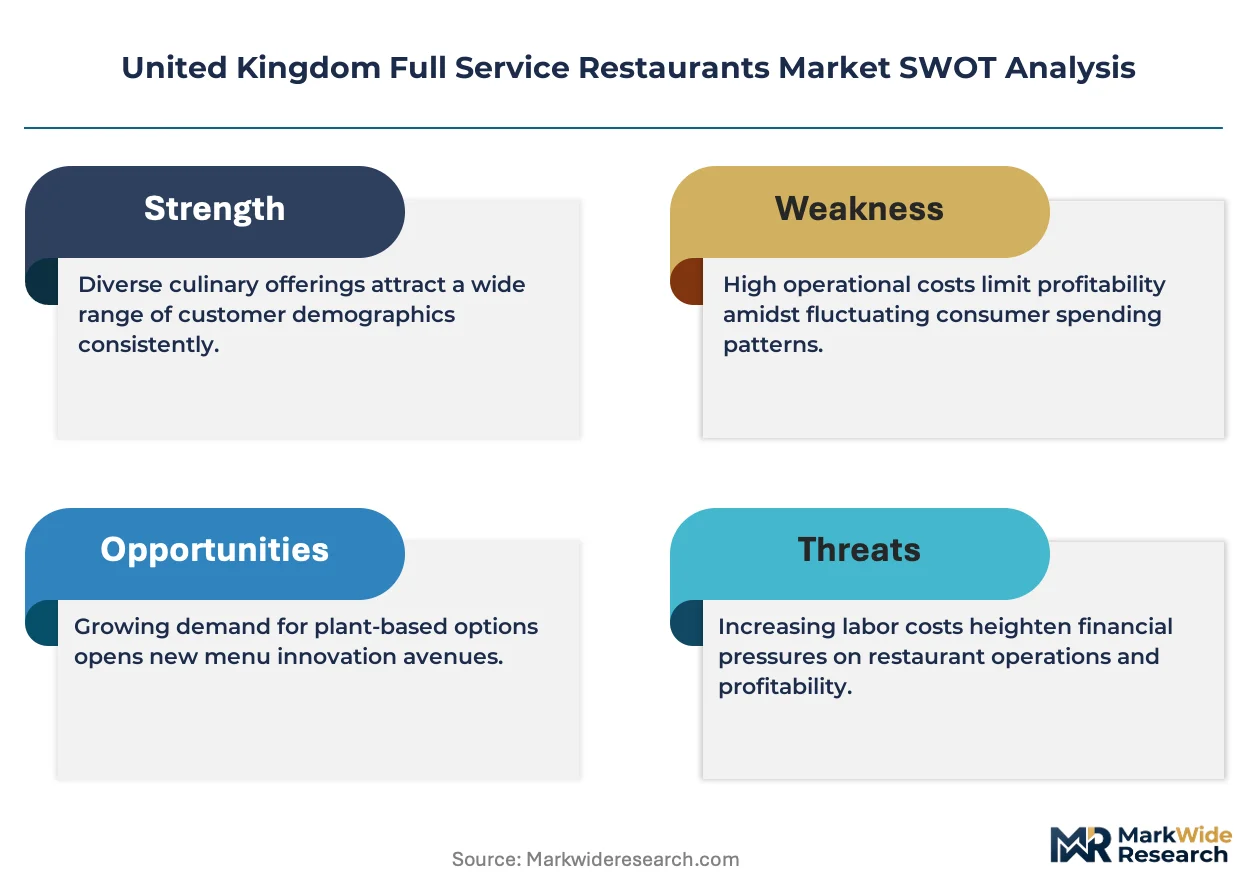
Plant-based protein adoption is compressing traditional meat procurement economics while the Food Standards Agency's hygiene rating scheme forces operational transparency across all tiers. Labor cost pressure from National Living Wage adjustments compounds margin stress in casual dining formats.
Growth Catalysts
- Urban professional density:Young professionals in London, Manchester, and Birmingham sustain weekday lunch trade and after-work dining frequency. Their disposable income concentration supports premium menu experimentation.
- The Food Hygiene Rating (Wales) Act 2013:This framework and its England, Scotland, and Northern Ireland equivalents create competitive differentiation through visible compliance. High-scoring premises capture disproportionate family segment traffic.
- Co-location hospitality models:Hotel-restaurant hybrids generate captive dinner traffic from accommodation guests. This operational pairing reduces customer acquisition costs and stabilizes midweek revenue.
Market Restraints
- Input cost volatility:Energy price fluctuations and fresh produce supply disruptions compress gross margins. Operators lack pricing power to pass full cost increases to price-sensitive casual dining segments.
- Supply concentration risk:Peri-peri chicken and other protein formats depend on limited marinade and spice suppliers. Brexit-related customs friction lengthens lead times for imported ingredients.
- Technical limitation:Kitchen hot-holding compliance at 65°C to 75°C constrains menu preparation flexibility and increases energy consumption versus quick-service alternatives.
Strategic Opportunities
- Underpenetrated suburban corridors:Italian menu formats show saturation in Greater London commuter belts but remain sparse in secondary cities like Leeds and Newcastle. Expansion here captures family occasion spending.
- Technology convergence:Kitchen display systems integrated with inventory management reduce waste and enable dynamic menu engineering. Early adopters in metropolitan zones achieve labor efficiency gains.
- Channel innovation:Dark kitchen and delivery-native formats separate production from front-of-house real estate. This asset-light model lowers entry barriers in high-rent postal districts.
Industry Challenges
- Chef and kitchen labor scarcity:Qualified hot-holding compliance officers and line cooks command wage premiums. The Low Pay Commission's scheduled adjustments intensify recruitment competition with retail and logistics sectors.
- Legacy POS integration complexity:HMRC's Making Tax Digital initiative requires real-time reporting infrastructure. Small independent operators face capex burdens to replace outdated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Full Service Restaurants Market |
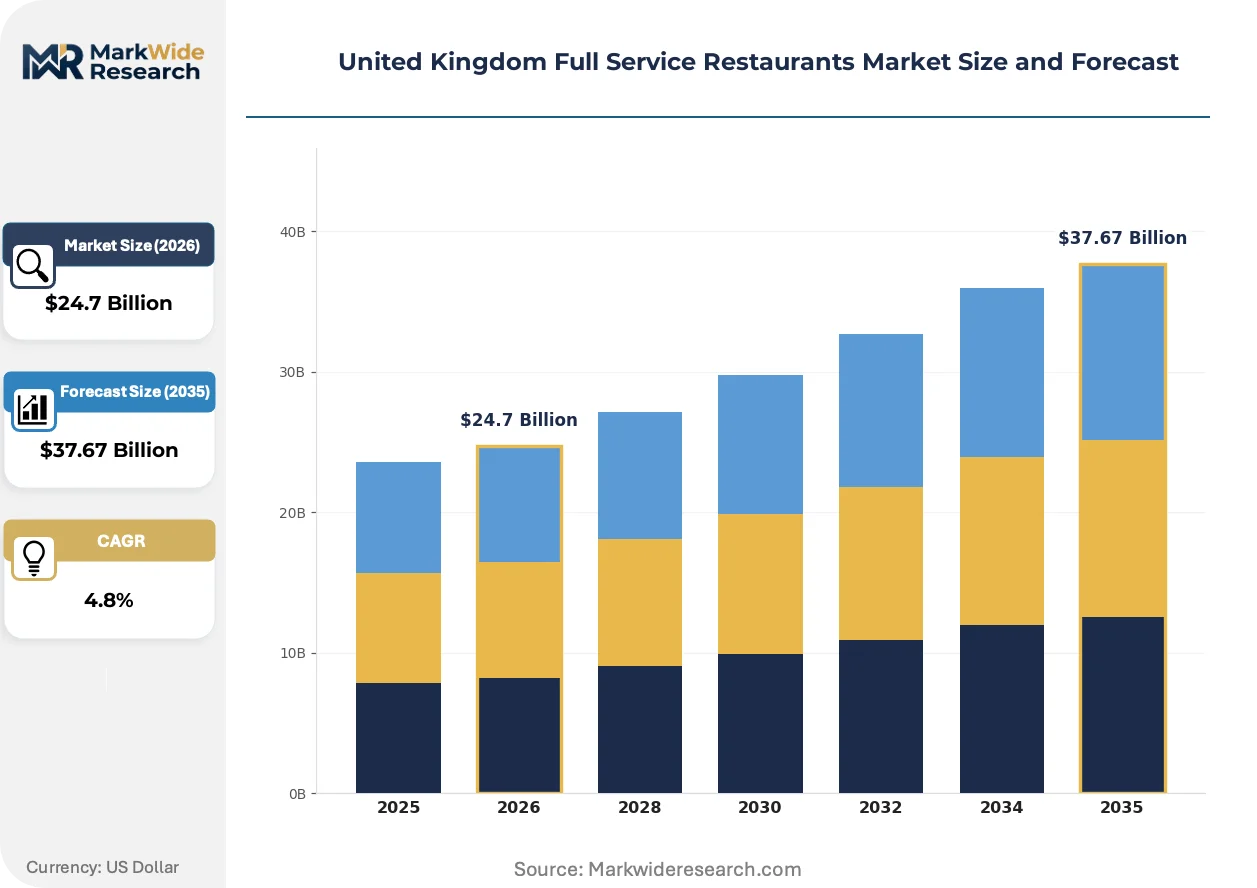
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $37.67 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-In, Takeout, Delivery, Catering Menu Type: Italian, Indian, American, Asian Dining Experience: Casual Dining, Fine Dining, Fast Casual, Buffet Customer Type: Families, Professionals, Tourists, Students |
| Companies Covered | Whitbread PLC, Nando's Chickenland Ltd, Mitchells & Butlers PLC, Pizza Express, J D Wetherspoon, The Restaurant Group PLC, Greene King Ltd, Wagamama, The Azzurri Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Full Service Restaurants Market Trends and Innovations
Digital ordering infrastructure and protein diversification are restructuring how full service restaurants acquire and serve customers. Operational technology investments now determine competitive survival.
Cloud-based kitchen management platforms are decentralizing production coordination across multi-site operators. Mid-market chains in Birmingham and Manchester deploy these systems to standardize quality while permitting local menu adaptation. The technology compresses centralized oversight costs without sacrificing unit-level flexibility.
The Food Standards Agency's hygiene rating disclosure mandates are reshaping consumer selection behavior. Premises must display scores at entrances and online, creating immediate competitive sorting. Family-oriented suburban locations face the strongest compliance pressure as parents prioritize visible safety assurance.
Subscription-based dining memberships are displacing traditional promotional discounting in metropolitan markets. Young professionals in London's restaurant corridor pay upfront for priority reservations and menu previews. This model locks in predictable revenue streams while reducing reliance on third-party booking platforms.
United Kingdom Full Service Restaurants Market Segmentation
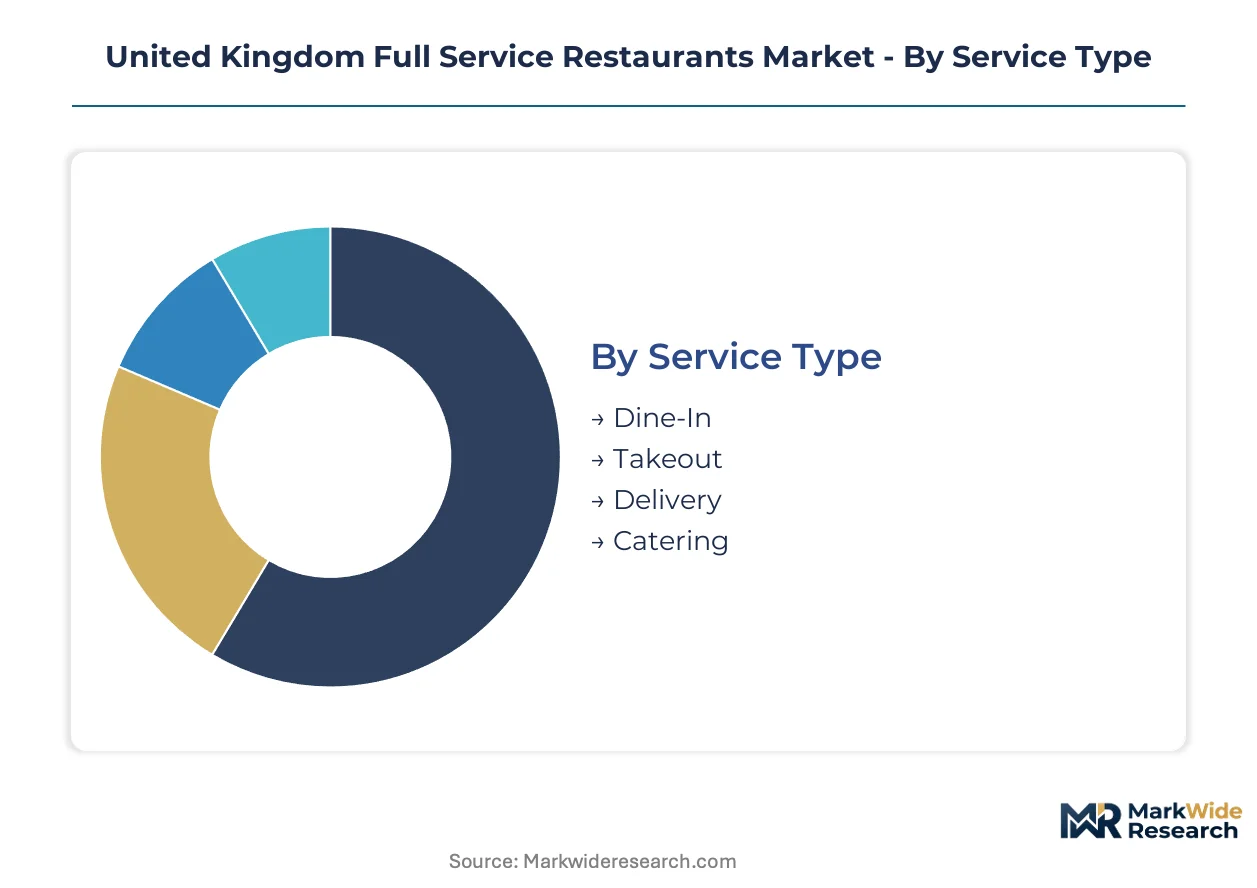
Segmentation in the United Kingdom full service restaurants market reveals how capital allocation, operational complexity, and regulatory exposure vary across service models and customer bases. Operators configure distinct supply chains, labor models, and real estate strategies for each segment cluster.
Service Type:
Dine-in formats command the highest upfront capital intensity due to front-of-house real estate requirements and full kitchen buildouts, while delivery-native models minimize fixed asset exposure.
- Dine-In:Table service operations require complete front-of-house staffing, interior design investment, and compliance with the Food Standards Agency's on-premises hygiene protocols. Demand concentrates in London's restaurant corridor where young professionals sustain weekday lunch frequency and drive premium menu experimentation. The Food Hygiene Rating (Wales) Act 2013 and its England, Scotland, and Northern Ireland equivalents create visible competitive sorting at entrances.
- Takeout:Counter-service collection points reduce seating footprint but maintain full kitchen infrastructure for order preparation. Family segments in suburban commuter belts favor this format for occasion dining without childcare logistics. Operators here face compressed margins from packaging costs and limited beverage attachment.
- Delivery:Third-party platform integration separates production from customer-facing real estate entirely. Dark kitchen configurations in high-rent postal districts of Birmingham and Manchester lower entry barriers.
- Catering:Off-site event service demands mobile hot-holding equipment and transport logistics. Corporate contracts in metropolitan zones provide revenue stability.
Most installed capacity flows through Dine-In. Expansion is steepest in Delivery.
Menu Type:
Protein procurement economics and supply chain complexity create divergent margin profiles across culinary formats, with Italian and Asian categories showing opposite concentration patterns.
- Italian:Pasta and pizza formats dominate suburban penetration in Greater London commuter belts, with standardized ingredient sourcing reducing supply risk. Leeds and Newcastle show underpenetration relative to population density. Family occasion spending drives weekend revenue concentration here.
- Asian:Metropolitan zones in London, Manchester, and Birmingham show the fastest format expansion, driven by young professional demand for menu experimentation. Imported spice and sauce dependencies create Brexit-related customs friction.
- Indian:Curry house traditions concentrate in urban centers with established South Asian populations. Tandoor equipment requires specialized ventilation infrastructure.
- American:Burger and steak formats compete in casual dining tiers with standardized preparation protocols. National Living Wage pressure hits labor-intensive grilling operations hardest.
Revenue concentration sits with Italian. Menu innovation velocity runs highest in Asian.
Dining Experience:
Price tier positioning determines kitchen labor ratios, with fine dining requiring disproportionate chef investment per cover versus casual formats optimized for throughput.
- Casual Dining:Volume-optimized operations capture the broadest customer base through standardized menus and efficient table turns. This segment absorbs the brunt of input cost volatility as operators lack pricing power to pass full increases to price-sensitive consumers.
- Fine Dining:Chef-driven tasting menus and wine programs command premium pricing with lower seat counts. Qualified kitchen labor scarcity and hot-holding compliance officer wage premiums intensify recruitment competition with retail and logistics sectors.
- Fast Casual:Hybrid formats combine counter ordering with elevated ingredient positioning. Technology convergence through kitchen display systems enables dynamic menu engineering.
- Buffet:Self-service models minimize front-of-house labor but require larger premises footprints and complex food safety monitoring.
Customer traffic volumes peak in Casual Dining. Margin capture concentrates in Fine Dining.
Customer Type:
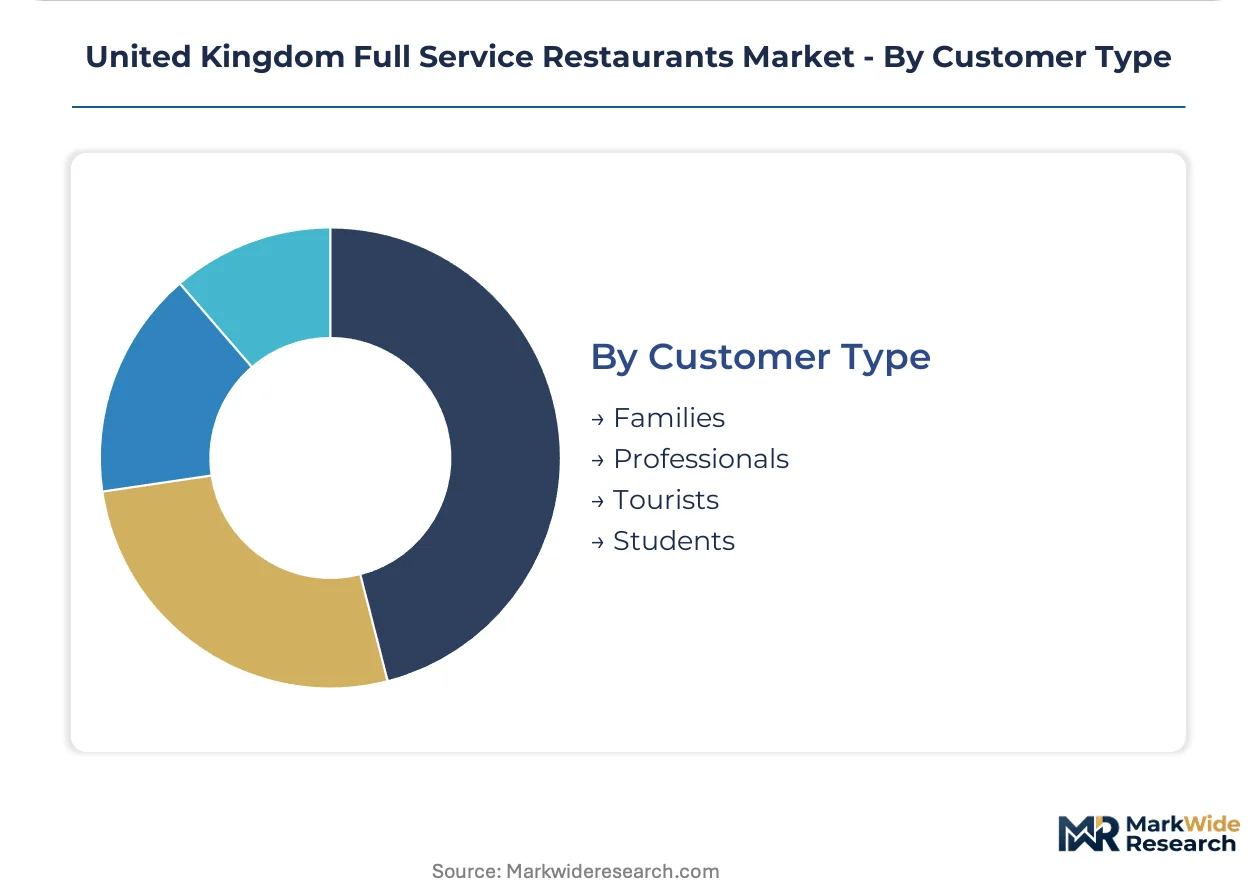
Temporal revenue patterns differ sharply across demographic segments, with professionals sustaining weekday operations while families drive weekend peaks.
- Professionals:Urban density in London, Manchester, and Birmingham supports after-work dining frequency and business entertainment expenditure. Subscription-based dining memberships are displacing traditional promotional discounting in this segment.
- Families:Suburban locations face strongest hygiene rating compliance pressure as parents prioritize visible safety assurance. Weekend revenue concentration requires staffing flexibility.
- Tourists:Co-location hospitality models from hotel-restaurant hybrids generate captive dinner traffic. This operational pairing reduces customer acquisition costs and stabilizes midweek revenue.
- Students:Price sensitivity limits format participation to casual tiers with high-volume, low-margin economics.
Weekday traffic depends on Professionals. Weekend volume flows through Families.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's restaurant corridor concentrates the United Kingdom's full service dining capacity, with Manchester and Birmingham forming secondary demand poles. Young professionals sustain weekday lunch trade across these urban centers. The Food Standards Agency's hygiene rating scheme creates visible competitive sorting at premises entrances nationwide.
London and the Southeast
Young professionals drive premium menu experimentation in the capital's dense urban core. The Food Hygiene Rating (Wales) Act 2013 and its England equivalents mandate score display at entrances, shaping consumer selection behavior. Co-location hospitality models from hotel-restaurant hybrids generate captive dinner traffic in Westminster and the City.
Midlands
Birmingham anchors metropolitan demand for Asian menu formats with the fastest expansion velocity. National Living Wage adjustments from the Low Pay Commission reshape labor cost structures across casual dining operations. Technology convergence through kitchen display systems enables dynamic menu engineering in Birmingham's restaurant clusters.
North England
Leeds and Newcastle show underpenetration for Italian formats relative to population density. Family occasion spending drives weekend revenue concentration in suburban commuter belts. Operators here face compressed margins from energy price fluctuations and fresh produce supply disruptions.
Scotland
Edinburgh and Glasgow sustain tourism expenditure through co-location hospitality models. The Food Hygiene Rating (Wales) Act 2013 equivalents apply across Scotland with unannounced inspections by Environmental Health Officers. Dark kitchen configurations lower entry barriers in high-rent postal districts of Glasgow.
Wales
The Food Hygiene Rating (Wales) Act 2013 originated here, creating the strictest disclosure framework in the United Kingdom. Cardiff's urban center shows growing young professional density supporting after-work dining frequency. Operators face compliance pressure from visible score display obligations at premises entrances.
United Kingdom Full Service Restaurants Market Competitive Landscape
Global majors compete with regional champions across operational scale and brand architecture dimensions. The vendor base clusters around pub-restaurant hybrids, peri-peri specialists, and hotel co-location operators. Three strategic archetypes dominate: integrated hospitality groups with accommodation assets, format-specific chains with captive supply chains, and diversified pub operators with distinct brand portfolios. Competitive moves concentrate on co-location expansion and supply chain backward integration.
Within the integrated hospitality tier, Whitbread PLC and Mitchells & Butlers PLC exemplify divergent real estate strategies. Whitbread occupies a position anchored by Premier Inn co-location models that sustain captive dinner traffic. Mitchells & Butlers sits within the pub-restaurant hybrid archetype, competing across multiple brand architectures. Nando's Chickenland Ltd represents the format-specific specialist archetype with in-house marinade production anchoring its peri-peri supply chain.
| Leading Market Players |
|---|
| Whitbread PLC |
| Nando's Chickenland Ltd |
| Mitchells & Butlers PLC |
| Pizza Express |
| J D Wetherspoon |
| The Restaurant Group PLC |
| Greene King Ltd |
| Wagamama |
| The Azzurri Group |
| Others |
Pricing and Supply Chain Analysis
Captive peri-peri marinade production at Nando's Chickenland Ltd anchors both supply security and menu pricing power against commodity protein volatility. Whitbread PLC's Premier Inn co-location model generates captive dinner traffic that stabilizes revenue per available seat hour independent of walk-in demand fluctuations.
Pricing Analysis
Input cost pass-through from National Living Wage adjustments and energy price fluctuations compresses margins in casual dining tiers where price-sensitive family segments resist full surcharge absorption. Three-tier pricing structure across premium, standard, and economy levels separates fine dining chef-driven menus from volume-optimized casual formats and limited-service pub-restaurant hybrids. Price differentiation rests on visible Food Standards Agency hygiene rating compliance and co-location hospitality assets. Pricing pressure intensifies in suburban Italian formats where standardized ingredient sourcing limits premium extraction.
Supply Chain Analysis
Freight cost elevation from Brexit-related customs friction lengthens lead times for peri-peri spices and Asian sauce imports through Channel ports. Protein procurement draws from domestic poultry suppliers, EU marinade ingredient sources, and South Asian spice routes. Single-source vulnerability concentrates in specialized tandoor equipment and ventilation infrastructure for Indian formats. Distribution runs through centralized commissary kitchens for multi-site operators and direct-to-premises delivery for independent establishments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom full service restaurants market compounds steadily through urban professional density sustaining weekday lunch frequency and premium menu experimentation in London, Manchester, and Birmingham.
For Market Incumbents: Anchor defensive positioning through backward integration into in-house marinade production and captive supply chain control over protein inputs. Co-location hospitality expansion with Premier Inn-type accommodation pairings reduces customer acquisition cost exposure against dark kitchen entrants. Certification investment in Food Standards Agency hygiene rating excellence captures disproportionate family segment traffic. For New Entrants and Emerging Players: The Food Hygiene Rating (Wales) Act 2013 and its England, Scotland, and Northern Ireland equivalents opens a window for technology-native formats with integrated compliance documentation from launch. Underpenetrated suburban corridors in Leeds and Newcastle for Italian menu types represent immediate white-space capture. Dark kitchen configurations in high-rent Birmingham and Manchester postal districts lower capital barriers with delivery-native customer acquisition. For Investors and Strategic Acquirers: Roll-up economics work for pub-restaurant hybrid operators because estate fragmentation across Mitchells & Butlers PLC-type portfolios permits brand architecture consolidation. Five-to-ten year viability hinges on labor efficiency technology adoption rates. The signal to monitor is kitchen display system penetration velocity as an indicator of operational scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Co-location Hospitality Expansion | Premier Inn-type pairings stabilize midweek revenue through captive dinner traffic from accommodation guests. |
| Backward Integration into Marinade Production | Nando's-style in-house peri-peri supply control insulates margin from Brexit-related import cost volatility. |
| Technology Convergence Investment | Kitchen display systems integrated with inventory management reduce waste and enable dynamic menu engineering. |
| Dark Kitchen Format Deployment | Delivery-native production separation from front-of-house real estate lowers entry barriers in high-rent districts. |
| Hygiene Rating Excellence Certification | Food Standards Agency compliance investment captures family segment traffic through visible entrance score display. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each jurisdiction's regulatory environment and operating conditions. Primary interviews with restaurant group operations directors, Environmental Health Officers, hotel-restaurant hybrid asset managers, and supply chain procurement leads combined with secondary validation from Food Standards Agency inspection databases, HMRC Making Tax Digital filings, and Low Pay Commission wage adjustment records. Bottom-up unit economics modeling triangulated against top-down sector expenditure estimates.
Rate-of-change decomposition across the analysis window separates volume growth from mix shift and pricing components. Segmentation dimensions modeled include service type, menu category, dining experience tier, and customer archetype, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from historical trajectory analysis adjusted for identified structural shifts including plant-based protein adoption velocity and labor cost inflation. Forecast inputs incorporated energy price scenario bands and immigration policy impacts on kitchen labor availability.
Revisions become necessary when National Living Wage adjustment schedules accelerate, Brexit customs protocols harden, or energy price volatility exceeds modeled bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
North America Online Grocery Delivery Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
GCC Online Grocery Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Online Food Delivery Market
Food Service
Commercial Sink Market
Food Service
Benelux Foodservice Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Peer-To-Peer Dining Market
Food Service
Wok Market
Food Service
Charbroiler Market
Food Service
Smart Food Logistics Market
Food Service
Commercial Cutlery Market
Food Service
United Arab Emirates Quick Service Restaurant Market