
 Steam Tables and Food Well Market | 2026-2036
Steam Tables and Food Well Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Tables and Food Well Market Insights
Modular drop-in food well configurations paired with mobile buffet systems is realigning how institutional buyers evaluate total cost of ownership. Vollrath leverages its deep stainless steel fabrication expertise to dominate specification-driven segments. Alto-Shaam anchors its position through precision humidity control technology that extends holding windows without quality degradation. Wells Manufacturing competes aggressively on lead-time reliability for custom-length steam table assemblies serving chain restaurant rollouts.
Steam tables and food wells are heated serving equipment designed to maintain prepared foods within the FDA-mandated danger zone threshold of 135°F to 165°F through thermostatically controlled water baths or dry heat elements, typically fabricated from 14- to 16-gauge type 304 stainless steel for corrosion resistance in high-moisture environments. Electric steam tables lead volume shipments due to simpler installation and tighter temperature control in urban locations with strict emissions codes, while gas steam tables retain preference in high-volume cafeterias where energy infrastructure favors natural gas and recovery speed matters. Stainless steel commands the material mix because operators prioritize durability and NSF compliance over first-cost savings from aluminum or composite alternatives.
NSF International certification, FDA Food Code provisions, and ENERGY STAR commercial kitchen equipment standards collectively shape product design mandates and procurement eligibility across the United States. The EPA's phasedown of hydrofluorocarbon refrigerants is indirectly pressuring wet-well manufacturers to evaluate alternative heating media and insulation chemistries. Stakeholders must weigh total lifecycle operating costs against capital outlay as utility benchmarking and carbon disclosure requirements penetrate foodservice operator RFPs.
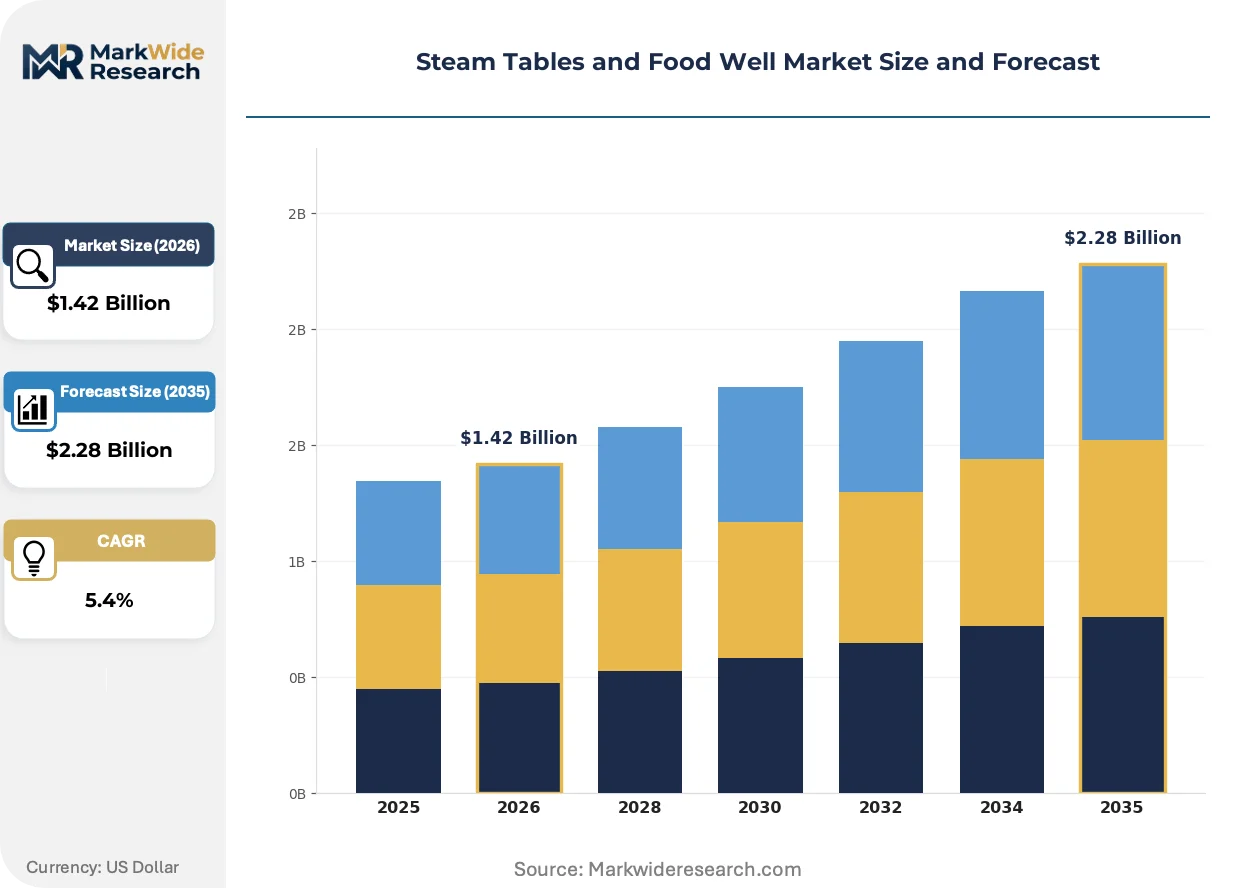
Market Dynamics
NSF International sanitation mandates and ENERGY STAR efficiency benchmarks are compressing product lifecycles as institutional buyers face simultaneous pressure to cut utility costs while maintaining FDA Food Code compliance. Equipment replacement cycles have shortened from ten-year norms toward seven-year refresh schedules.
Growth Catalysts
- Quick-service chain expansion:National rollouts of hot-holding infrastructure for menu diversification drive specification-grade volume demand.
- School nutrition program upgrades:USDA-backed cafeteria modernization initiatives mandate compliant equipment refreshes across K-12 districts.
- Electric infrastructure preference:Urban emissions codes in municipalities like New York and Los Angeles favor thermostatically controlled electric steam tables over gas alternatives.
Market Restraints
- Type 304 stainless steel price volatility:Nickel and chromium input cost swings squeeze fabrication margins and destabilize project quoting.
- Specialized welder concentration:Certified TIG welders for 14-gauge food-grade seams cluster in upper Midwest fabrication hubs, creating regional supply bottlenecks.
- Gas-to-electric conversion complexity:Existing gas-line infrastructure in legacy cafeterias creates sunk-cost friction against electric steam table adoption.
Strategic Opportunities
- Remote monitoring integration:IoT temperature logging converges with food safety audit requirements, opening premium positioning for connected well systems.
- Modular mobile buffet systems:Institutional catering and healthcare sectors seek reconfigurable serving lines that reduce fixed-installation capital.
- EPA refrigerant phase-down spillover:Wet-well manufacturers exploring alternative heating media gain first-mover advantage as hydrofluorocarbon restrictions tighten.
Industry Challenges
- NSF certification timeline compression:Third-party testing backlogs delay product launches and contract eligibility for six to nine months.
- Legacy control system integration:New humidity-control technologies require costly retrofitting of existing kitchen management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Tables and Food Well Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Steam Tables, Electric Steam Tables, Food Wells, Buffet Warmers End User: Restaurants, Catering Services, Cafeterias, Food Trucks Material: Stainless Steel, Aluminum, Plastic, Composite Materials Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Vollrath, Alto-Shaam, Wells Manufacturing, Duke Manufacturing, Hatco Corporation, Advance Tabco, Eagle Group, APW Wyott, Middleby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Tables and Food Well Market Trends and Innovations
Precision humidity management and connected sensor architectures are redefining competitive differentiation beyond stainless steel gauge thickness. Equipment vendors now compete on holding-window extension and predictive maintenance capability rather than fabrication alone.
Advanced humidity-control modules using capacitive sensing and microprocessor-driven steam injection are converging with precision holding requirements in healthcare and university dining. High-end institutional buyers deploy these systems to extend protein holding windows without moisture loss. The technology is converging with labor reduction mandates, compressing the premium tier toward mid-market price points.
EPA hydrofluorocarbon phasedown regulations are forcing wet-well manufacturers to reformulate insulation chemistries and evaluate alternative heating media. The industrial consequence is accelerated R&D spend on dry-heat alternatives and vacuum-insulated well designs. Custom fabrication shops serving chain rollouts face the steepest compliance timeline pressure.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for mid-size institutional operators. Healthcare systems and university consortiums now demand lifecycle cost guarantees and bundled service contracts. This pattern concentrates most visibly in United States K-12 districts aggregating purchases through state-level cooperative agreements.
Steam Tables and Food Well Market Segmentation
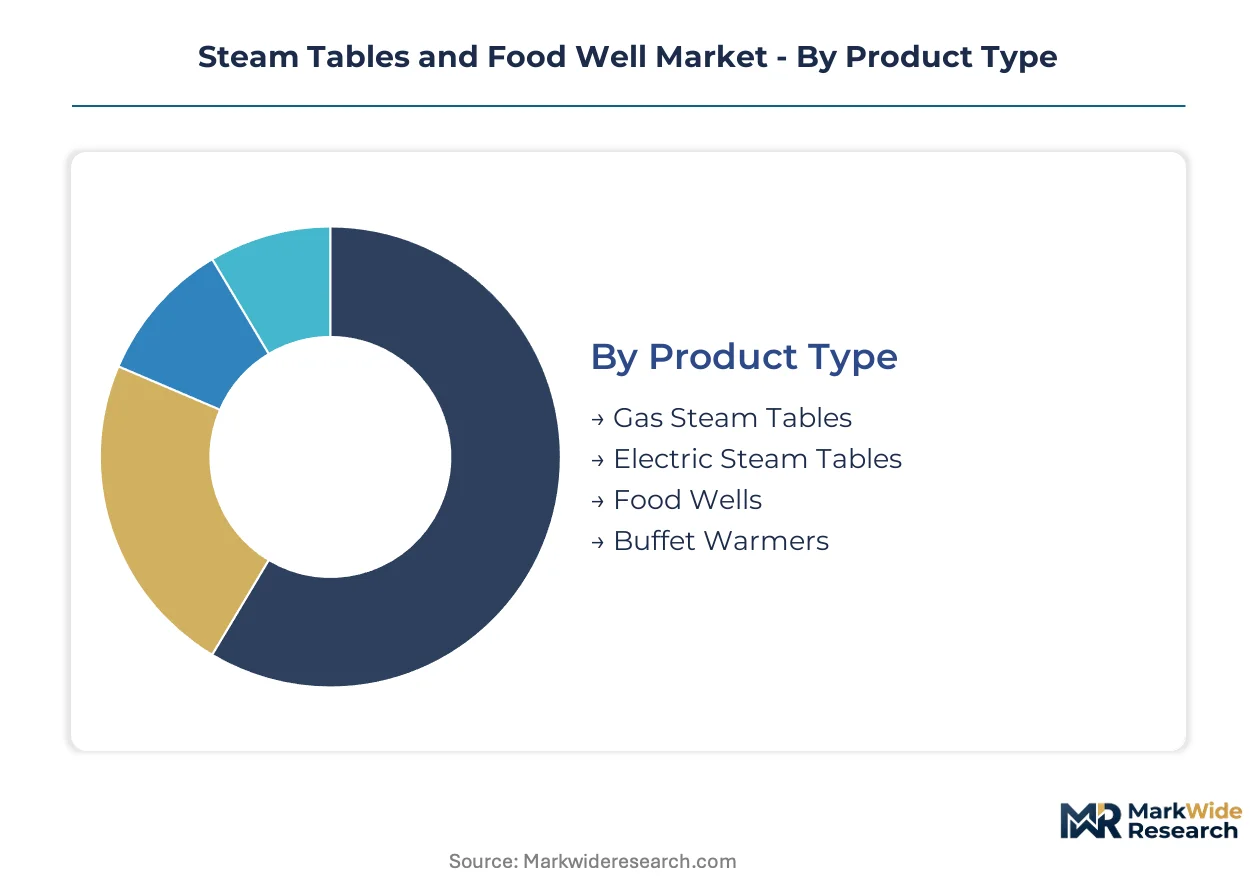
Steam table and food well procurement hinges on installation constraints, holding capacity requirements, and compliance specifications that vary sharply across operator types. Segmentation reveals where specification-grade fabrication commands premium pricing versus commodity replacement cycles.
Product Type:
Installation infrastructure and energy access dictate product selection more than holding capacity alone.
- Electric Steam Tables:Thermostatically controlled heating elements deliver precise temperature maintenance within the FDA-mandated 135°F to 165°F window. Urban operators in municipalities with strict emissions codes favor these units for simpler permitting and tighter zone control. NSF certification timelines compress refresh cycles toward seven-year norms.
- Food Wells:Drop-in configurations integrate with custom serving counters and mobile buffet systems, enabling reconfigurable institutional layouts. Healthcare and university dining sectors drive specification volume for modular installations that reduce fixed-capital commitment.
- Gas Steam Tables:Natural gas heating delivers faster recovery speeds for high-volume cafeterias with existing gas-line infrastructure.
- Buffet Warmers:Freestanding mobile units serve catering and temporary serving line applications where permanent installation is impractical.
Electric steam tables lead on scale; food wells lead on momentum as institutional buyers prioritize flexibility.
End User:
Volume concentration and replacement frequency separate specification-driven procurement from commodity purchasing.
- Restaurants:Quick-service chains deploy standardized steam table fleets across rollout locations, creating demand for custom-length assemblies with reliable lead times. Menu diversification into hot-held proteins and grain bowls extends holding equipment counts per location.
- Cafeterias:K-12 school nutrition programs and healthcare systems face USDA-backed modernization mandates and FDA Food Code compliance pressure. Group purchasing organizations consolidate procurement through state-level cooperative agreements, demanding lifecycle cost guarantees.
- Catering Services:Event-driven operators require portable warming capacity with rapid setup and breakdown capabilities.
- Food Trucks:Space-constrained mobile operators prioritize compact electric units compatible with generator or shore-power limitations.
Cafeterias lead on scale; restaurants lead on momentum through chain expansion velocity.
Material:
Corrosion resistance and NSF compliance separate durable fabrication from first-cost alternatives.
- Stainless Steel:Type 304 grade in 14- to 16-gauge thickness dominates specification-driven segments for corrosion resistance in high-moisture environments. Nickel and chromium input cost volatility squeezes fabrication margins and destabilizes project quoting.
- Aluminum:Lighter weight reduces shipping costs for mobile and temporary installations where durability requirements moderate.
- Plastic:Economy-tier buffet warmers and disposable catering applications accept lower thermal mass for cost minimization.
- Composite Materials:Emerging insulation-integrated panels address wet-well thermal efficiency under EPA refrigerant phasedown pressure.
Stainless steel leads on scale; composite materials lead on momentum as insulation chemistry R&D accelerates.
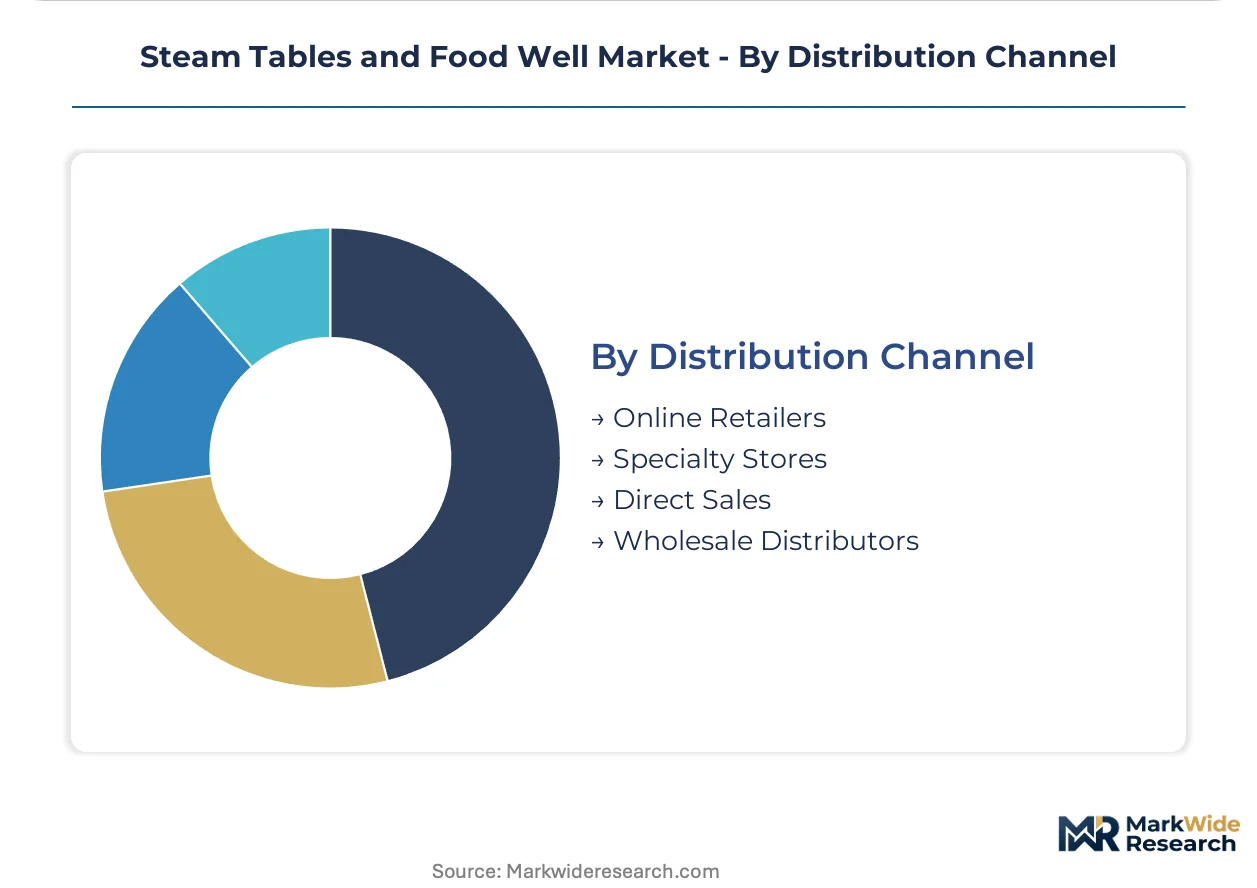
Distribution Channel:
Buyer scale and technical support requirements determine channel selection and margin capture.
- Direct Sales:Large institutional accounts and chain rollouts negotiate specification-grade fabrication with lifecycle service contracts. Manufacturers capture margin that wholesale distributors otherwise extract.
- Wholesale Distributors:Independent restaurants and mid-size operators rely on regional inventory availability and consolidated shipping. Lead-time reliability for replacement cycles sustains channel relevance.
- Online Retailers:Small operators and emergency replacement purchases accept standardized configurations for convenience and price transparency.
- Specialty Stores:Equipment dealers provide installation coordination and local service networks for complex gas-to-electric conversions.
Wholesale distributors lead on scale; direct sales lead on momentum as consolidated procurement concentrates buyer power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steam table and food well manufacturing originated in the industrial Midwest of the United States during the post-war expansion of institutional foodservice, with Wisconsin and Ohio fabrication hubs establishing the stainless steel supply chains that still dominate specification-grade production today.
United States
Quick-service chain rollouts and K-12 school nutrition program upgrades drive replacement demand across seven-year refresh cycles. NSF International certification and FDA Food Code compliance shape procurement eligibility for institutional buyers. Fabrication concentrates in Wisconsin and Ohio, where certified TIG welders cluster around legacy stainless steel stamping operations.
Germany
Commercial kitchen renovation cycles in hospitality and healthcare sectors sustain premium equipment demand. Ecodesign Directive efficiency benchmarks and EU F-Gas Regulation compliance pressure reshape wet-well insulation specifications. Industrial fabrication centers in North Rhine-Westphalia and Baden-Württemberg host precision metalworking operations serving pan-European distribution networks.
China
Urban foodservice expansion and international hotel chain penetration create specification-grade import demand alongside domestic production growth. GB standards for commercial kitchen equipment and local emissions codes in municipalities like Shanghai influence electric steam table adoption. Manufacturing clusters in Guangdong and Zhejiang provinces supply cost-competitive units for emerging market export.
Japan
Compact urban restaurant formats and convenience store hot-food programs require space-efficient holding equipment with precise temperature control. METI energy efficiency standards and JIS certification requirements filter procurement eligibility for commercial operators. Fabrication activity concentrates in Aichi Prefecture and Osaka industrial corridors, where precision metalworking traditions support high-specification production.
United Kingdom
Healthcare catering modernization and university dining contract renegotiations drive equipment refresh demand. CE marking requirements and evolving UKCA product safety regulations post-Brexit complicate import sourcing for institutional buyers. Distribution and light assembly operations cluster in West Midlands logistics corridors serving NHS and education sector procurement frameworks.
Steam Tables and Food Well Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and specification-grade fabrication capability. The vendor base stratifies into three tiers: NSF-certified specialists capturing institutional contracts, regional fabricators serving replacement cycles, and import-dependent distributors filling economy segments. Two dominant competitive moves define current positioning: precision humidity control technology licensing and consolidated procurement group partnerships that bundle lifecycle service contracts.
Among North American specialists, Vollrath Company, LLC and Alto-Shaam, Inc. occupy positions within the premium specification tier, while Wells Manufacturing exemplifies lead-time reliability positioning for chain restaurant rollouts. These three entities represent distinct competitive archetypes—deep fabrication heritage, precision environmental control technology, and custom assembly responsiveness—without exhaustively mapping the competitive set.
| Leading Market Players |
|---|
| Vollrath |
| Alto-Shaam |
| Wells Manufacturing |
| Duke Manufacturing |
| Hatco Corporation |
| Advance Tabco |
| Eagle Group |
| APW Wyott |
| Middleby Corporation |
| Others |
Pricing and Supply Chain Analysis
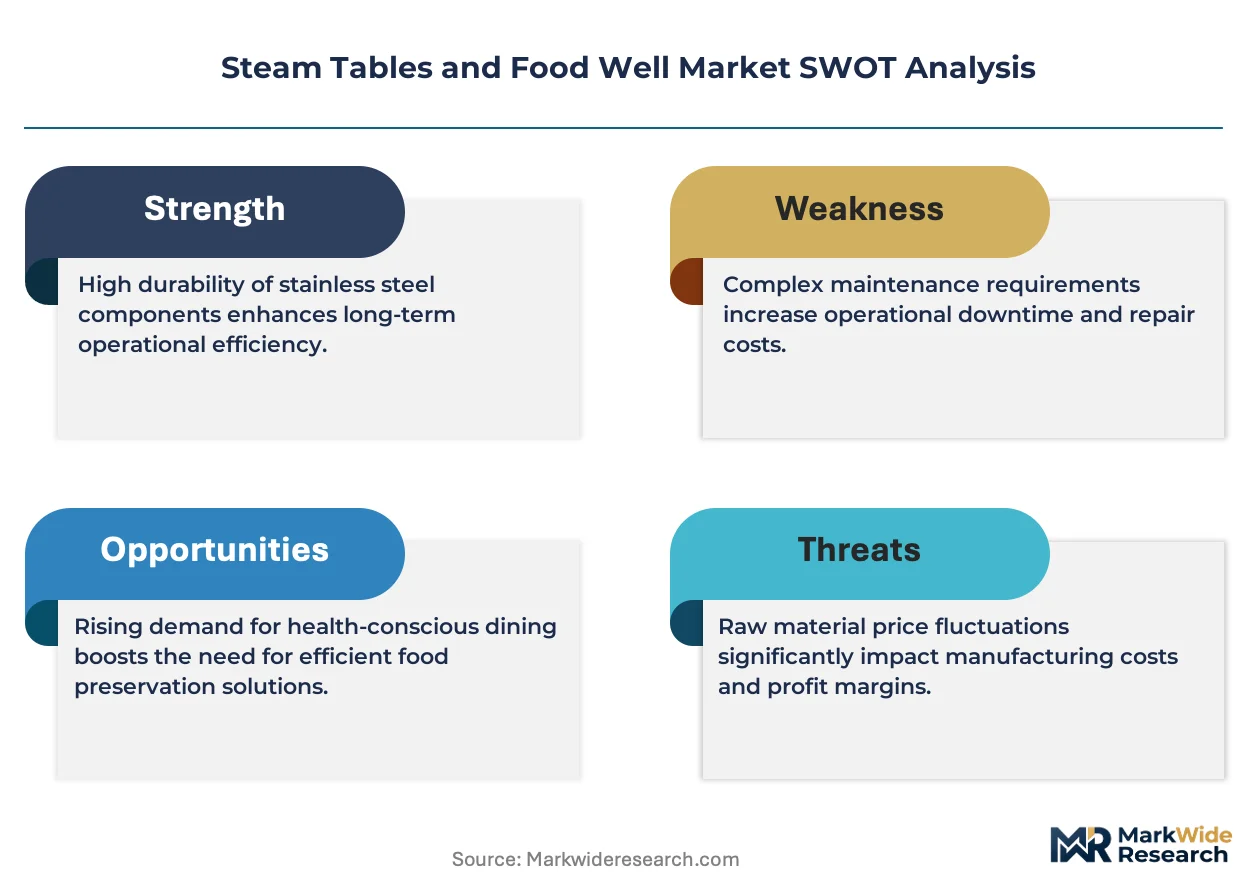
Nickel and chromium price indices on the London Metal Exchange cascade directly into Type 304 stainless steel fabrication costs, compressing margins for specification-grade steam table manufacturers and forcing three-tier pricing stratification across NSF-certified premium, standard-grade electric, and economy gas configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified precision humidity systems from basic electric holding cabinets and import-dependent gas alternatives. Price differentiation hinges on ENERGY STAR certification tier and after-sales service bundling. Cost compression in the standard tier intensifies because consolidated procurement through group purchasing organizations concentrates buyer leverage. Quick-service chains exhibit lowest price sensitivity due to lifecycle cost guarantees, while independent restaurants face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with certified TIG welders concentrated in Wisconsin and Ohio fabrication hubs. Manufacturing draws from Type 304 stainless steel mills in the United States, nickel suppliers from Indonesia and the Philippines, and chromium from South Africa and Kazakhstan. Commodity price volatility in nickel markets threatens margin stability for custom-length assembly producers. Distribution runs through wholesale distributors holding regional inventory for replacement cycles, with direct sales capturing chain rollout contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through precision humidity technology premiumization offsetting stainless steel input volatility, as institutional buyers shift specification weight toward holding-window extension and predictive maintenance capability.
For Market Incumbents: Lock in specification-grade positioning by deepening captive supply of Type 304 stainless steel through backward integration into Midwest fabrication hubs, while accelerating NSF certification pipelines to outpace testing backlog delays from emerging humidity-control competitors. For New Entrants and Emerging Players: Group purchasing organizations serving K-12 districts present the most penetrable channel for modular mobile buffet systems, where reconfigurable serving lines reduce fixed-installation capital and lifecycle cost guarantees displace incumbent direct relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with precision environmental control technology specialists holding proprietary humidity-management patents, given five-to-ten year viability as EPA refrigerant phasedown forces wet-well insulation chemistry reformulation and vacuum-insulated well R&D acceleration. Watch for ENERGY STAR benchmark tightening as inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Supply | Captive sourcing of Type 304 grade from Ohio and Wisconsin mills insulates fabrication margins against LME nickel volatility. |
| Precision Humidity Control Module Launch | Capacitive sensing and microprocessor-driven steam injection extends protein holding windows for healthcare sector contracts. |
| Group Purchasing Organization Partnership | State-level cooperative agreements for K-12 districts bundle lifecycle service contracts and consolidate procurement volume. |
| Vacuum-Insulated Well Design Development | Dry-heat alternatives gain first-mover advantage as EPA hydrofluorocarbon restrictions tighten wet-well compliance timelines. |
| Remote Monitoring Platform Integration | IoT temperature logging converges with FDA Food Code audit requirements for premium positioning in hospital systems. |
Research Methodology
Bottom-up cafeteria and restaurant operator modeling reconciled against top-down stainless steel fabrication capacity tracking forms the analytical core of this study. Primary interviews with commercial kitchen equipment procurement directors, NSF certification testing laboratory managers, foodservice distributor account executives, and K-12 nutrition program administrators combined with secondary validation from FDA Food Code provisions, EPA ENERGY STAR equipment databases, LME nickel price archives, and USDA school nutrition program modernization grant disclosures. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices map electric steam table, gas steam table, food well, and buffet warmer volumes against end-use segments, material grades, and distribution channels across the projection horizon. CAGRs derive from segmented growth rate reconciliation against macroeconomic foodservice expansion indicators and equipment replacement cycle compression from ten-year toward seven-year norms. Industry-specific forecast inputs include school nutrition program modernization funding trajectories and urban emissions code adoption patterns in municipalities with strict electric infrastructure preferences.
Revisions become necessary when nickel and chromium price volatility exceeds historical bands, when NSF International testing backlogs extend beyond nine months, or when EPA refrigerant phasedown timelines accelerate. Forecasts reflect documented assumptions about institutional buyer procurement consolidation and stainless steel fabrication capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Undercounter Ice Makers Market
Food Service
Popcorn Making Cart Market
Food Service
Inflight Catering Market
Food Service
Smokeless Grill Market
Food Service
China Online Food Delivery Market
Food Service
Bangladesh Food Service Market
Food Service
Kuwait Food Service Market
Food Service
Benelux Foodservice Market
Food Service
Smoker Grill Market
Food Service
GCC Online Grocery Market
Food Service
Commercial Grills Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
United States Foodservice Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Onboard Rail Catering Market