
 Commercial Burger Grill Market | 2026-2036
Commercial Burger Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Burger Grill Market Outlook
China is rewriting supply chain dynamics for commercial burger grill manufacturing as domestic foundries expand stainless steel fabrication capacity for export markets. Weber Inc. leverages its brand strength across North American dealer networks. Traeger Inc. differentiates through pellet-fired technology leadership in the premium commercial segment. Napoleon Grills anchors its position with Canadian manufacturing scale and cross-border distribution control.
A commercial burger grill is a thermostatically controlled cooking appliance engineered to deliver consistent surface temperatures between 300°F and 700°F across grooved or flat cast-iron or stainless steel plates, designed for high-volume protein preparation in professional foodservice environments. Gas grills occupy the dominant share of commercial installations due to operational familiarity and utility infrastructure prevalence, while electric grills represent the fastest-growing product type as urban kitchens confront ventilation restrictions and fire code limitations. Food chains command the largest application segment by unit volume, though food trucks generate disproportionate margin capture through compact, multi-fuel equipment specifications.
NSF International standards govern equipment sanitation and material safety across the United States commercial kitchen landscape, while the EU Machinery Directive and CE marking requirements shape product access across European member states. The U.S. Environmental Protection Agency regulates particulate emissions from charcoal and wood-fired installations, influencing fuel type selection in metropolitan jurisdictions with air quality management plans. Stakeholders must monitor evolving municipal electrification mandates and building code amendments that will determine permissible fuel configurations for new commercial kitchen construction.
Market Dynamics
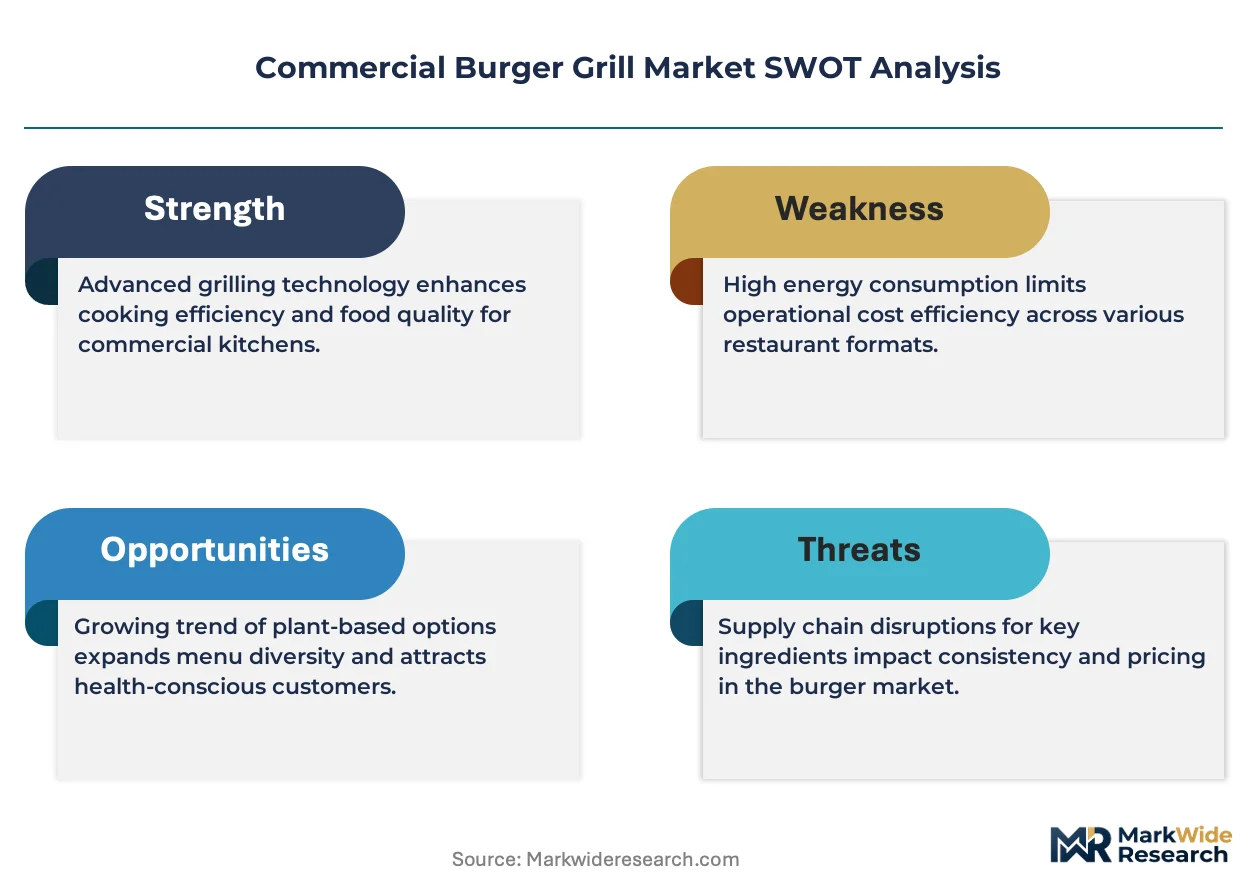
NSF International certification mandates are compressing supplier margins as stainless steel fabrication costs rise and third-party testing timelines extend. Quick-service chains now require documented grease management systems before equipment approval, shifting procurement criteria toward compliance depth rather than unit economics alone.
Growth Catalysts
- Electrification mandates:Municipal building codes in California and New York are prohibiting new gas hookups in commercial kitchens. Electric grill specifications are displacing propane infrastructure in urban food halls.
- Food truck proliferation:Mobile foodservice operators demand compact multi-fuel platforms. Equipment manufacturers are engineering modular burner systems that switch between propane, electricity, and pellet fuel within single chassis.
- NSF/ANSI 4 standards:Updated sanitation protocols require seamless weld construction and removable drip trays. Fabricators are retooling production lines to meet these material specifications.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input costs fluctuate with Indonesian export policies. Foundry contracts now carry 90-day price adjustment clauses.
- Guangdong supply concentration:Over 60 percent of cast-iron plate production sits in Pearl River Delta facilities. Port congestion and electricity rationing create delivery uncertainty.
- Ventilation retrofit costs:Existing kitchens face 15,000 to 40,000 dollar hood and duct modifications to accommodate high-BTU gas installations. Electric alternatives bypass this capex barrier.
Strategic Opportunities
- India cloud kitchen expansion:Delivery-aggregator platforms are building 500-plus ghost kitchen facilities annually. Compact electric grills with IoT temperature logging match these operators' space constraints and data requirements.
- EU F-Gas Regulation phase-down:Refrigerant restrictions are accelerating interest in hydrocarbon-based cooling for refrigerated prep stations adjacent to grill lines. Integrated equipment bundles capture this specification shift.
- Pellet-wood convergence:Traeger's auger-feed combustion systems are migrating from residential to commercial specifications. Smoked flavor profiles differentiate fast-casual burger chains in saturated markets.
Industry Challenges
- Certification timeline compression:NSF International testing queues now extend 14 to 18 weeks. Product launch windows misalign with seasonal buying cycles.
- Control system integration:Legacy kitchen display software lacks API compatibility with smart grill temperature monitoring. Middleware development consumes engineering resources.
- Weld inspection capacity:Radiographic testing facilities are backlogged across Midwest manufacturing corridors. Quality bottlenecks constrain output scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Burger Grill Market |
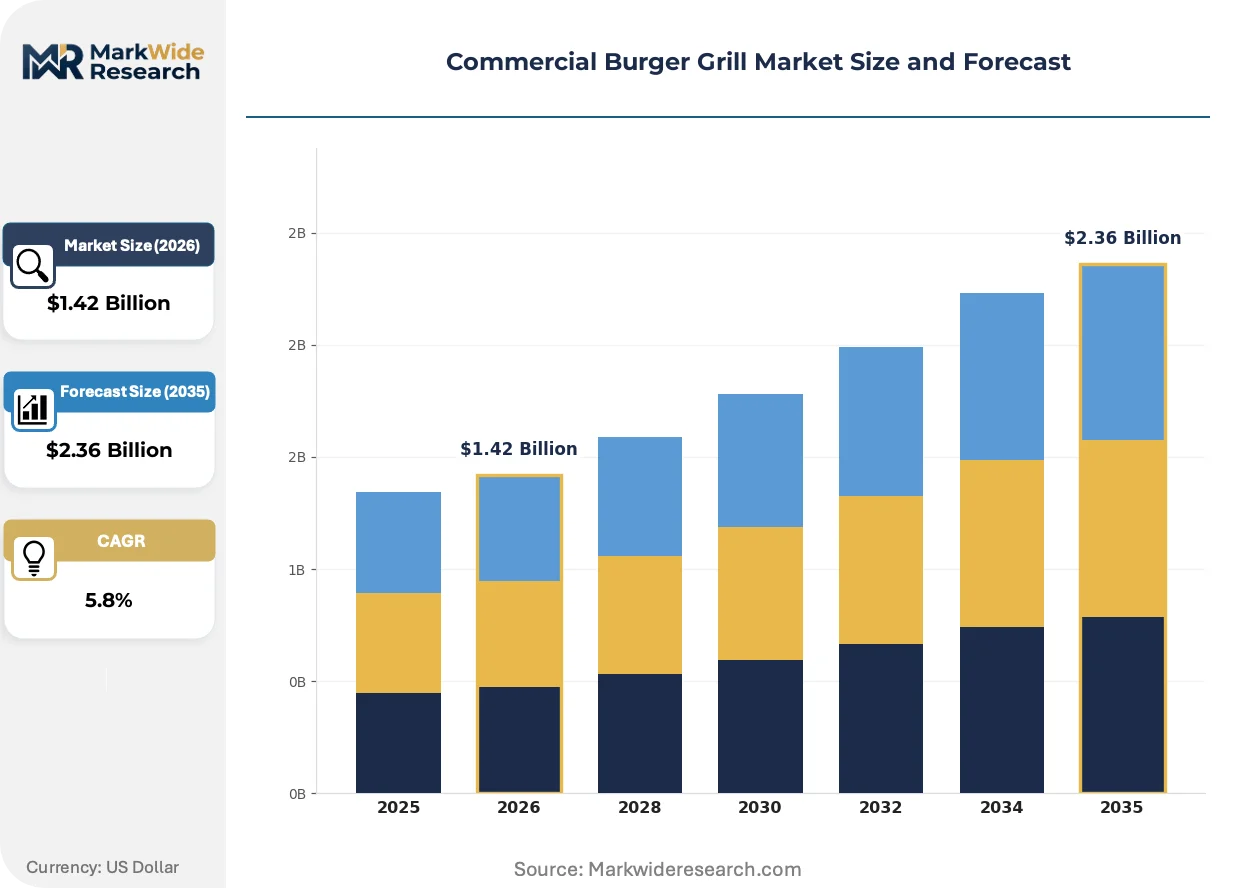
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Grills, Charcoal Grills, Electric Grills, Dual-Fuel Grills Application: Food Trucks, Restaurants, Catering Services, Food Chains End User: Commercial Kitchens, Fast Food Outlets, Diner Establishments, Catering Companies Distribution Channel: Online Retailers, Direct Sales, Specialty Stores, Wholesale Distributors |
| Companies Covered | Weber Inc., Traeger Inc., Char-Broil, Napoleon Grills, Blackstone, Masterbuilt, Pit Boss Grills, Crown Verity, Lynx Grills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Burger Grill Market Strategic Shifts
Infrared burner technology is collapsing the thermal recovery gap that previously separated gas from electric performance. Equipment specifiers now prioritize precision over raw output.
Platen-based infrared emitters from ceramic honeycomb substrates deliver 700°F surface temperatures within 90 seconds of activation. Fast-casual chains with 90-second ticket targets are specifying these systems for lunch rush throughput. The technology is collapsing the traditional tradeoff between temperature precision and energy density that constrained electric grill adoption.
EPA enforcement of particulate standards under the Clean Air Act is tightening in metropolitan air quality districts. Charcoal and wood-fired installations now require catalytic oxidizers or electrostatic precipitators in Los Angeles, Houston, and Phoenix jurisdictions. Smoked-burger concepts are migrating to pellet systems with controlled combustion chambers that meet emission thresholds without aftermarket treatment.
Equipment-as-a-service contracting is displacing capital purchase models among multi-unit franchisees. Middleby and Welbilt are piloting subscription programs bundling grills, maintenance, and IoT analytics. California and Texas franchise development groups are testing these arrangements to preserve liquidity for location expansion rather than kitchen buildout.
Commercial Burger Grill Market Segmentation
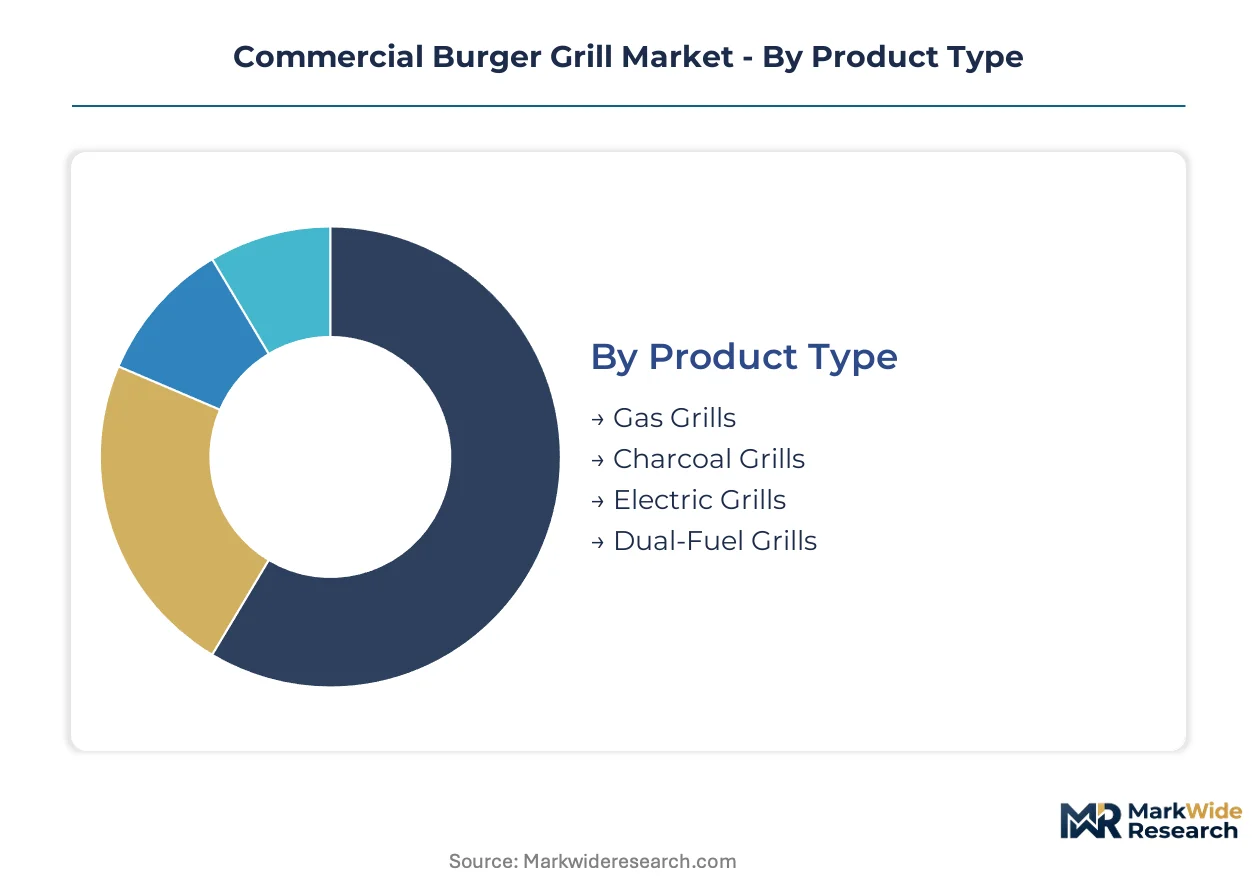
Equipment specification varies sharply across operational environments, from high-throughput food chains requiring NSF-certified gas platforms to mobile operators demanding compact multi-fuel flexibility. Understanding these segment boundaries enables manufacturers to align fabrication investments with actual procurement criteria rather than assumed demand patterns.
Product Type:
Kitchen infrastructure constraints and municipal fuel regulations create divergent specification requirements across installation types.
- Gas Grills:Thermostatically controlled propane or natural gas burners deliver 300°F to 700°F surface temperatures across cast-iron or stainless steel plates. Quick-service chains in Texas and Florida specify these for operational familiarity and existing utility infrastructure, though California and New York electrification mandates are compressing new installation permits.
- Electric Grills:Resistance-element or infrared emitter systems eliminate ventilation hood requirements and bypass fire code restrictions in urban food halls. Operators in Manhattan and San Francisco are specifying these to avoid 15,000 to 40,000 dollar duct retrofit costs, making this segment expand most quickly among product categories.
- Charcoal Grills:Open-flame combustion of hardwood or briquette fuel delivers distinct flavor profiles for premium positioning.
- Dual-Fuel Grills:Modular burner architectures switch between gas, electric, and pellet configurations within single chassis units.
Established volume favors Gas Grills; emerging adoption favors Electric Grills.
Application:
Throughput targets and mobility requirements segment procurement behavior across fixed and mobile foodservice operations.
- Food Chains:Corporate specification programs mandate NSF/ANSI 4 compliance, seamless weld construction, and documented grease management systems before vendor approval. Multi-unit operators in the United States concentrate replacement cycles and new unit openings into Q2-Q3 buying windows, compressing manufacturer delivery timelines.
- Food Trucks:Compact footprints and multi-fuel flexibility command premium pricing relative to stationary equivalents. California and Texas mobile operators specify pellet-gas hybrid systems to differentiate smoked flavor profiles while maintaining propane backup for locations lacking electrical infrastructure.
- Restaurants:Independent full-service operators balance equipment cost against menu positioning requirements.
- Catering Services:Event-based volume spikes demand rapid thermal recovery and portable configurations.
Unit concentration sits with Food Chains; margin capture concentrates in Food Trucks.
End User:
Operational scale and menu complexity determine whether buyers prioritize throughput velocity or equipment versatility.
- Fast Food Outlets:90-second ticket targets require infrared burner technology with sub-90-second thermal recovery. Platen-based ceramic honeycomb emitters are displacing traditional gas tubes in new buildouts across the United States.
- Commercial Kitchens:Centralized production facilities for delivery-aggregator platforms demand IoT-enabled temperature logging and compact electric specifications. India cloud kitchen operators are driving specification shifts toward data-integrated equipment bundles.
- Diner Establishments:Independent operators balance replacement cost constraints against NSF certification requirements.
- Catering Companies:Seasonal demand patterns favor rental or subscription contracting models over capital purchase.
Procurement standardization dominates Fast Food Outlets; flexibility requirements concentrate in Commercial Kitchens.
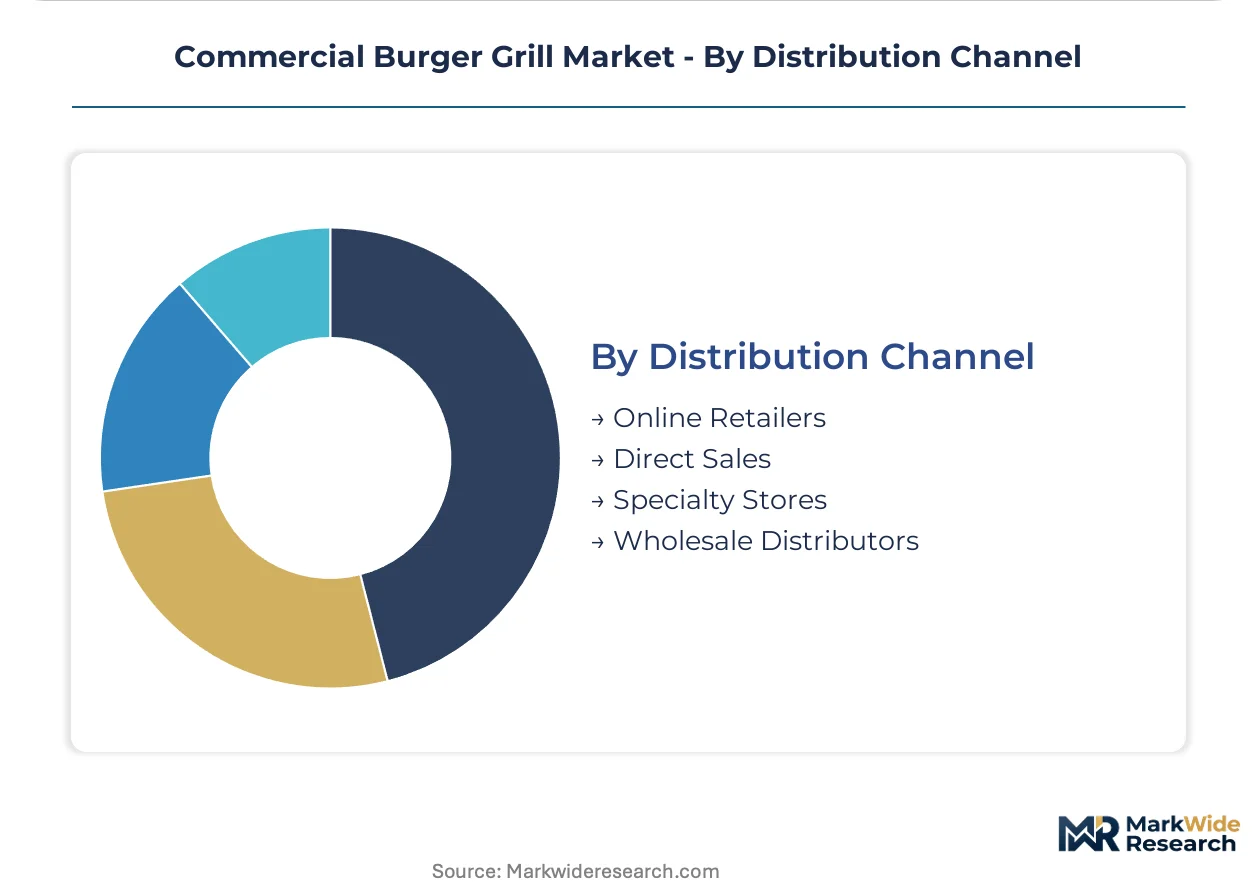
Distribution Channel:
Buyer sophistication and order scale determine whether transactions flow through direct relationships or intermediated retail.
- Direct Sales:Manufacturer field organizations manage specification development with multi-unit franchise development groups. Equipment-as-a-service pilot programs from Middleby and Welbilt are testing subscription bundling through this channel in California and Texas.
- Wholesale Distributors:Dealer networks anchor Weber Inc.'s North American penetration, providing installation and maintenance capacity that manufacturers lack directly.
- Specialty Stores:Regional fabricators and independent dealers serve replacement demand from independent restaurants.
- Online Retailers:E-commerce penetration remains limited by freight costs and installation complexity for commercial-grade equipment.
Contract value concentrates through Direct Sales; geographic coverage depends on Wholesale Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel fabrication capacity clusters in Guangdong Province supply casting components to North American and European assembly plants. Foundry electrification and export logistics shape regional competitive positioning.
United States
Quick-service chains in Texas and Florida drive replacement cycles for gas-fired platforms, while California electrification mandates compress new propane installations. The EPA enforces particulate standards under the Clean Air Act in Los Angeles, Houston, and Phoenix air quality districts. Chicago and Dallas manufacturing corridors face radiographic testing backlogs that constrain weld inspection capacity for NSF-certified equipment.
China
Pearl River Delta foundries supply over sixty percent of global cast-iron plate production for commercial grill assemblies. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate foundry electrification and emission controls. Foshan and Zhongshan industrial clusters retool stainless steel fabrication lines to meet NSF International material specifications for export markets.
Germany
Commercial kitchen operators prioritize CE-marked equipment under EU Machinery Directive compliance requirements. The EU F-Gas Regulation phase-down accelerates interest in hydrocarbon-based cooling for integrated prep station bundles. Bavarian and North Rhine-Westphalia equipment distributors anchor central European supply chain coverage for multi-unit franchise procurement.
India
Delivery-aggregator platforms commission five hundred-plus cloud kitchen facilities annually, specifying compact electric grills with IoT temperature logging. The Bureau of Indian Standards governs equipment safety certification for commercial foodservice installations. Maharashtra and Karnataka urban clusters concentrate ghost kitchen development, driving demand for space-constrained cooking platforms.
Canada
Cross-border distribution networks serve United States quick-service chains from Ontario and Quebec manufacturing bases. Health Canada regulates commercial food equipment safety through provincial adoption of national standards. Napoleon Grills anchors Canadian production scale with integrated supply chain control spanning Great Lakes distribution corridors.
Commercial Burger Grill Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on casting and control modules. Market structure consolidates around branded equipment manufacturers with certification depth, while foundry and burner component supply fragments across regional metalworking clusters. Three archetypes dominate: NSF-certified platform integrators, multi-fuel technology specialists, and contract fabrication houses serving private-label programs. Competitive moves concentrate on strategic partnerships for IoT integration and geographic expansion through distributor network capture.
Among North American platform integrators, Weber Inc. and Traeger Inc. occupy positions across premium commercial segments. Weber leverages established dealer network density for specification capture with multi-unit operators. Traeger exemplifies technology-led differentiation through pellet-fired combustion system migration from residential to commercial specifications. Napoleon Grills anchors Canadian manufacturing scale with cross-border distribution control into United States food chain procurement programs.
| Leading Market Players |
|---|
| Weber Inc. |
| Traeger Inc. |
| Char-Broil |
| Napoleon Grills |
| Blackstone |
| Masterbuilt |
| Pit Boss Grills |
| Crown Verity |
| Lynx Grills Inc. |
| Others |
Value Chain & Pricing Dynamics
Foshan and Zhongshan industrial clusters in Guangdong Province control over sixty percent of global cast-iron plate fabrication capacity for commercial grill assemblies, translating upstream foundry concentration into asymmetric pricing power for NSF-certified platform integrators serving North American quick-service chains.
Pricing Analysis
NSF/ANSI 4 certification dictates the pricing tier structure across the commercial burger grill landscape, separating seamless-weld stainless steel platforms with documented grease management systems from economy-grade welded alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with premium tiers commanding sustained margins through regulatory entrenchment. Cost compression in standard tiers is intensifying because Indonesian nickel export policies inject raw material volatility into foundry contracts. Independent diners and small multi-unit operators exhibit the highest price sensitivity, while corporate franchise development groups prioritize compliance depth over unit economics.
Supply Chain Analysis
Export-control scrutiny on advanced manufacturing equipment limits Western foundry technology transfers to Chinese stainless steel fabricators, constraining capacity expansion timelines for NSF-grade production lines. Supply concentrates in China for cast-iron plate casting, the United States for final assembly and certification testing, and Germany for precision control system components. Raw material flows draw from Indonesian nickel mines, South African chromium deposits, and Australian iron ore. Single-source vulnerability sits with Pearl River Delta electricity rationing and port congestion. Distribution runs through wholesale dealer networks anchored by regional fabricators with installation and maintenance capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where NSF certification timelines and radiographic testing backlogs create switching costs that entrench incumbent platform integrators against emerging competitors.
For Market Incumbents: Insulate market position by deepening captive supply relationships with Guangdong foundries retooling for NSF material specifications, while accelerating IoT temperature logging integration to meet India cloud kitchen data requirements. Electrification mandates in California and New York represent the primary regulatory threat compressing gas grill replacement cycles. Certification investment serves as the critical defensive lever against price erosion from contract fabrication houses. For New Entrants and Emerging Players: Compact electric grills for India cloud kitchen operators represent the most penetrable entry point, given delivery-aggregator platform procurement velocity and limited incumbent IoT bundling. Pellet-fired commercial specifications for fast-casual smoked-burger differentiation offer secondary white-space capture. A specification-sell approach targeting ghost kitchen facility developers bypasses entrenched dealer network control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with certification depth and cross-border distribution scale over component specialists exposed to raw material volatility. Long-term viability hinges on electrification mandate adaptation and IoT analytics bundling. Acquisition targets should demonstrate NSF testing queue relationships and foundry contract security. The signal to watch is municipal building code amendment velocity in metropolitan jurisdictions with air quality management plans.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Acceleration | Compresses 14-18 week testing queues to capture seasonal Q2-Q3 buying windows for multi-unit chains. |
| Foundry Electrification Partnership | Aligns Guangdong stainless steel capacity with dual carbon goals and export market access requirements. |
| IoT Platform Integration | Enables temperature logging specifications for India cloud kitchen procurement and subscription service pilots. |
| Multi-Fuel Modular Development | Addresses food truck operator demand for pellet-gas hybrid flexibility in California and Texas mobile markets. |
| Dealer Network Capture | Replicates Weber's North American specification penetration through installation and maintenance capacity control. |
Study Parameters
Initial hypotheses were tested against primary input from quick-service chain procurement directors, commercial kitchen equipment dealers, foundry operations managers, and NSF International certification engineers, and refined through secondary validation against customs trade records, SEC equipment manufacturer filings, EPA Clean Air Act enforcement databases, and municipal building code amendment trackers. Bottom-up demand modeling across food chain, food truck, and restaurant application segments was triangulated with top-down market sizing from fabrication capacity and import flow analysis.
Demand-supply balance dynamics across the analysis window were modeled through equipment replacement cycle tracking, new unit opening pipelines, and foundry output constraints. Segmentation dimensions included product type, application environment, end-user operational scale, and distribution channel structure. CAGRs were derived from installation base growth, technology substitution rates, and regulatory mandate diffusion curves. Forecast inputs incorporated electrification policy velocity, cloud kitchen facility commissioning rates, and pellet-fired technology migration timelines from residential to commercial specifications.
Practitioners should monitor NSF International testing queue extensions, Indonesian nickel export policy shifts, and municipal gas hookup prohibition enactments for early signals of forecast revision. Cross-checking against equipment manufacturer order backlog disclosures and foundry electricity rationing reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Foodservice Market
Food Service
Kuwait Food Service Market
Food Service
Commercial Tandoor Oven Market
Food Service
Catering Food Warmers Market
Food Service
Commercial Tableware Services Market
Food Service
Chile Food Delivery Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
United States Foodservice Market
Food Service
Food Trucks Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
India Quick Service Restaurant Market
Food Service
Wok Market
Food Service
North America Online Grocery Delivery Market
Food Service
Vietnam Food Service Market
Food Service
Brazil Foodservice Market
Food Service
Germany Smokeless Indoor Grills Market