
 India Foodservice Market | 2026-2036
India Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
India Foodservice Market Foresight
Multi-source procurement of fresh produce and packaged ingredients is consolidating as chains reduce dependency on unorganized mandi networks. Jubilant FoodWorks Limited anchors its supply chain through dedicated cold-chain partnerships across North and West India. Rebel Foods operates a cloud-kitchen infrastructure that leverages data-driven demand forecasting to optimize real estate and labor costs. Tata Starbucks Pvt Ltd differentiates through imported bean sourcing and in-house roasting protocols that sustain premium positioning in metro malls and business districts.
Foodservice encompasses the commercial preparation and sale of meals outside residential settings, spanning standardized quick-service counters to full-service dining with live cooking stations and curated beverage programs. The sector relies on cold-chain integrity, typically maintaining proteins at 4°C or below and frozen goods at minus 18°C, to prevent spoilage across India's tropical climate zones. Quick Service dominates transaction volume due to low ticket sizes and rapid throughput, while Full Service captures disproportionate margin pools through beverage attachment and experiential dining. Online Ordering through aggregator platforms and proprietary apps is the fastest-growing distribution channel, though Dine-in retains structural importance in South Indian formats where filter coffee and thali service define the value proposition.
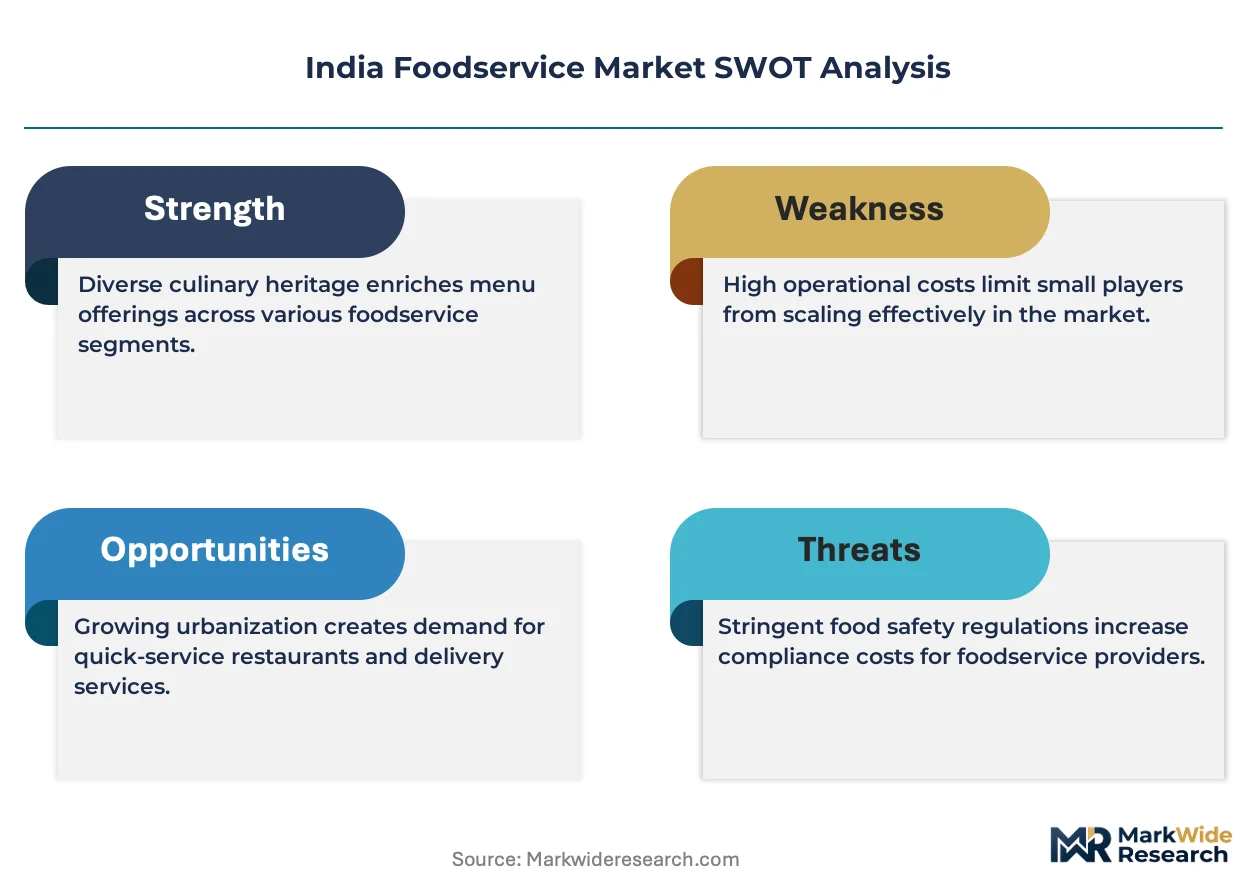
FSSAI mandates licensing and periodic hygiene audits for all food business operators, with state-level enforcement varying in stringency across Gujarat, Tamil Nadu, and Punjab. BIS standards for food-grade packaging materials and equipment safety create compliance costs that favor organized chains with dedicated quality teams over street vendors and single-outlet operators. The PLI scheme for food processing infrastructure indirectly benefits foodservice through expanded domestic supply of frozen dough, sauces, and partially prepared bases. Stakeholders must monitor evolving GST slab rationalization for restaurant services and the uneven pace of municipal health digitization across tier-two cities.
Market Dynamics
UPI integration and FSSAI-mandated digitization of hygiene audits are compressing operational margins for unorganized vendors while rewarding chains with centralized compliance infrastructure.
Growth Catalysts
- FSSAI Licensing Mandate:Standardized hygiene protocols under India's food safety regulator are accelerating formalization, pushing street vendors toward franchised models with built-in audit trails.
- Cloud Kitchen Proliferation:Data-driven demand forecasting enables asset-light expansion into micro-markets without prime real estate exposure, lowering break-even thresholds for new entrants.
- Maharashtra-Karnataka Metro Density:Concentrated disposable income in Mumbai, Pune, Bangalore, and Delhi NCR sustains premium format experimentation and beverage-forward concepts.
Market Restraints
- Arctic Cold-Chain Gaps:Intermittent power reliability and last-mile refrigeration deficits outside tier-one cities impose spoilage costs that erode protein-heavy menu viability.
- Unorganized Mandi Dependency:Fragmented vegetable and grain procurement through traditional wholesale markets creates price volatility and quality inconsistency for mid-scale operators.
- Input Cost Compression:Edible oil and wheat flour price swings directly squeeze QSR margins where ticket sizes resist pass-through elasticity.
Strategic Opportunities
- Tier-Two City Penetration:Underdeveloped foodservice density in Indore, Lucknow, and Kochi offers first-mover positioning before organized competition saturates local catchments.
- PLI Scheme Tailwinds:Production-linked incentives for food processing infrastructure expand domestic supply of frozen dough and sauce bases, reducing import dependency for standardized inputs.
- Aggregator Platform Convergence:Swiggy and Zomato's logistics networks enable pure-play delivery brands to bypass dine-in capex entirely while accessing national customer bases.
Industry Challenges
- Skilled Kitchen Labor Scarcity:Shortage of trained line cooks familiar with HACCP protocols and high-throughput equipment operation constrains outlet-level consistency.
- GST Slab Complexity:Ongoing rationalization debates between five percent and eighteen percent rates for restaurant services create pricing strategy uncertainty and working capital friction.
- Legacy POS Integration:Patchwork adoption of inventory-management software across franchise networks impedes real-time demand-supply matching and centralized procurement leverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Foodservice Market |
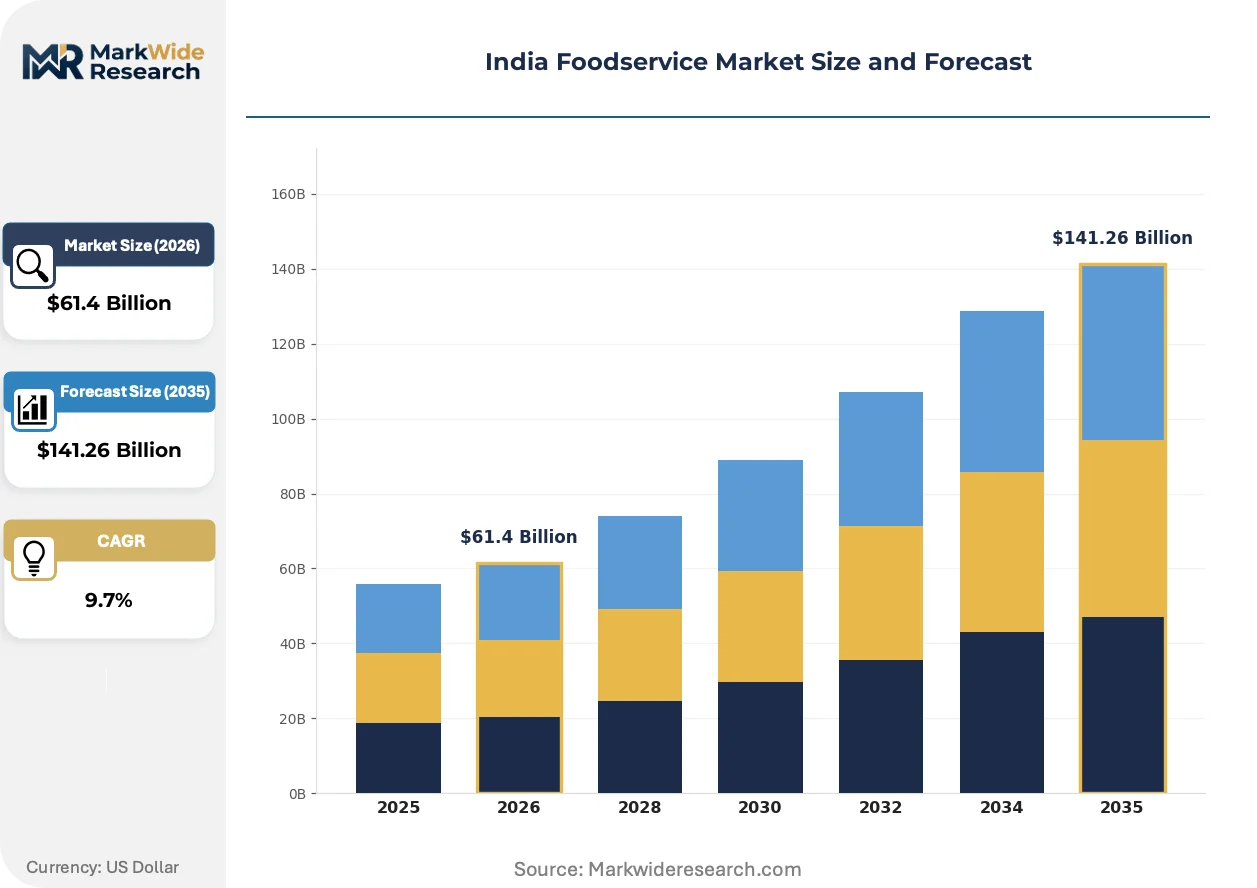
| Market Size in 2026 | $61.4 Billion |
| Market Size in 2035 | $141.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quick Service, Full Service, Cafeteria, Catering Customer Type: Individual Consumers, Corporate Clients, Educational Institutions, Event Organizers Distribution Channel: Online Ordering, Dine-in, Takeaway, Delivery Cuisine Type: North Indian, South Indian, Fast Food, Continental |
| Companies Covered | Tata Starbucks Pvt Ltd, Rebel Foods, Jubilant FoodWorks Limited, Doctor's Associates Inc (Subway), Wow! Momo Foods Pvt Ltd, Yum! Brands Inc, Coffee Day Enterprises Ltd, Hotel Saravana Bhavan, McDonald's Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Foodservice Market Shifts & Advancements
Digital payment rails and aggregator logistics are dissolving traditional location-based competitive moats, enabling format innovation that decouples brand presence from physical footprint.
AI-powered demand forecasting is absorbing uncertainty in cloud-kitchen site selection and menu mix optimization. Rebel Foods and similar operators deploy machine learning models trained on hyperlocal consumption patterns to pre-position inventory and labor hours. This compression of demand volatility is enabling multi-brand kitchen infrastructure that shares fixed costs across virtual restaurant concepts.
FSSAI's mandatory food-safety compliance digitization is absorbing paper-based audit processes into centralized traceability platforms. State-level enforcement variations across Gujarat, Tamil Nadu, and Punjab create uneven compliance burdens, with organized chains deploying dedicated quality teams to preempt inspection failures. Smaller operators face disproportionate adaptation costs as municipal health departments phase in biometric attendance and temperature-logging requirements.
Subscription-based meal programs are absorbing habitual office-lunch procurement from individual aggregator orders. Corporate clients in Bangalore and Hyderabad's IT corridors negotiate bulk contracts with cloud-kitchen networks for daily delivery of standardized thali and bowl formats. This behavioral pivot concentrates volume with fewer vendors, compressing customer acquisition costs while locking in predictable demand pools for backend production planning.
India Foodservice Market Segmentation
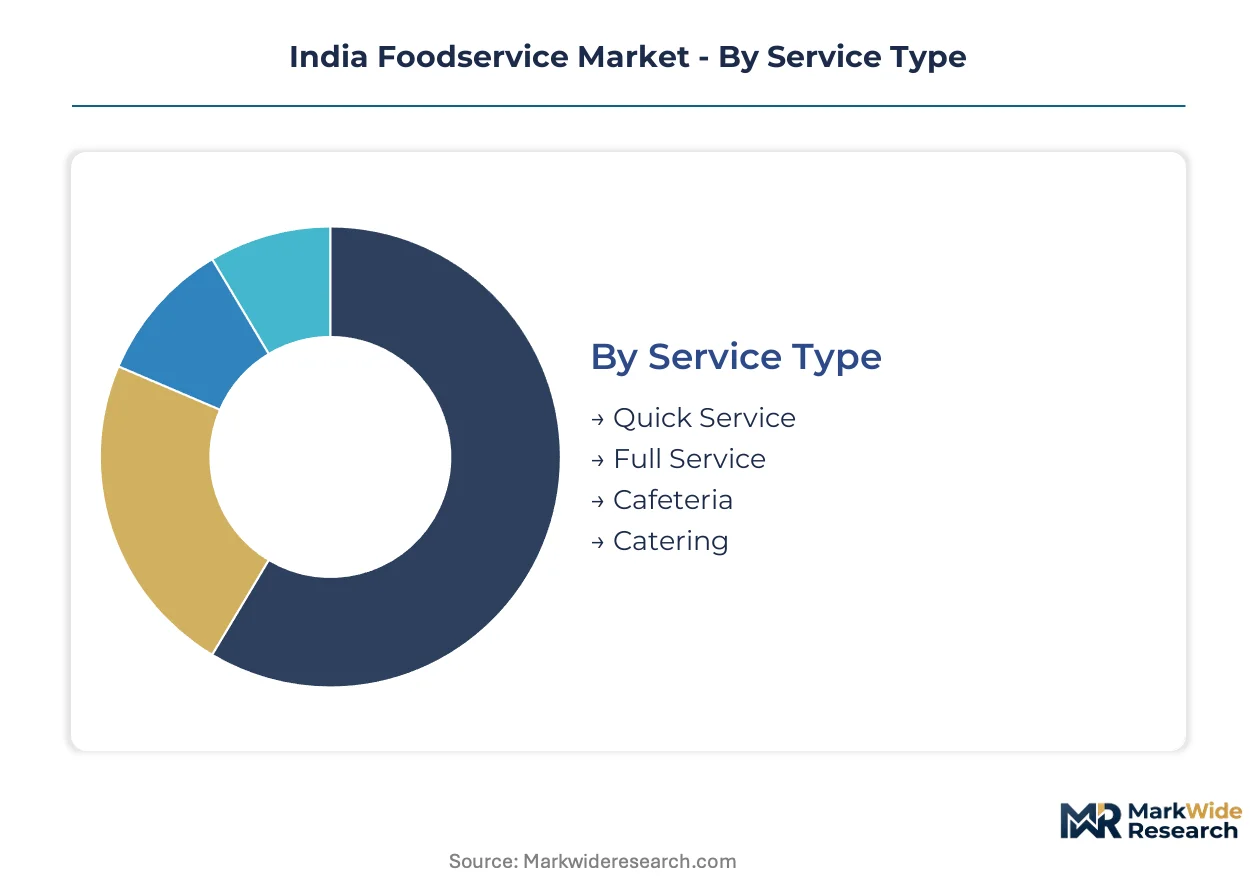
Service format differentiation determines capital intensity and margin structure across India's foodservice landscape. Segmentation reveals how urban density, corporate procurement patterns, and aggregator penetration reshape competitive boundaries between asset-heavy dine-in formats and digitally native delivery brands.
Service Type:
Supply concentration varies sharply by format, with standardized inputs and centralized kitchen infrastructure favoring scale operators in high-throughput segments.
- Quick Service:Standardized menu execution through pre-prepared bases and limited cooking stations enables sub-three-minute order cycles. Demand clusters along Mumbai Metro corridors and Bangalore IT parks where lunch-hour throughput dictates location viability; FSSAI compliance automation separates organized chains from street vendor competition.
- Full Service:Live cooking stations and curated beverage programs require skilled line cooks and front-of-house labor deployment. Premium positioning concentrates in Delhi NCR mall developments and Pune's Koregaon Park dining clusters; real estate costs absorb fifteen to twenty percent of revenue versus four to six percent for counter-service formats.
- Cafeteria:Institutional contracts with IT campuses and manufacturing facilities provide predictable volume with limited menu rotation. Karnataka and Tamil Nadu factory complexes anchor contract catering demand; biometric payment integration streamlines throughput.
- Catering:Event-based production scales from wedding banquets to corporate off-sites with severe demand seasonality. Maharashtra's wedding season concentration drives peak capacity requirements; cloud-kitchen spillover capacity absorbs volume during trough periods.
Quick Service absorbs the bulk of installed capacity; Cloud-adjacent delivery formats are expanding most quickly.
Customer Type:
Procurement authority concentration distinguishes fragmented individual spending from consolidated corporate purchasing power.
- Individual Consumers:Aggregator platform dependency creates loyalty to convenience rather than brand, with Swiggy and Zomato absorbing thirty-five percent of transaction value through commissions and delivery fees. UPI penetration enables impulse ordering without cash friction.
- Corporate Clients:Subscription meal contracts with cloud-kitchen networks lock in predictable demand pools across Bangalore and Hyderabad IT corridors; procurement teams negotiate standardized thali formats with daily delivery guarantees.
- Educational Institutions:Hostel and day-school feeding contracts require FSSAI licensing at facility level; Tamil Nadu and Gujarat state education boards mandate hygiene audit digitization.
- Event Organizers:Wedding and conference catering demands flexible capacity scaling with severe peak-to-trough labor scheduling challenges; unorganized operators dominate outside tier-one cities.
Individual Consumers generate the highest transaction frequency; Corporate Clients deliver the steadiest revenue visibility.
Distribution Channel:
Channel economics diverge sharply between fixed-cost dine-in infrastructure and variable-cost delivery logistics.
- Online Ordering:Aggregator platforms and proprietary apps dissolve location-based competitive moats for pure-play brands. Rebel Foods and similar operators bypass prime real estate entirely; machine learning demand forecasting optimizes kitchen site selection.
- Dine-in:Physical footprint retention matters disproportionately in South Indian formats where filter coffee service and thali presentation define experiential value. Mumbai and Bangalore mall developments concentrate premium full-service investment.
- Takeaway:Counter pickup without seating absorption enables lower breakeven thresholds; packaging costs and temperature retention constraints limit menu viability.
- Delivery:Third-party logistics networks enable national reach without captive fleet investment; commission structures compress margins below dine-in equivalents.
Dine-in retains structural importance in South Indian markets; Online Ordering climbs the fastest across metro corridors.
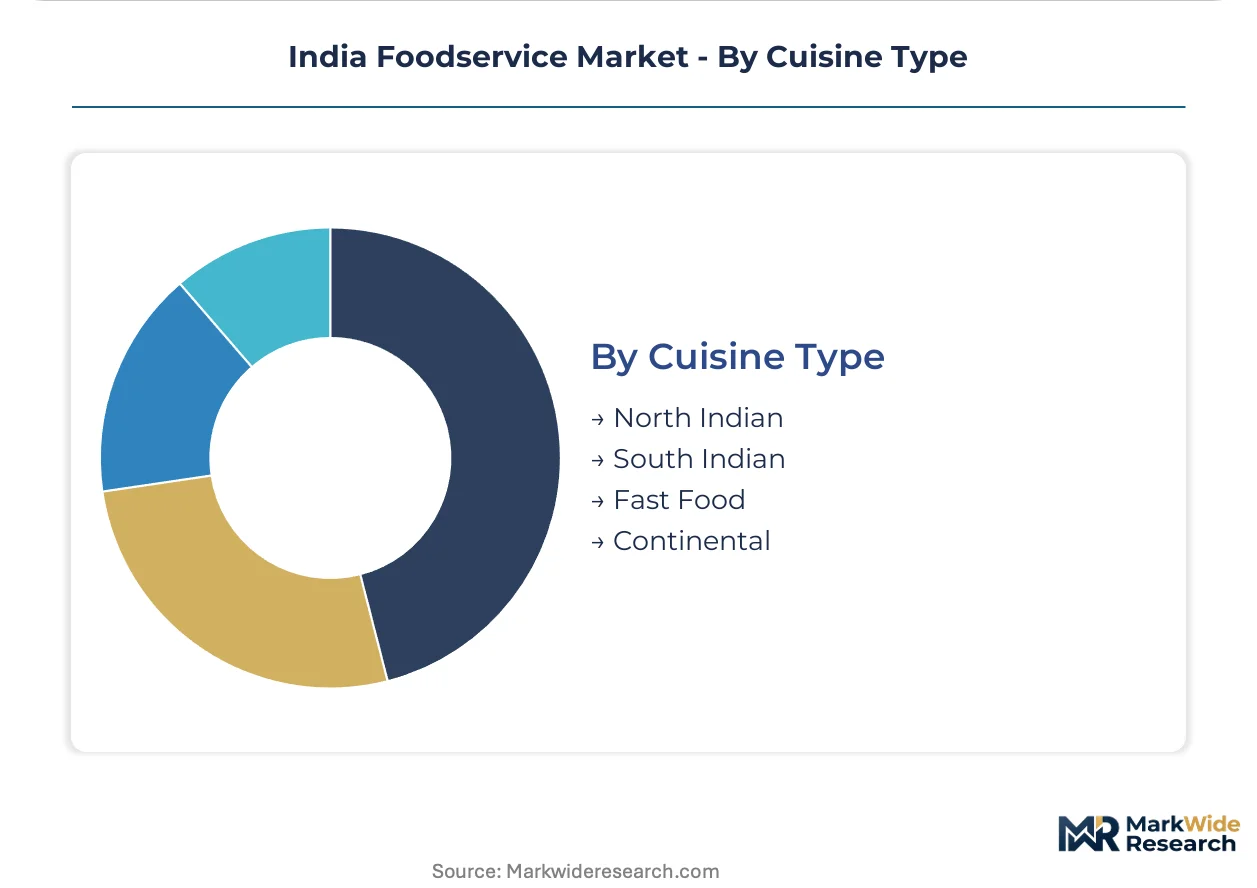
Cuisine Type:
Ingredient sourcing geography and cold-chain requirements shape regional competitive positioning.
- North Indian:Wheat-based breads and dairy-heavy gravies require reliable cold-chain for cream and paneer distribution. Delhi NCR and Punjab anchor demand; tandoor installation costs favor established operators.
- South Indian:Rice and lentil-based formats with lower protein dependency reduce spoilage risk in unreliable refrigeration zones. Karnataka and Tamil Nadu filter coffee culture sustains morning traffic patterns; Udupi restaurant networks demonstrate format portability.
- Fast Food:Standardized global formats with frozen supply chains bypass local mandi volatility. Jubilant FoodWorks dominates pizza and burger segments through dedicated cold-chain partnerships.
- Continental:Imported ingredient dependency and chef skill requirements limit penetration outside premium metro clusters. Mumbai and Bangalore five-star hotel spillover demand supports standalone European format experimentation.
North Indian captures the widest geographic penetration; South Indian formats demonstrate the strongest format portability into tier-two cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat procurement networks from Punjab and Haryana anchor North Indian supply chains, while coconut and spice corridors from Kerala and Karnataka sustain Southern formats. Metro density in Mumbai, Bangalore, and Delhi NCR concentrates premium format investment, with FSSAI digitization mandates reshaping compliance infrastructure across state boundaries.
Maharashtra
Mumbai's corporate lunch culture and Pune's manufacturing belt drive Quick Service transaction density. FSSAI mandates biometric attendance logging for food business operators in municipal corporations. Thane and Navi Mumbai cloud-kitchen clusters absorb spillover demand from saturated South Mumbai real estate.
Karnataka
Bangalore's IT corridor sustains subscription meal contracts and premium coffee formats with predictable daily volume. BIS standards for food-grade packaging materials elevate compliance costs for mid-scale operators. Whitefield and Electronic City host dense cloud-kitchen infrastructure serving corporate campuses.
Delhi NCR
High disposable income concentration supports full-service experimentation in Gurgaon mall developments and experiential dining in Khan Market. DGFT import regulations shape specialty ingredient access for premium Continental formats. Noida sector 62 and Cyber Hub anchor corporate catering procurement.
Tamil Nadu
Filter coffee culture and Udupi restaurant networks demonstrate format portability into tier-two cities like Coimbatore and Madurai. State education board mandates FSSAI licensing at facility level for institutional feeding contracts. Chennai's OMR IT corridor drives cafeteria contract demand with biometric payment integration.
Gujarat
Surat and Ahmedabad textile industry clusters sustain institutional catering contracts with severe peak seasonality around festival calendars. PLI scheme incentives for food processing infrastructure expand domestic frozen dough supply. GIFT City development attracts premium format experimentation for corporate expatriate demand.
India Foodservice Market Competitive Landscape
Format diversification dominates the current landscape as operators fragment across Quick Service, cloud-kitchen, and full-service archetypes. The market exhibits tiered consolidation: multinational chains with dedicated cold-chain partnerships occupy premium metro positioning, domestic cloud-kitchen platforms leverage data-driven site selection for asset-light expansion, and regional thali networks retain penetration in South Indian catchments. Strategic moves concentrate on aggregator platform partnerships and backward integration into sauce and dough production.
Among multinational operators, McDonald's Corporation and Yum! Brands Inc exemplify scale-driven Quick Service archetypes with standardized supply chains. Tata Starbucks Pvt Ltd occupies premium positioning through imported bean sourcing and in-house roasting protocols. Jubilant FoodWorks Limited anchors North and West India distribution through dedicated cold-chain infrastructure. Rebel Foods represents the cloud-native model, deploying multi-brand kitchen infrastructure with machine learning demand forecasting.
| Leading Market Players |
|---|
| Tata Starbucks Pvt Ltd |
| Rebel Foods |
| Jubilant FoodWorks Limited |
| Doctor's Associates Inc (Subway) |
| Wow! Momo Foods Pvt Ltd |
| Yum! Brands Inc |
| Coffee Day Enterprises Ltd |
| Hotel Saravana Bhavan |
| McDonald's Corporation |
| Others |
Supply & Pricing Matrix
Edible oil and wheat flour procurement from Punjab and Haryana mandi networks cascades through three distinct pricing tiers: premium full-service formats in Delhi NCR absorb import-dependent specialty ingredients, mid-market QSR chains negotiate annual contracts for frozen dough bases, and street vendors face spot-market volatility that compresses margins below sustainable thresholds.
Pricing Analysis
Service bundling separates organized chains from unorganized competitors, with FSSAI compliance infrastructure and cold-chain guarantees included in premium tier pricing while basic counter-service strips out temperature-logging and audit documentation to hit lower price points. Three-tier pricing structure across premium, standard, and economy levels reflects brand positioning, geographic real estate costs, and volume scale. Pricing pressure stems from input cost compression in edible oils and wheat flour where ticket sizes resist pass-through elasticity. Corporate subscription clients demonstrate lowest price sensitivity due to procurement convenience consolidation, while individual aggregator users exhibit highest sensitivity to delivery fee increments.
Supply Chain Analysis
Last-mile refrigeration deficits outside tier-one cities elevate logistics costs for protein-heavy formats, forcing menu engineering toward grain and lentil-based alternatives in tier-two expansion. Wheat and dairy inputs draw from Punjab, Haryana, and Uttar Pradesh agricultural belts, while spice and coconut corridors anchor in Kerala and Karnataka. Single-source vulnerability concentrates in imported specialty ingredients for Continental formats subject to DGFT regulation. Distribution runs through dedicated cold-chain partnerships for organized chains and fragmented mandi networks for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's foodservice sector is transitioning from location-dependent dine-in formats toward data-native cloud-kitchen infrastructure, with AI-powered demand forecasting displacing legacy intuition-based site selection and inventory management.
For Market Incumbents: Anticipate margin compression from aggregator commission structures and input cost volatility by securing backward integration into sauce and dough production through PLI scheme incentives. Deploy dedicated quality teams to preempt FSSAI inspection failures as state-level enforcement digitization accelerates. Prioritize captive supply of frozen bases to reduce mandi dependency. For New Entrants and Emerging Players: Capture underdeveloped foodservice density in Indore, Lucknow, and Kochi before organized competition saturates local catchments. Target corporate subscription contracts in Bangalore and Hyderabad IT corridors where procurement teams negotiate bulk meal programs. Lead with cloud-kitchen infrastructure to bypass prime real estate capex entirely. For Investors and Strategic Acquirers: FSSAI licensing mandate acceleration is the leading indicator that formalization tailwinds will consolidate market share toward organized chains with compliance infrastructure. Position for five-to-ten year horizon by acquiring multi-brand kitchen platforms with machine learning demand forecasting capabilities. Monitor municipal health digitization pace across tier-two cities as inflection signal for geographic expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Infrastructure Expansion | Data-driven site selection by Rebel Foods and peers optimizes real estate and labor allocation across micro-markets. |
| Backward Integration into Food Processing | PLI scheme incentives enable domestic frozen dough production, reducing import dependency for standardized inputs. |
| FSSAI Compliance Digitization Investment | Biometric attendance and temperature-logging infrastructure preempts state-level enforcement variations. |
| Corporate Subscription Program Launch | Bulk contracts with IT corridor clients lock in predictable demand pools and compress customer acquisition costs. |
| Tier-Two City Geographic Expansion | First-mover positioning in Indore and Lucknow captures underdeveloped catchments before saturation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving cloud-kitchen operations directors, FSSAI compliance officers, restaurant procurement managers, and aggregator platform strategy leads. FSSAI licensing databases, state-level municipal health digitization records, UPI transaction flow reports, and PLI scheme disclosure filings provided quantitative foundations. Bottom-up outlet-level capacity modeling and top-down consumption expenditure triangulation validated volume estimates.
Granularity-level modeling disaggregated the analysis window by service format, customer type, distribution channel, and cuisine type, with city-tier and state-level regulatory clusters as cross-cutting dimensions. CAGRs derived from segment-specific growth trajectory analysis incorporating cold-chain infrastructure rollout pace, aggregator penetration curves, and corporate procurement contract velocity. Forecast inputs included FSSAI digitization mandate implementation timelines and PLI scheme incentive uptake rates.
The model holds under continued UPI penetration and FSSAI formalization enforcement; deviation in power reliability for cold-chain infrastructure or GST slab rationalization outcomes would shift growth trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Hyperlocal Grocery Delivery Market
Food Service
Tabletop Pizza Oven Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Food Trucks Market
Food Service
Vietnam Online Food Delivery Market
Food Service
China Online Food Delivery Market
Food Service
Benelux Foodservice Market
Food Service
Switzerland Food Service Market
Food Service
Food Contract Manufacturing Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Quick-Service Restaurants Market
Food Service
Steam Stew Pot Market
Food Service
India Online Grocery Market
Food Service
Commercial Steam Table Market
Food Service
South Africa Fast Food Market
Food Service
Healthy Takeout Market