
 China Online Food Delivery Market | 2026-2036
China Online Food Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
China Online Food Delivery Market Intelligence
China's dual carbon goals is decoupling last-mile logistics from fossil fuel dependence, forcing platforms to electrify rider fleets and redesign packaging standards. Meituan leverages its proprietary dispatch algorithms to sustain delivery density across tier-one urban grids. Ele.me anchors merchant retention through integrated supply chain financing tools. JD.com competes on cold-chain infrastructure for premium grocery-meal convergence.
China online food delivery encompasses digital platforms that aggregate restaurant inventory, process mobile payments, and coordinate real-time courier dispatch through GPS-tracked rider networks with average fulfillment windows of 30-45 minutes. The system serves consumer convenience, corporate meal programs, and cloud kitchen distribution. On-demand delivery dominates transaction volume but subscription models capture higher lifetime value through prepaid meal plans. Healthy meals represent the fastest-growing food type as workplace wellness programs expand. Millennials drive frequency, though families generate larger order sizes during weekend clustering periods.
SAMR enforces antitrust and algorithm transparency rules that constrain platform commission rates and data usage. MEE packaging waste standards mandate biodegradable materials and deposit-return schemes for single-use containers. BIS food safety certifications govern cloud kitchen hygiene ratings displayed on platform interfaces. Stakeholders must track how carbon accounting requirements will reshape rider employment models and packaging cost structures.
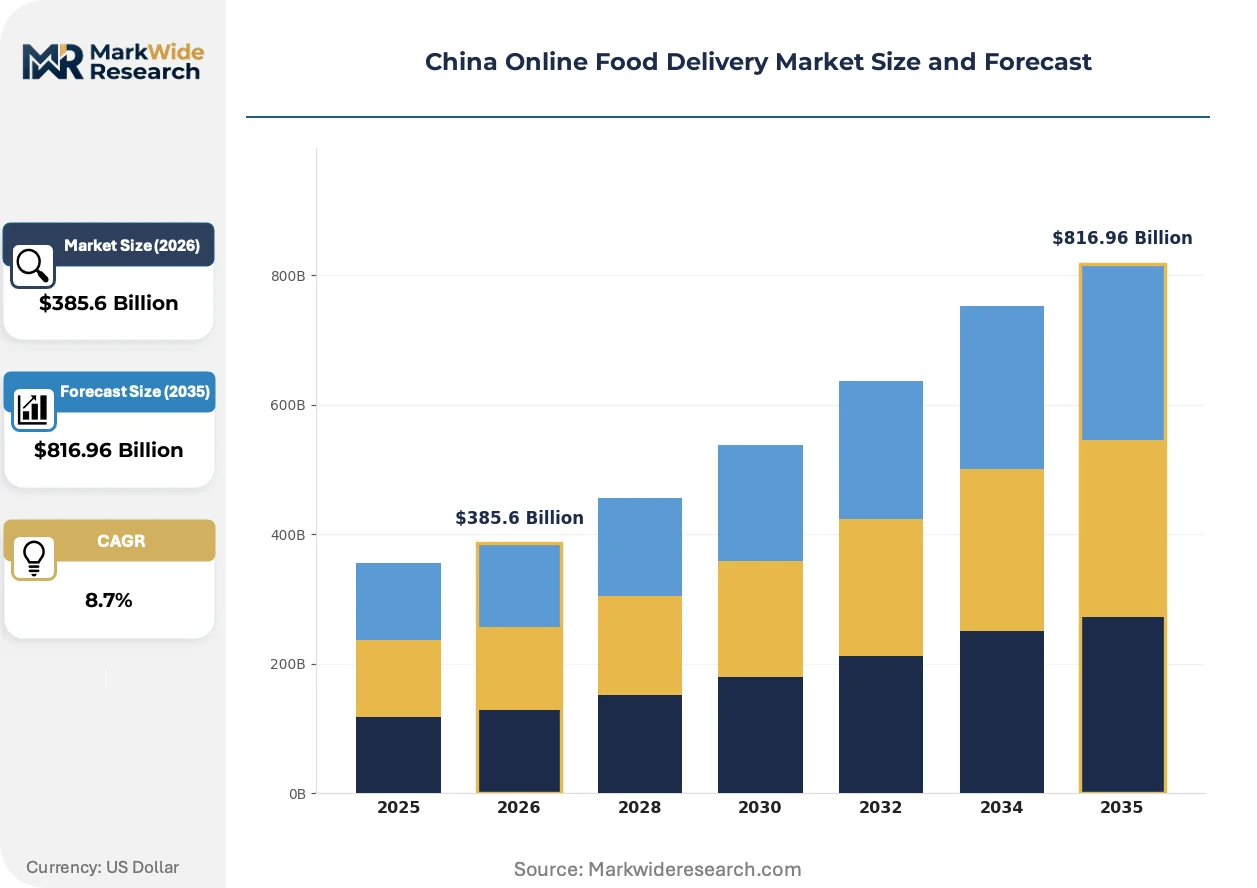
Market Dynamics
SAMR's algorithm governance framework is compressing platform commission flexibility while forcing transparent dispatch systems across China's tier-one urban corridors. This regulatory pressure is redistributing margin pools between aggregators and merchant networks.
Growth Catalysts
- Dual carbon mandates:MEE packaging waste standards and fleet electrification targets are accelerating biodegradable container adoption and electric two-wheeler deployment across Yangtze River Delta logistics networks.
- Corporate catering procurement:Centralized meal programs in Shanghai's central business district corridors are deepening platform engagement through volume contracts and integrated expense management systems.
- Cloud kitchen infrastructure:Dedicated delivery-only facilities in manufacturing zones are expanding addressable restaurant inventory without traditional real estate constraints.
Market Restraints
- Rider cost volatility:Labor platform regulations and social insurance mandates are structurally elevating per-delivery fulfillment costs beyond algorithmic efficiency gains.
- Packaging input concentration:Biodegradable material supply chains cluster in Zhejiang and Jiangsu provinces, creating geographic vulnerability to regional production disruptions.
- Commission rate ceilings:SAMR antitrust enforcement caps platform take rates, constraining revenue model flexibility for merchant acquisition spending.
Strategic Opportunities
- Tier-two city penetration:Chengdu, Hangzhou, and Nanjing exhibit underpenetrated corporate catering density relative to their commercial office stock and manufacturing employment bases.
- Cold-chain grocery convergence:Temperature-controlled logistics infrastructure originally built for fresh food is enabling premium prepared meal categories with extended shelf stability.
- Subscription prepaid models:Workplace wellness program integrations are creating locked-in demand pools with higher lifetime value than transactional on-demand ordering.
Industry Challenges
- Algorithm audit compliance:SAMR transparency mandates require explainable dispatch systems that expose proprietary routing logic to regulatory review and competitive reverse-engineering.
- Cross-platform data portability:Merchant migration between aggregators faces friction from locked historical performance data and re-certification requirements under BIS food safety protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Online Food Delivery Market |
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $816.96 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: On-Demand, Scheduled, Subscription, Instant Food Type: Fast Food, Healthy Meals, Vegetarian, Desserts Customer Segment: Millennials, Families, Professionals, Students Order Size: Single Meal, Small Group, Large Group, Catering |
| Companies Covered | Meituan, Ele.me, JD.com, ENJOY, Daojia, Home-cook, Koubei, FoodPanda, Seamless, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Online Food Delivery Market Strategic Shifts & Innovations
Digitization of meal procurement is converging with carbon accounting mandates to reshape how platforms design rider employment, packaging specifications, and merchant onboarding workflows across Chinese urban corridors.
AI-powered demand forecasting systems are rewriting dispatch density optimization. These predictive engines ingest weather patterns, local event calendars, and corporate office occupancy signals to pre-position rider supply. Cloud kitchen operators in Shenzhen and Guangzhou are adopting these tools most aggressively. The technology is rewriting traditional peak-hour surge pricing into preemptive capacity allocation models.
MEE packaging waste standards mandate deposit-return schemes and biodegradable material certifications for single-use containers. The industrial consequence is a forced supplier base consolidation toward certified packaging manufacturers with verified carbon footprints. Premium healthy meal categories face the steepest compliance cost increases as they rely heavily on multi-component packaging for temperature separation.
Corporate procurement departments are consolidating meal program vendors through centralized platform contracts that displace individual employee reimbursement models. Human resources functions in Beijing and Shanghai financial districts are driving this consolidation to capture volume discounts and simplify tax documentation. The shift is most visible in technology and professional services sectors with distributed workforces requiring flexible meal timing.
China Online Food Delivery Market Segmentation
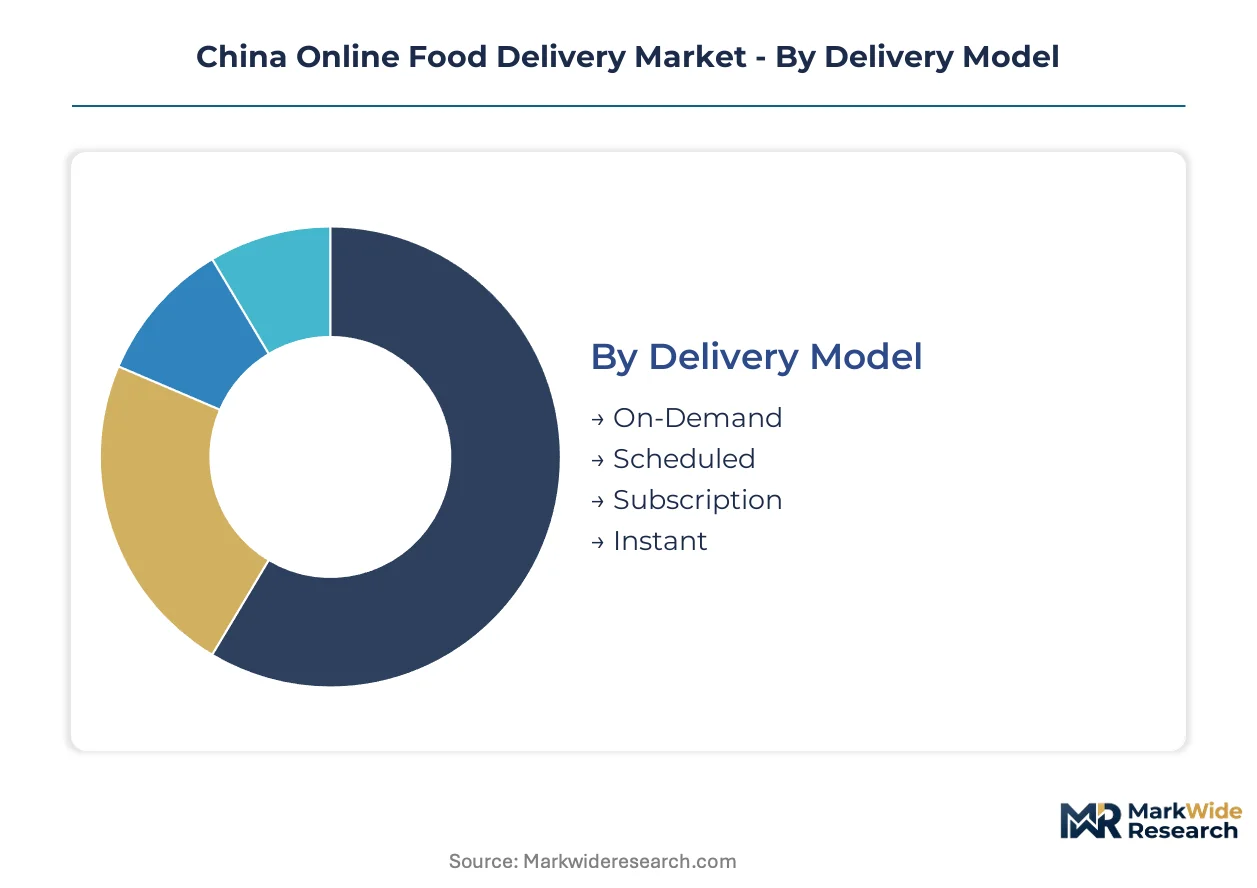
Platform monetization strategies diverge sharply across delivery models and customer cohorts in China's urban corridors. Segmentation reveals where algorithmic efficiency gains translate to margin expansion versus where rider cost inflation erodes unit economics.
Delivery Model:
Dispatch technology sophistication separates platforms competing on density optimization from those building subscription lock-in.
- On-Demand:Real-time GPS-coordinated rider networks fulfill 30-45 minute windows through proprietary algorithms. Shanghai's central business district corridors generate the highest order density, though SAMR transparency mandates now expose routing logic to regulatory audit.
- Subscription:Prepaid meal plans capture higher lifetime value through workplace wellness program integrations. Corporate procurement departments in Beijing financial districts are consolidating vendor contracts around this model to simplify expense documentation.
- Scheduled:Advance-order systems reduce peak-hour surge pricing exposure for price-sensitive users.
- Instant:Sub-15-minute fulfillment through pre-positioned cloud kitchen inventory targets convenience-maximizing professionals.
Mature deployment sits with On-Demand. Newer deployment is concentrated in Subscription.
Food Type:
Packaging compliance costs and temperature control requirements reshape profitability across menu categories.
- Healthy Meals:Multi-component packaging for temperature separation faces steepest MEE biodegradable material cost increases. Workplace wellness programs in Yangtze River Delta manufacturing zones are accelerating corporate procurement of this category.
- Fast Food:Standardized preparation enables cloud kitchen replication without traditional real estate constraints. Tier-two cities including Chengdu and Nanjing exhibit underpenetrated addressable inventory relative to commercial office stock.
- Vegetarian:Plant-based protein supply chains cluster in Zhejiang province packaging manufacturing zones.
- Desserts:Cold-chain infrastructure investments by JD.com and Ele.me enable premium confectionery delivery with extended shelf stability.
Fast Food commands current volume leadership. Healthy Meals are climbing the fastest as corporate catering procurement expands.
Customer Segment:
Frequency patterns and order size distributions determine platform marketing spend allocation across demographic cohorts.
- Millennials:Mobile-native ordering behavior drives highest per-capita transaction frequency. Weekend clustering periods generate larger basket sizes than weekday individual meal purchases.
- Families:Multi-person meal coordination produces the largest average order values, particularly during Saturday-Sunday concentrated ordering windows.
- Professionals:Corporate expense account integration enables premium category penetration in Shanghai and Beijing central business districts.
- Students:Price sensitivity concentrates demand in promotional periods and subsidized campus delivery programs.
Millennials anchor platform daily active user metrics. Families deliver the steepest revenue-per-order expansion trajectory.
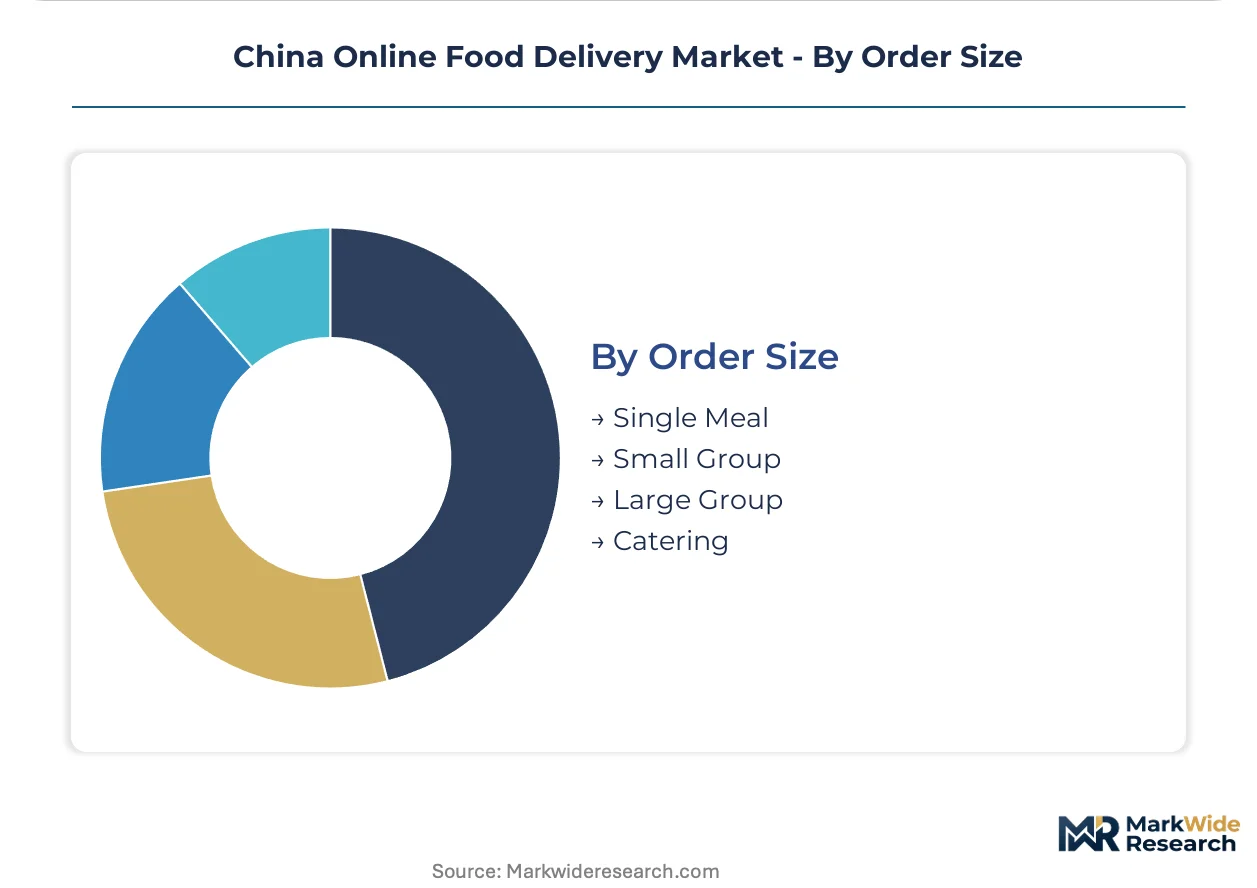
Order Size:
Fulfillment cost structures and rider utilization rates vary nonlinearly with order complexity and destination clustering.
- Single Meal:Individual portion delivery generates baseline unit economics where algorithmic batching determines profitability. SAMR commission rate ceilings constrain platform take rates on this high-frequency, low-margin segment.
- Catering:Centralized corporate meal programs in Shanghai financial districts enable volume discounts and integrated expense management systems that displace individual reimbursement models.
- Small Group:Two-to-four person orders balance basket size with manageable destination dispersion.
- Large Group:Multi-point office delivery requires specialized logistics coordination and extended fulfillment windows.
Single Meal dominates transaction count. Catering is gaining share fastest as human resources functions consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's central business district corridors anchor China's online food delivery density, with corporate catering procurement and cloud kitchen infrastructure concentrating in Yangtze River Delta manufacturing zones.
Beijing-Tianjin-Hebei
Financial district professionals and technology sector campuses drive subscription prepaid model adoption. SAMR algorithm governance rules enforce transparent dispatch systems across the capital's urban grid. Cloud kitchen clusters in Zhongguancun and Chaoyang District expand delivery-only restaurant inventory.
Yangtze River Delta
Shanghai's manufacturing employment bases and Hangzhou's e-commerce workforce generate concentrated meal program demand. MEE packaging waste standards mandate biodegradable container certifications throughout Jiangsu and Zhejiang provinces. Cold-chain logistics infrastructure in Suzhou and Ningbo enables premium grocery-meal convergence.
Pearl River Delta
Shenzhen and Guangzhou technology campuses accelerate AI-powered demand forecasting deployment. Dual carbon mandates force fleet electrification across Guangdong's logistics networks. Cloud kitchen operators in Dongguan manufacturing zones adopt predictive dispatch engines most aggressively.
Sichuan-Chongqing
Chengdu's underpenetrated corporate catering density relative to commercial office stock presents expansion opportunity. SAMR commission rate ceilings constrain platform take rates in this emerging tier-two market. Local merchant networks cluster around Jingjiang and Tianfu New Area business districts.
China Online Food Delivery Market Key Industry Players
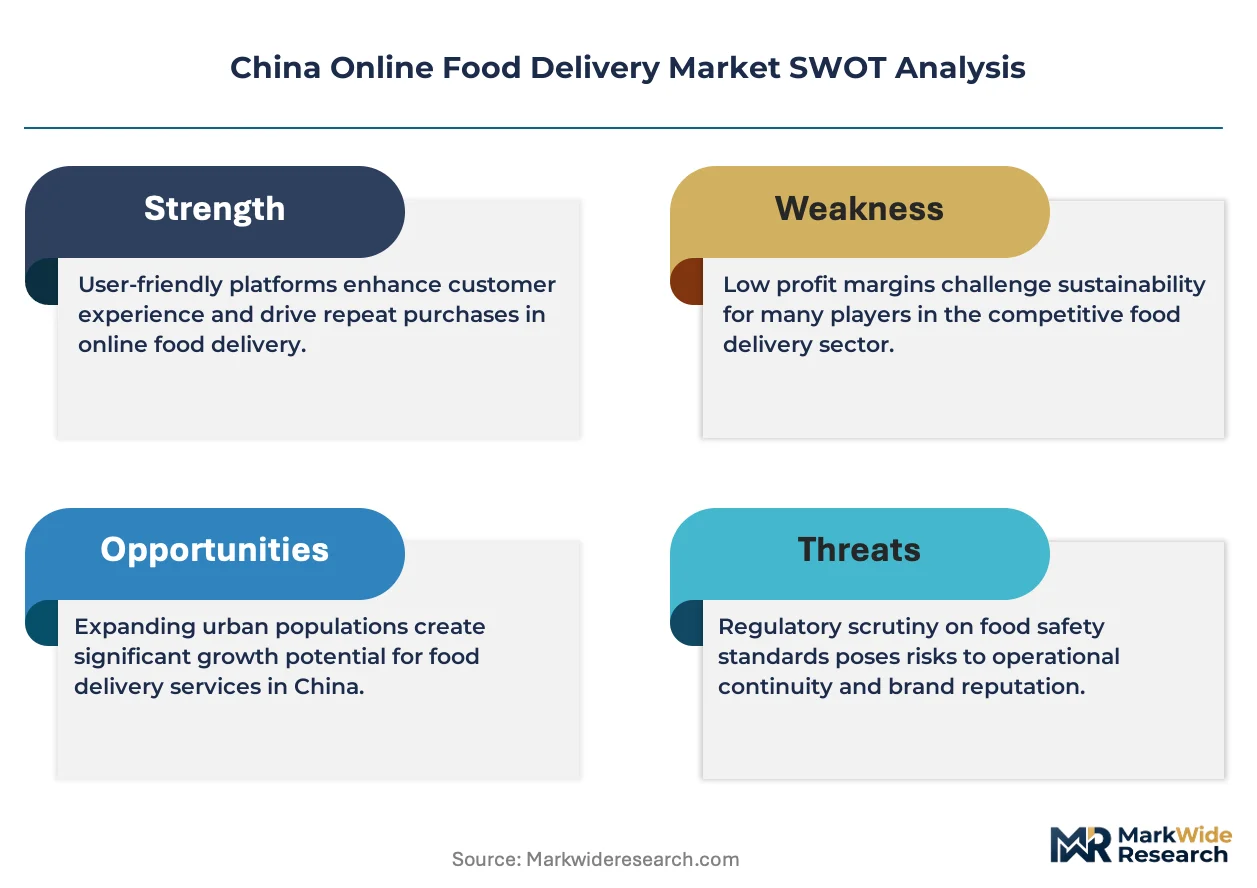
Premium-margin players sit above commodity-margin players across algorithm sophistication and cold-chain infrastructure depth. Three platform archetypes dominate: dispatch-optimized aggregators, supply-chain-integrated merchants, and subscription-focused workplace vendors. Consolidation pressure intensifies as SAMR antitrust enforcement caps revenue model flexibility. Dominant competitive moves include proprietary algorithm licensing and backward integration into cloud kitchen real estate.
Within the integrated-aggregator tier, Meituan and Ele.me occupy positions shaped by dispatch technology and merchant financing capabilities respectively. JD.com represents the infrastructure-heavy archetype, leveraging cold-chain investments originally built for fresh food logistics. These three platforms exemplify how regulatory pressure on commission structures is forcing differentiation through operational capability rather than pricing power.
| Leading Market Players |
|---|
| Meituan |
| Ele.me |
| JD.com |
| ENJOY |
| Daojia |
| Home-cook |
| Koubei |
| FoodPanda |
| Seamless |
| Others |
Cost & Logistics Intelligence
Backward integration into cloud kitchen real estate anchors supply position for platforms seeking pricing power against SAMR commission ceilings. This vertical control over delivery-only inventory buffers margin compression from algorithm transparency mandates and rider cost inflation.
Pricing Analysis
Throughput-based pricing anchors platform revenue models, with subscription prepaid plans capturing higher lifetime value than transactional on-demand orders. Price differentiation hinges on delivery speed tier and corporate volume scale, with instant sub-15-minute fulfillment commanding premium positioning. Cost compression in single-meal segments is intensifying because SAMR antitrust enforcement caps platform take rates. Students exhibit highest price sensitivity, while professionals with corporate expense account integration show lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates under MEE packaging waste standards are reshaping sourcing toward certified biodegradable manufacturers in Zhejiang and Jiangsu provinces. Raw material supply draws from polylactic acid producers, electric two-wheeler battery cell manufacturers, and GPS tracking hardware assemblers. Single-source vulnerability concentrates in biodegradable container supply chains clustered in eastern coastal manufacturing zones. Distribution runs through platform-controlled rider networks with algorithmic batching optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMR algorithm governance rules have transformed this market into a cost-of-compliance story, where MEE packaging certifications and transparent dispatch systems erect barrier-to-entry moats for compliant incumbents.
For Market Incumbents: Lock in merchant retention through integrated supply chain financing tools and proprietary cloud kitchen real estate in tier-one urban corridors. Defend against Ele.me's financing-led merchant capture by deepening algorithmic density optimization in Shanghai's central business district corridors. Prioritize certification investment in MEE-compliant packaging workflows to outrun regulatory cost escalation. For New Entrants and Emerging Players: The mid-tier price-point gap between premium healthy meal subscriptions and economy fast food orders presents white-space opportunity. Target underpenetrated corporate catering density in Chengdu and Nanjing commercial office districts. Pursue workplace wellness program integrations as the go-to-market angle for locked-in demand pools. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure-heavy platform archetypes with cold-chain logistics depth. Long-term viability favors players with backward integration into cloud kitchen real estate and proprietary dispatch technology. Monitor SAMR enforcement intensity on commission rate ceilings as the inflection indicator for margin model sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Real Estate Acquisition | Captive supply of delivery-only inventory buffers SAMR commission pressure in tier-one corridors. |
| Proprietary Dispatch Algorithm Licensing | Technology monetization offsets margin compression from transparent routing mandates. |
| Workplace Wellness Program Integration | Subscription lock-in with Beijing and Shanghai financial district HR functions stabilizes revenue. |
| Biodegradable Packaging Certification | MEE compliance creates supplier consolidation opportunity toward certified manufacturers. |
| Electric Fleet Deployment Partnership | Dual carbon mandate alignment secures regulatory goodwill and operational cost structure. |
Research Approach
Platform financial disclosures, SAMR regulatory filings, and MEE environmental compliance databases formed the secondary backbone. Primary interviews with food delivery platform operations executives, restaurant merchant network managers, corporate procurement officers, and logistics fleet coordinators validated demand and cost assumptions. Bottom-up and top-down triangulation reconciled order volume estimates with platform revenue disclosures.
Bottom-up modeling aggregated segment-level transaction frequencies and average order values across delivery models and food types. Top-down validation cross-checked aggregate market value against platform-reported gross merchandise volume. Segmentation dimensions included delivery model sophistication, food type packaging requirements, customer cohort ordering patterns, and order size fulfillment complexity. CAGRs were derived from trend extrapolation of corporate catering procurement growth and cloud kitchen inventory expansion.
Underlying measurement precision varies by segment; on-demand transaction volumes carry tighter precision than emerging subscription prepaid models. Forecasts reflect assumptions about SAMR enforcement trajectory and MEE packaging cost pass-through rates. Rider labor regulation evolution and biodegradable material supply stability present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Sandwich Toasters Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
Bangladesh Food Service Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Indonesia Foodservice Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Self-Heating Hot Pot Market
Food Service
Electric Tiffin Market
Food Service
United States Full Service Restaurants Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Global Food Retail Market
Food Service
Integrated Stove Market
Food Service
Virtual Kitchen Market
Food Service
A La Carte Market
Food Service
US Healthcare/Hospital Food Services Market