
 Vietnam Energy Drinks Market | 2026-2036
Vietnam Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Energy Drinks Market Insights
Young urban labor pool rotation toward gig economy and factory shift work is expanding consumption occasions beyond traditional student demographics. Red Bull leverages its heritage positioning and motorsport sponsorships to sustain premium pricing in tier-one cities. Tan Hiep Phat anchors domestic production scale through its Number 1 and Warrior brands, controlling distribution depth in provincial markets where foreign labels compete less aggressively.
An energy drink is a non-alcoholic beverage formulated with caffeine, taurine, B-vitamins, and sugar or alternative sweeteners, manufactured through acidification, carbonation, and hot-fill or aseptic processing to achieve shelf stability and stimulant bioavailability. Its primary commercial purpose is to reduce perceived fatigue and enhance mental alertness during extended work, study, or physical exertion periods. Caffeinated variants dominate volume sales due to established consumer familiarity and lower per-unit production costs, while sugar-free formulations capture margin pools from health-conscious professionals navigating Vietnam's evolving diabetes prevention discourse. Distribution through convenience stores leads transaction frequency, though online retailers represent the fastest-growing channel as same-day delivery platforms expand refrigerated logistics coverage.
Vietnam's Ministry of Health and the Vietnam Food Administration enforce caffeine content ceilings and mandatory warning labels under national food safety regulations, directly constraining formulation flexibility and packaging design choices for both domestic and imported brands. BIS-aligned quality certifications and evolving ASEAN harmonization standards further shape market access requirements for regional suppliers. Stakeholders must monitor enforcement consistency between Ho Chi Minh City and northern industrial zones, where provincial interpretation of additive rules creates compliance fragmentation that favors established players with dedicated regulatory affairs capacity.
Market Dynamics
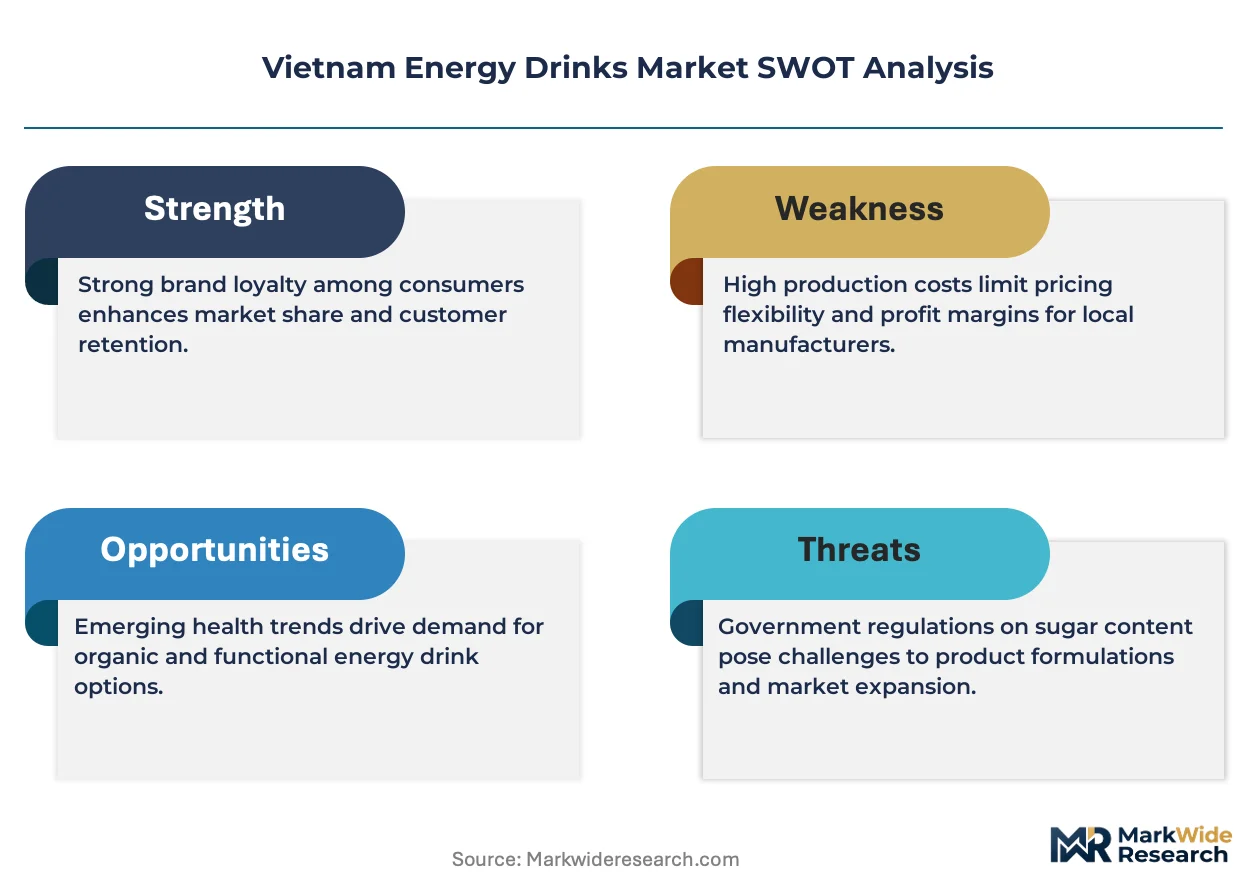
Vietnam's Ministry of Health tightened caffeine labeling requirements under national food safety standards, forcing reformulation across portfolios and reshaping how domestic and foreign brands compete on shelf visibility and consumer trust.
Growth Catalysts
- Fitness culture expansion:Urban gym chains and boutique studios proliferating in Ho Chi Minh City and Hanoi are normalizing pre-workout consumption occasions beyond traditional student demographics.
- Circular 27/2012/TT-BYT amendments:The Ministry of Health's updated caffeine content ceilings and mandatory warning labels are accelerating compliance investments that favor established players with dedicated regulatory affairs capacity.
- Gig economy labor rotation:Factory shift workers and delivery platform drivers in industrial zones are creating new consumption moments during non-traditional hours.
Market Restraints
- Input cost volatility:Caffeine anhydrous and taurine prices fluctuate with global pharmaceutical-grade chemical markets, squeezing margin pools for mid-tier brands.
- Supply concentration risk:Aseptic hot-fill processing capacity clusters in southern Vietnam, creating logistics bottlenecks for northern provincial distribution.
- Regulatory friction:Provincial interpretation variance between Ho Chi Minh City and northern industrial zones fragments compliance costs and enforcement consistency.
Strategic Opportunities
- Provincial market underpenetration:Secondary cities like Da Nang, Can Tho, and Hai Phong exhibit modern trade penetration gaps where local distributors command channel relationships foreign labels cannot replicate.
- Sugar-free formulation white space:Vietnam's evolving diabetes prevention discourse creates margin pools for health-conscious professionals seeking alternatives to sucrose-dominant portfolios.
- Same-day delivery platform expansion:Refrigerated logistics coverage by e-commerce operators is opening direct-to-consumer channels previously blocked by ambient-temperature distribution constraints.
Industry Challenges
- Regulatory affairs talent scarcity:BIS-aligned quality certification and evolving ASEAN harmonization standards require specialized compliance functions that outpace local university pipeline output.
- Cold chain capex intensity:Sugar-free and functional variants demand refrigerated storage and transport infrastructure that provincial distributors lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Energy Drinks Market |
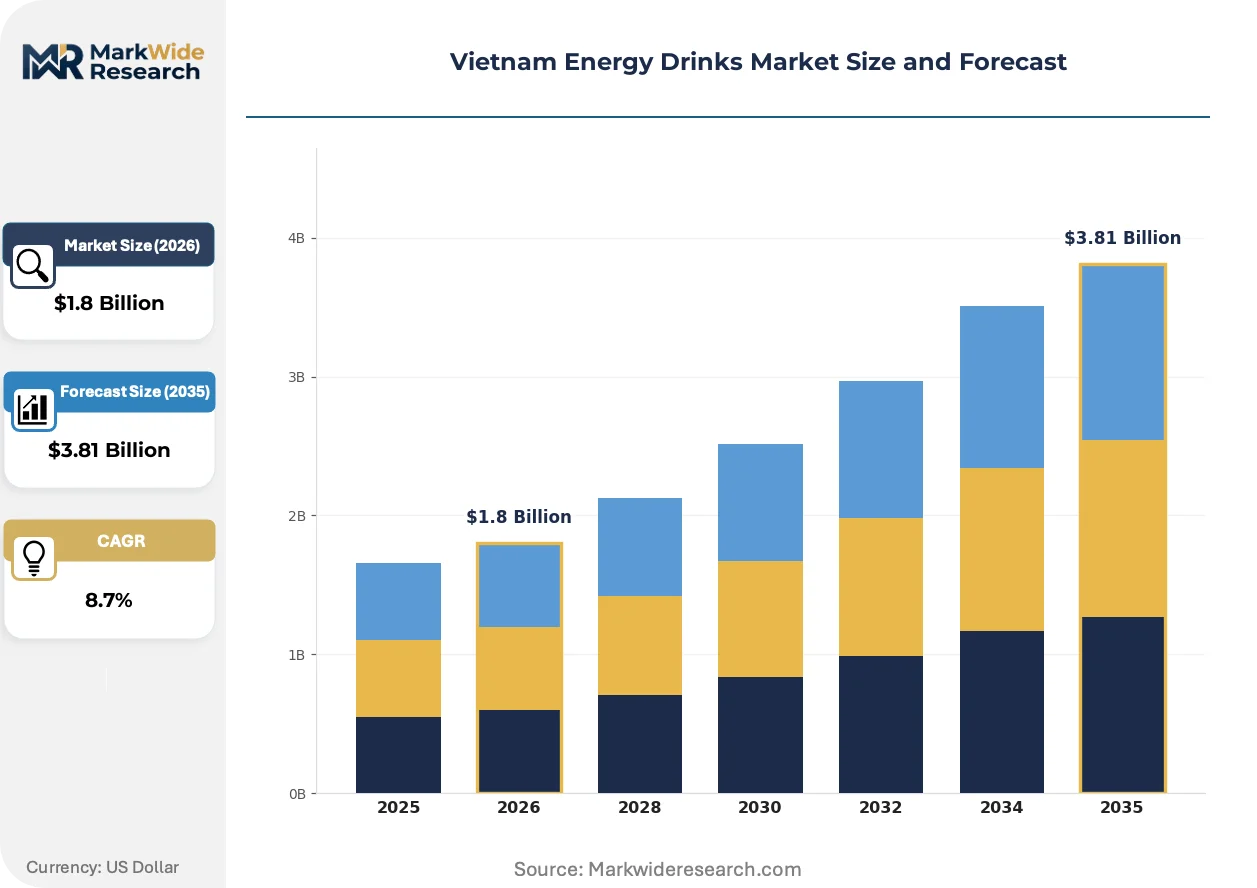
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeinated, Vitamin-Enriched, Herbal, Sugar-Free Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Fitness Centers Customer Type: Young Adults, Athletes, Professionals, Students Packing Type: Cans, Bottles, Pouches, Multi-Packs |
| Companies Covered | Red Bull, Suntory PepsiCo Vietnam, Coca-Cola Beverages Vietnam, Tan Hiep Phat, Sting, Monster Energy, Rockstar, Number 1, Warrior, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Energy Drinks Market Trends and Innovations
Refrigerated logistics networks are compressing delivery windows and enabling format experimentation that ambient distribution previously prohibited, while regulatory tightening forces transparency investments that reshape competitive positioning.
Natural caffeine extraction from green coffee beans is supplanting synthetic anhydrous formulations in premium positioning strategies. Health-conscious professionals in Hanoi and Ho Chi Minh City are driving adoption at double-digit rates within convenience store channels. This ingredient shift is enabling clean-label claims that command shelf price premiums and compress synthetic-dependent competitor margins.
Vietnam's Ministry of Health and Vietnam Food Administration enforcement of caffeine content ceilings is constraining formulation flexibility for both domestic and imported brands. Packaging redesign costs and warning label real estate are diverting marketing budgets toward compliance rather than consumer engagement. Sugar-free variants face stricter scrutiny than traditional formulations, accelerating reformulation timelines for health-positioned portfolios.
Convenience store transaction frequency is plateauing as online retailers capture growth through same-day delivery platforms. Young urban professionals in Ho Chi Minh City are substituting impulse purchases with scheduled subscription models that guarantee refrigerator stock. This channel rotation is most visible among fitness enthusiasts and shift workers who prioritize planning over point-of-sale discovery.
Vietnam Energy Drinks Market Segmentation
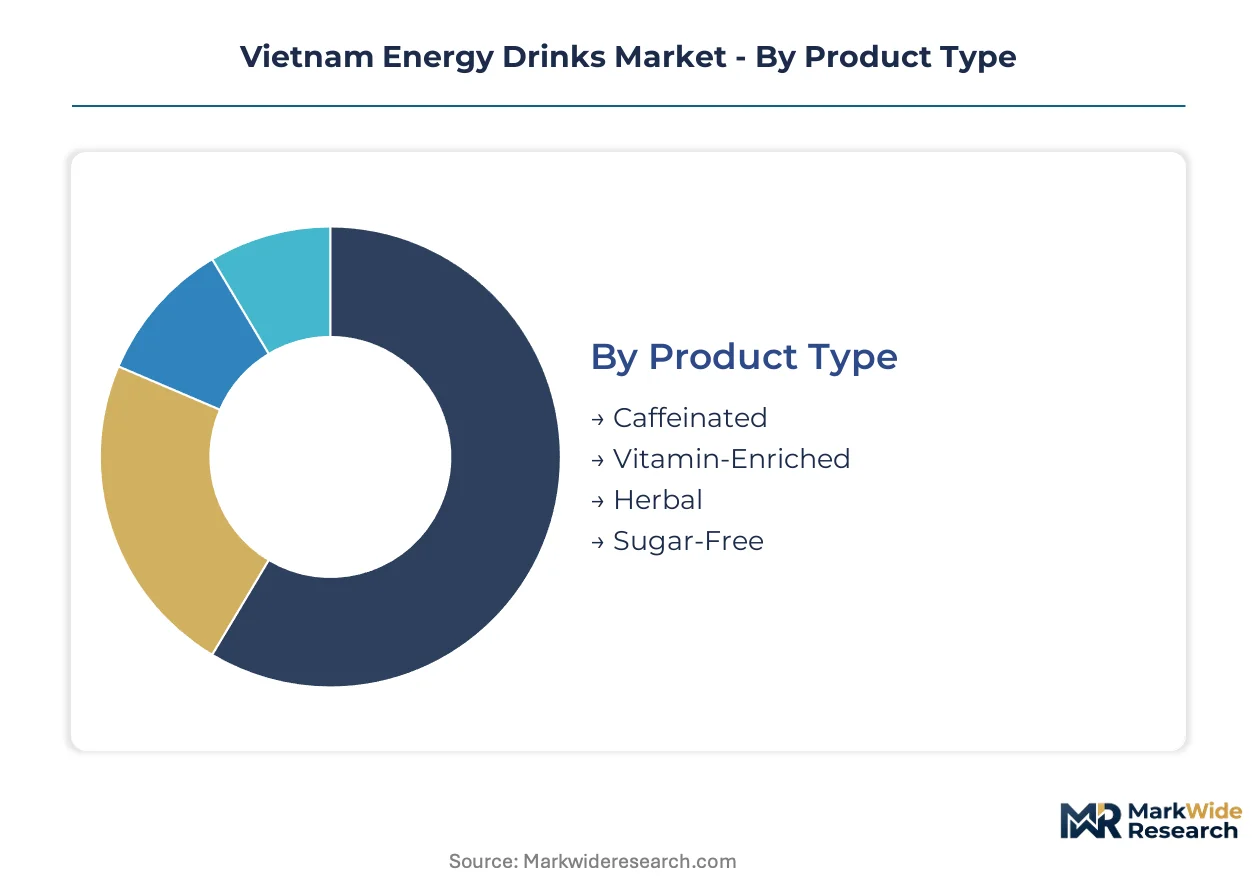
Segmentation reveals how Vietnam's energy drinks market fractures across consumption occasions, purchase contexts, and physiological needs. Each dimension carries distinct margin profiles and regulatory exposure that shape portfolio construction for domestic and multinational suppliers.
Product Type:
Caffeinated variants face intensifying substitution pressure from coffee shop culture and functional teas, forcing reformulation investments to defend habitual consumption.
- Caffeinated:Formulations rely on synthetic caffeine anhydrous or natural green coffee extracts, delivering standardized stimulant dosing for shift workers and drivers. Ho Chi Minh City's factory zones and logistics hubs concentrate demand where alertness during irregular hours commands premium shelf placement.
- Sugar-Free:Aspartame, sucralose, or stevia-sweetened portfolios target Hanoi professionals navigating diabetes prevention campaigns and corporate wellness programs. Refrigerated distribution requirements limit provincial penetration, concentrating volume in modern trade channels with cold chain infrastructure.
- Vitamin-Enriched:B-complex and electrolyte fortification appeals to gym enthusiasts seeking recovery positioning beyond pure stimulation.
- Herbal:Ginseng, guarana, and local botanical extracts attract consumers skeptical of synthetic additives, though caffeine content ceilings complicate efficacy claims.
Caffeinated anchors the volume base while sugar-free gains share at the steepest rate.
Distribution Channel:
Channel cost tiers separate premium-positioned entrants from mass-market domestic brands, with cold chain capex requirements acting as the primary gating mechanism.
- Convenience Stores:24-hour outlets in Ho Chi Minh City and Hanoi generate the highest transaction frequency for impulse purchases. Shelf fees and promotional slotting costs favor established players with trade marketing budgets, while provincial c-store networks remain fragmented among local distributors.
- Online Retailers:Same-day delivery platforms with refrigerated logistics coverage are capturing subscription-based demand from urban professionals. Shopee, Lazada, and TikTok Shop operators now stock temperature-controlled SKUs previously blocked by ambient distribution constraints.
- Supermarkets:Big C, WinMart, and Co.opmart chains drive multi-pack volume through promotional bundling during holiday periods.
- Fitness Centers:Boutique studios and gym chains in District 7 and Tay Ho normalize pre-workout consumption, though on-premise markup limits repeat purchase frequency.
Convenience stores dominate transaction volume while online retailers expand most quickly.
Customer Type:
Application-driven segmentation maps consumption moments to physiological need states, with professional use cases displacing traditional student demographics.
- Young Adults:Urban laborers aged 18-30 in gig economy roles—delivery drivers, warehouse pickers, and ride-hail operators—consume during non-traditional hours. Ho Chi Minh City's industrial zones and Hanoi's logistics corridors concentrate this cohort.
- Professionals:White-collar workers in finance and technology sectors prioritize sugar-free formulations for sustained focus without glycemic spikes. Corporate procurement channels and subscription models are displacing individual convenience store trips.
- Athletes:Competitive and recreational fitness enthusiasts drive pre-workout and intra-training consumption, with gym-based discovery translating to retail trial.
- Students:Examination-period consumption remains seasonal, with price sensitivity pushing volume toward economy-tier domestic brands.
Young adults anchor the volume base while professionals command the highest per-capita spend.
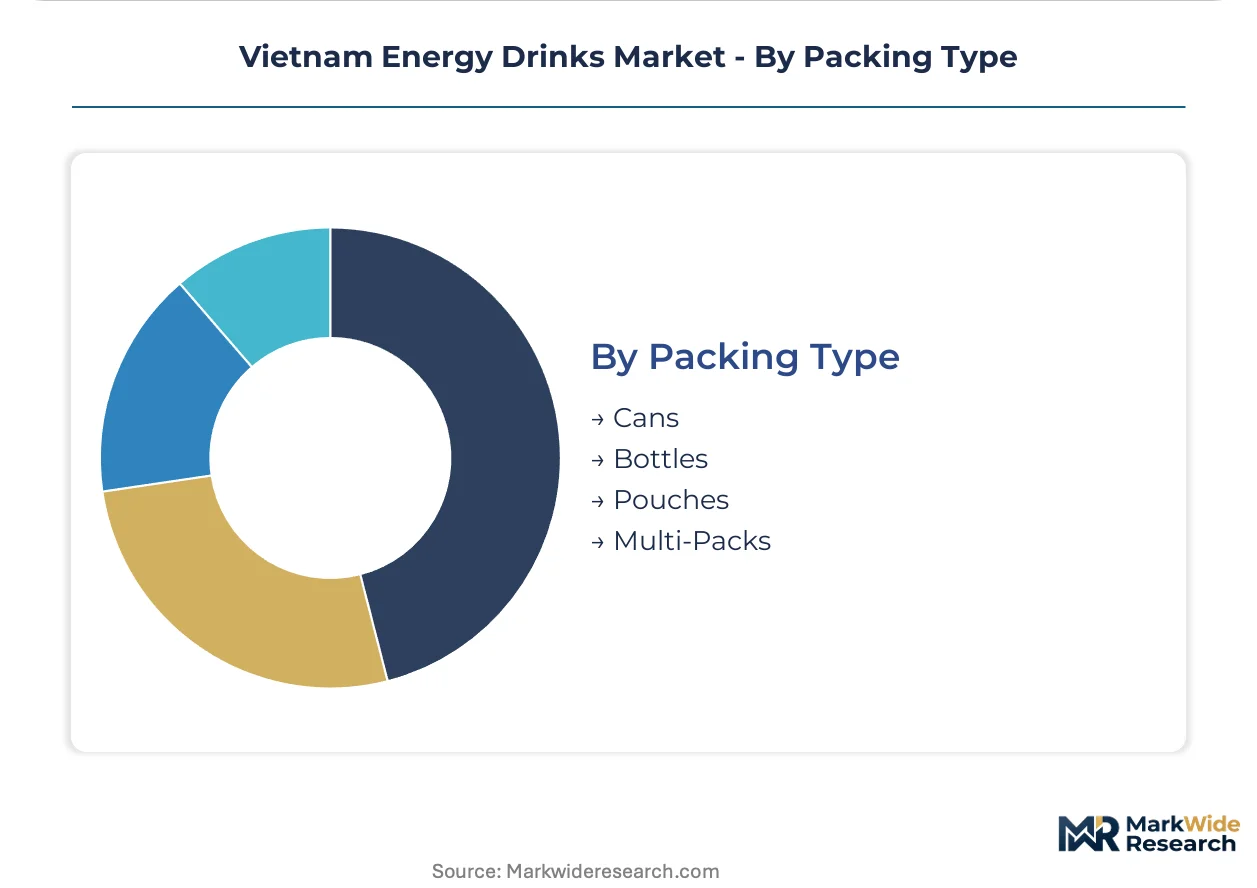
Packing Type:
Supply concentration in southern Vietnam's aseptic processing clusters shapes format availability, with canning lines dominating export-oriented production.
- Cans:Aluminum formats with hot-fill processing dominate export and premium domestic positioning. Southern Vietnam's Binh Duong and Dong Nai provinces concentrate canning capacity, creating logistics advantages for Ho Chi Minh City distribution.
- Bottles:PET and glass formats enable larger single-serve volumes for sharing occasions and extended consumption. Provincial distributors favor bottles for ambient storage flexibility where cold chain infrastructure is absent.
- Pouches:Flexible packaging reduces shipping cube and appeals to price-sensitive trial purchases in rural markets.
- Multi-Packs:Four-packs and six-packs drive pantry-loading behavior during promotional windows, though refrigerator stock constraints limit urban adoption.
Cans anchor the volume base while pouches climb the fastest in secondary city expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Vietnamese provinces diverge sharply between urban centers and industrial corridors, with southern factory zones favoring bulk caffeinated formats while northern metros drive sugar-free premiumization.
Ho Chi Minh City and Surrounding Industrial Provinces
Binh Duong and Dong Nai factory complexes generate concentrated demand among shift workers requiring sustained alertness during irregular hours. Vietnam's Ministry of Health caffeine labeling mandates hit hardest here due to dense distribution networks requiring rapid packaging turnover. Canning capacity clusters in southern provinces create logistics advantages for ambient-format distribution throughout the Mekong Delta corridor.
Hanoi and Northern Red River Delta
Corporate professionals in Cau Giay and Tay Ho districts prioritize sugar-free formulations aligned with workplace wellness programs. The Vietnam Food Administration enforces stricter provincial interpretation of additive rules in northern jurisdictions, elevating compliance costs for new entrants. Cold chain infrastructure gaps in Bac Ninh and Hai Duong industrial zones limit premium variant penetration despite rising disposable incomes.
Da Nang and Central Coast Expansion
Tourism-driven service workers and port logistics operators create hybrid consumption profiles mixing traditional caffeinated formats with emerging functional variants. National food safety standards apply uniformly, yet enforcement consistency lags behind southern benchmarks. Modern trade penetration remains below national averages, preserving opportunities for local distributor partnerships.
Hai Phong and Northern Port Corridor
Seaport logistics hubs and emerging manufacturing zones attract delivery platform drivers seeking convenient stimulant access during extended routes. Provincial regulatory interpretation variance creates compliance fragmentation that favors established players with dedicated regulatory affairs capacity. Refrigerated logistics coverage gaps constrain sugar-free variant availability despite professional demographic growth.
Can Tho and Mekong Delta Secondary Markets
Agricultural processing workers and river transport operators sustain demand for economy-tier caffeinated products in ambient distribution formats. Distribution depth challenges persist as foreign labels compete less aggressively against domestic portfolios with entrenched provincial relationships. Same-day delivery platform expansion is compressing traditional wholesale channel dominance in urban cores.
Vietnam Energy Drinks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates controlling premium shelf placement through trade marketing scale while domestic producers anchor provincial penetration via distributor relationships. The market structure reflects beverage industry consolidation patterns: two global energy drink specialists command tier-one urban positioning, three diversified multinational soft drink portfolios leverage cross-category distribution, and a concentrated domestic producer group defends provincial strongholds through vertical integration into aseptic processing. Dominant competitive moves include portfolio diversification into sugar-free and functional variants, plus strategic partnerships with same-day delivery platforms to bypass traditional cold chain limitations.
Among multinational specialists, Red Bull and Monster Energy exemplify heritage-positioned archetypes sustaining premium pricing through motorsport sponsorships and fitness culture alignment. Within the diversified beverage conglomerate tier, Suntory PepsiCo Vietnam and Coca-Cola Beverages Vietnam occupy positions leveraging existing soft drink distribution infrastructure for energy portfolio expansion. Tan Hiep Phat anchors the domestic integrated producer archetype, with its Number 1 and Warrior brands representing scale-driven provincial defense strategies that foreign competitors struggle to replicate.
| Leading Market Players |
|---|
| Red Bull |
| Suntory PepsiCo Vietnam |
| Coca-Cola Beverages Vietnam |
| Tan Hiep Phat |
| Sting |
| Monster Energy |
| Rockstar |
| Number 1 |
| Warrior |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty days of finished goods inventory in southern Vietnam's aseptic processing clusters compresses pricing power for northern distributors facing cold chain gaps. This lead-time asymmetry between Binh Duong canning capacity and Hanoi retail shelves forces premium markups on temperature-sensitive variants while ambient formats flow through consolidated wholesale channels at thinner margins.
Pricing Analysis
Long-term offtake contracts between Tan Hiep Phat and provincial distributors dominate volume pricing, insulating domestic brands from spot-market caffeine anhydrous volatility that squeezes mid-tier importers. Three-tier pricing structure across premium, standard, and economy levels separates Red Bull's motorsport-positioned SKUs from Warrior's factory-zone bulk formats and unbranded pouch alternatives. Pricing pressure stems from Vietnam Food Administration compliance investments diverting marketing budgets toward warning label redesigns. Factory shift workers in Binh Duong exhibit highest price sensitivity, while Hanoi corporate professionals tolerate steep premiums for sugar-free refrigerated variants.
Supply Chain Analysis
China and India anchor caffeine anhydrous and taurine feedstock production for Vietnamese formulators, with pharmaceutical-grade chemical markets in Mumbai and Shanghai setting input cost baselines. Vietnam's southern provinces concentrate aseptic hot-fill processing, drawing from imported stimulant inputs and domestic sugar refineries. Supply chain risk centers on single-source vulnerability for refrigerated logistics equipment servicing sugar-free distribution. Distribution runs through fragmented provincial wholesaler networks in secondary cities where foreign labels lack entrenched relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's energy drinks market sits at a high-growth inflection as Circular 27/2012/TT-BYT amendments force portfolio-wide reformulation and compliance investments that reshape competitive positioning.
For Market Incumbents: Secure regulatory affairs capacity in both Ho Chi Minh City and Hanoi jurisdictions to navigate provincial interpretation variance on additive rules. Backward integration into green coffee bean extraction capabilities commands clean-label premiums that synthetic-dependent competitors cannot match. Expand captive aseptic processing capacity in northern industrial zones to bypass southern logistics chokepoints threatening Binh Duong-centric supply networks. For New Entrants and Emerging Players: Lead with sugar-free formulations targeting corporate wellness programs in Cau Giay and Tay Ho districts where refrigerated infrastructure gaps have suppressed foreign penetration. Da Nang and Hai Phong modern trade channels offer underpenetrated white space where local distributor partnerships bypass incumbent shelf fee advantages. Deploy subscription-based same-day delivery models through Shopee and Lazada refrigerated logistics to circumvent traditional ambient distribution constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beverage conglomerates seeking to divest non-core energy portfolios amid compliance cost escalation. Five-to-ten year viability hinges on regulatory affairs scalability and cold chain infrastructure ownership rather than brand equity alone. Monitor enforcement consistency between Vietnam Food Administration's southern and northern offices as the signal for competitive consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sugar-Free Formulation Launch | Captures margin pools from Hanoi professionals navigating diabetes prevention campaigns. |
| Refrigerated Logistics Partnership | Enables direct-to-consumer channels via Shopee and Lazada temperature-controlled networks. |
| Provincial Distributor Acquisition | Secures channel control in Da Nang and Can Tho where foreign labels compete less aggressively. |
| Green Coffee Extraction Investment | Supports clean-label claims that compress synthetic caffeine competitor margins. |
| Regulatory Affairs Capacity Expansion | Addresses talent scarcity outpacing local university pipeline output for BIS-aligned certifications. |
Research Methodology
Operator-level perspectives from brand managers at domestic producers, category buyers at WinMart and Co.opmart chains, channel sales heads in provincial distribution networks, and supply planners at aseptic processing facilities anchored the qualitative base. These primary interviews combined with secondary validation from Vietnam Food Administration circulars, Nielsen retail audit data, customs import records for caffeine anhydrous, and ASEAN harmonization standard documents. Bottom-up volume modeling across consumption occasions and top-down value triangulation against macroeconomic indicators ensured cross-verification.
Sensitivity analysis tested forecast robustness against regulatory enforcement variance scenarios and input cost volatility bands across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer application, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for structural shifts in gig economy labor demographics and modern trade penetration rates. Forecast inputs incorporated fitness center expansion timelines and same-day delivery platform refrigerated coverage maps.
Forecasts assume regulatory continuity in Vietnam's national food safety standards and ASEAN harmonization frameworks; material policy shifts would require re-modeling. Specific risks include provincial interpretation divergence on additive rules and cold chain infrastructure investment shortfalls in northern industrial zones. Recalibration cycles align with material shifts in Ministry of Health enforcement patterns and delivery platform logistics expansion milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market