
 Spain Food Service Market | 2026-2036
Spain Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Service Market Insights
Corporate catering and airport hospitality is pivoting toward integrated service models that blend quick turnaround with elevated menu complexity. Compass Group PLC leverages its institutional contract infrastructure to dominate business client segments across Spanish transport hubs. Restalia Grupo De Eurorestauracion SL anchors its position in urban quick-service formats through disciplined franchise density in Madrid and Barcelona corridors. McDonald's Corporation sustains competitive pressure via supply chain control over its Iberian restaurant network.
Spain food service encompasses the preparation, sale, and delivery of meals and beverages through commercial establishments ranging from quick-service counters to full-service dining rooms, with operational parameters governed by HACCP protocols, cold-chain integrity standards, and real-time kitchen management systems. The sector's primary commercial purpose is to satisfy out-of-home consumption demand while optimizing labor productivity through standardized recipes and portion controls. Quick service formats command the largest transaction volume base, though full service captures superior per-check margins in metropolitan zones. Delivery and online ordering channels are expanding fastest, reshaping kitchen floor plans and labor deployment across restaurants and cafés.
Spain's food service operators navigate oversight from the Spanish Agency for Food Safety and Nutrition (AESAN) alongside EU-level hygiene regulations and municipal licensing regimes in cities such as Madrid, Barcelona, and Valencia. AESAN's enforcement of nutritional labeling and allergen disclosure rules is elevating compliance costs while creating barriers for unstandardized independent operators. Stakeholders must monitor how Spain's transposition of the EU Green Deal's packaging waste rules will reshape takeaway and delivery economics before the decade's midpoint.
Market Dynamics
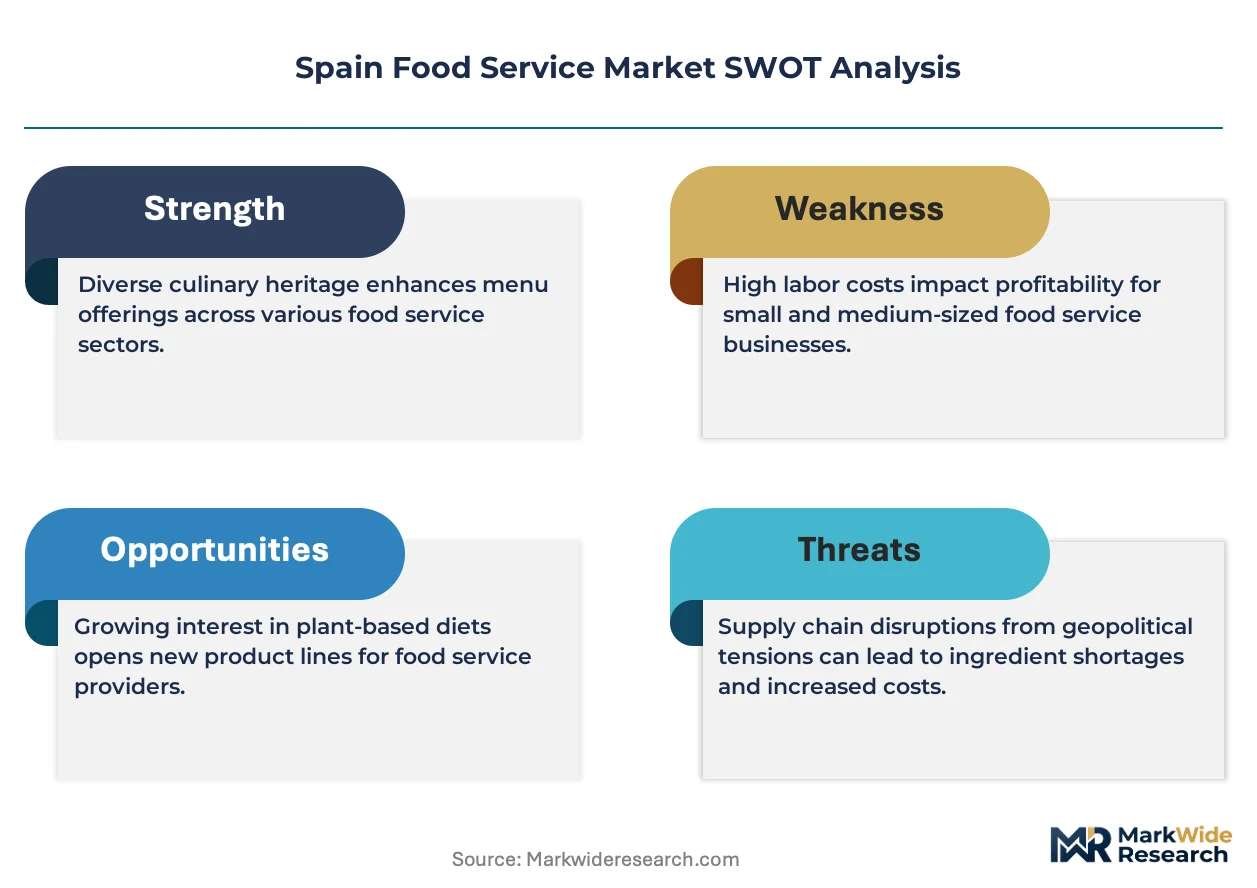
Spain's food service sector is experiencing structural compression as EU Green Deal packaging mandates intersect with Madrid and Barcelona's escalating real estate costs, forcing operators to reconfigure kitchen footprints and last-mile delivery economics simultaneously.
Growth Catalysts
- Corporate Campus Catering:Business parks in Madrid's AZCA district and Barcelona's 22@ innovation zone are expanding contract dining volumes. AESAN's nutritional transparency rules favor large-scale operators with standardized allergen protocols.
- EU Food Waste Directive:Spain's Ministry of Agriculture enforcement of waste reduction targets is accelerating investment in inventory management systems and portion-control technologies across institutional kitchens.
- Hybrid Delivery Infrastructure:Ghost kitchens and satellite prep stations in dense urban corridors are collapsing delivery radius economics. Cold-chain integrity investments are unlocking premium menu extensions.
Market Restraints
- Input Cost Volatility:Olive oil and Iberian pork prices fluctuate with climate-driven harvest variability. Operators lack forward-contract leverage against agricultural commodity swings.
- Labor Supply Concentration:Madrid and Barcelona absorb disproportionate kitchen talent, leaving Valencia and Seville operators competing for trained staff through wage escalation.
- Regulatory Friction:Municipal licensing regimes in Barcelona, Madrid, and Valencia impose divergent operating hour restrictions and terrace permit costs that complicate multi-city expansion.
Strategic Opportunities
- Andalusian and Galician Penetration:Secondary cities like Málaga, Córdoba, and Santiago de Compostela show underdeveloped full-service density relative to disposable income growth.
- EU Packaging Waste Rules:Spain's transposition of Green Deal mandates before 2030 will create first-mover advantages for operators with compostable container supply chains locked in.
- Airport Hospitality Convergence:Madrid-Barajas and Barcelona-El Prat are integrating grab-and-go with sit-down formats. Travel hub captive audiences support premium pricing compression.
Industry Challenges
- Digital Kitchen Integration:Legacy point-of-sale systems resist real-time synchronization with delivery aggregator APIs. Fragmented tech stacks delay order velocity optimization.
- HACCP Certification Velocity:AESAN's evolving allergen disclosure protocols require recurring staff retraining. Smaller operators struggle with documentation audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Service Market |
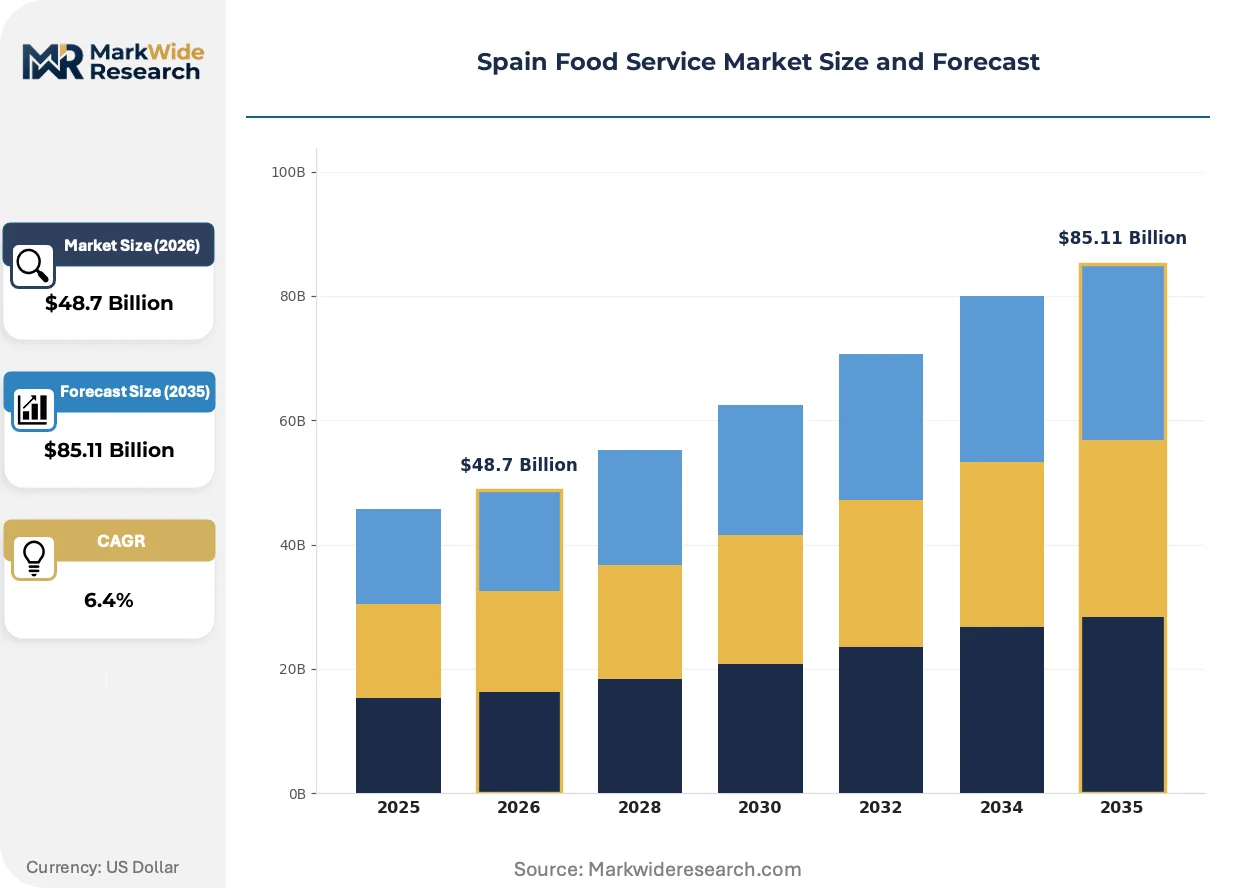
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quick Service, Full Service, Cafeteria, Catering Customer Type: Individual Consumers, Business Clients, Institutional Clients, Events End User: Restaurants, Cafés, Hotels, Hospitals Distribution Channel: Dine-In, Takeaway, Delivery, Online Ordering |
| Companies Covered | Groupo Ibersol, Compass Group PLC, Restalia Grupo De Eurorestauracion SL, McDonald's Corporation, Áreas SA, AmRest Holdings SE, Restaurant Brands Iberia, Comess Group, Alsea SAB de CV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Service Market Trends and Innovations
Spanish food service is absorbing three concurrent transformations: kitchen automation compressing labor dependency, regulatory packaging mandates reshaping takeaway economics, and procurement centralization altering operator-supplier power dynamics.
Robotic kitchen stations equipped with automated frying and plating modules are rewriting back-of-house staffing models. Full-service chains in Madrid's Salamanca district and Barcelona's Eixample are piloting these systems to maintain output during peak service windows without proportional wage bill expansion. The technology is compressing the traditional trade-off between menu complexity and throughput speed.
Spain's transposition of EU Green Deal packaging waste regulations is mandating phased elimination of single-use plastics in takeaway and delivery channels. Operators must absorb compostable container cost premiums or pass them through to price-sensitive urban consumers. Quick-service formats in Barcelona's Ciutat Vella and Madrid's Centro are most exposed, with margins thinnest and volume highest.
Corporate procurement departments are consolidating catering contracts across multi-site portfolios, displacing location-by-location vendor selection. Facility managers in Madrid's Cuatro Torres business area and Barcelona's Diagonal Mar cluster now demand consolidated billing, nutritional reporting, and carbon footprint disclosure. This concentration is visible most acutely in technology and pharmaceutical sector headquarters contracts.
Spain Food Service Market Segmentation
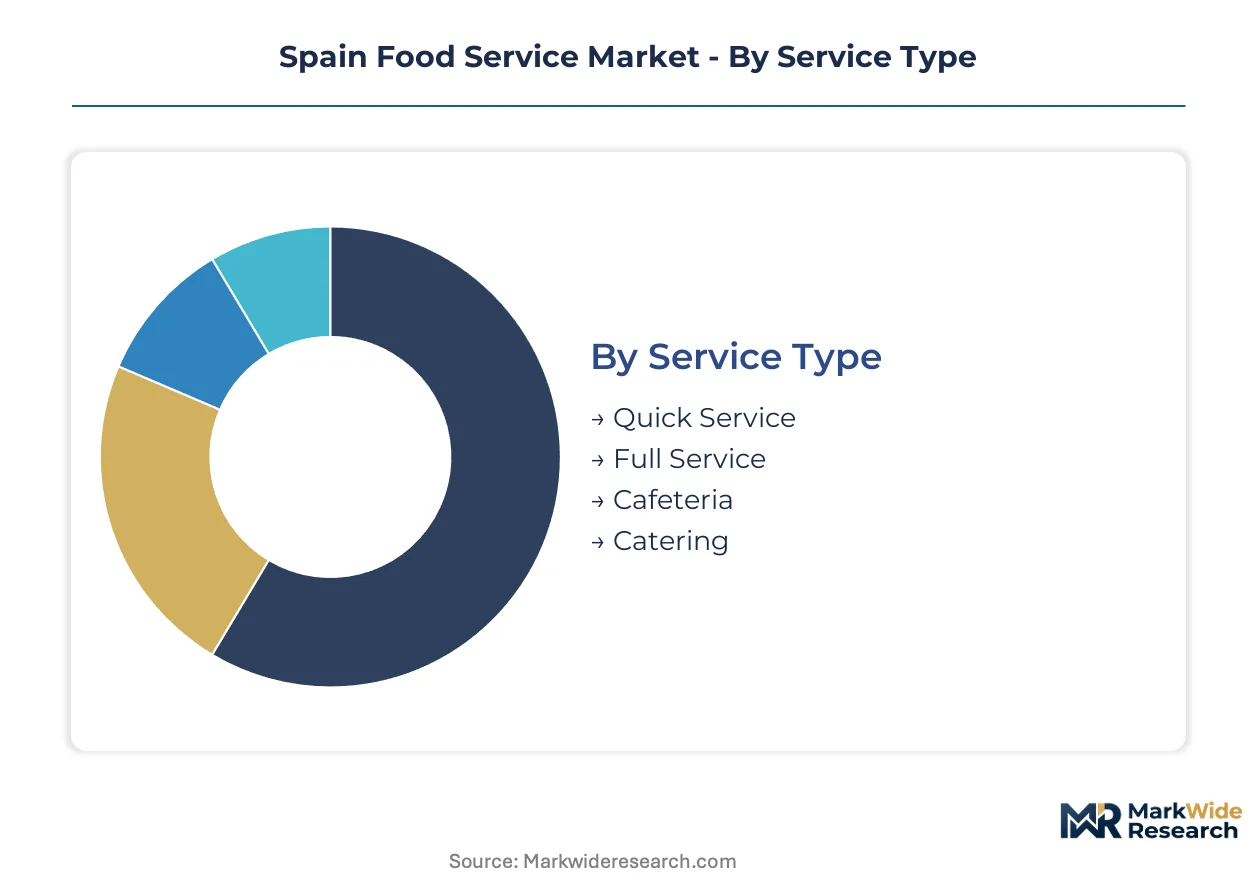
Spain's food service market fragments across service formats, customer relationships, and delivery modalities that each impose distinct operational architectures. Understanding these segment boundaries clarifies where capital requirements intensify and where margin structures diverge across Madrid, Barcelona, and secondary urban corridors.
Service Type:
Quick service formats operate as standalone volume engines with standardized production systems, while full service and catering embed within broader hospitality or corporate service ecosystems.
- Quick Service:Counter-service formats with limited menu breadth and 90-second throughput targets dominate transaction counts in Madrid's Centro and Barcelona's Eixample. AESAN's allergen disclosure mandates favor chains with centralized recipe databases over independent operators.
- Full Service:Table-service establishments in Salamanca and Gràcia districts capture premium per-check spending through extended dining durations and beverage attachment. Labor intensity peaks here, with kitchen brigades and front-of-house staffing ratios compressing margins during off-peak hours.
- Cafeteria:Self-service formats anchored in corporate campuses and educational institutions across AZCA and 22@ innovation zones. Contract pricing pressure from procurement consolidation limits menu experimentation.
- Catering:Event-driven and institutional volume production with off-premise service requirements. AESAN's HACCP documentation burdens scale disproportionately for smaller operators managing variable batch sizes.
Volume placements concentrate in Quick Service; the faster expansion belongs to Catering as corporate procurement centralizes.
Customer Type:
Cost tier stratification separates price-sensitive individual transactions from negotiated institutional contracts with reporting obligations.
- Individual Consumers:Discretionary spending on dining occasions with high price elasticity and brand switching frequency. Madrid and Barcelona urban cores show concentration of experience-seeking diners willing to queue for limited-concept openings.
- Business Clients:Corporate catering contracts across Cuatro Torres and Diagonal Mar clusters demand consolidated billing, nutritional transparency, and carbon footprint disclosure. Procurement departments now displace location-level vendor selection.
- Institutional Clients:Healthcare and education facilities with rigid procurement timelines and compliance documentation requirements. AESAN enforcement of food waste reduction targets elevates inventory management system investments.
- Events:One-off volume requirements with volatile demand timing and premium pricing tolerance during peak seasons. Barcelona's congress infrastructure and Madrid's trade fair calendar create concentrated seasonal demand spikes.
Revenue stability clusters with Business Clients; margin volatility peaks in Events.
End User:
Application context determines equipment specifications, staffing models, and regulatory exposure across facility types.
- Restaurants:Dedicated dining establishments ranging from independent single-sites to multi-unit chains. Ghost kitchen proliferation in Madrid's Usera district and Barcelona's Sant Martí is collapsing real estate requirements for delivery-native concepts.
- Cafés:Beverage-forward formats with limited food preparation and extended operating hours. Terrace permit costs in Barcelona's Ciutat Vella and Madrid's Malasaña constrain outdoor seating economics.
- Hotels:Integrated food service within hospitality operations, spanning breakfast service through banquet operations. Airport hospitality convergence at Barajas and El Prat is blending grab-and-go with sit-down formats.
- Hospitals:Clinical nutrition requirements with therapeutic menu specifications and strict HACCP protocols. AESAN's evolving allergen rules demand recurring staff retraining cycles.
Capital intensity peaks in Hotels; operational complexity concentrates in Hospitals.
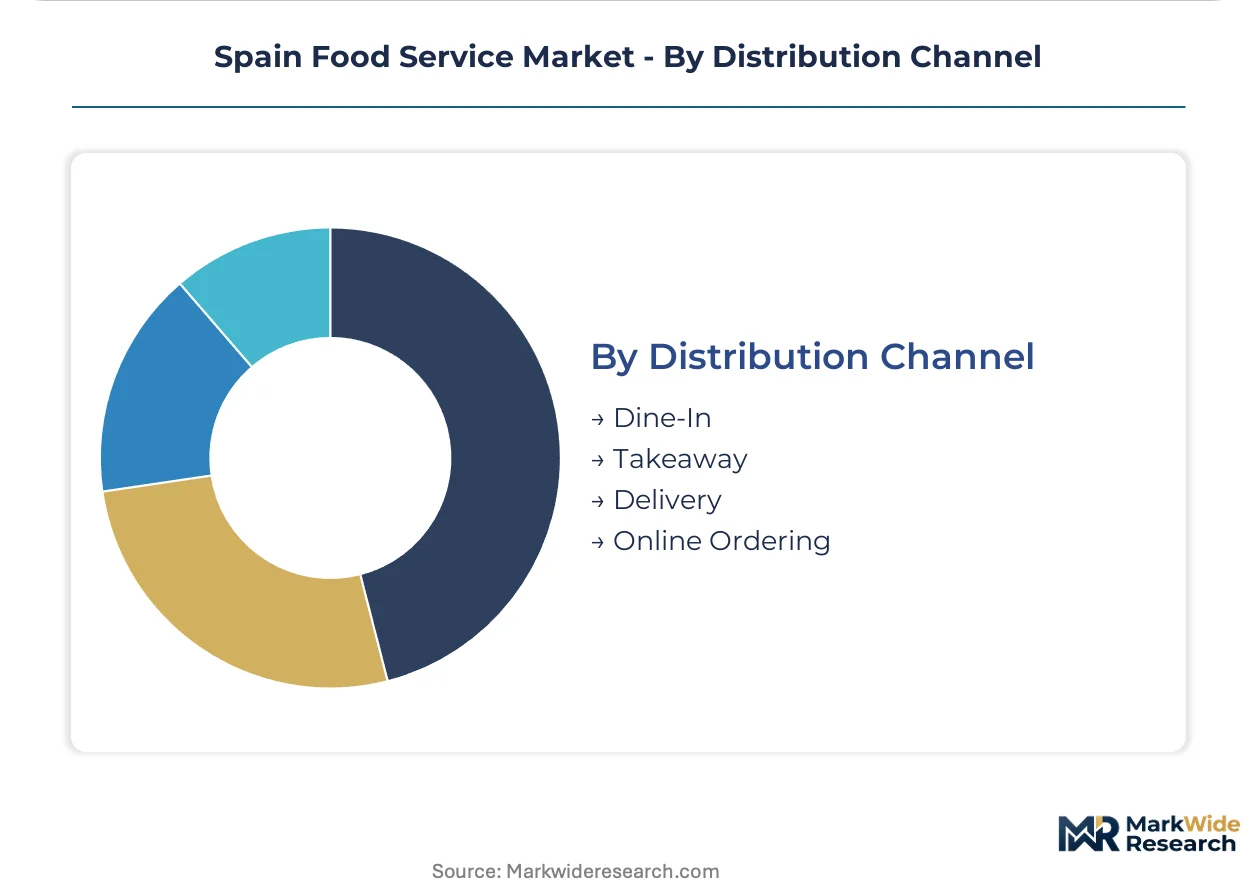
Distribution Channel:
Maturity and supply concentration separate established dine-in infrastructure from rapidly scaling digital-native channels.
- Dine-In:Traditional on-premise consumption with fixed seating capacity and location-dependent foot traffic. Real estate cost escalation in Madrid and Barcelona urban cores is forcing footprint compression.
- Takeaway:Counter collection with minimal service interaction and packaging-dependent food quality preservation. EU Green Deal packaging mandates are mandating compostable container transitions with cost absorption challenges.
- Delivery:Third-party aggregator-mediated fulfillment with commission structures compressing operator margins. Cold-chain integrity investments are unlocking premium menu extensions in dense urban corridors.
- Online Ordering:Direct digital channels bypassing aggregator fees but requiring proprietary technology investment. Legacy point-of-sale systems resist real-time synchronization with delivery APIs, fragmenting tech stacks.
Transaction volume still flows through Dine-In; share gains are climbing the fastest in Online Ordering as operators seek commission avoidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Zona Franca special-economic-zone incentives in Barcelona concentrate contract catering infrastructure near port logistics corridors. The national food service map tilts toward Mediterranean coastal demand density and inland urban corridors.
Madrid
Corporate campus dining in AZCA and Cuatro Torres business districts absorbs institutional catering contracts at scale. AESAN nutritional transparency mandates favor operators with centralized recipe databases. Ghost kitchen proliferation in Usera district compresses real estate costs for delivery-native concepts.
Catalonia
Barcelona's 22@ innovation zone and El Prat airport hospitality convergence drive integrated grab-and-go and sit-down format blending. EU Green Deal packaging waste transposition elevates compostable container compliance costs. Terrace permit restrictions in Ciutat Vella constrain outdoor seating economics for cafés.
Andalusia
Málaga and Córdoba show underdeveloped full-service density relative to disposable income trajectory. The Ministry of Agriculture's food waste reduction enforcement accelerates inventory management investments. Secondary urban corridors attract QSR franchise expansion from Madrid-based operators.
Basque Country
Bilbao's industrial heritage zones generate steady business client catering demand from manufacturing headquarters. Municipal licensing divergence complicates multi-city operator expansion. San Sebastián's premium dining concentration captures elevated per-check spending through gastronomic tourism.
Valencia
Labor supply competition with Madrid and Barcelona forces wage escalation for trained kitchen staff. The city's congress infrastructure creates seasonal event catering demand spikes. Port-adjacent logistics clusters support cold-chain distribution for institutional client contracts.
Spain Food Service Market Competitive Landscape
Top-tier vendors anchor institutional contract infrastructure, while mid-scale operators compete through franchise density in urban corridors. The market structure concentrates around three archetypes: global contract caterers with AESAN compliance scale, domestic QSR franchise aggregators, and airport hospitality specialists. Competitive moves center on ghost kitchen network expansion and compostable packaging supply chain lock-in ahead of EU mandate deadlines.
Within the institutional catering tier, Compass Group PLC and Áreas SA occupy positions defined by captive audience access at transport hubs and corporate campuses. Restalia Grupo De Eurorestauracion SL exemplifies the domestic franchise density archetype through disciplined urban corridor penetration. McDonald's Corporation anchors the scale-driven multinational segment with Iberian supply chain control.
| Leading Market Players |
|---|
| Groupo Ibersol |
| Compass Group PLC |
| Restalia Grupo De Eurorestauracion SL |
| McDonald's Corporation |
| Áreas SA |
| AmRest Holdings SE |
| Restaurant Brands Iberia |
| Comess Group |
| Alsea SAB de CV |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap operators concentrated in Madrid's urban corridors anchor supply behavior through generational procurement relationships with Andalusian olive oil cooperatives and Galician seafood distributors, while their pricing discipline reflects negotiated annual contracts that buffer against Iberian pork price volatility. This ownership pattern compresses margin flexibility when AESAN-mandated allergen labeling investments collide with compostable packaging cost premiums.
Pricing Analysis
Short lead-time premiums for fresh Iberian pork and daily-catch seafood from Galician ports command 15-25% markups over frozen inventory, while spot-market olive oil purchases in poor harvest years trigger acute cost pass-through attempts. Three-tier pricing structure across premium full-service Salamanca dining, standard quick-service Centro counters, and economy cafeteria formats in AZCA business parks separates experiential spending from convenience transactions. Pricing pressure stems from EU Green Deal packaging mandates absorbing margin in takeaway-heavy Barcelona Ciutat Vella operations. Quick-service formats show highest price sensitivity; corporate catering contracts with consolidated billing show lowest.
Supply Chain Analysis
Workforce availability in Extremadura's agricultural processing zones and Galicia's fishing ports constrains seasonal input velocity, forcing Madrid and Barcelona operators to extend inventory buffers. Supply concentrates in Spain's olive oil heartland (Jaén, Córdoba), Galician seafood landing sites (Vigo, A Coruña), and imported protein corridors through Valencia port. Raw material dependencies center on climate-vulnerable olive harvests, Iberian pork breeding cycles, and imported grain feedstocks. Single-source vulnerability runs through concentrated olive oil cooperative structures. Distribution runs through cold-chain networks anchored in Madrid's Mercamadrid and Barcelona's Mercabarna wholesale complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's food service sector is becoming a vertical-integration race as operators pursue captive supply of compostable packaging ahead of EU mandate deadlines and backward integration into Andalusian olive oil sourcing to hedge commodity volatility.
For Market Incumbents: Hedge AESAN compliance cost escalation by locking multi-year franchise agreements with centralized recipe database providers before allergen disclosure rules tighten further. Secure exclusive compostable container supply contracts with Basque Country packaging manufacturers to preempt 2030 EU Green Deal enforcement. Defend Madrid and Barcelona corridor density against ghost kitchen entrants through satellite prep station preemption in Usera and Sant Martí districts. For New Entrants and Emerging Players: Direct-to-consumer online ordering platforms offer the lowest-friction entry vector for bypassing third-party aggregator commissions that currently compress operator margins by 20-30%. Target underpenetrated Andalusian secondary cities—Málaga and Córdoba show full-service density gaps relative to disposable income growth. Lead with hybrid delivery-native concepts featuring cold-chain premium menus to differentiate from established QSR incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale full-service operators in Barcelona's Gràcia and Madrid's Chamberí districts facing terrace permit cost escalation and labor wage compression. Five-to-ten-year viability hinges on digital kitchen integration completion and AESAN audit readiness. Watch for inflection in compostable packaging cost parity signals—when bio-based container premiums drop below 15% versus conventional plastics, acquisition multiples for prepared operators should expand.| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Network Expansion | Collapses real estate requirements in Madrid's Usera and Barcelona's Sant Martí for delivery-native concepts. |
| Compostable Packaging Supply Lock-in | Creates first-mover advantage ahead of Spain's EU Green Deal transposition before 2030 deadline. |
| Corporate Catering Contract Consolidation | Captures procurement centralization in Cuatro Torres and Diagonal Mar business clusters with reporting capabilities. |
| Andalusian Secondary City Penetration | Exploits full-service density gaps in Málaga and Córdoba relative to income growth trajectories. |
| Robotic Kitchen Station Deployment | Compresses labor dependency in Madrid's Salamanca and Barcelona's Eixample peak-service windows. |
Research Methodology
Multi-period observation of Madrid and Barcelona restaurant opening rates, franchise disclosure document filings, and AESAN enforcement actions anchored the trend analysis, supplemented by interviews with contract catering procurement managers, ghost kitchen facility operators, quick-service franchise development directors, and compostable packaging supply chain managers. Secondary validation drew from Spanish Ministry of Agriculture food waste reports, EU Green Deal implementation timelines, municipal licensing databases in Madrid, Barcelona, and Valencia, and cold-chain logistics operator disclosures. Bottom-up outlet counting across service format segments triangulated against top-down consumer expenditure estimates from national accounts.
Segment-weighting across service type, customer relationship, and distribution channel dimensions structured the analytical framework, with explicit modeling of quick-service volume trajectories, full-service per-check dynamics, and delivery channel expansion rates over the projection horizon. CAGRs were derived from fitted growth curves incorporating urban real estate cost indices, labor supply concentration metrics, and regulatory compliance cost schedules. Industry-specific forecast inputs included EU packaging waste rule transposition timing and AESAN nutritional labeling enforcement intensity variations.
The model holds under steady EU regulatory implementation timelines and stable Iberian agricultural harvest patterns; deviation in olive oil price volatility spikes or accelerated AESAN audit frequency would shift operator margin assumptions and franchise expansion timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Delivery Services Market
Food Service
Egypt Food Service Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Breakfast Takeout Market
Food Service
Commercial Charbroiler Market
Food Service
Europe Barbeque Grill Market
Food Service
South Korea Foodservice Market
Food Service
Commercial Griddle Market
Food Service
Singapore Food Service Market
Food Service
Virtual Kitchen Market
Food Service
Ice Cream Carts Market
Food Service
Malaysia Food Service Market
Food Service
India Full Service Restaurants Market
Food Service
Ship Catering Service Market
Food Service
Beverage Coaster Market
Food Service
Food & Beverage in Asia Market