
 Global Self Heating Instant Hot Pot Market | 2026-2036
Global Self Heating Instant Hot Pot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self Heating Instant Hot Pot Market Outlook
The EU Green Deal's packaging waste reduction targets is restructuring procurement criteria across European retail channels. Haidilao International Holding Ltd. anchors its position through captive supply chains for Sichuan peppercorn and chili oil bases. Nissin Foods leverages its cup noodle manufacturing scale to achieve cost parity in aluminum foil pouch formats. Xiaolongkan Hotpot competes on regional flavor authenticity with dedicated R&D kitchens in Chengdu.
Self heating instant hot pot denotes a portable meal system combining pre-cooked ingredients with an exothermic chemical reaction—typically calcium oxide and water generating heat exceeding 85°C—enabling consumption without external power sources. The product serves outdoor enthusiasts, remote workers, and emergency preparedness segments requiring hot meals in infrastructure-limited settings. Beef and chicken variants dominate value contribution due to higher protein premiums and established consumer preference in East Asian markets. Online retail channels capture the fastest expansion trajectory, driven by direct-to-consumer subscription models and live-streaming commerce platforms that bypass traditional supermarket slotting fees.
FDA food-contact substance notifications and China's SAMR food safety labeling requirements govern market access for imported and domestic formulations respectively. REACH compliance for chemical heating packs constrains European formulation options, while Japan's METI product liability standards mandate explicit burn-risk warnings on outer packaging. Stakeholders must monitor evolving heat-pack chemistry regulations and channel-specific certification requirements as the category scales beyond its East Asian origins.
Market Dynamics
China's GB standards for self-heating package safety are tightening compliance requirements, forcing reformulation of exothermic chemistry and reshaping supplier qualification protocols across the entire supply base.
Growth Catalysts
- Emergency Preparedness Demand:Government stockpiling programs in Japan and South Korea are expanding procurement of shelf-stable hot meals for disaster relief inventories, creating institutional volume anchors.
- REACH Compliance Adaptation:European manufacturers are reformulating heating packs with magnesium iron oxide alternatives to satisfy chemical substance restrictions, opening regulated market access.
- Live-Streaming Commerce:China's Douyin and Kuaishou platforms are bypassing traditional retail slotting fees, enabling direct-to-consumer subscription models that accelerate trial and repeat purchase.
Market Restraints
- Calcium Oxide Price Volatility:Raw material costs for exothermic reactions fluctuate with construction-grade lime demand, compressing margin predictability for mid-tier producers.
- Single-Point Supply Risk:Aluminum foil pouch manufacturing concentrates in Zhejiang province, exposing brands to regional logistics disruptions and tariff exposure.
- Burn Liability Exposure:Japan's METI product liability standards mandate explicit warning labeling that increases packaging complexity and litigation defense costs.
Strategic Opportunities
- Southeast Asia Penetration:Indonesia and Vietnam's urban commuter populations remain underpenetrated for portable hot meal solutions, offering first-mover positioning for flavor-localized entrants.
- EU Green Deal Tailwind:Packaging waste reduction targets are restructuring European retail procurement criteria, favoring aluminum-recyclable formats over plastic-intensive alternatives.
- Halal Certification Gap:Muslim-majority markets in Malaysia and the Middle East lack certified self-heating hot pot options, creating white space for supply chain investments in halal-compliant protein sourcing.
Industry Challenges
- Food Safety Certification Timelines:China's SAMR labeling requirements and FDA food-contact substance notifications impose sequential approval bottlenecks that delay cross-border launches by 12-18 months.
- Heat-Pack Chemistry Talent Scarcity:Formulation expertise for stable exothermic reactions sits with a narrow pool of chemical engineers in East Asian research clusters, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self Heating Instant Hot Pot Market |
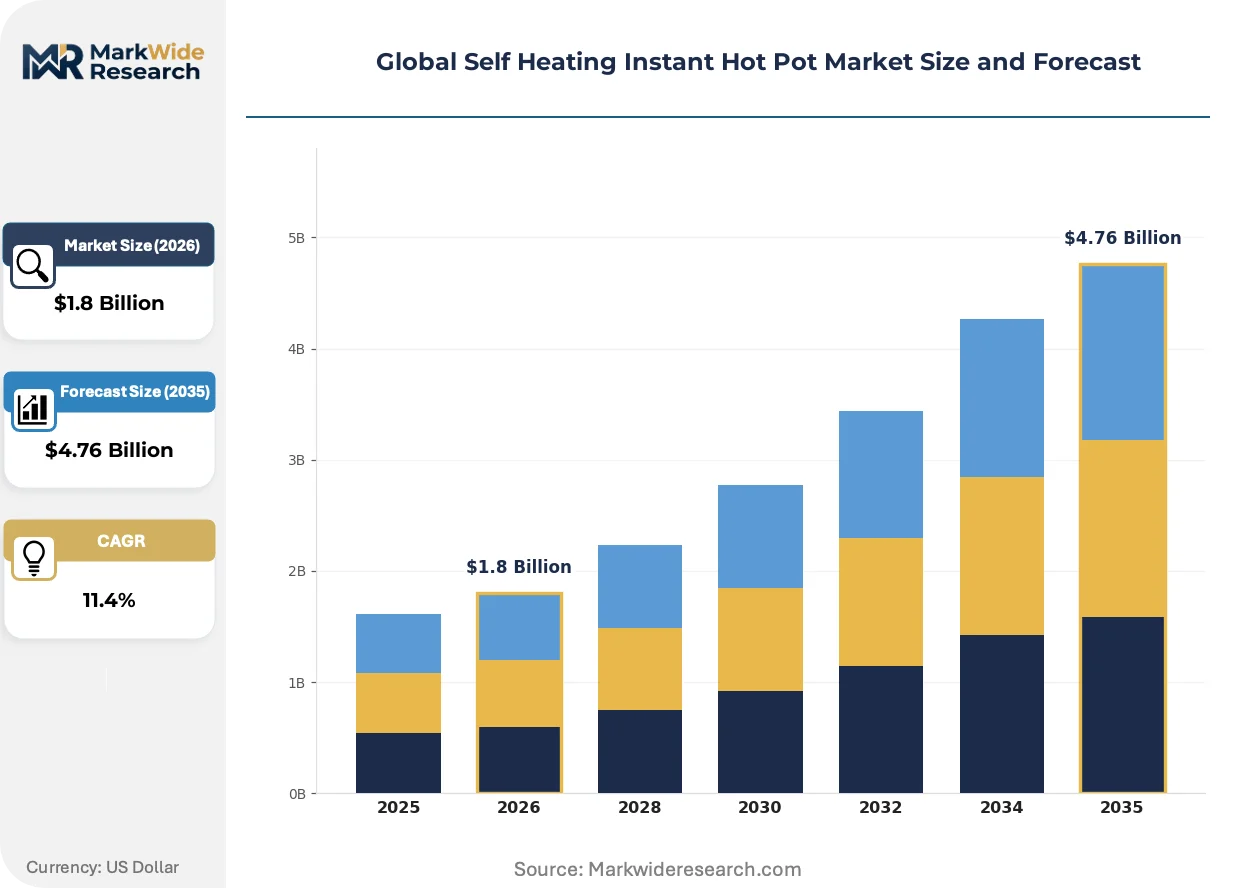
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Seafood, Chicken, Beef Packaging Type: Plastic Containers, Aluminum Foil, Bowls, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores End User: Households, Restaurants, Catering Services, Outdoor Enthusiasts |
| Companies Covered | Xiaolongkan Hotpot, Nissin Foods, Haidilao International Holding Ltd., Uni-President Enterprises Corp., Samyang Corp., Chongqing Ruya Technology Co. Ltd., Hong Phat Import Export Co. Ltd., CJ CheilJedang Corp., Shanghai Moxiaoxian Food Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self Heating Instant Hot Pot Market Strategic Shifts
Reformulation of exothermic chemistry and channel disintermediation are compressing traditional go-to-market timelines while expanding addressable use cases beyond outdoor recreation into institutional and emergency segments.
Biodegradable heating pack substrates are expanding into European and North American markets as brands respond to landfill diversion mandates. Outdoor retailers in Germany and California are prioritizing shelf space for compostable-format products that eliminate aluminum foil disposal friction. This material transition is expanding into premium positioning opportunities that command shelf price premiums of 15-25% over conventional formats.
The EU Green Deal's packaging waste reduction targets are forcing redesign of multi-layer pouch structures to satisfy extended producer responsibility schemes. Supermarket chains in France and the Netherlands are delisting SKUs that fail to meet 2025 recyclability thresholds, compressing supplier margins but accelerating standardization around mono-material aluminum designs. Heat-resistant barrier coatings are most affected, with coating suppliers investing in water-based alternatives to satisfy ECHA substance restrictions.
Subscription-based replenishment models are displacing single-unit impulse purchases in China's tier-one cities. Young urban professionals in Shanghai and Beijing are enrolling in auto-delivery programs that customize flavor rotations based on consumption velocity data. This behavioral shift is most visible in the Yangtze River Delta, where logistics density enables same-day fulfillment that reinforces habit formation and reduces brand switching.
Global Self Heating Instant Hot Pot Market Segmentation
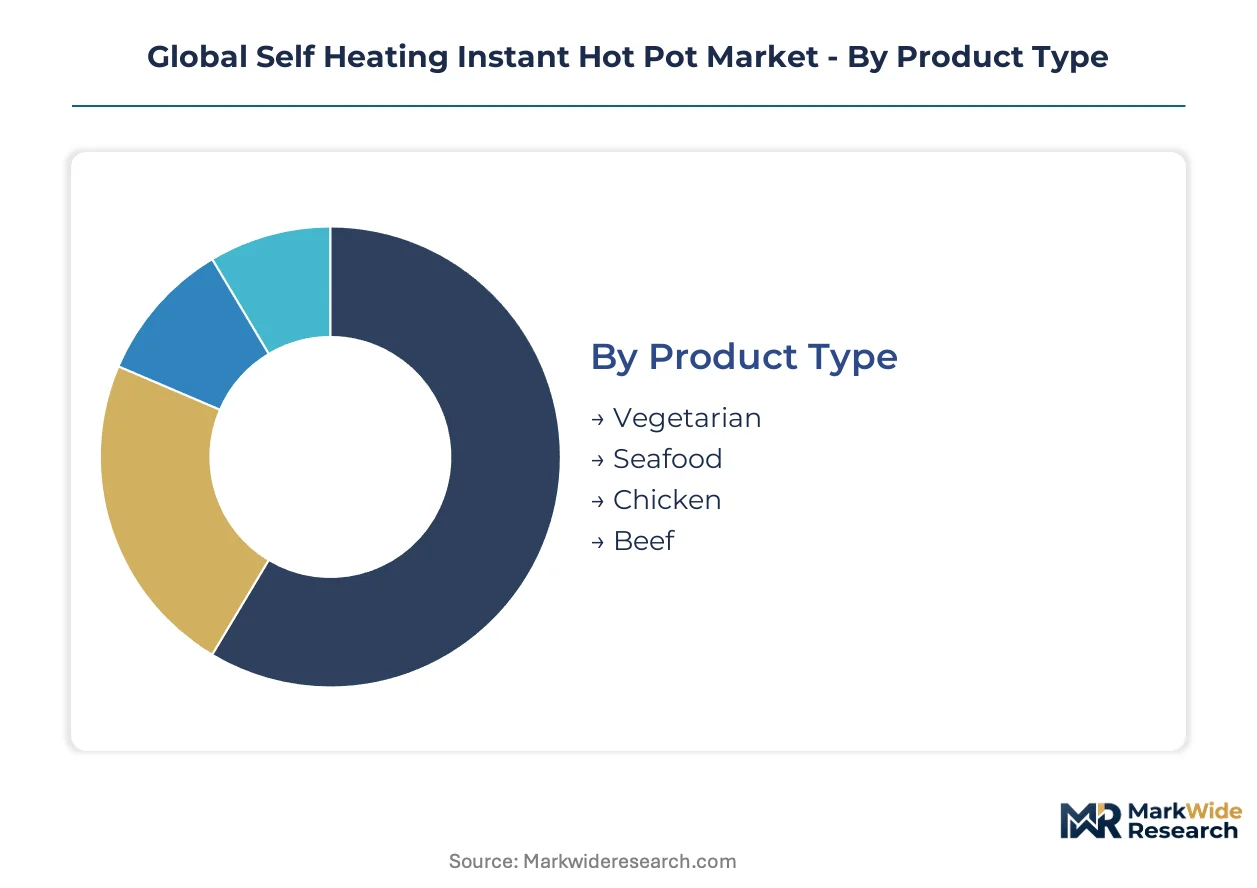
Segmentation in the self-heating hot pot market determines regulatory pathway complexity and margin structure. Product type and packaging format dictate whether formulations trigger FDA food-contact notifications, REACH compliance reviews, or China's GB standards for exothermic package safety.
Product Type:
Protein-based variants carry heavier certification burdens than plant-based alternatives, with beef and chicken formulations requiring sequential approvals across multiple jurisdictions.
- Beef:Premium protein positioning commands higher shelf prices and drives procurement from Australia's halal-certified supply chains. Demand concentrates in China's Yangtze River Delta manufacturing cluster, where young urban professionals prioritize convenience without sacrificing protein quality.
- Chicken:Lower input costs enable aggressive pricing in Southeast Asian markets, though avian influenza monitoring requirements from Japan's PMDA and China's SAMR add documentation overhead. Volume leadership in Indonesia and Vietnam reflects localized flavor development.
- Seafood:Shelf-stable fish and shellfish formulations face stricter FDA histamine controls and EU EFSA marine toxin standards.
- Vegetarian:Mushroom and tofu bases bypass most animal protein regulatory hurdles, accelerating entry into India's FSSAI-monitored market.
Leading the category by volume: Chicken. Expanding most quickly: Beef.
Packaging Type:
Material selection determines recyclability compliance under the EU Green Deal and Japan's container recycling laws, with aluminum formats gaining share against plastic alternatives.
- Aluminum Foil:Mono-material designs satisfy France and Netherlands supermarket delisting thresholds for 2025 recyclability. Zhejiang province suppliers dominate global capacity, creating single-point exposure to regional logistics disruptions.
- Pouches:Multi-layer barrier structures require heat-resistant coating reformulation to meet ECHA substance restrictions, compressing margins but enabling lighter shipping weights for e-commerce fulfillment.
- Bowls:Rigid formats suit restaurant and catering service bulk procurement with established microwave compatibility.
- Plastic Containers:Polypropylene designs face accelerating substitution pressure from German and California outdoor retailers prioritizing compostable alternatives.
Aluminum foil leads on margin contribution. Pouch formats are climbing the fastest on volume.
Distribution Channel:
Channel selection shapes customer acquisition economics, with digital platforms bypassing traditional slotting fee structures that burden supermarket penetration.
- Online Retail:Douyin and Kuaishou live-streaming commerce enables direct-to-consumer subscription models with same-day fulfillment in Shanghai and Beijing. Auto-delivery programs reduce brand switching through consumption velocity data customization.
- Supermarkets:Slotting fees and extended producer responsibility compliance costs favor established players with captive supply chains.
- Convenience Stores:Impulse purchase positioning targets Japan's commuter corridors and South Korea's urban density.
- Specialty Stores:Outdoor retailers in Germany and California command 15-25% shelf price premiums for biodegradable heating pack substrates.
Supermarkets retain volume leadership. Online retail shows the steepest expansion trajectory.
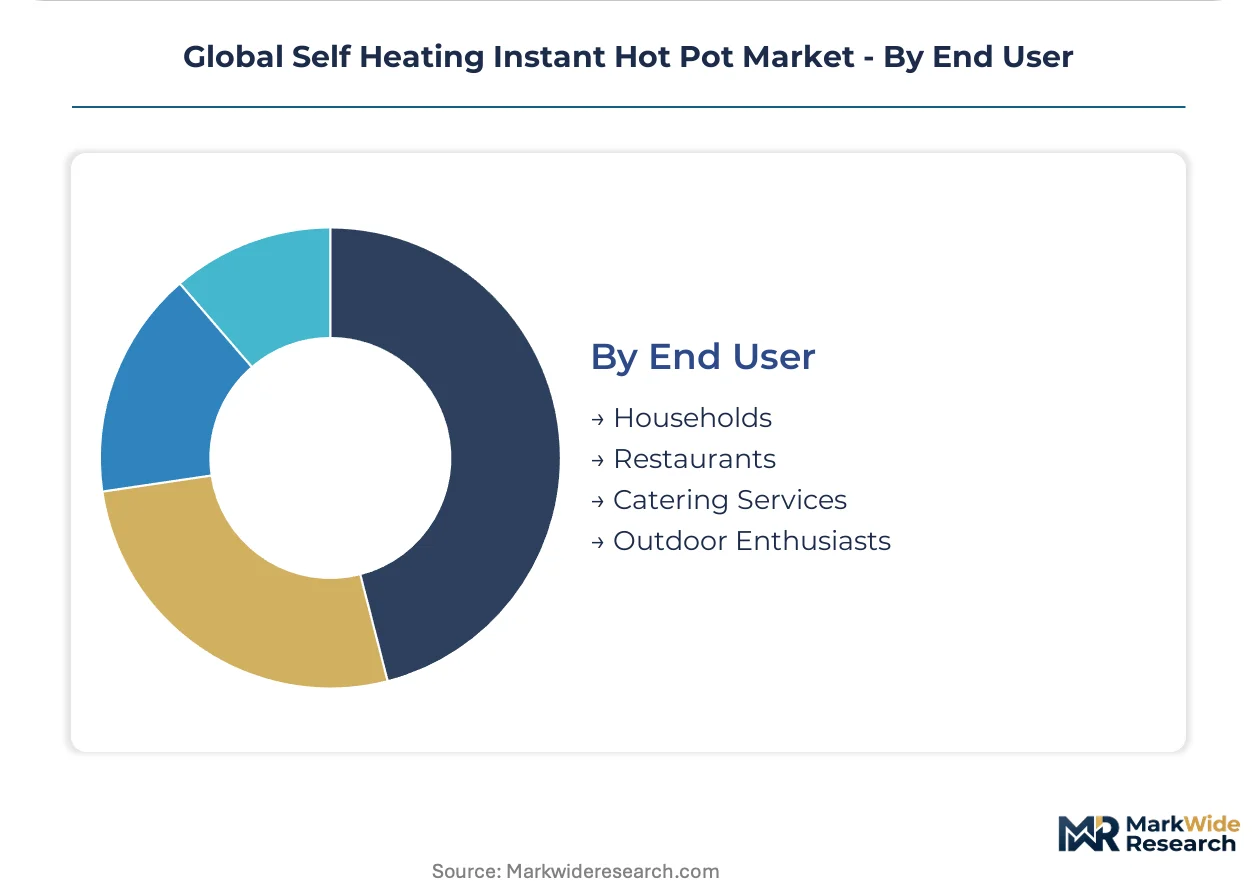
End User:
Institutional procurement carries longer sales cycles but anchors production planning, while household demand drives flavor innovation velocity.
- Households:Young urban professionals in China's tier-one cities accelerate trial through live-streaming platforms, with subscription models displacing single-unit purchases.
- Outdoor Enthusiasts:German and California retailers prioritize compostable formats that eliminate aluminum foil disposal friction in wilderness settings.
- Restaurants:Back-of-house applications demand consistent heat output timing for service synchronization.
- Catering Services:Bulk procurement from Japan and South Korea government stockpiling programs creates institutional volume anchors for disaster relief inventories.
Households dominate current volume. Catering services are gaining share fastest on emergency preparedness procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's Yangtze River Delta while consumption disperses across East Asian urban corridors and Western outdoor retail channels. Manufacturing gravity pulls toward Zhejiang and Jiangsu provinces for aluminum foil pouch fabrication. Regulatory divergence between China's SAMR, Japan's METI, and the EU's REACH framework fragments market access pathways.
China
Young urban professionals in Shanghai and Beijing drive subscription-based replenishment through Douyin live-streaming commerce. SAMR food safety labeling requirements and tightening GB standards for self-heating package safety force sequential reformulation of exothermic chemistry. The Yangtze River Delta cluster around Hangzhou anchors global aluminum foil pouch capacity, exposing brands to single-point supply risk.
Japan
Government stockpiling programs for disaster relief inventories create institutional volume anchors for shelf-stable hot meals. METI product liability standards mandate explicit burn-risk warnings on outer packaging, increasing litigation defense costs for entrants. Tokyo and Osaka commuter corridors sustain convenience store impulse purchase positioning for portable meal solutions.
South Korea
Emergency preparedness procurement from national disaster relief agencies expands institutional demand for certified shelf-stable formats. MFDS monitoring requirements for avian influenza documentation add compliance overhead for chicken-based variants. Seoul Capital Area logistics density enables same-day fulfillment that reinforces subscription habit formation among young professionals.
Germany
Outdoor retailers in Bavaria and Baden-Württemberg command shelf price premiums for biodegradable heating pack substrates that satisfy landfill diversion mandates. The EU Green Deal's packaging waste reduction targets force delisting of SKUs failing 2025 recyclability thresholds. REACH compliance for chemical heating packs constrains formulation options to magnesium iron oxide alternatives.
United States
FDA food-contact substance notifications govern market access for imported formulations, imposing 12-18 month approval bottlenecks. California outdoor retailers prioritize compostable-format products that eliminate aluminum foil disposal friction in wilderness settings. Pacific Northwest logistics networks support direct-to-consumer subscription models bypassing traditional supermarket slotting fees.
Global Self Heating Instant Hot Pot Market Competitive Environment
The competitive structure tilts toward diversified food conglomerates with captive supply chain control over flavor bases and regional specialists competing on authenticity. Three tiers separate scale-driven multinationals with cup noodle manufacturing assets, mid-tier players with vertical integration into Sichuan peppercorn sourcing, and emerging entrants targeting halal certification gaps. Dominant competitive moves include backward integration into upstream ingredient procurement and channel disintermediation through live-streaming commerce platforms.
Among Chinese-origin specialists, Xiaolongkan Hotpot and Haidilao International Holding Ltd. occupy positions within the authenticity-focused tier, exemplifying strategies built on regional flavor development and captive supply chain control. Nissin Foods represents the scale-driven multinational archetype, leveraging existing cup noodle manufacturing infrastructure to achieve cost parity in aluminum foil pouch formats. These three entities anchor the competitive spectrum from regional specialization to global manufacturing scale.
| Leading Market Players |
|---|
| Xiaolongkan Hotpot |
| Nissin Foods |
| Haidilao International Holding Ltd. |
| Uni-President Enterprises Corp. |
| Samyang Corp. |
| Chongqing Ruya Technology Co. Ltd. |
| Hong Phat Import Export Co. Ltd. |
| CJ CheilJedang Corp. |
| Shanghai Moxiaoxian Food Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's packaging waste reduction targets gate qualified supply and premium-tier pricing access, forcing aluminum-recyclable formats into procurement specifications while excluding plastic-intensive alternatives from supermarket shelves across France and the Netherlands.
Pricing Analysis
Heat output consistency anchors value-based pricing tiers, with brands commanding shelf price premiums of 15-25% for biodegradable heating pack substrates that satisfy German and California outdoor retailer mandates. Price differentiation separates compostable-format products from conventional aluminum foil designs, with certification grade and geographic delivery cost driving tier placement. Cost compression in mid-tier chicken variants is intensifying because avian influenza documentation overhead from Japan's PMDA and China's SAMR adds compliance burden without commensurate protein premium. Southeast Asian household buyers exhibit highest price sensitivity, while institutional procurement from Japan and South Korea government stockpiling programs demonstrates lowest sensitivity due to emergency preparedness mission requirements.
Supply Chain Analysis
Freight cost exposure concentrates in Zhejiang province's aluminum foil pouch manufacturing cluster, where same-day fulfillment density in Shanghai and Hangzhou masks vulnerability to regional logistics disruptions. Raw material inputs draw from construction-grade lime for calcium oxide exothermic chemistry, magnesium iron oxide REACH-compliant alternatives for European formulations, and Sichuan peppercorn flavor bases for authenticity positioning. Single-source vulnerability sits with Zhejiang suppliers dominating global aluminum foil pouch capacity. Distribution feeds from direct-to-consumer subscription models through Douyin and Kuaishou live-streaming platforms, bypassing traditional supermarket slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. China's tightening GB standards for self-heating package safety erect a barrier-to-entry moat that rewards incumbents with sequential reformulation capabilities while delaying cross-border launches for unprepared entrants.
For Market Incumbents: Lock in captive supply chains for Sichuan peppercorn and chili oil bases before raw material costs fluctuate with construction-grade lime demand. Prioritize magnesium iron oxide heating pack reformulation to satisfy REACH compliance and preempt European market access restrictions. Defend against emerging halal-certified entrants by accelerating supply chain investments in Australia's halal-compliant protein sourcing. For New Entrants and Emerging Players: Begin with Indonesia and Vietnam's underpenetrated urban commuter populations, where localized chicken flavor development can bypass established East Asian brand recognition. Target Malaysia and Middle East Muslim-majority markets lacking certified self-heating hot pot options. Pursue direct-to-consumer live-streaming commerce launch through Kuaishou to circumvent supermarket slotting fees that burden established players. For Investors and Strategic Acquirers: China's SAMR approval of magnesium iron oxide alternatives for domestic formulations is the leading indicator that REACH-compliant chemistry will achieve cost parity and unlock European market expansion. Position acquisition screening around mid-tier players with vertical integration into upstream ingredient procurement and existing live-streaming commerce infrastructure. Monitor Japan's METI burn-risk warning label enforcement intensity as a litigation cost inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Exothermic Chemistry Reformulation | Magnesium iron oxide alternatives satisfy REACH restrictions and unlock European supermarket access. |
| Halal Supply Chain Certification | Australia-sourced protein enables entry into Malaysia and Middle East Muslim-majority markets. |
| Live-Streaming Commerce Launch | Douyin and Kuaishou platforms bypass traditional retail slotting fees and accelerate trial. |
| Biodegradable Substrate Transition | Compostable heating packs command 15-25% shelf price premiums in German outdoor retail. |
| Captive Flavor Base Integration | In-house Sichuan peppercorn and chili oil production defends against input cost volatility. |
Study Parameters
Independent corroboration across regulatory filing databases, customs trade records, and live-streaming commerce transaction data underwrites the qualitative findings. Primary interviews with brand managers at diversified food conglomerates, category buyers at German outdoor retailers, procurement leads at Japan's disaster relief agencies, and chemical engineers specializing in exothermic formulations combined with secondary validation from SAMR labeling requirement documents, REACH substance restriction updates, and EU Green Deal implementation guidance. Bottom-up shipment data from Zhejiang province aluminum foil suppliers and top-down consumer expenditure patterns across China's tier-one cities enabled triangulation.
Rate-of-change decomposition across protein type, packaging format, distribution channel, and end-use segmentation dimensions drove the analytical framework. CAGRs were derived from modeled consumption velocity in Shanghai and Beijing subscription programs, institutional procurement expansion from Japan and South Korea government stockpiling, and penetration assumptions for Indonesia and Vietnam urban commuter corridors. Heat-pack chemistry stability timelines and cross-border certification approval bottlenecks informed scenario-weighted projections across the modeling period.
Underlying measurement precision varies by segment; online retail channel estimates carry tighter precision than emerging halal-certified market projections due to live-streaming platform data availability. Forecasts reflect assumptions about REACH compliance adaptation speed and SAMR reformulation timelines that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Egypt Food Service Market
Food Service
Street Vendors Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Global Meal Kit Market
Food Service
Philippines Foodservice Market
Food Service
Africa Foodservice Market
Food Service
Food Service Pasta Market
Food Service
United Arab Emirates Full Service Restaurants Market
Food Service
India Quick Service Restaurant Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
Takeout Dinner Market
Food Service
Global Cafe and Bars Market
Food Service
Airport Quick Service Restaurants Market
Food Service
Europe Online Grocery Delivery Market
Food Service
United Kingdom Full Service Restaurants Market