
 Ecuador Container Glass Market | 2026-2036
Ecuador Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Ecuador Container Glass Market Insights
Multi-source procurement for cullet and soda ash is decoupling from the historical single-supplier model that dominated Ecuador's container glass sector. O-I Glass, Inc. anchors North American technology transfer into its local operations through furnace modernization programs. Ecuaenvases Cia Ltda. specializes in customized jar formats for the domestic food processing sector. Vidriera Ecuatoriana competes on proximity to Guayaquil's port logistics, reducing inbound raw material transit costs.
Container glass comprises silica-based amorphous solids formed through batch melting at temperatures exceeding 1,500°C, followed by blow-and-blow or press-and-blow forming into hollow vessels with wall thickness typically ranging from 3 to 6 millimeters. The material serves as an inert, impermeable barrier for oxygen-sensitive contents across food, beverage, and pharmaceutical applications. Bottles sustain the dominant volume position within product type segmentation due to entrenched beverage industry demand for returnable and single-use formats. The pharmaceuticals end user segment records the fastest structural expansion as domestic drug packaging regulations tighten material compatibility requirements. Small and medium sizes concentrate margin pools through higher unit pricing and lower shipping cost intensity per container.
Ecuador's national standards body enforces packaging material compliance frameworks that mandate recyclability thresholds for glass containers sold into food and beverage channels. The country's environmental regulator applies emissions controls on furnace operations that shape capital allocation toward oxy-fuel conversion or electric melting pilot programs. Stakeholders must monitor regulatory timing for extended producer responsibility legislation that would restructure post-consumer collection economics and reshape competitive positioning between integrated and non-integrated producers.
Market Dynamics
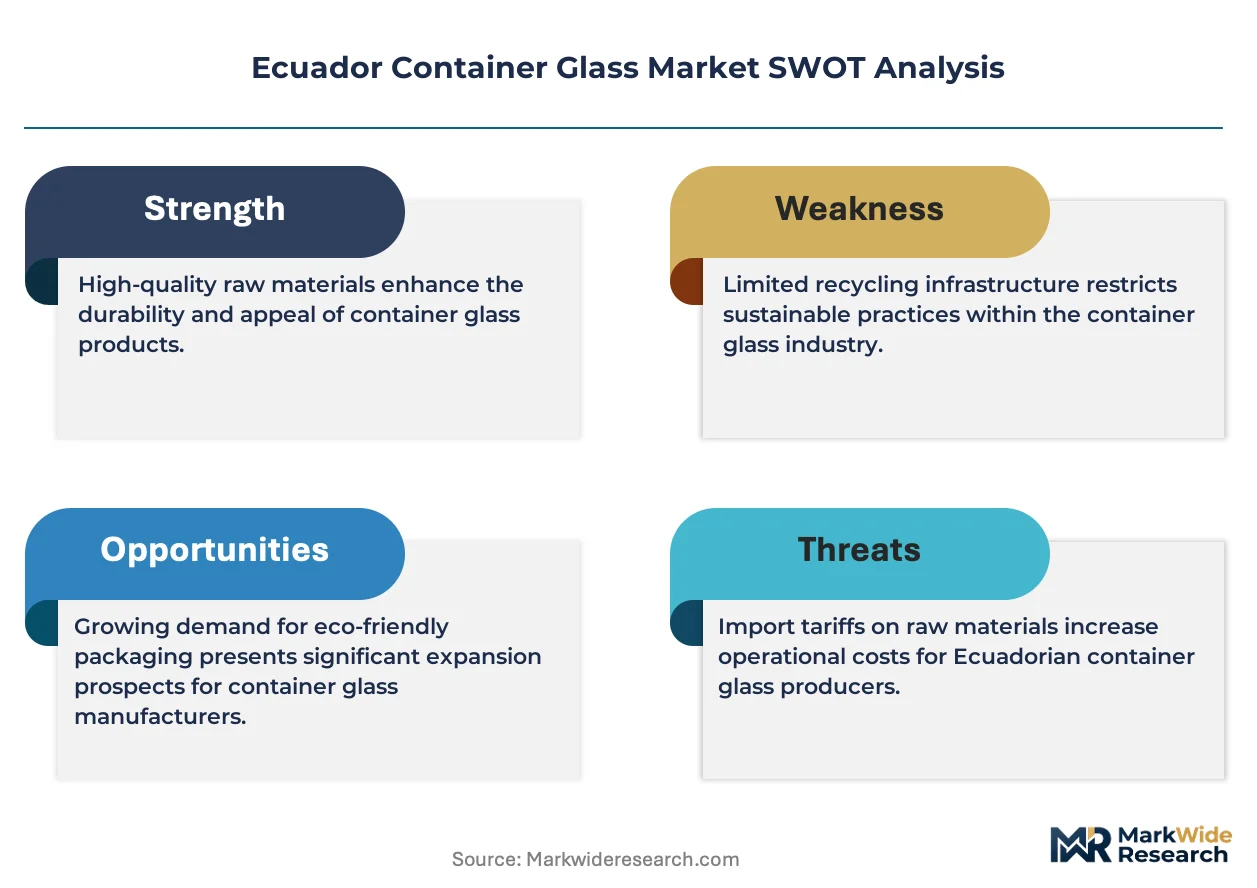
Ecuador's container glass sector faces a structural pivot as the national standards body tightens recyclability mandates while furnace operators absorb oxy-fuel conversion costs. This regulatory-capital squeeze is compressing margins for non-integrated producers and accelerating consolidation around Guayaquil's industrial corridor.
Growth Catalysts
- Extended Producer Responsibility frameworks:Ecuador's environmental regulator is drafting post-consumer collection mandates that would obligate manufacturers to finance reverse logistics networks, creating first-mover advantages for integrated producers with existing cullet processing capabilities.
- Returnable bottle systems:The domestic beverage industry is expanding deposit-return infrastructure for refillable glass formats, driven by carbon footprint reduction commitments from major soft drink and beer processors operating in the coastal zone.
- Pharmaceutical packaging compliance:Ecuador's national pharmaceutical regulator is enforcing material compatibility standards that disqualify certain polymer alternatives, channeling vaccine and injectable demand toward borosilicate and soda-lime glass vials.
Market Restraints
- Natural gas price volatility:Furnace operations depend on imported LNG through Guayaquil's terminal, exposing energy cost structures to international commodity swings that local producers cannot hedge effectively.
- Cullet supply concentration:Post-consumer glass collection remains fragmented across Ecuador's highland provinces, forcing manufacturers to rely on imported recycled material from Colombia and Peru at premium freight rates.
- Aluminum can substitution:Lightweight metal packaging is capturing share in single-serve beverage segments where logistics cost minimization outweighs sustainability premiums for returnable glass.
Strategic Opportunities
- Amazon basin food processing:Emerging agroindustrial clusters in Ecuador's eastern provinces lack proximate packaging supply, creating whitespace for satellite forming operations or mobile bottling services.
- Oxy-fuel furnace retrofits:Technology transfer partnerships with North American equipment suppliers could unlock carbon credit revenues under Ecuador's developing emissions trading framework while reducing NOx compliance burdens.
- Direct-to-processor digital platforms:B2B marketplaces connecting glass manufacturers with mid-sized food processors in Quito and Cuenca are eliminating distributor markups and shortening order-to-delivery cycles.
Industry Challenges
- Furnace refractory engineering expertise:Local technical institutes lack specialized curricula for high-temperature ceramics maintenance, forcing producers to import Brazilian or Mexican specialists at elevated contract rates.
- Batch plant automation integration:Legacy weighing and mixing equipment from the 1990s cannot interface with modern MES platforms, complicating real-time quality traceability required by pharmaceutical customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecuador Container Glass Market |
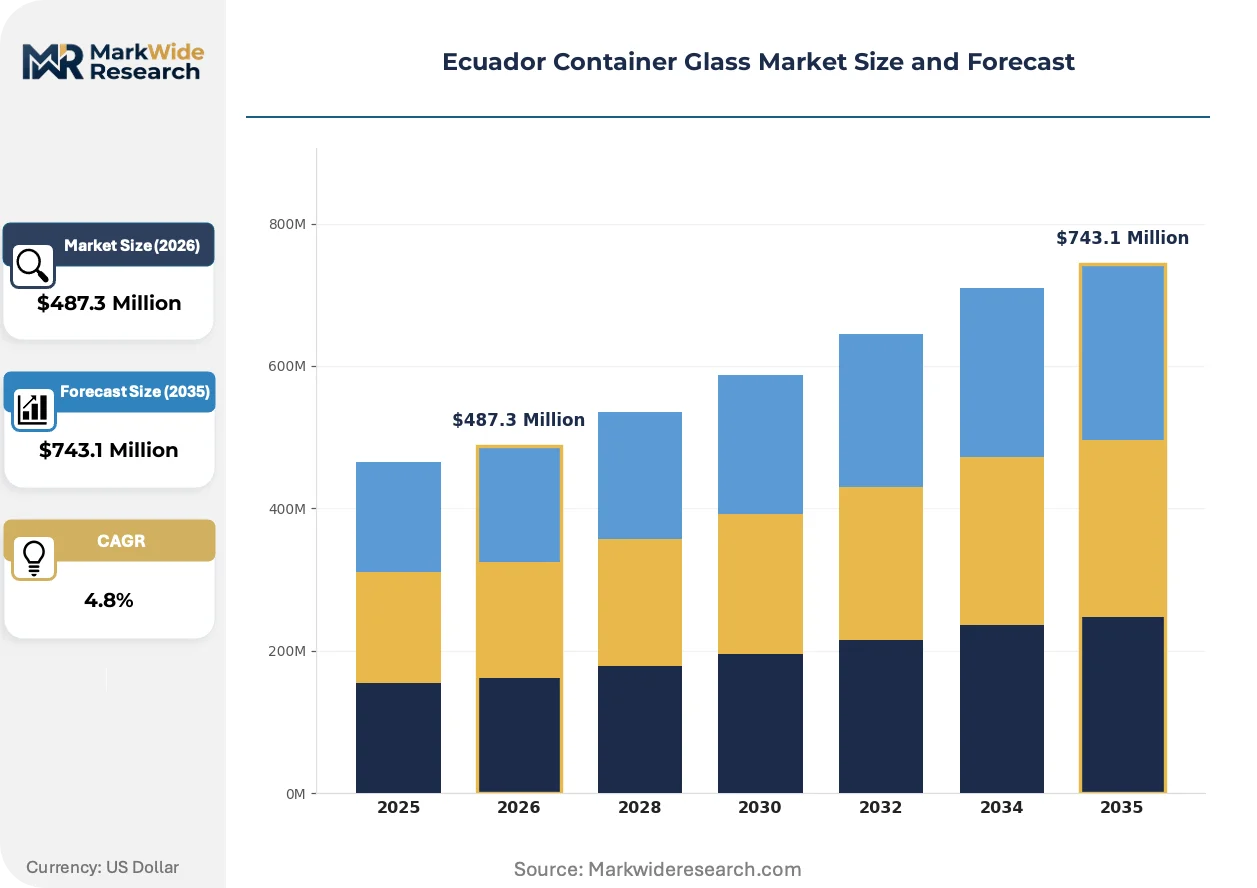
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food Industry, Beverage Industry, Pharmaceuticals, Cosmetics Size: Small, Medium, Large, Extra Large Manufacturing Stage: Raw Materials, Production, Quality Control, Packaging |
| Companies Covered | O-I Glass, Inc., Ecuaenvases Cia Ltda., Vidriera Ecuatoriana, EcuVidrio, Vitro, S.A.B. de CV, Feemio Group Co., Ltd., PSC Products Inc., O-I Cridesa, Botellas del Andes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecuador Container Glass Market Trends and Innovations
Active transformation in Ecuador's container glass sector centers on furnace decarbonization pathways, regulatory compliance digitization, and procurement relationship restructuring. These forces are rewriting capital allocation priorities and competitive differentiation mechanisms.
Electrical boosting technology is converging with traditional fossil-fired melting to create hybrid furnace architectures that reduce carbon intensity without requiring full infrastructure replacement. Pharmaceutical and premium food processors are piloting these configurations to secure supply chain certification for export markets. The structural consequence is a technology gap opening between early adopters with balance sheet capacity and legacy operators facing stranded asset risk.
Ecuador's national standards body is implementing digital traceability mandates for glass containers sold into food channels, requiring serialized batch records accessible to regulators within 48 hours. This compliance burden favors producers with integrated ERP systems and disadvantages smaller forming operations relying on manual documentation. The pharmaceutical segment is responding fastest, with domestic drug packagers already requiring supplier IT integration as a procurement precondition.
Consolidated buying cooperatives among Ecuador's mid-sized juice and sauce processors are displacing fragmented individual procurement arrangements that dominated the 2010s. These purchasing groups negotiate volume commitments across multiple SKUs in exchange for price stability clauses and priority capacity allocation. The coastal food processing belt around Guayaquil exhibits the most advanced cooperative formation, with three buying groups now representing over forty percent of regional container demand.
Ecuador Container Glass Market Segmentation
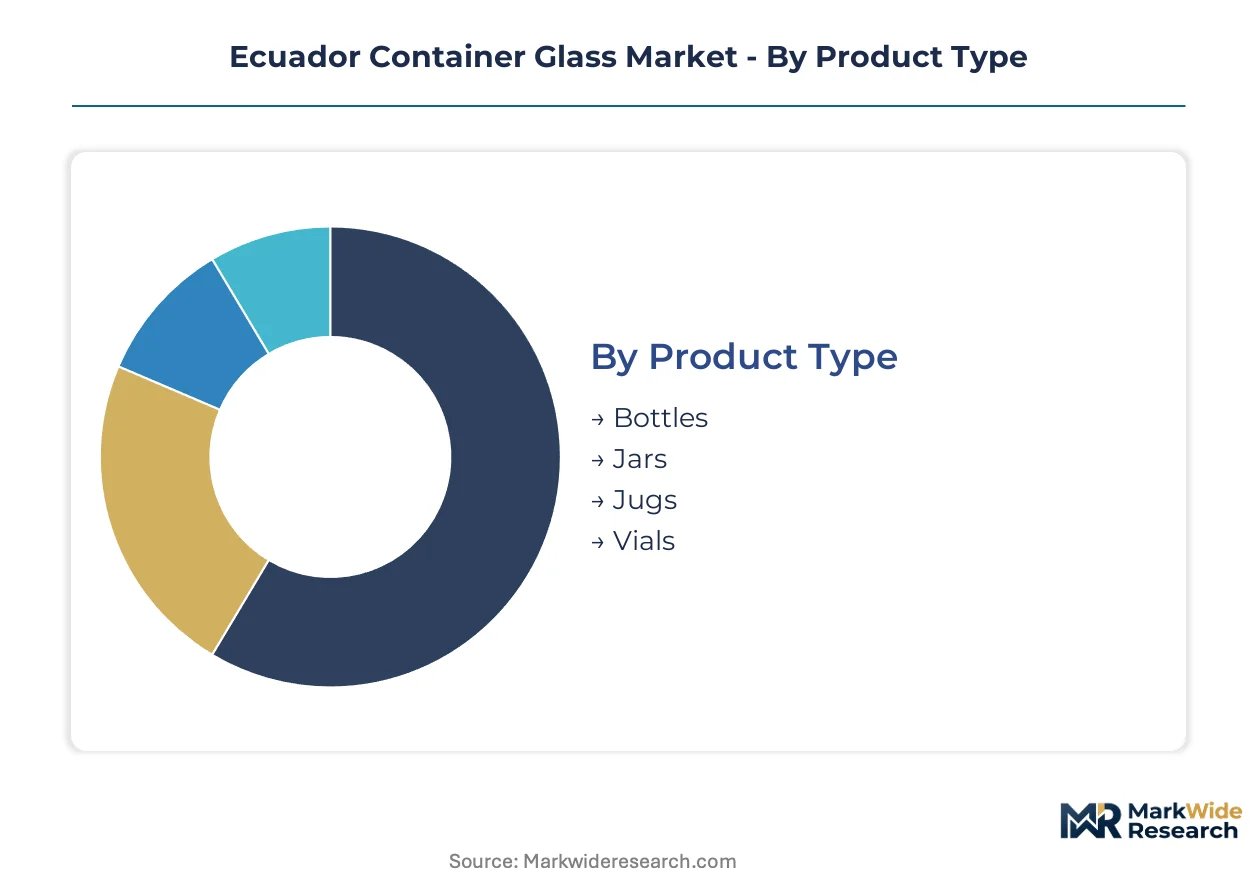
Segmentation in Ecuador's container glass sector reveals how furnace technology, end-use compliance requirements, and logistics economics partition value capture. Understanding these divisions exposes where capital deployment and regulatory exposure concentrate across the production chain.
Product Type:
Bottles operate as standalone packaging systems with established returnable infrastructure, while jars and vials embed into tightly regulated supply chains with stricter material traceability demands.
- Bottles:Hollow vessels formed through blow-and-blow or press-and-blow processes, typically 3-6 millimeter wall thickness, serve as the primary format for carbonated beverages and beer in Ecuador's coastal processing belt. Guayaquil's beverage clusters drive procurement volume for both single-use and returnable formats, with deposit-return systems expanding to meet carbon reduction commitments from major soft drink processors.
- Jars:Wide-mouth containers with threaded finishes accommodate viscous food products and preserves; customized formats for domestic sauce and condiment processors in Quito and Cuenca command premium positioning through shorter production runs and specialized closure compatibility.
- Jugs:Large-capacity containers for edible oils and bulk beverages concentrate demand among industrial food processors seeking reduced packaging cost per liter.
- Vials:Small-diameter borosilicate or soda-lime glass containers for injectable pharmaceuticals face tightening material compatibility standards from Ecuador's national pharmaceutical regulator.
Volume placements concentrate in bottles; the faster expansion belongs to vials.
End User:
Cost tier stratification separates commodity-driven beverage procurement from premium pharmaceutical compliance requirements, with food and cosmetics occupying intermediate positions on specification intensity.
- Food Industry:Processors of sauces, preserves, and edible oils in Ecuador's highland provinces and coastal agroindustrial zones require jar and bottle formats with migration-tested compliance for acidic contents.
- Beverage Industry:Carbonated soft drink and beer manufacturers anchor demand through returnable bottle systems; their deposit-return infrastructure investments lock in supplier relationships and create switching costs for glass producers.
- Pharmaceuticals:Domestic drug packagers are expanding fastest as regulatory material compatibility standards disqualify polymer alternatives for vaccines and injectables, channeling demand toward borosilicate and soda-lime vials with serialized batch traceability.
- Cosmetics:Premium skincare and fragrance brands in Quito's urban corridor source decorated glass with specialized coating and labeling compatibility, representing a margin-accretive niche with lower volume throughput.
Procurement scale peaks with beverages; pharmaceuticals are climbing the fastest.
Size:
Customer type differentiation separates industrial bulk users favoring large formats from retail-channel processors prioritizing shelf-ready small and medium sizes.
- Small:Single-serve and sample formats for pharmaceuticals and premium cosmetics concentrate margin pools through higher unit pricing and lower shipping cost intensity per container.
- Medium:Standard retail sizes for beverages and food products dominate unit volume across Guayaquil's distribution networks.
- Large:Family-size and foodservice formats for edible oils and bulk beverages serve institutional procurement with price-sensitive, high-volume contracting.
- Extra Large:Industrial and export-oriented containers for agroindustrial processors in Ecuador's eastern provinces remain underpenetrated due to logistics constraints.
Unit economics favor small sizes; extra large formats show the steepest expansion trajectory from a low base.
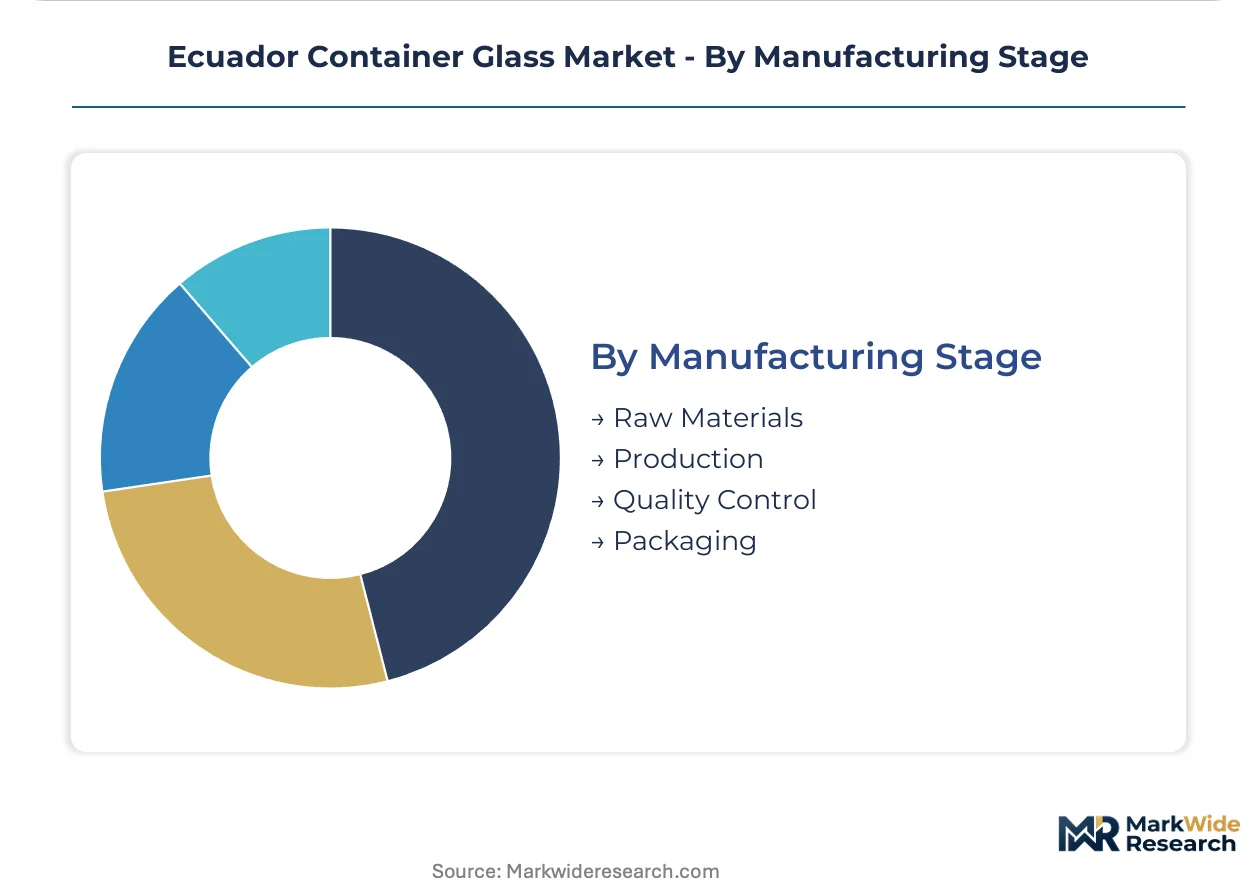
Manufacturing Stage:
Supply concentration varies sharply across the value chain, with raw materials and production stages dominated by integrated incumbents while quality control and packaging stages fragment among specialized service providers.
- Raw Materials:Silica sand, soda ash, and cullet procurement is decoupling from historical single-supplier models; manufacturers now source post-consumer recycled material from Colombia and Peru at premium freight rates due to fragmented domestic collection.
- Production:Batch melting at temperatures exceeding 1,500°C and subsequent forming operations concentrate among furnace operators in Guayaquil's industrial corridor, where O-I Glass and Vidriera Ecuatoriana anchor capacity.
- Quality Control:Automated inspection and material testing services are emerging as a distinct segment as pharmaceutical customers require real-time quality traceability that legacy 1990s-era equipment cannot support.
- Packaging:Palletization, labeling, and logistics coordination fragment among regional distributors and direct-to-processor digital platforms that are eliminating traditional markups.
Capital intensity peaks in production; quality control is gaining share fastest as compliance digitization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guayaquil's industrial corridor concentrates over half of Ecuador's container glass procurement volume through its dense beverage processing clusters and port logistics infrastructure.
Guayaquil Metropolitan Area
Carbonated soft drink and beer manufacturers anchor demand through returnable bottle deposit-return systems. Ecuador's environmental regulator enforces emissions controls on furnace operations that shape capital allocation toward oxy-fuel conversion. The coastal agroindustrial belt surrounding the port city hosts three buying cooperatives now representing over forty percent of regional container procurement.
Quito Highland Corridor
Sauce and condiment processors drive customized jar format demand with specialized closure compatibility requirements. The national standards body mandates recyclability thresholds for glass containers sold into food channels. Pharmaceutical packagers in the capital's urban corridor are expanding fastest as material compatibility standards tighten.
Cuenca Southern Hub
Mid-sized food processors concentrate procurement through direct-to-manufacturer digital platforms eliminating distributor markups. Ecuador's national pharmaceutical regulator enforces serialized batch traceability accessible within 48 hours. The city's artisan food sector sources decorated glass for premium export positioning.
Amazon Basin Frontier
Emerging agroindustrial clusters in Ecuador's eastern provinces lack proximate packaging supply creating whitespace opportunities. Extended producer responsibility legislation under draft would restructure post-consumer collection economics. Mobile bottling services and satellite forming operations represent untested market entry vectors.
Machala-El Oro Coastal Zone
Banana and cocoa processors generate institutional demand for large-capacity edible oil and bulk beverage containers. Natural gas price volatility through Guayaquil's LNG terminal exposes energy cost structures to international commodity swings. Logistics constraints limit extra-large format penetration despite price-sensitive high-volume contracting.
Ecuador Container Glass Market Competitive Landscape
Capacity expansion dominates the current landscape as furnace operators absorb oxy-fuel conversion costs to meet tightening emissions controls. The sector exhibits moderate consolidation around Guayaquil's industrial corridor where integrated producers with cullet processing capabilities command first-mover advantages. Two strategic archetypes define positioning: multinational technology transfer specialists leveraging North American furnace modernization programs, and domestic proximity-focused operators optimizing port logistics for raw material inbound. Competitive moves center on regulatory compliance digitization and multi-source procurement restructuring away from historical single-supplier models.
Among multinational anchors, O-I Glass, Inc. and O-I Cridesa exemplify the technology transfer archetype through furnace modernization investments. Domestic specialists Ecuaenvases Cia Ltda. and Vidriera Ecuatoriana occupy positions shaped by proximity to Guayaquil's port logistics and customized format capabilities for regional food processors. These four entities represent the core competitive set, with Vitro, S.A.B. de C.V. and Feemio Group Co., Ltd. serving as secondary references for cross-border supply relationships.
| Leading Market Players |
|---|
| O-I Glass, Inc. |
| Ecuaenvases Cia Ltda. |
| Vidriera Ecuatoriana |
| EcuVidrio |
| Vitro, S.A.B. de CV |
| Feemio Group Co., Ltd. |
| PSC Products Inc. |
| O-I Cridesa |
| Botellas del Andes |
| Others |
Pricing and Supply Chain Analysis
Backward integration into cullet processing anchors both supply security and pricing power for Ecuador's integrated furnace operators, while non-integrated competitors absorb premium freight costs for imported recycled material from Colombia and Peru. This structural divide concentrates margin capture among Guayaquil's industrial corridor incumbents who control post-consumer collection economics.
Pricing Analysis
After-sales service bundling separates furnace operators offering technical maintenance contracts from pure product suppliers competing on unit price alone. Contract-based long-term offtake agreements dominate procurement relationships between beverage processors and glass manufacturers, with price differentiation driven by certification grade for pharmaceutical compliance and volume scale for food industry buyers. Cost compression in standard beverage bottles is intensifying because aluminum can substitution erodes sustainability premiums previously captured by returnable glass. Small pharmaceutical vials exhibit the lowest price sensitivity due to material compatibility mandates, while bulk edible oil containers face the highest buyer price sensitivity.
Supply Chain Analysis
Dual-sourcing qualification requirements now mandate that Ecuadorian manufacturers certify both Colombian and Peruvian cullet suppliers to mitigate single-source vulnerability. Silica sand extraction concentrates in domestic highland quarries near Quito, while soda ash supply draws from Chilean and Peruvian chemical producers. Natural gas price volatility through Guayaquil's LNG terminal creates commodity exposure that local producers cannot hedge effectively. Distribution runs through port logistics clusters and direct-to-processor digital platforms eliminating traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ecuador's container glass sector is consolidating around oxy-fuel conversion investments that weaker balance sheets cannot fund. The national environmental regulator's tightening emissions controls are accelerating this winnowing.
For Market Incumbents: Deepen captive supply of post-consumer cullet through collection infrastructure investments in Guayaquil's coastal zone, securing first-mover advantage under extended producer responsibility frameworks. Expand furnace capacity with hybrid electric boosting technology to capture carbon credit revenues and defend against stranded asset risk from legacy fossil-fired assets. For New Entrants and Emerging Players: Mobile bottling services represent the most penetrable wedge for Amazon basin food processors lacking proximate packaging supply. Target satellite forming operations in Ecuador's eastern provinces where logistics constraints have left extra-large format demand unserved, using direct digital procurement platforms to bypass established distributor networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of mid-sized domestic jar specialists with pharmaceutical certification capabilities and proximity to Quito's highland food processing corridor. Long-term viability favors operators with integrated ERP systems capable of meeting serialized batch traceability mandates within 48 hours. Watch for inflection when extended producer responsibility legislation restructures post-consumer collection economics.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | Reduces NOx emissions for compliance with Ecuador's environmental regulator mandates while unlocking carbon credit revenues. |
| Backward Integration into Cullet Processing | Captures post-consumer collection economics and insulates margins from Colombian and Peruvian import premiums. |
| Pharmaceutical Certification Investment | Qualifies supply for domestic drug packagers facing tightening material compatibility standards from Ecuador's national pharmaceutical regulator. |
| Direct-to-Processor Digital Platform | Eliminates distributor markups for mid-sized food processors in Cuenca and shortens order-to-delivery cycles. |
| Hybrid Electric Boosting Pilot | Secures supply chain certification for export-oriented pharmaceutical and premium food processors in Quito's urban corridor. |
Research Methodology
Multi-period observation of furnace utilization rates, cullet import volumes, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with plant managers at Guayaquil's integrated producers, procurement leads at coastal beverage processors, technical R&D directors from North American equipment suppliers, and distribution channel partners serving Quito's highland corridor. Secondary validation drew from Ecuador's national standards body publications, environmental regulator emissions disclosures, customs records tracking soda ash and cullet imports, and SEC filings from multinational anchor operators. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, end user, size, and manufacturing stage dimensions structured the analytical framework across the projection horizon. CAGRs were derived from elasticity modeling against beverage industry volume growth and pharmaceutical packaging compliance expansion. Industry-specific forecast inputs included natural gas price scenarios through Guayaquil's LNG terminal and oxy-fuel conversion capital expenditure pipelines.
Several conditions sit outside the modeled scope, including specific timing of extended producer responsibility legislation passage and potential aluminum can substitution acceleration in single-serve segments. Deviation in natural gas price volatility or regulatory enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Spain Packaging Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
Saudi Arabia Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Hungary Container Glass Market