
 Japan Container Glass Market | 2026-2036
Japan Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Container Glass Market Foresight
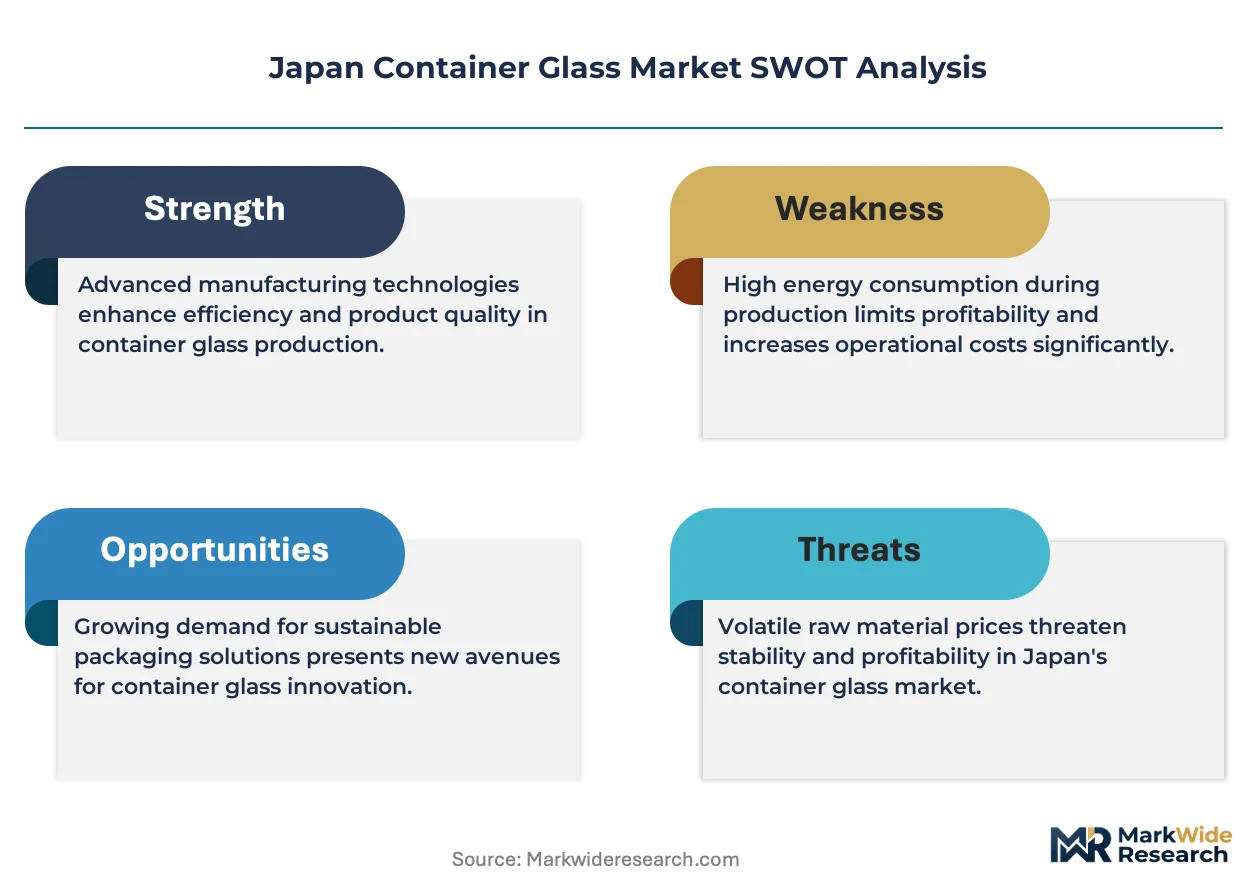
Japan's aging glassblower workforce is collapsing faster than automated blow molding lines can offset, tightening supply for premium decorated bottles. Nihon Yamamura Glass Co., Ltd. leverages its Kobe-area furnaces to dominate pharmaceutical vial output for domestic drugmakers. Toyo Glass Co., Ltd. sustains leadership in lightweight beer bottles through continuous R&D on thin-wall forming technology. Ishizuka Glass Co., Ltd. specializes in custom-embossed sake bottles that command premium positioning among regional brewers.
Container glass comprises silica-soda-lime formulations shaped by blow or press molding into hollow receptacles for liquid and semi-solid storage, with wall thickness typically ranging from 2 to 8 millimeters depending on internal pressure and thermal shock requirements. The material's chemical inertness and impermeability make it indispensable for oxygen-sensitive contents across food, pharmaceutical, and cosmetic applications. Glass bottles anchor the product mix as the mature volume base, while vials capture concentrated margin pools from Japan's expanding biologics fill-finish sector. Custom and decorated design types outpace standard formats as craft beverage brands seek shelf differentiation in convenience store and duty-free channels.
METI enforces energy-efficiency benchmarks for glass melting furnaces under the Act on Rationalizing Energy Use, pushing manufacturers toward electric boosting and oxy-fuel conversions. The Container and Packaging Recycling Law mandates minimum recycled content thresholds, directly shaping cullet sourcing strategies and furnace batch chemistry. JIS standards govern thermal shock resistance and dimensional tolerances for pharmaceutical and food-contact applications, creating compliance barriers for imported alternatives. Stakeholders must weigh furnace rebuild cycles against emerging deposit-return obligations and bioplastics substitution threats in non-premium beverage segments.
Market Dynamics
METI's furnace efficiency mandates and the Container and Packaging Recycling Law are compressing manufacturing economics while premium beverage brands pull for decorated, small-batch output that resists automation.
Growth Catalysts
- Carbon neutrality roadmap:METI's emission benchmarks push oxy-fuel and electric boosting retrofits, creating upgrade demand for furnace engineering services and batch chemistry optimization.
- Biologics fill-finish expansion:Domestic pharmaceutical vial output is climbing as PMDA accelerates biosimilar approvals and cold-chain infrastructure hardens around Tokyo and Osaka.
- Tohoku craft spirits cluster:Regional sake and shochu distillers are commissioning embossed and screen-printed bottles for duty-free and convenience store premium placement.
Market Restraints
- Natural gas price volatility:Melting furnace operations depend on LNG feedstock whose price swings directly compress margin on standard container output.
- Glassblower labor collapse:Artisan decorating skills are vanishing faster than robotic cold-end handling can replicate hand-embossed and applied-color labels.
- Bioplastics substitution:Non-premium beverage segments are trialing PLA and bio-PET for single-use bottles under retailer sustainability scorecards.
Strategic Opportunities
- Kyushu pharmaceutical corridor:Underdeveloped vial supply relative to Fukuoka's biotech manufacturing growth creates greenfield furnace investment potential.
- Deposit-return system preparation:Anticipated revisions to recycling law obligations favor early investment in cullet sorting and closed-loop batch systems.
- Lightweight thin-wall beer bottles:Advanced press-blow and vacuum-assisted forming technologies enable gram-weight reductions that satisfy brewer freight cost targets.
Industry Challenges
- Furnace rebuild cycle compression:Energy-efficiency mandates force mid-life rebuilds that strain capex planning and disrupt multi-year supply contracts.
- JIS thermal shock certification:Pharmaceutical vial approvals require extended testing timelines that delay new product launches and contract wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Container Glass Market |
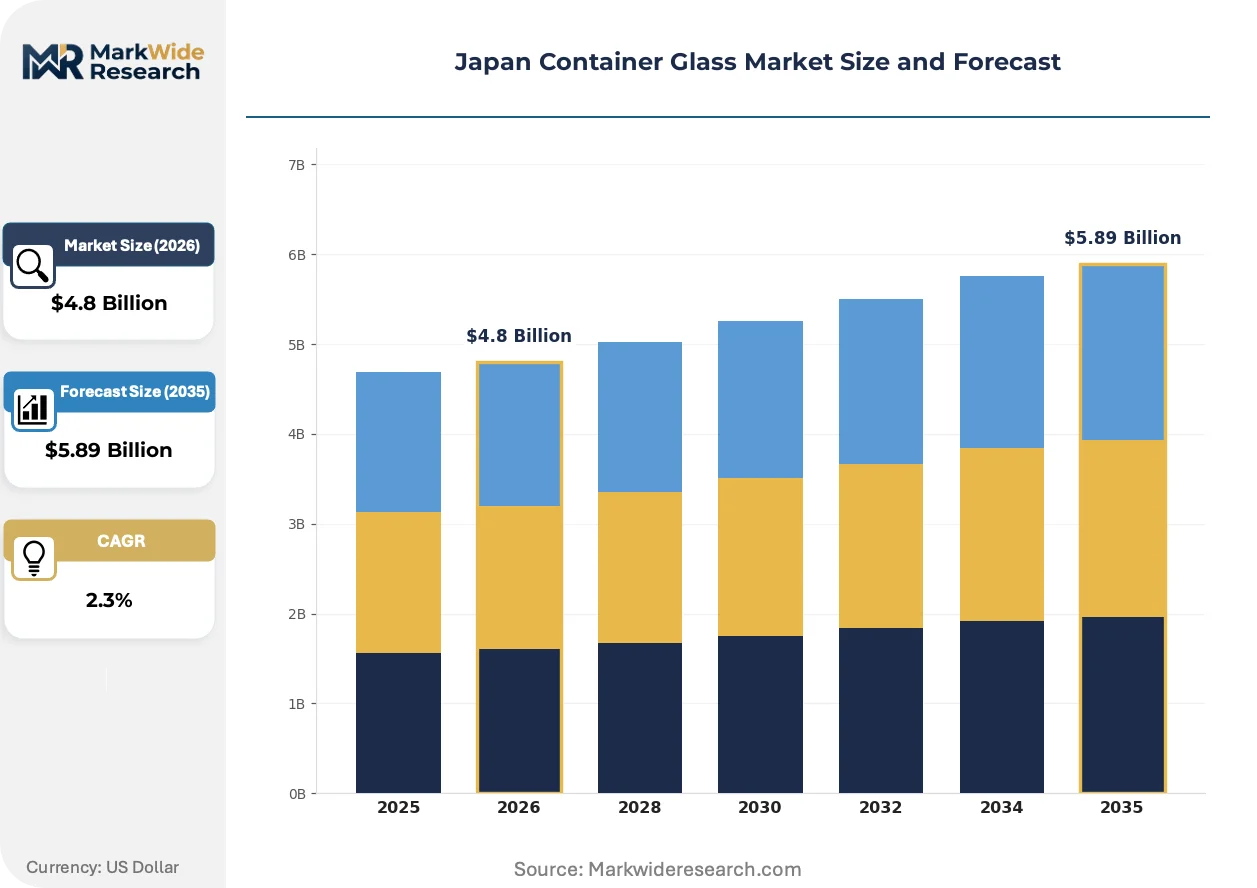
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Bottles, Jars, Vials, Tumblers End Use: Food & Beverage, Personal Care, Pharmaceuticals, Household Design Type: Standard, Custom, Decorated, Multi-layered Manufacturing Process: Blow Molding, Press Molding, Casting, Automatic Filling |
| Companies Covered | Nihon Yamamura Glass Co., Ltd., Toyo Glass Co., Ltd., Japan Seiko Glass Co., Ltd., KOA Glass Co., Ltd., Nihon Taisanbin Glass Bottle MFG Co., Ltd., Ishizuka Glass Co., Ltd., Okubo Glass Co., Ltd., DAI-ICHI GLASS CO., LTD., DAISHO GLASS Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Container Glass Market Shifts & Advancements
Digital decoration and forming technologies are fragmenting the traditional tradeoff between mass-production efficiency and premium customization capability.
Oxy-fuel combustion with electric boosting is decomposing the historical dominance of air-fuel regenerative furnaces in Japanese container glass manufacturing. Mid-cap breweries and pharmaceutical contract manufacturers are specifying these retrofits for new supply agreements. The technology is decomposing capital barriers that once separated commodity bottle producers from premium decorated specialists.
METI's Act on Rationalizing Energy Use is tightening furnace efficiency benchmarks through 2030 compliance windows. Manufacturers face accelerated rebuild cycles or penalties that reshape long-term depreciation schedules. Pharmaceutical vial producers in the Kanto corridor are prioritizing electric boosting to secure energy cost predictability.
Direct-to-distiller design services are displacing traditional trading company intermediaries in sake bottle procurement. Regional brewers in Niigata and Kyoto are contracting directly with mold shops and decorators for limited-run embossed designs. This channel compression is most visible in premium ginjo and daiginjo segments where shelf differentiation commands price premiums in Tokyo department store retail.
Japan Container Glass Market Segmentation
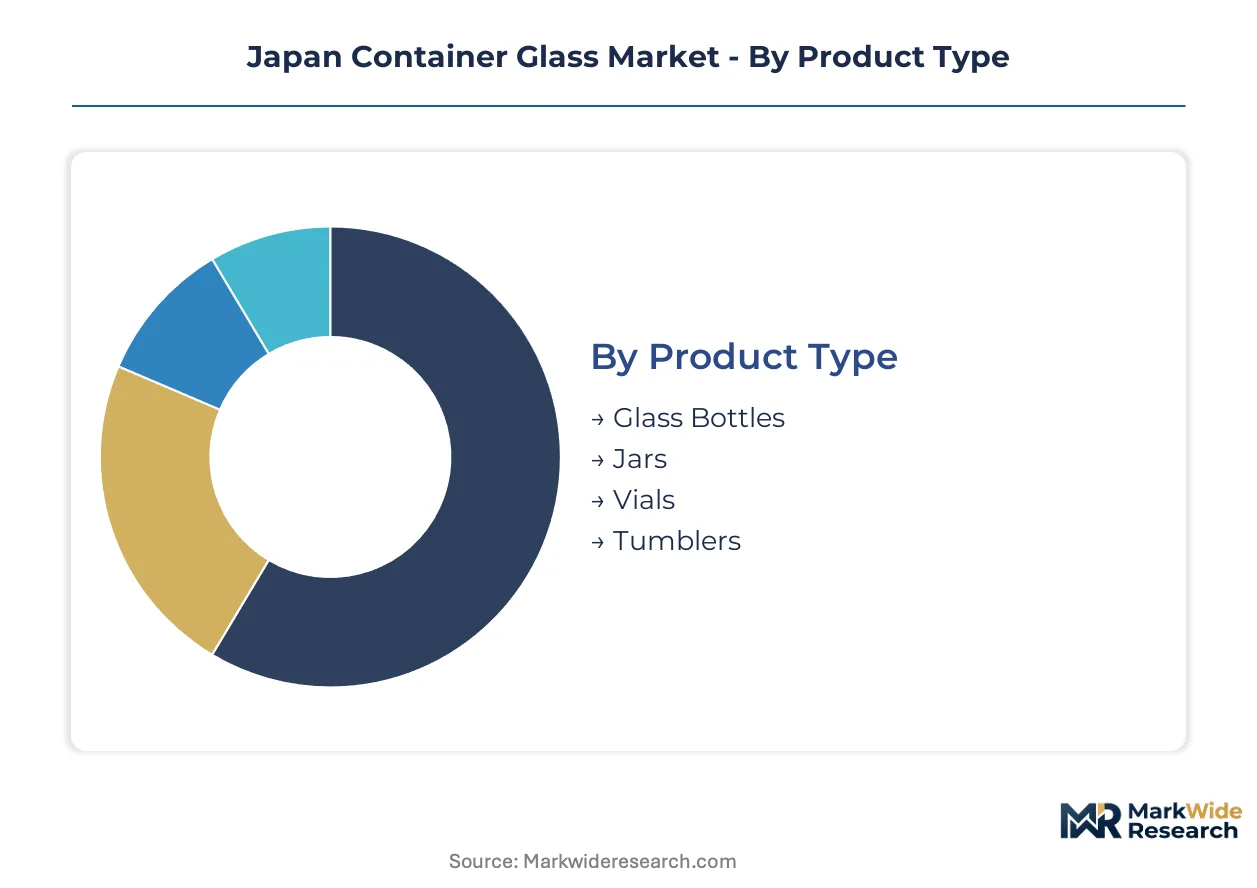
Container glass demand in Japan fragments across four distinct category axes, each mapping to divergent margin pools and furnace utilization profiles. Understanding these splits clarifies where METI efficiency mandates bite hardest and where premium customization commands pricing power.
Product Type:
Margin concentration sits with pharmaceutical-grade vials and premium beverage bottles, while commodity jars and tumblers compete on throughput scale.
- Glass Bottles:Silica-soda-lime formulations shaped by blow or press molding serve beer, sake, and spirits producers across the Tohoku craft cluster. Demand concentrates in lightweight thin-wall variants as brewers target freight cost reductions for export channels.
- Vials:Borosilicate and neutral glass formulations meet JIS thermal shock standards for biologics fill-finish operations. PMDA's accelerating biosimilar approvals are pulling output toward the Kanto corridor where cold-chain infrastructure clusters near Tokyo port facilities.
- Jars:Wide-mouth containers for pickled vegetables and condiments dominate standard food packaging with thinner margin profiles.
- Tumblers:Drinking vessels and cosmetic containers represent mature volume with limited differentiation potential.
The dominant share belongs to glass bottles, while vials are closing the gap fastest on margin contribution per furnace hour.
End Use:
Application mix determines regulatory exposure, with pharmaceuticals facing PMDA oversight and food-contact segments navigating FSSAI-aligned import standards for raw material traceability.
- Food & Beverage:Beer, sake, and soft drink bottling absorbs the largest furnace capacity share, with craft spirits in Niigata and Kyoto driving embossed and screen-printed specifications.
- Pharmaceuticals:Biologics vial demand is expanding most quickly as domestic fill-finish capacity hardens around Osaka and Fukuoka biotech manufacturing zones.
- Personal Care:Cosmetic bottles and jars for department store channels command premium positioning through direct-to-brand design services.
- Household:Storage containers and decorative vessels represent price-sensitive replacement demand with minimal customization.
Food and beverage retains volume leadership, though pharmaceuticals is gaining share fastest on per-unit value.
Design Type:
Customer procurement patterns split between automated high-speed lines favoring standard formats and craft distillers commissioning limited runs that resist economies of scale.
- Decorated:Applied-color labels, embossing, and screen-printing serve premium sake and craft spirits producers targeting duty-free and convenience store placement. Regional brewers in the Tohoku cluster are contracting directly with mold shops, compressing traditional trading company channels.
- Custom:Bespoke mold development for limited-edition releases commands pricing premiums that offset slower line speeds.
- Standard:Undecorated bottles for mass-market beer and soft drinks maximize furnace throughput.
- Multi-layered:Laminated barrier constructions for oxygen-sensitive contents remain niche in pharmaceutical applications.
Standard formats dominate unit volume, yet decorated designs are expanding most quickly as shelf differentiation becomes a priority lever for regional brewers.
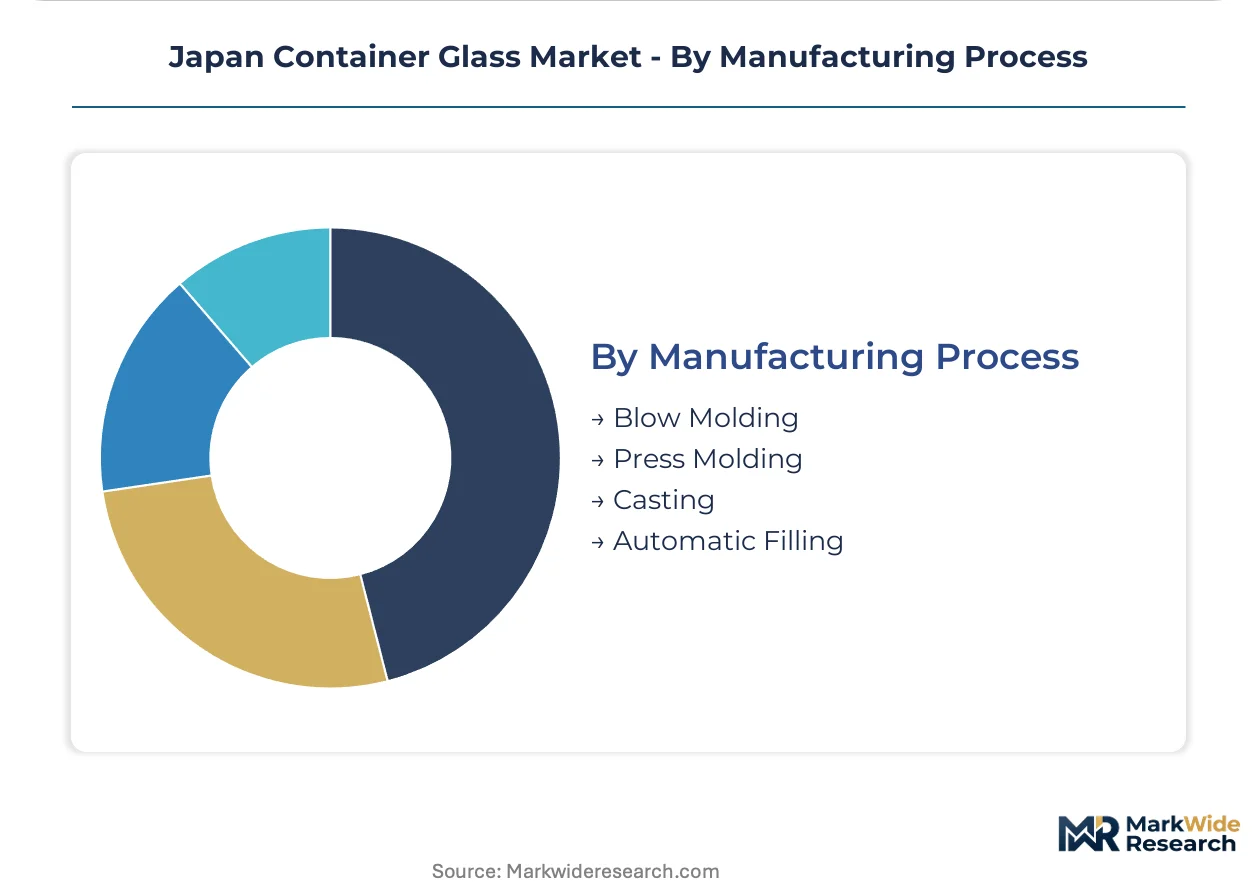
Manufacturing Process:
Technology selection maps directly to METI energy-efficiency compliance timelines, with oxy-fuel retrofits reshaping capital allocation across the furnace base.
- Blow Molding:Press-blow and blow-blow forming for hollow containers dominates beer and beverage output, with vacuum-assisted thin-wall technologies enabling gram-weight reductions.
- Press Molding:Direct pressing for wide-mouth jars and cosmetic containers offers dimensional precision but slower cycle speeds.
- Casting:Specialty glass pouring for heavy decorative pieces serves limited artisan markets.
- Automatic Filling:Integrated blow-fill-seal lines for pharmaceutical vials reduce particulate contamination risk in cleanroom environments.
Blow molding commands the installed base, while automatic filling is climbing the fastest as pharmaceutical contract manufacturers specify integrated contamination control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's container glass consumption fragments across distinct regional industrial bases, with pharmaceutical vial demand concentrating near Tokyo while craft beverage bottling clusters in northern prefectures. Each sub-region deploys furnace capacity toward divergent end-use priorities shaped by local manufacturing heritage and infrastructure access.
Kanto/Tokyo
Pharmaceutical vial output dominates Kanto furnace utilization as PMDA's accelerating biosimilar approvals pull fill-finish operations toward Tokyo and Yokohama port facilities. METI's carbon neutrality roadmap enforces oxy-fuel retrofits on aging furnaces in the Keihin industrial belt. Cold-chain infrastructure hardening around Narita and Haneda airports is expanding borosilicate vial demand for temperature-sensitive biologics exports.
Kansai/Osaka
Beer and spirits bottling absorbs the largest Kansai furnace share, with lightweight thin-wall technologies enabling freight cost reductions for export-bound brewers. The Container and Packaging Recycling Law mandates minimum recycled content thresholds that reshape cullet sourcing from Osaka's dense urban collection networks. Sakai and Amagasaki industrial zones host integrated blow-mold lines serving both domestic convenience store channels and Asian export markets.
Tohoku
Premium sake distillers in Niigata and Yamagata prefectures are commissioning embossed and screen-printed bottles for duty-free and Tokyo department store placement. Direct-to-distiller procurement patterns are compressing traditional trading company intermediaries in regional supply chains. Artisan decorating skills are vanishing faster than robotic cold-end handling can replicate hand-finished designs for limited-run ginjo releases.
Kyushu
Underdeveloped vial supply relative to Fukuoka's biotech manufacturing growth creates greenfield furnace investment potential in the northern Kyushu pharmaceutical corridor. Biologics contract manufacturers are specifying integrated blow-fill-seal lines to reduce particulate contamination risk. Local government incentives under the national regional revitalization framework are attracting pharmaceutical packaging investors away from saturated Kanto capacity.
Chubu/Nagoya
Automotive-linked chemical and cosmetic container demand sustains Chubu furnace operations through Nagoya's manufacturing supply chain density. Press-molded wide-mouth jars for industrial sealants and coatings represent stable volume with thinner margin profiles than pharmaceutical or beverage segments. Toyota-area logistics infrastructure enables just-in-time delivery schedules that favor local container sourcing over distant Kanto or Kansai alternatives.
Japan Container Glass Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with furnace-scale advantages separating commodity bottle producers from premium decorated specialists. The upper tier commands pharmaceutical vial contracts and lightweight beer bottle supply agreements through continuous R&D investment. Mid-cap players occupy niche positions in custom-embossed sake bottles and regional craft spirits packaging. Competitive moves center on oxy-fuel furnace retrofits for METI compliance and direct-to-brand design services that displace trading company intermediaries.
Among Kobe-area fabricators, Nihon Yamamura Glass Co., Ltd. anchors the pharmaceutical vial segment through furnace proximity to domestic drugmakers. Toyo Glass Co., Ltd. exemplifies the lightweight technology leader archetype with thin-wall forming capabilities for brewer freight cost targets. Ishizuka Glass Co., Ltd. occupies the custom decoration specialist position, serving regional sake producers seeking shelf differentiation in premium retail channels.
| Leading Market Players |
|---|
| Nihon Yamamura Glass Co., Ltd. |
| Toyo Glass Co., Ltd. |
| Japan Seiko Glass Co., Ltd. |
| KOA Glass Co., Ltd. |
| Nihon Taisanbin Glass Bottle MFG Co., Ltd. |
| Ishizuka Glass Co., Ltd. |
| Okubo Glass Co., Ltd. |
| DAI-ICHI GLASS CO., LTD. |
| DAISHO GLASS Co., Ltd. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Kanto pharmaceutical manufacturers and domestic furnace operators lock in borosilicate vial supply while insulating buyers from natural gas price swings that buffet spot-market beer bottle transactions. These agreements embed minimum volume commitments and energy-cost pass-through clauses that reshape capex planning for METI-mandated oxy-fuel retrofits.
Pricing Analysis
Contract-based long-term offtake dominates pharmaceutical vial procurement, while spot transactions govern commodity beer and soft drink bottles. Price differentiation rests on JIS thermal shock certification tiers and customization depth for embossed sake designs. Cost compression in standard beverage containers is intensifying because LNG feedstock volatility feeds directly into furnace operating economics. Mass-market brewers exhibit acute price sensitivity, whereas premium craft distillers absorb higher per-unit costs for decorated limited runs.
Supply Chain Analysis
Just-in-time delivery schedules prevail among Kanto pharmaceutical contract manufacturers, while strategic stockpiling of silica sand and soda ash concentrates in Kansai buffers against maritime logistics disruptions. Raw material sourcing draws from Australian high-purity silica, Chinese soda ash, and domestic limestone deposits. Single-source vulnerability concentrates in boron compounds for borosilicate formulations. Distribution runs through integrated trading company networks that are compressing as regional sake brewers contract directly with mold shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's container glass market operates as a substitution defense against bioplastics encroachment in non-premium beverage segments, where PLA and bio-PET trials threaten volume foundations. Incumbents must navigate this material transition while preserving premium decorated positioning that resists polymer alternatives.
For Market Incumbents: Secure oxy-fuel furnace retrofit completion ahead of METI's tightening efficiency windows to preserve pharmaceutical vial contract eligibility. Deepen backward integration into cullet sorting infrastructure to satisfy Container and Packaging Recycling Law thresholds and defend margin position against imported glass alternatives.
For New Entrants and Emerging Players: Direct-to-distiller design services represent the most penetrable white-space target, as regional sake producers in Niigata and Yamagata seek shelf differentiation without trading company intermediaries. Kyushu's underdeveloped vial supply relative to Fukuoka biotech growth offers greenfield furnace investment potential with local government incentives.
For Investors and Strategic Acquirers: Custom decoration specialists with captive mold shop relationships and established artisan embossing capabilities present the most defensible acquisition profile. Long-term viability hinges on biologics fill-finish expansion sustaining pharmaceutical vial demand against bioplastics substitution in beverage segments. Watch for deposit-return system legislation revisions as the inflection indicator that would revalue closed-loop cullet processing assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | METI compliance secures pharmaceutical vial contract eligibility and energy cost predictability. |
| Direct-to-Distiller Design Service | Channel compression captures premium positioning margins from regional sake and craft spirits producers. |
| Cullet Sorting Infrastructure Investment | Closed-loop batch systems anticipate Container and Packaging Recycling Law deposit-return obligations. |
| Lightweight Thin-Wall Technology Deployment | Gram-weight reductions satisfy brewer freight cost targets for export-bound beer shipments. |
| Kyushu Pharmaceutical Corridor Expansion | Greenfield furnace capacity addresses Fukuoka biotech manufacturing growth with local incentive support. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with pharmaceutical fill-finish engineers, sake brewery procurement managers, furnace operations directors, and cold-chain logistics specialists. Secondary validation incorporated METI energy-efficiency filings, PMDA biosimilar approval databases, JIS thermal shock certification records, and customs trade data on silica sand imports. Bottom-up furnace capacity modeling and top-down pharmaceutical vial demand estimation were triangulated to cross-verify volume outputs.
Across the analysis window, projections integrated product type segmentation by glass bottles, vials, jars, and tumblers; end-use splits across food and beverage, pharmaceuticals, personal care, and household; design type differentiation between standard, decorated, custom, and multi-layered formats; and manufacturing process variation across blow molding, press molding, casting, and automatic filling. CAGRs were derived from furnace utilization trends, biologics pipeline expansion rates, and craft spirits bottling capacity additions.
Forecasts assume regulatory continuity in METI carbon neutrality enforcement and Container and Packaging Recycling Law obligations; material policy shifts would require re-modeling. Revision becomes warranted when bioplastics substitution rates in mass-market beverages or natural gas price volatility crosses thresholds that alter furnace economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Cameroon Container Glass Market