
 Philippines Container Glass Market | 2026-2036
Philippines Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Container Glass Market Insights
Food and beverage bottling is broadening its share of container glass offtake as Filipino craft distilleries, coconut oil processors, and specialty sauce producers shift from plastic to glass. San Miguel Yamamura Packaging Corporation leverages its integrated brewing and packaging footprint to dominate domestic supply. Owens-Illinois Inc. sustains technical leadership through advanced lightweighting technology for premium spirits bottles. Manila Glass Manufacturing Co. anchors provincial distribution networks across Luzon and Visayas.
Container glass comprises silica sand, soda ash, limestone, and cullet melted at approximately 1,500 degrees Celsius to form rigid, chemically inert vessels for liquid and solid storage. The material offers zero permeability, UV protection, and infinite recyclability without quality degradation, making it indispensable for oxygen-sensitive and light-degradable contents. Bottles command the largest volume share across product types, driven by beverage and pharmaceutical liquid packaging requirements. Recyclable packaging types capture margin premiums as EPR compliance costs reshape procurement criteria among multinational brands operating in the Philippines.
The Department of Environment and Natural Resources administers extended producer responsibility regulations that mandate post-consumer collection targets for glass packaging producers. The Food and Drug Administration enforces pharmacopeial standards for pharmaceutical vials and containers, restricting import substitution in drug packaging. The Bureau of Product Standards certifies glass thermal shock resistance for hot-fill food applications. Stakeholders must monitor EPR enforcement intensity and FDA harmonization with ASEAN common technical dossiers to anticipate compliance cost trajectories and local content advantages.
Market Dynamics
Extended producer responsibility enforcement by the Department of Environment and Natural Resources is compressing operating margins while accelerating facility consolidation around Metro Manila and Cebu manufacturing corridors. This regulatory pressure is reshaping procurement criteria for multinational food and beverage brands.
Growth Catalysts
- EPR Compliance Mandates:The Department of Environment and Natural Resources enforces post-consumer collection targets that redirect procurement toward certified recyclable glass formats.
- Craft Distillery Expansion:Filipino specialty spirits producers are converting bottling lines from polyethylene terephthalate to amber and flint glass for premium positioning.
- Lightweighting Technology:Advanced mold engineering reduces per-unit silica consumption and furnace fuel intensity, lowering landed costs for export-bound pharmaceutical vials.
Market Restraints
- Soda Ash Import Dependency:The Philippines lacks domestic soda ash production, exposing manufacturers to freight volatility from Chinese and Turkish suppliers.
- Furnace Rebuild Cycles:Glass melting furnaces require cold repair every 10-12 years, demanding capital outlays that strain mid-scale producers.
- Flexible Packaging Substitution:Retort pouches and aseptic cartons capture shelf-stable food segments where glass once dominated, particularly in coconut milk distribution.
Strategic Opportunities
- Visayas Provincial Penetration:Cebu and Iloilo bottling corridors remain undersupplied relative to Luzon concentration, creating white space for distributed mold capacity.
- Pharmaceutical Serialization:The Food and Drug Administration's track-and-trace mandates favor glass vials with integrated marking compatibility.
- Cullet Recovery Infrastructure:Municipal collection partnerships in Davao and Cagayan de Oro can secure feedstock advantages under EPR credit mechanisms.
Industry Challenges
- Refractory Engineering Talent:Specialized furnace maintenance expertise concentrates among aging technical workforces in Bulacan and Laguna.
- Hot-Fill Certification Timelines:Bureau of Product Standards thermal shock testing creates 4-6 month approval delays for seasonal sauce launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Container Glass Market |
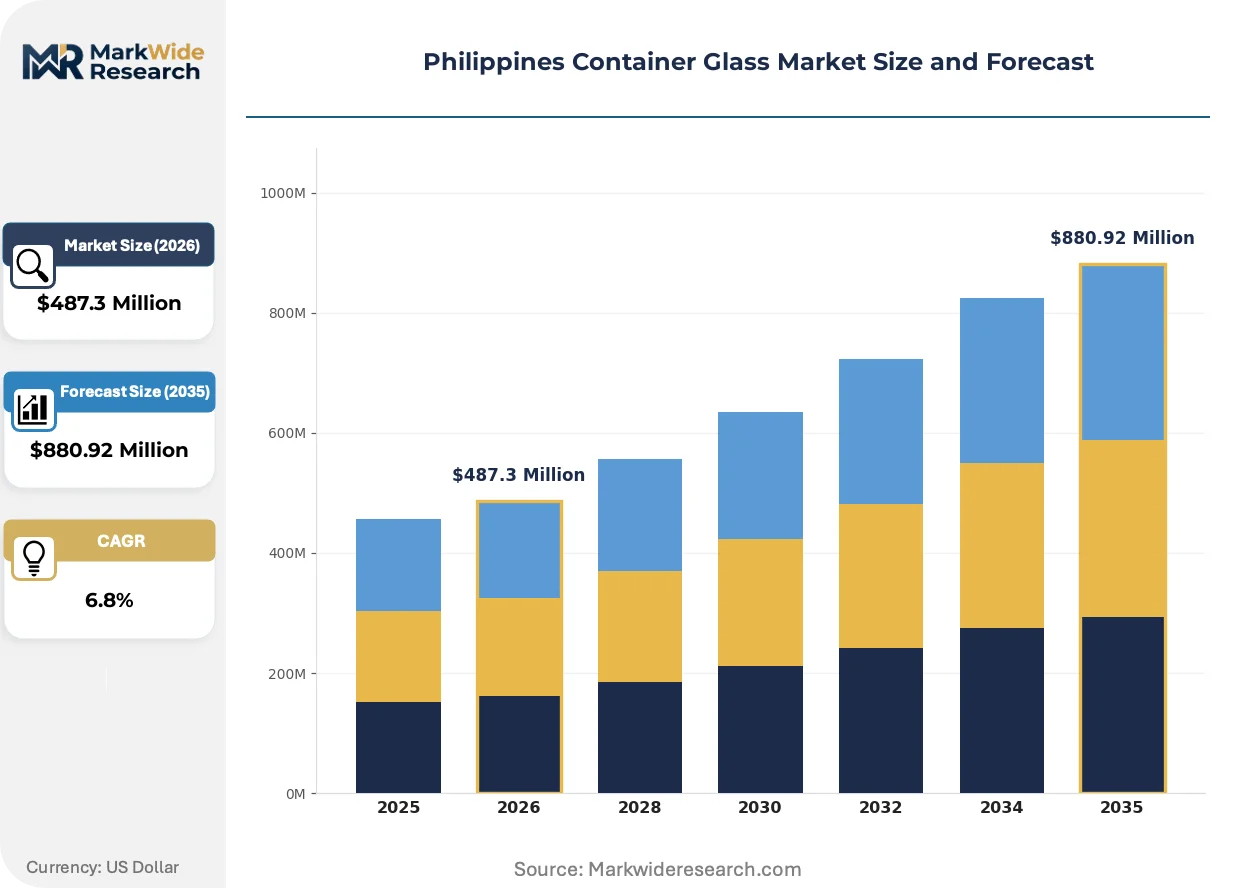
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Containers End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Size: Small, Medium, Large, Extra Large Packaging Type: Recyclable, Non-Recyclable, Specialty, Bulk |
| Companies Covered | San Miguel Yamamura Packaging Corporation, Manila Glass Manufacturing Co., Cebu Glass Industries, Davao Crystal Bottle Company, Luzon Glass Manufacturing Inc., Arcya, Bestpak, ECPACK, Owens-Illinois Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Container Glass Market Trends and Innovations
Digital mold design and cullet beneficiation are compressing production economics while EPR frameworks rewrite procurement specifications. These shifts favor integrated manufacturers with captive recycling streams.
Lightweighting technology is absorbing furnace capacity previously allocated to heavier bottle formats. Craft distilleries in Batangas and Laguna are adopting 320-gram premium spirits bottles, down from 420-gram standards. This weight reduction is absorbing natural gas consumption per thousand units, improving carbon intensity metrics for export compliance.
The Department of Environment and Natural Resources extended producer responsibility regulations now mandate 20% post-consumer cullet incorporation in new production. Large-format food processors face audit requirements that exclude non-compliant suppliers. Pharmaceutical packaging, exempt from cullet mandates, is absorbing premium pricing for virgin-flint certification.
Direct procurement from glassworks is displacing distributor intermediaries among multinational beverage brands. Nestlé Philippines and Unilever Philippines now negotiate annual volume contracts with mold-specific customization. This channel compression is most visible in Metro Manila, where logistics costs favor single-source supply agreements over fragmented procurement.
Philippines Container Glass Market Segmentation
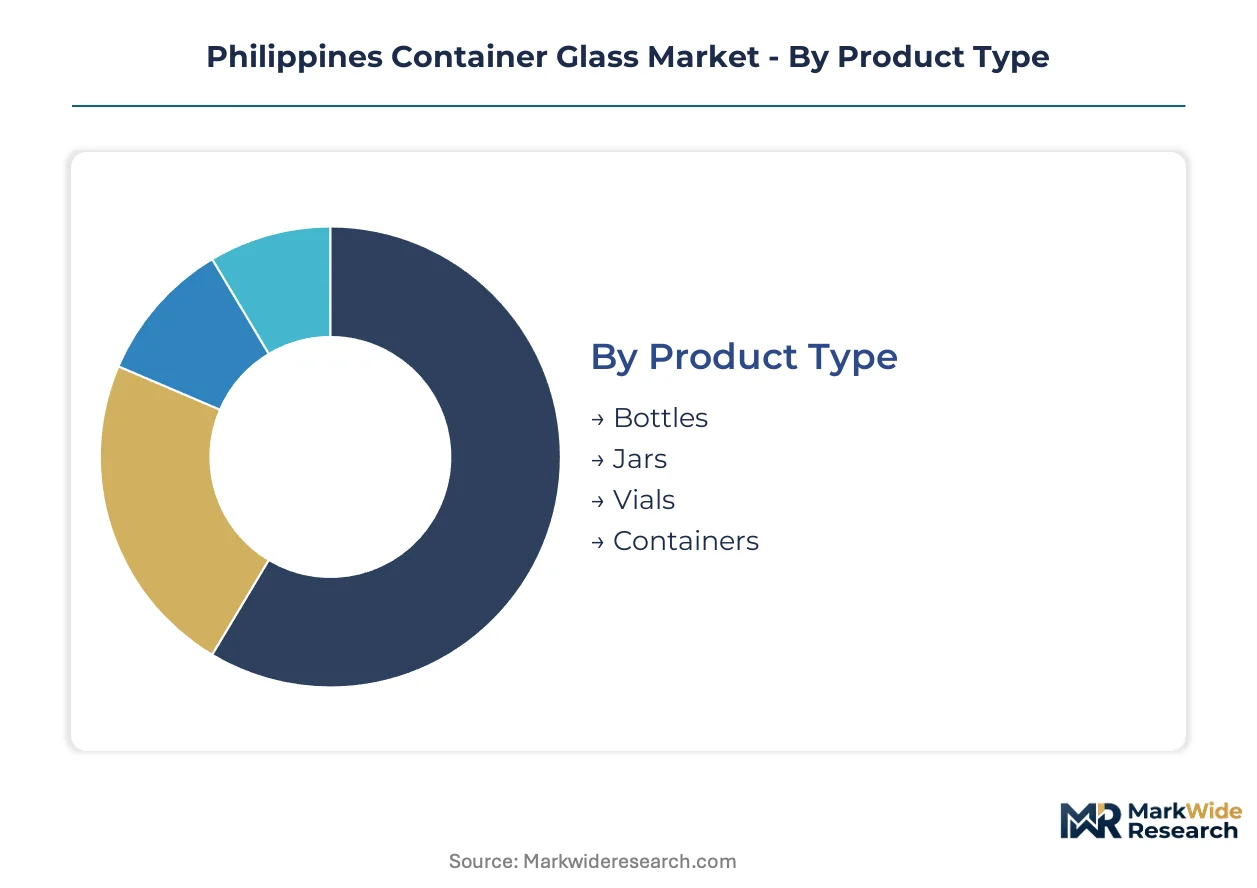
Segmentation in the Philippines container glass market reveals how EPR mandates and craft distillery premiumization reshape procurement patterns across product formats. Distinct technical requirements separate pharmaceutical vials from food-grade bottles, while cullet incorporation thresholds fragment packaging type economics.
Product Type:
Customization intensity varies sharply across this category, from standardized beverage bottles to precision-engineered pharmaceutical vials requiring pharmacopeial certification.
- Bottles:Flint and amber soda-lime compositions dominate beverage and spirits applications. Metro Manila craft distilleries drive demand for lightweight 320-gram premium formats as EPR audits intensify. The DENR's 20% cullet mandate compresses margins on virgin-flint certifications for export-bound spirits.
- Jars:Wide-mouth configurations with thermal shock resistance serve hot-fill coconut oil and specialty sauce processors. Bulacan and Laguna food manufacturers favor 300-500ml formats for retail shelf positioning. Bureau of Product Standards certification timelines delay seasonal launches by 4-6 months.
- Vials:Borosilicate and neutral glass types meet FDA pharmacopeial standards for injectable and oral drug packaging. Exempt from EPR cullet mandates, these command premium pricing for virgin-flint traceability in Cebu pharmaceutical corridors.
- Containers:Rectangular and cylindrical storage formats for household and industrial chemicals. Davao and Cagayan de Oro distribution networks favor bulk procurement of large-format containers for provincial market penetration.
Leading the category by volume: Bottles. Growing fastest: Vials as FDA track-and-trace mandates expand.
End User:
Margin structures diverge across this category, from commodity-priced household segments to pharmaceutical packaging commanding certification premiums.
- Food & Beverage:Coconut oil processors, craft distilleries, and specialty sauce producers generate the dominant volume share. San Miguel Yamamura's integrated brewing footprint anchors domestic supply for beer and spirits bottling.
- Cosmetics:Premium skincare and fragrance brands specify flint glass with UV protection for oxygen-sensitive formulations. Direct procurement from glassworks displaces distributor intermediaries among multinational beauty brands.
- Pharmaceuticals:Injectable vials and oral drug containers require FDA pharmacopeial compliance. Serialization mandates favor glass formats with integrated marking compatibility.
- Household:Cleaning agents and chemical storage drive demand for cost-optimized soda-lime containers. Flexible packaging substitution erodes glass share in shelf-stable household products.
Food & Beverage generates highest absolute volume. Pharmaceuticals deliver steepest margin expansion trajectory.
Size:
Furnace throughput economics and mold changeover frequency create distinct cost curves across dimensional categories.
- Small:Sub-100ml formats for pharmaceutical ampoules and cosmetic samples. Lightweighting technology absorbs disproportionate natural gas consumption per thousand units.
- Medium:100-500ml range captures spirits, sauces, and personal care applications. Cebu and Iloilo bottling corridors concentrate mid-size mold capacity investments.
- Large:500ml-1L configurations for coconut oil and beverage family packs. Metro Manila logistics costs favor single-source supply agreements at this scale.
- Extra Large:Above-1L formats for bulk food service and industrial chemical storage. Provincial distribution networks in Visayas remain undersupplied relative to Luzon concentration.
Medium sizes dominate production schedules. Small formats gain share fastest through pharmaceutical serialization expansion.
Packaging Type:
EPR compliance thresholds and cullet recovery infrastructure reshape competitive positioning across sustainability tiers.
- Recyclable:Certified post-consumer cullet incorporation meets DENR's 20% mandate. Large-format food processors face audit requirements that exclude non-compliant suppliers.
- Non-Recyclable:Virgin-flint and specialty compositions for pharmaceutical and premium cosmetic applications. Exempt from cullet mandates, these absorb pricing premiums for purity certification.
- Specialty:UV-protective amber, cobalt blue, and custom-tinted glass for light-degradable contents. Craft distilleries in Batangas specify amber for premium spirits positioning.
- Bulk:Uncustomized standard formats for industrial and food service procurement. Distributor intermediaries retain relevance in fragmented provincial markets.
Recyclable packaging commands procurement priority. Specialty formats expand most quickly through premium beverage premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production concentrates in Metro Manila and Cebu corridors, yet provincial demand in Visayas and Mindanao outpaces local supply capacity. This geographic mismatch drives logistics costs and shapes facility investment decisions across the archipelago.
Metro Manila
San Miguel Yamamura Packaging Corporation anchors brewing and spirits bottling capacity in the capital region. The Department of Environment and Natural Resources enforces 20% post-consumer cullet mandates that redirect procurement toward certified recyclable formats. Quezon City and Caloocan manufacturing clusters absorb lightweighting technology investments for premium spirits export compliance.
Central Luzon
Bulacan and Laguna provinces host specialty sauce processors and coconut oil bottlers demanding thermal shock-resistant jars. The Bureau of Product Standards certifies glass thermal shock resistance for hot-fill food applications, creating 4-6 month approval delays. Malolos and Santa Rosa industrial zones concentrate mold engineering talent for seasonal sauce launches.
Cebu
Cebu Glass Industries and pharmaceutical corridors drive borosilicate vial demand for FDA-tracked drug packaging. The Food and Drug Administration's pharmacopeial standards restrict import substitution in drug packaging. Mandaue City manufacturing absorbs serialization-compatible glass formats for injectable and oral drug applications.
Western Visayas
Iloilo bottling corridors remain undersupplied relative to Luzon concentration, creating white space for distributed mold capacity. Extended producer responsibility regulations mandate post-consumer collection targets that reshape procurement criteria. Bacolod and Iloilo City logistics networks favor bulk procurement partnerships for provincial market penetration.
Northern Mindanao
Cagayan de Oro and Davao cullet recovery infrastructure secures feedstock advantages under EPR credit mechanisms. Municipal collection partnerships in Davao de Oro province can secure raw material positioning for large-format food processors. Cagayan de Oro distribution networks favor single-source supply agreements for industrial chemical storage containers.
Philippines Container Glass Market Competitive Landscape
Top-tier vendors anchor integrated brewing and packaging footprints, while mid-scale fabricators compete on provincial distribution reach. The market structure favors manufacturers with captive cullet streams and furnace scale economies. Two strategic archetypes dominate: integrated beverage conglomerates with backward glass capacity, and specialized pharmaceutical vial producers with FDA certification track records. Competitive moves concentrate on Visayas capacity expansion and direct procurement contracts displacing distributor intermediaries.
Within the integrated conglomerate tier, San Miguel Yamamura Packaging Corporation exemplifies vertical control from brewing through bottling. Among specialized fabricators, Manila Glass Manufacturing Co. and Cebu Glass Industries occupy positions anchored in Luzon and Visayas distribution networks respectively. Owens-Illinois Inc. represents the multinational technology-licensing archetype, while domestic specialists Arcya and Bestpak sit within the mid-scale custom mold segment serving craft distillery and cosmetics verticals.
| Leading Market Players |
|---|
| San Miguel Yamamura Packaging Corporation |
| Manila Glass Manufacturing Co. |
| Cebu Glass Industries |
| Davao Crystal Bottle Company |
| Luzon Glass Manufacturing Inc. |
| Arcya |
| Bestpak |
| ECPACK |
| Owens-Illinois Inc. |
| Others |
Pricing and Supply Chain Analysis
Turkish and Chinese soda ash freight indices cascade through Philippine container glass pricing tiers, compressing margins on virgin-flint pharmaceutical certifications while elevating recyclable-format premiums under DENR extended producer responsibility mandates. Raw-material import exposure concentrates pricing power among furnace-scale integrated producers with captive cullet streams.
Pricing Analysis
Margin tightening in mid-scale custom mold segments reflects furnace rebuild cycle capital demands and soda ash import volatility. Three-tier pricing structure across premium pharmaceutical vials, standard food-grade bottles, and economy household containers stratifies by certification grade and volume scale. Cost-down pressure on recyclable formats accelerates as DENR audit requirements exclude non-compliant suppliers from multinational procurement. Large-format food processors exhibit highest price sensitivity due to thin operating margins, while pharmaceutical packaging buyers absorb premium pricing for FDA pharmacopeial traceability.
Supply Chain Analysis
Dual-sourcing qualification requirements for multinational beverage brands mandate redundant mold capacity across Metro Manila and Cebu corridors. Geographic supply concentration centers on China and Turkey for soda ash, with Australian silica sand and domestic limestone rounding out batch chemistry. Raw material dependencies on imported alkali expose manufacturers to freight volatility and currency fluctuation. Single-source vulnerability concentrates in Chinese soda ash supply chains, where shipping disruptions propagate rapidly through furnace operations. Distribution runs through direct procurement contracts displacing distributor intermediaries among Nestlé Philippines and Unilever Philippines volume agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Philippine container glass functions as a cost-of-compliance market where DENR extended producer responsibility regulations erect barrier-to-entry moats favoring integrated producers with captive cullet recovery infrastructure.
For Market Incumbents: Acquire municipal cullet collection partnerships in Davao and Cagayan de Oro to secure feedstock advantages under EPR credit mechanisms. Consolidate furnace capacity around Metro Manila and Cebu manufacturing corridors to absorb lightweighting technology investments and defend against flexible packaging substitution in coconut milk distribution. Backward integration into provincial distribution networks protects channel control against direct procurement compression. For New Entrants and Emerging Players: Visayas provincial bottling corridors remain underserved relative to Luzon concentration, presenting white space for distributed mold capacity targeting Iloilo and Bacolod food processors. Pharmaceutical serialization mandates favor glass vials with integrated marking compatibility, creating penetrable entry points in Cebu drug packaging corridors. Go-to-market positioning as DENR-compliant recyclable specialists unlocks multinational brand procurement criteria. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale fabricators with FDA certification track records in pharmaceutical vials and thermal shock-resistant jar capabilities for hot-fill food applications. Long-term viability hinges on furnace scale economies and EPR-compliant cullet infrastructure positioning. Monitor DENR enforcement intensity and Bureau of Product Standards certification timeline compression as inflection indicators for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Cullet Recovery Infrastructure Buildout | Municipal collection partnerships in Davao secure EPR credit advantages for large-format food processors. |
| Lightweighting Technology Licensing | Advanced mold engineering reduces natural gas consumption per thousand units for export-bound spirits. |
| Pharmaceutical Serialization Compatibility | FDA track-and-trace mandates favor glass vials with integrated marking in Cebu drug corridors. |
| Visayas Distributed Capacity Expansion | Iloilo and Bacolod bottling corridors remain undersupplied relative to Luzon manufacturing concentration. |
| Direct Procurement Contract Negotiation | Annual volume agreements with Nestlé Philippines displace distributor intermediaries in Metro Manila logistics. |
Research Methodology
Multi-period observation of furnace capacity utilization, soda ash import volumes, and DENR compliance certification timelines anchored the trend analysis, supplemented by interviews with plant managers at integrated glassworks, procurement leads at multinational beverage brands, distribution channel partners in Visayas corridors, and technical R&D directors specializing in lightweighting mold engineering. Secondary validation drew from Bureau of Product Standards thermal shock certification records, Department of Environment and Natural Resources EPR audit disclosures, customs trade data on Turkish and Chinese soda ash shipments, and SEC filings of packaging conglomerates with backward glass capacity. Bottom-up production volume estimates triangulated against top-down demand aggregation across food, pharmaceutical, and cosmetics end-use segments.
Segment-weighting across product type, end user, size, and packaging type dimensions calibrated value and volume outputs over the projection horizon. Product type stratification captured bottles, jars, vials, and containers with distinct technical requirements. End user segmentation distinguished food and beverage, cosmetics, pharmaceutical, and household demand pools with divergent margin structures. CAGRs derived from regression analysis of historical production trends, furnace investment cycles, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated pharmaceutical serialization mandate rollout schedules and craft distillery premiumization adoption curves.
Revisions become necessary when DENR enforcement intensity exceeds modeled thresholds, soda ash freight volatility disrupts batch chemistry cost assumptions, or flexible packaging substitution accelerates beyond historical rates in coconut milk and shelf-stable food segments. Deviation in EPR cullet incorporation mandate stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
France Container Glass Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Glass Growlers Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Paragon Glass Jar Market