
 Dominican Republic Container Glass Market | 2026-2036
Dominican Republic Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Dominican Republic Container Glass Market Insights
A capital-intensity divergence between furnace-scale incumbents and flexible niche operators is redrawing competitive boundaries in the Dominican Republic container glass sector. Caribbean Glass Industry S.A. leverages its Santo Domingo production base to anchor supply for domestic beverage bottlers. Owens-Illinois sustains technical leadership through advanced forming equipment and color consistency protocols. Saverglass SAS differentiates via premium decorative capabilities targeting luxury spirits export markets.
Container glass comprises soda-lime-silica formulations shaped by blow-and-blow or press-and-blow forming, with thermal shock resistance and chemical inertness enabling repeated sterilization cycles for food, beverage, and pharmaceutical contents. Bottles command the dominant product position due to rum and beer packaging volume, while pharmaceutical vials capture concentrated margin pools from stringent USP compliance requirements. The beverage end-use segment absorbs the majority of domestic furnace output, though personal care jars exhibit faster growth from cosmetics contract manufacturing near Santiago free zones.
The Dominican Republic's national standards body enforces B-type mechanical strength and thermal endurance specifications, while FDA import alignment governs pharmaceutical glass destined for US-bound drug products. Environmental regulators apply escalating post-consumer cullet recovery mandates that elevate furnace feedstock costs for non-compliant producers. Stakeholders must weigh furnace rebuild timing against lightweighting investment thresholds before the next energy tariff restructuring cycle.
Market Dynamics
Lightweighting technology and cullet recovery mandates are compressing furnace economics while opening margin pools for operators who rebuild ahead of the next energy tariff cycle.
Growth Catalysts
- INDOCAL B-type mechanical standards:The national standards body enforces thermal endurance specifications that disqualify imported alternatives, securing domestic furnace output for beverage bottlers.
- Rum export bottling:Premium spirits producers in Santo Domingo and Santiago corridors are expanding glass packaging capacity to capture duty-free access into US and European markets.
- Lightweighting forming:Advanced blow-and-blow equipment reduces per-unit silica consumption, cutting feedstock costs for compliant producers.
Market Restraints
- Natural gas price volatility:Furnace operations depend on imported LNG, exposing margins to Caribbean basin supply disruptions and currency fluctuation.
- Single-furnace supply concentration:Santo Domingo hosts the dominant production base, creating geographic vulnerability to port congestion or hurricane disruption.
- Plastic substitution in personal care:PET and HDPE jars capture mid-tier cosmetics packaging from Santiago free zone manufacturers seeking lower freight costs.
Strategic Opportunities
- Pharmaceutical vial expansion:USP compliance capabilities open contract manufacturing for US-bound generic drug producers seeking nearshore glass supply.
- Santiago free zone cosmetics:Underpenetrated jar demand from contract manufacturers serving North American beauty brands offers faster growth than beverage bottling.
- Post-consumer cullet mandates:Environmental regulators are escalating recovery requirements, creating first-mover advantage for operators with integrated recycling infrastructure.
Industry Challenges
- Furnace rebuild timing:Capex intensity of regenerative furnace reconstruction forces multi-year planning cycles that must anticipate energy tariff restructuring.
- Color consistency protocols:Amber and flint glass production requires precise oxidation control, with technical skill gaps limiting workforce scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dominican Republic Container Glass Market |
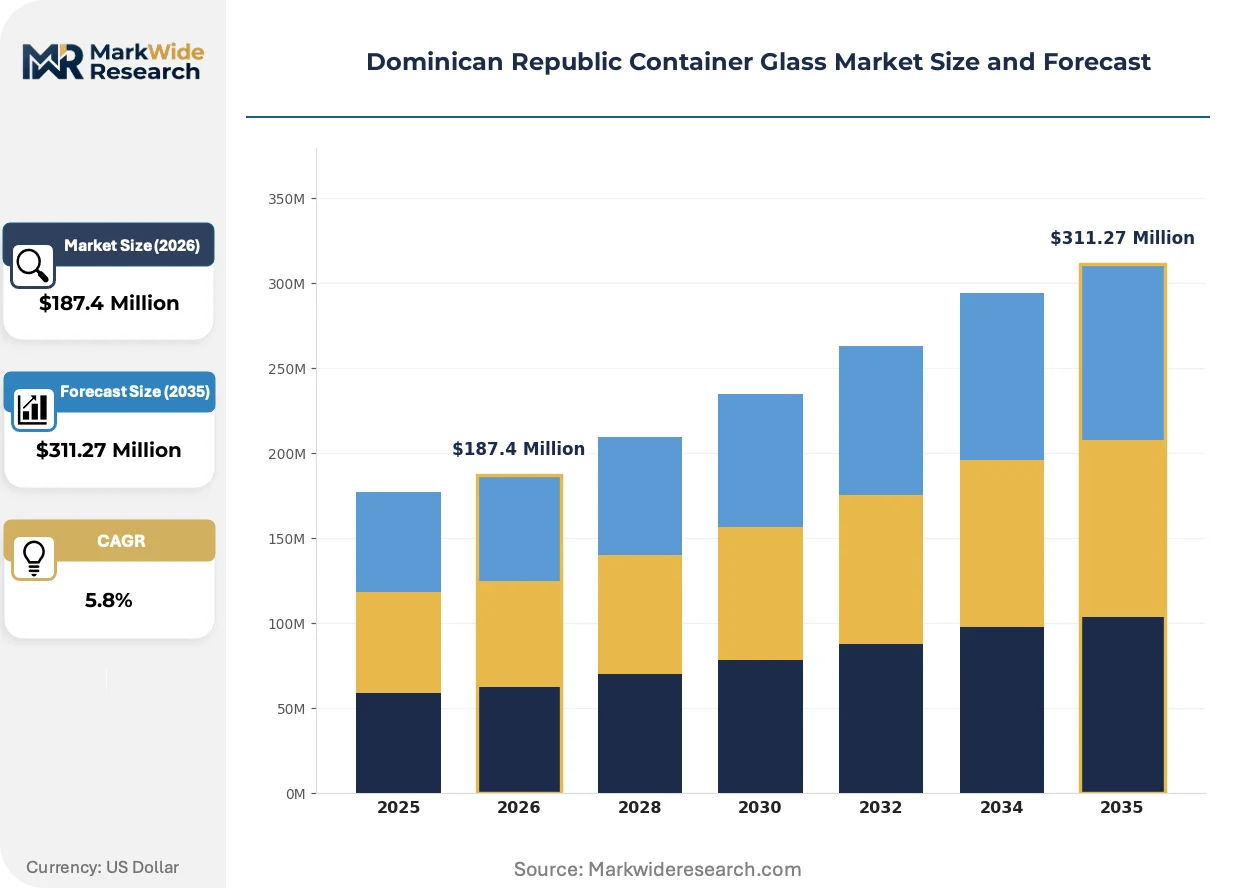
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Flask End User: Food Industry, Beverage Industry, Pharmaceutical, Personal Care Closure Type: Cork, Screw Cap, Flip Top, Snap-On Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Feemio Group Co., Ltd., ALPLA Caribe, Inc., Caribbean Glass Industry S.A., Owens-Illinois, Saverglass SAS, ZZ Glass, Almacenes Carballo, Vidrala SA, Vidrios del Caribe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dominican Republic Container Glass Market Trends and Innovations
Forming technology advances and regulatory pressure on circularity are restructuring production economics while export-oriented beverage bottlers drive specification upgrades.
Narrow-neck press-and-blow forming is decomposing the traditional blow-and-blow bottleneck in lightweight beer bottle production. Craft brewers in the Santiago corridor are specifying these geometries to reduce shipping weight. The technology is decomposing legacy furnace throughput assumptions as thinner walls require recalibrated thermal profiles.
Post-consumer cullet recovery mandates from environmental regulators are forcing furnace feedstock reformulation. Producers must now integrate 30% recycled content or face escalating compliance costs. Pharmaceutical glass destined for US-bound drug products faces the strictest contamination thresholds, pushing investment in optical sorting infrastructure.
Buyer consolidation among premium rum exporters is compressing supplier qualification timelines. Santo Domingo bottlers now demand six-month color consistency guarantees rather than annual contracts. This pattern concentrates procurement leverage with the three largest spirits exporters, marginalizing smaller furnace operators.
Dominican Republic Container Glass Market Segmentation
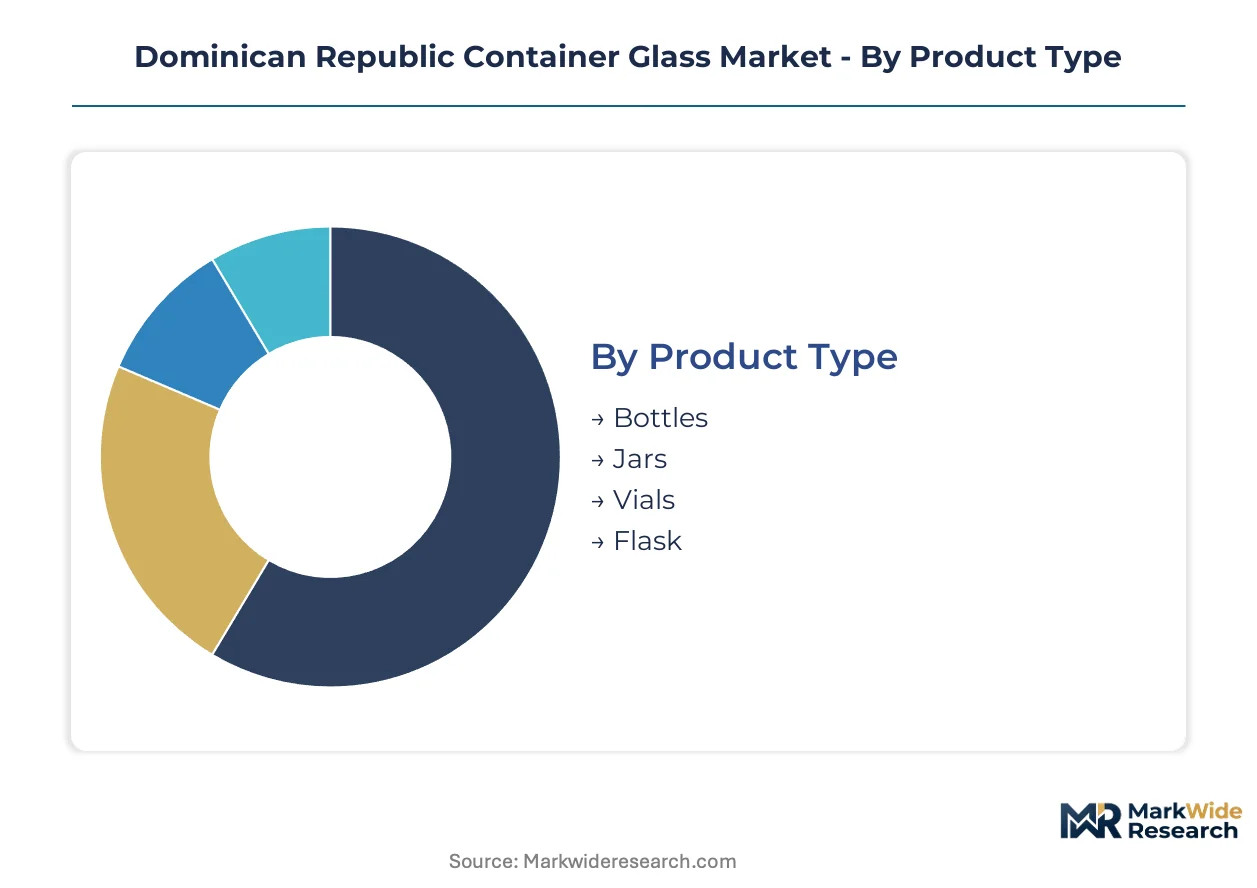
Container glass segmentation in the Dominican Republic reflects the tension between export-oriented beverage specifications and domestic regulatory compliance. Category boundaries align with INDOCAL B-type mechanical standards and FDA import alignment requirements that govern furnace output allocation.
Product Type:
INDOCAL thermal endurance specifications and USP compliance thresholds create divergent qualification barriers across product categories.
- Bottles:Soda-lime-silica formulations shaped by blow-and-blow or press-and-blow forming dominate furnace throughput. Rum and beer exporters in Santo Domingo and Santiago corridors absorb the majority of amber and flint capacity, with lightweighting technology reducing per-unit silica consumption for compliant producers.
- Jars:Wide-mouth geometries serve food preservation and cosmetics contract manufacturing near Santiago free zones. Personal care applications exhibit faster growth than traditional food packaging as North American beauty brands expand nearshore sourcing.
- Vials:USP compliance capabilities open contract manufacturing for US-bound generic drug producers seeking nearshore glass supply with stringent contamination thresholds.
- Flask:Laboratory and specialty chemical containment applications occupy niche furnace slots with premium pricing.
Bottles handle the majority of throughput; jars are the fastest mover on share.
End User:
Customer concentration patterns mirror the geographic clustering of free zone manufacturing and domestic bottling corridors.
- Food Industry:Thermal shock resistance and chemical inertness enable repeated sterilization cycles for preserved goods. Santo Domingo processors anchor demand for standard flint containers.
- Beverage Industry:Premium spirits producers expanding glass packaging capacity to capture duty-free access into US and European markets drive specification upgrades and color consistency requirements.
- Pharmaceutical:FDA import alignment governs glass destined for US-bound drug products, with optical sorting infrastructure investment separating qualified from marginal suppliers.
- Personal Care:Cosmetics contract manufacturing near Santiago free zones generates underpenetrated jar demand with faster expansion than beverage bottling.
Beverage Industry commands the dominant furnace allocation; Personal Care is climbing the fastest.
Closure Type:
Sealing technology selection tracks the premiumization gradient across export versus domestic market channels.
- Cork:Premium rum and aged spirits bottlers in Santo Domingo specify natural and synthetic cork for European and US export markets requiring traditional closure aesthetics.
- Screw Cap:Standardized threading dominates beer and mass-market spirits for operational efficiency in high-speed filling lines.
- Flip Top:Convenience-oriented personal care and pharmaceutical applications favor single-hand dispensing.
- Snap-On:Cost-sensitive food packaging segments utilize press-fit closures for reduced component complexity.
Screw Cap handles the majority of throughput; Cork is gaining share fastest among premium exporters.
Distribution Channel:
Channel structure reflects the capital intensity divergence between furnace-scale incumbents and flexible niche operators.
- Wholesale:Bulk procurement consolidation among premium rum exporters compresses supplier qualification timelines and concentrates leverage with the three largest spirits exporters.
- Retail:Smaller lot sizes serve mid-tier cosmetics and domestic food processors with less stringent color consistency requirements.
- Online:Digital procurement platforms emerge for standardized jar specifications in Santiago free zone cosmetics manufacturing.
- Direct Sales:Long-term supply agreements anchor furnace output planning for major beverage bottlers with dedicated technical service relationships.
Wholesale handles the majority of throughput; Direct Sales is expanding most quickly among qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Santiago free zones exhibit the highest price elasticity for cosmetics jar procurement, while premium rum exporters in Santo Domingo absorb specification premiums with minimal volume sensitivity.
Santo Domingo
The capital corridor hosts the dominant furnace infrastructure serving beverage bottlers with INDOCAL B-type mechanical standards compliance. Environmental regulators enforce escalating post-consumer cullet recovery mandates that elevate feedstock costs for non-compliant producers. Caribbean Glass Industry S.A. anchors supply from its Santo Domingo production base for domestic bottlers expanding export capacity.
Santiago
Free zone cosmetics contract manufacturers generate underpenetrated jar demand growing faster than beverage bottling. INDOCAL thermal endurance specifications govern domestic food processors while FDA import alignment requirements shape pharmaceutical glass destined for US-bound drug products. Lightweighting forming technology reduces per-unit silica consumption for compliant producers serving craft brewers specifying narrow-neck press-and-blow geometries.
Puerto Plata
Northern corridor rum distillers leverage duty-free access into US and European markets through expanded glass packaging capacity. The country's national standards body enforces color consistency protocols that disqualify marginal imported alternatives. Port infrastructure supports bulk cullet import for integrated recycling operations.
La Romana
Eastern sugar cane belt processors anchor demand for standard flint containers with thermal shock resistance enabling repeated sterilization cycles. Natural gas price volatility from imported LNG dependencies compresses margins for single-furnace operators. Hurricane exposure creates geographic vulnerability requiring contingency planning.
San Pedro de Macorís
Southeastern industrial zone personal care manufacturers face plastic substitution pressure from PET and HDPE jars capturing mid-tier cosmetics packaging. Buyer consolidation among premium rum exporters compresses supplier qualification timelines. Direct sales relationships anchor long-term supply agreements with dedicated technical service provisions.
Dominican Republic Container Glass Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Dominican Republic container glass sector. Furnace-scale incumbents leverage capital intensity barriers while flexible niche operators capture premium decorative and pharmaceutical specification pockets. Three archetypes dominate: integrated furnace operators with captive cullet processing, premium decorative specialists serving luxury spirits export markets, and regional packaging distributors with logistics scale. Competitive moves concentrate on furnace rebuild timing ahead of energy tariff restructuring and lightweighting technology licensing to compress per-unit feedstock costs.
Within the integrated furnace tier, Caribbean Glass Industry S.A. and Owens-Illinois occupy positions shaped by Santo Domingo production concentration and advanced forming equipment respectively. Saverglass SAS represents the premium decorative archetype targeting luxury spirits export markets. Feemio Group Co., Ltd. and ZZ Glass exemplify the flexible specialist pattern with capacity to serve specification-intensive segments without furnace-scale capital commitments.
| Leading Market Players |
|---|
| Feemio Group Co., Ltd. |
| ALPLA Caribe, Inc. |
| Caribbean Glass Industry S.A. |
| Owens-Illinois |
| Saverglass SAS |
| ZZ Glass |
| Almacenes Carballo |
| Vidrala SA |
| Vidrios del Caribe |
| Others |
Pricing and Supply Chain Analysis
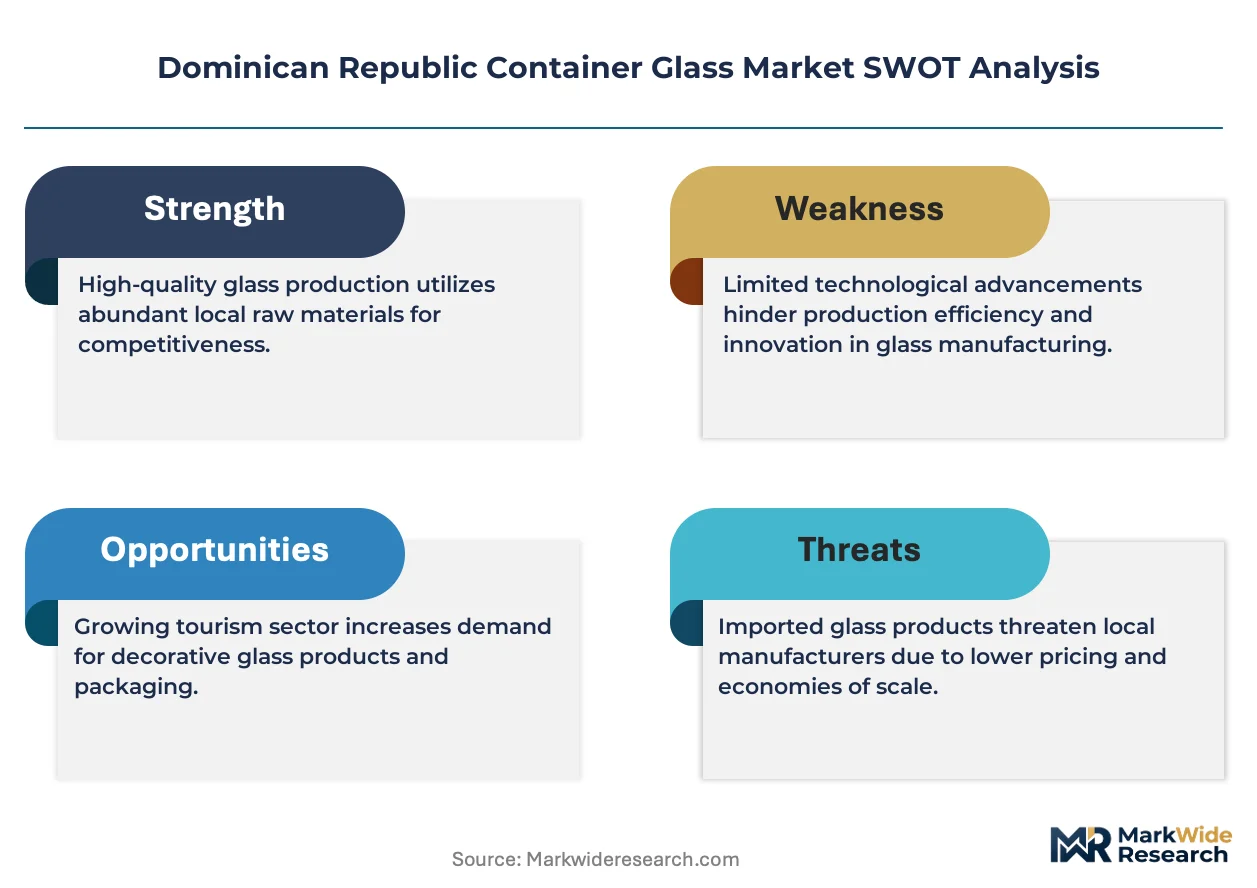
INDOCAL B-type mechanical standards and FDA import alignment govern qualification thresholds that simultaneously filter supplier eligibility and stratify price tiers across pharmaceutical and beverage segments. Santo Domingo furnace operators command specification premiums while Santiago free zone buyers exercise volume leverage on jar procurement.
Pricing Analysis
After-sales technical service contracts and multi-year color consistency guarantees anchor lifetime value for premium rum exporters consolidating procurement. Three-tier pricing structure across premium, standard, and economy levels separates USP-compliant pharmaceutical vials from INDOCAL-certified beverage bottles and commodity flint containers. Cost compression in standard-grade flint glass is intensifying because PET substitution erodes mid-tier cosmetics jar margins. Santiago free zone cosmetics manufacturers exhibit highest price elasticity; premium spirits exporters absorb specification premiums with minimal volume sensitivity.
Supply Chain Analysis
Port congestion at Caucedo terminal underwrites logistics vulnerability for Santo Domingo furnace operators dependent on imported LNG and bulk silica sand. Supply concentrates in the Dominican Republic for finished container glass, with raw material dependencies drawing from the United States, Mexico, and Colombia for high-purity silica and soda ash. Single-furnace geographic concentration creates hurricane exposure risk for domestic output. Distribution runs through wholesale procurement consolidation among the three largest spirits exporters, with direct sales relationships anchoring long-term supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dominican Republic container glass market represents early-cycle expansion as post-consumer cullet mandates and lightweighting technology adoption reshape production economics ahead of the next energy tariff restructuring.
For Market Incumbents: Shield furnace output allocation by accelerating regenerative rebuild timelines before tariff restructuring compresses margin structures. Secure backward integration into optical sorting infrastructure to capture first-mover advantage from escalating environmental compliance thresholds. Deepen captive cullet processing capabilities to insulate feedstock costs from recovery mandate penalties. For New Entrants and Emerging Players: Anchor in pharmaceutical vial contract manufacturing for US-bound generic drug producers seeking nearshore USP-compliant glass supply. Target underpenetrated Santiago free zone cosmetics jar demand growing faster than beverage bottling. Pursue digital procurement platform partnerships with standardized specifications to bypass wholesale consolidation leverage. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with stranded container glass assets lacking INDOCAL certification capabilities. Long-term viability hinges on furnace-scale operators with integrated recycling infrastructure and lightweighting technology licenses. Watch for inflection signals in natural gas tariff restructuring announcements and premium rum export volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Rebuild with Lightweighting Integration | Regenerative furnace reconstruction with narrow-neck press-and-blow equipment reduces per-unit silica consumption for compliant Santo Domingo operators. |
| Optical Sorting Infrastructure Investment | Post-consumer cullet recovery mandates from environmental regulators elevate contamination thresholds for pharmaceutical glass destined for US-bound drug products. |
| Direct Sales Relationship Expansion | Long-term supply agreements with dedicated technical service provisions anchor output planning for premium rum exporters consolidating procurement leverage. |
| Santiago Free Zone Cosmetics Focus | Underpenetrated jar demand from contract manufacturers serving North American beauty brands offers faster expansion than saturated beverage bottling corridors. |
| USP Compliance Capability Buildout | FDA import alignment requirements separate qualified pharmaceutical glass suppliers from marginal operators in nearshore generic drug supply chains. |
Research Methodology
A spread of perspectives from furnace operations managers, procurement leads at premium rum exporters, free zone cosmetics contract manufacturers, and environmental compliance officers converged on the working assumptions underlying volume and value projections. Secondary validation drew from INDOCAL regulatory filings, customs trade data for container glass imports, SEC disclosures from multinational packaging conglomerates, and Caribbean energy tariff restructuring announcements. Bottom-up capacity modeling triangulated against top-down demand segmentation across beverage, pharmaceutical, and personal care end-uses.
Segmentation dimensions modeled include product type, end-use industry, closure technology, and distribution channel across the projection horizon. CAGRs derived from furnace throughput assumptions, lightweighting adoption curves, and export volume elasticity to US and European market access. Industry-specific forecast inputs incorporated natural gas price volatility scenarios and post-consumer cullet recovery mandate compliance cost trajectories.
Material uncertainties — energy tariff restructuring timing, hurricane disruption frequency, and premium spirits export demand fluctuations — sit outside the modeled envelope. Forecasts reflect assumptions about INDOCAL enforcement consistency and FDA import alignment stability. Practitioners should keep alternative scenarios live as environmental regulator mandate escalation and LNG supply contract renegotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Congo Container Glass Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Colombia Container Glass Market