
 APAC Glass Bottles/Containers Market | 2026-2036
APAC Glass Bottles/Containers Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Glass Bottles/Containers Market Outlook
Premium borosilicate and pharmaceutical-grade flint glass is rotating toward the center of value creation in the APAC container industry. Hindustan National Glass and Industries Ltd. leverages its integrated furnace network across India to anchor supply for domestic beverage producers. Gerresheimer AG sustains specialized molding capabilities that differentiate its pharmaceutical vial output for regulated export markets.
Glass bottles and containers are hollow vessels formed from silica sand, soda ash, and limestone, typically manufactured through blow-and-blow or press-and-blow forming with wall thicknesses calibrated to internal pressure ratings and thermal shock resistance; they serve as chemically inert, impermeable packaging for liquids and solids across food, beverage, pharmaceutical, and personal care supply chains. Pharmaceutical vials command concentrated margin pools due to stringent USP Type I certification requirements and limited qualified furnace capacity, while beverage containers dominate absolute volume throughput across the region. Cosmetic jars represent the fastest-expanding product type as personal care brands in Japan and South Korea pursue shelf differentiation through heavyweight flint and cobalt-tinted glass.
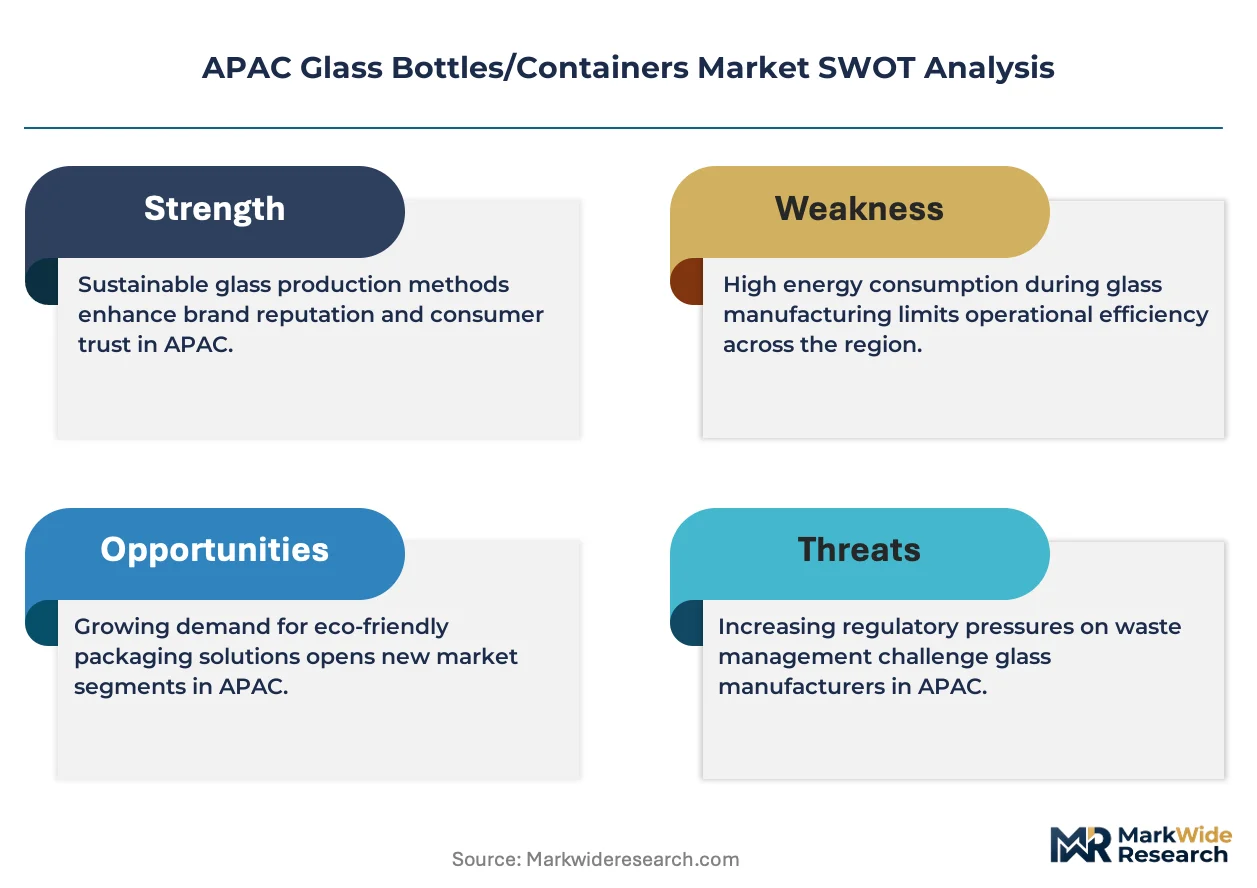
China's SAMR enforces GB 4806.5 food-contact glass standards that restrict lead and cadmium migration, directly shaping furnace chemistry and raw material sourcing decisions for domestic producers. India's BIS certification scheme for pharmaceutical packaging materials creates compliance barriers that filter out unqualified molders from supplying CDSCO-regulated drug manufacturers. Japan's METI circular economy guidelines promote post-consumer glass cullet incorporation, altering batch composition targets for Toyo Seikan Group Holdings Ltd. and Central Glass Co. Ltd. Stakeholders must monitor how tightening ESG disclosure rules across South Korea and Australia reshape procurement criteria for multinational beverage and cosmetics brands operating regional supply hubs.
Market Dynamics
China's SAMR enforcement of GB 4806.5 food-contact standards is compressing furnace chemistry choices across the APAC glass container industry, forcing producers to requalify raw material suppliers and redirect capital toward heavy-metal reduction systems.
Growth Catalysts
- Cosmetic packaging premiumization:South Korean skincare brands are converting serum lines from PET to heavyweight flint glass, creating specialized demand for borosilicate-compatible forming equipment.
- CDSCO pharmaceutical mandates:India's tightened BIS certification for injectable drug packaging is filtering qualified borosilicate vial suppliers into Mumbai-Hyderabad pharmaceutical corridors.
- Dual carbon goals:China's MEE directives on furnace emissions are accelerating electric melting pilot installations at container glass facilities in Shandong and Hebei provinces.
Market Restraints
- Soda ash price volatility:Energy-intensive synthetic soda ash production in China creates input cost instability for container glass batch formulations.
- Qualified furnace scarcity:USP Type I borosilicate certification capacity concentrates among a limited set of Indian and Japanese producers, creating supply bottlenecks for parenteral drug packaging.
- Aluminum substitution:Lightweight aluminum bottles are displacing glass in APAC sports beverage segments where transport cost sensitivity outweighs premium shelf positioning.
Strategic Opportunities
- Vietnam manufacturing expansion:Underpenetrated glass container production relative to ASEAN beverage demand creates greenfield furnace investment potential near Ho Chi Minh City logistics hubs.
- Post-consumer cullet integration:Japan's METI circular economy guidelines incentivize furnace batch composition shifts that reduce virgin silica sand consumption.
- Pharmaceutical serialization:Converging track-and-trace requirements with molded glass vial production enables integrated packaging-traceability service bundles for export markets.
Industry Challenges
- Forming technician scarcity:IS machine operation and mold maintenance expertise is aging out across Indian and Chinese glassworks without adequate apprenticeship pipeline replacement.
- Cross-border certification latency:Dual USP Type I and EP compliance timelines for borosilicate vial producers create 18-24 month market entry delays for new furnace qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Glass Bottles/Containers Market |
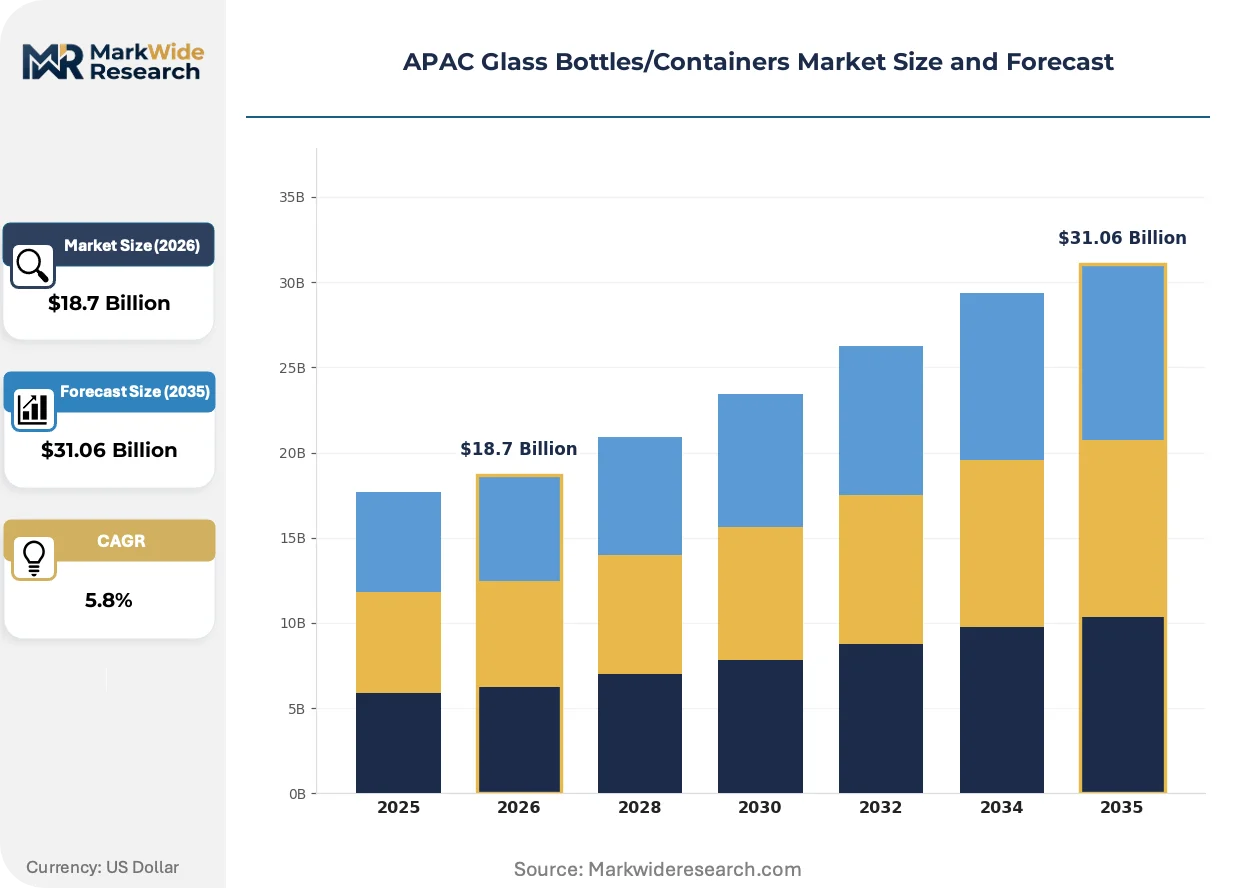
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine Bottles, Beverage Containers, Pharmaceutical Vials, Cosmetic Jars Closure Type: Cork, Screw Cap, Dropper, Pump Dispenser End User: Food Industry, Beverage Manufacturers, Personal Care Brands, Healthcare Providers Capacity: Small, Medium, Large, Custom Sizes |
| Companies Covered | Hindustan National Glass and Industries Ltd., PGP Glass Private Limited, Gerresheimer AG, O-I Glass, Inc., Ardagh Group S.A., Central Glass Co. Ltd., Haldyn Glass Ltd., Piramal Glass Pvt. Ltd., Toyo Seikan Group Holdings Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Glass Bottles/Containers Market Strategic Shifts
Active furnace technology diversification and regulatory chemistry mandates are fragmenting traditional production methodologies across the APAC container glass sector. These shifts are compressing legacy equipment depreciation cycles while opening specialized capability niches.
Lightweighting technology through narrow-neck press-and-blow forming is fragmenting standard container weight specifications across APAC beverage packaging. Japanese brewers and Australian wine exporters are adopting sub-300 gram standard wine bottles at accelerated replacement rates. This technology is compressing per-unit silica sand consumption while demanding precision mold investments that smaller regional producers cannot absorb.
China's GB 4806.5 heavy-metal migration limits are forcing furnace chemistry reformulations that exclude certain recycled cullet streams. Domestic producers in Jiangsu and Zhejiang are investing in raw material beneficiation to maintain lead and cadmium thresholds. Pharmaceutical and infant food glass segments are most affected, with some producers abandoning multi-purpose furnace strategies in favor of dedicated premium-grade lines.
Brand-led packaging specification convergence is consolidating procurement authority at multinational beverage and cosmetics headquarters. APAC regional supply managers are losing autonomy over container design decisions as global sustainability targets override local sourcing preferences. This pattern is most visible in South Korean and Australian markets where multinational beauty and alcohol brands operate centralized packaging innovation centers.
APAC Glass Bottles/Containers Market Segmentation
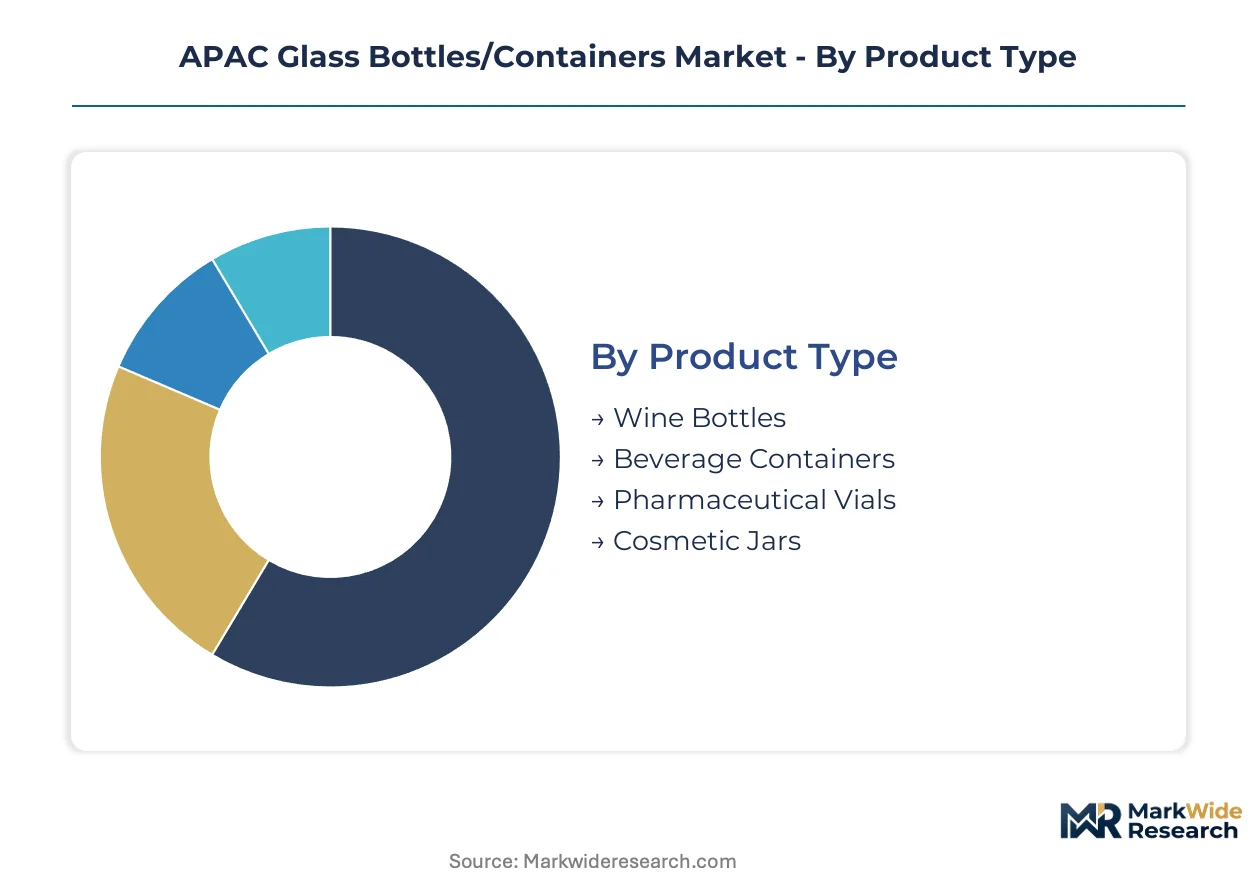
Glass container demand fragments across incompatible performance specifications, with pharmaceutical and cosmetic segments commanding premium furnace capacity while beverage volume drives raw material procurement scale. Substitution threats from aluminum and PET concentrate unevenly across these divisions, reshaping capital allocation priorities for regional producers.
Product Type:
Aluminum cans and flexible pouches exert the strongest displacement pressure on standard beverage containers, while pharmaceutical and cosmetic glass faces minimal viable substitution due to regulatory and brand equity barriers.
- Pharmaceutical Vials:Borosilicate glass manufactured to USP Type I and EP standards provides thermal shock resistance and chemical inertness for parenteral drug storage. Mumbai and Hyderabad drug manufacturers anchor regional demand as CDSCO tightens packaging material certification.
- Cosmetic Jars:Heavyweight flint and cobalt-tinted glass delivers shelf differentiation for premium skincare brands. South Korean serum producers are converting PET lines to glass, driving specialized forming equipment investments.
- Wine Bottles:Standard and lightweight configurations serve Australian and Chinese export markets with sub-300 gram narrow-neck press-and-blow variants gaining adoption.
- Beverage Containers:Food-grade soda-lime glass for juices, spirits, and non-alcoholic drinks faces sustained aluminum substitution in sports beverage segments.
Pharmaceutical vials anchor the volume base while cosmetic jars gain share at the steepest rate.
Closure Type:
Premium positioning strategies diverge sharply by closure mechanism, with pump and dropper systems capturing value in personal care while screw caps dominate cost-sensitive beverage applications.
- Pump Dispenser:Precision-molded glass neck finishes accommodate metered dosage systems for high-viscosity skincare formulations. Japanese and South Korean beauty brands specify these for premium serum and essence packaging.
- Dropper:Borosilicate-compatible pipette assemblies serve pharmaceutical tincture and cosmetic oil segments with tamper-evident glass bulb integration.
- Screw Cap:Standardized thread specifications dominate beverage and food container segments where cost minimization overrides dispensing sophistication.
- Cork:Traditional sealing for wine and spirits maintains position in premium positioning despite synthetic closure advances.
Pump dispensers command the highest unit value while screw caps process the greatest absolute volume.
End User:
Customer procurement sophistication varies dramatically, with healthcare and personal care buyers enforcing batch traceability that food and beverage purchasers rarely demand.
- Healthcare Providers:Hospital systems and clinic networks source USP-certified vials through qualified distributors with mandatory serialization compliance.
- Personal Care Brands:Multinational cosmetics headquarters in Seoul and Sydney centralize packaging specifications, overriding regional supply manager autonomy.
- Beverage Manufacturers:Brewers and soft drink bottlers dominate absolute tonnage consumption with lightweighting mandates compressing per-unit material costs.
- Food Industry:Infant formula and premium sauce producers face China's GB 4806.5 heavy-metal thresholds, forcing dedicated furnace lines.
Beverage manufacturers consume the most silica sand tonnage while personal care brands drive the fastest specification upgrading.
Capacity:
Scale economies in furnace operation favor standardized capacity ranges, though pharmaceutical and cosmetic segments sustain viable demand for non-standard configurations.
- Small:5-30 milliliter vials and ampoules serve injectable drug and sample-size cosmetic markets with precision forming tolerances.
- Medium:100-500 milliliter bottles balance handling convenience with production efficiency across wine and spirits applications.
- Large:Multi-liter carboys and demijohns retain niche demand for food service and industrial chemical containment.
- Custom Sizes:Non-standard dimensions accommodate proprietary brand architectures and specialized pharmaceutical dosing requirements.
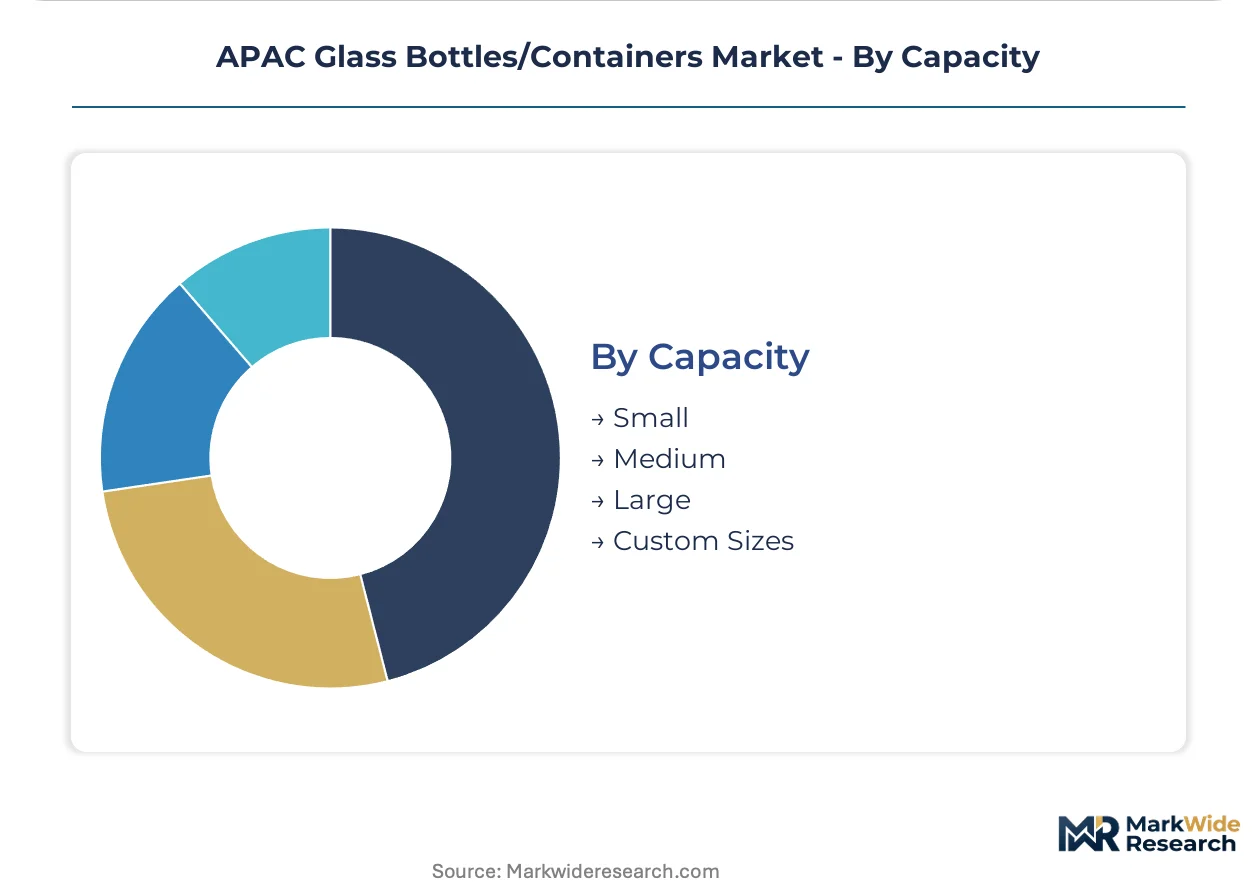
Medium capacity formats dominate furnace throughput while custom sizes capture the most specialized margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Furnace capacity clusters heavily in eastern China and western India, with specialized borosilicate production concentrating in Japan and pharmaceutical-grade forming in South Korea. These supply nodes anchor raw material procurement networks and export logistics for container glass across the broader region.
China
Shandong and Hebei provinces host the densest furnace networks serving beverage and food container demand. SAMR enforcement of GB 4806.5 heavy-metal thresholds is forcing batch chemistry reformulations that exclude certain recycled cullet streams. Zhejiang molders near Ningbo are investing in raw material beneficiation to maintain lead and cadmium compliance for infant food segments.
India
Mumbai and Hyderabad anchor pharmaceutical vial demand as CDSCO tightens BIS certification for injectable drug packaging. Hindustan National Glass leverages integrated furnace networks across Maharashtra and Gujarat to supply domestic beverage producers. Haldyn Glass and Piramal Glass occupy positions within this tiered supplier landscape.
Japan
Central Glass and Toyo Seikan sustain specialized forming capabilities for premium cosmetic and pharmaceutical applications. METI circular economy guidelines are shifting batch composition targets toward post-consumer cullet incorporation. Kanto-based producers face rising energy costs that compress furnace operating margins.
South Korea
Seoul-headquartered cosmetics brands are converting serum packaging from PET to heavyweight flint glass, creating demand for borosilicate-compatible equipment. MFDS pharmaceutical regulations align with USP Type I standards for export-oriented drug packaging. Busan-Ulsan logistics hubs support regional distribution for specialized container exports.
Vietnam
Ho Chi Minh City logistics corridors show underpenetrated glass container production relative to ASEAN beverage demand. Greenfield furnace investment potential exists near port infrastructure serving export markets. Domestic breweries and soft drink bottlers currently rely on imported containers from Thailand and China.
APAC Glass Bottles/Containers Market Competitive Environment
Concentration sits with integrated furnace operators and specialized pharmaceutical molders rather than fragmented commodity producers. The market structure tiers into scale-driven beverage container specialists, premium pharmaceutical-grade formers, and diversified packaging conglomerates. Strategic moves center on furnace technology upgrades for emissions compliance and backward integration into raw material beneficiation. Geographic expansion into Vietnam and Indonesia represents the second dominant competitive vector.
Within the integrated Indian tier, Hindustan National Glass and Industries Ltd. and Haldyn Glass Ltd. occupy positions as domestic furnace network operators. Among specialized pharmaceutical formers, Gerresheimer AG exemplifies the premium-grade archetype with regulated export market focus. Toyo Seikan Group Holdings Ltd. and Central Glass Co. Ltd. represent Japanese diversified packaging conglomerates with cosmetic and pharmaceutical specialization. These named entities anchor the competitive structure without exhausting the supplier landscape.
| Leading Market Players |
|---|
| Hindustan National Glass and Industries Ltd. |
| PGP Glass Private Limited |
| Gerresheimer AG |
| O-I Glass, Inc. |
| Ardagh Group S.A. |
| Central Glass Co. Ltd. |
| Haldyn Glass Ltd. |
| Piramal Glass Pvt. Ltd. |
| Toyo Seikan Group Holdings Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Indian pharmaceutical manufacturers and borosilicate vial suppliers lock in furnace capacity allocation and insulate qualified producers from spot soda ash volatility. These arrangements concentrate pricing power among USP Type I certified molders while forcing beverage container specialists into more exposed commodity procurement cycles.
Pricing Analysis
China's SAMR GB 4806.5 standards dictate the pricing tier structure across food-contact glass segments. Three-tier pricing separates pharmaceutical-grade borosilicate from standard flint and economy soda-lime containers. Certification grade and volume scale drive price differentiation, with CDSCO-mandated BIS compliance creating entry barriers that sustain premium positioning. Cost compression in beverage-grade containers is intensifying because aluminum substitution erodes glass share in sports drinks. Beverage manufacturers exhibit the highest price sensitivity, while cosmetic brands in Seoul demonstrate minimal elasticity for heavyweight flint serum packaging.
Supply Chain Analysis
China and India anchor furnace capacity across the APAC container glass sector. Shandong and Hebei provinces in China concentrate beverage-grade production, while Maharashtra and Gujarat in India host pharmaceutical-specialized networks. Raw material procurement draws from Australian silica sand deposits, Chinese synthetic soda ash, and limestone from Vietnamese quarries. Single-source vulnerability concentrates in qualified borosilicate furnace operations, where limited USP Type I certified capacity creates supply bottlenecks for parenteral drug packaging. Distribution runs through Ho Chi Minh City and Busan-Ulsan logistics hubs serving ASEAN and Northeast Asian demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects qualified incumbents. CDSCO and SAMR certification requirements create switching costs that lock pharmaceutical buyers into validated supplier relationships.
For Market Incumbents: Shield market position by accelerating backward integration into raw material beneficiation for heavy-metal compliance. Secure additional USP Type I furnace capacity in the Mumbai-Hyderabad corridor before CDSCO certification deadlines filter out marginal competitors. Aluminum substitution in sports beverages represents the most acute substitution threat requiring defensive capacity reallocation toward cosmetic and pharmaceutical grades. For New Entrants and Emerging Players: CDSCO fast-track certification pathways offer the most viable entry mechanism for specialized pharmaceutical vial production. Target Vietnam's underpenetrated glass container production relative to ASEAN beverage demand as the most penetrable geography. Greenfield furnace investment near Ho Chi Minh City port infrastructure, paired with technical licensing agreements from established Japanese molders, provides a credible go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward diversified packaging conglomerates with demonstrated pharmaceutical-grade forming capabilities and established regulatory compliance track records. Long-term viability hinges on furnace technology diversification for emissions compliance and circular economy integration. Watch for METI circular economy guideline expansion into mandatory cullet incorporation targets as the signal indicating accelerated batch composition shifts and capital requirements for incumbent furnace upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Beneficiation | GB 4806.5 compliance forces investment in heavy-metal reduction systems for infant food segments. |
| USP Type I Furnace Capacity Expansion | CDSCO tightening creates supply bottlenecks for parenteral drug packaging in Mumbai-Hyderabad corridors. |
| Electric Melting Pilot Installation | China's MEE dual carbon directives accelerate technology transition in Shandong and Hebei provinces. |
| Post-Consumer Cullet Integration | METI circular economy guidelines shift batch composition targets for Toyo Seikan and Central Glass operations. |
| Pharmaceutical Serialization Service Bundling | Track-and-trace convergence with molded vial production enables integrated packaging-traceability offerings for export markets. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with furnace operations managers, pharmaceutical procurement leads at CDSCO-regulated manufacturers, cosmetic packaging specification directors, and beverage supply chain executives; alongside secondary validation through BIS certification databases, SAMR GB standard filings, customs trade records for silica sand and soda ash, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity modeling triangulated against top-down demand segmentation across product types and end-use applications.
Across the analysis window, forecasts applied segmented growth rate derivation by product type, closure mechanism, end-user sophistication, and capacity format. Modeled dimensions included pharmaceutical certification tier, cosmetic premium positioning, beverage lightweighting adoption, and regional regulatory cluster alignment. CAGRs were computed from installed furnace capacity trajectories, raw material cost pass-through elasticity, and substitution threat intensity by end-use segment.
Decision-makers should treat outputs as directional under sustained CDSCO enforcement and China's dual carbon policy continuity; material deviation in regulatory timelines or energy cost trajectories would warrant model refresh. Recalibration cycles align with material shifts in SAMR standard revisions, MEE emissions directive updates, and pharmaceutical serialization mandate rollouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Glass Decanters Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Australia Container Glass Market