
 Retail Glass Packaging Market | 2026-2036
Retail Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Glass Packaging Market Analytics
European container glass manufacturers is pivoting toward lightweighting technologies and closed-loop recycling infrastructure. Owens-Illinois Inc. leverages its furnace refurbishment programs to sustain energy efficiency across multiple production sites. Ardagh Group anchors its competitive stance through geographic dominance in Northern European beverage contracts. Verallia differentiates via specialized pharmaceutical and cosmetic glass lines with premium surface treatments.
Retail glass packaging encompasses silica-based containers formed through blow-and-blow or press-and-blow processes, typically containing 70-75% silicon dioxide with sodium carbonate and calcium oxide fluxes, engineered to provide inert barriers against oxygen and moisture for consumable and cosmetic goods. Bottles occupy the largest volume share within product type segmentation, particularly in wine and spirits applications where UV-blocking amber and flint grades command margin premiums. Jars represent the fastest-expanding category within food end users, driven by premium preserves and spread brands abandoning multi-layer plastic laminates. Lightweight weight-class containers are displacing standard-weight equivalents in mass-market beverages as brands pursue freight cost reductions without sacrificing mechanical strength thresholds.
The European Commission's Packaging and Packaging Waste Regulation alongside ECHA REACH compliance requirements are mandating minimum recycled content thresholds and restricting heavy metal leachates in colored glass. FDA Type III soda-lime specifications and US EPA emissions standards for glass melting furnaces shape cross-border product qualification and capital expenditure planning for exporters. Stakeholders must monitor evolving extended producer responsibility fee structures and lightweighting certification protocols to align capacity investments with shifting compliance cost burdens.
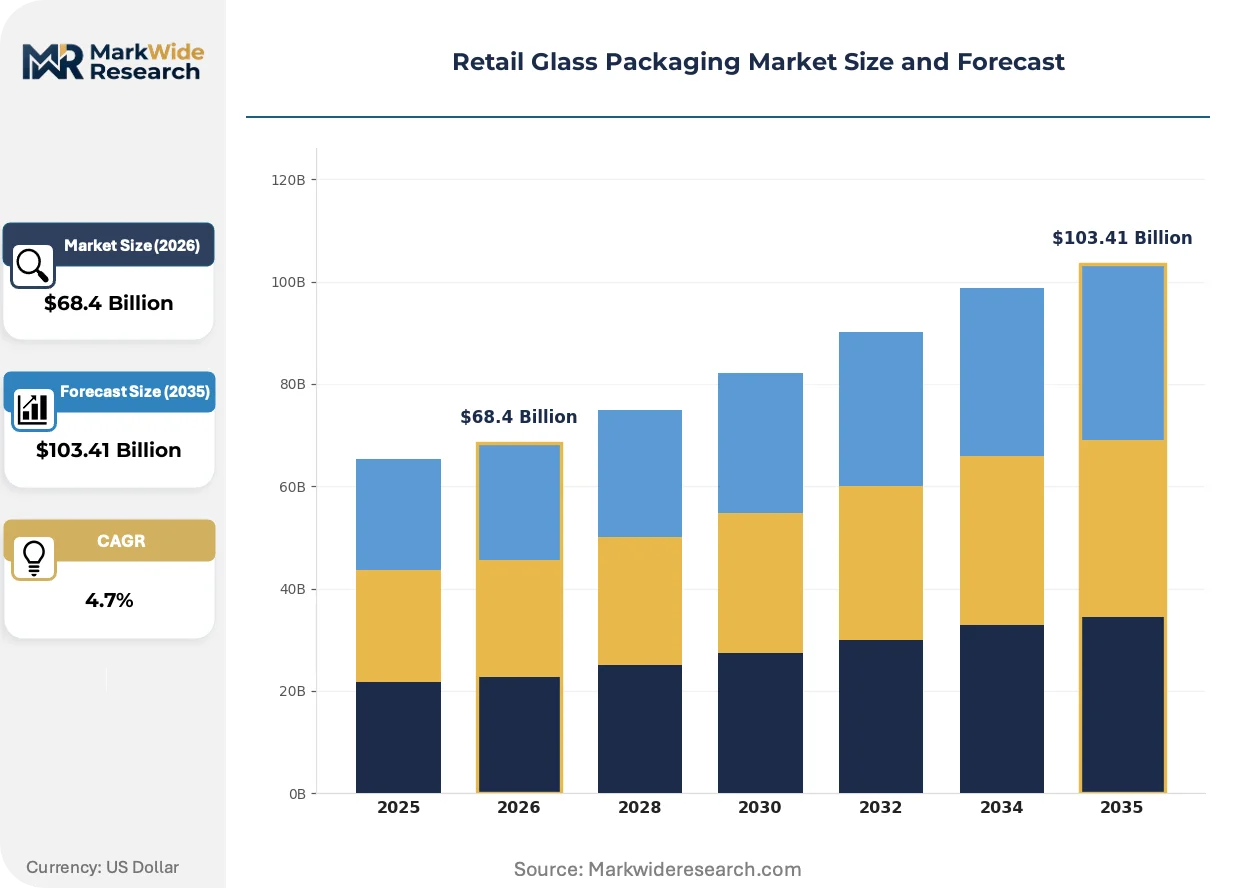
Market Dynamics
The EU Green Deal's carbon intensity mandates are compressing margins across European container glass manufacturers while simultaneously accelerating furnace refurbishment cycles and closed-loop recycling investments.
Growth Catalysts
- EU Green Deal Packaging Rules:Mandatory recycled content thresholds under the Packaging and Packaging Waste Regulation are pulling beverage producers toward returnable glass systems in Germany and France.
- Premium Cosmetic Migration:Skincare and fragrance brands in France are abandoning plastic laminates for UV-blocking amber glass, creating pull-through demand for specialized surface treatments.
- Lightweighting:Press-and-blow process innovations are reducing freight costs for mass-market beverage brands without compromising mechanical strength thresholds.
Market Restraints
- Energy Cost Volatility:Natural gas price spikes in Germany and Italy are destabilizing furnace economics for mid-tier producers without long-term supply contracts.
- Soda Ash Supply Concentration:Turkish and Chinese suppliers control over 60% of European soda ash feedstock, exposing converters to geopolitical freight disruptions.
- Plastic Substitution Threat:Advanced polyethylene terephthalate barrier coatings are recapturing share in still water and cooking oil segments where glass held temporary advantage.
Strategic Opportunities
- Pharmaceutical Glass Expansion:EMA's tightened extractables testing protocols are disqualifying plastic alternatives for parenteral packaging, opening volume for Type I borosilicate suppliers.
- Deposit-Return Infrastructure:Germany's DRS expansion into non-alcoholic beverages is creating captive demand for standardized returnable bottle formats.
- Cosmetic Airless Integration:Convergence of glass primary packaging with airless pump mechanisms is commanding 40-60% price premiums in prestige skincare channels.
Industry Challenges
- Furnace Engineer Scarcity:Specialized refractory and combustion expertise required for oxy-fuel conversions is concentrating among retiring cohorts in Czech and Polish manufacturing clusters.
- REACH Compliance Timelines:ECHA's evolving heavy metal leachate testing protocols are extending product qualification cycles for colored glass exports by 8-14 months.
- Legacy MES Integration:Brownfield sites in Northern France and Belgium face data architecture friction when connecting lightweighting monitoring systems to 1990s-era manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Glass Packaging Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tumblers End User: Cosmetics, Food & Beverage, Pharmaceuticals, Home Care Weight: Lightweight, Standard, Heavyweight, Extra Heavyweight Closure Type: Screw Caps, Corks, Snap Lids, Metal Caps |
| Companies Covered | Owens-Illinois Inc., Ardagh Group, Verallia, Gerresheimer AG, Vidrala S.A., Vetropack Holding Ltd, BA Glass BV, Schott AG, Piramal Glass Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Glass Packaging Market Evolving Landscape
Active modifications to furnace design, regulatory testing protocols, and procurement structures are redistributing competitive advantage across European glass packaging value chains.
Thin-wall container technology is modularizing production economics across European glassworks. Advanced press-and-blow controls enable 15-20% weight reduction in standard wine bottles without sacrificing vertical load strength. German beverage cooperatives are adopting these formats aggressively to offset diesel freight surcharges, compressing per-unit logistics costs while maintaining shelf presence parity with heavier legacy formats.
REACH Annex XVII amendments are tightening cadmium and lead leachate limits for colored glassware intended for food contact. The industrial consequence is a forced migration to selenium and cobalt decolorizers in flint and emerald green production. French tableware exporters targeting US retail channels are most affected, accelerating third-party migration testing investments to preempt FDA import detentions.
Consolidated buying desks at major beverage groups are compressing supplier rosters and extending contract tenors. Carrefour and Rewe's centralized packaging procurement functions now demand decade-long volume commitments with embedded lightweighting improvement clauses. This behavior is most visible in German discount retail, where private-label water and juice brands are locking in dual-source arrangements with Ardagh and Verallia to secure furnace allocation priority.
Retail Glass Packaging Market Segmentation
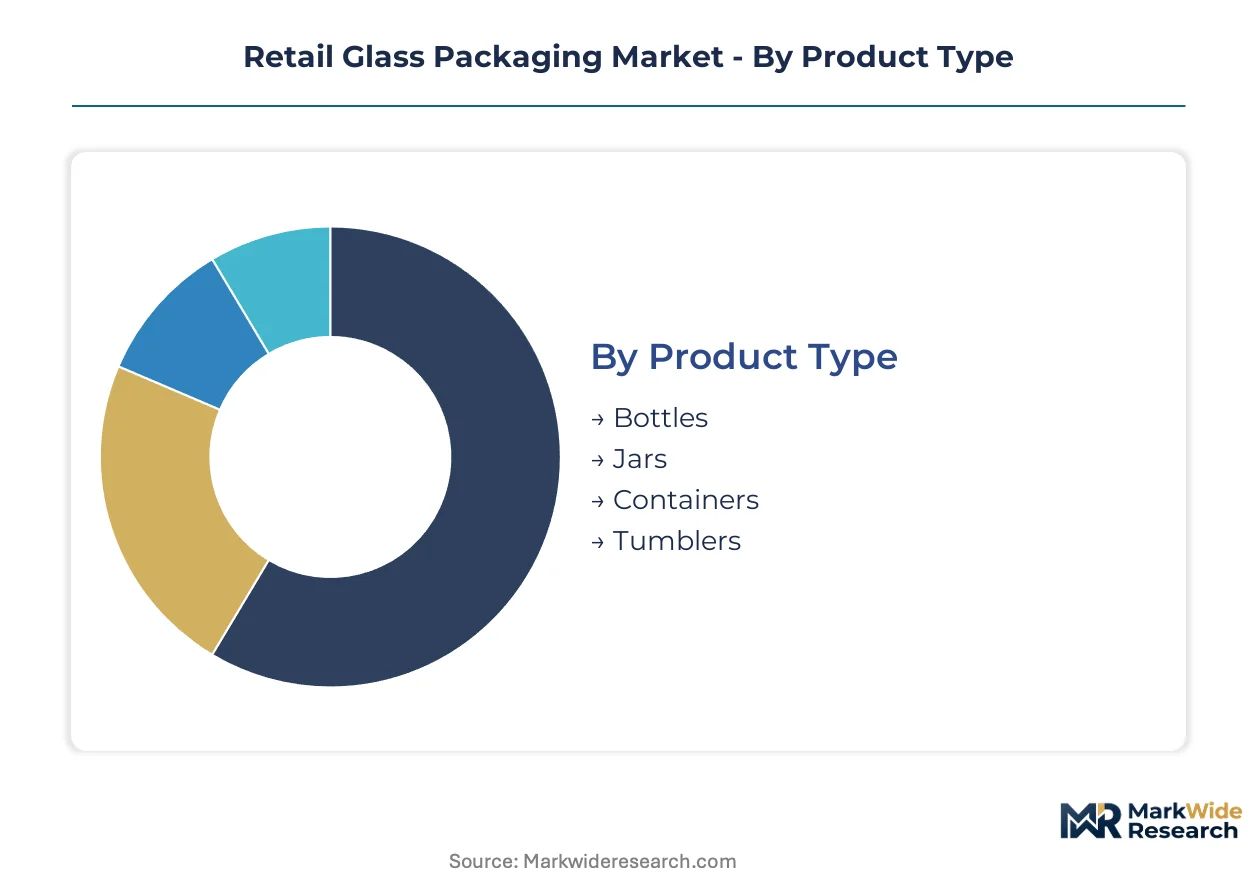
Glass packaging segmentation reveals how furnace allocation and mold investments concentrate around high-margin formats. Distinct product specifications, end-use requirements, and weight classifications create divergent capital intensity profiles across converter portfolios.
Product Type:
Supply concentration clusters around formats with the longest production runs and highest mold utilization rates.
- Bottles:Silica-based containers formed through blow-and-blow or press-and-blow processes, containing 70-75% silicon dioxide with sodium carbonate and calcium oxide fluxes. Wine and spirits producers in France and Germany absorb the majority of amber and flint grade capacity, with UV-blocking variants commanding margin premiums in premium spirits channels.
- Jars:Wide-mouth containers engineered for viscous contents and repeated access. Premium preserves and spread brands in Northern Europe are abandoning multi-layer plastic laminates for glass alternatives, driving the steepest expansion trajectory within food end users.
- Containers:Rectangular or cylindrical formats optimized for shelf efficiency and label adhesion. Pharmaceutical and cosmetic applications dominate demand for Type III soda-lime specifications.
- Tumblers:Straight-sided drinking vessels with minimal neck constriction. Candle and home fragrance brands in Germany represent the primary volume sink for this format.
Bottles absorb the bulk of installed capacity; jars are expanding most quickly.
End User:
Margin tiers separate applications by regulatory burden and surface treatment complexity.
- Food & Beverage:The foundational demand pool spanning still water, carbonated soft drinks, beer, wine, spirits, and preserved foods. German beverage cooperatives are converting from plastic to returnable glass systems under EU Green Deal packaging rules, locking in decade-long furnace commitments.
- Cosmetics:Skincare serums and fragrances require specialized surface treatments and UV-blocking amber grades. French premium brands are driving adoption of airless pump integrations that command substantial price premiums.
- Pharmaceuticals:Parenteral and oral solid dosage packaging governed by EMA extractables testing protocols. Type I borosilicate specifications are displacing plastic alternatives as regulatory thresholds tighten.
- Home Care:Dish and laundry applications with lower barrier requirements. This segment faces persistent substitution pressure from polyethylene terephthalate barrier coatings in mass-market channels.
Food & beverage commands the majority of furnace hours; cosmetics is climbing the fastest on value per ton metrics.
Weight:
Freight economics and mechanical strength trade-offs are redistributing volume across weight classifications.
- Lightweight:Containers achieving 15-20% material reduction through advanced press-and-blow controls without sacrificing vertical load strength. German discount retailers are adopting these formats aggressively to offset diesel freight surcharges.
- Standard:Conventional weight classes serving established beverage and food brands with legacy filling line specifications. This category retains the largest installed base of molds and inspection equipment.
- Heavyweight:Reinforced structures for returnable bottle systems and premium spirits presentation. Germany's deposit-return infrastructure expansion is sustaining demand for durable formats.
- Extra Heavyweight:Specialized containers for high-pressure contents or extreme reuse cycles. Limited to niche pharmaceutical and luxury spirits applications.
Standard weight retains the deepest mold inventory; lightweight formats are gaining share fastest on logistics cost advantages.
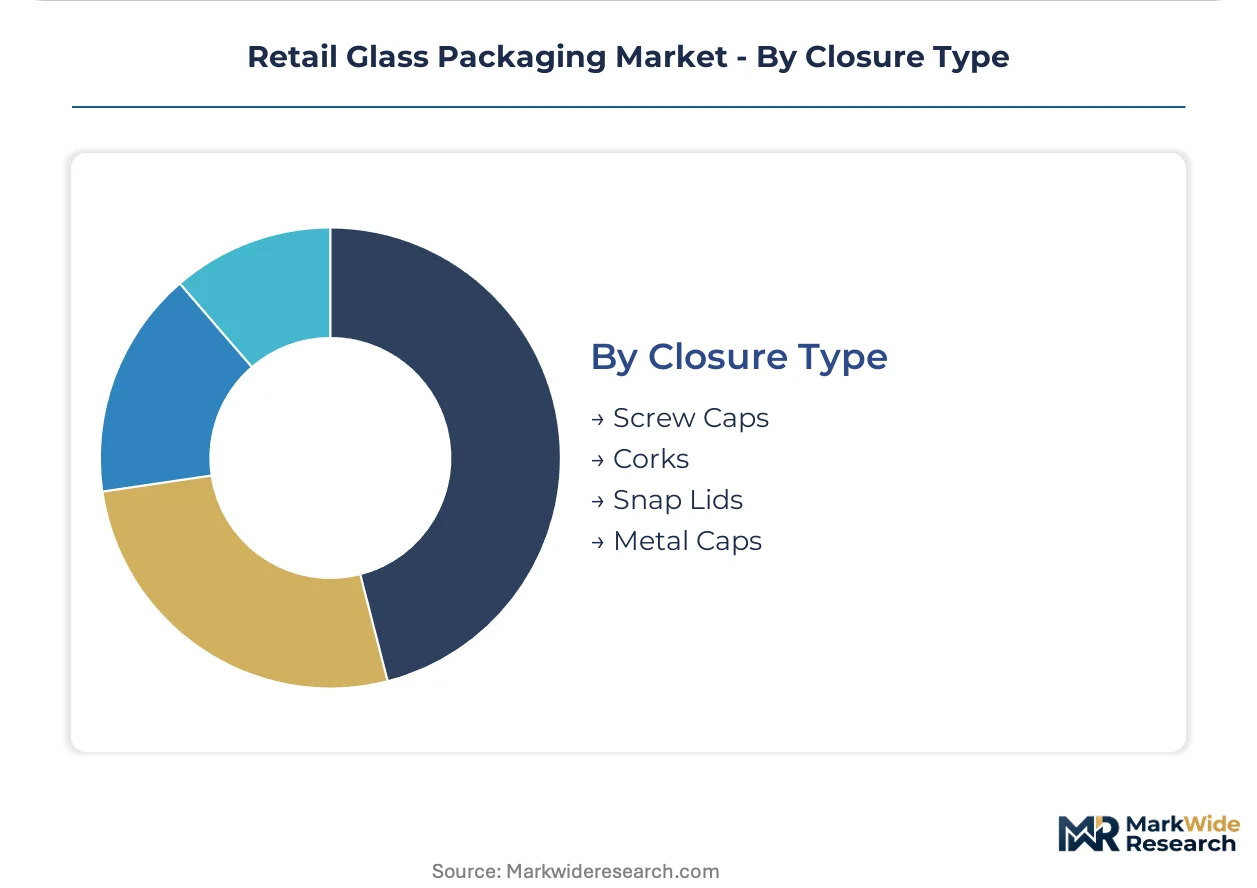
Closure Type:
Sealing mechanism selection tracks end-use shelf stability requirements and consumer convenience expectations.
- Screw Caps:Threaded aluminum or plastic closures enabling resealability and controlled dispensing. Wine and spirits producers in France and Germany are standardizing on these formats for retail channels.
- Corks:Natural or agglomerated bark seals preserving traditional wine aging protocols. Premium Bordeaux and Burgundy houses maintain demand despite synthetic substitution in volume tiers.
- Snap Lids:Press-fit metal closures for wide-mouth jars requiring repeated access. Food preservers and spread manufacturers favor this mechanism for consumer convenience.
- Metal Caps:Roll-on or crimped aluminum seals for carbonated beverages and pharmaceutical syrups. This format dominates returnable bottle systems where tamper evidence is mandatory.
Screw caps command the broadest application range; metal caps are tightening their hold on deposit-return system compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish and Chinese soda ash deposits supply over sixty percent of European glass flux requirements, anchoring feedstock dependency patterns that shape converter economics from furnace to finished container.
Germany
Beverage cooperatives in Bavaria and North Rhine-Westphalia are converting filling lines from polyethylene terephthalate to returnable glass systems under EU Green Deal packaging mandates. The country's deposit-return infrastructure expansion into non-alcoholic beverages locks in decade-long furnace commitments at Ardagh and Verallia plants. Cologne and Hamburg harbor zones concentrate import logistics for soda ash transshipment from Turkish suppliers.
France
Premium cosmetics houses in Île-de-France and Provence-Alpes-Côte d'Azur are abandoning plastic laminates for UV-blocking amber glass in skincare serums and fragrances. ECHA REACH Annex XVII amendments on cadmium and lead leachates are forcing pigment migrations to selenium and cobalt decolorizers at flint and emerald green production sites. Lorraine's historic glassmaking basin retains specialized pharmaceutical surface treatment capacity.
Italy
Consolidated wine cooperatives in Piedmont and Veneto are standardizing on lightweight press-and-blow formats to offset diesel freight surcharges across Alpine export routes. The country's national pharmaceutical regulator aligns Type III soda-lime specifications with EMA extractables protocols, qualifying domestic converters for parenteral packaging contracts. Tuscany's tableware exporters face extended FDA migration testing timelines for US retail channel access.
Spain
Vidrala's Castile and León production cluster serves Iberian beverage demand with furnace refurbishment programs targeting oxy-fuel conversion compliance. Spanish olive oil brands are resisting polyethylene terephthalate barrier coating substitution in export markets, sustaining glass bottle demand for extra virgin grades. Catalonia's cosmetic packaging specialists are integrating airless pump mechanisms with glass primary containers for prestige skincare channels.
Poland
Mid-tier converters in Silesia and Lower Silesia are capturing overflow volume from German beverage cooperatives seeking dual-source furnace allocation security. The country's glass engineering workforce concentrates specialized refractory and combustion expertise for oxy-fuel furnace conversions that retiring cohorts elsewhere in Europe no longer supply. Warsaw-based procurement desks are negotiating long-term natural gas supply contracts to stabilize furnace economics against Italian and German price volatility.
Retail Glass Packaging Market Competitive Landscape
Global majors compete with regional champions across furnace allocation and mold specialization, producing a tiered structure where scale-driven volume players, premium-format specialists, and mid-tier private-label suppliers each occupy defendable positions. Three archetypes dominate: integrated container giants with multi-site furnace networks, cosmetic-pharmaceutical specialists commanding surface treatment premiums, and regional cooperatives serving protected beverage geographies. Competitive moves concentrate on capacity reservation through decade-long supply contracts and lightweighting technology licensing to secure freight cost advantages.
Among integrated container giants, Owens-Illinois Inc. and Ardagh Group exemplify scale-driven archetypes with geographic dominance in Northern European beverage contracts. Verallia occupies a position within the premium-format specialist tier, differentiating through specialized pharmaceutical and cosmetic glass lines. Gerresheimer AG represents the pharmaceutical purity segment, anchoring Type I borosilicate supply as EMA extractables protocols tighten. These named entities illustrate how furnace refurbishment programs, geographic contract concentration, and regulatory compliance specialization distribute competitive advantage across converter portfolios.
| Leading Market Players |
|---|
| Owens-Illinois Inc. |
| Ardagh Group |
| Verallia |
| Gerresheimer AG |
| Vidrala S.A. |
| Vetropack Holding Ltd |
| BA Glass BV |
| Schott AG |
| Piramal Glass Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Specialized furnace engineering talent concentrated in Czech and Polish manufacturing clusters feeds labor-cost differentials that widen pricing spreads between premium lightweight formats and standard-weight commodity containers. EU Green Deal compliance investments at German and French sites compress margins on mid-tier production while specialized pharmaceutical surface treatments at Lorraine facilities sustain premium capture.
Pricing Analysis
Warranty and service bundling separates converter offerings, with decade-long furnace allocation commitments including embedded lightweighting improvement clauses commanding premiums over transactional spot purchasing. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade—EMA extractables-compliant Type I borosilicate versus standard Type III soda-lime—and by geographic delivery cost from Northern European production hubs. Pricing pressure stems from natural gas cost volatility destabilizing mid-tier furnace economics. Mass-market beverage brands exhibit highest price sensitivity; cosmetic and pharmaceutical buyers prioritize surface treatment quality over unit cost.
Supply Chain Analysis
Returnable bottle reverse-logistics infrastructure in Germany anchors closed-loop material flows, with deposit-return system expansion into non-alcoholic beverages creating standardized collection and refurbishment cycles. Raw material supply concentrates in Turkey and China for soda ash feedstock, with German and Italian converters drawing from these sources for 60% of flux requirements. Soda ash freight disruption risk from geopolitical chokepoints at Bosporus and Suez corridors threatens furnace economics. Distribution runs through harbor zones at Cologne and Hamburg for import transshipment, with rail links to Ardagh and Verallia plant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU Green Deal carbon intensity mandates and furnace refurbishment capital requirements force weaker mid-tier producers without long-term supply contracts toward exit or acquisition.
For Market Incumbents: Hedge against energy cost volatility by securing decade-long natural gas supply contracts at Polish and Czech sites where engineering talent sustains oxy-fuel conversion capability. Prioritize backward integration into closed-loop recycling infrastructure to capture deposit-return system volume and defend margin position against lightweighting technology licensing competitors. For New Entrants and Emerging Players: Capture overflow furnace allocation from German beverage cooperatives seeking dual-source security by establishing Silesia-based production with specialized pharmaceutical surface treatment qualifications. Target cosmetic airless pump integration segments where glass-primary packaging commands substantial premiums over plastic alternatives. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-cosmetic specialists given EMA extractables protocol tightening that disqualifies plastic alternatives for parenteral packaging. Long-term viability over a multi-year window favors converters with captive lightweighting technology and geographic concentration in Northern European beverage contracts. Monitor REACH Annex XVII heavy metal leachate testing timeline extensions as early signals of qualification cost escalation affecting colored glass exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Oxy-Fuel Conversion | Reduces carbon intensity per EU Green Deal mandates at German and Italian sites. |
| Lightweighting Technology Licensing | Enables 15-20% material reduction for French and German beverage cooperatives. |
| Closed-Loop Recycling Infrastructure | Captures deposit-return system volume expansion in Germany's non-alcoholic segment. |
| Pharmaceutical Surface Treatment Capacity | Qualifies converters for EMA extractables-compliant Type I borosilicate contracts. |
| Long-Term Natural Gas Supply Agreements | Stabilizes furnace economics against Italian and German price volatility exposure. |
Research Methodology
Document review covered EU regulatory filings including ECHA REACH Annex XVII amendments, FDA Type III soda-lime specifications, and EPA emissions standards for glass melting furnaces, complemented by interviews with furnace engineering directors at Czech and Polish manufacturing clusters, procurement leads at German beverage cooperatives, cosmetic packaging specialists in Île-de-France, and pharmaceutical quality assurance managers. Secondary validation drew from customs trade data for soda ash import flows, SEC 10-K disclosures from integrated container manufacturers, and industry association capacity reports. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Segment-level outputs across product type, end user, weight classification, and closure type dimensions were generated over the projection horizon. CAGRs derived from regression analysis of historical furnace utilization rates, lightweighting adoption curves, and regulatory compliance cost trajectories. Forecast inputs incorporated natural gas price volatility scenarios, soda ash supply disruption probabilities, and deposit-return system expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Packaging and Packaging Waste Regulation recycled content threshold revisions and ECHA heavy metal leachate protocol amendments. Practitioners should monitor Turkish soda ash export license policies and German DRS format standardization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market