
 Kenya Container Glass Market | 2026-2036
Kenya Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Kenya Container Glass Market Insights
Electric melting furnace technology is reconfiguring energy profiles at Kenyan container glass plants. Impala Glass Industries leverages its Mombasa facility location to anchor regional distribution across East Africa. Empire Glass Industries competes through specialized pharmaceutical-grade amber glass production. East African Glass Industries sustains cost advantages via cullet recycling integration with local beverage return schemes.
Container glass denotes soda-lime silica vessels formed through blow molding or press molding, annealed to withstand internal pressure and thermal shock, primarily serving liquid and semi-solid product containment. Bottles dominate volume throughput for beverage and pharmaceutical applications, while jars command premium positioning in cosmetics and specialty food segments. Blow molding leads manufacturing stage deployment for thin-walled, high-throughput bottle production, whereas press molding occupies niche markets requiring heavier base configurations.
Kenya Bureau of Standards enforces KS 1864 specifications for glass container dimensional tolerance and chemical durability, shaping product qualification requirements for domestic and export-bound manufacturers. National Environment Management Authority mandates emissions thresholds from furnace operations, directing capital allocation toward filtration and heat-recovery systems. Stakeholders must monitor KEBS alignment with evolving East African Community harmonization protocols to sustain cross-border market access without redundant certification burdens.
Market Dynamics
Electric melting furnace adoption is restructuring energy economics at Kenyan container glass facilities, compressing operational cost differentials between coastal and inland production locations while tightening KEBS quality enforcement reshapes product qualification thresholds for regional export.
Growth Catalysts
- Returnable bottle schemes:Beverage bottlers in Nairobi and Mombasa deploy closed-loop collection infrastructure, reducing raw material input costs and stabilizing cullet supply chains for furnace feedstock.
- KEBS KS 1864 alignment:Harmonization with East African Community protocols streamlines cross-border certification, eliminating redundant testing burdens for manufacturers serving Uganda and Tanzania.
- Pharmaceutical packaging demand:Regional drug manufacturers in the East African Community expand amber glass procurement for light-sensitive formulations, pulling specialized container capacity.
Market Restraints
- Natural gas price volatility:Furnace operations depend on imported LNG through Mombasa port, exposing energy cost instability to currency fluctuation and maritime supply disruption.
- Heavy soda ash import dependence:Kenya lacks domestic sodium carbonate production, concentrating input supply risk on South African and Egyptian chemical exporters.
- Plastic substitution pressure:PET bottle manufacturers in Nairobi industrial zones compete aggressively on lightweight logistics economics for non-premium beverage segments.
Strategic Opportunities
- Rwanda and Burundi penetration:Landlocked EAC neighbors lack indigenous container glass capacity, creating distribution white space for Kenyan producers with established regional logistics.
- Cosmetics jar specialization:Premium skincare brands in Nairobi's manufacturing zones seek differentiated thick-walled glass packaging for export positioning.
- NEMA emissions compliance incentives:Heat-recovery system investments qualify for accelerated depreciation, improving project returns for furnace upgrade cycles.
Industry Challenges
- Specialized furnace engineering talent:Electric melting retrofit projects require scarce refractory and combustion expertise, extending commissioning timelines.
- Legacy batch plant integration:Automated cullet sorting systems must interface with decades-old material handling infrastructure without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kenya Container Glass Market |
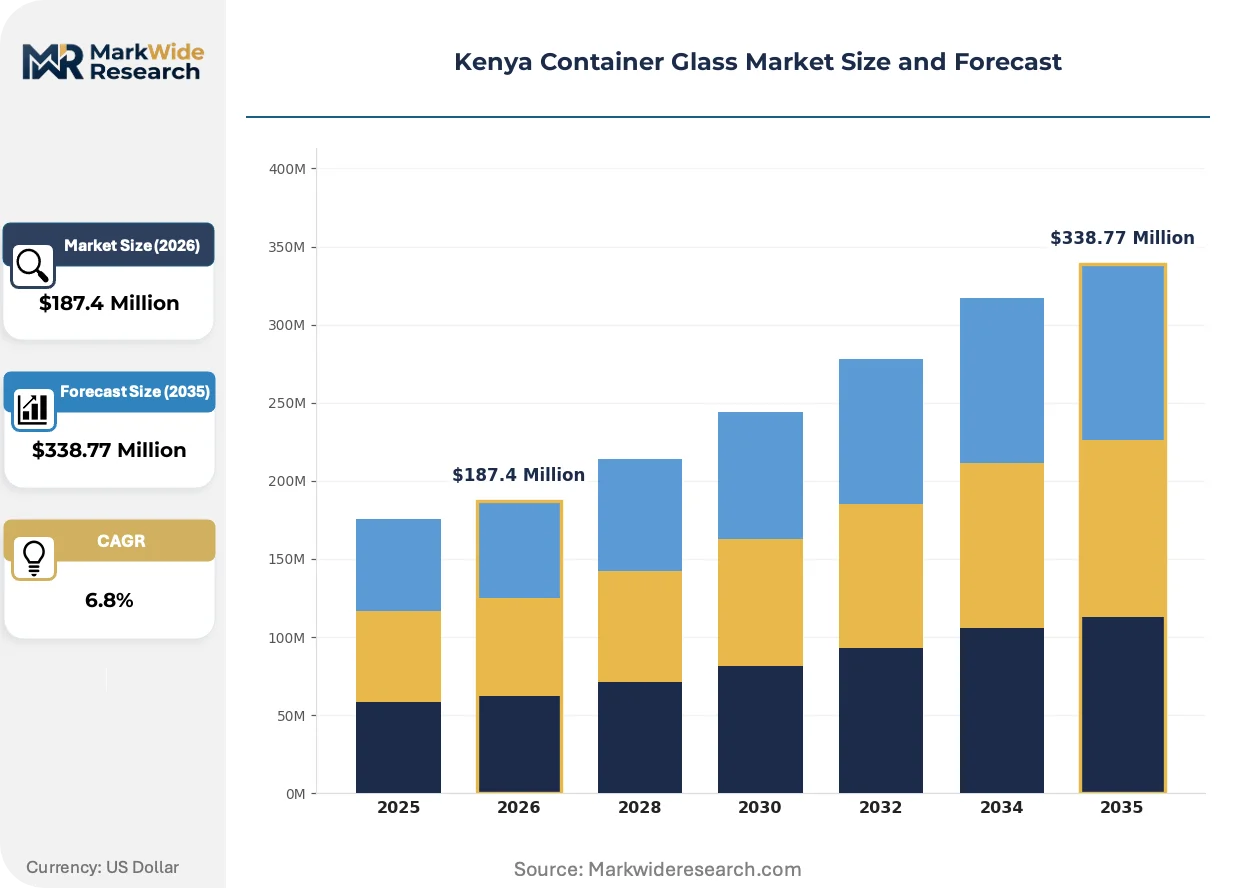
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Tumblers End User: Food Industry, Beverage Industry, Cosmetics, Pharmaceuticals Manufacturing Stage: Blow Molding, Press Molding, Glass Forming, Annealing Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Distributors |
| Companies Covered | Impala Glass Industries, Empire Glass Industries, East African Glass Industries, Kenya Glass Works Limited, Aluglass Africa, Emperor Glass Works, Coca-Cola Sabco, Bidco Africa, East African Breweries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kenya Container Glass Market Trends and Innovations
Container glass manufacturing in Kenya is experiencing technology substitution in melting systems, regulatory tightening on chemical durability standards, and buyer consolidation among beverage multinationals reshaping procurement concentration.
Oxy-fuel combustion technology is migrating from conventional air-fuel furnace designs at Mombasa-area plants, cutting nitrogen oxide emissions intensity while improving thermal efficiency. Premium spirits bottlers in Nairobi drive specification pressure for this transition, demanding lower particulate residue profiles. The shift compresses acceptable emissions thresholds across the domestic supplier base, forcing smaller furnace operators toward similar capital commitments or exit.
KEBS is tightening KS 1864 chemical durability testing protocols for food-contact glass, extending leachate examination to cover previously exempted decorative coatings and applied ceramic labels. This regulatory extension elevates compliance costs for exporters serving EAC harmonized markets. Pharmaceutical amber glass manufacturers face the steepest adaptation burden, reformulating base compositions to meet revised hydrolytic resistance grades without color shift.
Beverage procurement concentration is compressing supplier rosters as multinational bottlers in Nairobi consolidate glass sourcing under regional framework agreements. Long-term volume commitments replace spot purchasing, displacing smaller domestic converters from premium brand supply chains. This pattern concentrates most visibly in carbonated soft drink and beer segments, where three buyers now account for dominant volume throughput.
Kenya Container Glass Market Segmentation
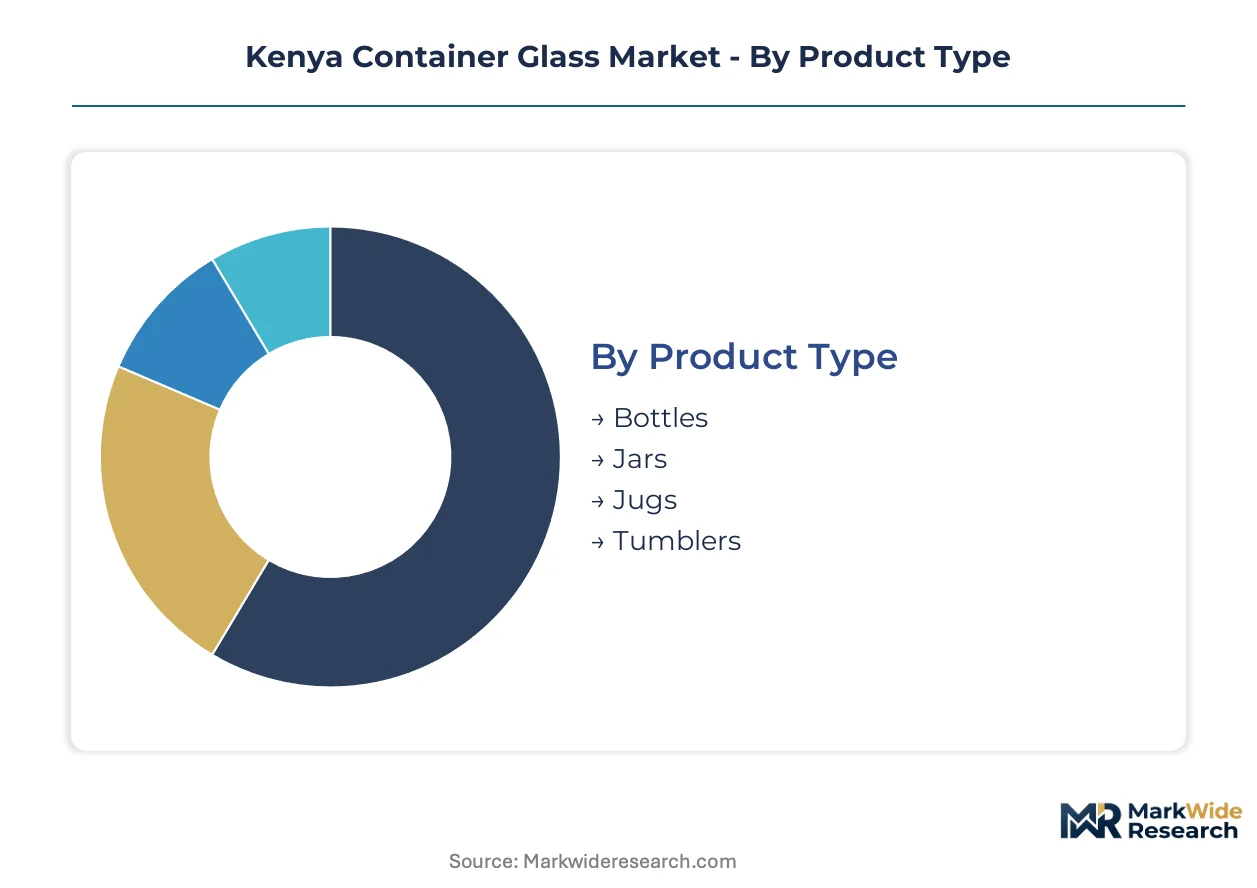
Segmentation in the Kenya container glass market reveals how furnace technology, regulatory compliance, and procurement consolidation reshape competitive boundaries across product formats and end-use applications. Distinct manufacturing economics and KEBS qualification thresholds separate premium pharmaceutical-grade output from commodity beverage containers.
Product Type:
Volume throughput and wall thickness specifications divide the product landscape into distinct furnace allocation and mold investment tiers.
- Bottles:Thin-walled soda-lime silica vessels formed through high-speed blow molding dominate furnace throughput. Nairobi beverage bottlers and Mombasa pharmaceutical exporters pull capacity for carbonated drinks, beer, and amber drug containers.
- Jars:Thicker-walled configurations with heavier base structures command premium positioning. Press molding or press-blow hybrid lines serve Nairobi cosmetics manufacturers and specialty food processors seeking differentiated shelf presence.
- Jugs:Intermediate capacity vessels bridge bottle and jar economics. Limited domestic demand concentrates in institutional food service and regional bulk beverage distribution.
- Tumblers:Open-top drinking vessels occupy niche capacity allocation. Hotel and restaurant supply chains in Nairobi and Mombasa drive intermittent batch production runs.
Bottles hold installed capacity. Jars is rotating up the share rankings.
End User:
Application-specific durability and chemical resistance requirements stratify qualification burdens and margin capture potential.
- Beverage Industry:Carbonated soft drink and beer bottlers in Nairobi generate highest volume demand. Returnable bottle schemes stabilize cullet supply chains while KEBS KS 1864 compliance enables cross-border EAC distribution.
- Pharmaceuticals:Amber glass for light-sensitive formulations demands hydrolytic resistance grade certification. Regional drug manufacturers in the East African Community pull specialized capacity from Empire Glass Industries and Impala Glass.
- Food Industry:Preserves, sauces, and condiment packagers specify chemical durability for acidic contents. KEBS tightening of leachate testing for decorative coatings elevates compliance costs.
- Cosmetics:Premium skincare brands seek thick-walled, visually differentiated packaging. Nairobi manufacturing zones drive specification pressure for press-molded jar configurations with applied ceramic labels.
Beverage Industry holds installed capacity. Pharmaceuticals is expanding most quickly.
Manufacturing Stage:
Process technology selection determines energy intensity, throughput velocity, and product dimensional precision.
- Blow Molding:Compressed air expansion of molten glass gobs into mold cavities achieves thin walls at high cycle speeds. Dominates bottle production for beverage throughput at coastal and inland facilities.
- Press Molding:Mechanical plunger compression forms heavier base configurations and precise rim geometries. Required for pharmaceutical amber glass and cosmetics jar segments demanding dimensional tolerance.
- Glass Forming:Broad category encompassing manual and semi-automatic shaping for specialty or prototype runs. Limited commercial scale in Kenyan operations.
- Annealing:Controlled cooling in lehr ovens relieves thermal stress and ensures mechanical durability. All container types require this stage; electric furnace retrofits integrate heat recovery for NEMA compliance.
Blow Molding holds installed capacity. Press Molding is climbing the fastest.
Distribution Channel:
Customer scale and order predictability determine logistics configuration and working capital requirements.
- Distributors:Regional stockholding intermediaries consolidate fragmented demand across Kenya and landlocked EAC neighbors. Impala Glass leverages Mombasa location for Rwanda and Burundi penetration.
- Wholesalers:Volume aggregators serving smaller beverage converters and food processors. Price-sensitive procurement concentrates in standard bottle formats with limited specification customization.
- Retail Stores:Direct procurement by micro-breweries and artisanal food producers. Limited scale; often served through distributor overflow or cash-and-carry arrangements.
- Online Platforms:Emerging channel for specialty cosmetics jar sampling and small-batch pharmaceutical packaging. Nairobi-based e-commerce logistics enable rapid prototype-to-production transitions.
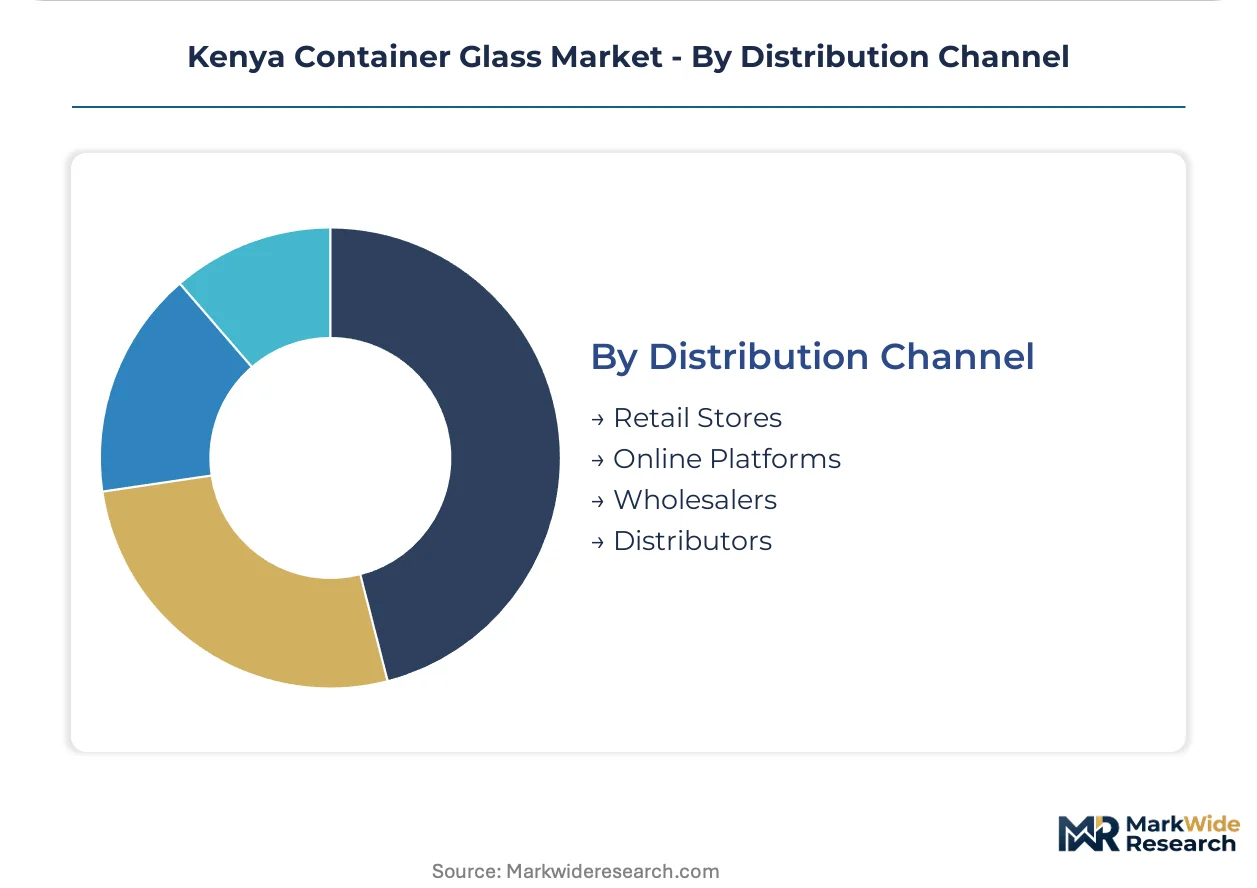
Distributors hold installed capacity. Wholesalers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers in Nairobi and Mombasa concentrate procurement volume, pulling container glass supply across East African Community trade corridors while KEBS quality enforcement shapes cross-border certification requirements.
Nairobi Metropolitan Area
Carbonated soft drink and beer bottlers generate highest volume demand for returnable bottle formats. KEBS KS 1864 specifications govern dimensional tolerance and chemical durability for all furnace output. Industrial zones in Embakasi and Industrial Area host pharmaceutical packaging converters seeking amber glass capacity.
Mombasa County
Coastal location anchors regional distribution networks into Rwanda and Burundi. NEMA emissions thresholds direct furnace upgrade investments toward heat-recovery and filtration systems. Kilifi and Kwale satellite operations support cullet collection infrastructure tied to beverage return schemes.
Central Kenya
Thika and Kiambu manufacturing corridors serve specialty food processors requiring chemical-resistant jar configurations. KEBS alignment with East African Community harmonization protocols streamlines export qualification. Local cosmetics formulators in the region drive specification pressure for thick-walled press-molded packaging.
Rift Valley Region
Nakuru and Eldoret industrial clusters support institutional food service demand for intermediate-capacity jugs. Returnable bottle collection networks extend into highland agricultural zones, stabilizing cullet feedstock for furnace operations. Regional logistics constraints elevate landed costs for imported soda ash.
Western Kenya
Kisumu and Busia border proximity enables informal cross-border glass trade with Uganda and Tanzania. KEBS certification requirements create compliance barriers for non-qualifying imports. Local micro-breweries and artisanal food producers generate intermittent demand for small-batch container runs.
Kenya Container Glass Market Competitive Landscape
Channel-controlling players compete with product-specialist players across furnace capacity tiers. Three domestic operators anchor installed capacity, while regional beverage multinationals exert procurement concentration through long-term framework agreements. Strategic archetypes separate coastal logistics-anchored producers from inland cullet-integrated specialists and pharmaceutical-grade amber glass experts. Competitive moves center on electric furnace retrofit cycles and EAC distribution network expansion.
Among Kenya-based fabricators, Impala Glass Industries exemplifies the coastal logistics-anchored archetype through its Mombasa facility positioning. Empire Glass Industries occupies the pharmaceutical-specialist tier with amber glass production capabilities. East African Glass Industries represents the cullet-integrated model, leveraging returnable bottle scheme linkages for feedstock security.
| Leading Market Players |
|---|
| Impala Glass Industries |
| Empire Glass Industries |
| East African Glass Industries |
| Kenya Glass Works Limited |
| Aluglass Africa |
| Emperor Glass Works |
| Coca-Cola Sabco |
| Bidco Africa |
| East African Breweries Limited |
| Others |
Pricing and Supply Chain Analysis
Coastal furnace underutilization at Mombasa-area plants compresses supplier pricing power while inland Nairobi bottlers exploit returnable bottle economics to negotiate volume discounts. KEBS quality enforcement tightens cost recovery options, forcing producers to absorb compliance investments or surrender market position.
Pricing Analysis
Cost-plus contracts with South African soda ash indexation dominate procurement agreements between Kenyan glassmakers and chemical suppliers. Price differentiation separates pharmaceutical-grade amber glass certified to hydrolytic resistance standards from commodity beverage bottles sourced through spot arrangements. Pricing pressure stems from PET substitution in Nairobi's carbonated soft drink segment, where lightweight plastic logistics undercut glass on landed cost. Beverage multinationals exhibit lowest price sensitivity due to long-term framework commitments, while artisanal food processors and micro-breweries drive hardest bargain hunting.
Supply Chain Analysis
Upstream feedstock dependence concentrates on Egyptian and South African soda ash exporters, with silica sand drawn from local Kenyan deposits near Kisumu and Mombasa. Furnace operations rest on imported LNG through Mombasa port alongside specialized refractory materials from European suppliers. Single-source vulnerability runs through maritime LNG delivery routes exposed to Red Sea disruption and currency fluctuation. Distribution runs through regional stockholding distributors consolidating fragmented EAC demand, with Impala Glass leveraging coastal positioning for Rwanda and Burundi penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Nairobi beverage multinationals has shifted buyer power decisively, compressing supplier margins and elevating volume commitment requirements for market access.
For Market Incumbents: Build captive cullet supply moats through deeper integration with beverage return schemes in Nairobi and Mombasa industrial zones. Secure KEBS KS 1864 pre-certification for emerging East African Community harmonization protocols to eliminate redundant testing burdens. Electric furnace retrofit investments at coastal facilities will defend position against inland cost advantages while tightening NEMA emissions compliance. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical amber glass serving regional drug manufacturers in the East African Community, where specialized hydrolytic resistance certification creates qualification barriers. Target cosmetics jar production for Nairobi's premium skincare brands seeking thick-walled press-molded differentiation. A go-to-market angle anchored on rapid prototype-to-production transitions through online platform sampling can bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cullet-integrated producers with long-term beverage return scheme contracts, offering feedstock security against soda ash volatility. Over the projection horizon, acquisition targets should demonstrate electric furnace upgrade progress and established EAC distribution infrastructure. The signal to watch is KEBS alignment speed with evolving East African Community harmonization protocols as inflection indicator for cross-border market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Retrofit | Impala Glass and competitors cut energy costs while tightening KEBS quality enforcement reshapes compliance thresholds. |
| Cullet Collection Infrastructure | East African Glass Industries secures feedstock through beverage return scheme linkages in Nairobi and Mombasa zones. |
| Pharmaceutical Amber Glass Specialization | Empire Glass Industries captures regional drug manufacturer demand for light-sensitive formulation packaging. |
| EAC Distribution Network Expansion | Mombasa coastal positioning enables Rwanda and Burundi penetration where indigenous container glass capacity is absent. |
| NEMA Heat-Recovery Investment | Accelerated depreciation incentives improve project returns for furnace upgrade cycles at Kenyan facilities. |
Research Methodology
A spread of perspectives from furnace operations managers, beverage procurement directors, pharmaceutical packaging converters, and KEBS regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against KEBS KS 1864 specification documents, NEMA emissions filings, East African Community harmonization protocols, and regional trade customs data. Bottom-up capacity assessments at Mombasa and Nairobi facilities triangulated against top-down demand modeling from beverage and pharmaceutical end-use segments.
Demand-supply balance framing anchored the forecast framework across the analysis window, with segmentation dimensions spanning product type, end-user application, manufacturing stage technology, and distribution channel configuration. CAGRs derived from installed capacity utilization trajectories, electric furnace adoption curves, and EAC cross-border trade flow projections. Industry-specific inputs included soda ash import price volatility indices and KEBS regulatory alignment timelines with East African Community protocols.
Sensitivities concentrate around LNG maritime supply disruption, KEBS testing protocol extensions to decorative coatings, and PET substitution acceleration in non-premium beverage segments. Forecasts reflect documented assumptions on furnace technology migration rates and regional procurement consolidation patterns. Material shifts in East African Community harmonization speed or NEMA emissions threshold tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
South Korea Container Glass Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
UAE Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Global Glass Bottles and Containers Market