
 Vietnam Commercial Vehicles Lubricants Market | 2026-2036
Vietnam Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Commercial Vehicles Lubricants Market Analytics
Logistics providers is repositioning as the dominant end-user vertical, overtaking construction firms in lubricant offtake as e-commerce fulfillment networks expand north from Ho Chi Minh City toward Hanoi. Petrolimex (PLX) leverages its nationwide service station network to control last-mile distribution. TotalEnergies anchors its position through specialized heavy-duty engine oil formulations for tropical operating conditions. Mekong Petrochemical JSC competes on price in the wholesale dealer channel.
Vietnam commercial vehicles lubricants are formulated base oil and additive packages designed to reduce friction, dissipate heat, and neutralize acidic combustion byproducts in diesel engines operating under high load cycles, with viscosity grades typically spanning SAE 15W-40 and 10W-30 for tropical climates. Engine oil commands the largest volume share given mandatory drain intervals tied to OEM warranty requirements, while hydraulic oil generates premium margins from construction equipment operators seeking extended service life in dusty environments. Transmission fluid trails in absolute volume but exhibits the fastest structural growth as automated manual transmissions penetrate medium-duty truck fleets.
Vietnam's Ministry of Transport emission protocols and the country's national technical regulation QCVN align lubricant specifications with Euro 4 and emerging Euro 5 engine standards, compelling reformulation toward lower SAPS additive chemistry. BIS-equivalent conformity assessment procedures administered by the Directorate for Standards, Metrology and Quality create compliance barriers for imported lubricant brands. Stakeholders must monitor how domestic refinery expansion at Nghi Son and Long Son reshapes base oil supply economics and import dependency ratios.
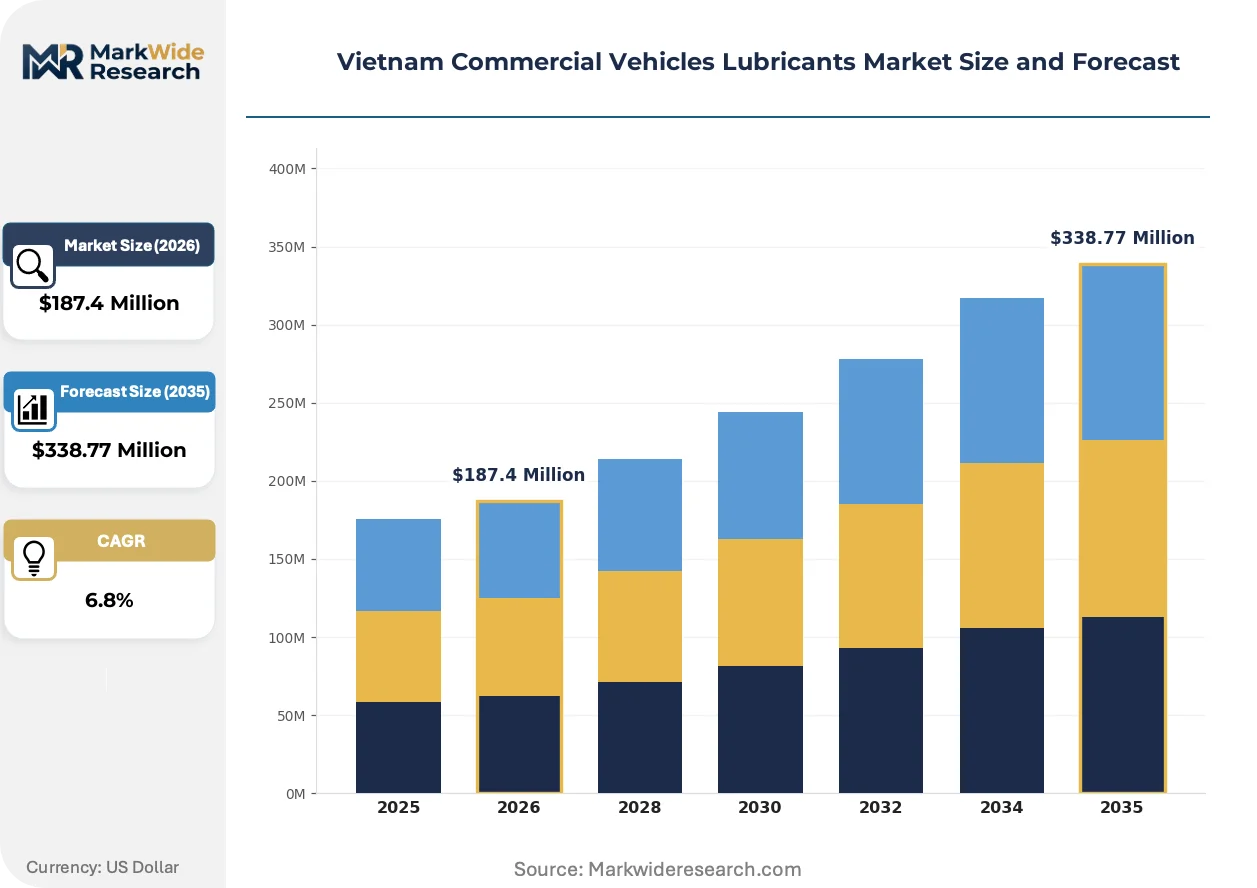
Market Dynamics
Vietnam's tightening emission protocols are forcing lubricant reformulation across the commercial vehicle fleet, as Euro 4 standards harden and Euro 5 approaches, compressing additive chemistry timelines for domestic blenders and importers alike.
Growth Catalysts
- E-commerce fulfillment expansion:Logistics providers operating the Ho Chi Minh City–Hanoi corridor are extending drain intervals through premium synthetic formulations to maximize vehicle uptime.
- QCVN alignment with Euro standards:Vietnam's national technical regulation is mandating lower SAPS chemistry, creating compliant product demand that domestic refiners at Nghi Son are positioned to capture.
- Automated manual transmission penetration:Medium-duty truck fleets are adopting ATF-requiring gearboxes faster than replacement cycles, expanding the transmission fluid addressable base.
Market Restraints
- Group II/III base oil import dependency:Domestic refinery output remains insufficient for high-performance lubricant production, exposing blenders to Singapore and South Korean supply pricing.
- BIS-equivalent conformity assessment:The Directorate for Standards, Metrology and Quality administers testing protocols that extend product registration timelines for imported brands.
- Extended drain interval technology:OEM-specified synthetic oils lasting 50,000+ kilometers are compressing absolute lubricant volume demand per vehicle.
Strategic Opportunities
- Mekong Delta fleet densification:Agricultural logistics operators in Can Tho and surrounding provinces remain underserved by branded service networks, presenting first-mover channel expansion potential.
- Fast-moving consumer goods distribution:Cold-chain operators are specifying food-grade hydraulic fluids for refrigerated truck liftgates, a premium segment with limited domestic competition.
- Used commercial vehicle import channels:Pre-owned trucks from Japan and South Korea entering through Haiphong require compliance-grade lubricant conversion, creating bulk retrofit demand.
Industry Challenges
- Additive package formulation expertise:Local blending operations lack tribochemistry specialists capable of balancing wear protection against after-treatment compatibility.
- Multi-brand fleet service complexity:Independent workshops struggle to stock OEM-specified lubricants across European, Japanese, and Chinese truck engine architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Commercial Vehicles Lubricants Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Grease End User: Transportation Companies, Logistics Providers, Construction Firms, Agriculture Businesses Application: Fleet Maintenance, Heavy Machinery, Construction Equipment, Agricultural Vehicles Distribution Channel: Online Retail, Wholesale Dealers, Direct Sales, Service Stations |
| Companies Covered | BP Plc (Castrol), Mekong Petrochemical JSC, Petrolimex (PLX), Royal Dutch Shell Plc, TotalEnergies, Chevron Corporation, ExxonMobil Corporation, Motul, PVOIL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Commercial Vehicles Lubricants Market Evolving Landscape
Reformulation pressures and fleet digitization are converging to reshape how lubricant value is captured, with chemistry, compliance, and connectivity advancing in parallel across Vietnam's commercial vehicle base.
Additive chemistry is modularizing around discrete function blocks—dispersants, anti-wear agents, friction modifiers—allowing blenders to reconfigure packages rapidly for emerging OEM specifications. Fleet maintenance managers at logistics conglomerates are specifying these modular formulations to hedge against future Euro 5 compliance costs. The technology is modularizing supply chain risk by reducing dependence on single-source fully-formulated additive systems.
Vietnam's Ministry of Transport emission protocols are tightening particulate matter thresholds for diesel engines, compelling lubricant producers to certify products against QCVN 86 and forthcoming Euro 5-aligned amendments. Industrial consequence includes accelerated R&D spending on low-ash formulations compatible with diesel particulate filters. Heavy-duty engine oil categories face the steepest reformulation burden, with domestic blenders seeking technical partnerships to compress development cycles.
Consolidated fleet procurement is displacing decentralized workshop purchasing as large logistics operators centralize lubricant supply contracts. National distributors are losing volume to direct manufacturer-fleet arrangements that bundle fluid supply with used oil analysis services. This concentration is most visible in the Ho Chi Minh City industrial belt, where e-commerce fulfillment networks operate thousand-plus vehicle fleets under unified maintenance protocols.
Vietnam Commercial Vehicles Lubricants Market Segmentation
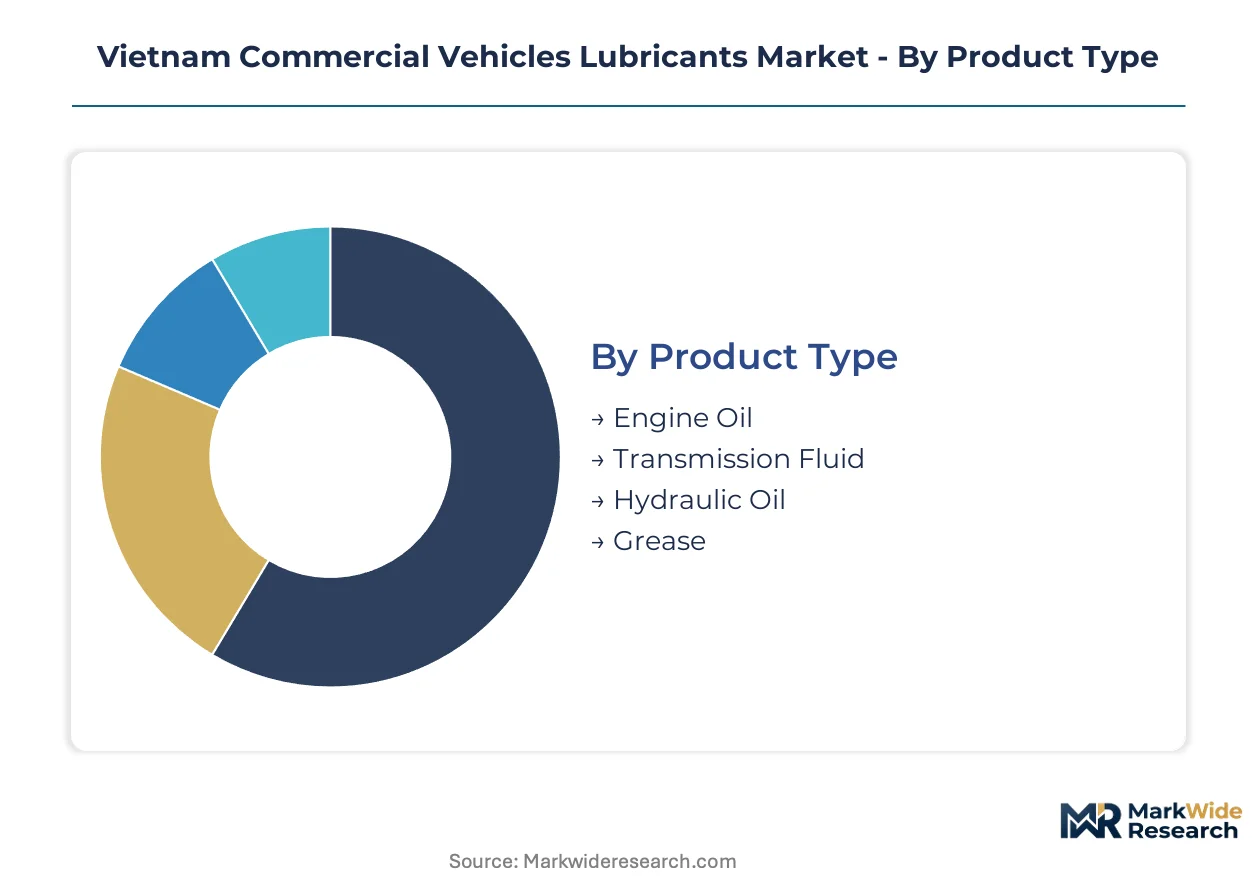
Segmentation in Vietnam's commercial vehicles lubricants market reveals how product specifications, end-user procurement power, and channel control determine margin capture. Fleet operators prioritize drain interval extension and warranty compliance over unit price, reshaping volume allocation across formulation tiers.
Product Type:
Upgrade cycles and replacement intervals vary sharply by product category, with engine architecture changes and emission compliance timelines driving reformulation frequency.
- Engine Oil:Formulated from Group II/III base stocks with SAPS-modified additive packages to meet Euro 4 and emerging Euro 5 standards for diesel particulate filter compatibility. Demand concentrates in logistics fleets operating the Ho Chi Minh City–Hanoi corridor, where OEM warranty terms mandate specific viscosity grades and drain intervals. Fleet managers specify synthetic 15W-40 formulations to maximize vehicle uptime across high-load tropical operating cycles.
- Transmission Fluid:Synthetic-based formulations for automated manual transmissions and conventional gearboxes, requiring precise friction characteristics and thermal stability. Adoption accelerates in medium-duty truck fleets replacing manual transmissions faster than vehicle replacement cycles, expanding the addressable base beyond traditional engine oil volumes.
- Hydraulic Oil:Anti-wear formulations with oxidation inhibitors for construction and agricultural equipment operating in dusty Mekong Delta environments.
- Grease:Lithium and calcium-based lubricants for chassis, bearings, and fifth-wheel applications with extended service life requirements.
Volume placements concentrate in Engine Oil; the faster expansion belongs to Transmission Fluid.
End User:
Procurement sophistication separates large-scale operators with centralized fluid management from decentralized purchasers sensitive to per-liter pricing.
- Transportation Companies:Bus and intercity coach operators with standardized fleet specifications and negotiated supply contracts. These entities specify premium formulations to meet manufacturer warranty requirements and minimize roadside failures on long-haul routes.
- Logistics Providers:E-commerce fulfillment networks with thousand-plus vehicle fleets under unified maintenance protocols. Procurement centralization enables direct manufacturer arrangements bundling fluid supply with used oil analysis, bypassing traditional distribution layers.
- Construction Firms:Project-based operators with seasonal demand patterns and equipment diversification across multiple OEM brands.
- Agriculture Businesses:Mekong Delta operators in Can Tho and surrounding provinces with limited access to branded service networks and price-sensitive purchasing behavior.
Logistics Providers command the largest volume share; Agriculture Businesses present the steepest expansion trajectory for channel development investment.
Application:
Operating environment severity and equipment utilization rates determine formulation premiumization potential across use cases.
- Fleet Maintenance:Scheduled lubricant replacement programs for commercial vehicle operators with documented service histories. These programs emphasize predictive maintenance integration and oil analysis services to optimize drain intervals.
- Heavy Machinery:High-load equipment in mining and material handling with extreme pressure and contamination exposure. Formulations require enhanced anti-wear additives and seal compatibility for extended component life.
- Construction Equipment:Intermittent-use machinery with cold-start wear concerns and dust ingress challenges.
- Agricultural Vehicles:Seasonal-intensity tractors and harvesters with moisture contamination and extended storage periods.
Volume concentrates in Fleet Maintenance; Heavy Machinery generates the highest margin per liter due to specialized formulation requirements.
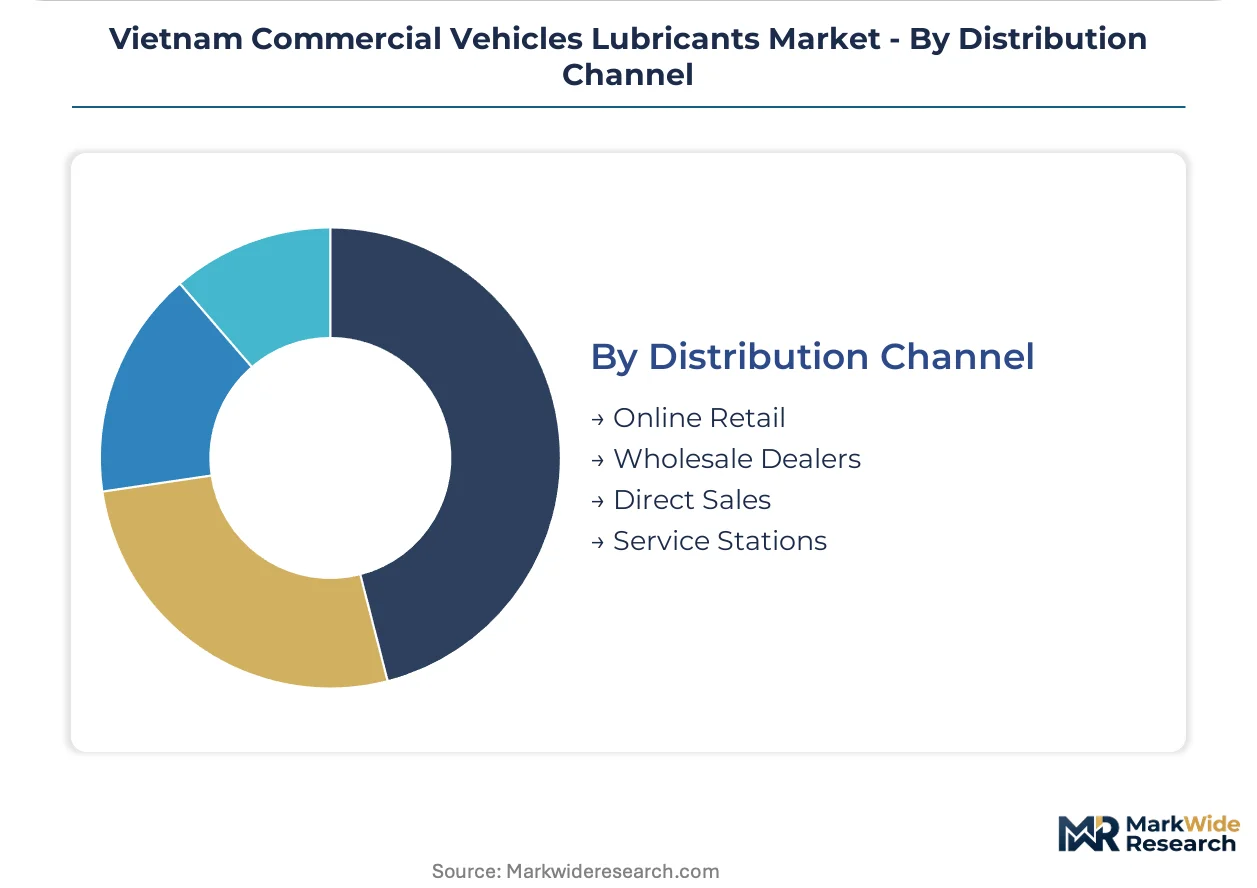
Distribution Channel:
Channel control determines price realization and customer relationship depth, with infrastructure investment requirements filtering competitive participation.
- Service Stations:Petrolimex leverages its nationwide retail network to control last-mile distribution, capturing fleet operators requiring immediate availability during route operations. The channel dominates emergency top-up demand and small fleet purchasing.
- Wholesale Dealers:Independent distributors serving regional workshops and smaller fleet operators with multi-brand inventory. Mekong Petrochemical JSC competes aggressively on price through this channel, sacrificing margin for volume placement.
- Direct Sales:Manufacturer-to-fleet arrangements eliminating distributor markup for large logistics conglomerates.
- Online Retail:Emerging platform for standardized products with transparent pricing and delivery logistics.
Service Stations anchor current volume; Direct Sales is gaining share fastest as fleet consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along Vietnam's eastern seaboard concentrate lubricant demand from manufacturing-linked logistics fleets. Tax incentives in these zones attract assembly plants and distribution centers that operate heavy-duty commercial vehicles. The resulting fleet density creates localized lubricant consumption clusters that outpace national averages.
Ho Chi Minh City and Surrounding Industrial Provinces
E-commerce fulfillment networks and container trucking operations dominate lubricant offtake in this southern hub. Vietnam's Ministry of Transport enforces Euro 4 emission standards through QCVN technical regulations that mandate compliant lubricant formulations. The Cat Lai port cluster and adjacent industrial zones in Binh Duong and Dong Nai provinces generate concentrated demand for heavy-duty engine oils serving cross-border freight routes into Cambodia.
Hanoi and Northern Manufacturing Belt
Electronics and automotive component manufacturers operate just-in-time delivery fleets requiring premium synthetic lubricants. The Directorate for Standards, Metrology and Quality administers BIS-equivalent conformity assessments that filter imported lubricant brands. Industrial parks in Bac Ninh, Vinh Phuc, and Hung Yen provinces house contract logistics providers centralizing procurement under direct manufacturer arrangements.
Da Nang and Central Coast Logistics Corridor
Intermodal freight terminals connecting rail and maritime transport drive medium-duty truck utilization. Vietnam's emission protocol enforcement tightens gradually in central provinces as infrastructure catches up to southern and northern standards. The Chu Lai economic zone and surrounding Quang Nam province attract cold-chain operators specifying food-grade hydraulic fluids for refrigerated transport.
Can Tho and Mekong Delta Agricultural Zone
Agricultural logistics operators move harvest volumes through seasonal intensity patterns that stress equipment lubrication systems. Provincial environmental regulations lag national standards, limiting enforcement of low-SAPS formulations in rural service networks. The Can Tho metropolitan area and surrounding An Giang, Dong Thap, and Kien Giang provinces remain underserved by branded lubricant distribution infrastructure.
Haiphong and Northern Deepwater Port Zone
Used commercial vehicle imports from Japan and South Korea enter through this northeastern gateway requiring compliance-grade lubricant conversion. Customs and quality inspection protocols administered by the Directorate for Standards, Metrology and Quality create registration friction for bulk lubricant shipments. The Dinh Vu industrial zone and Lach Huyen deepwater port support mining and construction equipment fleets with specialized hydraulic oil requirements.
Vietnam Commercial Vehicles Lubricants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with international oil companies commanding premium formulations while domestic blenders compete on price in volume channels. The market structure tiers into three distinct competitive archetypes: multinational lubricant majors with proprietary additive technology, national oil companies leveraging retail fuel networks, and independent blenders serving price-sensitive wholesale accounts. Capacity expansion and strategic partnerships dominate competitive moves as players position for Euro 5 compliance requirements.
Among international oil companies, BP Plc (Castrol), TotalEnergies, and Royal Dutch Shell Plc occupy positions exemplifying the premium-formulation archetype. These entities represent the technology-intensive tier where proprietary additive packages and OEM certification relationships create defensive positioning. Domestic competition concentrates in Petrolimex (PLX) and Mekong Petrochemical JSC, which anchor the national oil company and independent blender archetypes respectively. PLX exemplifies network-driven distribution control through service station infrastructure, while Mekong Petrochemical JSC represents price-competitive positioning in wholesale dealer channels.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| Mekong Petrochemical JSC |
| Petrolimex (PLX) |
| Royal Dutch Shell Plc |
| TotalEnergies |
| Chevron Corporation |
| ExxonMobil Corporation |
| Motul |
| PVOIL |
| Others |
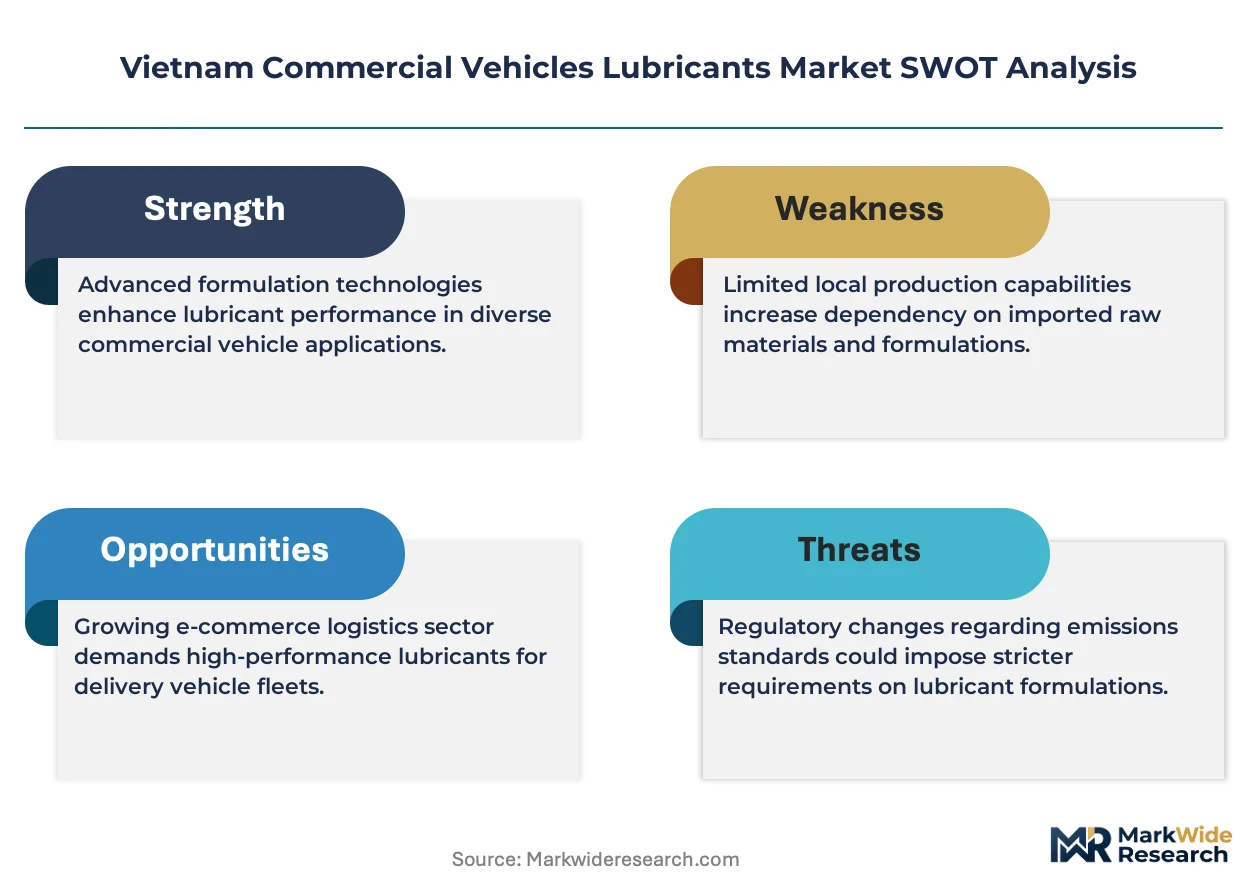
Value Network & Pricing Analysis
Sovereign-backed refiners at Nghi Son and Long Son anchor Vietnam's base oil supply, translating captive feedstock access into pricing discipline that shields domestic blenders from import volatility while compressing margins for independent distributors lacking upstream integration.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with logistics fleets paying markups for just-in-time delivery to maintain vehicle uptime across the Ho Chi Minh City–Hanoi corridor. Pricing stratifies across premium synthetic, standard mineral, and economy recycled tiers, with differentiation driven by Euro 4 certification grade and volume scale. Cost compression in the wholesale dealer channel is intensifying because Mekong Petrochemical JSC's aggressive volume placement. Small agricultural operators in the Mekong Delta exhibit highest price sensitivity; large e-commerce fulfillment networks prioritize warranty compliance over per-liter cost.
Supply Chain Analysis
QCVN certification administered by the Directorate for Standards, Metrology and Quality gates product registration, extending timelines for imported additive packages and base oil shipments. Geographic supply concentrates in Singapore, South Korea, and Thailand for Group II/III base stocks and specialty additive chemicals. Raw material dependencies include polyalphaolefin synthetic base stocks, zinc dialkyldithiophosphate anti-wear agents, and calcium sulfonate detergent packages. Single-source vulnerability pervades the high-performance additive segment, where three global suppliers control proprietary formulation technology. Distribution runs through Petrolimex's service station network for last-mile reach, direct manufacturer-to-fleet contracts for large logistics operators, and independent wholesale dealers for regional workshop coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base oil capacity constraints at domestic refineries prop pricing power for integrated blenders, creating supply-constrained conditions that favor players with captive feedstock or long-term offtake agreements.
For Market Incumbents: Deploy additive package modularity to compress reformulation cycles as Euro 5 standards approach. Secure backward integration into Group II/III base oil supply through partnerships with Nghi Son refinery expansion phases. Defensive positioning requires preemptive QCVN certification investment before regulatory timelines harden, while channel control through direct fleet contracts neutralizes price competition from Mekong Petrochemical JSC's wholesale aggression.
For New Entrants and Emerging Players: Capture the cold-chain hydraulic fluid segment in Da Nang and Chu Lai, where food-grade specifications create technical barriers that limit domestic competition. Target agricultural logistics operators in Can Tho and surrounding Mekong Delta provinces currently underserved by branded service networks. A technical partnership route with European additive suppliers enables rapid formulation credibility without captive R&D infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor independent blenders with established wholesale dealer channels in northern Vietnam, where BIS-equivalent conformity assessment friction has compressed valuations for import-dependent operations. Long-term viability hinges on Euro 5 compliance capability and fleet consolidation exposure. Monitor Nghi Son refinery output ramp rates as the inflection signal for domestic base oil supply economics and import dependency ratio shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive feedstock from Nghi Son refinery expansion reduces exposure to Singapore and South Korean pricing volatility. |
| Low-SAPS Additive Package Development | Euro 5 alignment through QCVN amendments mandates diesel particulate filter compatibility for heavy-duty engine oils. |
| Direct Fleet Contract Expansion | Bypassing wholesale dealer layers captures volume from centralized procurement at e-commerce logistics conglomerates. |
| Mekong Delta Channel Buildout | First-mover infrastructure in Can Tho and An Giang provinces accesses agricultural logistics operators with limited branded alternatives. |
| Used Oil Analysis Service Bundling | Predictive maintenance integration deepens customer relationships and extends drain interval specification authority. |
Research Methodology
Multi-period observation of fleet utilization rates, refinery output disclosures, and QCVN regulatory amendments anchored the trend analysis, supplemented by interviews with lubricant blending plant managers, procurement leads at logistics conglomerates, distribution channel partners, and technical R&D directors at additive suppliers. Secondary validation drew from Vietnam customs trade data, Directorate for Standards, Metrology and Quality certification registries, Petrolimex annual reports, and Nghi Son refinery production disclosures. Bottom-up volume modeling across product categories triangulated against top-down macroeconomic freight indicators.
Segment-weighting applied differential growth assumptions to engine oil, transmission fluid, hydraulic oil, and grease categories based on equipment replacement cycles and emission compliance timelines. The analytical framework modeled product type, end-user procurement sophistication, application severity, and distribution channel control dimensions across the projection horizon. CAGRs derived from fleet expansion trajectories in the Mekong Delta corridor and synthetic formulation penetration rates in logistics fleets. Industry-specific inputs included OEM warranty drain interval specifications and domestic refinery capacity utilization forecasts.
The model holds under steady QCVN enforcement and Nghi Son capacity ramp assumptions; deviation in Euro 5 adoption timelines or base oil import tariff structures would shift volume and value trajectories. A model refresh is warranted upon material change in domestic refinery output economics or fleet consolidation pace among e-commerce logistics operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Tire Mold Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Gear Box and Gear Motors Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Electric Parking Brake Actuator Components Market