
 Asia Pacific Automotive Parts Die Casting Market | 2026-2036
Asia Pacific Automotive Parts Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Parts Die Casting Market Outlook
Asset-light leasing arrangements for die-casting equipment is narrowing the capital barrier for mid-sized suppliers entering the Asia Pacific supply chain. Endurance Technologies Ltd. leverages its integrated tooling and machining footprint across western India to sustain cost advantages on transmission housings. Ahresty Corporation anchors its regional position through captive aluminum smelting and precision high-pressure lines serving Japanese OEMs in Thailand.
Automotive parts die casting involves injecting molten non-ferrous alloys—typically aluminum with 9-12% silicon content—into hardened steel molds at pressures exceeding 1,000 bar to produce complex, net-shape components with wall thicknesses below 3 millimeters. This process yields parts that reduce vehicle mass while maintaining structural integrity for powertrain and chassis applications. Aluminum alloys dominate the material mix due to their strength-to-weight ratio and recyclability, though magnesium alloys are gaining traction for steering wheels and connector housings where further mass reduction carries premium value. High pressure die casting leads the technology landscape, while gravity die casting retains stable share in aftermarket wheel production where lower tooling amortization suits smaller batch sizes.
China's MIIT enforces GB standards for automotive aluminum castings that restrict porosity levels and mandate X-ray inspection protocols, effectively filtering out uncertified foundries from OEM supply pools. India's BIS certification scheme for automotive components and Japan's JIS standards for die-casting alloys create overlapping compliance burdens for regional suppliers serving multiple national markets. Stakeholders must monitor how China's SAMR implements dual carbon goals across foundry energy quotas, as this will determine which alloy systems and casting technologies receive preferential capacity licenses in the decade ahead.
Market Dynamics
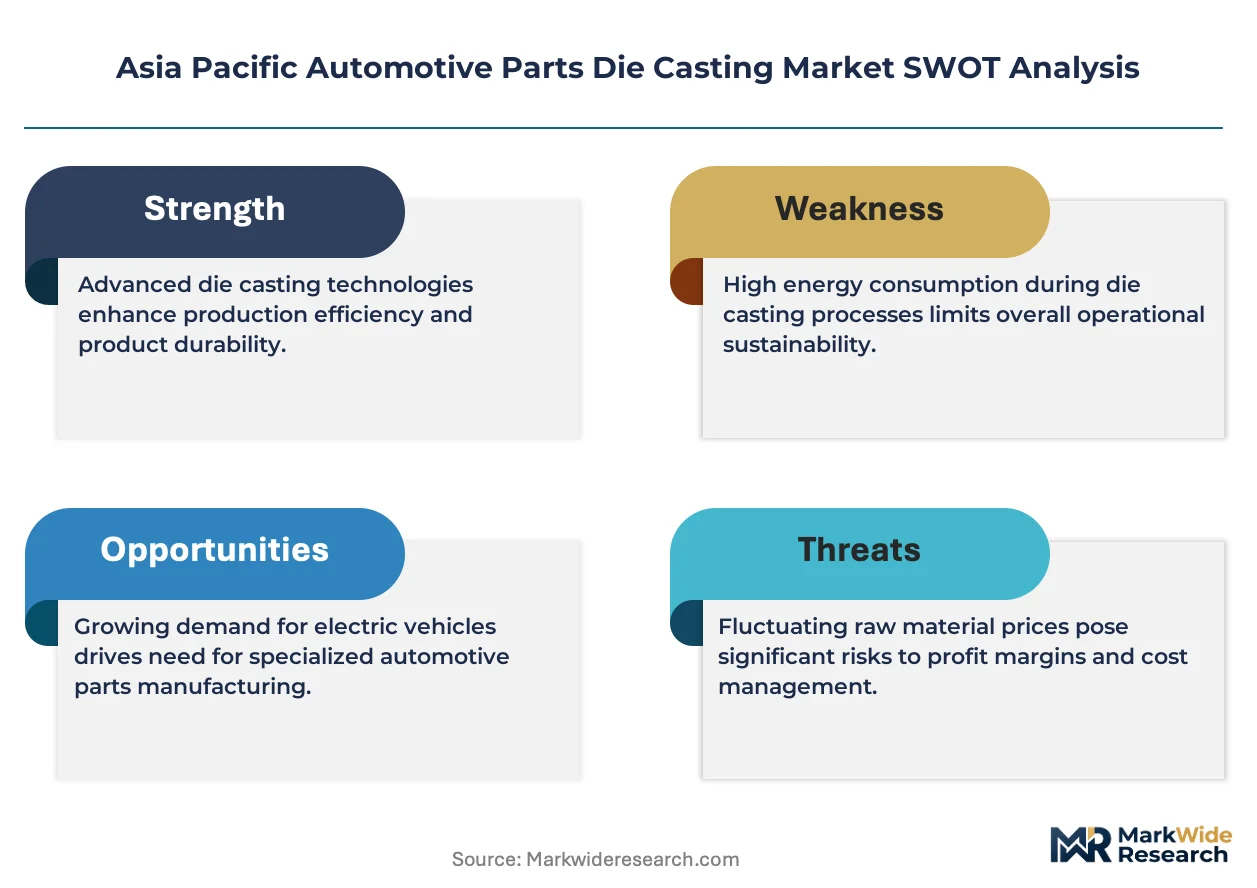
Electric vehicle powertrain architectures are compressing component counts while demanding higher structural complexity per casting, forcing foundries to requalify tooling for integrated motor-transmission housings that replace multi-part assemblies.
Growth Catalysts
- MIIT GB Standards:China's porosity and X-ray inspection mandates for aluminum automotive castings filter uncertified suppliers, concentrating orders among qualified foundries with certified metrology labs.
- Dual Carbon Goals:SAMR energy quotas for foundries favor low-carbon aluminum smelting and high-pressure die casting with shorter cycle times, accelerating technology replacement across Yangtze River Delta capacity.
- Lightweighting Mandates:Japanese OEMs in Thailand specify magnesium steering wheels and connector housings, pulling specialty alloy demand from traditional aluminum-dominated procurement.
Market Restraints
- Primary Aluminum Volatility:LME aluminum price swings compress foundry margins on fixed-price OEM contracts, particularly for gravity die casting operations with longer production runs.
- Smelter Concentration:Captive aluminum supply from integrated producers like Chalco and Hongqiao limits independent foundries' feedstock negotiating power in China's coastal clusters.
- Die Life Limitations:H13 steel molds for high-pressure die casting degrade after 80,000-120,000 shots on silicon-rich alloys, forcing capital-intensive refurbishment cycles.
Strategic Opportunities
- Vietnam Industrial Zones:Underdeveloped automotive die-casting capacity in northern Vietnam offers first-mover positioning as Japanese and Korean OEMs diversify supply chains from China.
- BIS Certification Arbitrage:Indian suppliers with BIS automotive component certification can capture orders from multinational OEMs seeking dual-qualified sources for ASEAN markets.
- Semi-Solid Rheocasting:Convergence of thixotropic metal forming with conventional high-pressure lines enables thinner-wall transmission housings without porosity defects, opening EV thermal management applications.
Industry Challenges
- Multi-Standard Qualification:Simultaneous BIS, JIS, and GB compliance requires redundant testing protocols, extending supplier onboarding timelines by 8-14 months for cross-border contracts.
- Process Control Talent:Shortage of technicians proficient in real-time shot monitoring and thermal management software limits yield improvements at mid-sized foundries upgrading from manual operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Parts Die Casting Market |
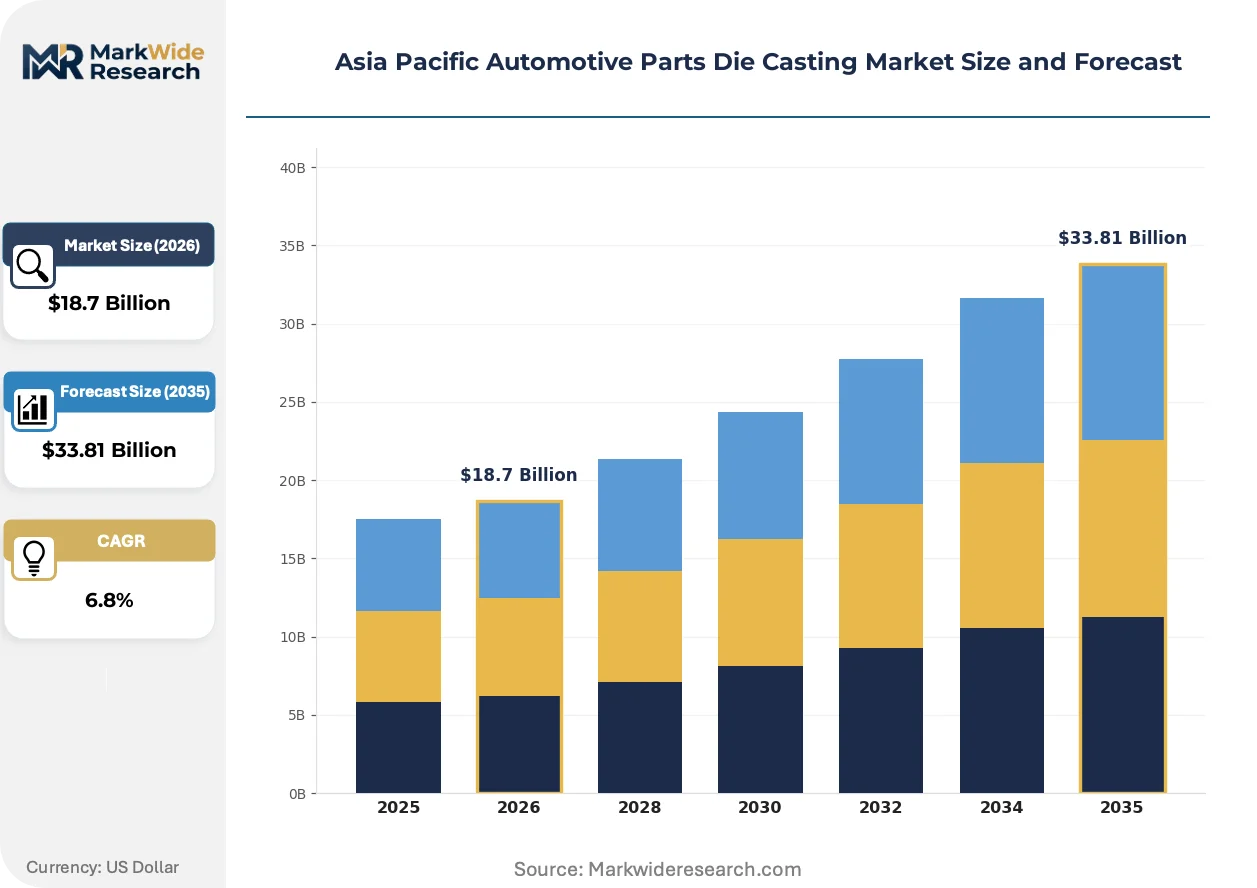
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Wheels, Connectors Technology: High Pressure Die Casting, Low Pressure Die Casting, Gravity Die Casting, Cold Chamber End User: Original Equipment Manufacturers, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Aluminum Alloys, Zinc Alloys, Magnesium Alloys, Copper Alloys |
| Companies Covered | Sunbeam Auto Pvt. Ltd., Pace Industries, Endurance Technologies Ltd., Castwel Autoparts Pvt. Ltd., Amtek Group, Dynacast Inc., SYX Die Casting, Ahresty Corporation, Sandar Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Parts Die Casting Market Strategic Shifts
Die-casting technology is bifurcating between ultra-high-pressure systems for structural EV components and flexible cell manufacturing for mixed-model production, with regulatory carbon accounting now influencing alloy selection and process design simultaneously.
Large structural die casting is migrating from traditional 4,000-ton machines to 6,000-9,000-ton integrated cells capable of producing single-piece EV underbodies. BYD and Tesla's Asian suppliers are commissioning these systems in China's Guangdong and Zhejiang provinces. This migration from multi-part welded assemblies to monocoque castings compresses tier-2 supplier counts while concentrating tooling investment among capital-heavy integrators.
China's dual carbon implementation through SAMR foundry energy quotas is tightening natural gas and electricity allocation per ton of output. Casting operations with gas-fired holding furnaces face retrofit pressure toward electric induction or hydrogen-ready systems. High-pressure die casting with shorter cycle times gains preferential licensing over gravity processes in Jiangsu and Shandong provincial capacity approvals.
Japanese OEM procurement patterns in Thailand and Indonesia are consolidating supplier panels from twenty-plus foundries per platform to six-to-eight certified partners with captive machining. Tier-1 integrators like Ahresty and Ryobi are absorbing finishing operations previously outsourced to independent machine shops, compressing the supplier base while extending their own alloy-to-assembly control.
Asia Pacific Automotive Parts Die Casting Market Segmentation
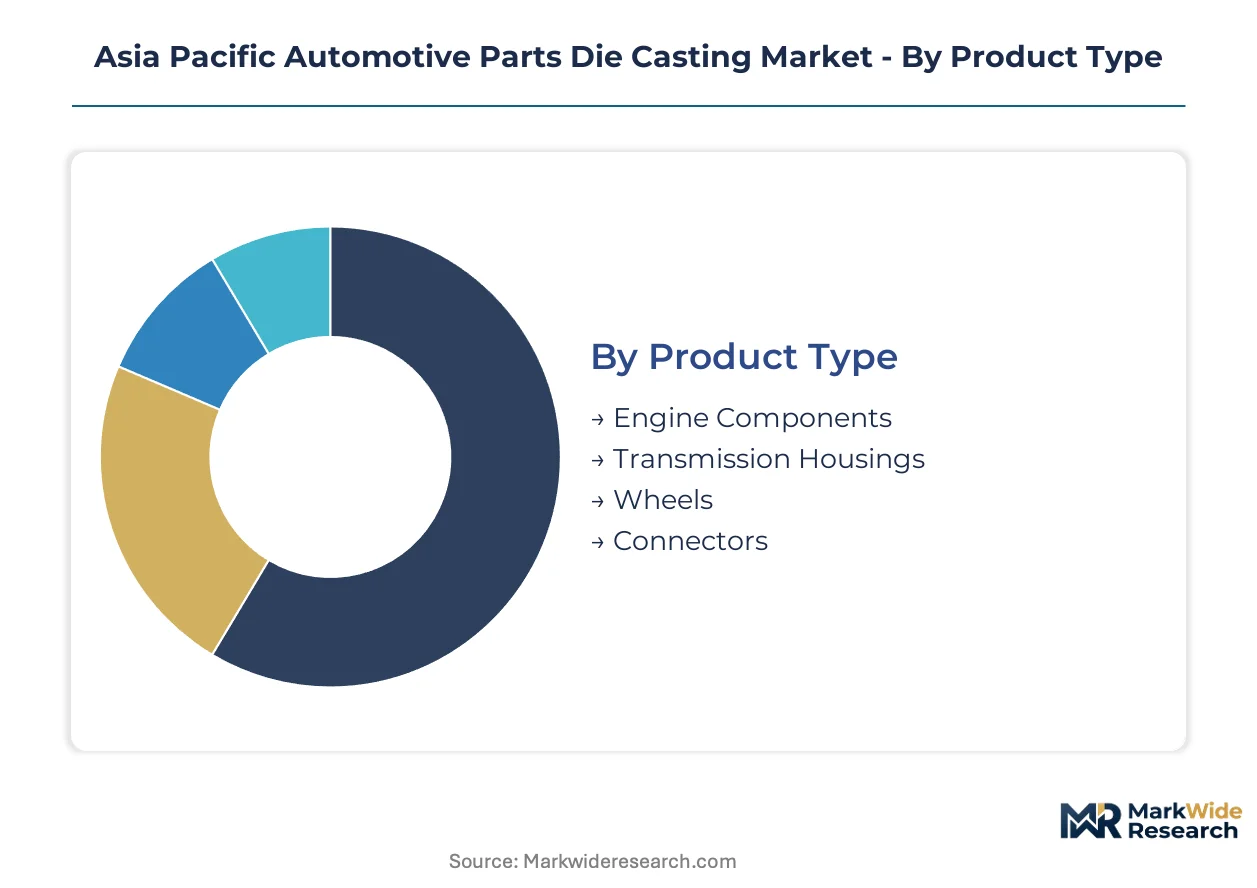
Segmentation in automotive die casting reveals how technology-material pairings align with powertrain electrification timelines and regulatory carbon accounting across Asia Pacific supply chains. Each dimension carries distinct qualification burdens and capital intensity profiles that reshape supplier competitive positioning.
Product Type:
Engine components and transmission housings span radically different electrification exposure profiles across internal combustion and battery-electric vehicle architectures.
- Engine Components:Cylinder heads, blocks, and oil pans utilize aluminum-silicon alloys with 9-12% silicon content for thermal fatigue resistance. Demand concentrates in India's western automotive corridor where commercial vehicle production sustains order volumes despite passenger EV transitions.
- Transmission Housings:Integrated motor-transmission units for electric vehicles require complex internal geometries with wall thicknesses below 2.5 millimeters. China's Yangtze River Delta foundries are requalifying 4,000-ton presses for these single-piece castings as EV powertrain architectures compress component counts.
- Wheels:Gravity die casting dominates aftermarket production where lower tooling amortization suits smaller batch sizes across Southeast Asian replacement markets.
- Connectors:Miniaturized electrical housings for high-voltage systems favor magnesium alloys in Japanese OEM specifications for Thailand-assembled vehicles.
Established volume favors engine components; emerging adoption favors transmission housings.
Technology:
Process selection hinges on cycle time economics, porosity tolerance, and SAMR energy quota compliance across Chinese provincial licensing regimes.
- High Pressure Die Casting:Molten metal injection at 1,000-1,500 bar produces net-shape parts with 3-millimeter wall thicknesses. Jiangsu and Shandong provinces grant preferential capacity licenses to these shorter-cycle operations under dual carbon implementation.
- Low Pressure Die Casting:Controlled metal rise from below yields superior internal integrity for structural wheels. Demand concentrates in aftermarket supply chains serving Indonesia's commercial vehicle fleet where durability specifications exceed cosmetic finish priorities.
- Gravity Die Casting:Atmospheric pouring suits lower-volume production with reduced capital barriers for Vietnam's emerging supplier base.
- Cold Chamber:Separate metal melting enables processing of aluminum alloys with higher copper content for thermal conductivity in power electronics housings.
High pressure die casting commands the dominant equipment investment share; cold chamber methods are climbing fastest in EV thermal management applications.
End User:
Customer type determines qualification timeline, contract structure, and captive versus merchant foundry sourcing patterns.
- Original Equipment Manufacturers:Direct procurement from BYD, Toyota, and Hyundai Motor specifies GB, JIS, and internal porosity standards simultaneously. Multi-standard qualification extends supplier onboarding by 8-14 months for cross-border contracts.
- Aftermarket Providers:Independent distributors source gravity-cast wheels and engine covers through Thailand's Laem Chabang port logistics hub serving ASEAN replacement demand.
- Tier-1 Suppliers:Integrators like Denso and Aisin consolidate finishing operations previously outsourced, extending alloy-to-assembly control.
- Vehicle Assemblers:Contract manufacturers in Vietnam's northern industrial zones seek first-mover die-casting partnerships as Japanese and Korean OEMs diversify from China.
Tier-1 suppliers absorb the steepest margin compression; vehicle assemblers in Vietnam offer the most rapid contract expansion trajectory.
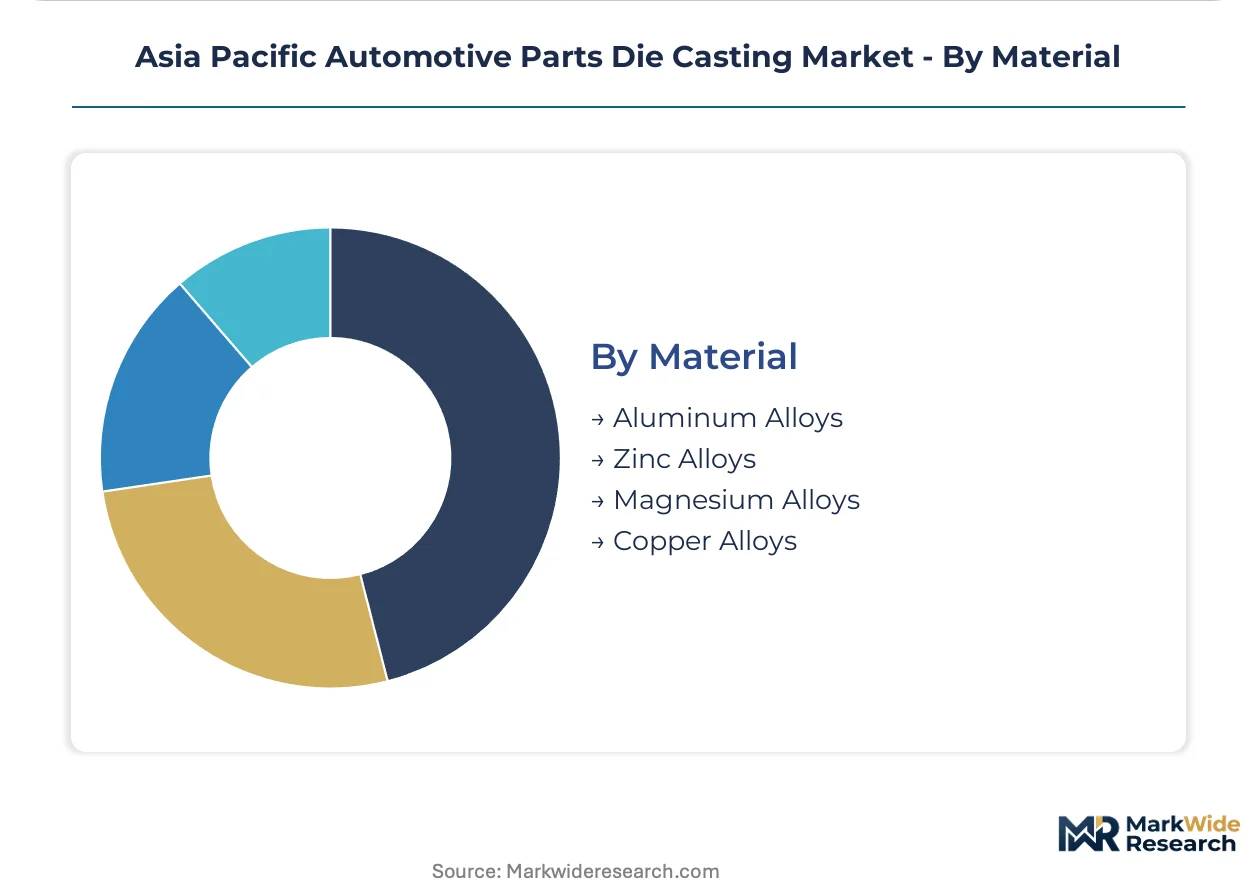
Material:
Alloy selection increasingly reflects carbon accounting boundaries and scrap recyclability under tightening foundry energy quotas.
- Aluminum Alloys:ADC12 and A380 grades with 9-12% silicon deliver strength-to-weight ratios above 150 MPa yield strength. China's coastal clusters depend on captive smelter supply from Chalco and Hongqiao, limiting independent foundry negotiating leverage.
- Zinc Alloys:Zamak compositions enable thin-wall decorative trim with superior surface finish for premium Japanese domestic market vehicles.
- Magnesium Alloys:AZ91D in steering wheels and connector housings achieves 30% mass reduction versus aluminum equivalents. Japanese OEM procurement in Thailand pulls specialty demand from traditional aluminum-dominated supply pools.
- Copper Alloys:High thermal conductivity grades serve power electronics cooling plates in high-performance EV inverters.
Aluminum alloys retain the dominant procurement volume; magnesium alloys are gaining share fastest in lightweighting-sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and India's BIS certification mandates are reshaping supplier qualification timelines across the region. Foundry capacity concentrates in coastal industrial clusters where energy quotas and material standards filter market participation.
China
EV manufacturers in the Yangtze River Delta are accelerating orders for lightweight transmission housings. MIIT enforces GB standards restricting porosity levels and mandating X-ray inspection protocols. Foundry capacity for aluminum alloy engine components continues expanding across Jiangsu and Zhejiang provinces under SAMR energy quota systems.
India
Commercial vehicle production sustains order volumes for cylinder heads and engine blocks in the western automotive corridor. BIS certification for automotive components creates compliance barriers for uncertified foundries. Endurance Technologies leverages integrated tooling and machining footprints across Maharashtra and Gujarat to sustain cost advantages.
Japan
Domestic OEMs specify magnesium steering wheels and connector housings for mass reduction premiums. METI oversees JIS standards for die-casting alloys that overlap with regional compliance regimes. Ahresty Corporation anchors regional supply through captive aluminum smelting serving Japanese production networks.
Thailand
Japanese OEM procurement patterns are consolidating supplier panels from twenty-plus foundries to six-to-eight certified partners per platform. Board of Investment incentives attract die-casting investments for EV supply chain diversification. Laem Chabang port logistics hubs serve ASEAN aftermarket demand for gravity-cast wheels.
Vietnam
Underdeveloped automotive die-casting capacity in northern industrial zones offers first-mover positioning. Japanese and Korean OEMs are diversifying supply chains from China into Bac Ninh and Hai Phong provinces. Contract manufacturers seek die-casting partnerships as regional assembly expands.
Asia Pacific Automotive Parts Die Casting Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply hierarchies. Tier-1 integrators absorb finishing operations previously outsourced, extending alloy-to-assembly control while compressing independent supplier counts. Three archetypes dominate: capital-heavy integrators with captive smelting, mid-sized specialists with certified metrology labs, and asset-light operators leasing die-casting equipment. Competitive moves concentrate on vertical integration into machining and strategic positioning for multi-standard qualification.
Within the integrated tooling tier, Endurance Technologies Ltd. exemplifies cost-advantaged positioning across western India. Among Japan-based fabricators, Ahresty Corporation occupies a position anchored by captive aluminum supply. Chinese specialists including SYX Die Casting represent the mid-cap certified tier navigating GB standard compliance.
| Leading Market Players |
|---|
| Sunbeam Auto Pvt. Ltd. |
| Pace Industries |
| Endurance Technologies Ltd. |
| Castwel Autoparts Pvt. Ltd. |
| Amtek Group |
| Dynacast Inc. |
| SYX Die Casting |
| Ahresty Corporation |
| Sandar Technologies |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Jiangsu and Zhejiang foundry clusters is compressing contract pricing for aluminum transmission housings while simultaneously forcing independent suppliers toward asset-light leasing models to preserve liquidity. This utilization-driven margin squeeze redistributes bargaining power toward OEMs with multi-year offtake agreements and captive smelter access.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified suppliers across the Asia Pacific supply base. Three-tier pricing structure separates GB-certified foundries with X-ray inspection capability from BIS-registered Indian operators and uncertified gravity-casting shops serving aftermarket demand. Cost compression in the mid-tier is intensifying because Japanese OEMs in Thailand are consolidating supplier panels while demanding simultaneous JIS and internal porosity compliance. Aftermarket distributors sourcing through Laem Chabang port exhibit the highest price sensitivity, whereas EV platform engineers at BYD and Hyundai Motor prioritize defect rates over unit cost in integrated motor-transmission housing procurement.
Supply Chain Analysis
Tariff exposure between China and Vietnam is accelerating supplier diversification into Bac Ninh and Hai Phong industrial zones as Japanese and Korean OEMs reroute procurement. Primary aluminum supply concentrates in China's coastal clusters where Chalco and Hongqiao operate captive smelters, while magnesium feedstock for steering wheel applications draws from Shanxi province and imported sources. Single-source vulnerability in H13 steel mold supply from specialized toolmakers creates refurbishment bottlenecks for high-pressure die casting operations. Distribution runs through tier-1 integrators like Denso and Aisin that have absorbed finishing operations previously outsourced to independent machine shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV platform standardization across motor-transmission architectures is collapsing component counts while elevating structural complexity per casting, creating winner-take-most dynamics among foundries with 6,000-ton press capability and certified metrology infrastructure.
For Market Incumbents: Harden qualification moats by securing simultaneous BIS, JIS, and GB certification ahead of supplier panel consolidation at Japanese OEMs in Thailand. Captive aluminum smelting or long-term offtake agreements with Chalco and Hongqiao anchor feedstock cost control against LME volatility that threatens gravity-casting margins. For New Entrants and Emerging Players: Northern Vietnam's underdeveloped automotive die-casting capacity offers first-mover positioning as Korean and Japanese assemblers diversify from China's Yangtze River Delta. Target contract manufacturing relationships with vehicle assemblers in Bac Ninh rather than direct OEM qualification, leveraging shorter onboarding timelines and lower capital barriers through equipment leasing arrangements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ultra-high-pressure die casting as 6,000-9,000-ton integrated cells replace traditional 4,000-ton machines for single-piece EV underbodies. Mid-sized specialists with certified metrology labs and existing multi-standard compliance represent the most defensible acquisition profile. SAMR energy quota enforcement velocity serves as the critical signal to watch for capacity license allocation and technology replacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Simultaneous BIS, JIS, and GB qualification extends supplier onboarding timelines, filtering competition. |
| Captive Aluminum Smelting or Long-Term Offtake | Feedstock security against LME volatility preserves margins on fixed-price OEM transmission housing contracts. |
| Ultra-High-Pressure Capacity Expansion | 6,000-9,000-ton integrated cells enable single-piece EV underbody production, compressing tier-2 supplier counts. |
| Vietnam Manufacturing Footprint Establishment | Bac Ninh and Hai Phong industrial zones attract Japanese and Korean OEM diversification from China. |
| Semi-Solid Rheocasting Technology Adoption | Thixotropic metal forming enables thinner-wall transmission housings without porosity defects for EV thermal management. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foundry operations directors, OEM platform engineers at BYD and Hyundai Motor, tier-1 procurement leads at Denso and Aisin, and aftermarket distributors through Thailand's Laem Chabang logistics hub. Secondary validation drew from MIIT GB standard filings, SAMR energy quota implementation notices, BIS certification registries, Japanese OEM supplier panel disclosures, and LME aluminum price series. Bottom-up capacity utilization data from Jiangsu and Zhejiang foundry clusters was triangulated against top-down EV production forecasts across the analysis window.
Calibration against historical capacity expansion patterns and alloy price elasticity informed the projection framework. Segmentation dimensions modeled include product type, technology, end user, and material grade, with vehicle propulsion architecture and regional regulatory cluster as cross-cutting variables. CAGRs were derived from slope-consistent trajectory fitting across the modeling period. Key inputs encompassed SAMR dual carbon implementation velocity, Japanese OEM supplier consolidation timelines, and Vietnam industrial zone incentive structures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese integrators or accelerated Korean OEM supply chain diversification would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
VVT and Start-Stop Systems Market