
 Video Surveillance As a Service Market | 2026-2036
Video Surveillance As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Video Surveillance As a Service Market Intelligence
Multi-source cloud provisioning is rebalancing how enterprises acquire video surveillance capabilities, shifting capital expenditure toward operational models. Axis Communications AB leverages its open-platform architecture to sustain interoperability across third-party analytics ecosystems. Bosch Sicherheitssysteme GmbH anchors European critical infrastructure projects with hardened edge-to-cloud pipelines. Eagle Eye Networks differentiates through pure-play cloud-native infrastructure that eliminates on-premise server dependencies.
Video Surveillance As a Service delivers camera-to-cloud video management through encrypted streaming protocols, typically employing H.265 compression and redundant storage architectures across geographically distributed data centers, with primary commercial purpose centered on real-time threat detection and forensic evidence preservation. Cloud storage and real-time analytics command the largest current revenue pools as organizations prioritize searchable video archives and automated alert generation over passive recording. Hybrid solutions are gaining structural momentum among mid-market buyers seeking to bridge legacy on-premise investments with elastic cloud scalability.
FCC guidelines govern broadband reliability standards underlying remote monitoring service levels, while GDPR and Illinois Biometric Information Privacy Act impose strict constraints on facial recognition data retention and consent protocols. These frameworks elevate compliance costs for cross-border operators but simultaneously create market access barriers that favor vendors with certified privacy-by-design architectures. Stakeholders must monitor evolving municipal procurement standards for public space surveillance as cities weigh security efficacy against civil liberties litigation exposure.
Market Dynamics
Cloud-native video architectures are compressing deployment timelines from months to days while biometric privacy mandates in Illinois and Texas force architectural redesigns around consent workflows and data retention limits.
Growth Catalysts
- GDPR Article 17 erasure mandates:European enterprises accelerate cloud migration to automate right-to-be-forgotten compliance across distributed camera networks.
- Smart city infrastructure buildouts:Municipalities in Germany and Japan prioritize camera-to-cloud platforms for traffic management and public safety modernization.
- H.265 compression adoption:Bandwidth efficiency gains enable 4K streaming over standard broadband, expanding addressable mid-market accounts.
Market Restraints
- Edge hardware supply concentration:Specialized AI chipsets for camera-embedded analytics depend on Taiwan-based foundry capacity with limited second sourcing.
- Biometric consent friction:Illinois BIPA's private right of action exposes operators to statutory damages per violation, chilling facial recognition deployments.
- Hybrid integration complexity:Legacy analog-to-IP bridge requirements extend project timelines and inflate professional services costs.
Strategic Opportunities
- Convergence of video and access control:Unified physical security platforms consolidate vendor relationships and expand annual contract values.
- Japan's Society 5.0 infrastructure program:National digitization targets create procurement pipelines for AI-enabled surveillance in transportation hubs.
- Outcome-based monitoring contracts:Retail loss prevention buyers shift from equipment purchases to per-incident response fee structures.
Industry Challenges
- Cloud security architecture certification:FedRAMP and ISO 27001 attestation timelines stretch 12-18 months, delaying federal and enterprise sales cycles.
- Legacy VMS interoperability:Proprietary ONVIF implementations force custom middleware development for multi-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Surveillance As a Service Market |
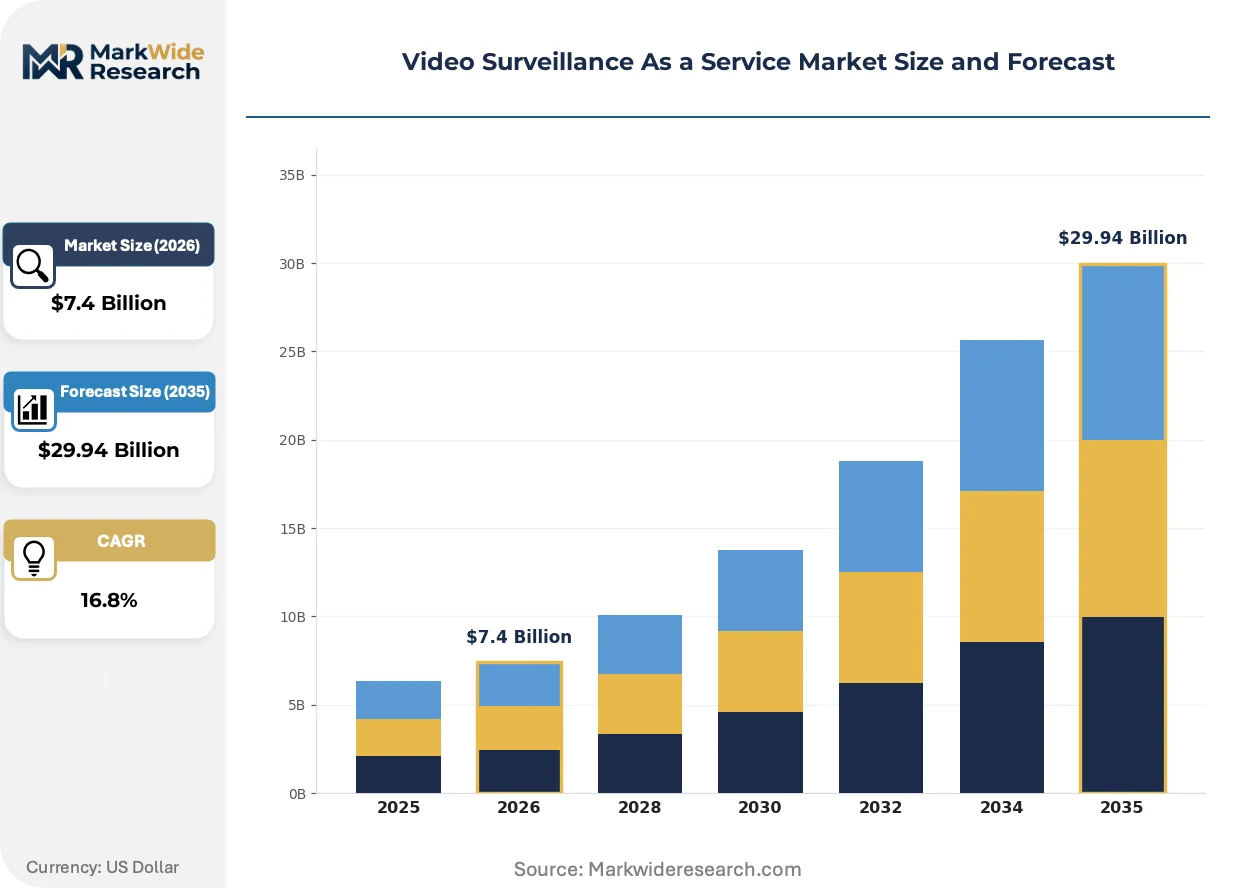
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $29.94 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Storage, Real-Time Analytics, Remote Monitoring, Incident Reporting, Access Control Integration Application: Retail Security, Campus Safety, Traffic Management, Critical Infrastructure Protection, Event Surveillance End User: Commercial Complexes, Educational Institutions, Logistics Centers, Public Transportation, Hospitality Venues Deployment Model: Public Cloud, Private Cloud, Hybrid Solutions, On-Premise Cloud, Edge-Enabled Systems |
| Companies Covered | ADT Inc., Johnson Controls International Plc, Axis Communications AB, Honeywell International Inc., Alarm.com, Eagle Eye Networks, Bosch Sicherheitssysteme GmbH, Genetec Inc., Avigilon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Surveillance As a Service Market Strategic Shifts & Innovations
Artificial intelligence inference is migrating from centralized data centers to camera-edge processors, compressing alert latency while complicating firmware update orchestration across dispersed device fleets.
Edge AI chipsets with embedded neural processing units are modularizing how analytics capabilities deploy across camera networks. Mid-market retailers and logistics operators adopt these systems to reduce cloud egress costs. The technology is modularizing vendor ecosystems by decoupling hardware from software licensing, enabling mix-and-match procurement.
The EU AI Act's high-risk system classification imposes conformity assessment obligations on biometric identification deployments. Operators must maintain technical documentation and human oversight protocols. Public space surveillance projects across France and Germany face procurement delays as authorities interpret enforcement timelines.
Subscription-based service bundling is displacing perpetual license sales across commercial security channels. Systems integrators in the United States restructure compensation around recurring revenue share rather than hardware markup. This reconfiguration concentrates buyer relationships with cloud-native platform providers.
Video Surveillance As a Service Market Segmentation
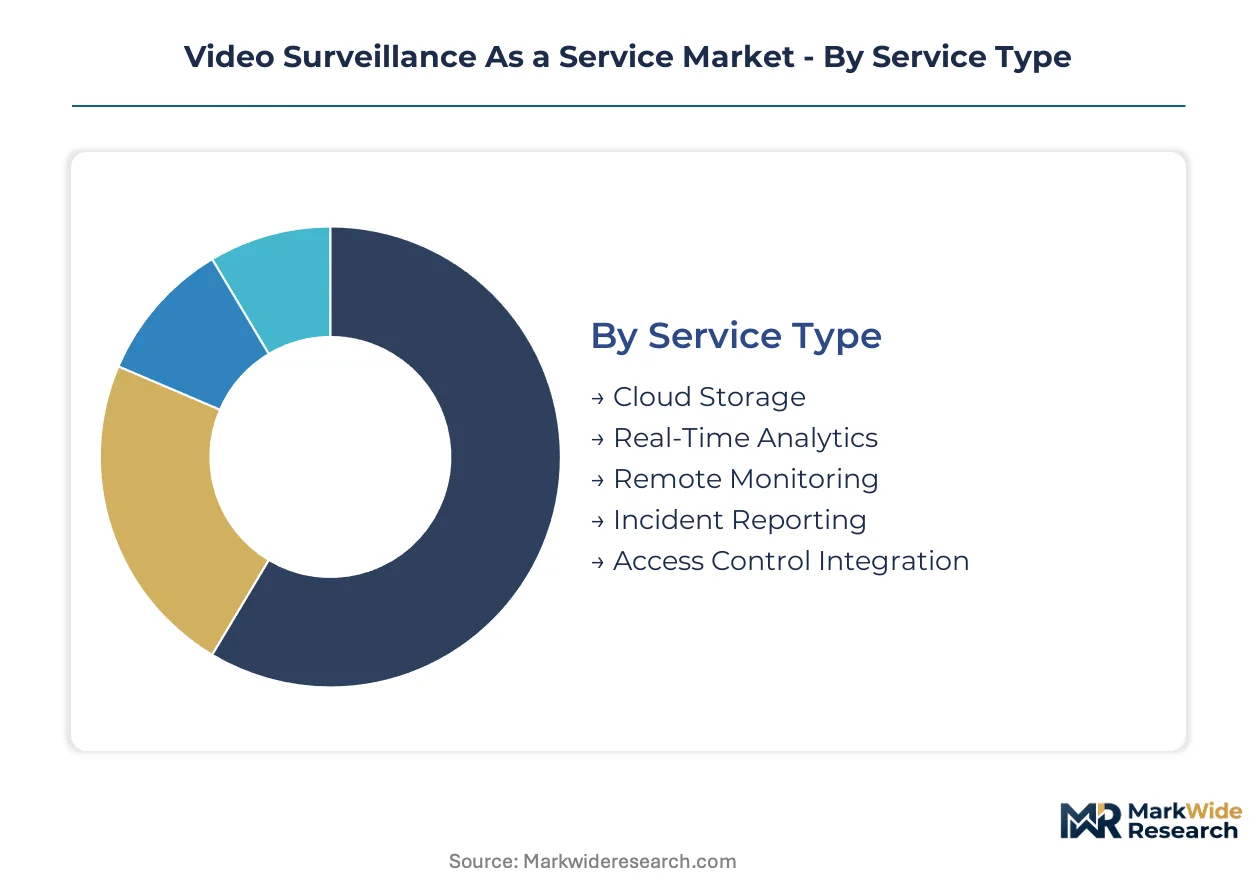
Video Surveillance As a Service procurement patterns diverge sharply across deployment architectures and operational use cases. Service type selection directly determines compliance architecture, while deployment model choices reflect legacy infrastructure maturity and data sovereignty requirements.
Service Type:
Cloud storage and real-time analytics command the largest current revenue pools as organizations prioritize searchable video archives and automated alert generation over passive recording.
- Cloud Storage:Encrypted redundant architectures across geographically distributed data centers preserve forensic evidence with automated retention policies. Demand concentrates in multi-site retail operators across Germany and Japan seeking GDPR-compliant erasure workflows.
- Real-Time Analytics:AI-powered threat detection running on H.265-compressed streams enables automated alert generation without human monitoring. Campus safety deployments in the United States drive adoption as educational institutions modernize emergency response protocols.
- Remote Monitoring:Centralized command center oversight of dispersed camera networks reduces on-site security staffing.
- Incident Reporting:Automated evidence packaging with chain-of-custody documentation accelerates insurance claims and legal proceedings.
- Access Control Integration:Unified credential management converges video verification with door entry permissions.
Mature deployment sits with Cloud Storage. Newer deployment is concentrated in Real-Time Analytics.
Application:
Cost tier differentiation separates high-complexity critical infrastructure from standardized commercial security deployments.
- Retail Security:Loss prevention systems with POS integration and shopper behavior analytics reduce shrinkage across distributed store networks. Multi-site commercial operators in the United States accelerate cloud migration to unify security operations centers.
- Critical Infrastructure Protection:Hardened edge-to-cloud pipelines with air-gapped failover meet national security requirements for energy and telecommunications facilities. German municipalities prioritize these systems under federal critical infrastructure directives.
- Campus Safety:Emergency mass notification integration with video verification supports active shooter response protocols.
- Traffic Management:License plate recognition and congestion analytics feed smart city command platforms.
- Event Surveillance:Temporary camera networks with rapid deployment timelines serve sporting venues and political gatherings.
Volume concentration favors Retail Security. Margin expansion is steepest in Critical Infrastructure Protection.
End User:
Customer type segmentation reveals divergent procurement sophistication between enterprise facilities and fragmented hospitality operators.
- Commercial Complexes:Mixed-use developments with unified lobby, parking, and tenant space monitoring require scalable camera licensing. Logistics centers in Japan's Society 5.0 program drive AI-enabled surveillance adoption for warehouse automation coordination.
- Educational Institutions:K-12 and university systems balance open campus access with perimeter security and emergency lockdown capabilities. Illinois and Texas biometric privacy laws force architectural redesigns around consent workflows for facial recognition deployments.
- Logistics Centers:Yard management and cargo integrity monitoring integrate with warehouse management systems.
- Public Transportation:Station platform and vehicle interior surveillance supports passenger safety and liability protection.
- Hospitality Venues:Guest privacy requirements limit camera placement while maintaining public area coverage.
Procurement standardization sits with Commercial Complexes. Compliance complexity is highest in Educational Institutions.
Deployment Model:
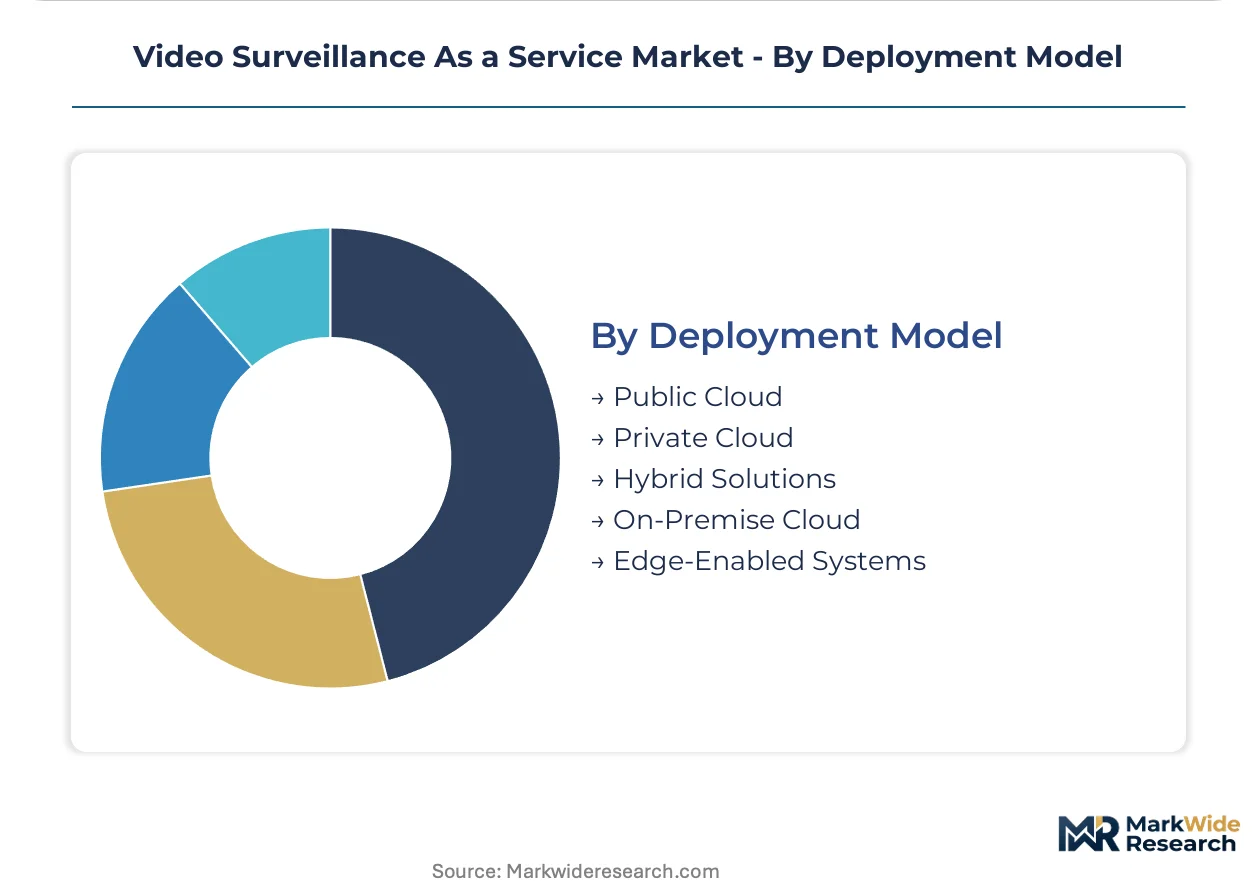
Supply concentration in edge hardware manufacturing shapes availability timelines for AI-enabled camera deployments.
- Hybrid Solutions:Bridge architectures preserving legacy analog investments while enabling elastic cloud scalability dominate mid-market procurement. Professional services costs inflate due to proprietary ONVIF implementation requirements across multi-vendor environments.
- Edge-Enabled Systems:Neural processing units embedded in camera hardware compress alert latency and reduce cloud egress costs. Taiwan-based foundry capacity constraints for specialized AI chipsets create supply bottlenecks with limited second sourcing.
- Public Cloud:Shared infrastructure with metered storage and compute pricing suits variable workloads.
- Private Cloud:Dedicated tenant environments meet data residency requirements for sensitive facilities.
- On-Premise Cloud:Local server clusters with cloud-native software stacks serve bandwidth-constrained locations.
Adoption velocity is climbing the fastest in Edge-Enabled Systems. Integration friction peaks in Hybrid Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadband infrastructure density and data sovereignty requirements anchor geographic deployment patterns for camera-to-cloud architectures. Municipal smart city programs and biometric privacy frameworks create divergent procurement conditions across national markets.
United States
Campus safety modernization and retail loss prevention drive cloud migration across multi-site operators. FCC broadband reliability standards govern remote monitoring service levels while Illinois BIPA and Texas biometric laws force consent workflow redesigns. Chicago and Dallas educational institutions face architectural constraints on facial recognition deployments.
Germany
Critical infrastructure protection mandates accelerate hardened edge-to-cloud procurement for energy and telecommunications facilities. GDPR Article 17 erasure requirements automate right-to-be-forgotten compliance across distributed camera networks. Frankfurt and Munich municipalities prioritize camera-to-cloud platforms under federal critical infrastructure directives.
Japan
Society 5.0 infrastructure targets create procurement pipelines for AI-enabled surveillance in transportation hubs and logistics centers. METI digitization programs coordinate warehouse automation with video verification systems. Tokyo and Osaka commercial complexes drive standardization in scalable camera licensing for mixed-use developments.
United Kingdom
Retail security deployments concentrate among multi-site commercial operators seeking unified security operations centers. Information Commissioner's Office guidance on automated decision-making shapes analytics procurement criteria. London logistics corridors adopt cloud-native platforms for yard management and cargo integrity monitoring.
India
Smart city mission funding supports traffic management and public safety modernization in tier-1 urban centers. TRAI data localization consultations influence cloud architecture decisions for government surveillance projects. Mumbai and Bangalore commercial developments balance scalable licensing with bandwidth-constrained connectivity.
Video Surveillance As a Service Market Key Industry Players
Global majors compete with regional champions across platform architecture and compliance certification dimensions. The vendor base organizes around three tiers: cloud-native pure-plays, diversified industrial conglomerates with security divisions, and specialized systems integrators. Strategic archetypes include open-platform specialists, hardware-anchored incumbents, and vertical-focused service bundlers. Competitive moves concentrate on recurring revenue model transitions and privacy-by-design certification attainment.
Within the open-platform tier, Axis Communications AB exemplifies interoperability-focused positioning. Bosch Sicherheitssysteme GmbH anchors European critical infrastructure presence through hardened system architectures. Eagle Eye Networks occupies the cloud-native pure-play position with serverless infrastructure models. These three represent divergent responses to biometric privacy mandates and hybrid deployment complexity.
| Leading Market Players |
|---|
| ADT Inc. |
| Johnson Controls International Plc |
| Axis Communications AB |
| Honeywell International Inc. |
| Alarm.com |
| Eagle Eye Networks |
| Bosch Sicherheitssysteme GmbH |
| Genetec Inc. |
| Avigilon |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up cloud platform specialists now dominate mid-market channel ownership, compressing procurement leverage for systems integrators while enforcing subscription pricing discipline across multi-site retail deployments. This ownership concentration tightens margin capture at the software layer even as Taiwan-based foundry constraints prop camera hardware premiums.
Pricing Analysis
Warranty and firmware-update bundling separates premium cloud-native providers from unbundled hardware-centric competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FedRAMP-authorized platforms command substantial premiums over uncertified alternatives. Cost compression in the economy tier is intensifying because mid-market retailers demand H.265-enabled 4K streaming without enterprise-grade analytics. Educational institutions exhibit highest price sensitivity due to municipal budget cycles, while critical infrastructure operators show lowest sensitivity given national security procurement mandates.
Supply Chain Analysis
FedRAMP and ISO 27001 certification gating restricts vendor eligibility for federal and enterprise contracts, elongating supplier qualification timelines. Camera hardware production concentrates in Taiwan, China, and South Korea, with neural processing units drawing from TSMC foundry capacity. Specialized AI chipsets, H.265 encoder modules, and hardened edge servers constitute critical input dependencies. Single-source vulnerability in Taiwan-based NPU manufacturing creates supply bottlenecks with limited second sourcing. Distribution runs through systems integrator channels in the United States and security distributors across Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan foundry capacity constraints for edge AI chipsets prop hardware premiums and sustain pricing power for certified platform providers. Supply scarcity at the component layer favors vendors with pre-allocated foundry relationships.
For Market Incumbents: To counter cloud-native pure-plays eroding mid-market share, incumbents must accelerate backward integration into edge AI chipset supply through foundry partnership commitments and harden certification moats by compressing FedRAMP authorization timelines from 18 months to 12 months through pre-audited architecture templates. For New Entrants and Emerging Players: The price-point gap between premium FedRAMP-authorized platforms and economy-tier uncertified alternatives creates white-space opportunity in mid-market hybrid deployments. Japan's Society 5.0 logistics centers and Germany's GDPR-compliant municipal projects represent most penetrable geographies. A channel-native go-to-market angle through systems integrator revenue-share partnerships bypasses direct enterprise sales cycle barriers. For Investors and Strategic Acquirers: Illinois BIPA enforcement actions against facial recognition operators is the leading indicator that privacy-by-design certification will consolidate vendor relationships around compliant platforms. Long-term viability favors cloud-native pure-plays with pre-authorized federal architectures over hardware-anchored incumbents burdened by legacy VMS interoperability costs. Acquisition targets should display ISO 27701 privacy management certification and established foundry allocation agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies video verification with access control credentials across Axis Communications and Genetec ecosystems. |
| Geographic Expansion | Captures Japan Society 5.0 procurement pipelines for AI-enabled transportation hub surveillance. |
| Acquisition of Specialist Firm | Absorbs edge AI analytics providers to compress alert latency and reduce cloud egress costs. |
| Product Launch | Introduces H.265-native camera lines enabling 4K streaming over standard broadband infrastructure. |
| Strategic Partnership | Secures foundry capacity commitments with Taiwan-based NPU manufacturers against supply bottlenecks. |
Research Approach
SEC filings, hyperscaler capex disclosures, and customs/trade data formed the secondary backbone for vendor revenue triangulation. Primary interviews with physical security directors, systems integrator principals, municipal procurement officers, and cloud platform engineers validated deployment timelines and pricing structures. Bottom-up camera shipment modeling and top-down security spending allocation across the analysis window reconciled market size estimates.
Historical trendline analysis of cloud storage pricing compression and H.265 adoption curves informed projection frameworks across the modeling period. Segmentation dimensions modeled include deployment architecture, service type, end-user vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted penetration rates applied to addressable camera base expansion. Forecast inputs incorporated FCC broadband reliability standards and GDPR Article 17 automation requirements as demand shifters.
Inputs from hyperscaler infrastructure disclosures and municipal procurement databases were available through the study window; gaps in private-cloud deployment cost structures introduce uncertainty bands around hybrid solution forecasts. Forecasts reflect assumptions of sustained Taiwan foundry allocation and stable biometric privacy enforcement intensity. A model refresh is warranted upon material change in NPU manufacturing capacity or EU AI Act high-risk system classification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Under-Vehicle Surveillance Market