
 Wireless Home Security Camera Market | 2026-2036
Wireless Home Security Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Home Security Camera Market Analysis
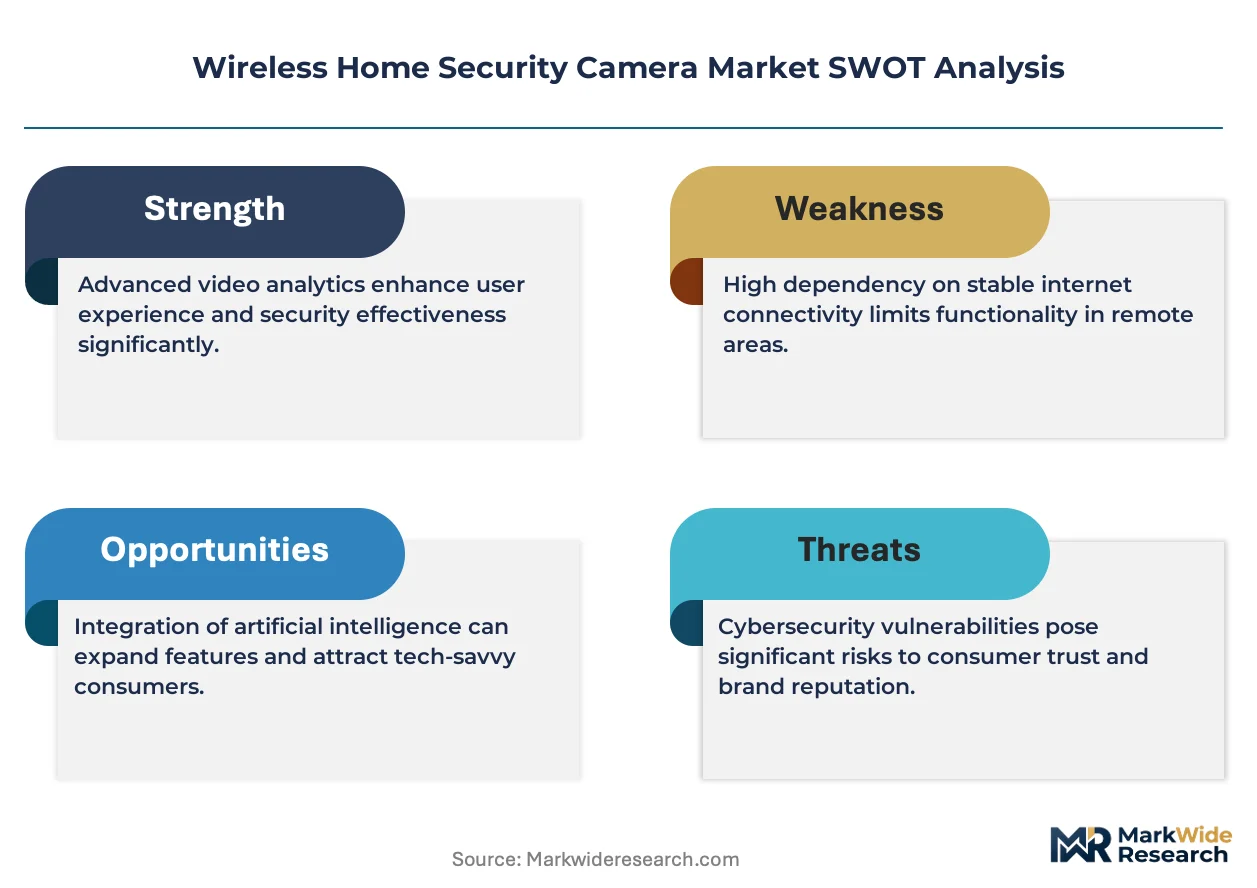
The gap between premium AI-enabled systems and basic motion-detection units is recalibrating how manufacturers allocate engineering resources and channel investments. Arlo Technologies differentiates through proprietary wire-free platforms with integrated solar charging. Wyze Labs competes on aggressive household pricing while sustaining margin through recurring cloud subscriptions. Ring anchors its position via deep integration with broader smart home ecosystems and neighborhood-facing software services.
Wireless home security cameras are self-contained video surveillance devices transmitting footage via radio frequency protocols to local or cloud-based storage, typically operating on battery, solar, or line power with resolutions spanning 1080p to 4K and fields of view between 110 and 160 degrees; their primary purpose is real-time property monitoring, intrusion deterrence, and forensic evidence capture for residential and small commercial environments. Indoor cameras dominate unit volumes due to lower weatherproofing costs and simpler installation, while smart video doorbells command higher average selling prices through embedded two-way audio and package detection algorithms. Wi-Fi connectivity leads installations globally, though cellular modules gain traction in rural properties lacking broadband infrastructure.
The FCC enforces Part 15 emission limits and cybersecurity labeling requirements that constrain hardware design and firmware update obligations for devices sold in the United States. The EU's Radio Equipment Directive and GDPR impose parallel technical conformity and data residency standards that complicate cross-border product strategies. China's MIIT administers network access licenses and GB standards for wireless transmission power that shape manufacturing specifications for export-oriented producers. Stakeholders must monitor evolving encryption mandates and cross-border data flow restrictions that will determine which feature sets remain salable across jurisdictional boundaries.
Market Dynamics
DIY installation and subscription-based cloud monitoring are restructuring competitive economics, compressing hardware margins while elevating recurring revenue streams as the primary value capture mechanism for manufacturers.
Growth Catalysts
- FCC Part 15 cybersecurity labeling:The United States regulator now mandates firmware update obligations and emission compliance that accelerate product refresh cycles and create upgrade demand among security-conscious households.
- Cellular module adoption:Rural properties lacking broadband infrastructure in Texas, Montana, and Alaska are deploying LTE-enabled cameras, expanding addressable market beyond Wi-Fi coverage zones.
- Solar charging integration:Wire-free platforms with photovoltaic supplementation eliminate battery replacement friction, extending deployment feasibility to perimeter locations previously inaccessible to line power.
Market Restraints
- Image sensor supply concentration:CMOS sensor fabrication concentrates among Taiwanese and South Korean foundries, exposing manufacturers to geopolitical disruption and foundry allocation constraints.
- GDPR data residency requirements:The EU directive compels localized cloud infrastructure that fragments platform economics and elevates operational complexity for cross-border vendors.
- Professional monitoring substitution:Central station alarm services with human verification retain preference among affluent suburban households skeptical of AI-only intrusion detection.
Strategic Opportunities
- MIIT network access licenses:China's GB standards for transmission power create compliant product differentiation for export-oriented producers targeting domestic and Belt-Road markets.
- Edge AI convergence:On-device neural processing for package detection and facial recognition reduces cloud dependency and latency, enabling premium pricing in bandwidth-constrained environments.
- Insurance channel partnerships:Property underwriters in Florida and California are bundling camera discounts with homeowner policies, creating embedded distribution at point of risk assessment.
Industry Challenges
- Firmware security engineering scarcity:Embedded systems talent capable of implementing end-to-end encryption and secure boot protocols commands premium compensation, constraining development velocity at mid-tier manufacturers.
- Cross-certification timeline compression:Simultaneous FCC, CE marking, and MIIT approvals extend product launch windows, delaying revenue recognition against competitor releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Home Security Camera Market |
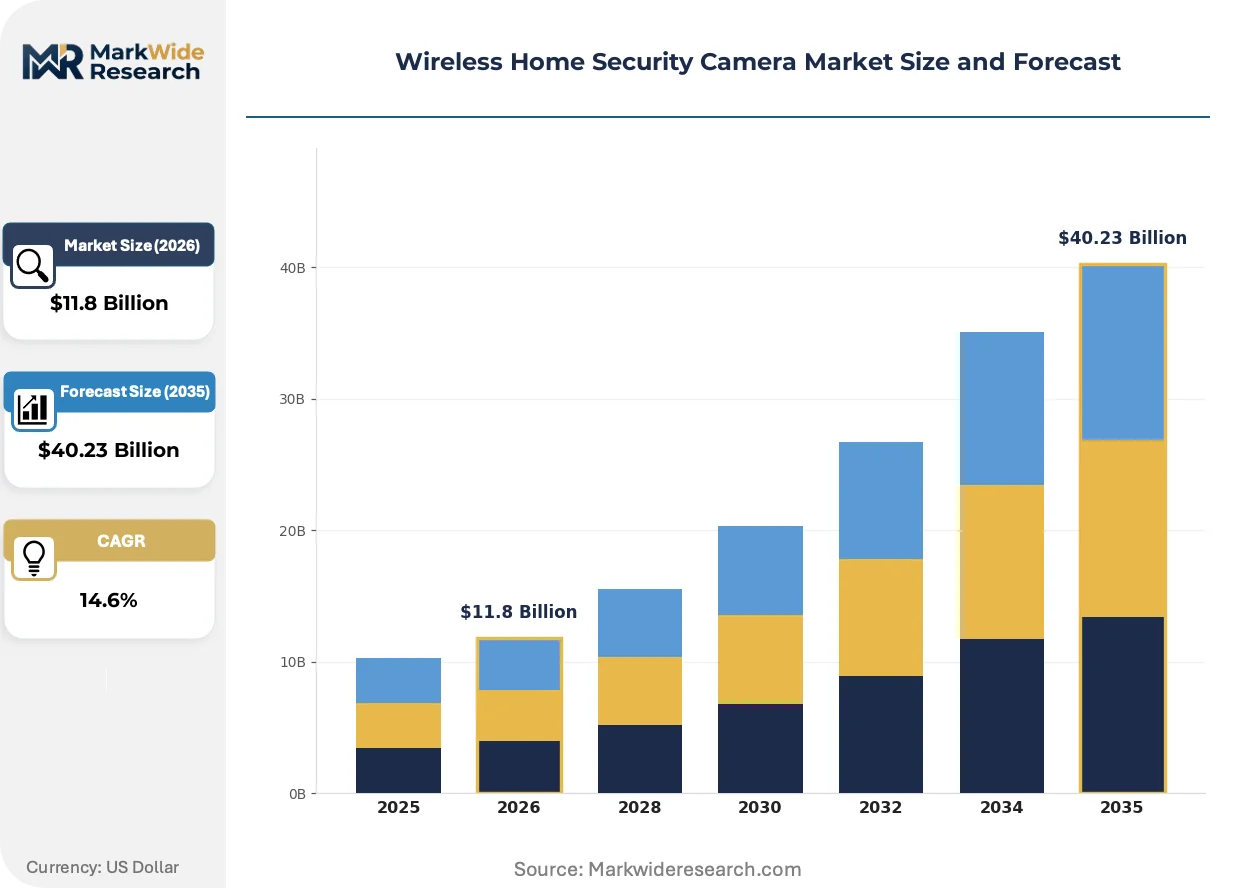
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Cameras, Outdoor Cameras, PTZ Cameras, Smart Video Doorbells Connectivity: Wi-Fi, Bluetooth, Cellular, Ethernet End User: Households, Small Businesses, Property Managers, Rental Properties Features: Night Vision, Motion Detection, Two-Way Audio, Cloud Storage |
| Companies Covered | Arlo Technologies, Ring, Nest Labs, Amazon.com, Lorex Technology, Wyze Labs, Samsung Electronics, ADT, Reolink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Home Security Camera Market Emerging Trajectories
On-device intelligence and localized processing architectures are displacing cloud-dependent workflows, reducing latency and data transfer costs while complicating platform monetization strategies.
Edge-based computer vision is automating intrusion verification and reducing false alarm rates that previously eroded user trust and monitoring center profitability. Mid-market households in Germany and the United Kingdom are adopting these systems faster than premium segments, compressing the technology diffusion cycle from enterprise to consumer applications. The shift is automating tier-one technical support functions and enabling self-service troubleshooting that reduces subscriber churn.
The EU AI Act's risk classification framework is imposing conformity assessment obligations on biometric identification features that exceed general product safety requirements. Camera systems with facial recognition capabilities now face third-party auditing and documentation burdens that extend development cycles by four to six months. Vendors are responding by bifurcating product lines, stripping biometric functions from European SKUs while preserving them for North American and Asian markets.
Subscription unbundling is fragmenting the traditional all-inclusive monitoring package into modular components. Buyers in the United States are selecting cloud storage tiers, AI feature sets, and professional monitoring à la carte through direct-to-consumer channels. This pattern is most pronounced among millennial first-time homeowners who reject long-term contracts and prefer month-to-month flexibility, forcing incumbents to restructure pricing architectures and customer lifetime value calculations.
Wireless Home Security Camera Market Segmentation
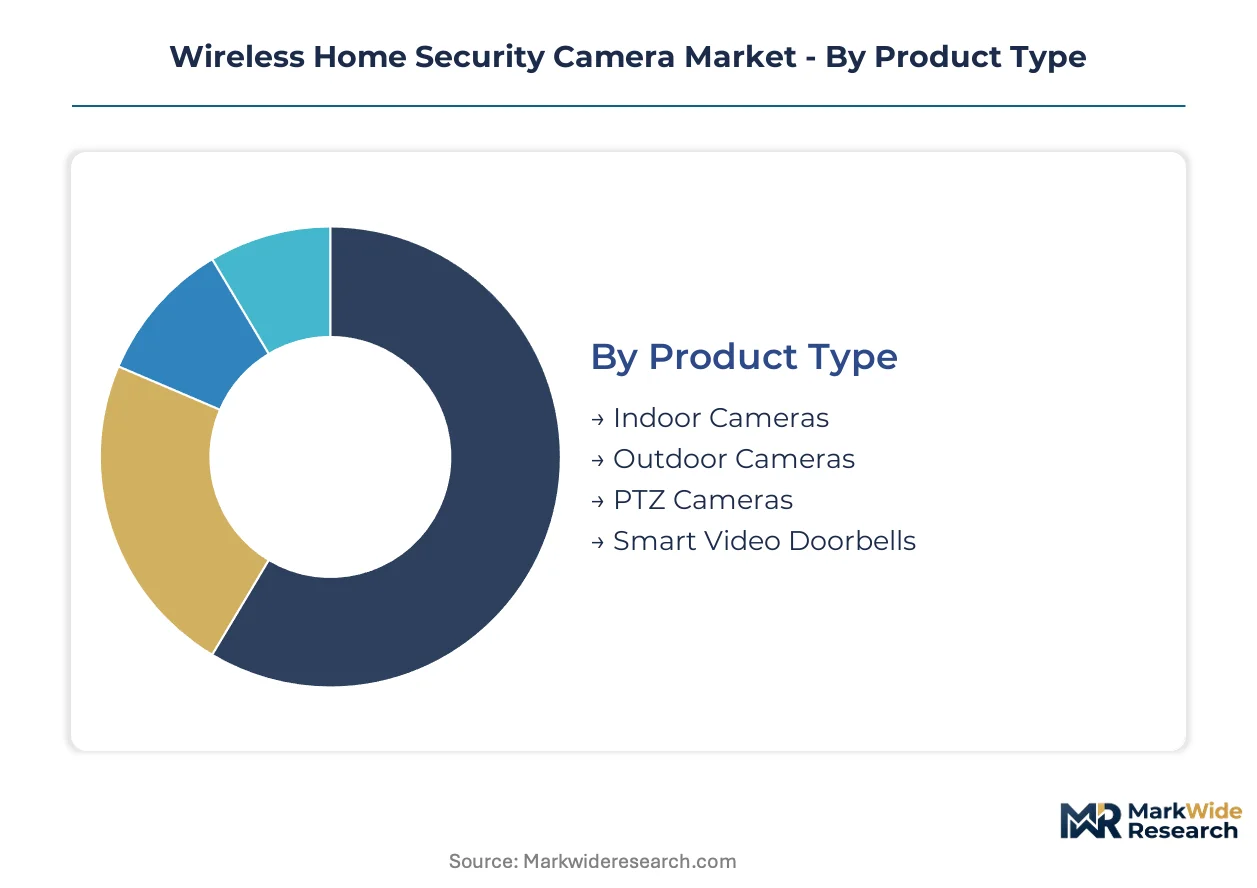
Wireless home security camera segmentation reveals how installation constraints, connectivity infrastructure, and feature sophistication reshape purchasing patterns across residential and commercial environments. Manufacturers calibrate hardware specifications, subscription tiers, and channel strategies to match distinct buyer capabilities and property types.
Product Type:
Cost tier differentiation separates buyers seeking minimal weatherproofing investment from those prioritizing perimeter coverage and mechanical articulation.
- Indoor Cameras:These units eliminate IP65+ sealing requirements and operate within controlled temperature ranges, enabling polycarbonate housings and simplified mounting hardware. Demand concentrates in apartment complexes across Germany and Japan where landlord restrictions prohibit exterior modifications. FCC Part 15 emission compliance remains straightforward due to shielded indoor environments.
- Outdoor Cameras:Weather-resistant enclosures with -20°C to 50°C operating ranges and ingress protection dominate single-family home installations in Texas, Florida, and California. Solar panel integration eliminates battery maintenance for fence-line and garage deployments previously inaccessible to power outlets.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with 360-degree coverage serve large rural properties in Montana and Alaska requiring single-device perimeter monitoring.
- Smart Video Doorbells:Embedded two-way audio and package detection algorithms command premium positioning through embedded neural processing and low-latency notification pipelines.
Volume sits with Indoor Cameras; growth tilts toward Smart Video Doorbells.
Connectivity:
Application context determines whether buyers prioritize bandwidth economy, installation simplicity, or infrastructure independence.
- Wi-Fi:IEEE 802.11ac/ax protocols handle 1080p to 4K streaming across suburban households with fiber or cable broadband. Dense deployments in Chinese tier-1 cities and US metropolitan corridors exploit mesh network coverage.
- Cellular:LTE and emerging 5G modules unlock rural properties in Texas, Montana, and Alaska lacking fixed-line infrastructure. MIIT network access licenses in China and FCC equipment authorization in the US impose divergent certification timelines for modem integration.
- Bluetooth:Low-energy pairing enables initial device configuration and localized sensor networks without continuous cloud dependency.
- Ethernet:Power-over-Ethernet installations satisfy commercial property managers in Germany requiring guaranteed uptime and centralized VLAN segmentation.
Wi-Fi commands unit volume; Cellular expands the addressable market fastest.
End User:
Customer type shapes whether purchases flow through retail, insurance channels, or integrated property management platforms.
- Households:DIY installation preferences and month-to-month subscription flexibility dominate millennial first-time homeowners in the United States. Arlo, Wyze, and Ring compete through direct-to-consumer positioning with divergent hardware margin and recurring revenue models.
- Small Businesses:Retail storefronts and professional offices in the United Kingdom prioritize visible deterrence and insurance documentation over AI sophistication.
- Property Managers:Multi-unit residential operators in California and Florida negotiate enterprise pricing for centralized dashboard administration across distributed portfolios.
- Rental Properties:Temporary installation requirements and deposit-friendly hardware pricing shape demand in German urban markets with high tenant turnover.
Households drive installed base; Property Managers deliver contract value concentration.
Features:
Margin structure separates basic motion-alert commoditization from premium AI-enabled verification workflows.
- Night Vision:Infrared LED arrays with 850nm wavelength enable monochrome capture to 30 meters, essential for unlit driveways and alleyways.
- Motion Detection:Pixel-change algorithms and PIR sensors trigger recording while conserving battery and bandwidth resources.
- Two-Way Audio:Full-duplex speaker-microphone systems with echo cancellation support delivery verification and intrusion deterrence through remote vocal intervention.
- Cloud Storage:Tiered retention policies from 7-day rolling to 30-day event archives generate recurring subscription revenue that offsets hardware margin compression.
Motion Detection saturates baseline configurations; Cloud Storage monetization is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor supplies the majority of wireless camera modules worldwide, with component clusters in Dongguan and Guangzhou feeding assembly lines that serve North American and European brands.
United States
Suburban households in Texas and Florida drive replacement cycles for weather-resistant outdoor units, while millennial first-time buyers in California prefer DIY indoor systems. FCC Part 15 cybersecurity labeling mandates firmware update obligations that accelerate product refresh timelines. The Dallas-Fort Worth metroplex hosts distribution centers for direct-to-consumer brands expanding same-day delivery coverage.
Germany
Apartment dwellers in Berlin and Munich favor compact indoor cameras compatible with landlord restrictions on exterior modifications. GDPR data residency requirements compel localized cloud infrastructure investments from foreign vendors. The Stuttgart region anchors engineering talent pools developing edge AI processing for privacy-conscious European households.
China
Tier-1 cities including Shanghai and Beijing deploy dense Wi-Fi mesh networks supporting multi-camera residential installations. MIIT network access licenses and GB transmission power standards shape manufacturing specifications for domestic and export production. The Yangtze River Delta concentration of CMOS foundries exposes supply chains to geopolitical allocation constraints.
United Kingdom
Retail storefronts in London and Manchester prioritize visible deterrence over AI sophistication for insurance documentation purposes. The EU AI Act's risk classification framework imposes conformity assessment obligations on biometric identification features. The Cambridge technology cluster incubates computer vision startups targeting European privacy regulations.
Japan
Aging householders in Tokyo and Osaka adopt simplified interfaces with voice-activated controls for property monitoring. METI standards for wireless transmission power align product specifications with adjacent regional markets. The Nagoya manufacturing belt produces precision optical components for premium camera assemblies.
Wireless Home Security Camera Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base separates into three strategic archetypes: vertically integrated electronics conglomerates controlling sensor supply, direct-to-consumer specialists monetizing through recurring subscriptions, and contract manufacturers serving private-label retailers. Dominant competitive moves include technology licensing agreements for edge AI processing and strategic partnerships with property insurers embedding cameras at point of risk assessment.
Among US-based platform operators, Arlo Technologies and Ring exemplify the subscription-centric archetype, while Wyze Labs occupies a position representing aggressive household pricing with margin sustained through cloud service tiers. These three anchors demonstrate divergent resource allocation between hardware engineering and software platform development.
| Leading Market Players |
|---|
| Arlo Technologies |
| Ring |
| Nest Labs |
| Amazon.com |
| Lorex Technology |
| Wyze Labs |
| Samsung Electronics |
| ADT |
| Reolink |
| Others |
Supply Flow & Price Mechanics
AI-performance bifurcation between edge-enabled verification systems and basic motion-alert units splits both pricing power and component sourcing strategies across the wireless home security camera market. Premium tiers command recurring subscription multiples through on-device neural processing, while commodity hardware competes on CMOS sensor cost curves shaped by Taiwanese and South Korean foundry allocation.
Pricing Analysis
Subscription-based recurring revenue anchors value-based pricing for cloud-enabled verification tiers, with hardware margins compressed to customer acquisition costs. Price differentiation rests on edge AI capability and FCC Part 15 cybersecurity certification tier, not raw sensor resolution. Cost compression in entry-level Wi-Fi cameras intensifies as Chinese OEMs flood direct-to-consumer channels. Millennial first-time homeowners in the United States exhibit highest price sensitivity, while property managers in California and Florida prioritize centralized dashboard value over unit economics.
Supply Chain Analysis
CE marking and FCC equipment authorization gates create qualification backlogs that favor incumbents with established regulatory affairs teams. Manufacturing concentrates in China, Taiwan, and South Korea, with Shenzhen assembly feeding North American and European brands. CMOS image sensors, lithium battery cells, and LTE modem modules constitute critical input dependencies. Single-source vulnerability in Taiwanese foundry capacity exposes production schedules to geopolitical allocation disruptions. Distribution runs through direct-to-consumer platforms, Amazon marketplace, and insurance channel partnerships in Florida and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FCC Part 15 cybersecurity labeling and EU AI Act conformity assessments erect barrier-to-entry moats favoring players with established regulatory infrastructure and firmware engineering depth.
For Market Incumbents: Acquire embedded systems talent pools capable of implementing end-to-end encryption and secure boot protocols to defend against mid-tier competitors facing firmware security engineering scarcity. Consolidate certification capabilities across FCC, CE marking, and MIIT approval workflows to compress cross-certification timelines that delay competitor revenue recognition. Prioritize backward integration into CMOS sensor supply relationships to mitigate Taiwanese foundry allocation constraints. For New Entrants and Emerging Players: Edge AI convergence for package detection and facial recognition on resource-constrained devices offers technology-first positioning against cloud-dependent incumbents. Target rural properties in Texas, Montana, and Alaska lacking broadband infrastructure through LTE-enabled camera systems with cellular module differentiation. Pursue insurance channel partnerships in Florida and California as embedded distribution at point of risk assessment. For Investors and Strategic Acquirers: Re-rating potential sits with direct-to-consumer specialists monetizing through recurring cloud subscriptions given subscription unbundling trends among millennial first-time homeowners. Long-term viability favors asset-light designers with proven subscriber retention mechanics over capital-heavy producers exposed to hardware margin compression. Watch cellular module adoption rates in rural broadband deserts as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Platform Development | On-device neural processing reduces cloud dependency and latency for bandwidth-constrained rural deployments. |
| Regulatory Certification Acceleration | Simultaneous FCC, CE marking, and MIIT approvals compress product launch windows against competitor releases. |
| Insurance Channel Partnership | Property underwriters in Florida and California embed cameras at point of risk assessment. |
| Solar Charging Integration | Photovoltaic supplementation eliminates battery maintenance for perimeter locations beyond line power reach. |
| Cellular Module Certification | LTE and 5G modem integration unlocks rural properties lacking fixed-line broadband infrastructure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with connected device engineering directors, cloud platform product managers, retail channel buyers, and firmware security specialists. FCC equipment authorization databases, EU CE marking registries, MIIT network access license disclosures, and import-export manifests provided shipment and certification tracking. Bottom-up unit economics modeling triangulated against top-down market sizing across connectivity protocols and end-user segments.
Granularity-level modeling distinguished Wi-Fi, cellular, Bluetooth, and Ethernet connectivity tiers; indoor, outdoor, PTZ, and smart video doorbell product types; and household, small business, property manager, and rental property end-user categories. CAGRs derived from segment-level adoption curves, replacement cycle assumptions, and subscription attach rate trajectories across the analysis window. Edge AI penetration rates and solar charging adoption patterns informed technology diffusion assumptions.
Several conditions sit outside the modeled scope, including unannounced regulatory encryption mandates, cross-border data flow restrictions, and geopolitical disruptions to CMOS sensor fabrication. Forecasts reflect assumptions regarding broadband infrastructure expansion, smart home ecosystem integration depth, and insurance channel partnership maturation. A model refresh is warranted upon material change in FCC cybersecurity labeling enforcement intensity or EU AI Act biometric identification risk classification implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Home Security Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
Night Vision System (NVS) Market